
 Switzerland Data Center Market | 2026-2036
Switzerland Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Data Center Market Insights
The Switzerland data center landscape is restructuring around a widening gap between premium facilities with liquid-cooled, AI-ready infrastructure and commodity sites serving legacy enterprise workloads. Green Datacenter leverages its alpine hydropower contracts to sustain carbon-neutral positioning across the Zurich and Bern corridors. Equinix anchors interconnection density at its Zurich ZH5 campus, while Swisscom dominates domestic telecommunications-integrated edge deployments through its nationwide fiber backbone.
A data center constitutes a purpose-built facility housing compute, storage, and networking equipment with controlled environmental parameters—typically maintaining temperatures between 18°C and 27°C per ASHRAE guidelines—designed to ensure continuous availability of digital services for enterprises and cloud operators. Colocation deployments occupy the mature revenue core as established financial institutions retain physical asset control, yet liquid cooling segments are capturing disproportionate capital flow as GPU cluster densities exceed 50 kW per rack. Hyperscale builds from cloud service providers represent the fastest-growing capacity layer, though modular prefabricated units are gaining traction among alpine-edge applications where construction windows narrow seasonally.
Swissmedic-adjacent data integrity requirements for pharmaceutical logistics, combined with FINMA operational resilience directives and the Federal Act on Data Protection's cross-border transfer constraints, collectively elevate facility certification standards and restrict vendor eligibility. The Swiss Federal Office of Energy's efficiency benchmarking further tightens power usage effectiveness thresholds for new builds. Stakeholders must weigh locational advantages in the Mittelland plateau against emerging cantonal tax incentives targeting digital infrastructure investment in peripheral regions.
Market Dynamics
The Switzerland data center market is bifurcating around liquid cooling infrastructure as GPU rack densities breach 50 kW thresholds, forcing facility operators to choose between premium AI-ready retrofits and stranded legacy assets. FINMA operational resilience mandates and revised Federal Act on Data Protection cross-border constraints are simultaneously tightening certification requirements while compressing deployment timelines for new capacity.
Growth Catalysts
- FINMA Operational Resilience Directives:Swiss financial institutions must maintain redundant data processing capabilities within national borders, accelerating colocation demand among private banks and asset managers.
- Alpine Hydropower Contracts:Facilities with secured renewable energy agreements in the Zurich-West and Bern corridors achieve carbon-neutral positioning that satisfies ESG-linked procurement criteria from pharmaceutical and wealth management clients.
- GPU Cluster Density Thresholds:AI training workloads exceeding 50 kW per rack are forcing migration from air-cooled legacy facilities to liquid-cooled infrastructure, concentrating demand in purpose-built campuses.
Market Restraints
- Construction Input Cost Volatility:Specialized cooling equipment and high-voltage switchgear face extended lead times from European suppliers, inflating capex budgets for greenfield projects.
- Permitting Timeline Compression:Cantonal environmental review processes for alpine-edge facilities narrow to seasonal construction windows, delaying modular deployments in peripheral regions.
- Legacy Air-Cooled Stranding Risk:Facilities built before 2020 lack structural load capacity and piping infrastructure for liquid cooling retrofits, creating asset obsolescence in the Mittelland plateau.
Strategic Opportunities
- Ticino Cantonal Tax Incentives:Peripheral southern regions offer digital infrastructure investment credits that offset land acquisition costs for edge deployments serving cross-border Italian-speaking enterprises.
- Swissmedic Data Integrity Convergence:Pharmaceutical logistics providers require temperature-validated compute environments adjacent to distribution hubs, creating specialized colocation demand near Basel and Geneva.
- Direct Liquid Cooling and Immersion Hybridization:Facilities combining cold plate and tank-based cooling technologies capture workloads across varying GPU density tiers without overprovisioning infrastructure.
Industry Challenges
- Specialized Thermal Engineering Talent Scarcity:Liquid cooling system design and maintenance requires expertise rare in traditional HVAC labor pools, extending commissioning timelines for high-density halls.
- Federal Act on Data Protection Certification Complexity:Cross-border transfer adequacy assessments and third-party processor audits impose documentation burdens that delay facility go-live dates.
- Legacy Interconnection Migration Friction:Financial institutions with decades-old mainframe dependencies face integration complexity when relocating to cloud-interconnected colocation environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Data Center Market |
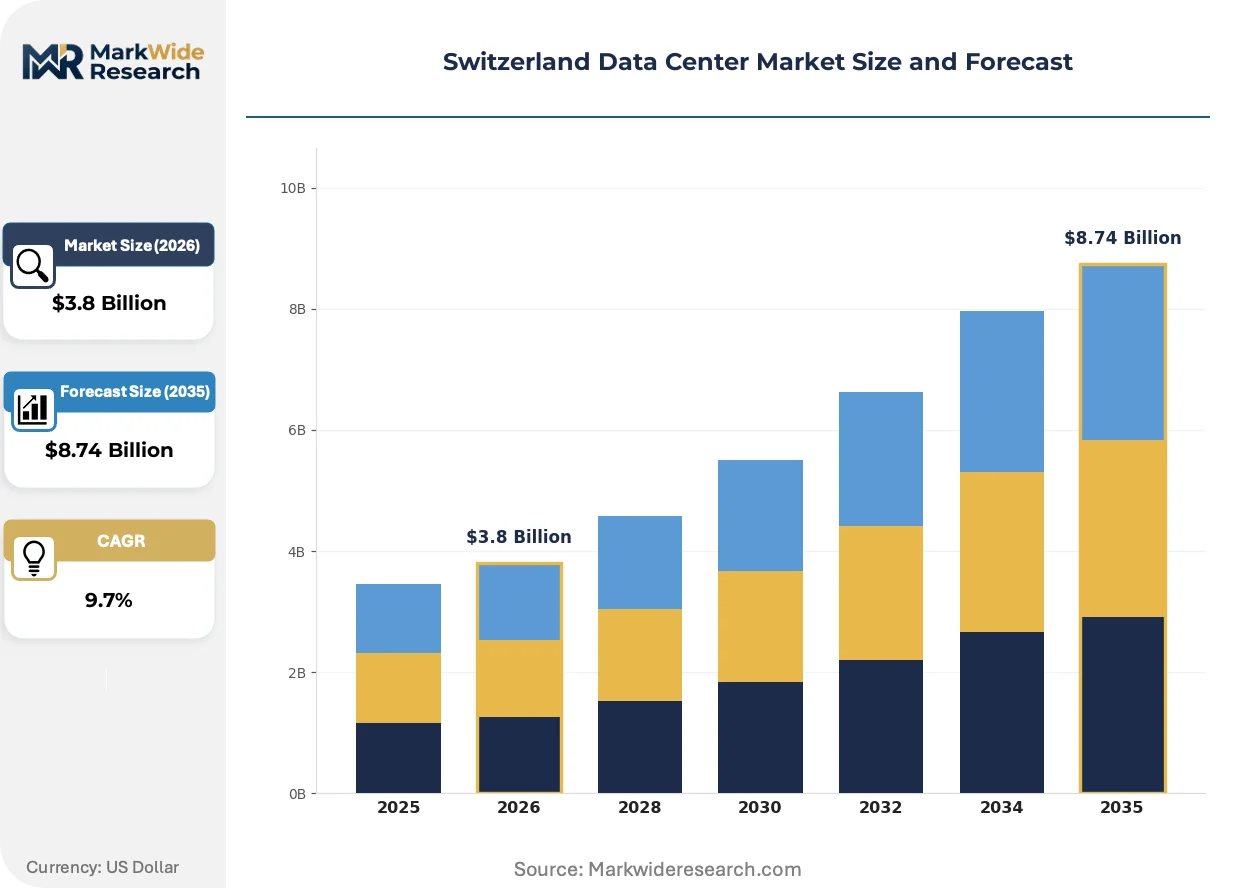
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Mode: On-Premises, Colocation, Hyperscale, Modular Cooling Technology: Air Cooling, Liquid Cooling, Evaporative Cooling, Green Cooling Power Type: Grid Power, Renewable Energy, Backup Diesel, UPS End User: IT Services, Telecommunication, Finance, Cloud Service Providers |
| Companies Covered | Green Datacenter, Equinix, STACK Infrastructure, Swisscom, NTT Data, Microsoft Corporation, Digital Realty, NorthC, Vantage Data Centers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Data Center Market Trends and Innovations
Liquid cooling architectures are displacing conventional air-handling units as the default infrastructure choice for new Swiss data center builds, with adoption patterns diverging sharply between retrofit-constrained legacy facilities and greenfield campuses. Three concurrent developments are compressing technology cycles and reshaping competitive positioning.
Direct liquid cooling is expanding into high-performance computing environments through cold plate systems that capture heat at the chip level before it enters the facility air stream. Swiss pharmaceutical researchers and quantitative trading firms are adopting these configurations for GPU-intensive simulation workloads. The technology is expanding into mid-density enterprise segments as air-cooled capacity constraints force migration decisions earlier than planned replacement cycles.
The Federal Act on Data Protection revision mandates data localization for sensitive personal information processed by financial and healthcare entities. Swiss facility operators must demonstrate technical and organizational measures that prevent unauthorized cross-border transfers. Domestic colocation providers with certified compliance frameworks are capturing wallet share from international hyperscale operators lacking equivalent Swiss-specific audit credentials.
Enterprise procurement teams are consolidating vendor relationships around facilities offering integrated compliance, interconnection, and sustainability verification. Single-provider contracts covering compute, network, and carbon accounting are displacing multi-vendor arrangements that fragment operational responsibility. This concentration is most visible among Geneva-based private banks and Basel pharmaceutical headquarters seeking simplified governance structures.
Switzerland Data Center Market Segmentation
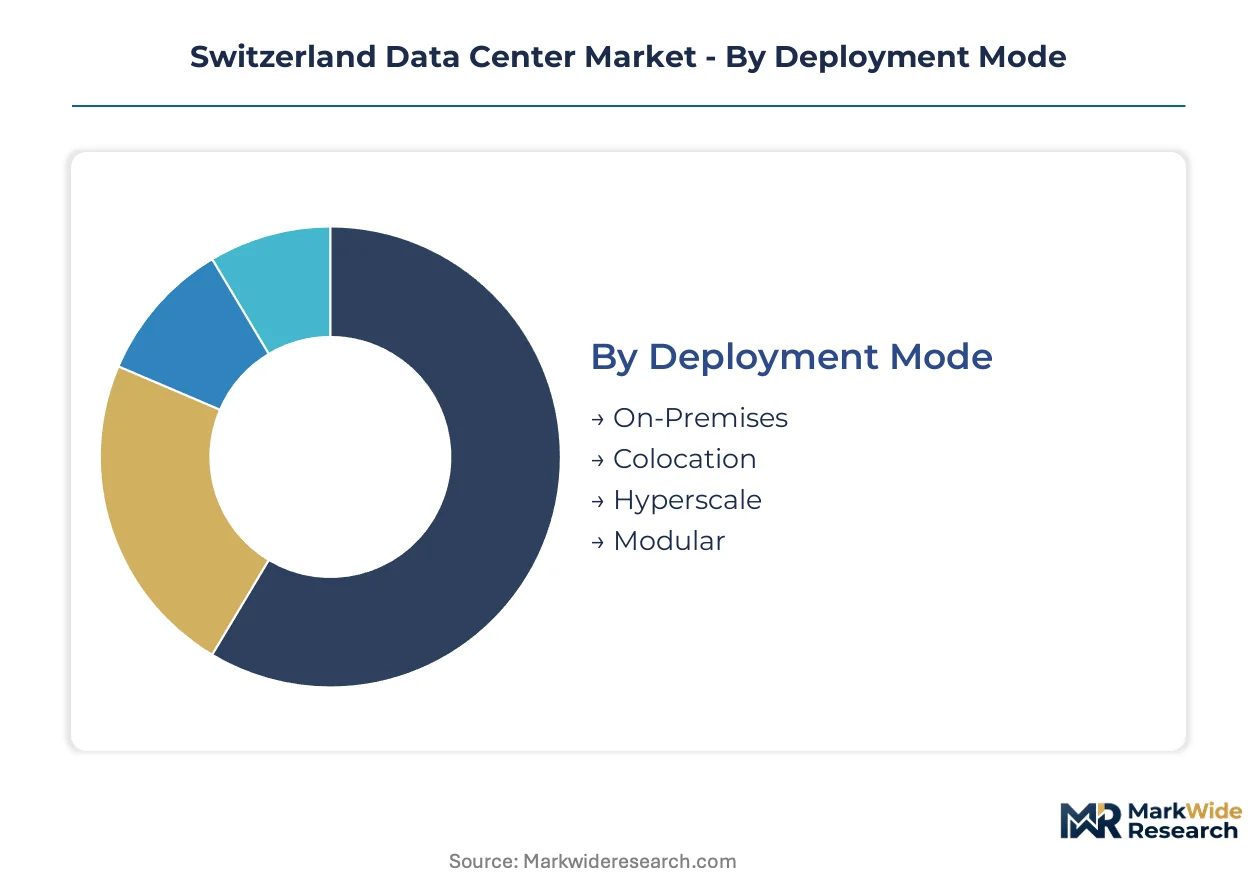
Switzerland's data center market segments reflect divergent compliance burdens across FINMA, Swissmedic, and Federal Act on Data Protection requirements. Certification complexity varies sharply by deployment architecture and end-user sensitivity.
Deployment Mode:
FINMA operational resilience mandates and Swissmedic data integrity rules impose distinct certification timelines across deployment architectures, with cross-border transfer restrictions favoring domestic-controlled facilities.
- On-Premises:Enterprises retain full physical custody of compute infrastructure within owned real estate, satisfying the most stringent Swiss Federal Act on Data Protection localization requirements for systemically important banks. Zurich-based private wealth managers dominate demand here, driven by FINMA's redundant processing mandates that prohibit sole reliance on third-party facilities.
- Colocation:Multi-tenant facilities where enterprises lease rack space while retaining hardware ownership, capturing the mature revenue core as financial institutions balance physical asset control against operational flexibility. Basel pharmaceutical headquarters and Geneva private banks concentrate demand, pressured by Swissmedic temperature-validation requirements for logistics-adjacent compute.
- Hyperscale:Purpose-built campuses exceeding 10 MW designed for cloud service provider self-operation, expanding most quickly as Microsoft, Google, and Amazon Web Services secure alpine hydropower contracts. These builds face compressed permitting timelines under cantonal environmental review processes.
- Modular:Prefabricated units factory-assembled for rapid field deployment, serving seasonal construction windows in Ticino and peripheral Mittelland regions where conventional builds face weather constraints.
Leading the category by volume: Colocation. Growing fastest: Hyperscale.
Cooling Technology:
Capital allocation splits between retrofit-constrained legacy infrastructure and greenfield purpose-built systems as GPU rack densities breach thermal thresholds.
- Air Cooling:Conventional raised-floor designs with computer room air handlers dominate installed base but face stranding risk as 50 kW rack densities exceed thermal dissipation capacity. Mittelland plateau facilities built before 2020 lack structural load and piping infrastructure for liquid cooling conversion.
- Liquid Cooling:Direct-to-chip cold plate and immersion tank configurations capture AI training and quantitative simulation workloads, climbing the fastest as Swiss pharmaceutical researchers and GPU-intensive trading operations migrate from air-cooled legacy sites. Green Datacenter and Equinix ZH5 campus deployments anchor this segment.
- Evaporative Cooling:Adiabatic systems leveraging Switzerland's alpine air dryness reduce mechanical refrigeration load, serving mid-density enterprise halls in Bern corridor facilities with favorable wet-bulb conditions.
- Green Cooling:Hydropower-driven absorption chillers and free-air cooling architectures, concentrated in Zurich-West corridor builds where renewable energy contracts enable carbon-neutral positioning for ESG-linked procurement.
Highest installed capacity: Air Cooling. Steepest expansion trajectory: Liquid Cooling.
Power Type:
Federal Office of Energy efficiency benchmarking and cantonal renewable mandates reshape power procurement strategies across facility vintages.
- Grid Power:Utility-sourced electricity from Swiss Federal Railways and cantonal utilities serves baseline load, with Zurich and Basel grid interconnection density determining site selection for latency-sensitive financial workloads.
- Renewable Energy:Direct hydropower purchase agreements from alpine utilities dominate new build economics, with Green Datacenter's long-term contracts setting the benchmark for carbon-neutral operations.
- Backup Diesel:Emergency generation sets required for Tier III/IV uptime certification, facing fuel storage regulations and emissions scrutiny under cantonal environmental permits.
- UPS:Battery and flywheel uninterruptible power supply systems bridge generator startup intervals, with lithium-ion configurations displacing legacy valve-regulated lead-acid in premium facilities.
Dominant procurement focus: Grid Power. Fastest contract growth: Renewable Energy.
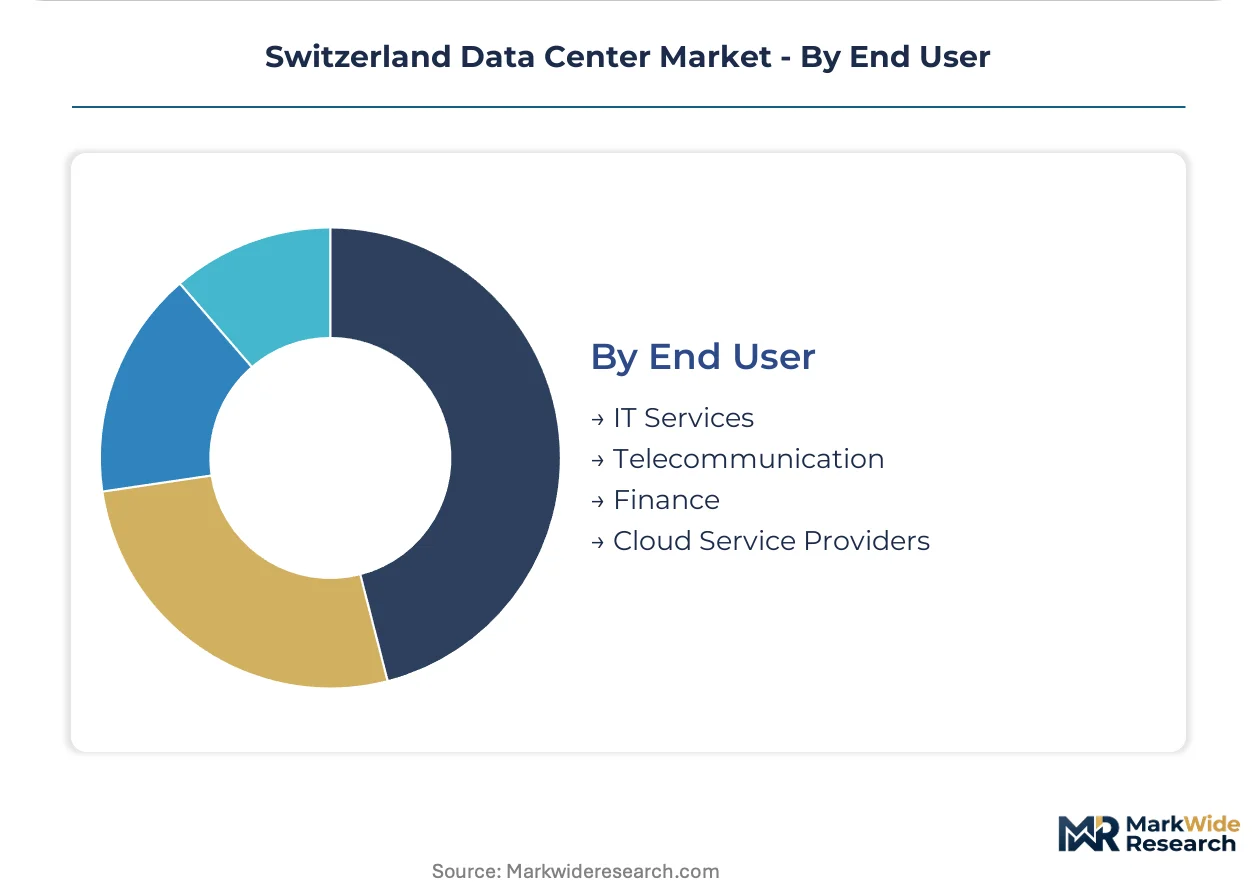
End User:
Vertical-specific regulatory frameworks fragment demand patterns across compliance, latency, and density requirements.
- IT Services:Systems integrators and managed service providers aggregate enterprise demand, concentrated in Zurich-West corridor colocation for domestic mid-market outsourcing.
- Telecommunication:Swisscom and Sunrise UPC drive edge deployment through nationwide fiber backbone integration, with 5G core infrastructure demanding distributed low-latency presence.
- Finance:Private banks, asset managers, and insurance carriers generate the highest certification burden, with FINMA operational resilience directives mandating redundant domestic processing capabilities that favor Tier IV facilities.
- Cloud Service Providers:Hyperscale operators represent the fastest-growing capacity absorption, with Microsoft Azure, Google Cloud, and AWS expanding Zurich-region availability zones under renewable power contracts.
Largest revenue share: Finance. Most rapid capacity expansion: Cloud Service Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zurich-West corridor anchors Swiss data center capacity through converging fiber density and alpine hydropower access, concentrating financial sector colocation demand within a 30-kilometer industrial band.
Zurich-West Corridor
Private banks and asset managers drive rack space absorption here, compelled by FINMA operational resilience mandates requiring redundant domestic processing capabilities. The Federal Act on Data Protection's cross-border transfer constraints elevate Tier IV facility premiums. Glattbrugg and Schlieren sub-markets host liquid-cooled campuses serving GPU-intensive quantitative trading operations.
Bern Corridor
Federal administration proximity sustains demand from government contractors and healthcare data processors. Swissmedic-adjacent pharmaceutical logistics providers require temperature-validated compute environments near distribution hubs. Ostermundigen and Ittigen industrial zones attract modular prefabricated deployments exploiting favorable cantonal permitting timelines.
Basel Region
Pharmaceutical headquarters concentration generates specialized colocation demand for clinical trial data integrity and supply chain traceability. Novartis and Roche vendor ecosystems require facilities meeting GDP (Good Distribution Practice) annex validation standards. Muttenz chemical park adjacency creates dual-use infrastructure opportunities for batch processing workloads.
Geneva
Private wealth management and commodity trading houses sustain premium pricing for latency-sensitive cross-border connectivity. French-speaking enterprise procurement favors simplified governance through single-provider contracts covering compute, network, and carbon accounting. Vernier and Meyrin zones leverage proximity to CERN research infrastructure for high-performance computing spillover demand.
Ticino
Cantonal tax incentives offset land acquisition costs for edge deployments serving Italian-speaking cross-border enterprises. Seasonal construction windows narrow conventional build feasibility, favoring factory-assembled modular units. Lugano and Bellinzona sub-markets capture Milan metro area latency requirements through Swisscom fiber backbone extension.
Switzerland Data Center Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and cooling infrastructure density, with liquid-cooled AI-ready facilities commanding 40-60% pricing premiums over legacy air-cooled assets. Market structure bifurcates between domestic operators with long-term hydropower contracts and international hyperscale entrants securing renewable energy through corporate PPAs. Three archetypes dominate: alpine-hydropower-anchored sustainability specialists, interconnection-dense financial sector incumbents, and modular edge rapid-deploy operators. Dominant competitive moves center on M&A for fiber-rich real estate and strategic partnerships with cantonal utilities for behind-the-meter renewable access.
Among sustainability-focused domestic operators, Green Datacenter exemplifies the carbon-neutral positioning archetype through secured alpine hydropower agreements. Equinix occupies the interconnection density tier at its Zurich ZH5 campus, representing financial sector colocation incumbent positioning. Swisscom anchors telecommunications-integrated edge deployment through nationwide fiber backbone control, exemplifying carrier-neutral infrastructure convergence.
| Leading Market Players |
|---|
| Green Datacenter |
| Equinix |
| STACK Infrastructure |
| Swisscom |
| NTT Data |
| Microsoft Corporation |
| Digital Realty |
| NorthC |
| Vantage Data Centers |
| Others |
Pricing and Supply Chain Analysis
Copper futures volatility on the London Metal Exchange cascades through Swiss data center construction budgets, compressing margins on electrical infrastructure and forcing tiered pricing adjustments across liquid-cooled premium facilities and legacy air-cooled assets.
Pricing Analysis
Uptime certification anchors value-based pricing tiers, with Tier IV facilities commanding substantial premiums over Tier III equivalents due to FINMA operational resilience mandates. Price differentiation separates Swissmedic-validated pharmaceutical compute environments from standard enterprise colocation. Pricing pressure stems from GPU density migration forcing premature air-cooled asset obsolescence. Mid-market enterprises exhibit highest price sensitivity, while private wealth managers prioritize compliance assurance over unit economics.
Supply Chain Analysis
Specialized cooling equipment supply rests on German and Swiss precision engineering producers for high-voltage switchgear and liquid cooling manifolds. Raw material dependencies span copper busbars, aluminum heat exchangers, and fluorinated cooling fluids. Single-source vulnerability concentrates in European transformer manufacturing. Distribution runs through integrated EPC contractors delivering turnkey builds to Zurich-West and Bern corridor sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Switzerland's data center sector occupies a technology-transition phase as direct liquid cooling displaces air-cooled legacy infrastructure across GPU-intensive workloads.
For Market Incumbents: Acquire fiber-rich real estate parcels in the Zurich-West corridor to anchor interconnection density against hyperscale entrants. Secure long-term hydropower purchase agreements with cantonal utilities to defend carbon-neutral positioning. Liquid cooling engineering talent scarcity threatens commissioning timelines; invest in Swiss Federal Institute of Technology partnerships to build specialized technician pipelines. For New Entrants and Emerging Players: Peripheral pharmaceutical logistics providers in Basel and Geneva represent underserved buyer archetypes requiring Swissmedic-adjacent temperature-validated compute. Ticino cantonal tax incentives offset land costs for modular edge deployments serving Italian-speaking cross-border enterprises. Position through single-provider contracts bundling compliance, interconnection, and carbon accounting to capture simplified procurement demand. For Investors and Strategic Acquirers: Distressed-cycle entries favor stranded air-cooled assets in the Mittelland plateau with conversion potential to hybrid liquid cooling architectures. Long-term viability hinges on renewable energy contract durations and FINMA certification renewal rates. Watch for Federal Act on Data Protection enforcement actions as inflection indicators for compliance-premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hydropower Purchase Agreement | Secures carbon-neutral positioning for ESG-linked procurement from pharmaceutical clients. |
| Liquid Cooling Retrofit | Extends asset life for air-cooled facilities facing GPU density migration pressure. |
| Swissmedic Certification Investment | Unlocks specialized colocation demand from Novartis and Roche vendor ecosystems. |
| Fiber Backbone Extension | Reduces latency for Geneva private banks requiring cross-border connectivity. |
| Modular Prefabricated Deployment | Bypasses seasonal construction constraints in Ticino and peripheral alpine regions. |
Research Methodology
Document review covered FINMA circulars, Swiss Federal Office of Energy efficiency benchmarks, and cantonal environmental permit databases, complemented by interviews with data center facility operators, Swissmedic compliance officers, and pharmaceutical procurement leads. Secondary validation drew from utility interconnection filings, hyperscaler capex disclosures, and construction permit records. Bottom-up capacity build tracking and top-down demand segmentation triangulate market sizing.
Capacity and revenue outputs reflect integrated modeling across deployment mode, cooling technology, power procurement type, and end-user vertical throughout the projection horizon. Segmentation dimensions include certification tier, rack density threshold, and cantonal regulatory cluster. CAGRs derive from facility pipeline tracking and enterprise workload migration patterns. Hydropower contract availability and GPU cluster density adoption curves constitute primary forecast inputs.
Revisions become necessary when FINMA operational resilience enforcement intensifies, hydropower pricing renegotiations accelerate, or liquid cooling equipment lead times extend beyond seasonal construction windows. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Sweden Data Center Rack Market
Data Center Infrastructure
Brazil Data Center Market
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
Italy Data Center Physical Security Market
Data Center Infrastructure
South Korea Data Center Market
Data Center Infrastructure
Cloud Network Infrastructure Market
Data Center Infrastructure
Canada Data Center Storage Market
Data Center Infrastructure
Public Cloud System Infrastructure Service Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
North America Data Center Infrastructure Management Market
Data Center Infrastructure
United Kingdom Data Center Market
Data Center Infrastructure
Underwater Data Center Market
Data Center Infrastructure
Denmark Data Center Rack Market
Data Center Infrastructure
Denmark Data Center Market
Data Center Infrastructure
Poland Data Center Market
Data Center Infrastructure
Data Center Renovation Market