
 Middle East Data Center Power Market | 2026-2036
Middle East Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Data Center Power Market Insights
Saudi Arabia's renewable energy mandates are rebalancing procurement patterns across the Middle East data center power landscape. Schneider Electric leverages its integrated EcoStruxure platform to dominate turnkey power infrastructure deployments from Riyadh to Dammam. Vertiv Group Corp. anchors critical cooling-to-power integration for hyperscale operators facing extreme ambient temperatures. Eaton Corporation competes through advanced UPS architectures designed for Gulf-specific grid instability scenarios.
Middle East data center power encompasses electrical infrastructure systems rated from 10 kVA to multi-megawatt scales, encompassing uninterruptible power supplies, diesel and gas generators, intelligent power distribution units, and software-defined energy management platforms engineered to maintain 99.999% uptime for digital workloads. UPS systems lead capital deployment as cloud service providers demand lithium-ion battery integration with 15-minute ride-through capacity. Generator sets retain structural importance despite fuel cell pilot programs, while power management software captures expanding margin pools as operators pursue predictive load balancing across hybrid renewable-diesel architectures.
SFDA guidelines on medical data sovereignty, UAE MOHAP digital health mandates, and Saudi CITC cloud localization requirements collectively tighten compliance frameworks for power infrastructure serving regulated workloads. These bodies enforce tiered redundancy standards that directly determine generator sizing, battery autonomy specifications, and renewable penetration thresholds for facility certification. Stakeholders must monitor how evolving national data sovereignty laws cascade into mandatory on-site power generation quotas before committing to long-term equipment procurement cycles.
Market Dynamics
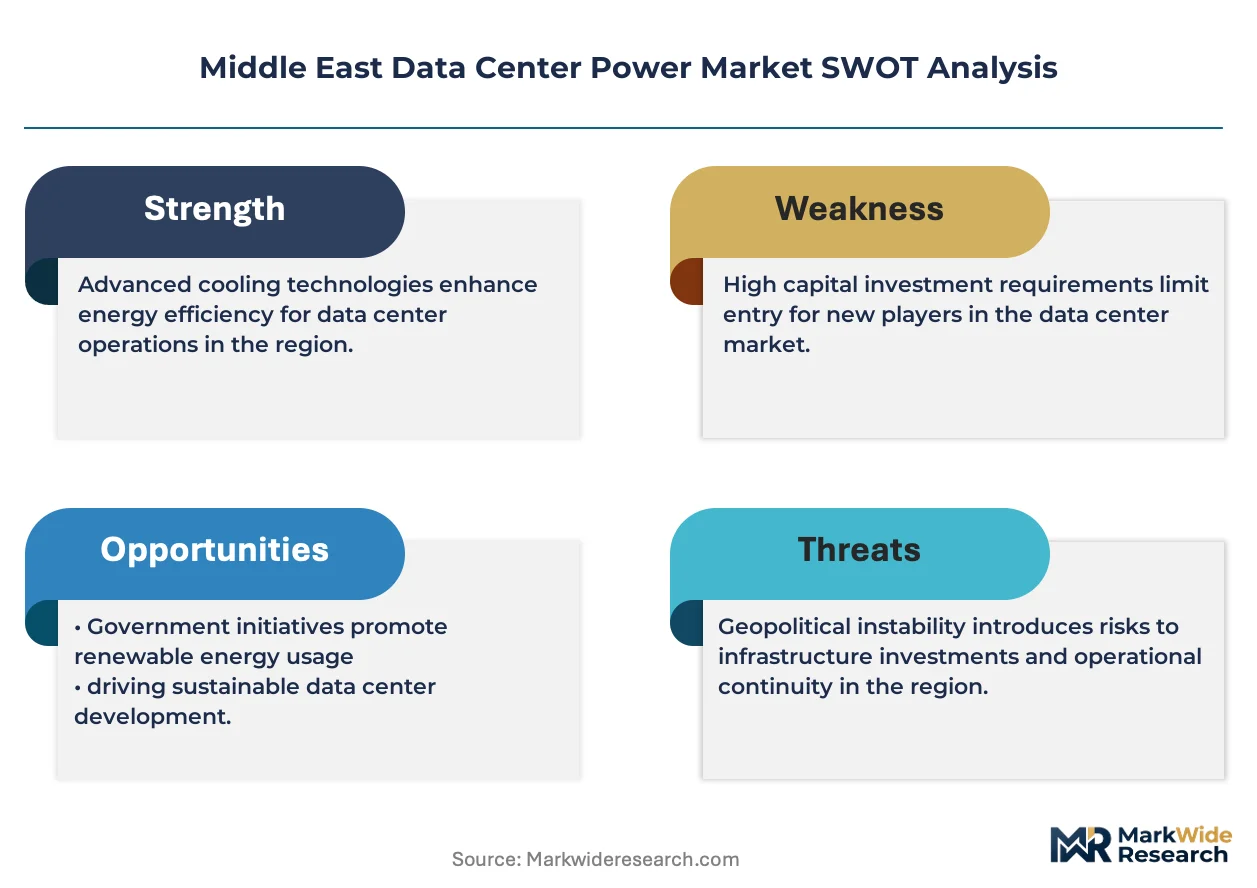
Sovereign data localization mandates across the Gulf Cooperation Council are forcing hyperscale operators to construct captive power infrastructure faster than grid interconnection timelines permit.
Growth Catalysts
- SFDA medical data sovereignty rules:Saudi Arabia's pharmaceutical regulator mandates on-premise storage for clinical trial data, requiring redundant power systems in Riyadh and Jeddah facilities.
- Hyperscale cloud expansion:Gulf-based cloud service providers are commissioning multi-megawatt facilities with 99.999% uptime SLAs, driving demand for lithium-ion integrated UPS architectures.
- UAE net-zero commitments:Dubai's clean energy targets are accelerating solar-integrated backup system deployments across new data center clusters.
Market Restraints
- Transformer supply concentration:Core electrical components for medium-voltage distribution rely on a limited set of East Asian foundries, creating 26-32 week lead times for Gulf projects.
- Diesel price volatility:Backup generator operating costs fluctuate with regional fuel subsidies, complicating ten-year total cost of ownership calculations for operators.
- Grid interconnection delays:Saudi CITC certification timelines for utility-scale connections extend facility commissioning by 8-14 months beyond power equipment installation.
Strategic Opportunities
- Kuwait and Bahrain penetration:These markets currently host under 200 MW of commissioned hyperscale capacity, presenting first-mover advantages for integrated power infrastructure providers.
- Fuel cell pilot integration:Hydrogen-ready backup systems are entering commercial validation with Saudi Aramco-backed data center operators seeking to displace diesel gensets.
- MOHAP digital health mandates:UAE Ministry of Health requirements for healthcare data residency are creating specialized demand for certified Tier III power infrastructure in Dubai Healthcare City.
Industry Challenges
- Certified commissioning engineer scarcity:Gulf markets lack sufficient technicians qualified to integrate lithium-ion battery systems with legacy diesel generator controls, extending project handover timelines.
- Hybrid renewable-diesel control complexity:Operators struggle to synchronize solar inverters with traditional UPS architectures during grid transition events, risking downtime during commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Data Center Power Market |
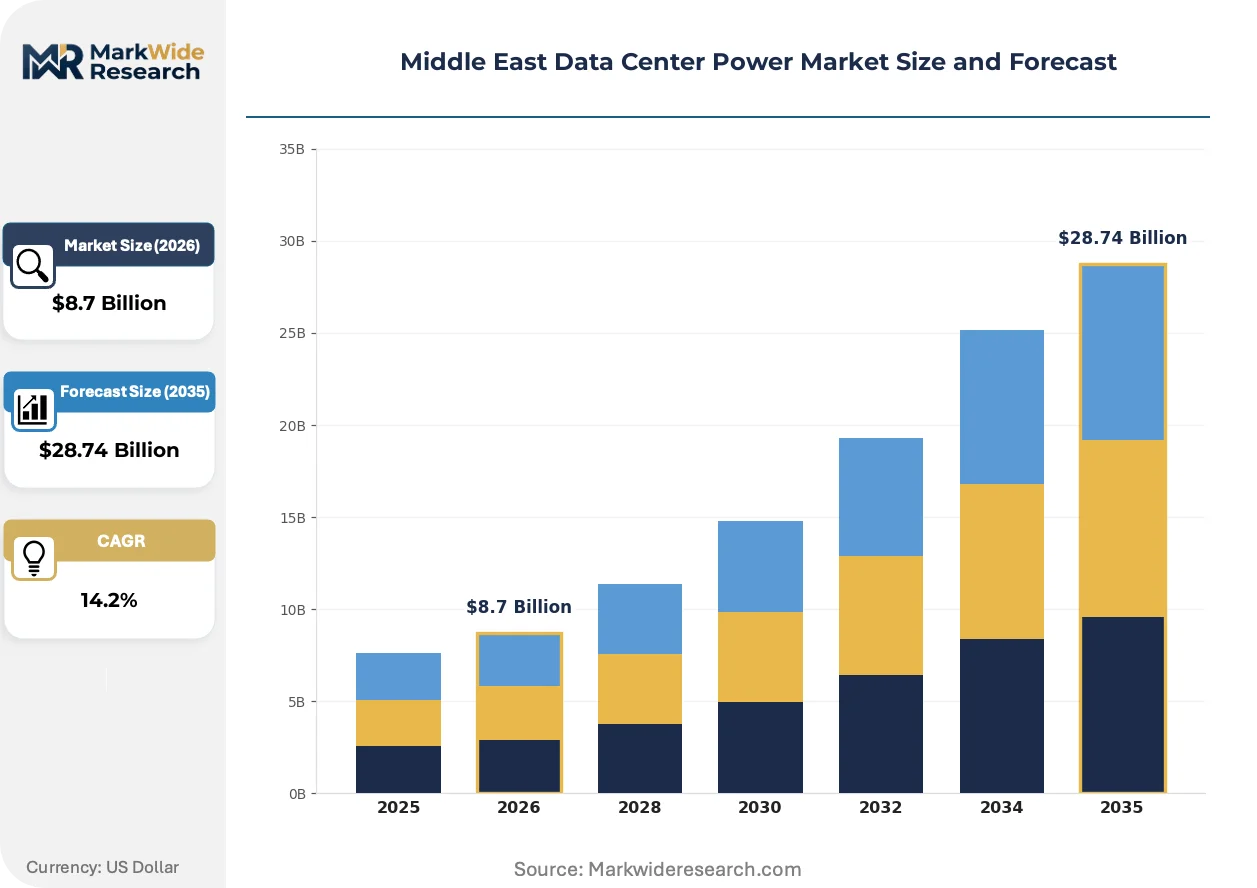
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Type: UPS, Generator, Power Distribution Unit, Power Management Software Service Type: Managed Services, Consulting, Hardware Installation, Maintenance End User: Cloud Service Providers, Telecommunications, Enterprises, Government Technology: Renewable Energy, Fuel Cells, DC Power, Smart Grid |
| Companies Covered | Schneider Electric, Vertiv Group Corp., Eaton Corporation, ABB, Delta Power Solutions, Legrand Group, Caterpillar, Generac Holdings, GE Aerospace, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Data Center Power Market Trends and Innovations
Power infrastructure architecture is pivoting from standalone diesel backup toward software-orchestrated hybrid systems that optimize across grid, renewable, and stored energy sources.
Lithium-ion battery systems with 15-minute ride-through capacity are expanding into hyperscale facilities across Riyadh and Dubai. Cloud operators are specifying these systems for all new builds rather than retrofitting existing VRLA installations. This chemistry transition is expanding into procurement specifications that now exclude lead-acid alternatives from tender documents.
SFDA guidelines on medical data sovereignty are tightening compliance frameworks for power infrastructure serving regulated workloads. These rules enforce tiered redundancy standards that directly determine generator sizing and battery autonomy specifications for facility certification. Pharmaceutical-grade data centers in Riyadh and Jeddah are responding by over-specifying N+1 power architectures beyond typical commercial requirements.
Long-term power purchase agreements with renewable developers are displacing traditional diesel-centric backup planning among Gulf hyperscale operators. Colocation providers are bundling solar-backed uptime guarantees into customer contracts, shifting risk allocation toward energy performance rather than equipment availability. This financing innovation is most visible in Dubai's Dubai South and Saudi Arabia's King Abdullah Economic City developments.
Middle East Data Center Power Market Segmentation
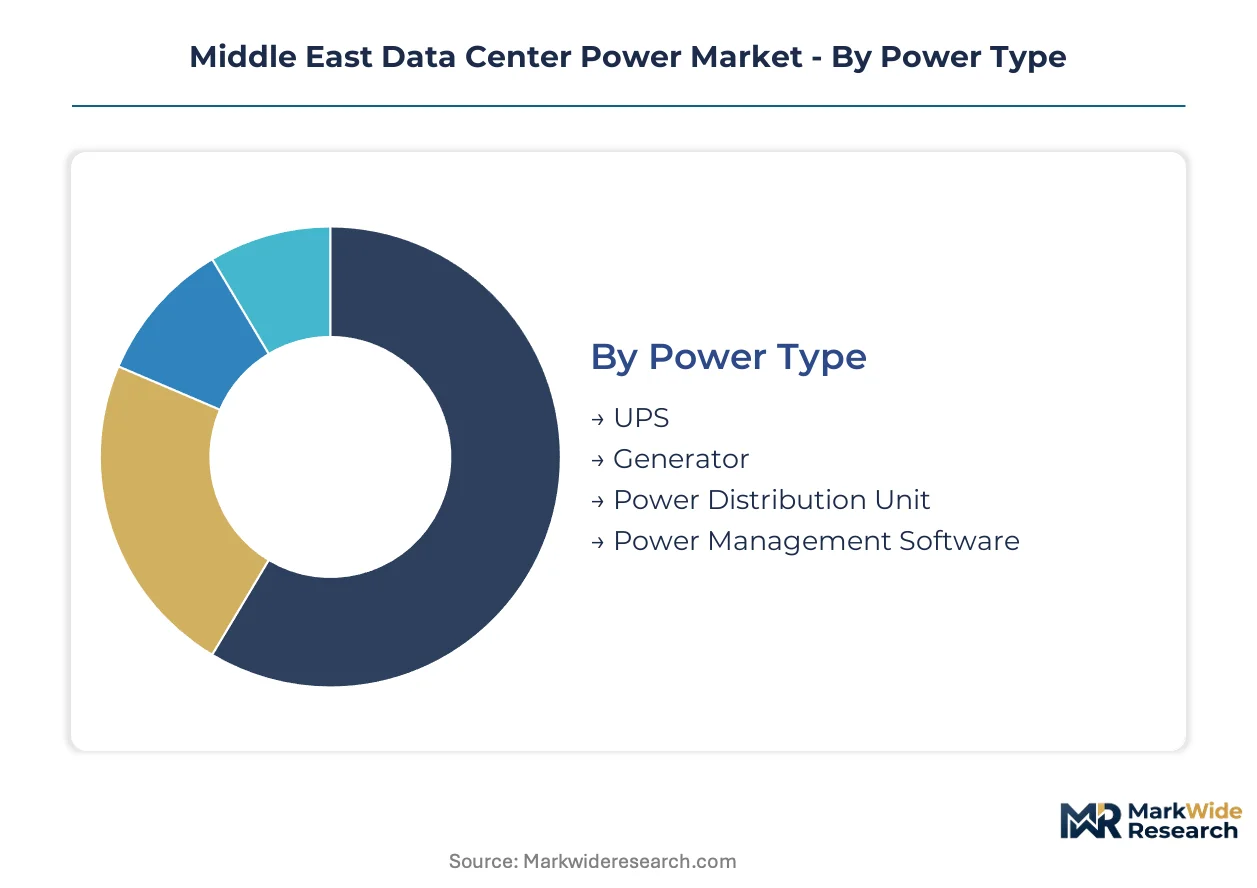
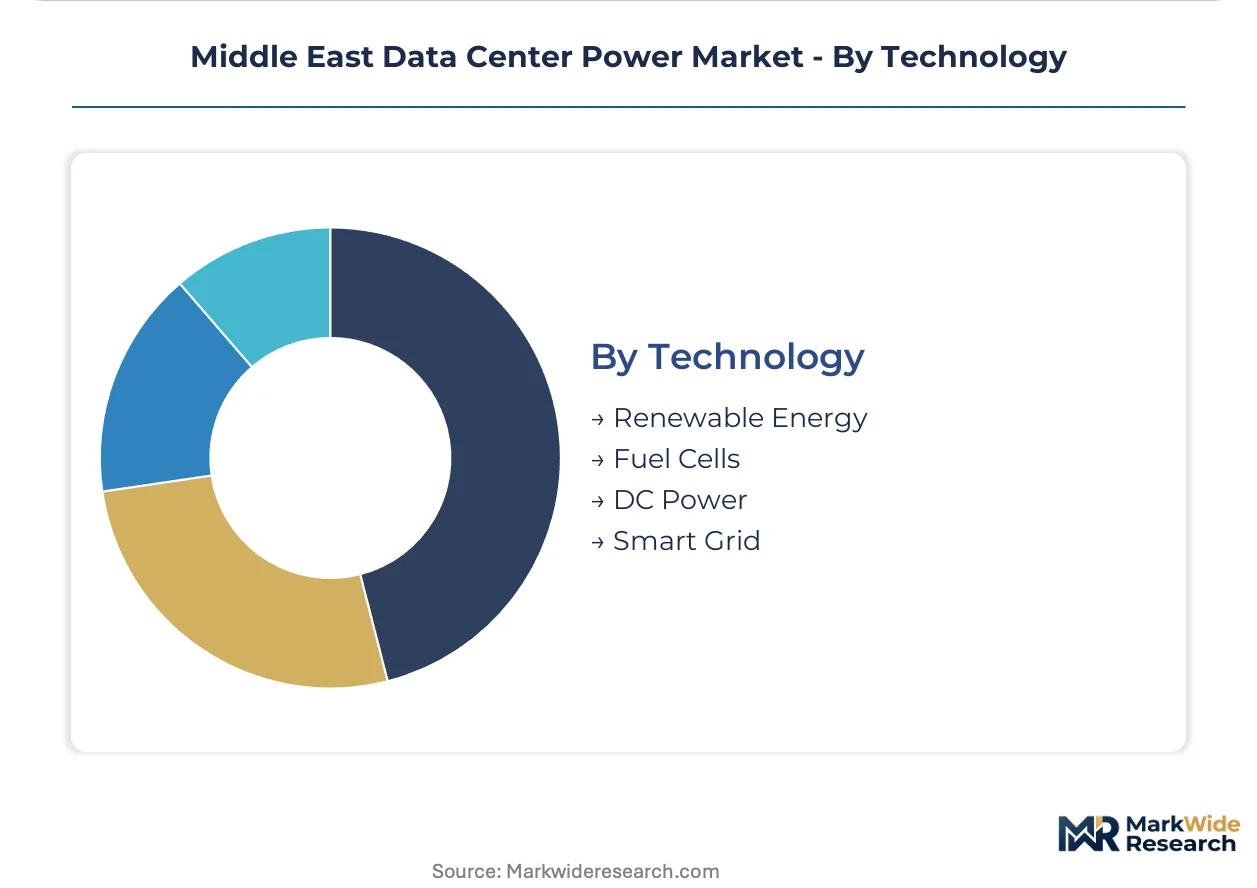
Power infrastructure procurement across the Gulf Cooperation Council fragments across four critical dimensions. Each segmentation axis carries distinct margin structures, certification requirements, and vendor qualification barriers that reshape competitive positioning.
Power Type:
Supply concentration for critical electrical components tilts procurement leverage toward integrated platform providers.
- UPS:Lithium-ion battery architectures with 15-minute ride-through capacity dominate hyperscale specifications across Riyadh and Dubai. Cloud service providers now exclude lead-acid alternatives from tender documents, compressing vendor pools to chemistry-certified suppliers.
- Generator:Diesel and gas gensets retain structural importance despite fuel cell pilots, with Saudi Aramco-backed operators testing hydrogen-ready backup systems. Grid interconnection delays extending 8-14 months reinforce on-site generation mandates.
- Power Distribution Unit:Intelligent PDUs with outlet-level monitoring capture expanding share in Tier III facilities requiring granular load visibility.
- Power Management Software:Software-defined energy orchestration platforms optimize across grid, renewable, and stored sources. Predictive load balancing commands premium pricing in hybrid renewable-diesel architectures.
Today's leader: UPS systems. Tomorrow's challenger: Power Management Software.
Service Type:
Customer procurement patterns bifurcate between capital-intensive hardware deployment and recurring operational expenditure models.
- Managed Services:Long-term power infrastructure operations contracts bundle uptime guarantees with predictive maintenance. Colocation providers in Dubai South and King Abdullah Economic City favor this model to shift operational risk.
- Consulting:Engineering services for hybrid renewable-diesel integration command scarcity premiums given certified commissioning engineer shortages across Gulf markets.
- Hardware Installation:Turnkey electrical infrastructure deployment remains volume-driven, with 26-32 week transformer lead times constraining project velocity.
- Maintenance:Post-warranty service agreements for lithium-ion battery systems require specialized technician qualifications extending project handover timelines.
Managed Services capture margin expansion fastest. Hardware Installation anchors near-term revenue concentration.
End User:
Demand concentration clusters around entities facing the strictest data sovereignty compliance deadlines.
- Cloud Service Providers:Hyperscale operators commission multi-megawatt facilities with 99.999% uptime SLAs, driving lithium-ion integrated UPS specifications. Sovereign data localization mandates force captive power construction faster than grid interconnection permits.
- Telecommunications:5G edge computing deployments require distributed power architectures with rapid deployment timelines.
- Enterprises:Pharmaceutical and financial verticals respond to SFDA guidelines and central bank mandates with over-specified N+1 power architectures.
- Government:Smart city initiatives and digital government programs create demand for certified Tier III infrastructure with renewable penetration thresholds.
Cloud Service Providers dominate capital deployment. Government verticals present steepest expansion trajectory given sovereign fund prioritization.
Technology:
Technology selection increasingly determines facility certification eligibility under evolving regulatory frameworks.
- Renewable Energy:Solar-integrated backup systems accelerate across Dubai and Saudi Arabia as net-zero commitments reshape procurement. Long-term power purchase agreements with renewable developers displace diesel-centric planning.
- Fuel Cells:Hydrogen-ready backup systems enter commercial validation with operators seeking diesel displacement. Saudi Aramco-backed pilots test commercial viability at hyperscale scale.
- DC Power:Direct current architectures gain traction in high-performance computing environments optimizing for energy efficiency.
- Smart Grid:Grid-interactive power management enables demand response participation, though CITC certification timelines delay utility-scale connection commissioning.
Renewable Energy integration leads deployment momentum. Fuel Cells represent the most significant technology transition risk for incumbent generator suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified commissioning engineers concentrate in Riyadh and Dubai, anchoring project execution capacity across the Gulf Cooperation Council. This technical workforce distribution shapes where hyperscale facilities achieve operational readiness fastest.
Saudi Arabia
SFDA medical data sovereignty rules and CITC cloud localization requirements drive redundant power system deployments. The pharmaceutical regulator mandates on-premise storage for clinical trial data. Riyadh and Jeddah facilities respond with over-specified N+1 power architectures beyond typical commercial requirements.
United Arab Emirates
MOHAP digital health mandates and Dubai's net-zero commitments reshape procurement toward solar-integrated backup systems. The Ministry of Health requirements for healthcare data residency create specialized demand in Dubai Healthcare City. Colocation providers bundle solar-backed uptime guarantees into customer contracts across Dubai South developments.
Kuwait
Under 200 MW of commissioned hyperscale capacity presents first-mover advantages for integrated power infrastructure providers. The national communications regulator enforces data localization frameworks that require captive generation. Planned facilities in Subiya and Al-Zour cluster near planned renewable generation zones.
Bahrain
Financial services data residency requirements from the central bank drive Tier III power infrastructure demand. The national cloud-first policy accelerates sovereign facility construction faster than grid interconnection permits. Manama and the Bahrain Financial Harbour district concentrate early hyperscale investment.
Qatar
Smart city initiatives and FIFA legacy digital infrastructure programs expand government vertical demand. The national cyber security agency mandates redundant power for critical data classifications. Lusail and Education City developments host certified facilities with renewable penetration thresholds.
Middle East Data Center Power Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Middle East data center power landscape. Integrated platform providers with captive manufacturing anchor turnkey deployment capacity, while specialized engineering firms capture scarcity premiums for hybrid system integration. Three archetypes dominate: full-stack infrastructure vendors, cooling-to-power integration specialists, and software-defined energy orchestration platforms. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms race to secure transformer supply allocations and certified commissioning talent.
Within the integrated platform tier, Schneider Electric anchors turnkey power infrastructure deployments with its EcoStruxure platform spanning Riyadh to Dammam. Vertiv Group Corp. occupies a position as the cooling-to-power integration specialist for hyperscale operators facing extreme ambient temperatures. Eaton Corporation exemplifies the advanced UPS architecture segment with Gulf-specific grid instability designs. These three firms represent distinct strategic positioning vectors rather than overlapping capability sets.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv Group Corp. |
| Eaton Corporation |
| ABB |
| Delta Power Solutions |
| Legrand Group |
| Caterpillar |
| Generac Holdings |
| GE Aerospace |
| Others |
Pricing and Supply Chain Analysis
Certified commissioning engineer concentration in Riyadh and Dubai creates labor-cost differentials that widen pricing-tier spreads between Gulf markets and emerging deployment zones in Kuwait and Bahrain. Premium pricing for integrated power infrastructure bundles captures scarcity premiums where qualified technicians command elevated deployment rates, while standardized hardware-only transactions compress margins in markets with shallower technical talent pools.
Pricing Analysis
Project-based contracting with outcome-linked uptime guarantees dominates hyperscale procurement across the Gulf Cooperation Council. Price differentiation separates Tier III-certified integrated deployments from standard commercial installations, with lithium-ion battery chemistry and predictive maintenance software commanding substantial premiums. Cost compression in hardware-only tiers is intensifying because transformer supply bottlenecks force vendors to absorb extended lead time risks. Cloud service providers demonstrate lowest price sensitivity given sovereign data localization deadlines, while enterprise pharmaceutical facilities facing SFDA compliance timelines accept premium positioning for expedited certification support.
Supply Chain Analysis
Direct-to-hyperscale channels handle multi-megawatt facility demand, while systems integrators serve mid-tier enterprise deployments across secondary Gulf markets. Manufacturing concentration for medium-voltage transformers and power semiconductors centers on South Korea, Japan, and select East Asian foundries. Raw material dependencies include copper busbar stock, silicon carbide substrates, and lithium carbonate for battery cell production. Single-source vulnerability in transformer winding equipment creates structural risk for project timelines. Distribution runs through authorized channel partners with CITC certification credentials in Saudi Arabia and MOHAP-registered integrators in UAE healthcare zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Dubai's established commissioning engineer density and Kuwait's 200 MW hyperscale capacity gap create divergent entry economics for integrated power infrastructure providers.
For Market Incumbents: Extend predictive maintenance software attach rates to capture recurring revenue streams and offset hardware margin compression. Deepen captive manufacturing of lithium-ion battery enclosures to reduce exposure to East Asian supply concentration. Certify additional commissioning engineers through Saudi CITC and UAE MOHAP pathways to defend deployment velocity against emerging specialized engineering firms. For New Entrants and Emerging Players: Begin with fuel cell integration engineering services for Saudi Aramco-backed operators seeking hydrogen-ready backup validation. Target Kuwait's Subiya and Al-Zour development zones where first-mover positioning remains unclaimed. Pursue consulting-led entry bundling hybrid renewable-diesel control system expertise rather than competing on hardware-only tenders. For Investors and Strategic Acquirers: Cloud service providers expanding sovereign Gulf capacity are the most active acquirer in this space, seeking captive power infrastructure capabilities to accelerate facility commissioning. Acquisition targets with certified Tier III project portfolios and established CITC relationships offer strongest five-to-ten year viability given regulatory tightening. Monitor Saudi renewable penetration mandate announcements as the critical inflection signal for diesel generator displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Fuel Cell Pilot Integration | Saudi Aramco-backed operators validate hydrogen-ready backup commercial viability at hyperscale. |
| Long-term Power Purchase Agreement | Dubai South colocation providers bundle solar-backed uptime guarantees shifting risk allocation. |
| Certified Commissioning Engineer Expansion | Schneider Electric and Vertiv secure CITC-credentialed talent pools for Riyadh-Dammam corridor dominance. |
| Lithium-ion Chemistry Transition | Cloud service providers exclude lead-acid alternatives from tender documents compressing vendor pools. |
| Managed Services Bundling | King Abdullah Economic City operators shift operational risk through predictive maintenance contracts. |
Research Methodology
Direct dialogue with data center facility directors, electrical infrastructure procurement managers, CITC certification officers, and MOHAP digital health compliance leads grounded qualitative findings. Secondary validation drew from Saudi Customs import records, UAE Ministry of Energy project registries, hyperscaler capital expenditure disclosures, and Gulf Cooperation Council renewable energy auction results. Bottom-up facility-level capacity aggregation and top-down national infrastructure planning targets were triangulated to reconcile volume estimates.
Bottom-up modeling segmented deployments across power type, service model, end-user vertical, and technology integration level. The analytical lens weighted hyperscale cloud provider demand patterns against government smart city program procurement timelines across the projection horizon. CAGRs were derived from facility commissioning schedules, grid interconnection approval velocities, and renewable penetration threshold enforcement patterns. Forecast inputs included transformer lead time trajectories and certified commissioning engineer graduation rates from Saudi technical institutes.
Several conditions sit outside the modeled scope, including abrupt diesel subsidy elimination, regional conflict disrupting East Asian component shipping lanes, and accelerated fuel cell cost parity achievement. Forecasts reflect assumptions about CITC certification timeline stability and MOHAP enforcement consistency. Periodic stress-testing of base assumptions is recommended against actual sovereign wealth fund digital infrastructure allocation announcements and renewable mandate implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Netherlands Data Center Physical Security Market
Data Center Infrastructure
Israel Data Center Rack Market
Data Center Infrastructure
Mexico Data Center Market
Data Center Infrastructure
Chile Data Center Server Market
Data Center Infrastructure
Hong Kong Data Center Server Market
Data Center Infrastructure
Bengaluru Data Center Market
Data Center Infrastructure
Japan Data Center Physical Security Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Asia-Pacific Virtual Desktop Infrastructure Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
North America Containerized Data Center Market
Data Center Infrastructure
New Zealand Data Center Physical Security Market
Data Center Infrastructure
Data Center Rack Market
Data Center Infrastructure
Vietnam Data Center Rack Market
Data Center Infrastructure
Chile Data Center Processor Market
Data Center Infrastructure
New Zealand Data Center Market