
 Middle East and Africa Containerized Data Center Market | 2026-2036
Middle East and Africa Containerized Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Containerized Data Center Market Foresight
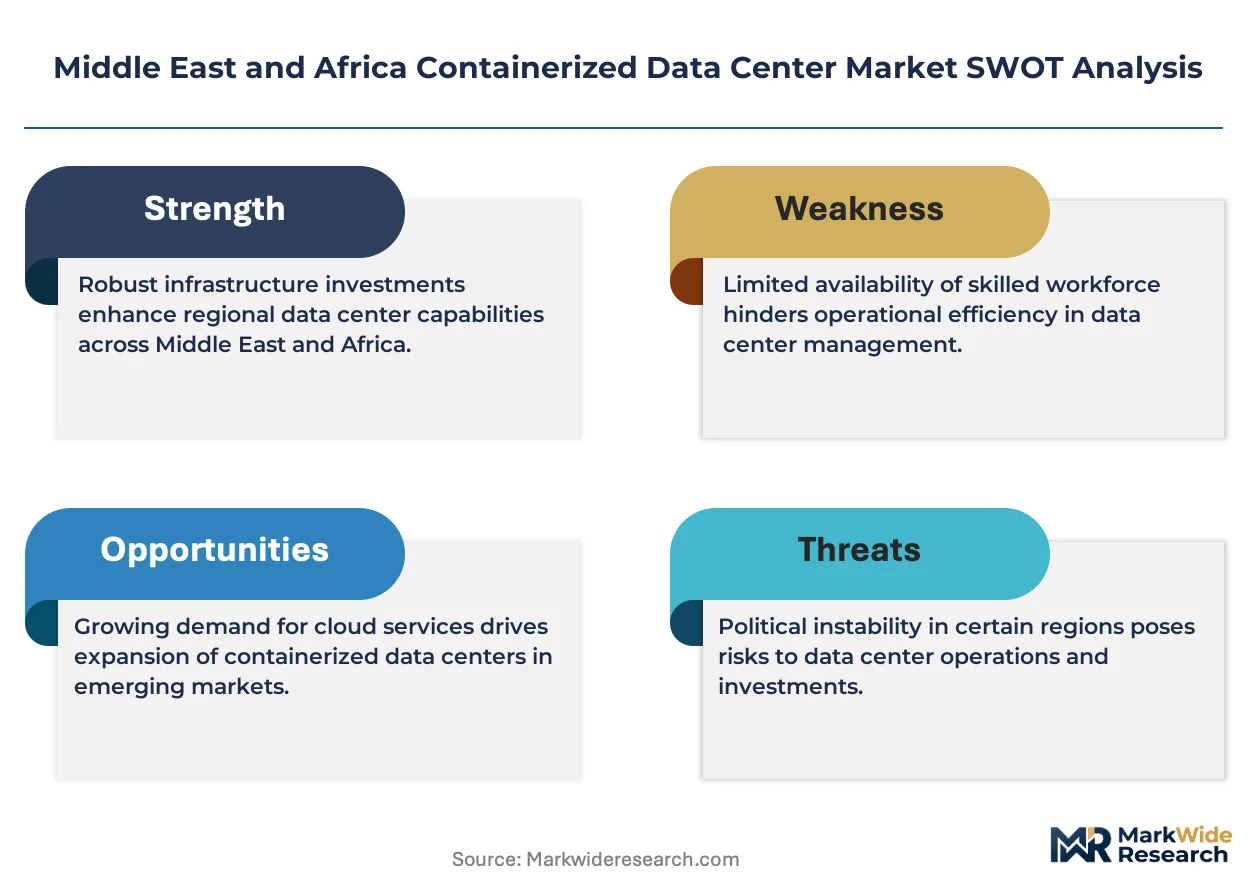
Data center engineering talent scarcity across the Middle East and Africa is bifurcating vendor strategies between turnkey international suppliers and emerging local integrators. Schneider Electric SE leverages its regional training academies in Dubai to sustain a certified installer network across Gulf markets. Huawei Technologies anchors large-scale deployments through direct government relationships in Saudi Arabia and Egypt. Vertiv competes on thermal management specialization, particularly in liquid cooling configurations for high-density workloads in arid climates.
Containerized data centers are self-contained, prefabricated modular facilities built within standardized shipping containers or purpose-built enclosures, typically incorporating power distribution units, cooling systems, and IT racks in densities ranging from 50 to 500 kW per module, designed for rapid deployment in locations lacking traditional brick-and-mortar infrastructure. Standardized and prefabricated product types dominate current procurement volumes due to shorter lead times and predictable capital expenditure profiles, while custom container configurations command premium positioning for defense and sovereign cloud applications. Managed services and hybrid deployment models are expanding fastest as enterprises seek operational outsourcing without surrendering physical control, with cooling technology selection increasingly favoring evaporative and liquid systems over air cooling to address ambient temperature extremes exceeding 45°C in Gulf summer conditions.
Saudi Arabia's Communications and Information Technology Commission and South Africa's National Regulator for Compulsory Specifications shape market access through local content requirements and electrical safety certifications, while the UAE's Telecommunications and Digital Government Regulatory Authority accelerates permitting for edge nodes supporting smart city programs. Compliance with these overlapping frameworks demands modular designs adaptable to disparate grounding, fire suppression, and energy efficiency codes. Stakeholders must monitor evolving data localization edicts and carbon disclosure rules that will determine whether containerized assets qualify for green financing instruments or face stranded investment risk.
Market Dynamics
Data sovereignty mandates across Gulf Cooperation Council states are forcing immediate infrastructure localization, compelling enterprises to deploy modular capacity domestically rather than relying on hyperscale cloud regions in Europe or Asia.
Growth Catalysts
- 5G Network Densification:Telecom operators in the United Arab Emirates and Saudi Arabia require edge nodes within 10 kilometers of end-users to meet latency specifications for autonomous systems and industrial IoT.
- National Data Management Office Directives:Saudi Arabia's regulatory framework mandates in-country data storage for government and financial sectors, eliminating cross-border processing options for sensitive workloads.
- Arid Climate Engineering:Evaporative and liquid cooling technologies purpose-built for ambient temperatures exceeding 45°C unlock deployment feasibility in previously unserviceable desert locations.
Market Restraints
- Copper and Aluminum Price Volatility:Busbar and heat exchanger material costs fluctuate with commodity markets, compressing module margins and complicating fixed-price contracting.
- Skilled Installer Concentration:Certified commissioning engineers cluster in Dubai and Johannesburg, creating 8-12 week deployment bottlenecks for projects in secondary African markets.
- Grid Interconnection Standards:Divergent electrical grounding and harmonic filtering requirements across Egypt, Nigeria, and Kenya force module redesigns that erode standardization benefits.
Strategic Opportunities
- East African Fiber Corridors:Kenya and Ethiopia's submarine cable landings create demand for transit-optimized edge nodes serving landlocked neighbors without redundant international backhaul.
- Sovereign Cloud Mandates:Defense and intelligence agencies in Morocco and Jordan seek air-gapped containerized facilities with electromagnetic shielding and biometric access controls.
- Green Financing Eligibility:Modular designs achieving PUE below 1.3 qualify for sustainability-linked loans under emerging UAE and South Africa disclosure frameworks.
Industry Challenges
- Thermal Commissioning Expertise Gap:Liquid cooling loop balancing and refrigerant handling require specialized technicians scarce outside Schneider Electric's Dubai academy and Vertiv's Johannesburg facility.
- Multi-Jurisdiction Certification Overlap:Modules deployed across Gulf Cooperation Council borders must simultaneously satisfy Saudi Arabia's Communications and Information Technology Commission, UAE's Telecommunications and Digital Government Regulatory Authority, and Qatar's national safety codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Containerized Data Center Market |
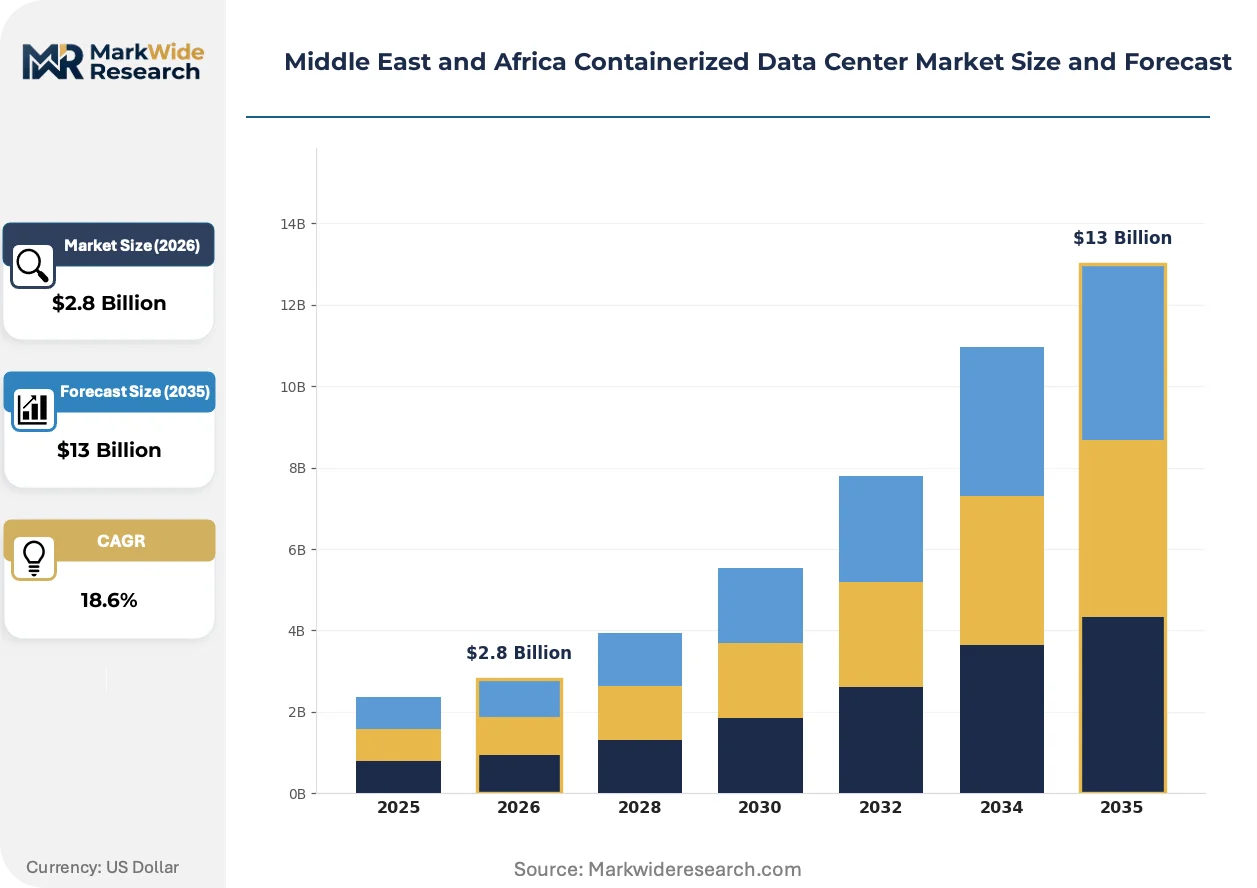
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standardized, Custom Container, Prefabricated, Integrated End User: Telecommunication, Government, BFSI, Retail Deployment Model: On-Premises, Off-Premises, Hybrid, Managed Services Cooling Technology: Air Cooling, Liquid Cooling, Evaporative Cooling, Others |
| Companies Covered | Schneider Electric SE, Huawei Technologies, Cisco Systems Inc., Microsoft Corporation, Vertiv, ABB, Delta Electronics, Hewlett Packard Enterprise, Khazna Data Centers, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Containerized Data Center Market Shifts & Advancements
Modular infrastructure architectures are converging with software-defined power and cooling management, enabling remote optimization of containerized assets deployed in minimally staffed edge locations across harsh environments.
Direct liquid cooling is displacing air-cooled designs in high-density modules targeting AI training and inference workloads. Saudi Aramco and UAE-based financial exchanges are specifying cold plate and immersion configurations for racks exceeding 30 kW. This thermal approach is displacing traditional CRAC-based architectures from the premium segment of the Gulf market.
Saudi Arabia's National Data Management Office and South Africa's National Regulator for Compulsory Specifications are tightening local content thresholds for public sector procurement. These frameworks mandate domestic assembly or component sourcing percentages that reshape supplier qualification criteria. Defense and government cloud segments are responding by qualifying regional integrators previously excluded from national infrastructure tenders.
Enterprise buyers are unbundling hardware procurement from decade-long operational contracts, favoring modular acquisition with renewable 3-5 year managed service attachments. This pattern fragments the vendor-customer relationship and elevates independent service providers in Nigeria and Kenya. Financial services and healthcare verticals in South Africa and the UAE are driving this transition fastest.
Middle East and Africa Containerized Data Center Market Segmentation
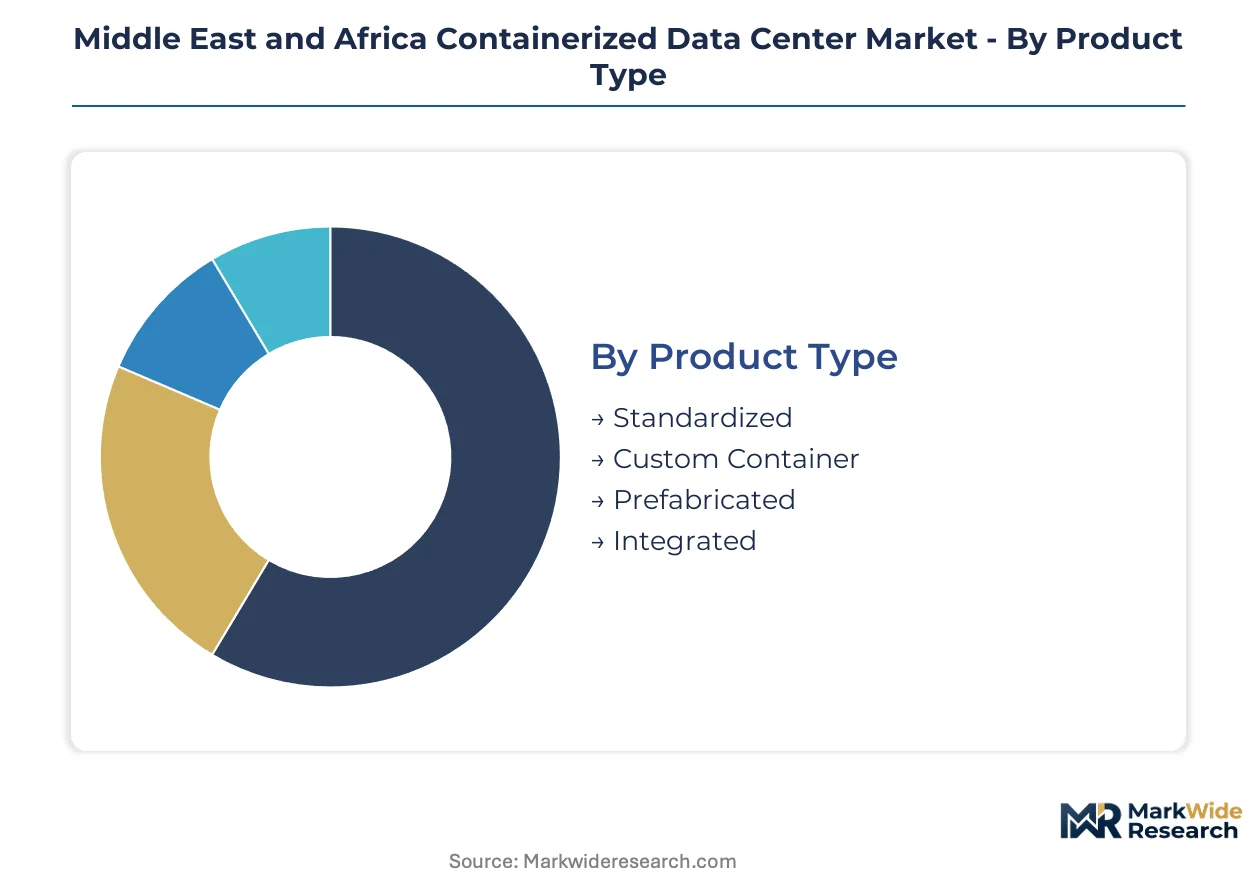
Containerized data center procurement patterns across the Middle East and Africa diverge sharply by deployment urgency, thermal constraints, and sovereignty compliance. Segmentation reveals where standardization economies clash with customization premiums.
Product Type:
Standardized modules face substitution pressure from rapidly maturing prefabricated alternatives that compress lead times without sacrificing configurability.
- Standardized:Factory-built containers with fixed 50-250 kW power densities and pre-integrated UPS, cooling, and fire suppression. Demand clusters with UAE telecom operators rolling out 5G edge nodes under tight commissioning windows imposed by the Telecommunications and Digital Government Regulatory Authority.
- Custom Container:Purpose-engineered enclosures with non-standard dimensions, electromagnetic shielding, and biometric access for defense and intelligence workloads. Saudi Arabia's National Data Management Office mandates drive procurement for air-gapped government cloud facilities.
- Prefabricated:Modular halls assembled from factory-built skids with flexible aisle configurations. South African financial institutions favor these for campus expansions in Johannesburg and Cape Town.
- Integrated:Turnkey modules bundling IT racks, power, cooling, and DCIM software from single-source vendors. Kenya's submarine cable landing stations deploy these to minimize multi-contractor coordination.
Standardized configurations retain volume leadership; custom container specifications hold the steepest expansion curve as sovereign cloud mandates proliferate.
End User:
Procurement scale tilts toward entities with capital deployment autonomy and regulatory compulsion to localize infrastructure.
- Telecommunication:Mobile network operators deploying edge nodes within 10 kilometers of subscribers to meet 5G latency specifications. Etisalat and stc Group anchor regional demand across UAE and Saudi Arabia.
- Government:Defense ministries and civilian agencies requiring data residency compliance. Morocco's intelligence services and Egypt's administrative modernization programs specify containerized facilities with sovereign accreditation.
- BFSI:Banks and insurers subject to financial sector data localization rules. South Africa's National Regulator for Compulsory Specifications shapes procurement through electrical safety and business continuity certifications.
- Retail:Omnichannel operators deploying edge capacity for inventory systems and customer analytics. Nigerian supermarket chains and UAE mall operators represent emerging demand.
Telecommunication verticals dominate current procurement volumes; government segments are expanding most quickly as national security frameworks harden.
Deployment Model:
Operational control preferences are fragmenting vendor-customer relationships across the ownership spectrum.
- On-Premises:Customer-owned and operated modules on dedicated real estate. Saudi Aramco and UAE sovereign wealth funds favor this for sensitive hydrocarbon and financial data workloads.
- Off-Premises:Colocated containers within multi-tenant facilities. South African enterprises use these to bypass grid reliability constraints in secondary cities.
- Hybrid:Split workloads across owned modules and third-party capacity. Kenyan enterprises deploy this model to balance sovereignty requirements with capital efficiency.
- Managed Services:Vendor-operated modules with renewable operational contracts. Nigerian and UAE healthcare verticals are shifting procurement toward this structure.
On-premises deployment retains the largest installed base; managed services are climbing the fastest as skills scarcity drives operational outsourcing.
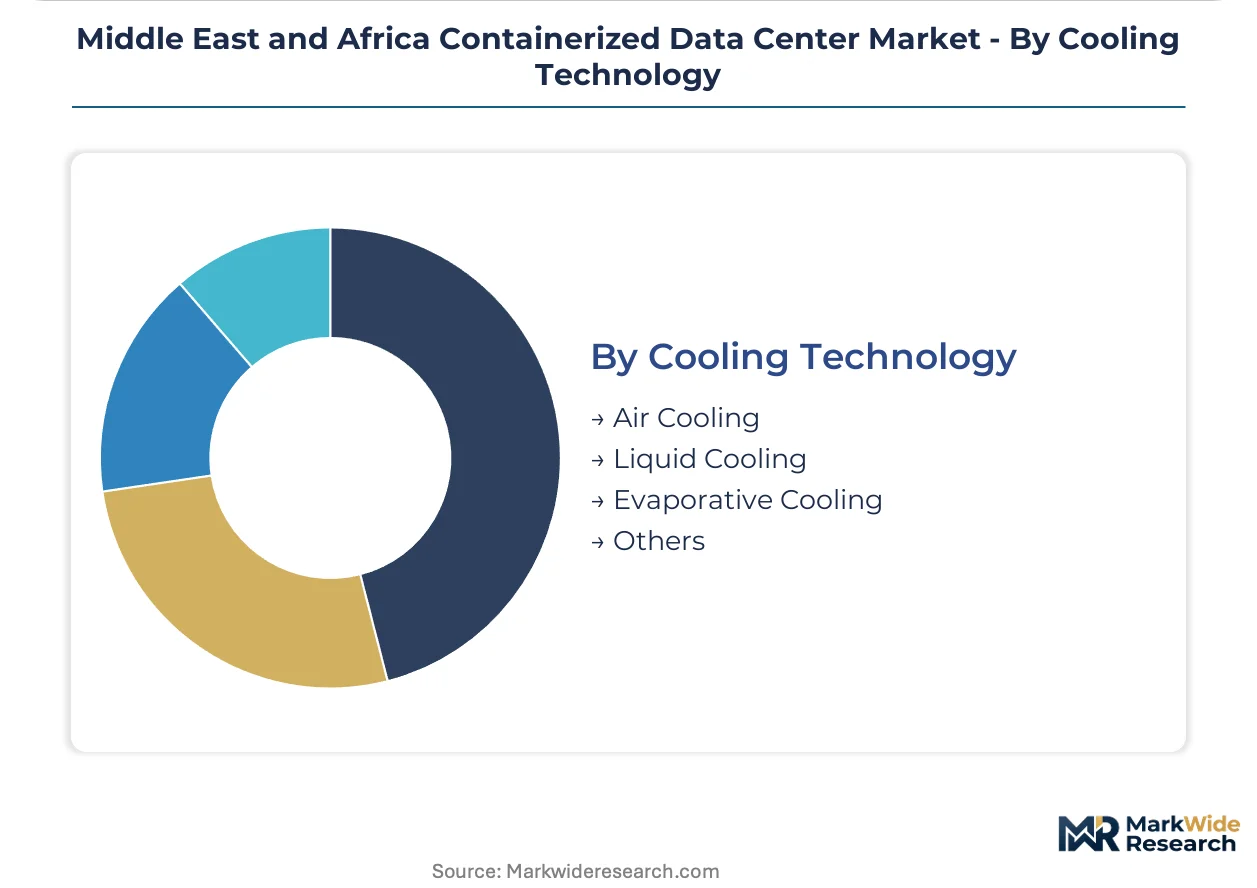
Cooling Technology:
Thermal engineering selection directly determines deployment feasibility across ambient temperature extremes exceeding 45°C.
- Air Cooling:Traditional CRAC and CRAH units with DX or chilled water loops. Limited to low-density workloads in climate-controlled environments or seasonal operation in temperate African highlands.
- Liquid Cooling:Cold plate and immersion configurations for racks exceeding 30 kW. Saudi Aramco and UAE financial exchanges specify these for AI training clusters.
- Evaporative Cooling:Adiabatic and wet-bulb systems exploiting low humidity in Gulf climates. Dubai and Abu Dhabi edge nodes deploy these for 40-50% efficiency gains over air cooling.
- Others:Phase-change materials and thermosiphon loops for remote sites lacking water access. Ethiopian and Djibouti transit nodes experiment with these architectures.
Evaporative cooling commands the largest share of new Gulf deployments; liquid cooling is gaining share fastest as AI workload densities escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE's Telecommunications and Digital Government Regulatory Authority anchors the Middle East containerized data center landscape through accelerated permitting frameworks for edge infrastructure. Saudi Arabia's National Data Management Office and South Africa's National Regulator for Compulsory Specifications shape parallel compliance pathways across the region.
United Arab Emirates
Etisalat and du drive 5G edge node deployment across Dubai and Abu Dhabi to meet sub-10-kilometer latency specifications for autonomous systems. The Telecommunications and Digital Government Regulatory Authority compresses commissioning timelines for smart city infrastructure. Dubai Internet City clusters prefabricated module integrators serving African transit markets.
Saudi Arabia
stc Group and Saudi Aramco anchor demand for liquid-cooled configurations exceeding 30 kW per rack for AI training clusters. The National Data Management Office mandates in-country data storage for government and financial workloads. Riyadh and the Eastern Province concentrate sovereign cloud deployments with electromagnetic shielding specifications.
South Africa
Johannesburg and Cape Town financial institutions favor prefabricated modular halls for campus expansions subject to business continuity certifications. The National Regulator for Compulsory Specifications enforces electrical safety and local content thresholds for public procurement. Grid reliability constraints in secondary cities drive colocation container adoption.
Egypt
Administrative modernization programs specify containerized facilities for government cloud migration. The country's national telecommunications regulator shapes market access through divergent electrical grounding requirements that force module redesigns. Cairo anchors deployment concentration for intelligence and defense workloads with biometric access controls.
Kenya
Submarine cable landings at Mombasa create demand for transit-optimized edge nodes serving Ethiopia and landlocked neighbors without redundant international backhaul. Hybrid deployment models balance sovereignty requirements with capital efficiency for enterprises. Nairobi clusters managed service providers offering renewable operational contracts.
Middle East and Africa Containerized Data Center Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa containerized data center market. The vendor base concentrates around three strategic tiers: international turnkey suppliers with regional training infrastructure, government-aligned technology providers with direct state relationships, and emerging local integrators qualifying for national content mandates. Competitive positioning sharpens through portfolio diversification into thermal management specializations and geographic expansion via certified installer networks.
Among France-based electrical infrastructure specialists, Schneider Electric SE exemplifies the turnkey international supplier archetype through regional training academy investments. Vertiv occupies a position within the thermal management specialist tier, while Huawei Technologies anchors the government-aligned technology provider segment. These three companies represent the dominant competitive archetypes shaping procurement patterns across Gulf Cooperation Council markets.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Huawei Technologies |
| Cisco Systems Inc. |
| Microsoft Corporation |
| Vertiv |
| ABB |
| Delta Electronics |
| Hewlett Packard Enterprise |
| Khazna Data Centers |
| Others |
Supply & Pricing Matrix
Factory utilization rates above 80% at Dubai-based module assembly plants compress lead times for Gulf telecom operators while establishing price floors that secondary African markets struggle to match. Saudi Arabia's National Data Management Office mandates and South Africa's local content thresholds fragment procurement scale, preventing the volume discounts that would otherwise flow from standardized designs.
Pricing Analysis
Price spreads between UAE hub deliveries and Nigerian secondary-city deployments exceed 25% due to logistics fragmentation and import duty layering. Three-tier pricing structure across premium liquid-cooled configurations, standard evaporative modules, and economy air-cooled units reflects certification grade and after-sales bundling differentiation. Cost compression in the standard tier is intensifying because copper busbar and aluminum heat exchanger commodity volatility erodes fixed-price contracting feasibility. Telecom operators in Saudi Arabia and the UAE exhibit lowest price sensitivity due to 5G rollout urgency; Kenyan transit-node buyers face acute budget constraints.
Supply Chain Analysis
Inventory cycles stretching 16-20 weeks for liquid cooling components constrain deployment velocity for AI training clusters ordered by Saudi Aramco and UAE financial exchanges. Manufacturing concentrates in China for power distribution units, Germany for precision cooling skids, and the UAE for final module integration. Raw material dependencies span copper busbar, aluminum heat exchangers, and lithium-ion UPS batteries. Single-source vulnerability in refrigerant supply chains for direct liquid cooling systems poses qualification risks. Distribution runs through certified installer networks anchored by Schneider Electric's Dubai academy and Vertiv's Johannesburg facility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containerized data center adoption across the Middle East and Africa sits in early-cycle expansion, with data sovereignty mandates from Saudi Arabia's National Data Management Office and comparable regulators accelerating localization faster than hyperscale cloud buildouts can satisfy demand.
For Market Incumbents: Fortify certified installer network density beyond Dubai and Johannesburg to preempt deployment bottlenecks in secondary African markets. Deepen backward integration into liquid cooling component production to offset copper and aluminum price volatility that compresses module margins. Strengthen direct government relationships in Saudi Arabia and Egypt where procurement favors state-aligned technology providers over turnkey international suppliers.
For New Entrants and Emerging Players: Lead with sovereign cloud compliance specialization targeting Morocco and Jordan defense agencies requiring electromagnetic shielding and biometric access controls. Exploit local content qualification gaps in South Africa and Nigeria where national integrators remain underdeveloped against international turnkey suppliers. Position through managed service attachments rather than hardware-only procurement to capture renewable operational contract revenue streams.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed service providers with renewable 3-5 year operational contracts in Nigerian and UAE healthcare verticals. Long-term viability over the projection horizon rests on thermal management specialization as AI workload densities escalate liquid cooling penetration. Acquisition targets should demonstrate certified installer network scale or direct government procurement relationships. Monitor PUE certification thresholds under emerging UAE and South Africa green financing frameworks as inflection indicators for stranded asset risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Specialization | Cold plate and immersion configurations unlock AI training deployments for Saudi Aramco and UAE exchanges. |
| Certified Installer Network Expansion | Regional training academies reduce 8-12 week deployment bottlenecks in secondary African markets. |
| Sovereign Cloud Compliance Qualification | Air-gapped facilities with electromagnetic shielding capture Morocco and Jordan defense procurement. |
| Managed Service Attachment Development | Renewable operational contracts fragment vendor-customer relationships and elevate independent service providers. |
| Green Financing Certification Pathway | PUE below 1.3 unlocks sustainability-linked loans under UAE and South Africa disclosure frameworks. |
Research Methodology
Operator-level perspectives from data center engineering directors, telecom infrastructure procurement officers, government cloud program managers, and modular facility integrators anchored the qualitative base. Primary interview insights triangulated against secondary validation from SEC filings of electrical infrastructure suppliers, hyperscaler capex disclosures, and customs records of containerized module imports. Regulatory documentation from Saudi Arabia's Communications and Information Technology Commission, UAE's Telecommunications and Digital Government Regulatory Authority, and South Africa's National Regulator for Compulsory Specifications supplemented demand-side calibration. Bottom-up project pipeline tracking and top-down addressable market sizing converged through iterative reconciliation.
Sensitivity analysis tested deployment velocity assumptions against commodity price volatility scenarios and regulatory timeline slippage. The analytical framework segmented across product type, end user vertical, deployment model, cooling technology, and geographic regulatory cluster throughout the forecast period. CAGRs derived from logistic diffusion curves fitted to sovereign mandate implementation schedules and 5G network densification roadmaps. Forecast inputs incorporated evaporative cooling efficiency gains in Gulf climates and liquid cooling penetration rates for AI workload densities.
The analysis sits within stated boundaries; outcomes outside sustained copper and aluminum price stability or accelerated data localization enforcement would require recalibration. Forecasts reflect assumptions regarding certified installer network expansion velocity and green financing framework adoption rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Monitoring Systems Market
Data Center Infrastructure
Austria Data Center Power Market
Data Center Infrastructure
Global Data Center Accelerator Market
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
IT Infrastructure Market
Data Center Infrastructure
Data Center Power Market
Data Center Infrastructure
Global Hyper-Converged Infrastructure Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Mini Data Center Market
Data Center Infrastructure
Brazil Data Center Market
Data Center Infrastructure
Belgium Data Center Market
Data Center Infrastructure
China Data Center Rack Market
Data Center Infrastructure
Ireland Data Center Market
Data Center Infrastructure
Chicago Data Center Market
Data Center Infrastructure
London Data Center Market
Data Center Infrastructure
Norway Data Center Storage Market