
 Switzerland Data Center Construction Market | 2026-2036
Switzerland Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Data Center Construction Market Insights
Capital-intensity divergence between hyperscale-ready builders and traditional facility contractors is unwinding competitive stability in Swiss data center construction. Arup leverages its integrated engineering-architecture model to anchor complex master planning for multi-tenant campuses. Implenia competes through its domestic civil infrastructure dominance, extending tunneling and shell expertise into subterranean cooling configurations. Gruner specializes in geotechnical and environmental risk assessment, sustaining premium positioning on Alpine-constrained sites where seismic and hydrological factors complicate foundation design.
Switzerland data center construction encompasses the engineering, procurement, and physical assembly of mission-critical facilities housing servers, storage, and networking equipment, typically requiring power densities exceeding 15 kW per rack and precision cooling within ±1°C tolerance to maintain uptime. These structures serve as compute and data storage nodes for financial services, pharmaceutical research, and cloud platforms demanding jurisdictional data sovereignty. Hyperscale data centers command the largest capital allocation pools due to multi-hundred-megawatt power commitments and decade-long lease structures. Modular data centers represent the fastest-growing product type as enterprises and edge operators seek deployable capacity with reduced on-site construction duration. Cooling solutions technology captures disproportionate engineering attention because alpine water availability and seasonal temperature variation create unique free-cooling economics unavailable in warmer European markets.
Swissmedic guidelines on pharmaceutical data integrity, FINMA operational resilience requirements for financial institutions, and SIA Swiss engineering standards collectively elevate facility certification thresholds, filtering out contractors lacking documented critical infrastructure experience. The EU Green Deal alignment through Switzerland's bilateral agreements imposes progressive carbon intensity benchmarks on facility power sourcing, directing procurement toward renewable-backed supply contracts and on-site thermal reuse systems. Stakeholders must monitor evolving cantonal zoning restrictions on power grid interconnection capacity, as utility approval timelines increasingly determine project feasibility ahead of construction mobilization.
Market Dynamics
Liquid cooling infrastructure is forcing a capital reallocation across Swiss data center construction as power densities breach 30 kW per rack thresholds, rendering traditional air-handling designs economically unviable for new hyperscale commitments.
Growth Catalysts
- EU Green Deal alignment:Bilateral agreements impose progressive carbon intensity benchmarks on facility power sourcing, directing procurement toward renewable-backed supply contracts and on-site thermal reuse systems.
- Pharmaceutical compute demand:Swissmedic guidelines on data integrity for clinical trial storage mandate sovereign hosting, pulling specialized facility investment toward Basel and Zurich corridors.
- Free-cooling economics:Alpine water availability and seasonal temperature variation create unique thermal management advantages unavailable in warmer European markets, attracting cloud provider regional hub placement.
Market Restraints
- Utility interconnection bottlenecks:Cantonal zoning restrictions on grid capacity extension create approval timelines that increasingly determine project feasibility ahead of construction mobilization.
- Specialized contractor scarcity:SIA Swiss engineering standards and FINMA operational resilience requirements filter out builders lacking documented critical infrastructure experience, compressing the qualified vendor pool.
- Seismic foundation complexity:Alpine-constrained sites require geotechnical risk assessment capabilities that extend project development cycles and elevate engineering contingency reserves.
Strategic Opportunities
- Subterranean cooling configurations:Tunneling expertise from domestic civil infrastructure projects transfers into data center shell construction, enabling novel thermal management architectures.
- Edge node deployment:Modular data centers address enterprise demand for deployable capacity with reduced on-site construction duration, particularly around Geneva's financial services corridor.
- Thermal reuse integration:District heating interconnection mandates in select cantons create revenue streams from waste heat recovery, improving project returns beyond pure colocation leasing.
Industry Challenges
- Precision cooling certification timelines:Achieving ±1°C tolerance validation for mission-critical uptime guarantees extends commissioning phases and defers revenue recognition.
- Multi-tenant security segmentation:FINMA operational resilience requirements for financial institutions impose physical and logical separation standards that complicate shell design for multi-tenant campuses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Data Center Construction Market |
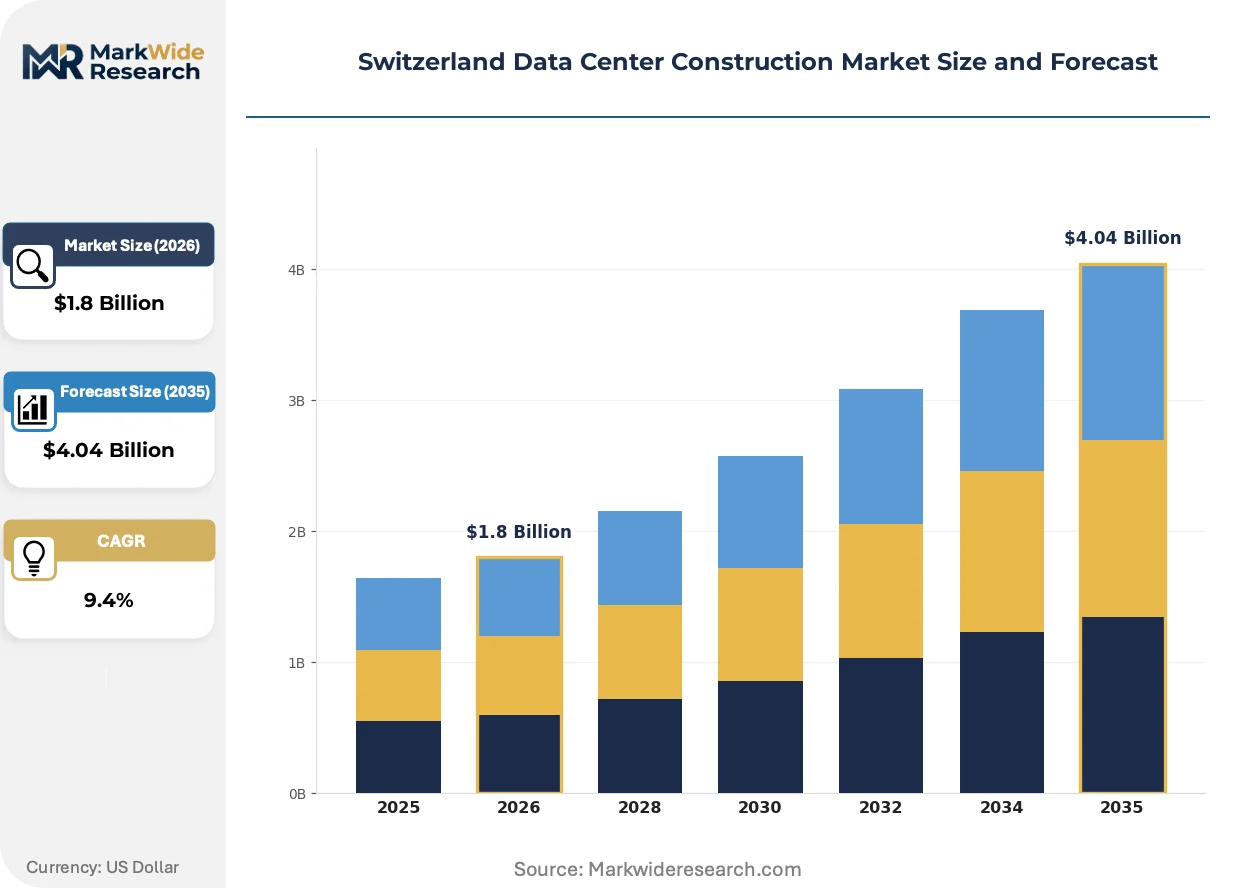
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation Facilities, Hyperscale Data Centers, Modular Data Centers, Edge Data Centers Technology: Cooling Solutions, Power Management, Network Infrastructure, Fire Detection End User: Cloud Service Providers, Enterprises, Telecom Operators, Government Agencies Service Type: Design & Build, Facility Management, Maintenance Services, Consultancy |
| Companies Covered | Arup, DPR Construction, Legrand, AECOM, Basler & Hofmann, Gruner, Turner & Townsend, Webuild Group, Implenia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Data Center Construction Market Trends and Innovations
Direct-to-chip liquid cooling architectures are supplanting traditional facility designs as the dominant engineering paradigm, compressing mechanical infrastructure footprints and altering contractor capability requirements across Swiss projects.
Immersion cooling systems using dielectric fluids are supplanting rear-door heat exchangers in high-performance computing deployments. Hyperscale operators deploying AI training clusters in Zurich and Geneva corridors are specifying tank-based architectures for racks exceeding 50 kW density. This transition is supplanting conventional CRAC unit procurement with specialized fluid management and chemical handling contracts, reshaping vendor qualification criteria.
Switzerland's alignment with EU F-Gas Regulation through bilateral agreements restricts synthetic refrigerant deployment in cooling systems, accelerating natural refrigerant adoption and ammonia-based chiller investment. Facility operators must now document phasedown compliance in environmental impact assessments submitted to cantonal authorities. Pharmaceutical and financial services tenants—both heavily represented in Swiss facility demand—are incorporating F-Gas compliance into green lease clauses, transferring regulatory risk to builders.
Build-to-suit contracting models are displacing speculative development for hyperscale commitments, compressing developer risk profiles and lengthening pre-construction engagement timelines. Cloud providers now require 12-18 month design collaboration periods before groundbreaking, shifting revenue recognition patterns for construction firms. This behavioral shift concentrates most visibly in Zurich's Glattbrugg corridor, where Microsoft, Google, and Amazon Web Services have established sequential facility footprints with consistent design specifications.
Switzerland Data Center Construction Market Segmentation
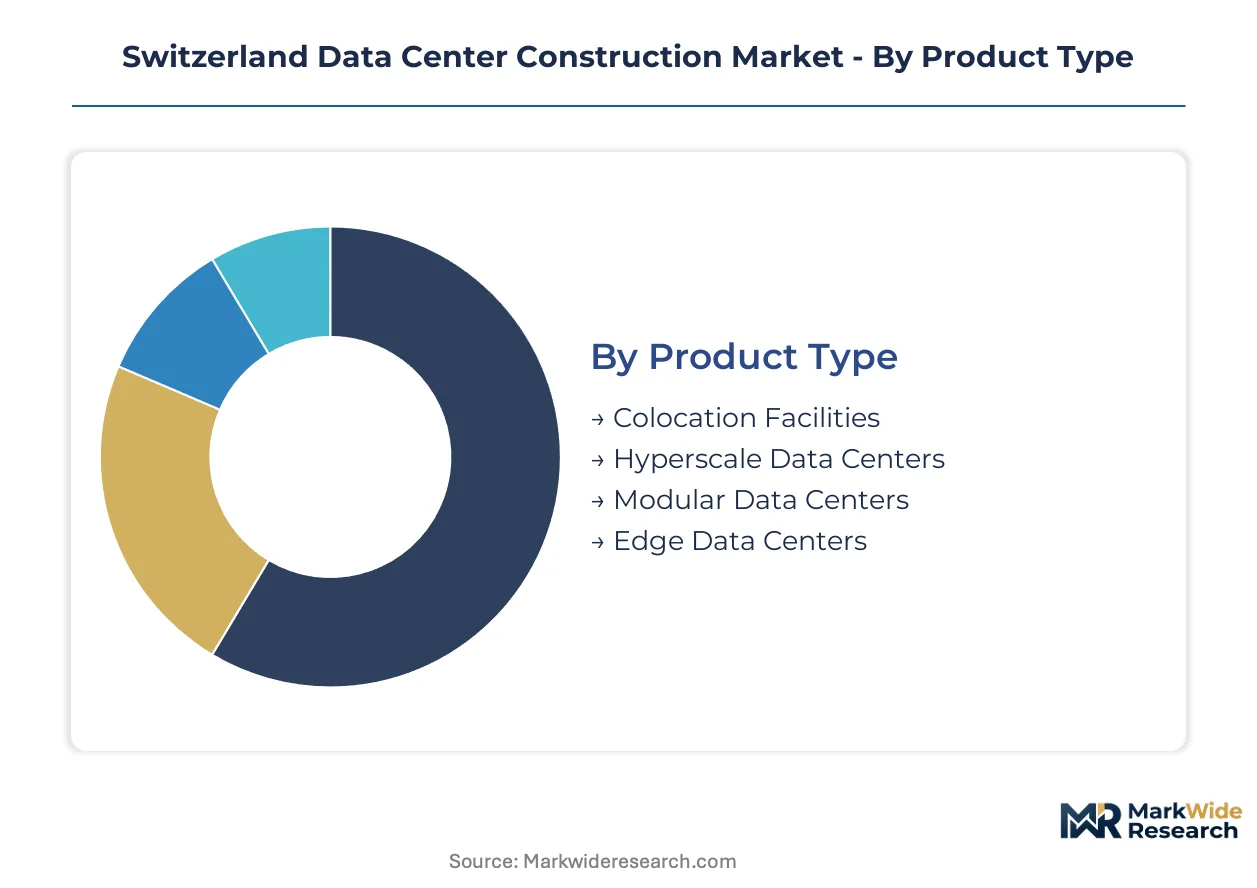
Swiss data center construction segments diverge sharply in capital intensity and regulatory exposure, with hyperscale commitments demanding decade-long planning horizons while modular deployments compress procurement cycles. Understanding these structural divides illuminates where contractor capabilities must stretch versus where standardization dominates.
Product Type:
Hyperscale and edge configurations exert the strongest substitution pressure on traditional enterprise builds, as cloud providers internalize capacity planning and enterprises downsize owned footprints.
- Hyperscale Data Centers:Multi-hundred-megawatt facilities with decade-long lease structures and sovereign power commitments. Microsoft, Google, and Amazon Web Services concentrate demand in Zurich's Glattbrugg corridor, where FINMA proximity and fiber latency to European hubs create locational premiums.
- Modular Data Centers:Deployable capacity units with reduced on-site construction duration. Enterprises and edge operators around Geneva's financial services corridor adopt these for rapid capacity scaling without cantonal zoning delays.
- Colocation Facilities:Multi-tenant shell construction with physical and logical security segmentation for Swissmedic and FINMA compliance.
- Edge Data Centers:Distributed compute nodes positioned for sub-10 millisecond latency to population centers.
Hyperscale Data Centers retain volume leadership; Modular Data Centers hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium liquid-cooling engineering from commoditized power distribution, with cooling solutions commanding disproportionate engineering attention.
- Cooling Solutions:Direct-to-chip liquid cooling and immersion systems using dielectric fluids for racks exceeding 50 kW density. Alpine water availability and seasonal temperature variation create free-cooling economics unavailable in warmer European markets.
- Power Management:Uninterruptible power supply and switchgear integration for 15 kW-plus rack densities. Cantonal utility interconnection bottlenecks increasingly determine procurement specifications ahead of equipment selection.
- Network Infrastructure:Fiber latency optimization and cross-connect architecture for multi-tenant campuses.
- Fire Detection:Early warning systems with Swiss SIA engineering standard certification for mission-critical uptime guarantees.
Cooling Solutions captures the premium engineering tier; Power Management anchors baseline procurement volume.
End User:
Customer type fragmentation splits the market between sovereign-hosting mandates and speculative capacity plays, with regulatory filters determining viable contractor relationships.
- Cloud Service Providers:Build-to-suit contracting with 12-18 month design collaboration periods before groundbreaking. EU Green Deal alignment through bilateral agreements imposes progressive carbon intensity benchmarks on facility power sourcing.
- Enterprises:Pharmaceutical and financial services tenants incorporating F-Gas compliance into green lease clauses. Swissmedic guidelines on data integrity for clinical trial storage mandate sovereign hosting in Basel and Zurich corridors.
- Telecom Operators:Network edge positioning for 5G latency requirements and distributed compute architectures.
- Government Agencies:Federal and cantonal data sovereignty requirements with classified facility security standards.
Cloud Service Providers drive the largest capital allocation pools; Enterprises exhibit the most stringent certification thresholds.
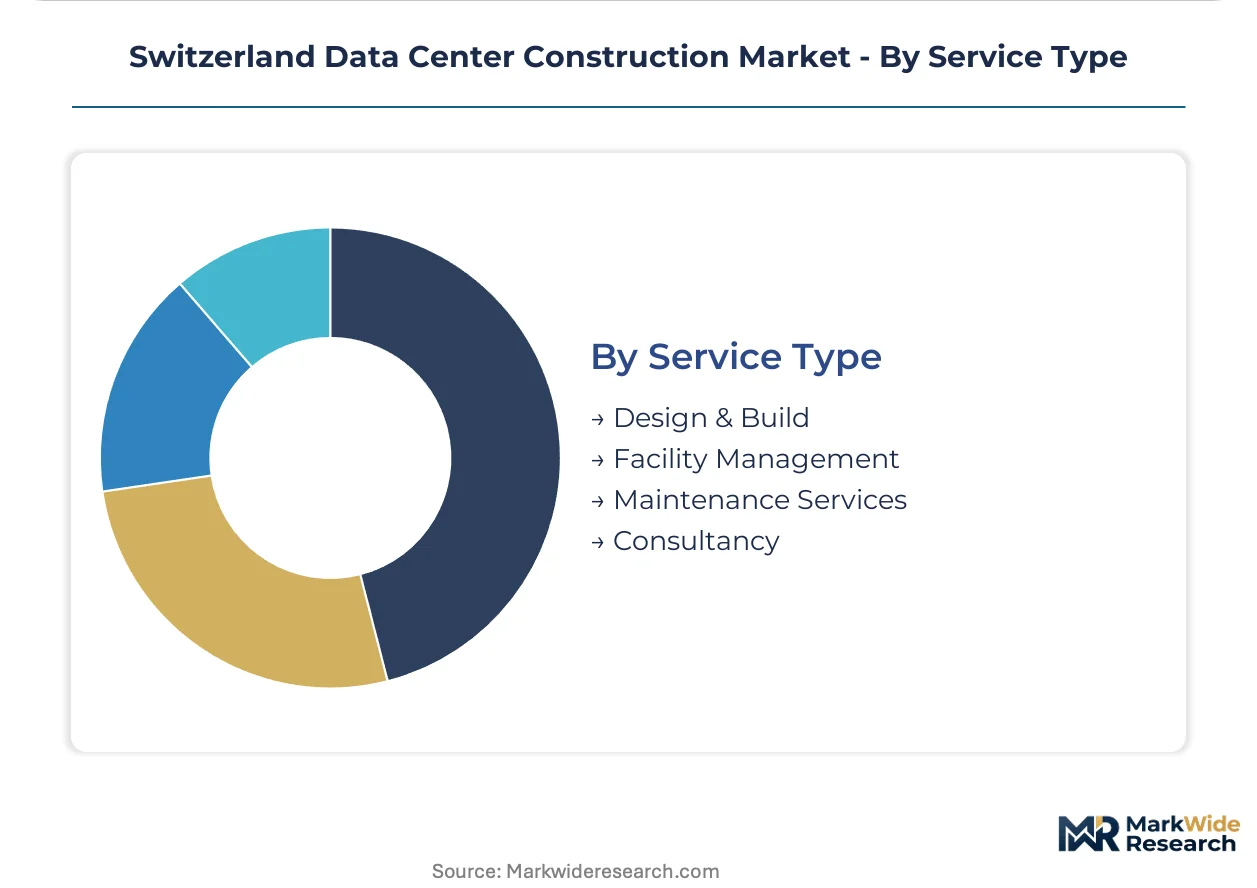
Service Type:
Maturity gradients separate established design-build workflows from emerging thermal reuse integration, with service bundling reshaping contractor margin structures.
- Design & Build:Integrated engineering-procurement-construction delivery with SIA Swiss engineering standards compliance. Arup and Implenia anchor this segment through master planning and civil infrastructure dominance.
- Facility Management:Operational continuity services with ±1°C precision cooling tolerance validation. Revenue recognition defers until commissioning phases complete.
- Maintenance Services:Preventive and corrective infrastructure upkeep with documented critical infrastructure experience requirements.
- Consultancy:Geotechnical and environmental risk assessment for Alpine-constrained sites where seismic and hydrological factors complicate foundation design.
Design & Build retains the dominant revenue share; Facility Management is climbing the fastest as operational resilience mandates extend post-construction engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Zurich and Geneva corridors where fiber latency to European financial hubs commands locational premiums, while peripheral cantons face compressed returns amid utility interconnection bottlenecks and extended approval timelines.
Zurich Metropolitan Area
Hyperscale cloud commitments from Microsoft, Google, and Amazon Web Services drive multi-hundred-megawatt power demand in the Glattbrugg corridor. FINMA operational resilience requirements for financial institutions elevate facility certification thresholds, filtering contractor pools. Basel anchors pharmaceutical data integrity demand under Swissmedic guidelines, pulling sovereign hosting investment toward the northern corridor.
Geneva Financial Corridor
Private banking and wealth management compute requirements sustain colocation demand with stringent physical security segmentation mandates. Modular data center adoption accelerates among enterprises seeking deployable capacity without cantonal zoning delays. The city's proximity to CERN research infrastructure creates specialized high-performance computing clustering.
Ticino Border Region
Italian cross-border fiber connectivity and lower land costs attract edge node positioning for sub-10 millisecond latency to Milan financial markets. EU Green Deal alignment through bilateral agreements imposes carbon intensity benchmarks that redirect procurement toward renewable-backed supply contracts. Lugano emerges as a secondary hub for blockchain and cryptocurrency custody facilities.
Central Alpine Cantons
Seismic foundation complexity and geotechnical risk assessment requirements extend project development cycles in Uri, Schwyz, and Valais. Alpine water availability creates free-cooling economics that attract thermal-intensive AI training cluster placement. Gruner and specialized environmental consultancies sustain premium positioning on these constrained sites.
Northwestern Basel-Land
Pharmaceutical manufacturing concentration from Roche and Novartis operations generates captive data integrity requirements for clinical trial storage. Swissmedic guidelines mandate sovereign hosting, insulating regional demand from cloud migration pressures. The Rhine river corridor provides district heating interconnection potential for thermal reuse revenue streams.
Switzerland Data Center Construction Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Swiss data center construction, with integrated engineering-architecture firms commanding premium positioning on complex master planning while domestic civil infrastructure specialists compete on shell delivery speed. The qualified vendor pool compresses under SIA Swiss engineering standards and FINMA operational resilience documentation requirements. Three archetypes dominate: integrated design-build operators, geotechnical environmental risk assessors, and tunneling-civil infrastructure extenders. Competitive moves concentrate on strategic partnerships with hyperscale cloud providers and portfolio diversification into thermal reuse integration services.
Within the integrated engineering tier, Arup anchors complex multi-tenant campus master planning through its architecture-engineering convergence model. Domestic civil infrastructure dominance positions Implenia to extend tunneling and shell expertise into subterranean cooling configurations. Geotechnical specialists Gruner occupy the environmental risk assessment niche on Alpine-constrained sites where seismic and hydrological factors complicate foundation engineering.
| Leading Market Players |
|---|
| Arup |
| DPR Construction |
| Legrand |
| AECOM |
| Basler & Hofmann |
| Gruner |
| Turner & Townsend |
| Webuild Group |
| Implenia |
| Others |
Pricing and Supply Chain Analysis
Dielectric fluid immersion systems displacing conventional air-handling infrastructure simultaneously redraw procurement geography toward German and Austrian chemical suppliers and compress pricing premiums for legacy mechanical contractors unable to certify fluid management capabilities.
Pricing Analysis
The customization-premium spread between build-to-suit hyperscale contracts and speculative colocation shell delivery spans three distinct pricing tiers: sovereign-certified facilities for Swissmedic and FINMA compliance, standard multi-tenant configurations, and rapid-deploy modular units. Price differentiation hinges on certification grade against SIA Swiss engineering standards and liquid-cooling engineering depth. Cost compression in standard colocation tiers is intensifying because cloud providers internalize capacity planning and squeeze developer margins through 12-18 month pre-construction collaboration periods. Enterprises in pharmaceutical and financial services verticals exhibit the lowest price sensitivity due to data sovereignty mandates, while edge operators around Geneva demonstrate acute cost consciousness for modular deployments.
Supply Chain Analysis
Extended lead times for direct-to-chip cold plates and ammonia-based chillers now stretch 26-32 weeks, forcing project developers to pre-position inventory ahead of cantonal utility approvals. Geographic supply concentration centers on Germany for precision mechanical components, Austria for dielectric fluid formulation, and Switzerland for SIA-certified electrical switchgear. Raw material dependencies span copper busbar, specialized aluminum alloys for heat exchangers, and natural refrigerants constrained by EU F-Gas Regulation phasedown schedules. Single-source vulnerability runs through German pump and valve suppliers serving liquid-cooling architectures. Distribution runs through design-build contractors who bundle procurement under integrated EPC contracts rather than owner-managed equipment sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Switzerland data center construction is entering a cyclical upswing driven by hyperscale cloud provider capacity commitments extending through the decade, though contractor qualification bottlenecks will filter participation.
For Market Incumbents: Shield margin position by deepening backward integration into liquid-cooling system design and securing exclusive relationships with German fluid management suppliers before scarcity hardens. Arup and Implenia should accelerate certification investment for subterranean cooling configurations to preempt emerging tunneling specialists from capturing Alpine-constrained site premiums. FINMA operational resilience documentation requirements create a defensive moat that filters smaller competitors lacking decade-long critical infrastructure track records. For New Entrants and Emerging Players: Anchor in Ticino's Lugano corridor where Italian cross-border fiber connectivity and lower land costs attract blockchain custody and edge compute demand with reduced incumbent saturation. Target thermal reuse integration services for district heating interconnection mandates in Basel-Land and select Alpine cantons, where revenue streams from waste heat recovery remain underdeveloped by established contractors. A go-to-market angle partnering with municipal utilities on heat-offtake agreements bypasses direct competition for shell construction. For Investors and Strategic Acquirers: The market sits at a capacity-constrained expansion phase that favors geotechnical environmental consultancies with documented Alpine site experience. Long-term viability over the next decade rests on regulatory alignment with EU Green Deal carbon intensity benchmarks and bilateral agreement evolution. Acquisition targets should demonstrate SIA Swiss engineering standards compliance plus liquid-cooling project delivery. The signal to watch is cantonal utility interconnection approval timeline compression, which would accelerate project mobilization and unlock trapped development pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Engineering Certification | SIA Swiss engineering standards compliance separates qualified contractors from filtered vendor pools. |
| Thermal Reuse Integration | District heating interconnection mandates in Basel-Land and Alpine cantons create alternative revenue streams. |
| Subterranean Cooling Configuration | Tunneling expertise from domestic civil infrastructure transfers into novel data center thermal architectures. |
| Hyperscale Design Collaboration | 12-18 month pre-construction engagement periods with Microsoft, Google, and Amazon Web Services concentrate demand. |
| EU F-Gas Regulation Compliance | Natural refrigerant adoption and ammonia-based chiller investment redirects procurement toward specialized suppliers. |
Research Methodology
Desk research of SEC hyperscaler capex disclosures, cantonal utility interconnection databases, and EU F-Gas Regulation implementation guidance preceded structured interviews with data center developers, SIA-certified engineering contractors, pharmaceutical facility planners, and FINMA compliance officers. Primary fieldwork validated secondary projections through bottom-up project pipeline assessment and top-down capital allocation analysis across cloud provider and enterprise segments. Triangulation across these sources anchored segmentation splits by product type, cooling technology, and end-user vertical.
Variance decomposition across the projection horizon isolates growth contributions from hyperscale commitments, modular edge deployment, and thermal reuse integration services. Segmentation dimensions modeled include facility scale tier, cooling architecture type, end-user regulatory exposure, and regional cantonal cluster. CAGRs were derived from installed base evolution and replacement cycle analysis rather than simple trend extrapolation. Forecast inputs incorporate utility interconnection approval timelines and EU Green Deal bilateral agreement implementation pacing.
Decision-makers should treat outputs as directional under assumptions of sustained hyperscale cloud expansion and stable Swiss-EU regulatory alignment; material deviation in bilateral agreement terms or cantonal zoning restrictions would warrant model refresh. Specific project-level returns depend on site-specific geotechnical conditions and utility negotiation outcomes not captured in aggregate projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Direct-to-Chip Coolant Fluids Market
Data Center Infrastructure
Delhi-NCR Data Center Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
France Data Center Server Market
Data Center Infrastructure
Canada Data Center Construction Market
Data Center Infrastructure
Switchgear for Data Centers Market
Data Center Infrastructure
Saudi Arabia Data Center Physical Security Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
China Data Center Rack Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
China Data Center Construction Market
Data Center Infrastructure
Server Station Market
Data Center Infrastructure
Data Center in Middle East Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
Ireland Data Center Rack Market