
 Delhi-NCR Data Center Market | 2026-2036
Delhi-NCR Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Delhi-NCR Data Center Market Insights
Uptime Institute Tier III and IV certification is bifurcating the competitive landscape between bankable operators and speculative entrants. CtrlS Datacenters sustains one of India's largest Tier IV-certified portfolios with integrated captive power infrastructure. STT GDC India anchors its Noida-Greater Noida corridor through long-term land leases and utility-scale renewable tie-ups. Princeton Digital Group India positions aggressively on hyperscale pre-commitments from international cloud platforms.
Delhi-NCR data centers constitute mission-critical facilities engineered for concurrent maintainability, with Tier III facilities demanding minimum 99.982% uptime and dual-power feed architecture with N+1 redundancy on all active systems. Colocation and hyperscale deployments absorb the majority of new supply as enterprise IT departments shed owned assets for operational expenditure models. Edge computing within the technology stack gains traction for latency-sensitive financial trading and content delivery workloads across the National Capital Region's dense enterprise corridor.
BIS equipment certification, MeitY data localization directives, and Delhi Pollution Control Committee emissions norms collectively determine facility design standards and customer eligibility for government-linked contracts. The Telecom Regulatory Authority of India's infrastructure sharing mandates alter interconnection economics between competing campus developments. Stakeholders must track evolving state-level power tariff structures and renewable purchase obligations that determine long-term operating cost trajectories against fixed-price customer commitments.
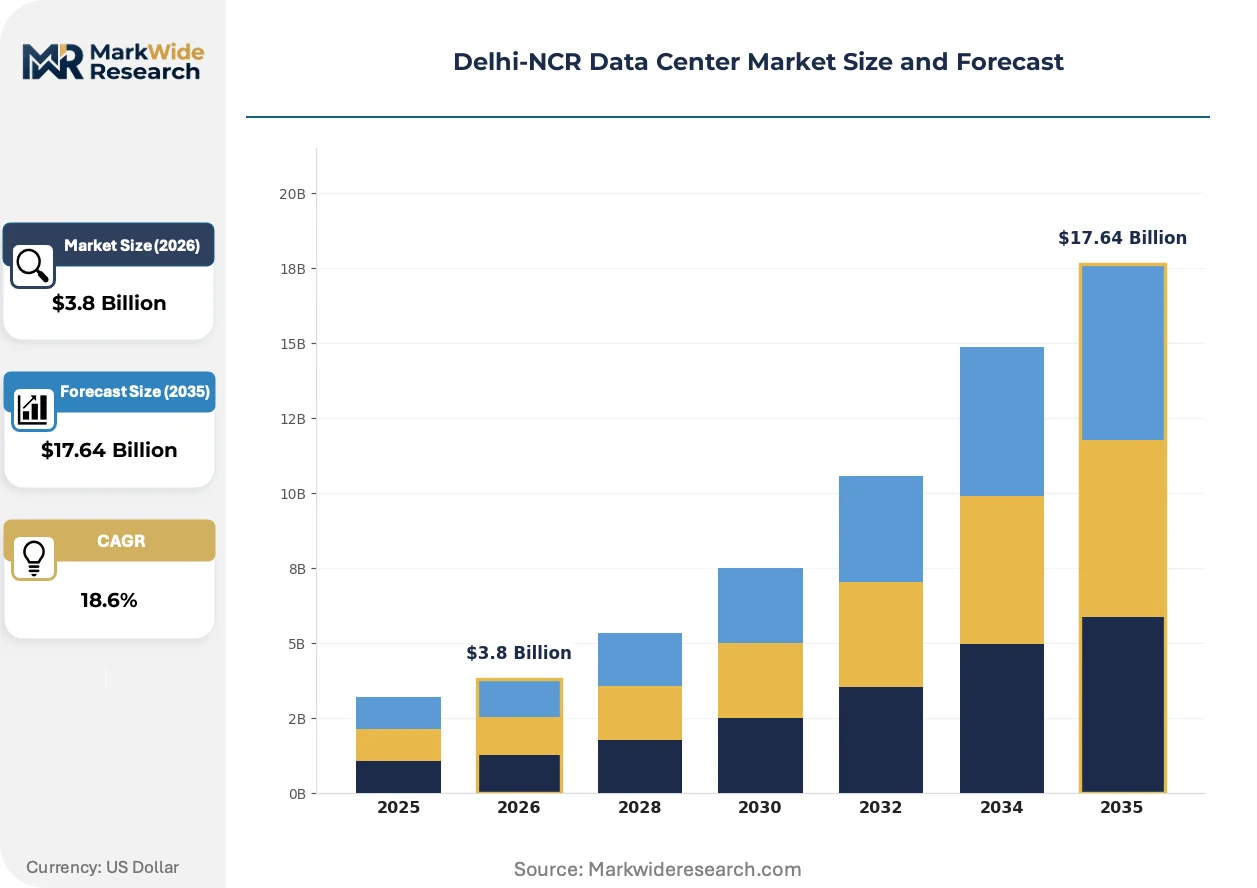
Market Dynamics
Cloud service providers' hyperscale pre-commitments are compressing development timelines and forcing operators to secure land and power years ahead of revenue recognition. This demand concentration is reshaping capital deployment patterns across Noida, Gurgaon, and Greater Noida corridors.
Growth Catalysts
- MeitY Data Localization Mandates:Government directives requiring domestic storage of sensitive citizen data are compelling multinational enterprises to establish India-based infrastructure. Financial services and healthcare verticals face the strictest compliance deadlines.
- AI/ML Training Clusters:GPU-intensive workloads for generative AI development are driving demand for high-density power configurations above 50 kW per rack. Domestic technology firms and research institutions are expanding captive capacity.
- Noida-Greater Noida Land Availability:Dedicated data center zones with pre-approved environmental clearances and substation access are accelerating project commissioning timelines versus central Delhi constraints.
Market Restraints
- Power Grid Instability:Uttar Pradesh and Haryana distribution utilities experience seasonal load shedding that forces operators to overbuild captive diesel generation. Fuel storage compliance with Petroleum and Explosives Safety Organization norms adds site complexity.
- Lithium-Ion Battery Supply Concentration:Cell manufacturing dominance by Chinese producers creates import dependency for UPS and energy storage systems. DGFT licensing requirements and rupee-dollar volatility amplify working capital pressure.
- Water Scarcity Constraints:NCT Delhi and surrounding states face groundwater depletion that limits evaporative cooling options. Operators must deploy adiabatic or liquid cooling architectures at 15-25% capex premiums.
Strategic Opportunities
- Faridabad-Ballabhgarh Corridor:Underdeveloped industrial zones south of Delhi offer land parcels at 40-60% discounts versus established Noida nodes. Haryana power utilities are extending dedicated 220 kV feeders to attract anchor tenants.
- Edge Micro-Data Centers:5G network densification and autonomous vehicle testing zones require sub-10 millisecond latency infrastructure. Telecom infrastructure providers are seeking colocation partnerships for distributed compute nodes.
- Green Hydrogen Pilot Integration:Ministry of New and Renewable Energy subsidies for renewable hydrogen production enable long-duration storage alternatives to diesel backup. Early movers can secure carbon-neutral positioning for ESG-mandated clients.
Industry Challenges
- Tier IV Certification Expertise Gap:Uptime Institute's stringent documentation and testing protocols require specialized commissioning engineers. Local talent pools lack experience with concurrent maintainability validation and fault simulation procedures.
- Legacy Enterprise Migration Complexity:Government and public sector undertakings operate decades-old mainframe environments with hardcoded IP addresses. Lift-and-shift strategies fail, forcing costly application refactoring before cloud migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Delhi-NCR Data Center Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Colocation, Wholesale, Hyperscale Service Type: Infrastructure as a Service, Platform as a Service, Disaster Recovery, Managed Services Technology: Cloud Computing, Virtualization, Edge Computing, Automation End User: Telecommunications, BFSI, IT Services, E-Commerce |
| Companies Covered | NTT GDC India, CtrlS Datacenters, STT GDC India, AdaniConneX, Equinix India, Yotta Infrastructure, Web Werks – Iron Mountain, Princeton Digital Group India, Nxtra Data Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Delhi-NCR Data Center Market Trends and Innovations
Immersion cooling and direct liquid cooling architectures are displacing traditional air-cooled designs as power densities exceed 30 kW per rack. Regulatory pressure on water consumption and carbon intensity is accelerating technology substitution across the NCR operator base.
Direct-to-chip liquid cooling is displacing raised-floor air circulation in new hyperscale builds. Cloud service providers deploying NVIDIA H100 clusters are mandating coolant distribution units as standard infrastructure. This shift is compressing mechanical plant footprints by 40% and enabling 50% higher rack densities within identical building envelopes.
BIS certification timelines for imported IT equipment are extending from 12 to 18 months under revised conformity assessment procedures. The Bureau's mandatory factory audits and sample testing protocols are delaying server and storage deployments for international operators. Domestic system integrators with established BIS relationships are capturing procurement preference from time-constrained enterprises.
Consumption-based power pricing is replacing flat-rate utility contracts for large colocation tenants. Retail and wholesale buyers are negotiating real-time tariff linkage clauses that pass through state electricity regulatory commission rate adjustments. This transfer mechanism is most visible in Uttar Pradesh and Haryana facilities serving price-sensitive Indian SaaS providers and fintech startups.
Delhi-NCR Data Center Market Segmentation
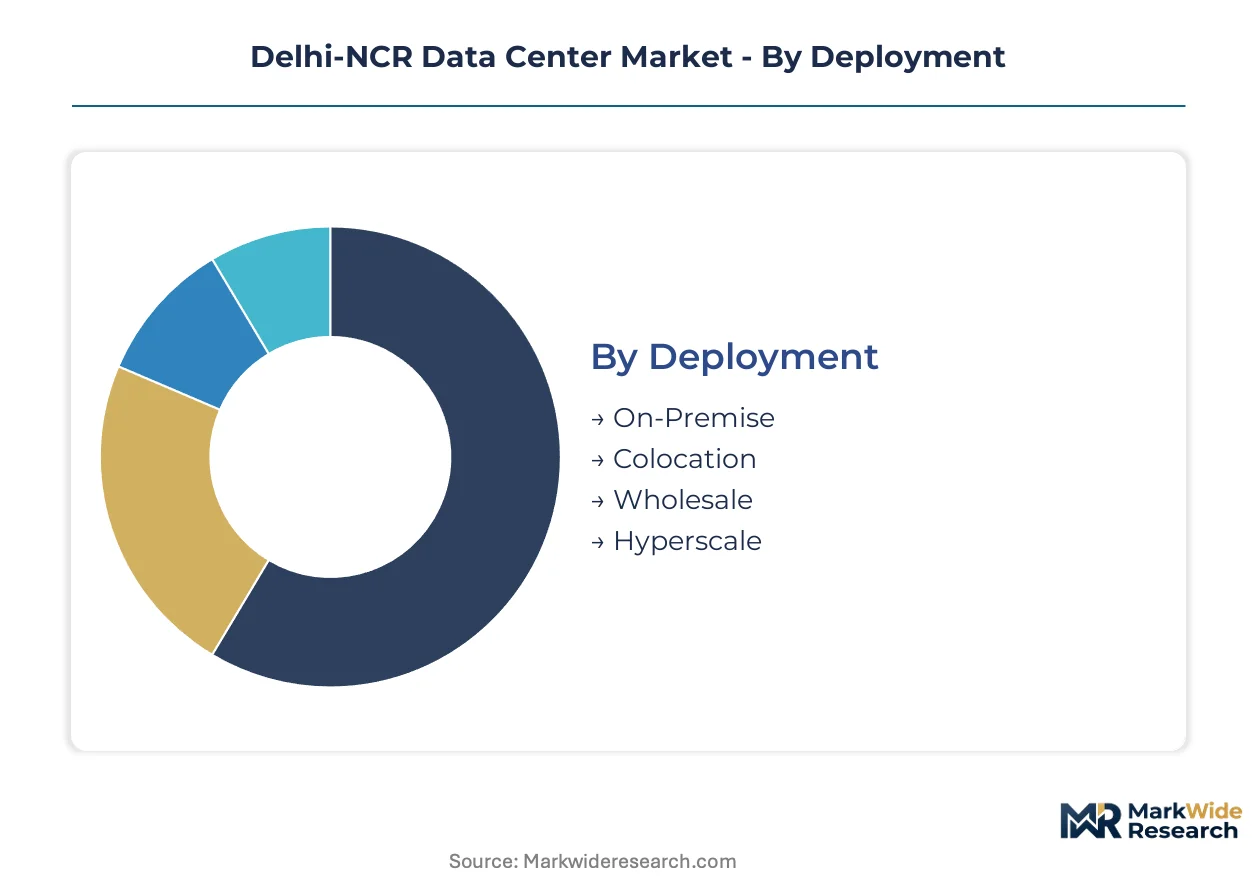
Delhi-NCR data center segmentation reveals divergent margin profiles across deployment models and customer verticals. Infrastructure buyers prioritize operational expenditure conversion over capital ownership, reshaping supplier economics across Noida and Gurgaon corridors.
Deployment:
Margin pools concentrate in long-term contracted capacity with utility-scale power arrangements.
- Hyperscale:Purpose-built facilities exceeding 10 MW with direct utility interconnection and renewable power purchase agreements. Cloud service providers anchor Noida-Greater Noida developments through 10-15 year lease structures with inflation-linked escalators.
- Colocation:Retail space leased by rack or cage with shared mechanical infrastructure. Financial services and SaaS providers in Gurgaon's Cyber City corridor drive demand for Tier III-certified multi-tenant environments with cross-connect density.
- Wholesale:Dedicated data hall leases with tenant-controlled security and power distribution. Domestic enterprises migrating from captive infrastructure favor this intermediate model for workload segregation compliance.
- On-Premise:Enterprise-owned facilities with full operational control. Government undertakings and defense-linked entities maintain this deployment for sovereign data requirements under MeitY localization directives.
Hyperscale holds installed capacity. Colocation is rotating up the share rankings.
Service Type:
Revenue visibility varies by contract duration and technical complexity within each offering.
- Infrastructure as a Service:Compute and storage resources delivered on consumption-based metering. Indian fintech startups and e-commerce platforms favor IaaS for Diwali-season traffic elasticity without capital commitment.
- Disaster Recovery:Secondary site replication with defined recovery time objectives. BFSI regulators mandate RPO thresholds below 15 minutes for core banking systems, driving premium pricing for synchronous replication capabilities.
- Platform as a Service:Application development environments with managed middleware stacks. IT services firms leverage PaaS for client project acceleration without underlying infrastructure provisioning.
- Managed Services:Operational outsourcing covering monitoring, patching, and capacity planning. Legacy enterprise migrations require these wraparound services to address internal skill gaps in cloud-native operations.
Disaster Recovery commands pricing premiums. Infrastructure as a Service is expanding most quickly among mid-market adopters.
Technology:
Capital intensity and facility design standards diverge sharply across technology stacks.
- Cloud Computing:Distributed resource pools with software-defined networking and storage virtualization. Multi-tenant architectures enable 40-60% utilization improvements versus siloed enterprise infrastructure.
- Edge Computing:Sub-10 millisecond latency nodes positioned for autonomous vehicle testing zones and 5G network densification. Faridabad-Ballabhgarh corridor offers land cost advantages for distributed micro-data center deployment.
- Virtualization:Server consolidation through hypervisor abstraction layers. Mature technology with compressed margins as containerization and Kubernetes orchestration displace legacy VM workloads.
- Automation:Infrastructure-as-code deployment and predictive maintenance systems. Reduces operational headcount requirements by 30-40% in hyperscale facilities with standardized hardware fleets.
Cloud Computing dominates committed power capacity. Edge Computing is climbing the fastest as latency requirements tighten for financial trading applications.
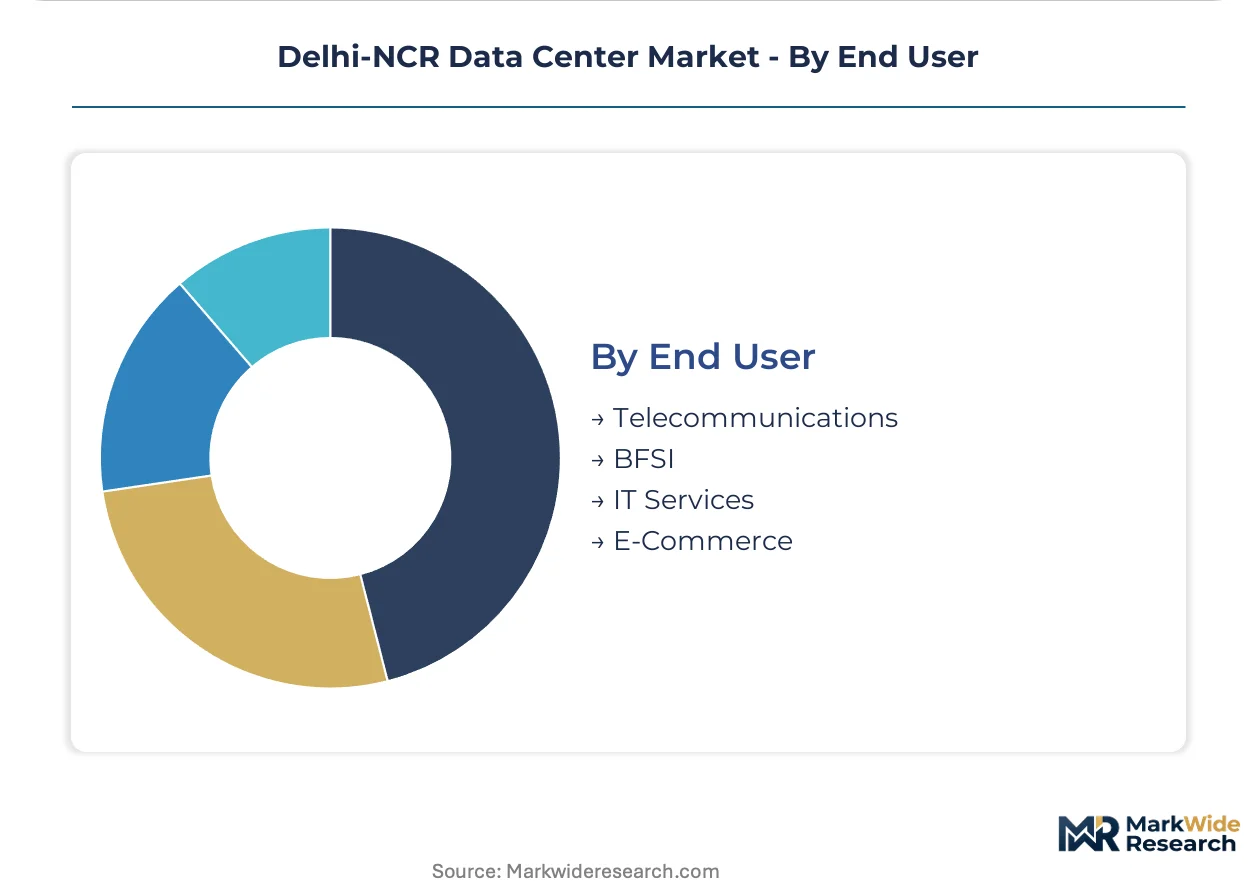
End User:
Compliance burden and density requirements create distinct customer archetypes with diverging procurement behaviors.
- BFSI:Banking, financial services, and insurance with RBI-mandated data localization and disaster recovery requirements. Tier IV certification and synchronous replication between Noida and Mumbai corridors command 25-35% pricing premiums.
- IT Services:Domestic technology firms and global capability centers delivering client workload hosting. Export-oriented revenue models drive sensitivity to rupee-denominated power tariffs and renewable purchase obligation compliance costs.
- Telecommunications:5G core network functions and content delivery infrastructure. TRAI infrastructure sharing mandates alter interconnection economics for edge node placement across NCR telecom circles.
- E-Commerce:Seasonal demand spikes requiring elastic compute scaling. Flash sales and festival-season traffic drive preference for consumption-based IaaS contracts with committed use discounts.
BFSI anchors premium-tier capacity commitments. IT Services is gaining share fastest as global capability center expansion accelerates across Gurgaon and Noida.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud service providers anchor capacity commitments across Delhi-NCR sub-markets, with hyperscale pre-commitments compressing development timelines in Noida and Gurgaon corridors. Financial services and IT services verticals drive secondary demand for Tier III-certified colocation. State-level power tariff structures and renewable purchase obligations determine operator economics against long-term customer contracts.
Noida
Hyperscale deployments from international cloud platforms dominate new supply absorption in this Uttar Pradesh node. BIS certification mandates for imported IT equipment extend equipment procurement cycles, advantaging domestic system integrators with established regulator relationships. The Noida-Greater Noida corridor concentrates pre-approved data center zones with dedicated 220 kV substation access and streamlined environmental clearances.
Gurgaon
Financial services tenants in Cyber City and Golf Course Road corridors demand synchronous replication capabilities with sub-15 minute recovery point objectives. Haryana power utilities extend dedicated feeders to campus developments, though seasonal load shedding forces diesel generation overbuild. The city's dense enterprise base supports premium pricing for cross-connect density and carrier-neutral interconnection.
Greater Noida
Land parcels at 40-60% discounts versus established Noida nodes attract wholesale and hyperscale commitments from domestic enterprises shedding captive infrastructure. MeitY data localization directives compel multinational technology firms to establish India-based storage for sensitive citizen data. STT GDC India anchors this corridor through long-term land leases and utility-scale renewable power purchase agreements.
Faridabad-Ballabhgarh
Emerging industrial zones south of Delhi offer cost advantages for edge micro-data center deployment targeting 5G network densification and autonomous vehicle testing. Haryana state incentives for data center investments include concessional power tariffs and stamp duty exemptions. The corridor remains underdeveloped relative to Noida-Gurgaon nodes but gains traction for latency-sensitive distributed compute workloads.
Central Delhi
Legacy enterprise-owned facilities persist among government undertakings and defense-linked entities with sovereign data requirements. Land scarcity and power grid constraints prevent new greenfield development, ceding growth to peripheral sub-markets. Existing operators focus on managed services wraparounds for mainframe environments requiring application refactoring before cloud migration.
Delhi-NCR Data Center Market Competitive Landscape
Player mix skews toward integrated operators with captive power infrastructure and Tier IV certification capabilities. The competitive landscape bifurcates between bankable operators with Uptime Institute credentials and speculative entrants lacking utility-scale power arrangements. Three archetypes dominate: hyperscale specialists with direct cloud provider relationships, multi-tenant colocation providers serving financial services compliance requirements, and captive infrastructure operators transitioning to commercial hosting. Capacity pre-commitments and long-term land lease securing represent the dominant competitive moves, with renewable power procurement emerging as a secondary differentiator.
Within the integrated infrastructure tier, CtrlS Datacenters and STT GDC India exemplify operators with Tier IV-certified portfolios and captive generation assets. Princeton Digital Group India occupies a position focused on hyperscale pre-commitments from international cloud platforms. Among carrier-neutral interconnection providers, Equinix India represents the global platform archetype with established cross-connect density in Gurgaon's enterprise corridors. NTT GDC India and Yotta Infrastructure sit within the scale-driven expansion category, leveraging parent entity balance sheets for land and power advance procurement. AdaniConneX exemplifies the energy conglomerate-backed model with vertical integration into renewable power development.
| Leading Market Players |
|---|
| NTT GDC India |
| CtrlS Datacenters |
| STT GDC India |
| AdaniConneX |
| Equinix India |
| Yotta Infrastructure |
| Web Werks – Iron Mountain |
| Princeton Digital Group India |
| Nxtra Data Limited |
| Others |
Pricing and Supply Chain Analysis
Long-term power purchase agreements with inflation-linked escalators lock in both utility-scale supply access and operating cost visibility for Noida-Greater Noida operators securing 10-15 year customer commitments. These structures transfer state electricity regulatory commission rate volatility to end-users while anchoring project financeability.
Pricing Analysis
Cost-plus contracts with tariff indexation to state electricity regulatory commission adjustments dominate wholesale and hyperscale segments. Price differentiation rests on Uptime Institute certification tier and cross-connect density in carrier-neutral facilities. Cost compression in retail colocation intensifies as domestic SaaS providers and fintech startups negotiate real-time tariff linkage clauses. Indian SaaS providers exhibit highest price sensitivity; BFSI anchors with RBI-mandated disaster recovery requirements show lowest.
Supply Chain Analysis
Strategic stockpiling of lithium-ion battery cells and diesel generator sets prevails over just-in-time approaches given DGFT licensing delays and rupee-dollar volatility. Cell manufacturing concentrates in China, South Korea, and Japan, with Chinese producers commanding dominant share. UPS and energy storage systems draw from this concentrated base, exposing operators to single-source vulnerability. Distribution runs through domestic system integrators with established BIS relationships who capture procurement preference from time-constrained enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Delhi-NCR data center infrastructure sits at an inflection where MeitY data localization mandates and GPU-intensive AI training clusters are compressing development timelines and reshaping competitive economics.
For Market Incumbents: Consolidate through captive renewable power procurement and Tier IV certification deepening to defend against hyperscale specialists with direct cloud provider relationships. Lock in long-term land leases in Greater Noida and Faridabad-Ballabhgarh corridors before speculative entrants secure substation access. Prioritize backward integration into green hydrogen pilot programs for carbon-neutral positioning against ESG-mandated clients. For New Entrants and Emerging Players: Differentiate on edge micro-data center deployment for 5G network densification and autonomous vehicle testing zones where latency requirements under 10 milliseconds create defendable positioning. Target Faridabad-Ballabhgarh corridor land parcels at 40-60% discounts versus established Noida nodes. Pursue colocation partnerships with telecom infrastructure providers seeking distributed compute nodes rather than competing head-to-head with integrated operators. For Investors and Strategic Acquirers: Capital is best deployed toward operators with secured 220 kV substation access and pre-approved environmental clearances in Noida-Greater Noida corridor, as these assets compound in scarcity value across the analysis window. Monitor BIS certification timeline extensions as signal of procurement advantage shifting toward domestic system integrators with established regulator relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Utility-Scale Renewable PPA Procurement | Locks in power cost visibility against state electricity regulatory commission volatility for 10-15 year contract structures. |
| Tier IV Certification Investment | Commands 25-35% pricing premiums from BFSI vertical with RBI-mandated disaster recovery requirements. |
| Edge Micro-Data Center Deployment | Captures 5G network densification demand with sub-10 millisecond latency positioning in Faridabad-Ballabhgarh corridor. |
| Green Hydrogen Pilot Integration | Secures carbon-neutral positioning for ESG-mandated clients under Ministry of New and Renewable Energy subsidies. |
| Domestic System Integrator Partnership | Mitigates BIS certification timeline extensions from 12 to 18 months for imported IT equipment procurement. |
Research Methodology
Cross-validation between primary interviews with data center operators, cloud service provider infrastructure planners, and state utility regulatory officers anchors the qualitative findings against secondary validation. Secondary sources include TRAI infrastructure sharing mandates, state electricity regulatory commission tariff orders, Uptime Institute certification databases, and MeitY data localization guidelines. Bottom-up project pipeline tracking and top-down demand segmentation triangulate capacity and revenue estimates.
Sensitivity analysis around power tariff escalation rates, BIS certification timeline assumptions, and hyperscale pre-commitment conversion probabilities shapes the analytical framework across the analysis window. Segmentation dimensions modeled include deployment model, service type, technology stack, and end-user vertical with specific treatment of GPU-intensive AI training cluster demand. CAGRs derive from regression against historical capacity absorption patterns and cloud provider capex disclosure trajectories.
Forecasts assume regulatory continuity in BIS equipment certification, MeitY data localization, and state renewable purchase obligation regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as Uttar Pradesh and Haryana power grid stability and lithium-ion battery import licensing conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Philippines Data Center Server Market
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
Sweden Data Center Rack Market
Data Center Infrastructure
Thailand Data Center Market
Data Center Infrastructure
Data Center Rack Market
Data Center Infrastructure
Europe Hyperscale Data Center Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
Japan Data Center Physical Security Market
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
India Data Center Server Market
Data Center Infrastructure
United Kingdom Data Center Power Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
North America Data Center Server Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
Datacenter Infrastructure Services Market
Data Center Infrastructure
Poland Data Center Rack Market