
 China Data Center Rack Market | 2026-2036
China Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
China Data Center Rack Market Insights
Aftermarket service revenue is narrowing as a margin pool migration from hardware sales toward lifecycle management contracts. Schneider Electric SE leverages its integrated power and cooling portfolio to capture recurring service streams. Huawei anchors its position through in-house silicon-to-rack vertical integration. Inspur competes on manufacturing scale for domestic cloud provider procurement.
A data center rack is a standardized metal framework that houses servers, networking equipment, and power distribution units, typically conforming to 19-inch EIA-310-D specifications for mounting width and 42U to 52U height configurations, designed to organize IT infrastructure, optimize airflow, and enable scalable capacity expansion in controlled environments. Enclosed rack configurations command premium positioning where thermal containment and physical security drive procurement decisions, while high-density variants represent the fastest-growing product type as AI training clusters push power densities beyond 30 kW per rack. Edge computing deployment patterns are fragmenting demand geography, pulling rack specifications away from hyperscale uniformity toward modular, weather-hardened form factors.
MIIT enforces GB 50174 data center design standards that mandate power usage effectiveness thresholds and cooling efficiency metrics, directly shaping rack-level thermal management requirements and product certification pathways. SAMR administers compulsory product certification that gates market access for imported rack assemblies, creating compliance cost asymmetries between domestic and foreign suppliers. Stakeholders must monitor how NMPA's evolving dual carbon enforcement timelines recalibrate rack power density roadmaps against provincial energy quota allocations.
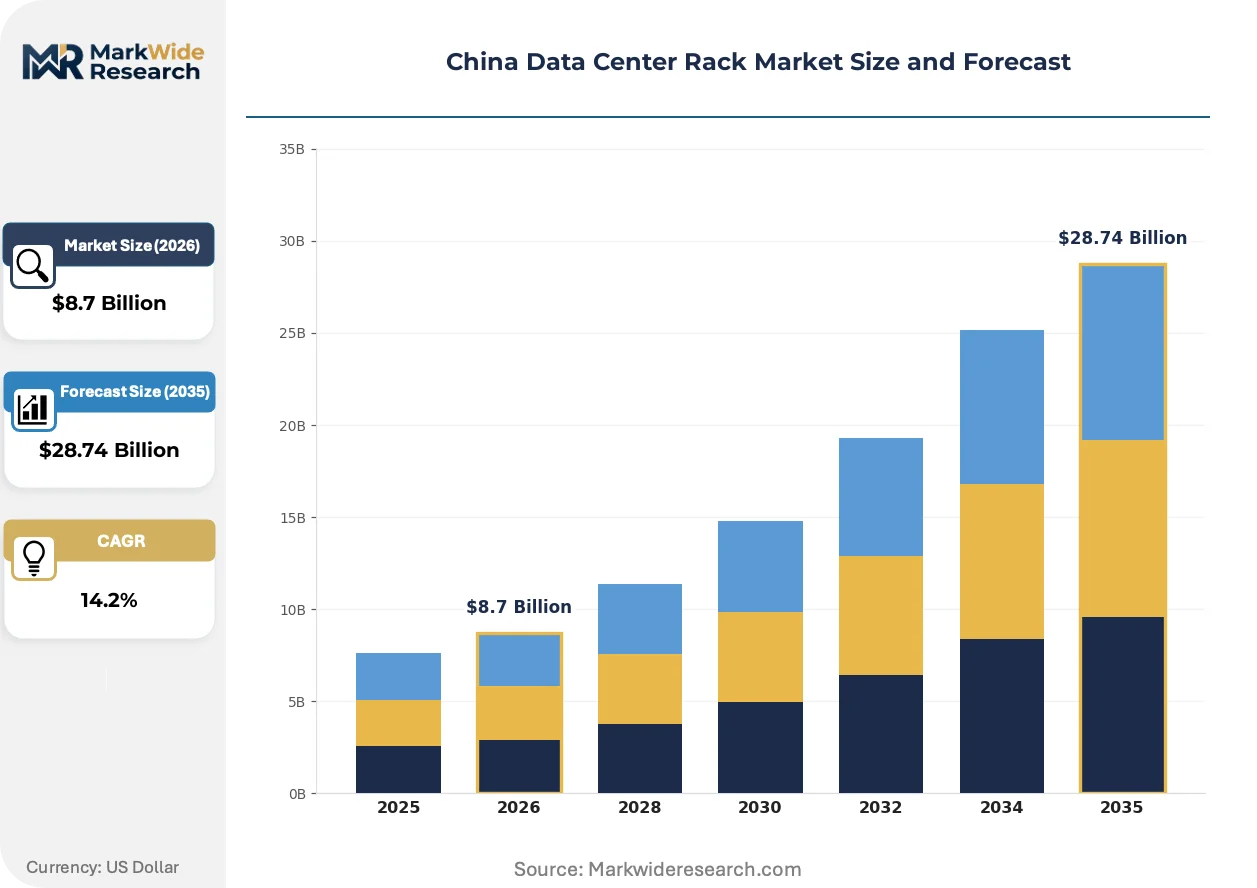
Market Dynamics
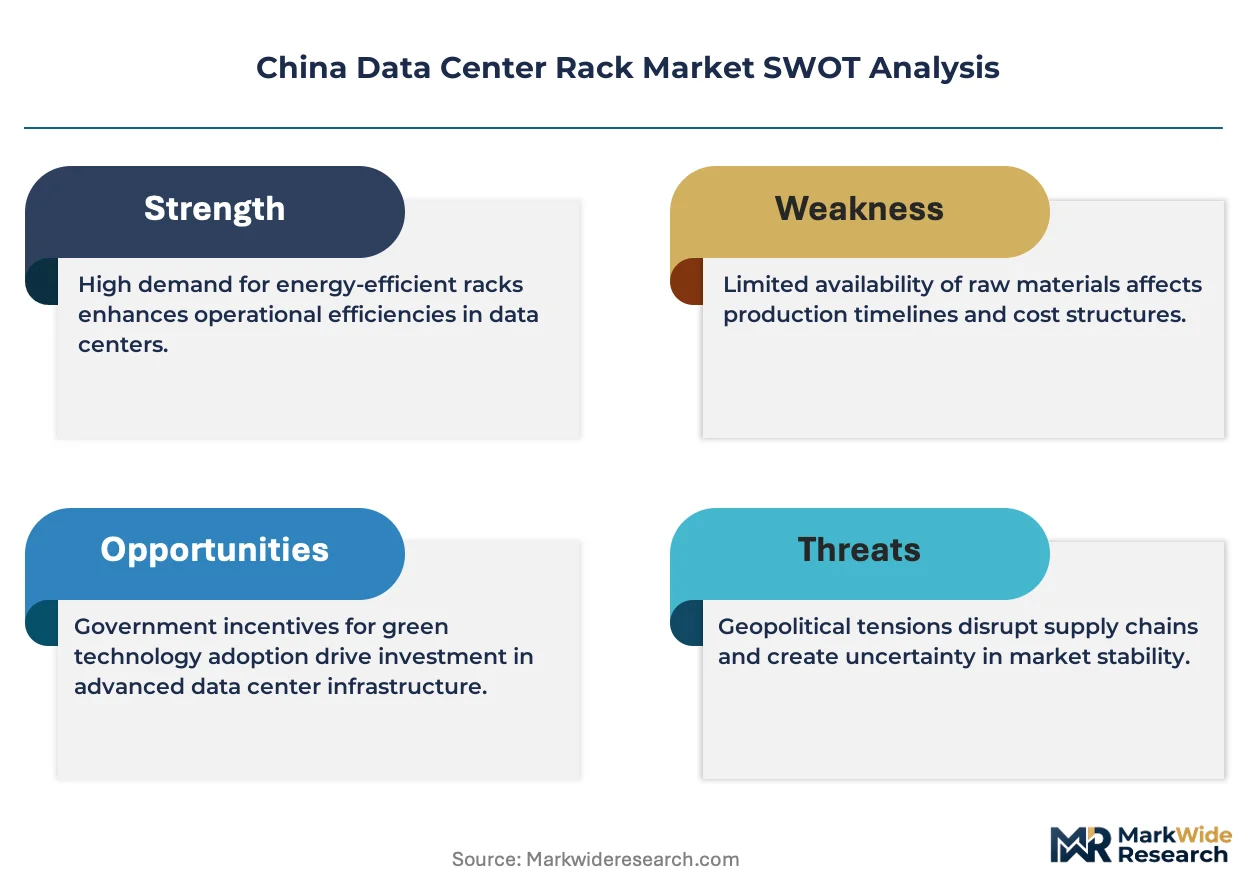
MIIT's dual carbon enforcement timelines are compressing rack procurement cycles as data center operators race to deploy liquid-cooled infrastructure before provincial energy quota deadlines lock in capacity allocations.
Growth Catalysts
- AI training cluster expansion:Hyperscale cloud providers in Beijing, Shanghai, and Shenzhen are commissioning 30+ kW racks to support GPU-intensive workloads, pulling demand for high-density thermal containment systems.
- GB 50174 efficiency mandates:MIIT's power usage effectiveness thresholds force retrofit cycles in existing facilities, creating replacement demand for compliant rack assemblies with integrated airflow management.
- Edge node proliferation:Telecom operators are deploying modular, weather-hardened racks in Tier-2 and Tier-3 cities to support low-latency applications, fragmenting specifications away from hyperscale uniformity.
Market Restraints
- Copper and steel input volatility:Raw material price swings compress margins for domestic rack fabricators who lack long-term supply contracts with state-owned metal traders.
- SAMR certification asymmetry:Compulsory product certification gates market access for imported rack assemblies, creating compliance cost disadvantages for foreign suppliers against domestic manufacturers.
- Power infrastructure bottlenecks:Provincial grid capacity constraints in Guangdong and Jiangsu delay rack energization timelines, extending customer payment cycles and working capital strain.
Strategic Opportunities
- Western China data center clusters:Ningxia, Guizhou, and Inner Mongolia offer subsidized land and renewable energy quotas for rack deployments serving eastern load centers via dedicated fiber trunk lines.
- Immersive liquid cooling convergence:Integration of direct-to-chip cooling with rack-level power distribution units opens specification windows for integrated thermal-electrical platforms.
- Lifecycle service contracts:Cloud providers are unbundling hardware procurement from decade-long maintenance agreements, creating recurring revenue pools for rack vendors with field service networks.
Industry Challenges
- Thermal engineering talent scarcity:Liquid cooling system design and computational fluid dynamics modeling skills concentrate among semiconductor and aerospace engineers, forcing rack vendors to poach from adjacent industries.
- Legacy facility retrofit complexity:Raised-floor data centers built to 10-15 kW per rack specifications require structural reinforcement and plumbing overhauls to accommodate 30+ kW liquid-cooled deployments.
- GB standard revision lag:Rapid AI rack power density evolution outpaces MIIT's standards update cycle, leaving procurement teams without certified product categories for emerging configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Data Center Rack Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed, High-Density, Wall-Mounted End User: Telecom Providers, Cloud Service Providers, Enterprises, Government Institutions Deployment: On-Premises, Colocation, Edge Computing, Hybrid Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Schneider Electric SE, Rittal GmbH & Co. KG, Huawei, Dell Inc., Black Box Corporation, Inspur, Eaton Corporation, Legrand SA, Vertiv Group Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Data Center Rack Market Trends and Innovations
Direct liquid cooling architectures are compressing traditional air-cooled rack design cycles while MIIT efficiency mandates accelerate product obsolescence timelines across installed base retrofits.
Immersion cooling systems using dielectric fluids are rendering obsolete conventional raised-floor air conditioning in high-performance computing deployments. Hyperscale operators in Beijing and Shanghai are piloting two-phase immersion racks for 100+ kW AI clusters. This thermal approach is rendering obsolete the 20-year dominance of perimeter CRAC units in Chinese data center design specifications.
MIIT's GB 50174-2017 amendment drafts are tightening power usage effectiveness thresholds for new data center approvals. Provincial economic planning commissions are denying construction permits to facilities projected above 1.3 PUE. Northern and western provinces with cooler ambient temperatures are capturing disproportionate rack deployment share as operators chase natural cooling advantages against regulatory deadlines.
Cloud providers are consolidating rack procurement under direct OEM relationships, bypassing traditional IT distribution channels. Alibaba, Tencent, and ByteDance now issue multi-year framework agreements specifying custom rack dimensions, power busbar configurations, and cooling manifold interfaces. This channel compression is most visible in Jiangsu and Zhejiang where manufacturing proximity enables just-in-time rack delivery against compressed construction schedules.
China Data Center Rack Market Segmentation
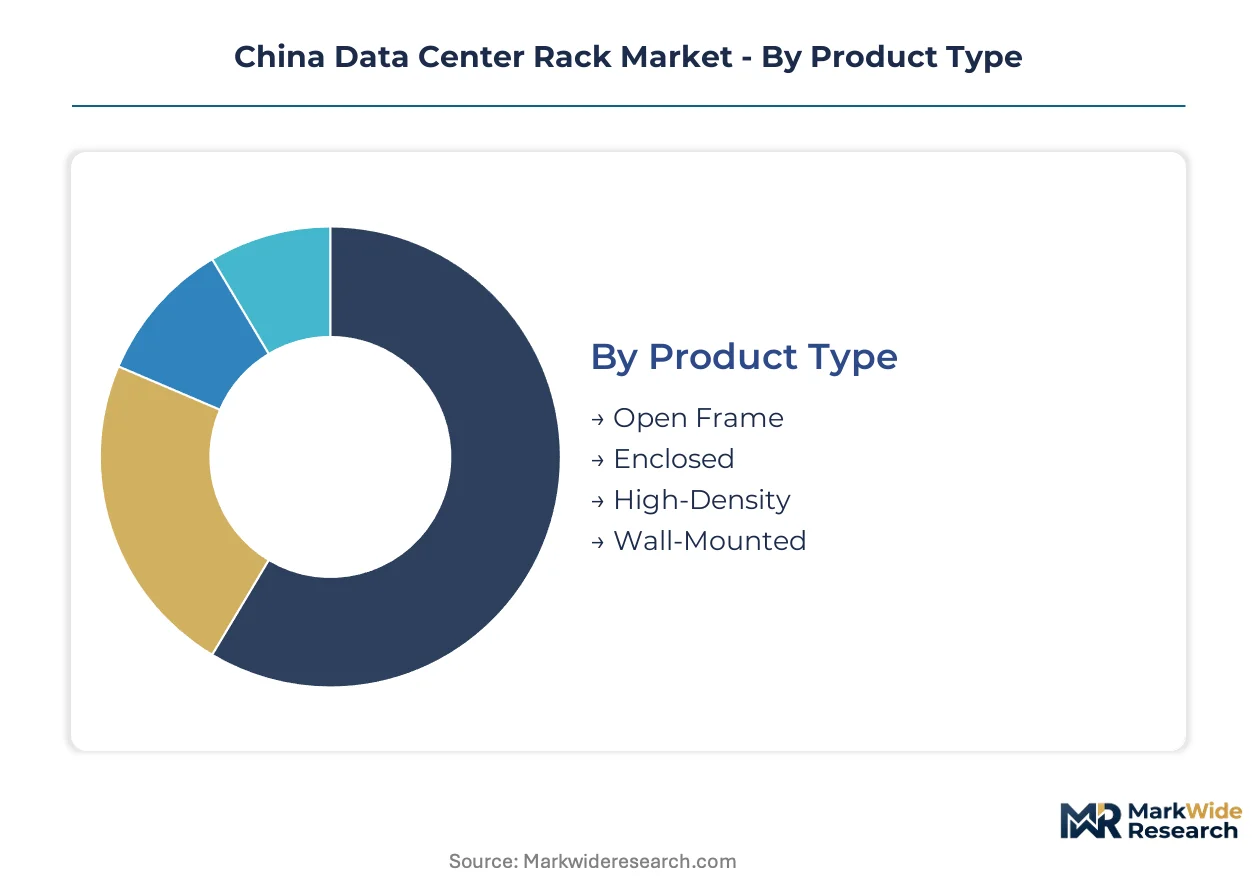
Rack specification fragmentation across China's data center market reflects divergent thermal, security, and density requirements between hyperscale cloud builds and distributed edge infrastructure. Procurement patterns increasingly segment by power density thresholds rather than traditional form factors as MIIT efficiency mandates reshape deployment economics.
Product Type:
Mature open-frame configurations coexist with emerging liquid-cooled high-density variants as operators navigate retrofit versus greenfield investment cycles.
- Enclosed:Lockable side panels and thermal containment doors address physical security mandates from MIIT and enterprise compliance teams. Beijing and Shanghai financial services operators specify these for multi-tenant facilities where tenant isolation drives procurement.
- High-Density:Reinforced frames support 30+ kW GPU clusters with integrated liquid cooling manifolds and blind-mate power busbars. Cloud providers in Shenzhen and Hangzhou commission these for AI training workloads under compressed provincial energy quota deadlines.
- Open Frame:Standardized 19-inch EIA mounting without enclosure panels serves cost-optimized hyperscale halls with perimeter security.
- Wall-Mounted:Compact 6U-12U cabinets support network closets and branch office server consolidation in Tier-2 city enterprise deployments.
Enclosed racks retain volume leadership; high-density variants hold the steepest expansion curve.
End User:
Customer-type concentration shapes specification divergence between capital-intensive hyperscale builds and budget-constrained institutional deployments.
- Cloud Service Providers:Alibaba, Tencent, and ByteDance issue multi-year framework agreements specifying custom rack dimensions and cooling interfaces. Their procurement concentrates in Jiangsu and Zhejiang manufacturing corridors for just-in-time delivery.
- Telecom Providers:China Mobile and China Unicom deploy modular edge racks across Tier-2 and Tier-3 cities for 5G latency-sensitive applications. Weather-hardened specifications dominate their outdoor node requirements.
- Enterprises:Private data center builds in manufacturing and logistics sectors favor standardized enclosed racks with integrated cable management.
- Government Institutions:State-owned enterprises and provincial cloud projects prioritize SAMR-certified domestic suppliers under procurement localization directives.
Cloud service providers anchor procurement volume; telecom edge deployments are gaining share fastest.
Deployment:
Physical location strategy segments rack requirements across centralized efficiency optimization versus distributed latency reduction tradeoffs.
- Colocation:Multi-tenant facilities in Beijing, Shanghai, and Shenzhen deploy standardized 42U-48U enclosed racks with dual power feeds. Operator competition on PUE metrics drives demand for hot-aisle containment configurations.
- Edge Computing:Micro data centers in western provinces and Tier-2 cities require NEMA-rated outdoor enclosures with integrated cooling and power distribution. Ningxia and Guizhou renewable energy quotas attract these deployments.
- On-Premises:Enterprise-owned facilities in Guangdong and Jiangsu face retrofit pressure from GB 50174 efficiency thresholds.
- Hybrid:Mixed cloud-private workloads drive rack standardization across owned and leased footprint.
Colocation maintains revenue concentration; edge computing infrastructure shows the most rapid specification evolution.
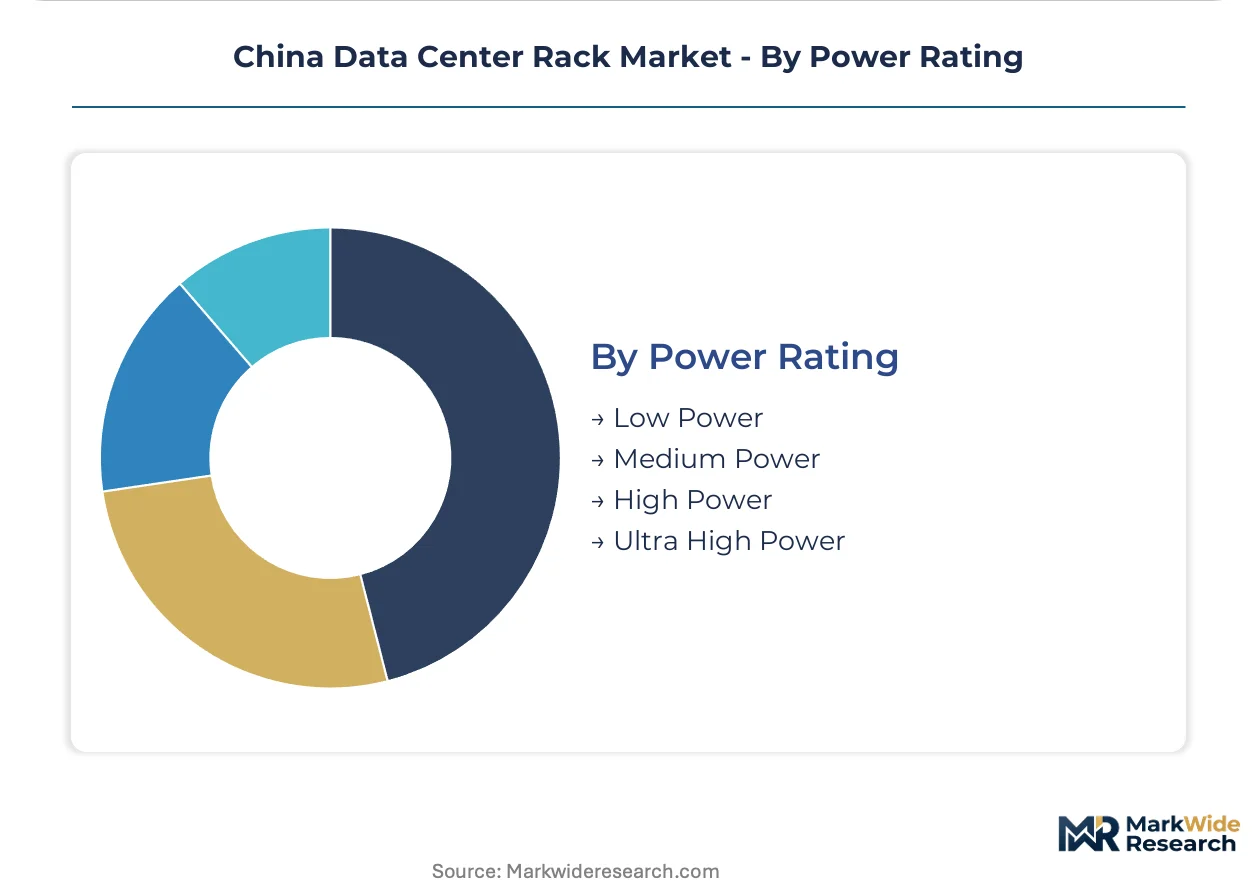
Power Rating:
Density tier segmentation compresses legacy air-cooled categories while ultra-high-power liquid-cooled configurations capture disproportionate capital allocation.
- Ultra High Power:50+ kW direct-to-chip and immersion cooling racks serve AI training clusters. Hyperscale pilots in Beijing are testing two-phase immersion for 100+ kW densities.
- High Power:20-50 kW air-cooled and hybrid liquid-assisted configurations bridge legacy retrofits and new GPU deployments.
- Medium Power:5-20 kW standard density serves general compute and storage workloads in enterprise facilities.
- Low Power:Sub-5 kW network and edge equipment racks dominate telecom access node deployments.
Medium power ratings retain installed base dominance; ultra-high-power configurations command the steepest investment trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale operators in eastern coastal provinces show the least price elasticity for premium liquid-cooled racks, while Tier-2 city edge deployments in central and western regions drive hard negotiations on standardized enclosures.
Beijing-Tianjin-Hebei
MIIT's GB 50174 enforcement and municipal carbon quotas compress procurement timelines for 30+ kW AI training racks. Beijing municipal authorities deny construction permits to facilities projected above 1.3 PUE. Daxing International Airport Economic Zone hosts concentrated hyperscale builds serving state cloud and fintech workloads.
Yangtze River Delta
Alibaba, Tencent, and ByteDance issue multi-year framework agreements specifying custom rack dimensions and cooling interfaces. Jiangsu and Zhejiang provincial economic planning commissions prioritize PUE compliance in new data center approvals. Suzhou and Hangzhou manufacturing corridors enable just-in-time rack delivery against compressed construction schedules.
Pearl River Delta
Guangdong provincial grid capacity constraints delay rack energization timelines and extend customer payment cycles. Shenzhen and Guangzhou hyperscale operators pilot two-phase immersion cooling for 100+ kW AI clusters. Dongguan fabrication hubs supply reinforced frames with integrated liquid cooling manifolds.
Western China
Ningxia, Guizhou, and Inner Mongolia offer subsidized land and renewable energy quotas for rack deployments serving eastern load centers via dedicated fiber trunk lines. Provincial dual carbon enforcement timelines remain more flexible than coastal counterparts. Zhongwei and Gui'an New Area host government-directed cloud computing bases with standardized procurement.
Sichuan-Chongqing
Chengdu and Chongqing municipal governments attract data center investment through electricity price discounts and simplified approval processes. Local operators favor medium-power air-cooled racks for general compute workloads. Western Hub Big Data Industrial Park in Yibin concentrates rack deployment for disaster recovery and cold storage applications.
China Data Center Rack Market Competitive Landscape
Capability concentration sits with integrated power-cooling specialists; scale advantage sits with domestic fabricators with state-backed procurement relationships. The vendor base stratifies across three tiers: multinational platform providers with full-stack portfolios, domestic champions with MIIT certification priority, and regional metal fabricators competing on raw material access. Dominant competitive moves include backward integration into thermal management components and geographic expansion into western provincial clusters under Ningxia and Guizhou incentive programs.
Within the multinational tier, Schneider Electric SE and Rittal GmbH & Co. KG occupy positions anchored by integrated power distribution and enclosure portfolios. Huawei exemplifies vertical control from silicon through rack assembly, leveraging in-house semiconductor design to specify custom power busbar configurations. Inspur represents the domestic manufacturing scale archetype, capturing procurement volume from state-affiliated cloud providers under localization directives. These three patterns—platform breadth, captive technology stack, and production scale—define the competitive structure.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Rittal GmbH & Co. KG |
| Huawei |
| Dell Inc. |
| Black Box Corporation |
| Inspur |
| Eaton Corporation |
| Legrand SA |
| Vertiv Group Corp |
| Others |
Pricing and Supply Chain Analysis
Steel and copper concentrate among state-owned metal traders in Hebei and Jiangsu provinces, concentrating margin capture in raw material tiers while downstream rack fabricators face compressed assembly margins. This upstream consolidation forces domestic manufacturers toward lifecycle service contracts to recover profitability pools eroded at the hardware tier.
Pricing Analysis
Lifecycle maintenance contracts and decade-long service agreements now drive lifetime value capture for rack vendors. Three-tier pricing structure across premium liquid-cooled, standard enclosed, and economy open-frame configurations stratifies procurement tiers. Price differentiation rests on MIIT GB 50174 certification grade and integrated thermal management complexity. Cloud providers in Beijing and Shanghai show minimal price sensitivity for 30+ kW AI racks, while Tier-2 city telecom edge deployments negotiate aggressively on standardized enclosures. Cost compression in medium-power air-cooled segments is intensifying because copper price volatility squeezes fabricator margins.
Supply Chain Analysis
US export controls on advanced GPU and high-bandwidth memory technologies limit rack-level integration options for AI training clusters. Manufacturing concentrates in China, Germany, and the United States for precision enclosure fabrication and thermal management components. Cold-rolled steel, copper busbar, and dielectric cooling fluids anchor raw material dependencies. Single-source vulnerability runs through domestic liquid cooling manifold suppliers serving hyperscale pilots. Distribution runs through direct OEM relationships with Alibaba, Tencent, and ByteDance, bypassing traditional IT distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's data center rack market sits in early-cycle expansion as AI training cluster deployments accelerate liquid-cooled rack penetration ahead of provincial energy quota deadlines. MIIT's dual carbon enforcement timelines compress procurement cycles and favor vendors with certified high-density thermal platforms.
For Market Incumbents: Harden certification pipelines for GB 50174-2017 amendment compliance before MIIT tightens PUE thresholds. Deepen captive supply of liquid cooling manifolds and blind-mate power busbars to defend against emerging domestic thermal specialists. Anchor field service networks in Ningxia and Guizhou to capture lifecycle contracts under western provincial incentive programs. For New Entrants and Emerging Players: Establish a beachhead in modular edge rack specifications for China Mobile and China Unicom 5G deployments across Tier-2 and Tier-3 cities. Target weather-hardened NEMA-rated enclosures where hyperscale incumbents lack tailored product lines. Partner with Dongguan fabrication hubs for rapid prototype-to-production scaling against compressed delivery timelines. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated thermal-electrical platform specialists with in-house CFD modeling capabilities and MIIT certification priority. Long-term viability favors vendors controlling both rack assembly and direct-to-chip cooling integration. Watch for inflection when MIIT publishes finalized GB 50174 amendment drafts certifying 100+ kW immersion cooling configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Platform Integration | Schneider Electric and Huawei anchor positions through unified thermal-electrical rack platforms. |
| Backward Integration into Cooling Manifolds | Domestic fabricators secure supply continuity for 30+ kW AI rack deployments under quota pressure. |
| Western China Geographic Expansion | Ningxia and Guizhou renewable energy quotas attract rack deployments serving eastern load centers. |
| MIIT Certification Investment | SAMR compliance gates market access and creates procurement preference for domestic suppliers. |
| Lifecycle Service Contract Scaling | Cloud providers unbundle hardware from decade-long maintenance, creating recurring revenue pools. |
Research Methodology
A spread of perspectives from data center engineering directors, MIIT policy researchers, cloud provider procurement leads, and thermal systems specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against MIIT GB standard filings, provincial economic planning commission construction permits, hyperscaler capex disclosures, and customs data on steel and copper inputs. Bottom-up rack deployment tallies triangulated against top-down data center construction pipeline estimates.
Demand-supply balance modeling anchored projections across the analysis window. Segmentation dimensions included product type, power density tier, end-user archetype, and deployment geography. CAGRs derived from deployment run-rate analysis against provincial energy quota timelines. Forecast inputs incorporated MIIT dual carbon enforcement schedules and AI training cluster expansion curves from Beijing, Shanghai, and Shenzhen hyperscale operators.
Stress conditions across copper price volatility, provincial grid capacity constraints, and GB standard revision lag were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on MIIT enforcement consistency and hyperscale capex commitment levels. Material shifts in US export control scope or MIIT PUE threshold timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Mumbai Data Center Market
Data Center Infrastructure
Italy Data Center Rack Market
Data Center Infrastructure
Hyperscale Data Center Market
Data Center Infrastructure
US Data Center Rack Market
Data Center Infrastructure
APAC Green Data Center Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
Switzerland Data Center Market
Data Center Infrastructure
London Data Center Market
Data Center Infrastructure
LAMEA Virtual Desktop Infrastructure Market
Data Center Infrastructure
New Zealand Data Center Power Market
Data Center Infrastructure
Global Data Center RFID Market
Data Center Infrastructure
Spain Data Center Physical Security Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
IT Infrastructure Management Tools Market
Data Center Infrastructure
Managed Data Center Services Market
Data Center Infrastructure
Data Center Construction Market