
 Server Station Market | 2026-2036
Server Station Market Size, Share, and Industry Trends Forecast 2026-2036
Server Station Market Analytics
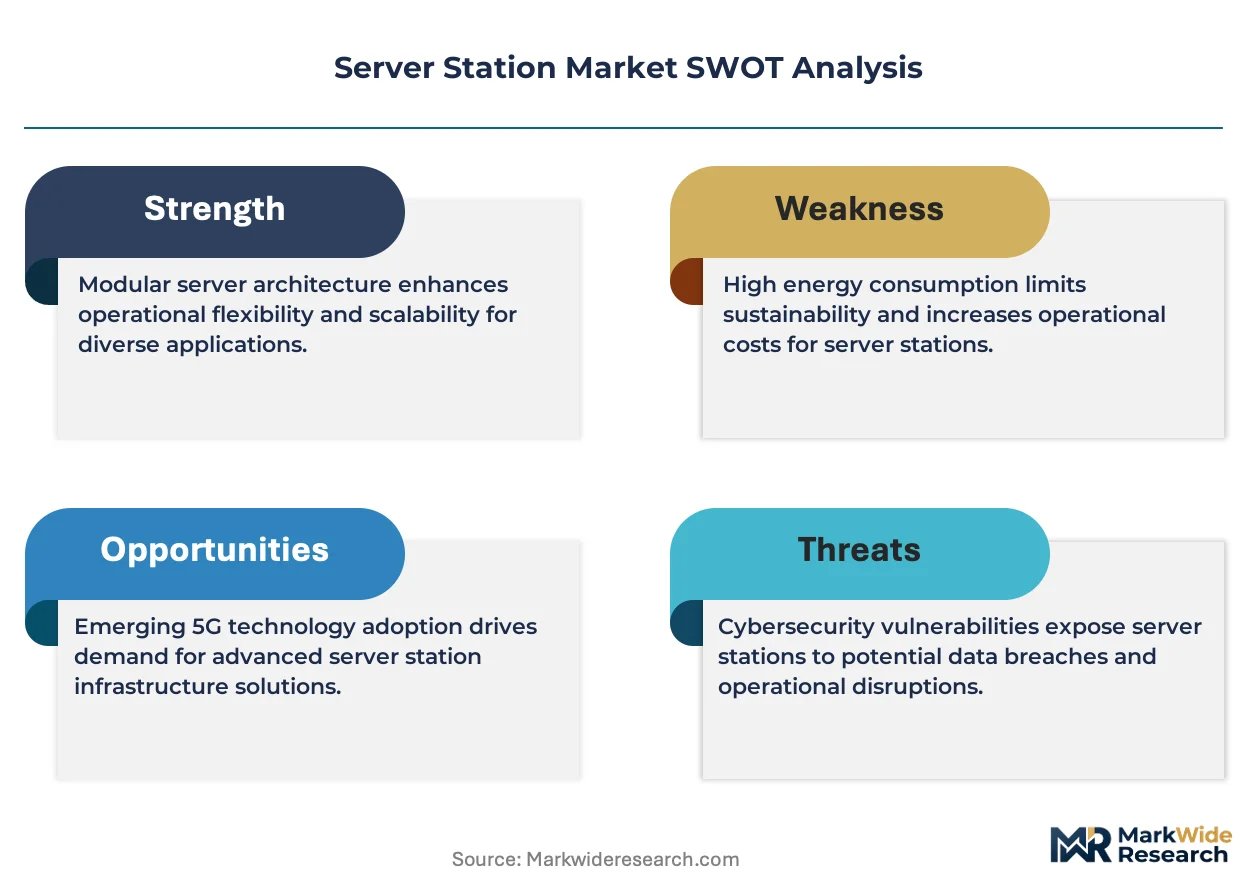
ISO/IEC 27001 certification is reorganizing vendor eligibility for government and financial contracts, pushing smaller integrators toward compliance investments or partnership models. Dell Technologies leverages its direct supply chain control to sustain margin structures across enterprise rack deployments. HPE anchors its position through in-house silicon development for edge-optimized server lines. Supermicro competes aggressively on thermal design density for AI training clusters.
A server station comprises compute hardware—processors, memory modules, storage arrays, and network interface cards—housed in standardized enclosures designed for rack, blade, or modular configurations, typically operating within 10°C to 35°C ambient thresholds and drawing 200W to 30kW per unit depending on workload intensity. Its primary purpose centers on centralized data processing, virtualization hosting, and cloud service delivery for enterprise and telecommunications workloads. Rack servers dominate volume shipments across data center applications due to flexible density scaling and established cable management conventions. Blade configurations capture premium positioning in cloud computing deployments where shared power and cooling infrastructure reduce per-unit operational overhead. Tower variants retain stable demand within education and small government facilities constrained by capital budgets and existing physical infrastructure.
EPA ENERGY STAR specifications and EU Ecodesign requirements now mandate minimum efficiency thresholds for server power supplies, effectively filtering entry-level suppliers from transatlantic procurement pools. FCC equipment authorization and CE marking impose electromagnetic compatibility standards that extend product development cycles by six to eighteen months for non-compliant designs. Stakeholders must weigh regulatory certification costs against the volume premium accessible in North American and European public-sector tenders.
Market Dynamics
Liquid-cooled rack configurations are restructuring procurement priorities as hyperscale operators confront EPA energy efficiency mandates and thermal density limits in AI training clusters.
Growth Catalysts
- EPA ENERGY STAR thresholds:Federal efficiency mandates compel data center operators to retire legacy air-cooled infrastructure and adopt liquid-cooled alternatives.
- AI training workload density:Generative model development concentrates compute demand in specialized GPU clusters requiring 30kW+ per rack unit.
- Taiwan ODM capacity:Concentrated motherboard manufacturing in Hsinchu and Taichung Science Parks accelerates server platform iteration cycles.
Market Restraints
- Copper and rare earth input volatility:Power distribution components and high-performance magnet supply expose margins to commodity price swings.
- Single-source liquid cooling component risk:Cold plate and manifold fabrication concentrates among specialized Taiwanese and German suppliers.
- FCC electromagnetic compatibility timelines:Six-to-eighteen month authorization cycles delay product launches for non-compliant designs.
Strategic Opportunities
- India data center buildout:PLI scheme incentives and digital infrastructure investments open greenfield deployment opportunities outside saturated East Asian markets.
- Edge-optimized server convergence:Integration of 5G baseband processing with compute nodes creates new form factor categories for telecommunications deployments.
- ISO/IEC 27001 certification gap:Smaller integrators face exclusion from government tenders, creating partnership or acquisition targets for compliant vendors.
Industry Challenges
- Thermal engineering talent scarcity:Liquid cooling system design and computational fluid dynamics simulation skills outpace supply in North American and European labor markets.
- Legacy air-cooled infrastructure stranded asset risk:Enterprise data centers face write-downs on five-to-seven year depreciation schedules misaligned with three-year cooling technology refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Server Station Market |
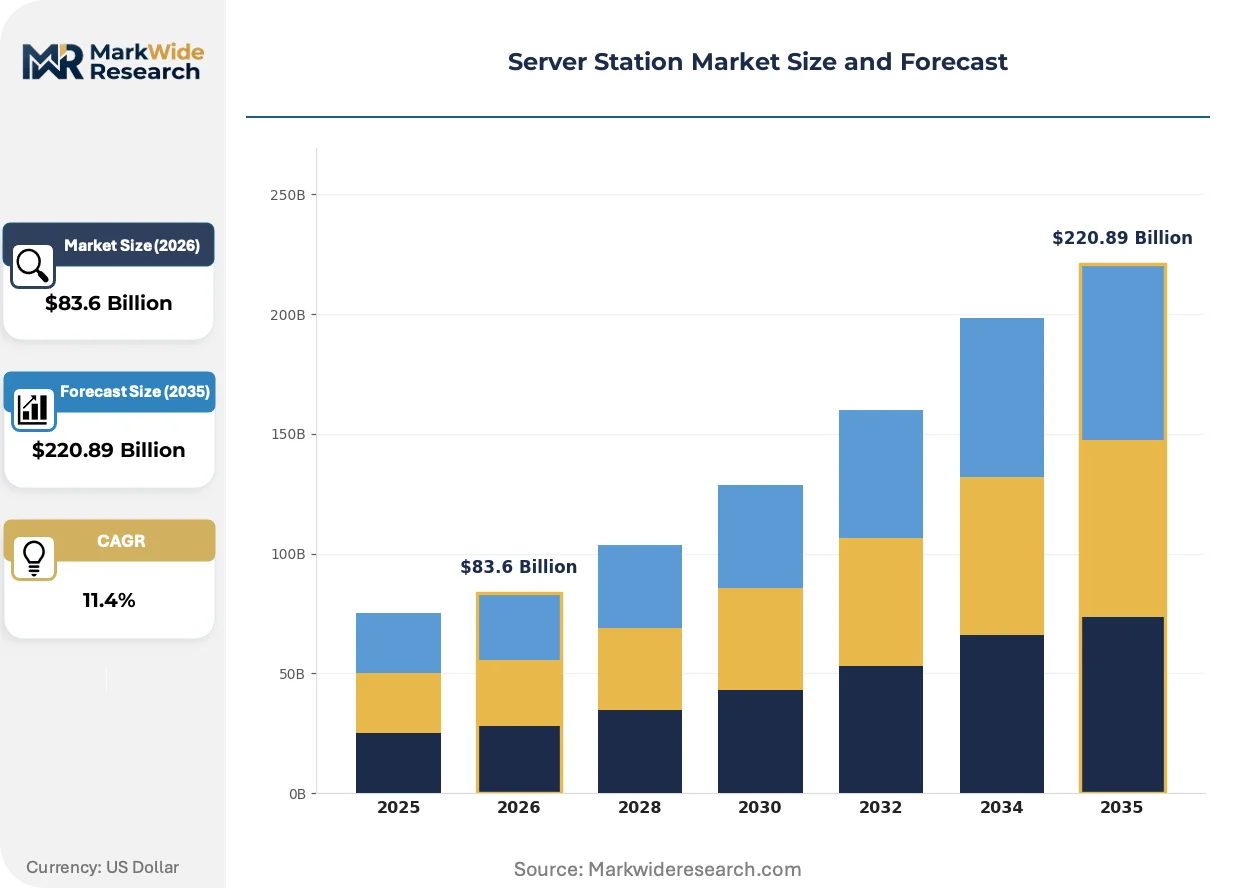
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $220.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Servers, Rack Servers, Tower Servers, Modular Servers Application: Data Center, Cloud Computing, Virtualization, Web Hosting End User: IT Enterprises, Telecommunications, Government, Education Connectivity: Ethernet, Fiber Channel, InfiniBand, Wireless |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise (HPE), Supermicro, Inspur, Lenovo, Cisco Systems, Schneider Electric, Vertiv, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Server Station Market Evolving Landscape
Direct-to-chip liquid cooling architectures are compressing facility-level power usage effectiveness ratios while reshaping rack-level integration requirements across hyperscale and enterprise deployments.
Immersion cooling systems using engineered dielectric fluids are displacing traditional air-handling unit configurations in high-density AI training environments. Hyperscale operators in the United States and Germany are piloting two-phase immersion for 100kW+ rack densities. This displacement is collapsing the mechanical infrastructure cost per kilowatt by eliminating raised floor plenum and perimeter CRAC unit requirements.
EU Ecodesign requirements for server power supply efficiency are filtering entry-level suppliers from transatlantic procurement pools. The regulation mandates minimum load-proportional efficiency curves that legacy 80 PLUS Bronze designs fail to meet. Tier-one OEMs are responding by vertically integrating power supply design and qualifying only platinum-rated units for European shipments.
Cloud service providers are consolidating server procurement under direct ODM relationships, bypassing traditional channel distributors for standardized rack configurations. This disintermediation concentrates volume with Taiwanese and South Korean manufacturers while compressing margin structures for value-added resellers. The pattern is most visible in North American hyperscale contracts where direct procurement now exceeds fifty percent of annual server volume.
Server Station Market Segmentation
Server station procurement patterns diverge sharply across deployment contexts, with hyperscale operators, enterprise IT departments, and government agencies each imposing distinct thermal, security, and interoperability requirements on hardware configurations.
Product Type:
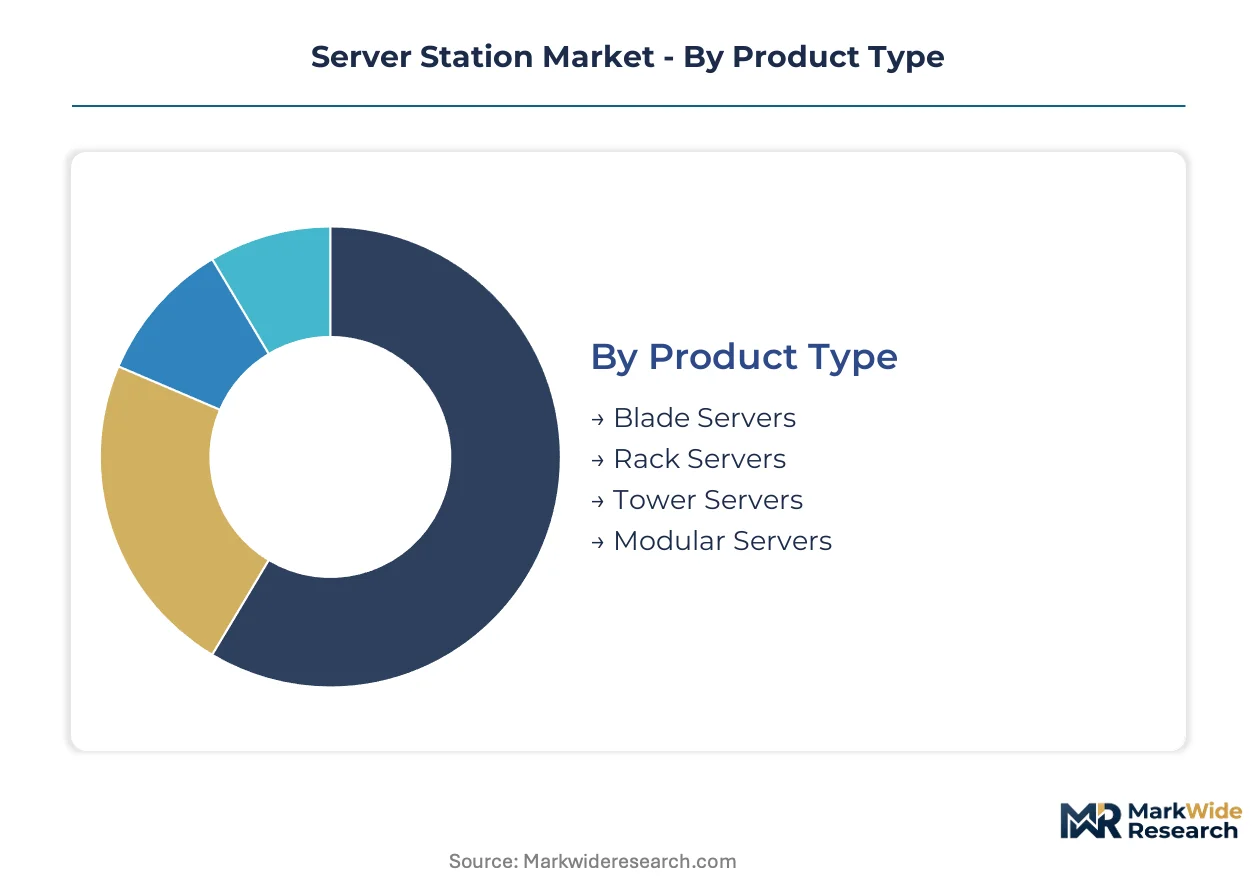
Domestic procurement in the United States and Germany concentrates on rack and blade configurations for hyperscale data centers, while tower servers retain stronger demand in education and small government facilities across India and Brazil with constrained capital budgets.
- Rack Servers:Standardized 19-inch enclosures accommodate processors, memory modules, and storage arrays in vertically stackable units. Demand concentrates in North American hyperscale facilities where flexible density scaling aligns with 10kW to 30kW per-rack power envelopes. EPA ENERGY STAR mandates accelerate retirement of legacy air-cooled rack infrastructure.
- Blade Servers:Shared power and cooling infrastructure across multiple compute nodes reduces per-unit operational overhead. Cloud computing deployments in Germany and the United States drive premium positioning where space constraints and energy efficiency targets outweigh acquisition cost premiums.
- Tower Servers:Self-contained vertical enclosures suit facilities lacking raised floor infrastructure. Education sectors in India and Brazil sustain stable demand through depreciation schedules aligned with constrained refresh cycles.
- Modular Servers:Disaggregated compute, storage, and networking components enable workload-specific resource pooling. Emerging adoption in edge computing deployments across Japan and South Korea.
Rack servers command the established base. The steepest expansion runs through blade configurations in cloud computing environments.
Application:
Cost tier stratification separates capital-intensive data center builds from operational-expense-driven cloud service consumption, with virtualization and web hosting occupying intermediate positions on the infrastructure ownership spectrum.
- Data Center:Enterprise-owned facilities housing centralized compute infrastructure for internal workloads. Demand concentrates in United States financial services and healthcare verticals where HIPAA and SOX compliance requirements mandate on-premise control.
- Cloud Computing:Third-party provisioned infrastructure with consumption-based pricing. Hyperscale operators in Germany and the United States drive volume through direct ODM procurement relationships bypassing traditional channel distributors.
- Virtualization:Software abstraction of physical compute resources into logical partitions. Mid-market enterprises in the United Kingdom and France adopt hybrid deployments balancing on-premise control with burst capacity.
- Web Hosting:Shared or dedicated server provision for internet-facing applications. Price-sensitive demand in Southeast Asia and Eastern Europe concentrates on commodity rack configurations.
Data center applications retain the revenue base. Cloud computing gains share fastest through hyperscale operator procurement consolidation.
End User:
Customer type determines certification requirements and procurement channel access, with government and telecommunications imposing the most stringent qualification barriers.
- IT Enterprises:Corporate technology departments across banking, manufacturing, and retail verticals. ISO/IEC 27001 certification increasingly filters vendor eligibility for procurement shortlists in European and North American markets.
- Telecommunications:Network operators integrating compute with 5G infrastructure. Edge-optimized server demand accelerates in South Korea and Japan through baseband processing convergence requirements.
- Government:Federal, state, and municipal agencies with mandated security and domestic content requirements. FCC equipment authorization and CE marking extend development cycles for non-compliant designs.
- Education:Universities and K-12 institutions with depreciation schedules and physical infrastructure constraints. Tower server demand persists in budget-constrained markets.
IT enterprises anchor volume shipments. Telecommunications represents the steepest climb through 5G edge infrastructure buildouts.
Connectivity:
Supply concentration in high-speed interconnects shapes procurement options, with InfiniBand and Fiber Channel requiring specialized integration expertise concentrated in Taiwanese and German component suppliers.
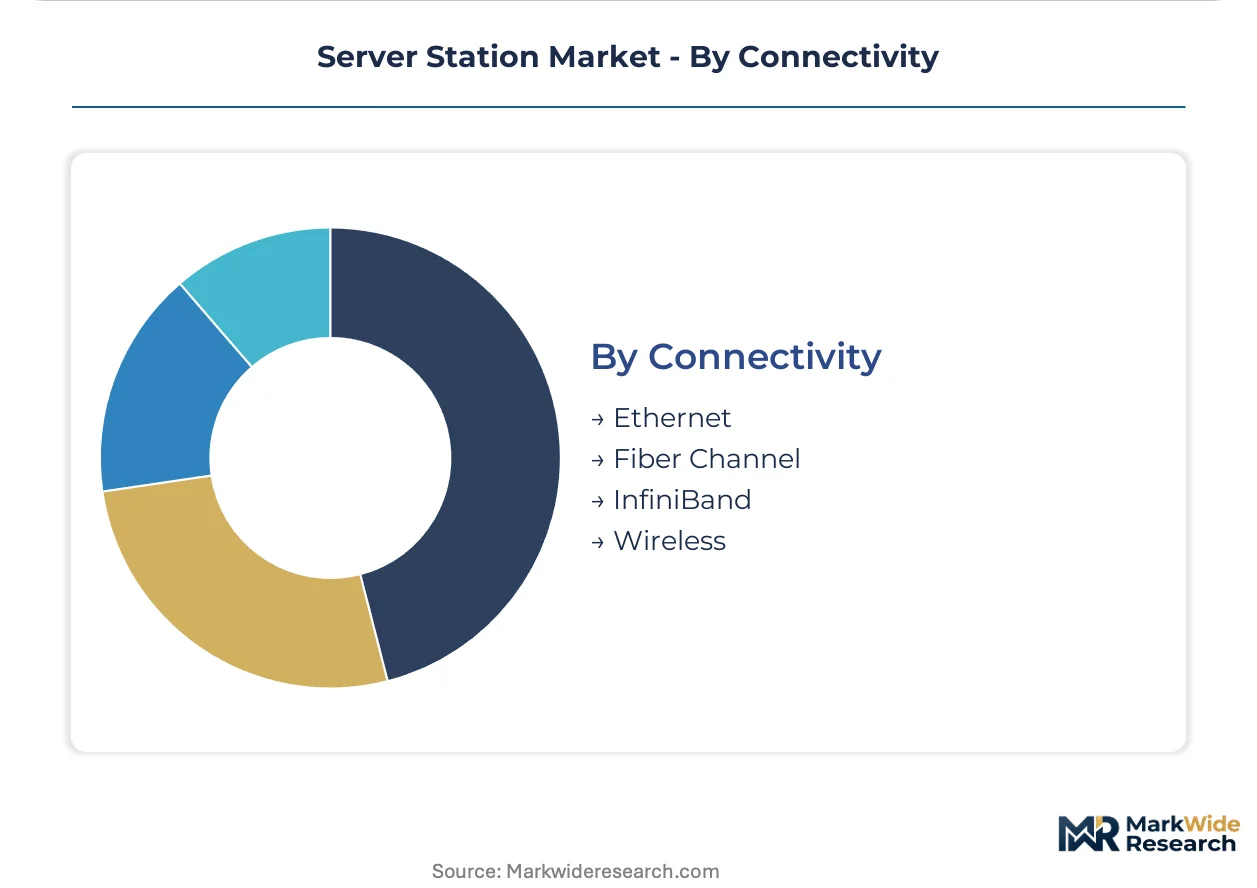
- Ethernet:Dominant Layer 2 protocol for general-purpose data center traffic. Standardized 10GbE through 400GbE interfaces suit enterprise virtualization and web hosting workloads across all geographies.
- InfiniBand:Low-latency, high-throughput interconnect for high-performance computing clusters. AI training deployments in the United States and Germany adopt 400Gb/s NDR configurations for GPU cluster scaling.
- Fiber Channel:Storage area network protocol for enterprise block storage access. Financial services data centers in the United States and United Kingdom sustain demand through legacy infrastructure refresh cycles.
- Wireless:Wi-Fi and cellular backhaul for edge and remote deployments. Emerging adoption in industrial IoT and temporary event infrastructure.
Ethernet retains connectivity dominance. InfiniBand climbs fastest through AI cluster density requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center operators in the United States drive procurement volume for liquid-cooled rack configurations, while East Asian manufacturing clusters control critical server board production capacity. Government efficiency mandates in Germany and domestic content requirements in India reshape competitive access across procurement pools.
United States
EPA ENERGY STAR mandates compel hyperscale operators to retire legacy air-cooled infrastructure and adopt liquid-cooled alternatives for AI training clusters. FCC equipment authorization timelines extend six to eighteen months for non-compliant electromagnetic designs. Northern Virginia and Dallas-Fort Worth data center corridors concentrate new rack deployments for cloud service providers.
Germany
EU Ecodesign requirements for server power supply efficiency filter entry-level suppliers from procurement pools through minimum load-proportional efficiency curves. The country's national data center efficiency regulator enforces strict thermal performance standards for enterprise facilities. Frankfurt and Berlin metropolitan areas anchor enterprise-owned data center construction for financial services compliance.
China
MIIT domestic content requirements and dual carbon goals accelerate procurement of locally manufactured server platforms for government and telecommunications workloads. The national standards administration mandates GB certification for electromagnetic compatibility in data center equipment. Yangtze River Delta manufacturing clusters in Shanghai and Suzhou concentrate motherboard production for regional supply.
India
PLI scheme incentives and digital infrastructure investments open greenfield deployment opportunities for hyperscale operators outside saturated East Asian markets. TRAI spectrum allocation policies accelerate 5G edge infrastructure buildouts requiring compute-integrated baseband processing. Maharashtra and Karnataka states concentrate data center construction in Mumbai and Bangalore technology corridors.
South Korea
5G baseband processing convergence requirements accelerate demand for edge-optimized server configurations in telecommunications infrastructure. The national telecommunications regulator enforces equipment certification standards for network-integrated compute nodes. Seoul Capital Area and Busan-Ulsan industrial zones concentrate ODM production capacity for regional export.
Server Station Market Competitive Landscape
Player mix skews toward vertically integrated OEMs with captive supply chain control and specialized ODMs serving hyperscale direct procurement channels. Tier-one OEMs anchor enterprise and government segments through certification compliance and service infrastructure. ODMs capture hyperscale volume through direct relationships bypassing traditional channel distributors. Competitive moves concentrate on backward integration into power supply design and thermal engineering capability acquisition.
Within the tier-one OEM tier, Dell Technologies, HPE, and Supermicro exemplify divergent strategic positioning. Dell Technologies occupies a position emphasizing direct supply chain control across enterprise rack deployments. HPE anchors its competitive stance through in-house silicon development for specialized workload optimization. Supermicro sits within the thermal design density specialist archetype, competing aggressively on liquid-cooled configurations for AI training clusters.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise (HPE) |
| Supermicro |
| Inspur |
| Lenovo |
| Cisco Systems |
| Schneider Electric |
| Vertiv |
| Huawei Technologies |
| Others |
Value Network & Pricing Analysis
Ninety-to-one-hundred-twenty-day motherboard lead times concentrate pricing power with Taiwanese ODMs serving hyperscale direct procurement channels, while copper and rare earth input volatility compresses margins for tier-two integrators lacking long-term offtake agreements.
Pricing Analysis
Cost-plus contracts indexed to LME copper and NdFeB magnet spot prices dominate hyperscale procurement, insulating ODMs from commodity swings while exposing enterprise buyers to passthrough volatility. Three-tier pricing structure across liquid-cooled premium, air-cooled standard, and legacy economy configurations separates certification-grade EPA ENERGY STAR units from entry-level alternatives. Cost compression in standard rack tiers is intensifying because cloud service providers are consolidating volume under direct ODM relationships. Government and telecommunications segments exhibit lowest price sensitivity due to mandated domestic content and security certification requirements.
Supply Chain Analysis
Taiwan and South Korea anchor critical server motherboard and high-bandwidth memory production, with Hsinchu Science Park and Yongin semiconductor clusters feeding global hyperscale deployment pipelines. Cold plate fabrication and precision manifold machining draw from specialized German and Taiwanese component suppliers, creating single-source vulnerability for liquid-cooled rack configurations. Distribution runs through direct ODM relationships for hyperscale operators and tier-one OEM channel networks for enterprise and government segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward hyperscale operators consolidating procurement under direct ODM contracts, fragmenting traditional channel distributor relevance and compressing margin structures for value-added resellers lacking thermal engineering differentiation.
For Market Incumbents: Compound defensive positioning through backward integration into power supply design and captive qualification of platinum-rated units for EU Ecodesign compliance. Acquire specialized thermal engineering talent pools in Taiwan and Germany to defend against ODM disintermediation. Lock in long-term rare earth magnet offtake agreements to insulate margins from commodity volatility. For New Entrants and Emerging Players: Lead with ISO/IEC 27001 certification as a wedge into government and financial services procurement shortlists currently filtering out smaller integrators. Target India's PLI-subsidized data center buildout through edge-optimized server configurations integrating 5G baseband processing. Pursue partnership models with compliant tier-one OEMs rather than direct hyperscale competition. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate industrial parents with stranded liquid cooling component divisions lacking hyperscale customer relationships. Long-term viability hinges on thermal engineering capability depth and ODM relationship access. Watch for inflection when EPA mandates accelerate legacy air-cooled infrastructure retirement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Direct ODM Relationship Establishment | Bypasses traditional channel distributors and captures hyperscale volume concentration. |
| Liquid Cooling Thermal Engineering Acquisition | Addresses talent scarcity in computational fluid dynamics and cold plate design. |
| Power Supply Vertical Integration | Secures platinum-rated unit supply for EU Ecodesign compliance and margin defense. |
| ISO/IEC 27001 Certification Investment | Unlocks government and financial services procurement pools filtering non-compliant vendors. |
| India PLI Scheme Manufacturing Footprint | Captures greenfield data center demand outside saturated East Asian supply clusters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, ODM production filings, and EPA regulatory dockets. Data collection combined structured interviews with data center infrastructure executives, thermal engineering leads at liquid cooling specialists, and procurement officers at cloud service providers. Validation drew from SEC 10-K supply chain disclosures, Taiwan Stock Exchange ODM revenue filings, and FCC equipment authorization databases. Bottom-up server unit shipment estimates triangulated against top-down data center power capacity expansion projections.
Segmentation dimensions modeled include rack configuration type, cooling architecture, workload application, end-user vertical, and regional regulatory cluster across the projection horizon. CAGRs were derived from installed base retirement schedules and efficiency mandate compliance timelines. Forecast inputs incorporated AI training cluster density trajectories and liquid cooling adoption curves in hyperscale facilities.
Forecasts assume regulatory continuity in EPA ENERGY STAR and EU Ecodesign regimes; material policy shifts would require re-modeling. Specific risks include rare earth export restrictions, FCC authorization timeline extensions, and stranded asset acceleration for legacy air-cooled infrastructure. Recalibration cycles align with material shifts in hyperscale procurement consolidation patterns and thermal technology refresh cadences.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
London Data Center Market
Data Center Infrastructure
Water Leak Detection System for Server Rooms and Data Centers Market
Data Center Infrastructure
Denmark Data Center Physical Security Market
Data Center Infrastructure
Data Center Construction Market
Data Center Infrastructure
Data Center Life Cycle Services Market
Data Center Infrastructure
Indonesia Data Center Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
Austria Data Center Market
Data Center Infrastructure
South Korea Data Center Market
Data Center Infrastructure
Italy Data Center Rack Market
Data Center Infrastructure
LAMEA Virtual Desktop Infrastructure Market
Data Center Infrastructure
Japan Data Center Construction Market
Data Center Infrastructure
Europe Data Center Server Market
Data Center Infrastructure
Thailand Data Center Power Market
Data Center Infrastructure
APAC Data Center Server Market
Data Center Infrastructure
Scientific Data Management System Market