
 Data Center in Middle East Market | 2026-2036
Data Center in Middle East Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center in Middle East Market Insights
Liquid cooling is shifting thermal management economics across Middle East data centers as operators confront ambient temperatures exceeding 45°C for extended periods. Khazna Data Centers leverages direct-to-chip cooling architectures to sustain power usage effectiveness ratios below 1.2 in Abu Dhabi facilities. Gulf Data Hub anchors regional interconnection density through its Dubai campus, while Equinix competes on cross-border latency optimization between Europe and Asia-Pacific routes.
A data center in the Middle East constitutes a purpose-built facility housing compute, storage, and networking infrastructure designed to operate in desert climates with ambient temperatures regularly surpassing 40°C and dust particulate challenges, typically employing redundant cooling systems and air filtration rated at MERV 13 or higher to maintain ISO 27001-certified uptime. Colocation services dominate current revenue as enterprises outsource capital-intensive infrastructure builds, while modular data centers represent the fastest-growing deployment architecture by enabling rapid capacity scaling without traditional construction timelines. Cloud services command expanding margin pools as hyperscale providers negotiate multi-year commitments with government and telecom clients.
UAE's Telecommunications and Digital Government Regulatory Authority mandates data residency for financial and healthcare records, compelling foreign operators to establish local presence. Saudi Arabia's National Data Management Office enforces classification standards that restrict certain data categories from cross-border transfer, shaping facility certification requirements. Stakeholders must monitor evolving sovereign cloud policies across Gulf states as localization rules tighten and domestic capacity targets expand.
Market Dynamics
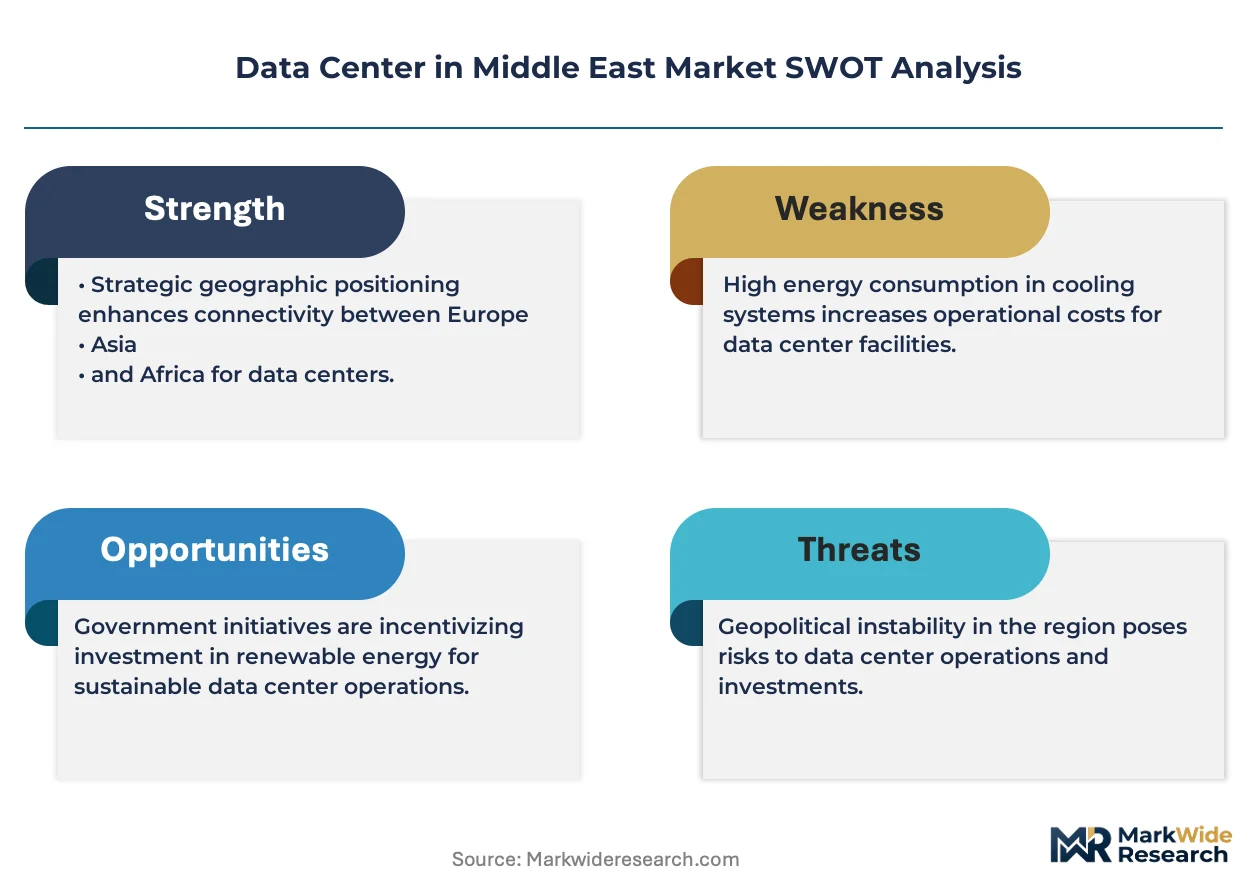
Sovereign data localization mandates across Gulf Cooperation Council states are forcing hyperscale operators to construct certified facilities domestically rather than serving regional demand from European or Asian hubs. This regulatory compression is restructuring capital deployment timelines and vendor selection criteria.
Growth Catalysts
- Vision 2030 Digital Transformation:Saudi Arabia's national framework mandates cloud-first government procurement, compelling state agencies to migrate workloads to in-country facilities.
- Liquid Cooling Architectures:Direct-to-chip and immersion systems enable sustained operations in ambient temperatures exceeding 45°C without prohibitive energy penalties.
- Smart Dubai Initiative:The emirate's regulatory push for AI and blockchain infrastructure anchors demand for tier-III and tier-IV certified colocation capacity.
Market Restraints
- Power Infrastructure Bottlenecks:Grid interconnection timelines in Riyadh and Jeddah lag facility construction by 18-24 months, delaying revenue recognition.
- Desalinated Water Dependency:Cooling system operations rely on energy-intensive water treatment, exposing opex to oil-price-linked electricity tariffs.
- Construction Labor Concentration:Specialized data center contracting capacity concentrates in the UAE, inflating build costs in Saudi Arabia and Kuwait.
Strategic Opportunities
- Edge Computing in Secondary Cities:Dammam, Muscat, and Manama lack hyperscale presence despite growing enterprise demand from energy and logistics sectors.
- Green Hydrogen Power Purchase Agreements:NEOM's renewable energy cluster offers 100% carbon-free electricity contracts that satisfy EU-linked corporate sustainability requirements.
- Modular Deployment Architectures:Prefabricated all-in-one modules compress commissioning from 24 months to 6 months for cloud providers needing rapid capacity.
Industry Challenges
- Certified Engineering Talent Scarcity:Uptime Institute-accredited design professionals and BICSI-certified technicians remain concentrated in Dubai, constraining multi-site expansion.
- Cross-Border Data Classification Complexity:Saudi Arabia's National Data Management Office restrictions on certain data categories force operators to architect physically segmented network zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center in Middle East Market |
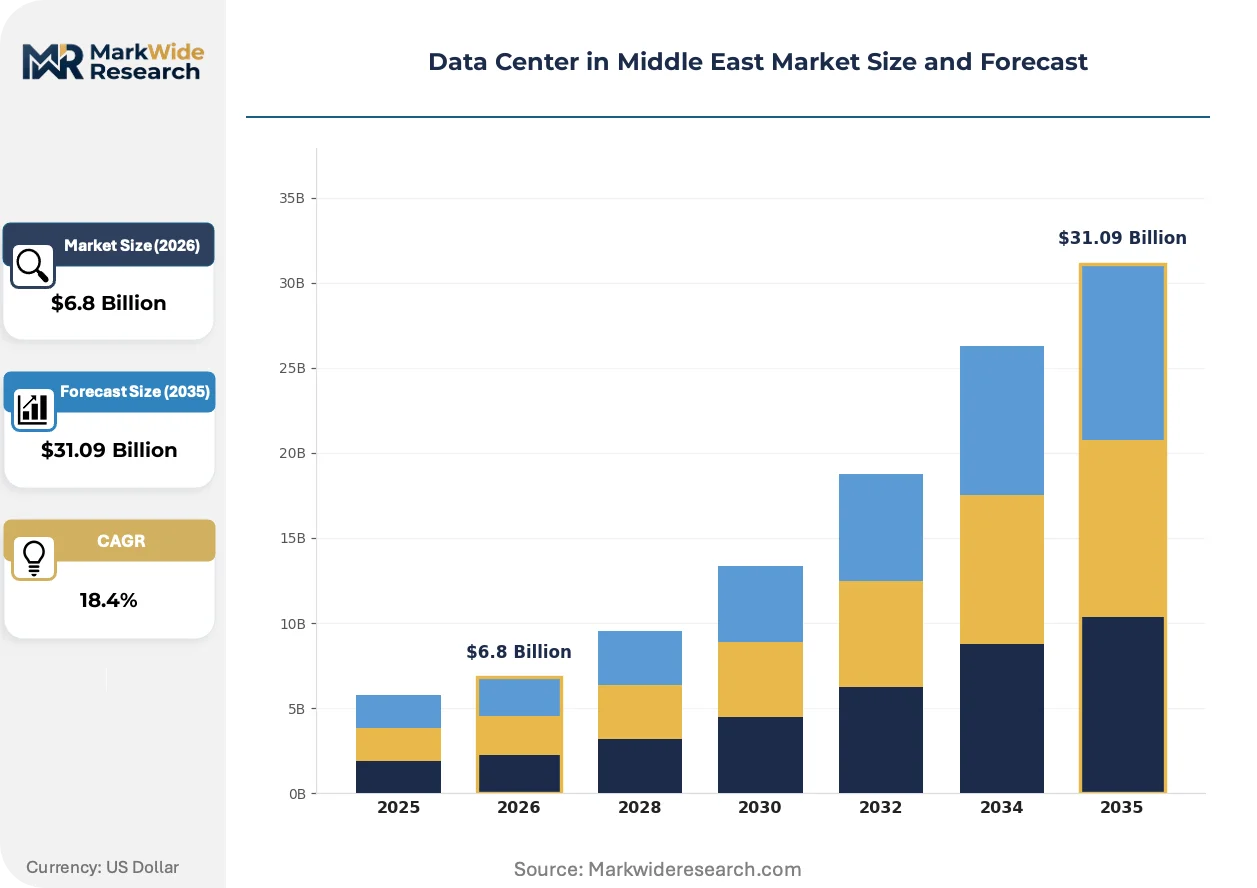
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Blade Servers, Rack Servers, Modular Data Centers, High-Density Solutions Service Type: Colocation Services, Managed Services, Cloud Services, Disaster Recovery End User: Enterprises, Government Agencies, Telecommunication Companies, Educational Institutions Deployment: On-Premise, Hybrid Cloud, Multi-Cloud, Remote Cloud |
| Companies Covered | Khazna Data Centers, Gulf Data Hub, Etisalat, STC, center3, Edgnex Data Centres, Equinix, Digital Realty, DataVolt, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center in Middle East Market Trends and Innovations
Liquid cooling is compressing thermal management economics across desert climates while sovereign cloud frameworks reconfigure buyer-supplier relationships. These shifts are accelerating facility design standardization and procurement model evolution.
Immersion cooling using dielectric fluids is converging with high-density GPU clusters for AI training workloads. Hyperscale operators in Abu Dhabi and Riyadh are deploying single-phase immersion tanks at 50-100 kW per rack. This convergence is displacing traditional CRAH-based designs for new-build facilities above 10 MW capacity.
UAE's Telecommunications and Digital Government Regulatory Authority mandates data residency for financial and healthcare records, compelling foreign cloud providers to establish local availability zones. Financial institutions must maintain primary data storage within national borders, with cross-border replication restricted to disaster recovery only. Banks and insurers are responding by negotiating dedicated suites in certified tier-III facilities rather than public cloud shared infrastructure.
Enterprise buyers are consolidating vendor relationships from multi-provider strategies to single-partner frameworks with committed capacity blocks. This concentration displaces transactional colocation contracts in favor of 5-7 year agreements with pre-negotiated expansion rights. The shift is most pronounced among Saudi petrochemical conglomerates and UAE-based airline groups centralizing IT estate consolidation.
Data Center in Middle East Market Segmentation
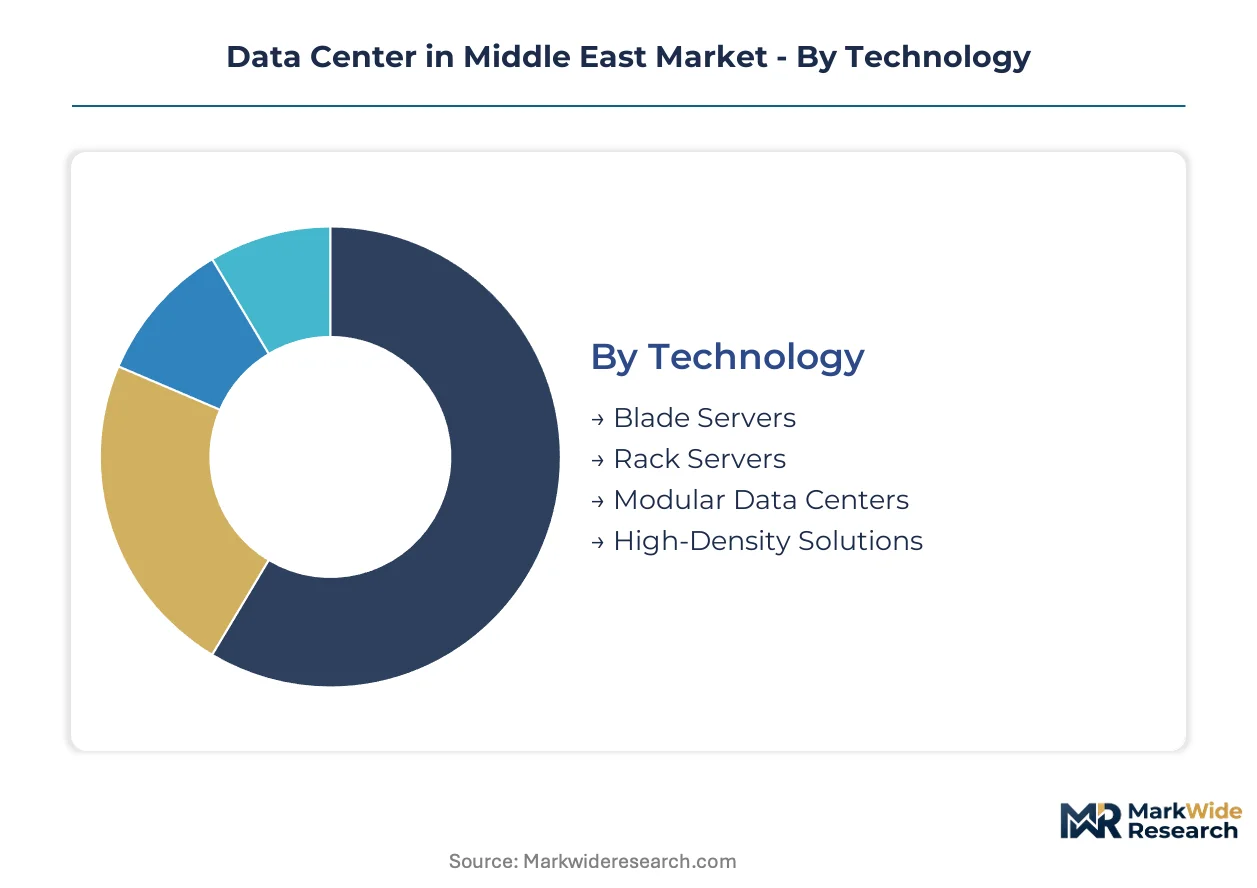
Segmentation reveals how capital deployment and operational priorities diverge across the Middle East data center landscape. Facility operators, service providers, and enterprise buyers each navigate distinct cost structures and regulatory constraints that shape procurement decisions.
Technology:
Capital intensity varies sharply across technology segments, with infrastructure choices locking in decade-long operational economics and thermal management capabilities.
- Blade Servers:Compact form factor housing multiple server nodes in shared chassis with centralized power and cooling. Demand concentrates among Saudi Aramco and UAE airline groups consolidating legacy estates into high-density footprints. Power density requirements above 15 kW per rack favor blade architectures for space-constrained Dubai facilities.
- Rack Servers:Standalone units in standard 19-inch enclosures with independent power supplies and cooling. Enterprises in Riyadh and Jeddah prefer rack servers for predictable capex and modular expansion paths. Lower upfront investment suits mid-market buyers navigating Saudi Arabia's evolving certification requirements.
- Modular Data Centers:Prefabricated, containerized units enabling rapid deployment in secondary cities.
- High-Density Solutions:GPU clusters and liquid-cooled racks supporting AI training workloads above 50 kW per rack.
Rack servers absorb the bulk of installed capacity; modular data centers are expanding most quickly.
Service Type:
Margin structures and contract duration separate service categories, with multi-year commitments reshaping vendor-client relationships.
- Colocation Services:Third-party facility space with power, cooling, and physical security. Saudi petrochemical conglomerates and UAE banks negotiate dedicated suites in tier-III facilities to satisfy data residency mandates from the Telecommunications and Digital Government Regulatory Authority.
- Cloud Services:On-demand compute and storage with usage-based billing. Hyperscale providers anchor new availability zones in Abu Dhabi and Riyadh to capture government cloud-first procurement under Vision 2030 directives.
- Managed Services:Outsourced infrastructure operations including monitoring and maintenance.
- Disaster Recovery:Backup site provisioning and business continuity orchestration.
Colocation services command the largest revenue pool; cloud services are climbing the fastest.
End User:
Buyer sophistication and procurement autonomy create distinct engagement models across organizational types.
- Enterprises:Private sector organizations spanning finance, aviation, and energy verticals. Emirates NBD and Qatar Airways centralize IT estate consolidation through single-partner frameworks with pre-negotiated expansion rights.
- Government Agencies:State entities bound by sovereign cloud and data localization policies. Saudi Arabia's National Data Management Office classification standards restrict certain data categories from cross-border transfer, compelling domestic facility certification.
- Telecommunication Companies:Incumbent carriers building edge capacity for 5G and IoT workloads.
- Educational Institutions:Universities and research centers with intermittent high-performance computing bursts.
Enterprises absorb the bulk of installed capacity; government agencies are expanding most quickly.
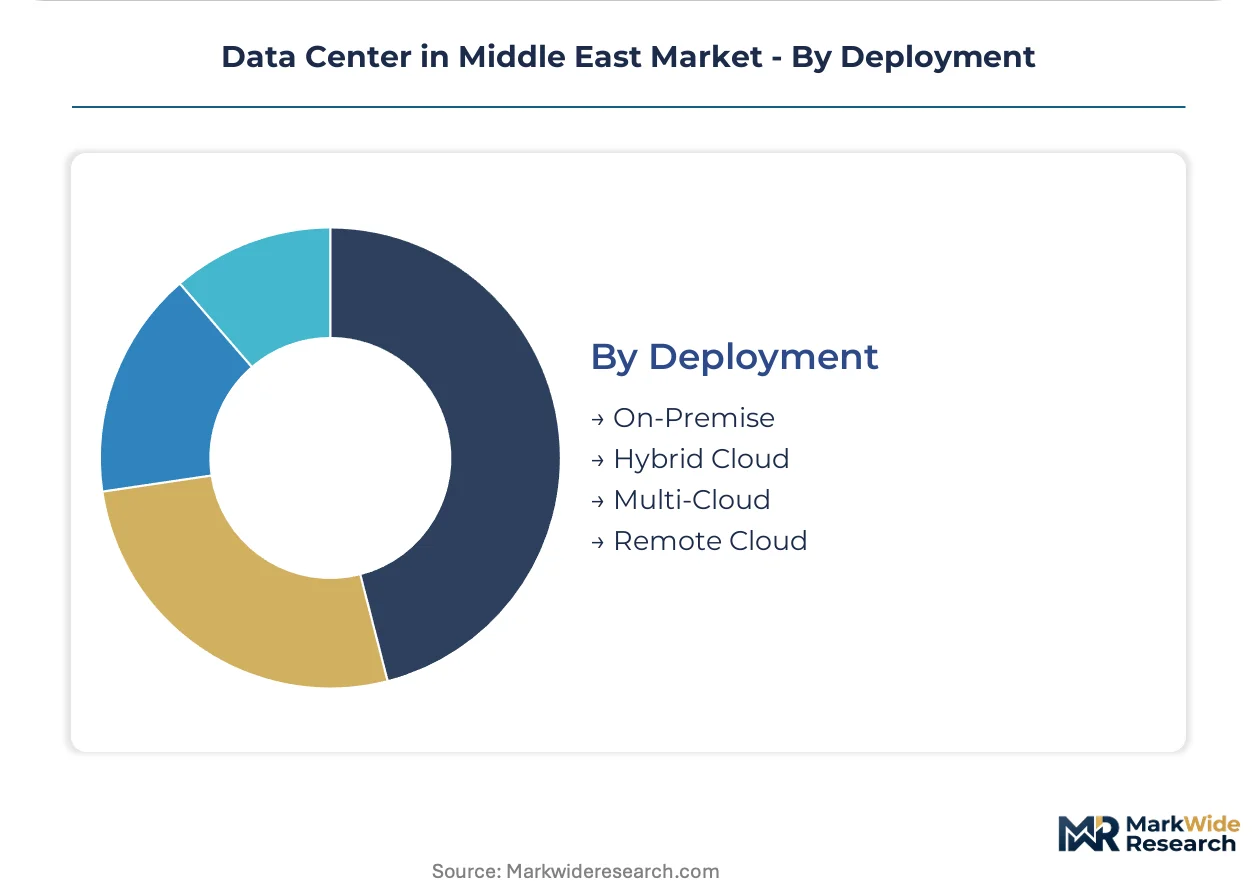
Deployment:
Architecture choices reflect risk tolerance, legacy system constraints, and regulatory segmentation requirements.
- On-Premise:Dedicated facilities owned and operated by the end user. Saudi defense and critical infrastructure operators maintain on-premise capacity for data categories restricted from third-party hosting under National Data Management Office regulations.
- Hybrid Cloud:Integrated on-premise and public cloud environments with workload portability. UAE healthcare providers deploy hybrid architectures to keep primary patient records local while bursting analytics to cloud regions.
- Multi-Cloud:Distribution across two or more public cloud providers to avoid vendor lock-in.
- Remote Cloud:Edge-delivered services from distributed micro-data centers.
On-premise retains the largest installed base; hybrid cloud is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Riyadh, Dubai, and Jeddah as hyperscale operators anchor new facilities to serve sovereign cloud requirements. Saudi Arabia's Vision 2030 and the UAE's Smart Dubai initiative are compressing capital deployment timelines across the Gulf Cooperation Council states.
Saudi Arabia
Saudi Aramco and petrochemical conglomerates drive enterprise colocation demand as they consolidate legacy IT estates. The National Data Management Office enforces classification standards that restrict certain data categories from cross-border transfer, compelling domestic facility certification. Riyadh anchors hyperscale construction with tier-III and tier-IV campuses under development by multiple operators.
United Arab Emirates
Emirates NBD and UAE airline groups negotiate single-partner frameworks with pre-negotiated expansion rights for IT centralization. The Telecommunications and Digital Government Regulatory Authority mandates data residency for financial and healthcare records, compelling foreign cloud providers to establish local availability zones. Dubai's campus concentration dominates regional interconnection density.
Qatar
Qatar Airways and energy sector enterprises generate concentrated demand for high-availability infrastructure. The national communications regulator enforces data localization for critical sectors, shaping procurement requirements. Doha facilities serve as redundancy nodes for financial institutions requiring disaster recovery capacity outside Saudi Arabia and the UAE.
Kuwait
Logistics and maritime trade operators in the port corridor generate edge computing requirements for real-time cargo tracking. Specialized data center contracting capacity concentrates in the UAE, inflating build costs relative to neighboring markets. Kuwait City lacks hyperscale presence despite growing enterprise demand from energy trading houses.
Oman
Energy and logistics sectors in the industrial port zone generate intermittent high-performance computing bursts for seismic analysis. The national telecommunications framework is evolving toward stricter data classification standards. Muscat remains underpenetrated by hyperscale operators despite its geographic position on Europe-Asia-Pacific cable routes.
Data Center in Middle East Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with facility operators competing on certification tier and interconnection density rather than price alone. The vendor base organizes around three archetypes: sovereign-aligned domestic champions, global hyperscale platforms, and specialist colocation operators. Consolidation pressure is accelerating through multi-year committed capacity blocks and pre-negotiated expansion rights. Geographic expansion into secondary cities and modular deployment architectures represent the dominant competitive moves.
Among UAE-based operators, Khazna Data Centers and Gulf Data Hub exemplify the sovereign-aligned archetype through tier-III and tier-IV certified campuses. Equinix represents the global platform model with cross-border latency optimization between Europe and Asia-Pacific routes. These three anchors illustrate how competitive positioning depends on certification depth, interconnection fabric density, and alignment with government cloud-first procurement mandates.
| Leading Market Players |
|---|
| Khazna Data Centers |
| Gulf Data Hub |
| Etisalat |
| STC |
| center3 |
| Edgnex Data Centres |
| Equinix |
| Digital Realty |
| DataVolt |
| Others |
Pricing and Supply Chain Analysis
Captive power infrastructure integration anchors both supply positioning and pricing power for Middle East data center operators, as on-site generation capacity insulates against grid interconnection delays that compress commissioning timelines and inflate construction-phase carrying costs. Operators with secured electricity offtake from NEOM's renewable cluster command premium positioning against competitors exposed to oil-price-linked tariff volatility.
Pricing Analysis
Volume commitments versus margin capture splits sharply across contract tiers. Tier-III certified colocation suites in Dubai and Riyadh command premium positioning against standard tier-II facilities, with pricing pressure intensifying as hyperscale providers negotiate multi-year blocks with pre-negotiated expansion rights. Government agencies under Vision 2030 mandates exhibit lowest price sensitivity, while mid-market enterprises in secondary cities resist rate escalation without guaranteed redundancy levels.
Supply Chain Analysis
Uptime Institute certification gating concentrates qualified engineering capacity in the UAE, forcing Saudi and Kuwaiti projects to absorb elevated contracting premiums or accept extended mobilization timelines. Critical infrastructure components draw from Germany, China, and the USA, with diesel generator sets and switchgear facing single-source vulnerability from European OEMs. Distribution runs through Dubai-based logistics hubs serving Gulf Cooperation Council states, exposing projects to customs clearance variability at Jebel Ali.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified engineering talent scarcity props pricing power for incumbent operators, as construction labor concentration in the UAE creates a structural bottleneck that delays multi-site expansion timelines across Saudi Arabia and Kuwait.
For Market Incumbents: Deploy modular deployment architectures to compress commissioning timelines from twenty-four months to six months, countering emerging specialist colocation operators entering through prefabricated all-in-one modules. Anchor tier-IV certification investments in Riyadh and Dubai campuses to defend against hyperscale providers capturing government cloud-first procurement under tightening data localization mandates. For New Entrants and Emerging Players: Direct-channel enterprise sales routes into Dammam, Muscat, and Manama bypass incumbent interconnection density advantages in primary cities. Target edge computing demand from energy and logistics sectors in secondary cities lacking hyperscale presence, with sovereign cloud compliance as the primary go-to-market wedge against global platform competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by sovereign-aligned domestic champions seeking geographic expansion capabilities. Long-term viability hinges on alignment with Gulf state localization requirements and renewable power purchase agreement access. Watch for NEOM green hydrogen contract announcements as inflection indicators for carbon-free electricity positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Deployment | Direct-to-chip architectures sustain PUE below 1.2 in Abu Dhabi facilities exceeding 45°C ambient. |
| Sovereign Cloud Certification | Tier-III and tier-IV accreditation satisfies UAE Telecommunications and Digital Government Regulatory Authority mandates. |
| Modular Capacity Expansion | Prefabricated units enable rapid scaling without traditional construction timelines in secondary cities. |
| Green Power Purchase Agreement | NEOM renewable contracts satisfy EU-linked corporate sustainability requirements for carbon-free operations. |
| Cross-Border Interconnection | Dubai campus density optimizes latency between Europe and Asia-Pacific cable routes. |
Research Methodology
Independent corroboration across facility operators, hyperscale cloud procurement officers, and regulatory affairs specialists underwrites the qualitative findings, with secondary validation from Uptime Institute certification databases, Gulf Cooperation Council customs records, and national communications regulator filings. Bottom-up capacity tracking across Riyadh, Dubai, and Jeddah facilities triangulates against top-down sovereign cloud spending commitments documented in Vision 2030 and Smart Dubai initiative disclosures.
Comparable historical deployment patterns anchor the projection framework across the analysis window, with segmentation modeling across technology tiers, service types, and end-user categories. CAGRs derive from facility commissioning timelines, power infrastructure interconnection schedules, and hyperscale lease-up rates. Forecast inputs incorporate liquid cooling adoption curves and modular deployment penetration assumptions.
The model holds under stable regulatory localization requirements; deviation in Saudi National Data Management Office classification enforcement or UAE data residency rule expansion would shift capacity deployment timelines. A model refresh is warranted upon material change in sovereign cloud procurement mandate implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Netherlands Data Center Market
Data Center Infrastructure
Norway Data Center Physical Security Market
Data Center Infrastructure
Philippines Data Center Server Market
Data Center Infrastructure
Netherlands Data Center Rack Market
Data Center Infrastructure
Global Data Colocation Market
Data Center Infrastructure
Saudi Arabia Data Center Physical Security Market
Data Center Infrastructure
Global Containerized Data Center Market
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
Global Data Center Rack PDU Market
Data Center Infrastructure
South Korea Data Center Power Market
Data Center Infrastructure
Data Center IT Asset Disposition Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
North America Data Center Infrastructure Management Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
South America Data Center Market
Data Center Infrastructure
Australia Data Center Rack Market