
 UK Construction Market | 2026-2036
UK Construction Market Size, Share, and Industry Trends Forecast 2026-2036
UK Construction Market Outlook
A widening capability gap between asset-heavy and asset-light operating models is redrawing competitive tiers in UK construction. Balfour Beatty leverages its integrated design-build capability to capture complex infrastructure contracts. Laing O'Rourke sustains manufacturing-led differentiation through its Explore Industrial Park prefabrication facility. Morgan Sindall Group anchors its position in affordable housing and education frameworks through regional contracting density.
UK construction encompasses the planning, assembly, and maintenance of built structures using concrete, steel, timber, and masonry composites to achieve specified load-bearing, thermal, and fire-resistance ratings. The sector delivers residential dwellings, commercial premises, industrial facilities, and public infrastructure to meet spatial, economic, and regulatory requirements. Residential construction leads output value but faces margin compression from material volatility, while infrastructure commands longer contract tenors and stronger backlog visibility. New construction dominates volume, though renovation activity is expanding fastest as retrofit mandates intensify across England's aging building stock.
Building Regulations 2010, the Building Safety Act 2022, and Environment Agency permitting frameworks collectively govern structural integrity, fire safety, and environmental compliance across English and Welsh projects. These standards are elevating demand for certified cladding systems, digital building passports, and whole-life carbon assessments. Stakeholders must monitor emerging UK Net Zero Building Standard thresholds and local authority planning capacity constraints to align procurement and workforce strategies with enforcement timelines.
Market Dynamics
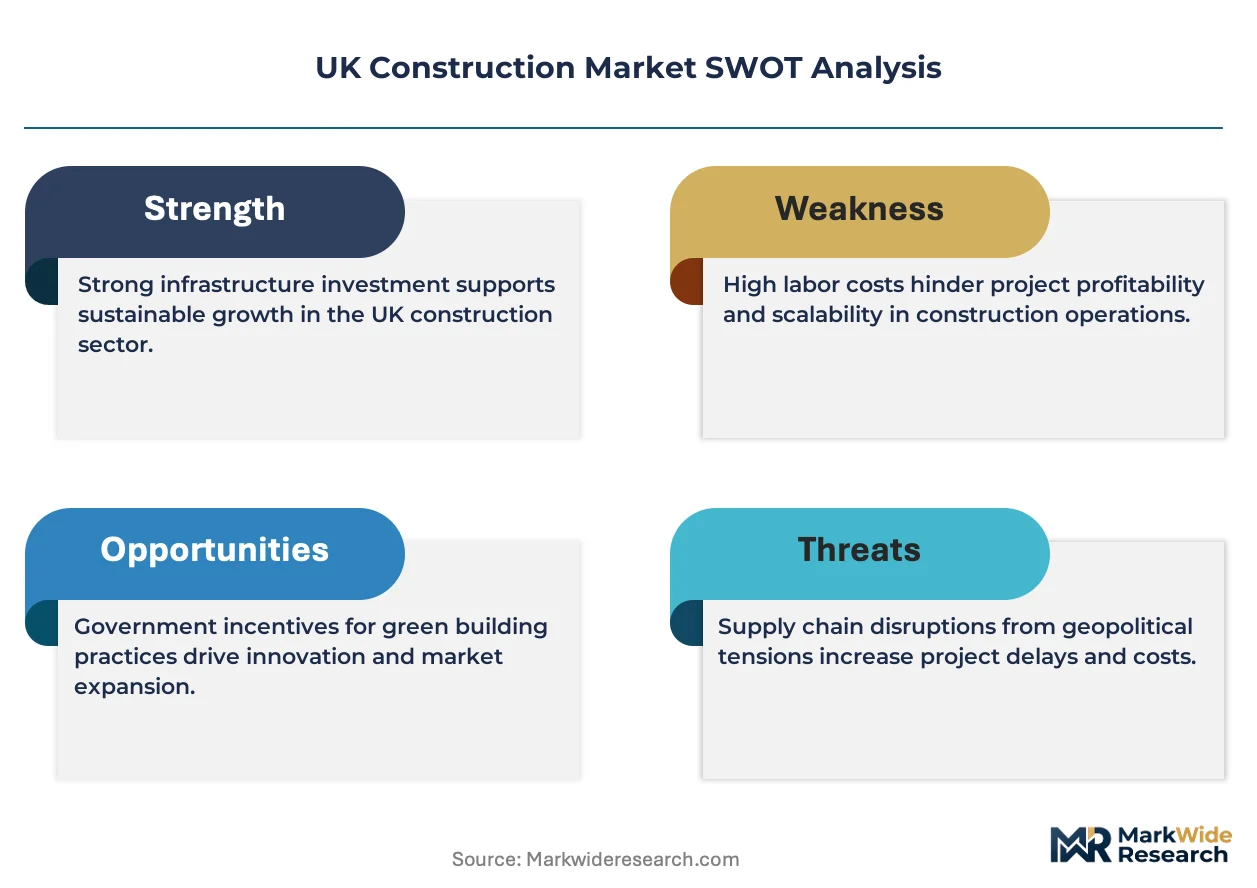
The Building Safety Act 2022 is forcing a fundamental reconfiguration of liability chains and compliance workflows across English construction, elevating digital traceability and certified competency to non-negotiable contract terms.
Growth Catalysts
- Social Housing Decarbonisation Fund:Retrofit mandates for aging tower blocks are accelerating demand for whole-building energy assessments and low-carbon envelope upgrades across England's public housing stock.
- Transport infrastructure pipelines:Network Rail's renewal programmes and Highways England maintenance frameworks are sustaining long-tenor civil engineering contracts with multi-year backlog visibility.
- Offsite manufacturing adoption:Modular construction methods are compressing programme durations and reducing on-site labour exposure for residential and healthcare schemes in Greater London.
Market Restraints
- Structural steel price volatility:Input cost swings tied to energy-intensive production and import dependency are compressing fixed-price contract margins for steel-framed commercial schemes.
- Planning authority capacity constraints:Local authority resource shortages are extending pre-construction timelines, particularly for complex urban regeneration projects requiring environmental impact assessments.
- Skilled trades shortage:Scarcity of certified electricians, plumbers, and fire safety specialists is inflating wage costs and constraining project mobilisation across the South East.
Strategic Opportunities
- Digital building passports:Mandatory asset information requirements under the Building Safety Regulator are creating demand platforms for software-enabled compliance documentation and lifecycle data management.
- Heat pump integration:Boiler upgrade scheme incentives are opening retrofit revenue streams for mechanical contractors capable of integrating air-source and ground-source systems into existing housing stock.
- Brownfield remediation:Environment Agency permitting frameworks for contaminated land are channelling investment into former industrial sites across the West Midlands and Northern England.
Industry Challenges
- Competency certification backlogs:Building Safety Regulator registration requirements are creating bottlenecks for principal designers and contractors seeking authorised status.
- Legacy procurement system integration:Public sector frameworks still running on fragmented IT infrastructure are delaying digital submission workflows and payment automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Construction Market |
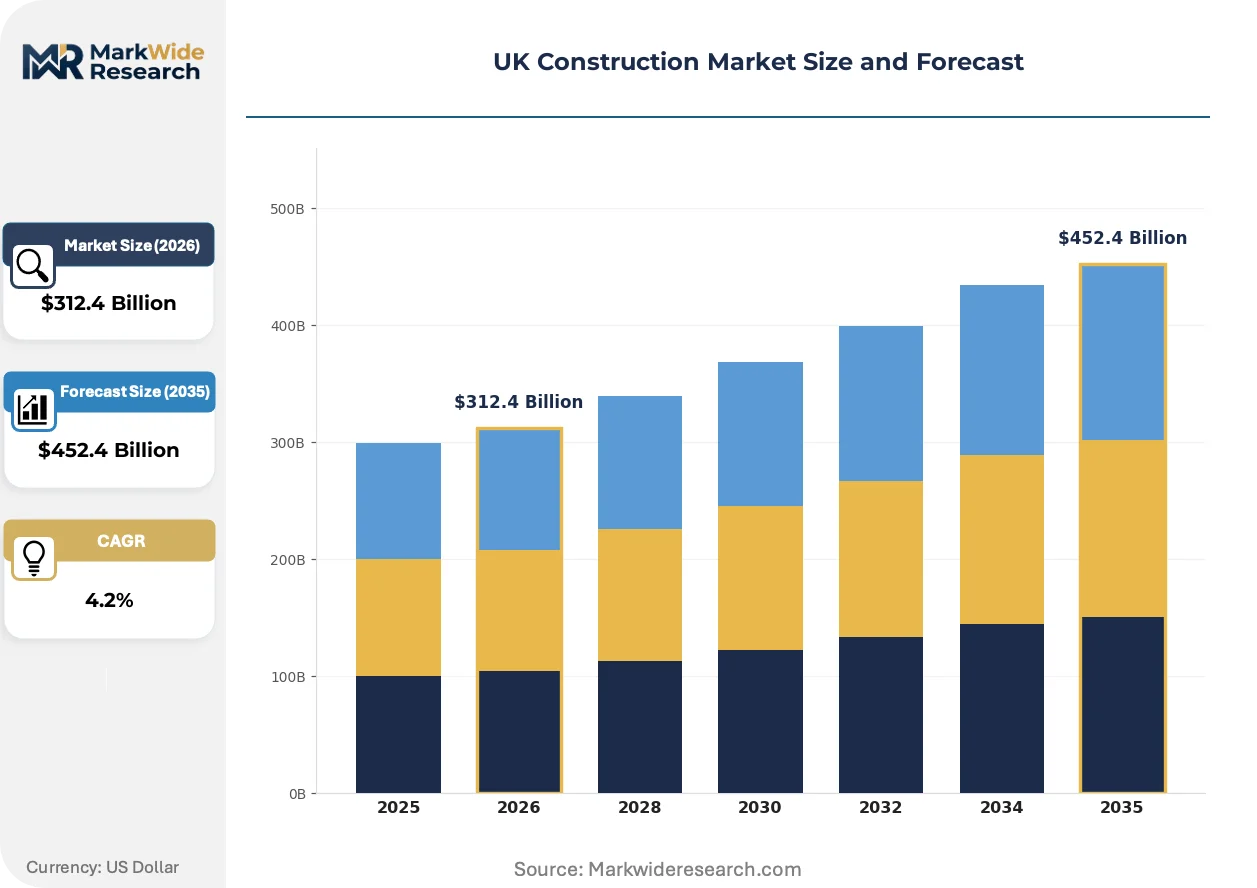
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $452.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential, Commercial, Industrial, Infrastructure Application: New Construction, Renovation, Demolition, Restoration Service Type: Design, Consulting, Project Management, Construction Material: Concrete, Steel, Wood, Brick |
| Companies Covered | Balfour Beatty, Morgan Sindall Group, Kier Group, Laing O'Rourke, Mace Group, Wates Construction, Multiplex Construction Europe, Lendlease, Skanska UK, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Construction Market Strategic Shifts
Digital fabrication and regulatory data mandates are converging to reshape how UK construction projects are designed, procured, and handed over, with compliance automation emerging as a distinct competitive battleground.
Building Information Modelling (BIM) Level 2 mandates for public projects are decomposing traditional document-based handover processes into structured, machine-readable asset data. Tier-one contractors and asset owners are mandating COBie-compliant deliverables for healthcare and education frameworks. This technology is decomposing the document-control margin that specialist clerks of works previously captured.
The Building Safety Act 2022 establishes the Building Safety Regulator as a statutory dutyholder enforcement body with criminal liability pathways for non-compliance. Developers must now submit gateway declarations at design, construction, and completion phases for higher-risk buildings. Residential schemes exceeding 18 metres face the most stringent competence and documentation requirements, driving consolidation around accredited supply chains.
Public sector clients are unbundling design liability from construction risk through two-stage open-book procurement with pain-share mechanisms. Framework agreements for the Ministry of Justice and Department for Education now embed operational performance metrics extending ten years post-handover. This reconfiguration is most advanced in Scotland and Wales, where devolved procurement policy has accelerated outcome-based contracting for social infrastructure.
UK Construction Market Segmentation
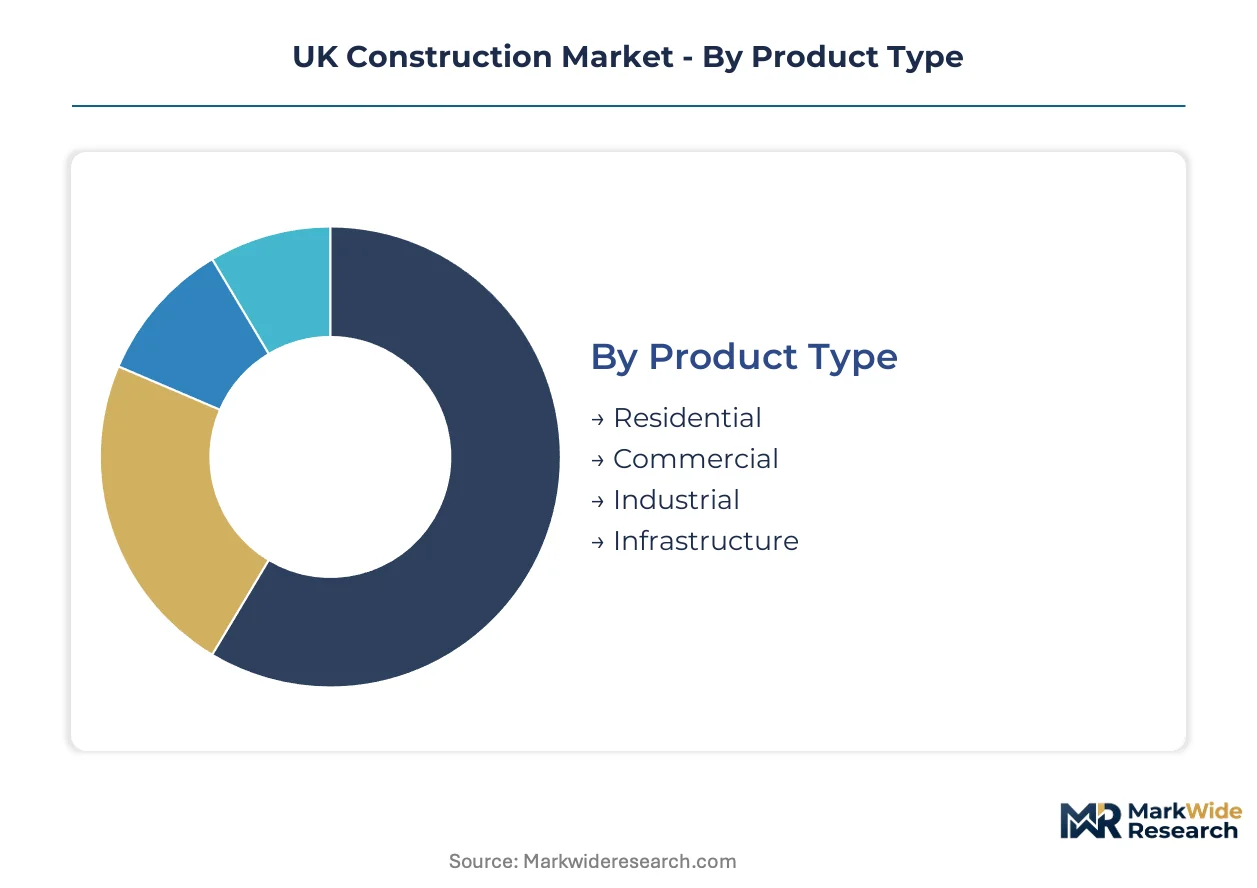
Segmentation in UK construction reveals how procurement channels, material specifications, and service bundling reshape contract economics. Understanding these divisions exposes where margin pools concentrate and where regulatory compliance creates entry barriers.
Product Type:
Channel mix varies sharply across product types, with public sector frameworks dominating infrastructure flows while speculative development drives residential volumes.
- Residential:Encompasses single-family dwellings, apartment blocks, and social housing schemes delivered through both speculative private development and registered provider frameworks. Demand clusters in Greater London and the South East where planning permissions for higher-density schemes face acute capacity constraints at local authority level.
- Commercial:Covers office premises, retail spaces, and hospitality structures where tenant fit-out specifications increasingly mandate whole-life carbon assessments and smart building system integration. The segment concentrates in urban regeneration zones across Birmingham, Manchester, and London's outer boroughs where transport connectivity upgrades unlock development viability.
- Industrial:Includes logistics warehouses, manufacturing facilities, and distribution centers. E-commerce fulfillment demand is reshaping specification toward higher clear heights and automated material handling compatibility in the Midlands logistics corridor.
- Infrastructure:Spans transport, utilities, and public realm projects delivered through long-tenor framework agreements with Network Rail, National Highways, and water utilities. These contracts flow through pre-qualified contractor pools with demonstrated BIM Level 2 capability.
Residential dominates installed base. Infrastructure is where expansion concentrates.
Application:
Cost tier differentiation separates new build premium pricing from renovation's labour-intensive economics and demolition's waste-handling compliance burdens.
- New Construction:Greenfield and brownfield development of structures on previously undeveloped or cleared sites. Volume concentrates in housebuilding where Help to Buy successor schemes and planning reform consultations are reshaping site viability assessments across England.
- Renovation:Retrofit and refurbishment of existing structures including energy efficiency upgrades, façade remediation, and internal reconfiguration. Social Housing Decarbonisation Fund allocations are accelerating demand for whole-building envelope improvements in tower blocks exceeding 18 metres.
- Demolition:Systematic dismantling of structures with waste hierarchy compliance and hazardous material remediation. The segment faces tightening Environment Agency permitting for asbestos handling and crushed concrete reprocessing.
- Restoration:Heritage-sensitive repair of listed buildings and conservation area structures. Specialist contractor accreditation through bodies such as the National Heritage Training Group governs eligibility for Historic England-funded schemes.
New Construction commands highest absolute spend. Renovation is climbing the fastest as retrofit mandates intensify.
Service Type:
Customer type fragmentation splits between asset owners seeking bundled design-build delivery and public sector clients unbundling risk through separated professional services appointments.
- Design:Architectural and engineering services spanning concept development through technical specification. Building Safety Act gateway declarations are elevating demand for principal designer competency certification and digital model management.
- Consulting:Advisory services covering planning strategy, cost consultancy, and sustainability certification. The segment is expanding around PAS 2035 retrofit coordinator roles and whole-life carbon assessment mandates.
- Project Management:Programme oversight, contract administration, and stakeholder coordination. Two-stage open-book procurement is compressing traditional quantity surveying margins while extending performance accountability periods.
- Construction:Physical assembly and installation execution. Labour scarcity for certified trades is inflating wage costs and constraining mobilisation timelines across the South East.
Construction dominates employment. Design is where margin expansion concentrates.
Material:
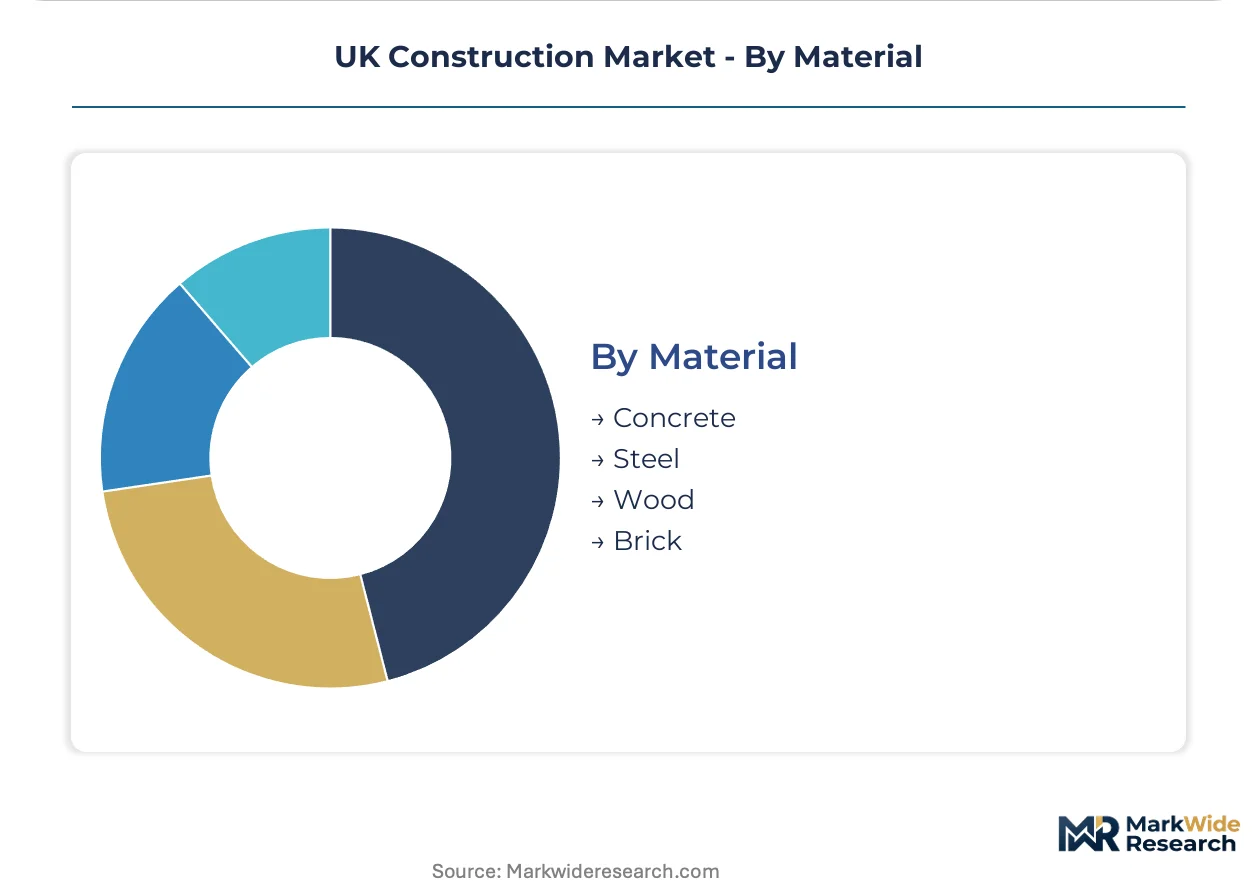
Supply concentration and import exposure differentiate material economics, with domestic production capacity constraining availability for steel and cement.
- Concrete:Cement-based composites for foundations, frames, and precast elements. Low-carbon concrete specification using ground granulated blast-furnace slag is gaining traction in Transport for London frameworks.
- Steel:Structural sections, reinforcement, and metal decking. Energy-intensive production and import dependency expose the segment to price volatility that compresses fixed-price contract margins.
- Wood:Timber framing, cross-laminated panels, and engineered products. Offsite manufacturing adoption is accelerating demand for precision-cut structural timber in residential and healthcare modular schemes.
- Brick:Clay masonry for external walls and heritage restoration. Domestic kiln capacity constraints and rising energy costs are reshaping specification toward thin-joint blockwork alternatives.
Concrete dominates structural tonnage. Wood is gaining share fastest as prefabrication scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK construction sector runs a modest trade surplus in professional services and engineering consultancy, though structural materials and specialist components draw heavily on continental European supply chains. Regional performance splits sharply between the overheated Greater London market and recovering Northern cities where public investment pipelines are deepening.
Greater London and the South East
Transport for London's capital renewal programmes and Crossrail 2 preparatory works sustain civil engineering demand across the capital. The Building Safety Act 2022 gateway declarations concentrate compliance workload in boroughs with the tallest residential towers. The Thames Gateway corridor anchors modular manufacturing investment, with factory-built housing units supplying constrained central sites.
Midlands Engine
Logistics warehouse construction along the M6 corridor responds to e-commerce fulfillment demand and rail freight terminal upgrades. West Midlands Combined Authority devolution deals are unlocking brownfield remediation funding for former industrial zones. Birmingham's Big City Plan regeneration cluster is absorbing mixed-use development capital as office-to-residential conversions accelerate.
North England
Network Rail's Transpennine Route Upgrade and Northern Powerhouse Rail preparatory works are sustaining heavy civils contracts across Lancashire and Yorkshire. Homes England's Affordable Homes Programme is channelling registered provider investment into former coalfield communities. Manchester's Northern Gateway and Liverpool's Wirral Waters schemes exemplify city-region densification strategies.
Scotland
Scottish Government infrastructure investment planning and the National Infrastructure Mission are extending contract tenors for water and transport utilities. Building Standards Scotland amendments on energy performance are accelerating deep retrofit demand in Glasgow's tenement housing stock. The Edinburgh and South East Scotland City Region Deal is concentrating innovation district construction around biomedical and data economy anchors.
Wales
Welsh Government capital budgets and the Mutual Investment Model are mobilising private finance for health and education infrastructure. Future Wales national development framework planning permissions are concentrating housing delivery in Cardiff-Newport corridor growth areas. Swansea Bay City Region energy infrastructure is anchoring offshore wind supply chain fabrication facilities.
UK Construction Market Competitive Environment
Concentration sits with integrated tier-one contractors capable of delivering design-build-finance-operate bundles for complex infrastructure and public sector frameworks. The vendor base arranges into three distinct tiers: national full-service contractors with framework pre-qualification status; regional specialists dominating local authority maintenance and small works panels; and emerging offsite manufacturing entrants capturing standardised residential and healthcare schemes. Consolidation is accelerating through framework aggregation and distressed asset acquisition, while capability differentiation is shifting toward digital delivery and whole-life carbon accountability.
Among UK-based integrated contractors, Balfour Beatty, Morgan Sindall Group, and Laing O'Rourke exemplify divergent strategic positioning within the tier-one tier. Balfour Beatty represents the infrastructure-heavy archetype with transport and utilities framework density. Morgan Sindall Group anchors the social infrastructure and affordable housing specialism through education and registered provider relationships. Laing O'Rourke occupies the manufacturing-led differentiation position through its Explore Industrial Park prefabrication capability and direct production control over structural components.
| Leading Market Players |
|---|
| Balfour Beatty |
| Morgan Sindall Group |
| Kier Group |
| Laing O'Rourke |
| Mace Group |
| Wates Construction |
| Multiplex Construction Europe |
| Lendlease |
| Skanska UK |
| Others |
Value Chain & Pricing Dynamics
Two-stage open-book procurement with pain-share mechanisms locks in both supply access and price visibility for tier-one contractors bidding on Highways England and Network Rail frameworks. This contract structure transfers material volatility risk to clients while embedding multi-year supplier relationships that secure steel and concrete allocation ahead of spot market exposure.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across infrastructure and commercial segments. Three-tier pricing structure across premium, standard, and economy levels separates BIM Level 2-certified contractors from regional specialists and unaccredited entrants. Cost compression in fixed-price residential schemes is intensifying because structural steel price volatility feeds directly into margin erosion. Registered providers and public sector framework clients exhibit lowest price sensitivity due to operational performance guarantees extending ten years post-handover.
Supply Chain Analysis
Extended lead times for structural timber and cross-laminated panels now stretch delivery schedules for modular manufacturing facilities. UK construction draws from China, Germany, and Turkey for structural steel sections, cement clinker, and engineered timber products. Single-source vulnerability concentrates in energy-intensive domestic cement production and continental European steel imports. Distribution runs through builder merchant networks and direct-to-site logistics contracts with regional precast concrete suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital building passport compliance and PAS 2035 retrofit coordinator services represent a service-attach opportunity expanding faster than traditional construction output. Recurring revenue from lifecycle data management contracts now outpaces one-off construction margins for tier-one contractors with software-enabled delivery platforms.
For Market Incumbents: Fortify framework pre-qualification status by accelerating Building Safety Regulator competency certification for principal designers and contractors. Deepen captive supply of structural timber through offsite manufacturing facility investment to offset steel price volatility. Consolidate regional maintenance and small works panel density before distressed asset acquisition windows close. For New Entrants and Emerging Players: Building Safety Regulator fast-track certification for higher-risk building competence opens eligibility for residential towers exceeding 18 metres. Target social housing decarbonisation frameworks where retrofit coordinator scarcity creates procurement bottlenecks. Deploy heat pump integration specialisation as the go-to-market angle for mechanical contractor positioning against incumbent M&E bundling. For Investors and Strategic Acquirers: Modular manufacturing specialists with Explore Industrial Park-scale prefabrication capability offer the clearest acquisition target archetype for vertical integration plays. Long-term viability hinges on capturing standardised residential and healthcare scheme volume as planning reform accelerates site viability assessments. Watch Building Safety Act gateway declaration enforcement timelines as the inflection indicator for accredited supply chain consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Building Passport Platform Development | Captures mandatory compliance documentation demand from Building Safety Regulator gateway declarations. |
| Offsite Manufacturing Scale-Up | Compresses programme durations for Greater London residential schemes facing skilled trades shortage. |
| PAS 2035 Retrofit Coordinator Certification | Unlocks Social Housing Decarbonisation Fund revenue streams across England's tower block stock. |
| Backward Integration into Structural Timber | Reduces import dependency exposure for cross-laminated panel supply to modular healthcare projects. |
| Two-Stage Open-Book Procurement Adoption | Aligns risk-sharing mechanisms with Ministry of Justice ten-year operational performance frameworks. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with tier-one contractor framework directors, local authority planning officers, registered provider procurement leads, and Building Safety Regulator competency assessors. Secondary validation drew from Homes England Affordable Homes Programme allocations, Environment Agency permitting databases, Network Rail capital delivery disclosures, and Department for Education framework agreement documentation. Bottom-up project pipeline aggregation was cross-checked against top-down sector output estimates to ensure triangulation integrity.
Across the analysis window, the forecasting framework models construction output across product type, application, service type, and material specification dimensions. CAGRs were derived from regression analysis of historical output trends against planned infrastructure investment pipelines and housing delivery targets. Key inputs included local authority planning permission grant rates, steel and cement price indices, and Building Safety Act implementation phase transitions.
Decision-makers should treat outputs as directional under sustained government capital commitment assumptions; material deviation in fiscal consolidation policy would warrant model refresh. Revision becomes warranted when Building Safety Regulator registration backlogs for principal contractors cross thresholds that constrain project mobilisation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Modular and Portable Building Market
Building Construction
3D Printing Building Construction Market
Building Construction
US Prefabricated Buildings Market
Building Construction
North America Prefabricated Buildings Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
India Construction Market
Building Construction
Precast Construction Market
Building Construction
Vietnam Construction Market
Building Construction
Turkey Commercial Construction Market
Building Construction
UAE Facade Market
Building Construction
ASEAN Prefab Wood Buildings Market
Building Construction
Thailand Construction Market
Building Construction
Qatar Construction Market
Building Construction
Eastern Europe Construction Market
Building Construction
GCC Construction Market
Building Construction
Malaysia Construction Market