
 Sweden New Construction Market | 2026-2036
Sweden New Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden New Construction Market Insights
Aftermarket service revenue from building operations and maintenance contracts is narrowing as a margin-pool migration pushes value back toward initial construction and integrated design-build delivery. Skanska leverages its in-house engineering capabilities to capture upstream design fees alongside traditional contracting margins. Peab anchors its position through geographic concentration in Sweden's three largest urban regions, controlling local subcontractor networks and municipal permitting relationships. NCC competes on manufacturing scale via its prefabrication facilities, which supply standardized structural elements to multiple concurrent projects.
Sweden new construction encompasses the ground-up erection of buildings and infrastructure using structural systems designed to withstand Nordic climatic loads, with engineered timber increasingly substituting for steel and concrete in mid-rise applications to meet thermal performance and carbon targets. Residential construction leads by volume as housing deficits in Stockholm, Gothenburg, and Malmö sustain permit backlogs, while institutional projects carry higher margins due to complex MEP requirements and extended performance warranties. Wood as a material type is expanding fastest, driven by Sweden's sustainable forestry base and advances in cross-laminated timber manufacturing that extend structural height limits.
Bovering enforces national building codes that mandate energy performance thresholds, while the Swedish Environmental Protection Agency administers climate reporting requirements affecting material sourcing decisions. Miljöbyggnad certification operates as a voluntary but market-differentiating standard that shapes developer specifications and tenant lease premiums. Stakeholders must monitor whether the EU Taxonomy's technical screening criteria for sustainable construction will tighten capital access for conventional concrete-intensive projects or redirect institutional investment toward certified timber and low-carbon concrete alternatives.
Market Dynamics
Engineered timber substitution is compressing project timelines and redirecting capital allocation across Sweden's mid-rise residential pipeline, as cross-laminated timber manufacturing scales to meet Boverket's revised structural height allowances.
Growth Catalysts
- Transit-oriented development mandates:Stockholm County's densification policies are concentrating permits along commuter rail corridors, reducing land acquisition friction for residential developers.
- Miljöbyggnad certification premiums:Tenant willingness-to-pay for certified space is expanding developer margins on greenfield projects, particularly in Gothenburg's corporate leasing market.
- Mass timber engineering:Advances in fire-rated CLT assemblies are extending structural applications to eight-story residential, unlocking previously concrete-dependent segments.
Market Restraints
- Structural adhesive supply concentration:Sweden relies on German and Austrian suppliers for polyurethane binders used in CLT manufacturing, exposing projects to input cost volatility.
- Boverket energy code stringency:Stepwise tightening of thermal envelope requirements is extending design-review cycles and compressing developer IRRs on speculative builds.
- Concrete substitution limits:Foundation and core systems still require conventional materials, fragmenting supply chains and preventing full timber-system cost advantages.
Strategic Opportunities
- EU Taxonomy alignment:Green bond eligibility for certified timber structures is redirecting institutional capital toward low-carbon construction, favoring early-certifying developers.
- Prefabricated volumetric modules:Factory-built bathroom and kitchen pods are reducing on-site labor dependency and compressing weather-risk exposure in Nordic climates.
- Malmö corridor underbuild:Housing permit backlogs in Sweden's third metropolitan region exceed Stockholm's on a per-capita basis, offering first-mover positioning.
Industry Challenges
- Timber engineering talent scarcity:Structural designers with CLT-specific fire and acoustic modeling capabilities command wage premiums that erode contractor margins.
- Miljöbyggnad documentation burden:Third-party verification timelines for indoor environmental quality credits frequently extend marketing windows and pre-leasing risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden New Construction Market |
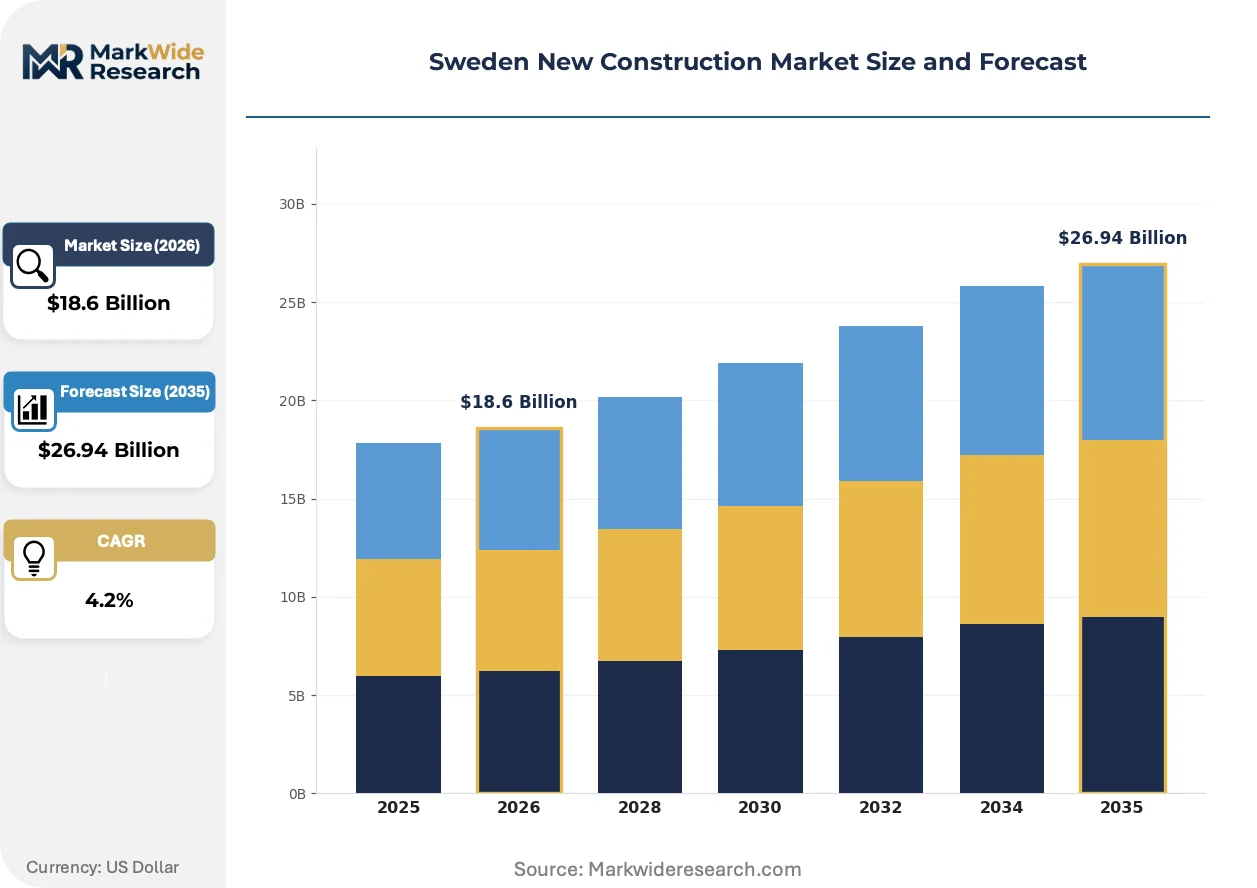
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $26.94 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Construction Type: Residential, Commercial, Industrial, Institutional Material Type: Concrete, Steel, Wood, Brick Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects End User: Developers, Contractors, Government, Homeowners |
| Companies Covered | Skanska, NCC, Peab, Sweco, AFRY, Bravida, Serneke Group, Instalco, JM AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden New Construction Market Trends and Innovations
Building information modeling integration is compressing design-construction handoff friction, while regulatory pressure on embodied carbon is accelerating material specification shifts across Sweden's developer community.
Digital twin technology is digitizing asset performance monitoring from commissioning through operations. Institutional owners in Stockholm's commercial office segment are mandating sensor-integrated handover packages that feed facility management platforms. This capability is compressing warranty claim resolution and enabling outcome-based maintenance contracting.
Boverket's 2024 energy performance standards are tightening thermal bridge allowances and mandating whole-building life-cycle carbon declarations. Residential developers are responding by pre-certifying projects under Miljöbyggnad Gold to secure green financing advantages. The policy is most acute in Stockholm's competitive leasing market, where certification gaps translate directly to rent concessions.
Tenant procurement patterns are fragmenting traditional general-contractor relationships. Large corporate occupiers in Gothenburg and Malmö are engaging design-build entities directly, unbundling property development from construction execution. This disintermediation is visible in the logistics and life-science verticals, where speed-to-occupancy overrides traditional risk-allocation preferences.
Sweden New Construction Market Segmentation
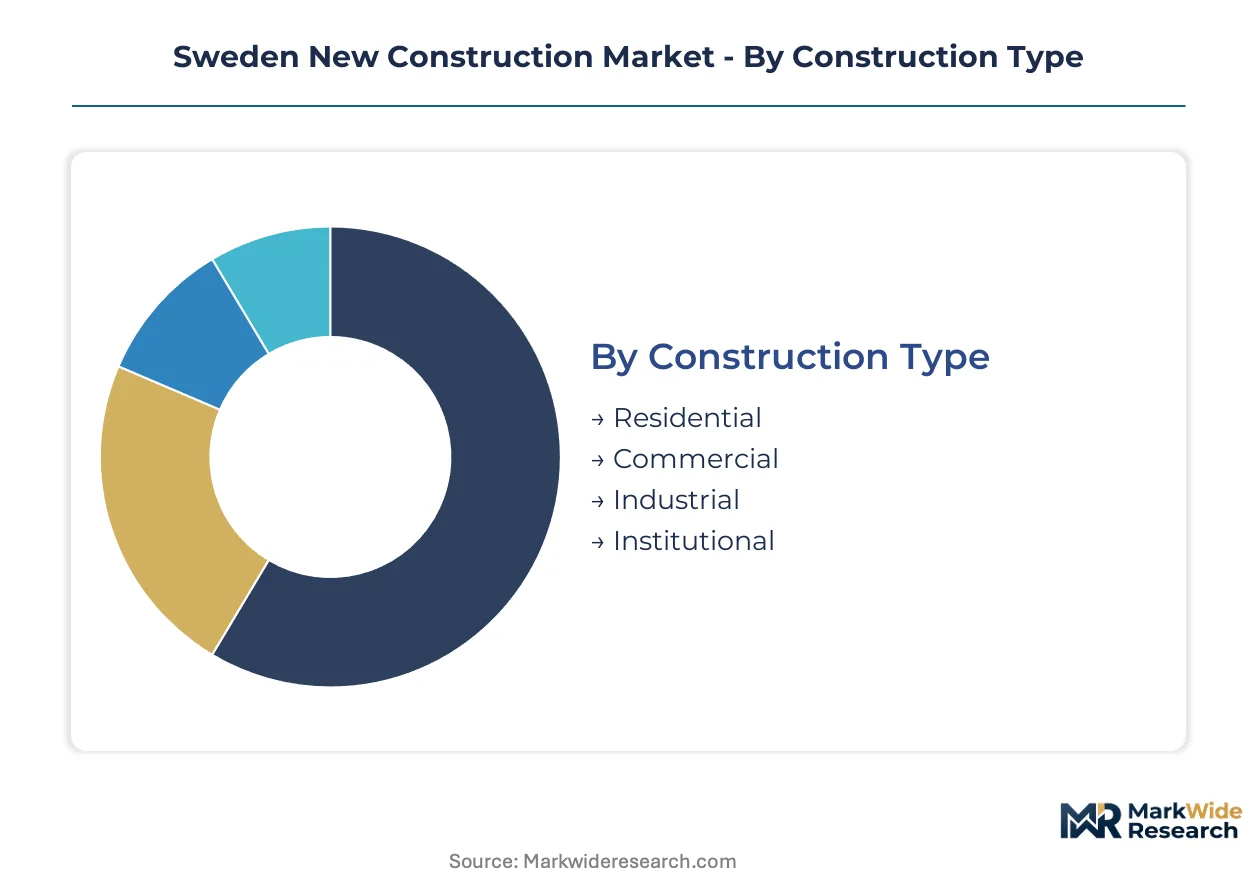
Construction type and material specifications in Sweden's new build sector determine project financing structures, permitting timelines, and operational revenue streams throughout the building lifecycle. Segmentation clarity enables stakeholders to align capital deployment with regulatory incentives and tenant procurement patterns across Stockholm, Gothenburg, and Malmö metropolitan corridors.
Construction Type:
After-sales service intensity varies sharply across construction types, with institutional projects demanding extended performance warranties and integrated facility management handovers that residential developers rarely provide.
- Residential:Multi-family housing dominates permit volumes in Stockholm County, where transit-oriented development policies concentrate construction along commuter rail nodes. Housing deficits sustain developer pipelines, though Boverket energy code compliance compresses speculative build margins.
- Commercial:Office and retail structures in Gothenburg's corporate leasing market command Miljöbyggnad certification premiums, with tenant willingness-to-pay expanding margins on greenfield developments. Lease structures increasingly incorporate outcome-based maintenance clauses.
- Industrial:Logistics facilities concentrate in Malmö corridor and peripheral Stockholm zones, where speed-to-occupancy overrides traditional risk-allocation preferences. Direct design-build engagement by corporate occupiers is fragmenting general-contractor relationships.
- Institutional:Healthcare and educational buildings carry complex MEP requirements and extended performance warranties. Boverket mandates and Swedish Environmental Protection Agency climate reporting shape material sourcing decisions throughout project delivery.
By volume, residential leads. By growth pace, institutional is climbing the fastest as public sector procurement accelerates certified timber adoption.
Material Type:
Cost tier stratification separates premium engineered timber systems from commodity concrete and steel, with certification grade determining financing eligibility under EU Taxonomy technical screening criteria.
- Concrete:Foundation and core systems still require conventional materials, fragmenting supply chains and preventing full timber-system cost advantages. Boverket's whole-building life-cycle carbon declarations expose concrete-intensive projects to capital access tightening.
- Steel:Structural steel retains dominance in high-rise applications exceeding mass timber height allowances. Thermal bridge performance gaps relative to engineered wood systems pressure specification shares in mid-rise residential.
- Wood:Cross-laminated timber manufacturing advances extend structural applications to eight-story residential, unlocking previously concrete-dependent segments. Sweden's sustainable forestry base and domestic CLT capacity anchor supply security.
- Brick:Façade and partition applications persist in heritage-sensitive urban contexts, though structural substitution by timber frame systems accelerates in volume housing. Aesthetic premiums sustain niche positioning in premium residential.
By installed value, concrete retains leadership. By specification momentum, engineered timber is gaining share fastest as green bond eligibility redirects institutional capital.
Project Size:
Customer type concentration distinguishes mega projects with sovereign wealth and pension fund backing from homeowner-driven small-scale development, with procurement patterns diverging across risk tolerance and timeline flexibility.
- Small Scale:Single-family and small multi-family projects concentrate in homeowner and small developer segments. Permitting friction is lower but financing costs exceed institutional project benchmarks.
- Medium Scale:Mid-rise residential and commercial infill dominates Stockholm and Gothenburg permit backlogs. Prefabricated volumetric modules reduce on-site labor dependency in these project tiers.
- Large Scale:Master-planned residential districts and corporate campuses require integrated design-build delivery. Skanska and Peab anchor positioning through geographic concentration and local subcontractor network control.
- Mega Projects:Infrastructure-coupled development and major institutional complexes concentrate public procurement attention. Extended performance warranties and digital twin handover mandates shape contractor capability requirements.
By permit count, medium scale leads. By capital deployment, mega projects show the steepest expansion trajectory as transit-oriented development policies intensify.
End User:
Margin structure varies across end user categories, with government procurement emphasizing lifecycle cost and warranty terms while developers prioritize speed-to-market and pre-leasing risk mitigation.
- Developers:Speculative residential and commercial builders concentrate in Stockholm metropolitan corridor, where housing shortages sustain permit backlogs. Pre-certification under Miljöbyggnad Gold secures green financing advantages.
- Contractors:Design-build entities and traditional general contractors compete on manufacturing scale and prefabrication integration. NCC's factory-built structural elements supply multiple concurrent projects.
- Government:Public procurement mandates energy performance thresholds and climate reporting compliance. Boverket enforcement and Swedish Environmental Protection Agency administration shape material specification decisions.
- Homeowners:Individual commissioning concentrates in small-scale residential and renovation-adjacent new build. Financing access depends on certified contractor networks and municipal permitting relationships.
By project volume, developers lead. By contract value concentration, government procurement is expanding most quickly as public infrastructure coupling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stockholm's transit-oriented development policies concentrate permit issuance differently than Gothenburg's corporate leasing market or Malmö's logistics corridor, creating distinct construction-type mixes across Sweden's three metropolitan anchors.
Stockholm Metropolitan Corridor
Multi-family residential dominates permit volumes as housing deficits sustain developer pipelines along commuter rail nodes. Boverket's energy performance standards mandate thermal envelope compliance that extends design-review cycles. The Stockholm County densification policy concentrates construction in Solna, Sundbyberg, and Kista, where prefabricated volumetric modules reduce on-site labor dependency.
Gothenburg Corporate Leasing Market
Office and commercial structures command Miljöbyggnad certification premiums that expand developer margins on greenfield projects. The Swedish Environmental Protection Agency administers climate reporting requirements affecting material sourcing decisions. Lindholmen Science Park and Hisingen district anchor life-science and logistics verticals where speed-to-occupancy overrides traditional risk-allocation preferences.
Malmö Corridor
Housing permit backlogs exceed Stockholm's on a per-capita basis, offering first-mover positioning in Sweden's third metropolitan region. EU Taxonomy technical screening criteria for sustainable construction redirect institutional investment toward certified timber structures. Hyllie and Västra Hamnen districts concentrate transit-oriented development with integrated digital twin handover mandates for institutional owners.
Uppsala-Stockholm Periphery
Medium-scale residential infill connects to Stockholm's commuter rail network with lower land acquisition friction than core county zones. Boverket enforces national building codes that mandate energy performance thresholds across all new construction. Knivsta and Bålsta municipalities experience accelerated permitting as developers seek alternatives to Stockholm's competitive land market.
Sweden New Construction Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The Sweden new construction market structures around three to four dominant integrated contractors controlling municipal permitting relationships and local subcontractor networks, while mid-tier specialists compete on prefabrication integration and certified timber delivery. Strategic archetypes include geography-anchored general contractors, manufacturing-scale prefabrication suppliers, and design-build entities capturing upstream engineering fees. Competitive moves center on EU Taxonomy alignment for green bond eligibility and prefabricated volumetric module deployment to compress weather-risk exposure.
Among Sweden-based contractors, Skanska, NCC, and Peab occupy positions across the capability-scale spectrum. Skanska exemplifies the integrated design-build archetype through in-house engineering capabilities. NCC represents manufacturing-scale competition via factory-built structural elements. Peab anchors geographic concentration in Sweden's three largest urban regions, controlling local subcontractor networks.
| Leading Market Players |
|---|
| Skanska |
| NCC |
| Peab |
| Sweco |
| AFRY |
| Bravida |
| Serneke Group |
| Instalco |
| JM AB |
| Others |
Pricing and Supply Chain Analysis
German and Austrian polyurethane adhesive concentration exposes Swedish CLT manufacturers to input cost volatility that simultaneously widens pricing spreads between certified timber structures and conventional concrete systems while forcing supply chain fragmentation around foundation-core material dependencies.
Pricing Analysis
Project-based contracting dominates procurement, with long-term offtake agreements rare outside institutional mega-projects. Price differentiation rests on Miljöbyggnad certification grade and volume-scale prefabrication integration, with Gold-certified timber commanding financing advantages under EU Taxonomy screening. Cost compression in speculative residential runs through structural adhesive import exposure and timber engineering talent scarcity. Small-scale homeowner segments exhibit highest price sensitivity, while institutional buyers prioritize lifecycle cost certainty over upfront capital outlay.
Supply Chain Analysis
Cross-laminated timber manufacturing concentrates in Sweden, Austria, and Germany, with Swedish domestic capacity anchored by sustainable forestry certification advantages. Raw material flows draw from Nordic spruce stands, German polyurethane binder chemistry, and Austrian engineering software for fire-rated assembly design. Single-source vulnerability sits with adhesive suppliers, where three producers control European structural binder output. Distribution runs through integrated contractor prefabrication facilities and regional timber merchant networks serving project-based demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Structural designers with CLT-specific fire and acoustic modeling capabilities command wage premiums that erode contractor margins, creating acquisition targets for engineering capability buildout and partnership structures that lock scarce talent.
For Market Incumbents: Entrench municipal permitting relationships in Stockholm, Gothenburg, and Malmö through accelerated pre-certification under Boverket's tightening energy codes. Capture backward integration into CLT manufacturing capacity before adhesive supply concentration triggers further cost volatility. Anchor geographic density to control local subcontractor networks against emerging design-build competitors.
For New Entrants and Emerging Players: Malmö corridor housing permit backlogs exceeding Stockholm's per-capita baseline offer first-mover positioning with lower land acquisition friction. Target medium-scale residential infill in Uppsala-Stockholm periphery municipalities where commuter rail connectivity reduces core county competitive intensity. Enter through prefabricated volumetric module specialization that compresses on-site labor dependency and weather-risk exposure.
For Investors and Strategic Acquirers: EU Taxonomy technical screening criteria tightening reshapes the acquisition landscape toward certified timber capabilities and Miljöbyggnad Gold pre-certification pipelines. Long-term viability centers on contractors with integrated design-build delivery and captive CLT engineering talent. Monitor Boverket stepwise energy code announcements as inflection signals for capital reallocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| CLT Manufacturing Scale-Up | Domestic cross-laminated timber capacity anchors supply security against German adhesive import volatility. |
| Miljöbyggnad Gold Pre-Certification | Early certification secures green bond eligibility under EU Taxonomy technical screening criteria. |
| Prefabricated Volumetric Module Deployment | Factory-built bathroom and kitchen pods compress weather-risk exposure in Nordic construction cycles. |
| Timber Engineering Talent Acquisition | CLT-specific fire and acoustic modeling capabilities command premiums that determine project viability. |
| Transit-Oriented Development Pipeline Lock | Stockholm County densification policies concentrate permits along commuter rail corridors with reduced land friction. |
Research Methodology
Cross-validation between municipal permitting databases and contractor project pipelines anchors the qualitative findings in this study. Primary interviews with residential developers, structural timber engineers, Boverket compliance officers, and institutional facility managers combined with secondary validation from Swedish Environmental Protection Agency climate reporting disclosures, EU Taxonomy technical screening documentation, and forestry certification registry data. Bottom-up project pipeline enumeration and top-down construction value triangulation establish volume boundaries.
Calibration against historical permit issuance patterns and material specification shifts across Stockholm, Gothenburg, and Malmö metropolitan corridors informs the analytical framework. Segmentation dimensions modeled include construction type, material specification, project scale tier, and end-user procurement archetype across the projection horizon. CAGRs derive from weighted scenario analysis incorporating Boverket regulatory step-change assumptions and CLT manufacturing capacity expansion trajectories. Timber engineering labor market tightness and adhesive import cost volatility serve as industry-specific forecast inputs.
Practitioners should monitor Boverket energy code amendment timing and EU Taxonomy screening criteria evolution for early signals of forecast revision. Quarterly review of CLT manufacturing capacity utilization and German adhesive supplier pricing disclosure is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
GCC Cement Market
Building Construction
Global Dry Construction Market
Building Construction
Construction Market
Building Construction
China Modular Construction Market
Building Construction
Thailand Construction Market
Building Construction
Middle East & Africa Infrastructure Construction Market
Building Construction
Vietnam Prefabricated Buildings Market
Building Construction
Saudi Arabia Transportation Infrastructure Construction Market
Building Construction
France Prefab Wood Building Market
Building Construction
United States Commercial Construction Market
Building Construction
Saudi Arabia Construction Market
Building Construction
India Pre-Engineered Buildings Market
Building Construction
Brazil Construction Market
Building Construction
India Prefabricated Buildings Market
Building Construction
Germany Prefabricated Buildings Market
Building Construction
Modular and Portable Building Market