
 Global Orthopedic Veterinary Implants Market | 2026-2036
Global Orthopedic Veterinary Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Orthopedic Veterinary Implants Market Foresight
Aftermarket service revenue is reconfiguring how orthopedic veterinary implant suppliers capture lifetime value from their installed base. DePuy Synthes leverages its Johnson & Johnson infrastructure to extend technical training and instrument refurbishment programs into companion animal hospitals. Arthrex Vet Systems competes through specialized arthroscopy platforms that dominate the cruciate ligament reconstruction segment. BioMedtrix anchors its position with titanium alloy plating systems designed specifically for canine anatomy.
Orthopedic veterinary implants comprise screws, plates, pins, and advanced fixation devices manufactured from titanium alloys, stainless steel, cobalt-chrome, or bioabsorbable polymers to stabilize bone fractures and reconstruct joints in companion and production animals. These devices typically achieve osseointegration within twelve to twenty-four weeks and must withstand cyclic loading at forces proportional to species body weight. Metal implants, particularly titanium systems, command the largest revenue share due to proven fatigue resistance and biocompatibility profiles. Joint reconstruction applications represent the fastest-expanding category as tibial plateau leveling osteotomy and total hip replacement volumes rise in specialty referral practices.
FDA Center for Veterinary Medicine oversees implant biocompatibility and sterilization validation, while ISO 10993 standards govern cytotoxicity and sensitization testing for devices entering multiple jurisdictions. The EU Veterinary Medicines Regulation and MDR framework impose additional clinical documentation requirements on manufacturers distributing across European member states. Stakeholders must monitor evolving reimbursement pathways for advanced orthopedic procedures as pet insurance models shift from indemnity structures toward direct veterinary payment systems.
Market Dynamics
Specialty veterinary clinics are consolidating orthopedic surgical capacity through centralized referral networks, concentrating demand for advanced fixation systems and joint reconstruction platforms among fewer high-volume purchasers with stringent technical support requirements.
Growth Catalysts
- EU MDR Framework:Stricter clinical documentation requirements for implantable devices entering European markets are accelerating manufacturer investment in biocompatibility validation, raising barriers for marginal competitors and protecting established suppliers with robust quality systems.
- Titanium Alloy Systems:Proven osseointegration performance and fatigue resistance under cyclic loading conditions proportional to canine body weight are cementing titanium's position as the default material for plating and screw applications across companion animal trauma centers.
- Pet Insurance Penetration:Direct veterinary payment systems replacing traditional indemnity structures in the United States, Germany, and Japan are reducing owner cost sensitivity for advanced procedures, expanding addressable volumes for tibial plateau leveling osteotomy and total hip replacement.
Market Restraints
- Titanium Feedstock Volatility:Aerospace and medical device competition for aerospace-grade titanium sponge concentrates supply risk among a limited base of certified smelters, compressing margin stability for implant manufacturers without long-term offtake agreements.
- FDA Center for Veterinary Medicine:Extended sterilization validation timelines and biocompatibility testing requirements for novel materials or surface treatments create regulatory friction that delays product commercialization by eighteen to thirty-six months relative to human orthopedic equivalents.
- External Fixation Substitutes:Ring fixators and linear external skeletal fixation systems retain cost and versatility advantages for complex fracture management in large-breed dogs and exotic species, limiting internal implant penetration in price-sensitive practice segments.
Strategic Opportunities
- Production Animal Segment:Brazil and Australia's cattle and equine industries present underpenetrated demand for fracture stabilization in high-value breeding stock and performance animals, where economic loss from culling drives willingness to invest in surgical intervention.
- 3D-Printed Patient-Specific Implants:Additive manufacturing convergence with computed tomography-based surgical planning is digitizing preoperative workflow, enabling anatomically contoured plates for brachycephalic breeds and exotic species with non-standard skeletal geometry.
- Technical Training Programs:Instrument refurbishment and surgeon certification services represent a channel innovation that locks in recurring revenue and creates switching costs, with DePuy Synthes leveraging Johnson & Johnson infrastructure to embed service contracts within hospital purchasing agreements.
Industry Challenges
- Veterinary Orthopedic Surgeon Pipeline:The four to six year residency requirement for board certification in veterinary surgery creates a talent bottleneck that limits procedure volume expansion even where implant availability and owner demand align.
- ISO 10993 Cytotoxicity Testing:Multi-jurisdictional compliance with sensitization and systemic toxicity validation protocols extends certification timelines and requires redundant testing when formulations or sterilization methods change, compressing product refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Orthopedic Veterinary Implants Market |
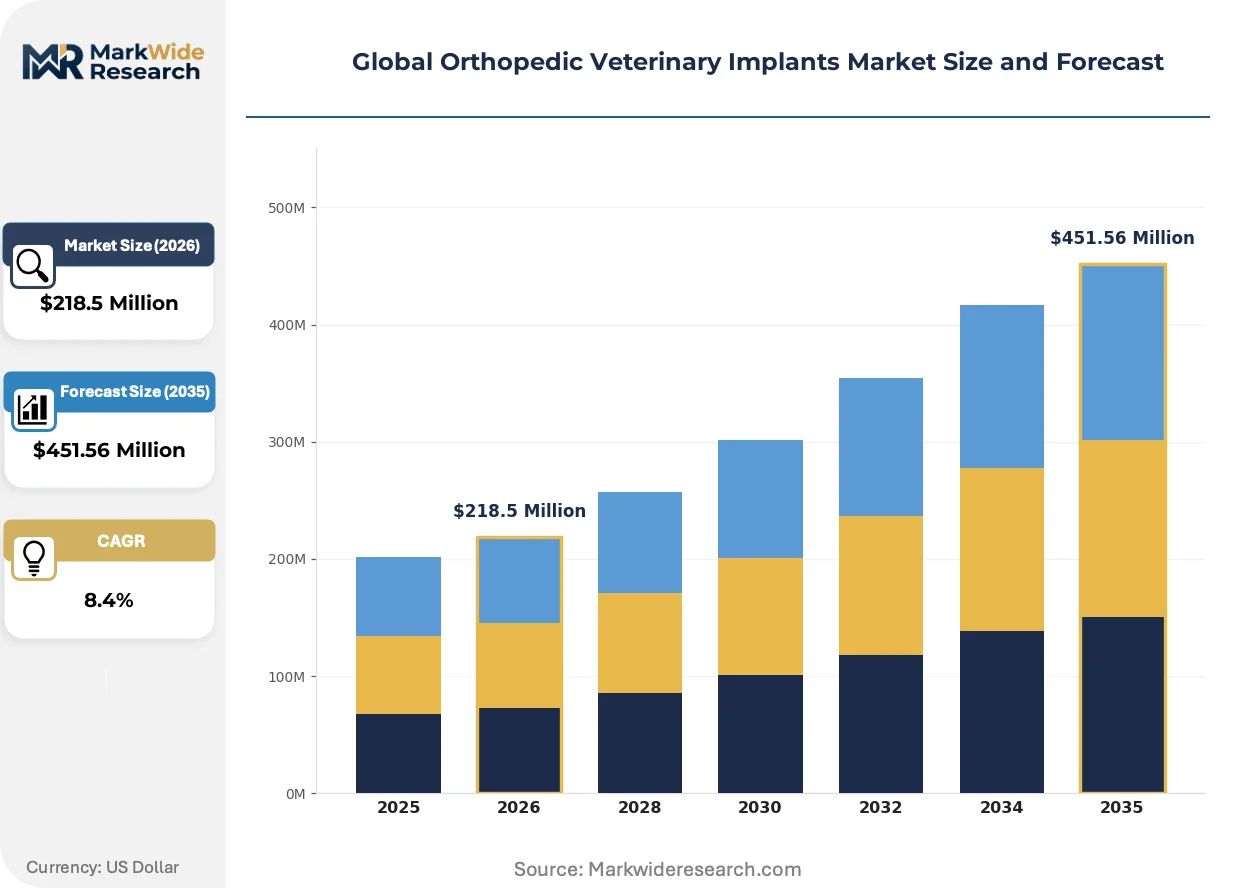
| Market Size in 2026 | $218.5 Million |
| Market Size in 2035 | $451.56 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screws, Plates, Pins, Implants Material: Metals, Polymers, Composites, Ceramics Application: Bone Fractures, Joint Reconstruction, Soft Tissue Repairs, Spinal Surgery End User: Veterinary Clinics, Animal Hospitals, Research Institutes, Rehabilitation Centers |
| Companies Covered | Movora (Vimian Group), DePuy Synthes (Johnson & Johnson), Arthrex Vet Systems, B. Braun, BioMedtrix, Integra LifeSciences, Veterinary Instrumentation, Orthomed (UK) Ltd., IMEX Veterinary, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Orthopedic Veterinary Implants Market Shifts & Advancements
Digital surgical planning platforms and bioabsorbable polymer formulations are compressing traditional metal-dominated fixation paradigms, while regulatory harmonization pressures and evolving procurement models reshape competitive positioning across developed veterinary markets.
Additive manufacturing of titanium lattice structures is digitizing implant customization workflows, enabling patient-specific plate geometries that match individual canine tibial anatomy. Specialty referral practices in the United States and Germany are adopting these platforms at accelerating rates, compressing lead times from imaging to sterilized implant delivery from weeks to under seventy-two hours. This capability is digitizing competitive differentiation away from standard catalog breadth toward surgical planning software integration and distributed manufacturing networks.
EU MDR implementation is tightening clinical evidence requirements for implantable veterinary devices entering European member states, forcing manufacturers to retroactively compile biocompatibility documentation previously accepted under notified body discretion. The regulatory burden falls most heavily on mid-tier suppliers lacking dedicated regulatory affairs infrastructure, accelerating consolidation toward enterprises with established human medical device compliance capabilities. Swissmedic and TGA are monitoring MDR implementation outcomes to calibrate their own veterinary implant oversight frameworks.
Consolidation among specialty veterinary hospital groups is concentrating purchasing authority among fewer procurement decision-makers with standardized vendor qualification criteria. Independent distributors that historically stocked multiple manufacturer lines are losing shelf space to direct manufacturer partnerships with national hospital networks, most visibly in Japan where corporate veterinary chains now control over forty percent of cruciate ligament procedure volumes. This channel compression favors suppliers with dedicated field service engineers and instrument loaner programs capable of supporting centralized sterilization departments.
Global Orthopedic Veterinary Implants Market Segmentation
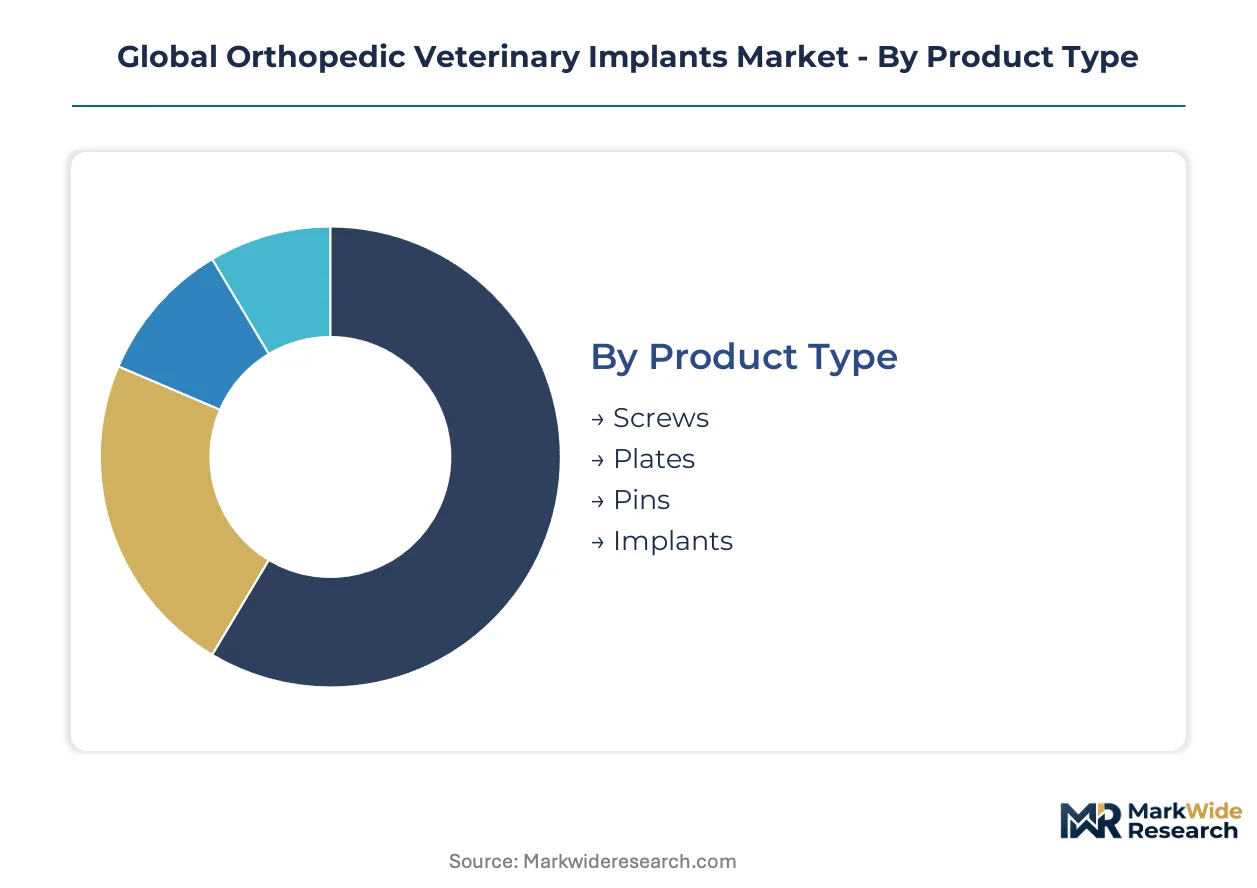
Segmentation in orthopedic veterinary implants reveals how material science, surgical application, and care setting interact to determine purchasing patterns. Manufacturers must align product portfolios across these dimensions to capture value from trauma centers, referral hospitals, and emerging production animal markets.
Product Type:
Mature fixation hardware dominates current surgical volumes while advanced implantable systems emerge as the fastest-expanding category.
- Screws:Titanium and stainless steel cortical and cancellous bone screws provide primary fixation for fracture reduction in companion animals. Demand concentrates in United States trauma centers where board-certified surgeons perform high-volume fracture repairs, with titanium alloy variants preferred for their fatigue resistance under cyclic loading proportional to canine body weight.
- Plates:Dynamic compression plates and locking plate systems manufactured from titanium alloys or stainless steel stabilize long-bone fractures through rigid internal fixation. German and Japanese specialty hospitals drive adoption of anatomically contoured plating systems designed for specific breeds, with direct manufacturer partnerships replacing traditional distributor channels.
- Pins:Intramedullary pins and Kirschner wires offer cost-effective stabilization for simple fractures and pediatric patients. Brazil's equine and cattle sectors utilize pins for production animal fracture management where economic constraints limit internal implant penetration.
- Implants:Advanced fixation devices including interlocking nails and total joint prostheses represent the technology frontier in veterinary orthopedics. Australia's growing referral network and Japan's corporate veterinary chains are expanding volumes for tibial plateau leveling osteotomy and total hip replacement platforms.
Plates handle the majority of throughput; implants are the fastest mover on share.
Material:
Cost tier stratification separates premium biocompatible metals from emerging biodegradable alternatives.
- Metals:Titanium alloys, stainless steel, and cobalt-chrome deliver proven osseointegration and fatigue resistance for permanent fixation. FDA and USDA regulatory frameworks enforce biocompatibility validation that favors established suppliers with robust quality systems.
- Polymers:Bioabsorbable poly-L-lactic acid and polyglycolic acid formulations eliminate implant removal surgeries in juvenile patients. European specialty practices under EU MDR compliance pressure are evaluating polymer systems for selected applications.
- Composites:Carbon fiber-reinforced polymers and polymer-ceramic hybrids balance strength with radiolucency for postoperative imaging. Research institutes in Germany and Japan pilot composite systems for exotic species with non-standard skeletal geometry.
- Ceramics:Hydroxyapatite-coated and bulk ceramic implants enhance bone bonding for joint reconstruction applications. United States academic veterinary medical centers investigate ceramic femoral heads for total hip replacement durability.
Metals absorb the dominant share of material expenditure; polymers are climbing the fastest on clinical validation.
Application:
Volume concentration in trauma care contrasts with margin expansion in reconstructive procedures.
- Bone Fractures:Internal fixation of traumatic long-bone and pelvic fractures constitutes the foundational application for plating and screw systems. United States emergency and referral hospitals generate consistent demand from motor vehicle trauma and sporting injuries in working dogs.
- Joint Reconstruction:Cruciate ligament repair, tibial plateau leveling osteotomy, and total hip replacement command premium pricing and specialized instrumentation. Japanese corporate veterinary chains now control substantial procedure volumes, concentrating purchasing authority among centralized procurement departments.
- Soft Tissue Repairs:Suture anchors and interference screws address tendon and ligament injuries in performance and racing animals. Australia's equine industry drives specialized demand for suspensory ligament repair systems.
- Spinal Surgery:Vertebral stabilization plates and pedicle screw systems manage intervertebral disc disease and spinal trauma. German and United States neurology referral centers pioneer advanced spinal fixation techniques.
Bone fractures generate the highest procedure count; joint reconstruction delivers the steepest expansion trajectory.
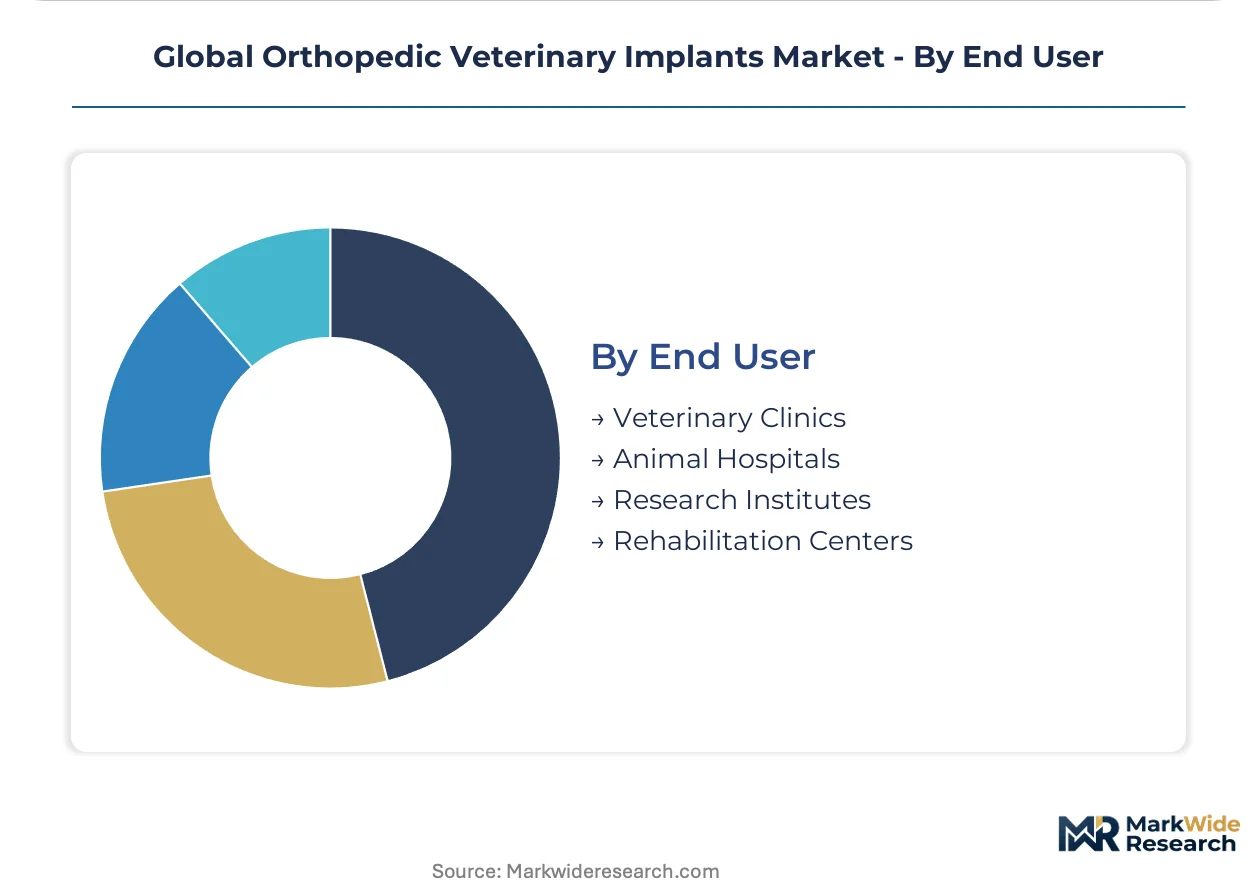
End User:
Customer type determines technical support requirements and procurement sophistication.
- Veterinary Clinics:General practice clinics manage simple fracture repairs and postoperative rehabilitation with basic fixation inventory. United States and German general practitioners refer complex cases to specialty centers, limiting advanced implant stocking.
- Animal Hospitals:Multi-specialty and emergency hospitals maintain comprehensive orthopedic instrumentation and sterilization infrastructure. Japan's corporate hospital networks and United States university-affiliated teaching hospitals concentrate demand for advanced joint reconstruction platforms.
- Research Institutes:Academic veterinary medical centers validate novel materials and surgical techniques through controlled studies. German and United States institutions collaborate with manufacturers on biomechanical testing and clinical outcome documentation.
- Rehabilitation Centers:Postoperative physical therapy facilities coordinate with surgical centers for implant monitoring and complication management. Emerging integration with specialty hospitals in Australia and Japan creates continuity-of-care revenue opportunities.
Animal hospitals command the largest procurement budgets; research institutes are gaining influence on technology adoption curves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across veterinary markets: owners in Japan and Germany exhibit minimal cost sensitivity where pet insurance penetration exceeds forty percent, while Brazilian cattle producers and Australian equine operators demand fracture stabilization at commodity-equivalent price points.
United States
Corporate veterinary chains now control over forty percent of cruciate ligament procedure volumes, concentrating purchasing authority among centralized procurement departments with standardized vendor qualification criteria. FDA Center for Veterinary Medicine oversees implant biocompatibility and sterilization validation, extending commercialization timelines eighteen to thirty-six months versus human orthopedic equivalents. University-affiliated teaching hospitals in California and North Carolina drive adoption of advanced joint reconstruction platforms through residency training programs.
Germany
Specialty referral practices under EU MDR compliance pressure are evaluating bioabsorbable polymer systems for selected juvenile applications while maintaining titanium alloy dominance in trauma centers. The EU Veterinary Medicines Regulation and MDR framework impose additional clinical documentation requirements on manufacturers distributing across European member states. Bavarian and Baden-Württemberg veterinary medical centers collaborate with manufacturers on biomechanical testing and clinical outcome documentation.
Japan
Corporate veterinary chains concentrate demand for tibial plateau leveling osteotomy and total hip replacement platforms among fewer high-volume purchasers with stringent technical support requirements. METI monitors veterinary device oversight frameworks as Swissmedic and TGA track MDR implementation outcomes for calibration. Tokyo and Osaka metropolitan areas host the densest concentration of board-certified veterinary surgeons in the Asia-Pacific region.
Brazil
Cattle and equine industries present underpenetrated demand for fracture stabilization in high-value breeding stock and performance animals, where economic loss from culling drives willingness to invest in surgical intervention. ANVISA regulates veterinary product registration with timelines that compress margin recovery for imported implant systems. São Paulo and Rio Grande do Sul veterinary networks serve as distribution hubs for southern cone production animal markets.
Australia
Growing referral networks expand volumes for advanced fixation systems as specialty hospitals integrate with postoperative rehabilitation facilities for continuity-of-care revenue capture. TGA monitors EU MDR implementation outcomes to calibrate veterinary implant oversight frameworks. New South Wales and Victoria concentrate equine suspensory ligament repair demand from thoroughbred racing and performance breeding operations.
Global Orthopedic Veterinary Implants Market Competitive Landscape
Capability concentration sits with diversified medical device conglomerates; scale advantage sits with specialized veterinary-focused suppliers. The market structures around three tiers: human orthopedic divisions extending into companion animal applications, dedicated veterinary implant manufacturers with species-specific anatomical expertise, and regional fabricators serving price-sensitive production animal segments. Dominant competitive moves include direct manufacturer partnerships with national hospital networks replacing independent distributor channels, and instrument refurbishment services embedding recurring revenue within hospital purchasing agreements.
Within the diversified medical device tier, DePuy Synthes and B. Braun represent archetypes of human orthopedic infrastructure extending into veterinary applications through technical training and instrument refurbishment programs. BioMedtrix occupies a position exemplifying dedicated veterinary specialization with titanium alloy systems designed specifically for canine anatomy. Among arthroscopy-focused suppliers, Arthrex Vet Systems anchors the cruciate ligament reconstruction segment through specialized platform development.
| Leading Market Players |
|---|
| Movora (Vimian Group) |
| DePuy Synthes (Johnson & Johnson) |
| Arthrex Vet Systems |
| B. Braun |
| BioMedtrix |
| Integra LifeSciences |
| Veterinary Instrumentation |
| Orthomed (UK) Ltd. |
| IMEX Veterinary |
| Others |
Supply & Pricing Matrix
Trans-Pacific air freight corridors connecting titanium sponge producers in Japan to precision machining clusters in Germany and the United States impose landed cost differentials that stratify implant pricing across veterinary markets. These logistics economics concentrate margin recovery among manufacturers with captive sterilization infrastructure near end-user demand, while compressing price realization for suppliers dependent on third-party terminal sterilization.
Pricing Analysis
Long-term offtake agreements for aerospace-grade titanium sponge anchor pricing stability for tier-one suppliers, while spot-market exposure punishes smaller manufacturers during feedstock volatility. Three-tier pricing structure across premium, standard, and economy levels reflects FDA validation status, ISO 10993 certification completeness, and bundled technical training. Pricing pressure stems from Brazilian and Australian production animal segments demanding commodity-equivalent fracture stabilization, while Japanese corporate veterinary chains exhibit minimal cost sensitivity under direct veterinary payment systems.
Supply Chain Analysis
Contract manufacturing concentration sits with Swiss and German precision machining houses holding EU MDR-compliant quality certifications, while titanium alloy forging capacity clusters in United States and Japanese aerospace-adjacent facilities. Supply chains draw from cobalt-chrome feedstock in United States, titanium sponge in Japan, and bioabsorbable polymer resin in Germany. Single-source vulnerability concentrates in aerospace-grade titanium sponge from certified smelters serving both human and veterinary device manufacturers. Distribution runs through direct manufacturer partnerships with national hospital networks, displacing independent veterinary distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orthopedic veterinary implants represent early-cycle expansion as pet insurance penetration crosses critical thresholds in developed markets, converting historically discretionary procedures into financially accessible care pathways.
For Market Incumbents: Build regulatory documentation moats by retroactively compiling ISO 10993 biocompatibility portfolios under EU MDR pressure, accelerating consolidation toward enterprises with established human medical device compliance capabilities. Deepen backward integration into titanium alloy forging capacity to hedge aerospace feedstock competition. Lock in switching costs through instrument refurbishment contracts embedded within hospital purchasing agreements, defending against specialized veterinary-focused competitors with species-specific anatomical expertise. For New Entrants and Emerging Players: Brazil's cattle and equine fracture stabilization markets represent the most penetrable entry point, where economic loss from culling drives surgical intervention willingness absent insurance infrastructure. Australia's growing specialty referral networks for equine suspensory ligament repair offer second-mover positioning in performance animal orthopedics. Partner with computed tomography-based surgical planning platforms to bypass capital-intensive sterilization infrastructure requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates with underutilized veterinary divisions lacking dedicated regulatory affairs infrastructure. Five-to-ten year viability hinges on convergence between human orthopedic manufacturing scale and veterinary-specific anatomical customization capabilities. Watch for inflection in 3D-printed patient-specific implant adoption rates among brachycephalic breed specialists as signal of manufacturing workflow digitization maturity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Investment | Retroactive biocompatibility documentation protects market access across German and French veterinary markets. |
| Direct Hospital Network Partnership | Bypassing independent distributors captures procurement authority concentrated in Japanese corporate chains. |
| 3D-Printed Patient-Specific Implant Launch | Computed tomography integration compresses lead times from imaging to sterilized delivery under seventy-two hours. |
| Technical Training Program Expansion | Surgeon certification services embed recurring revenue and create switching costs within purchasing agreements. |
| Production Animal Segment Entry | Brazilian cattle and Australian equine markets offer underpenetrated demand for fracture stabilization systems. |
Research Methodology
The analysis maps titanium alloy plating systems, bioabsorbable polymer formulations, and 3D-printed patient-specific implants, each validated through interviews with board-certified veterinary surgeons, hospital procurement managers, biomedical engineers, and GPO contracts managers. Primary intelligence combined with secondary validation from FDA Center for Veterinary Medicine filings, EU MDR notified body documentation, ISO 10993 test reports, and hospital procurement databases. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue segmentation.
Assumptions held fixed include regulatory framework stability across the analysis window, while pet insurance penetration trajectories and titanium feedstock pricing were varied under sensitivity scenarios. Segmentation dimensions modeled encompass material type, surgical application, end-user category, and regional referral practice density. CAGRs derived from procedure volume elasticity to insurance coverage expansion and surgeon pipeline graduation rates, cross-referenced against implant pricing trend analysis.
Practitioners should monitor EU MDR implementation spillover into Swissmedic and TGA frameworks, veterinarian surgeon residency graduation rates, and pet insurance model shifts from indemnity to direct payment for early signals of forecast deviation. Quarterly review of titanium sponge spot pricing, corporate veterinary chain consolidation announcements, and 3D-printing platform adoption metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Ophthalmic Equipment Market
Veterinary
Global Livestock Vaccines Market
Veterinary
Companion Animal Vaccines Market
Veterinary
Compression Veterinary Bandages Market
Veterinary
Veterinary Vaccines Market
Veterinary
Global Swine Vaccines Market
Veterinary
Pet Light Therapy Devices Market
Veterinary
Vet Software Market
Veterinary
Milking Salve Market
Veterinary
Clostridium Vaccine (Animal Health) Market
Veterinary
Veterinary Clostridium Vaccine Market
Veterinary
Veterinary in Vitro Fertilization Market
Veterinary
US Surgical Pet Collar Market
Veterinary
Homeopathic Veterinary Medicines Market
Veterinary
Global Animal Model Market
Veterinary
Pet Cremation Market