
 Argentina Compound Feed Market | 2026-2036
Argentina Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Compound Feed Market Outlook
Specialized pellet-to-mash bundling is repositioning procurement patterns among mid-sized Argentine livestock operators. Nutreco N.V. anchors its presence through advanced premix formulations tailored to regional forage deficits. Cargill Inc dominates the upstream grain origination chain, securing cost advantages in corn-soybean sourcing across the Pampas. JBS S.A. leverages its integrated protein platform to pull compound feed volumes through captive slaughter capacity.
Compound feed denotes nutritionally complete rations manufactured by blending grains, oilseed meals, protein supplements, minerals, vitamins, and additives into specified formulations meeting species-specific metabolizable energy and amino acid requirements. Pellet form commands premium placement in intensive poultry and swine systems due to reduced feed wastage and improved digestibility. Crumbles occupy the fastest-growing form niche as broiler operators transition from starter mash to denser configurations. Additives represent the concentrated margin pool where phytogenic and acidifier categories attract formulation investment.
SENASA enforces feed safety and veterinary residue standards that shape import approval pathways for novel additives. The Argentine Secretariat of Agriculture, Livestock and Fisheries monitors grain reserve policies that directly alter input cost structures for domestic millers. Buenos Aires province regulators coordinate environmental compliance for large-scale feedlot effluent management. Stakeholders must track how drought-induced grain export quota shifts redistribute bargaining power between integrated processors and independent formulators.
Market Dynamics
SENASA feed safety protocols are compressing formulation flexibility while drought-induced grain export quotas redistribute bargaining power between integrated processors and independent millers across the Pampas.
Growth Catalysts
- Poultry intensification:Broiler operators in Córdoba and Santa Fe provinces are expanding climate-controlled housing, pulling compound feed volumes through mechanized feeding systems.
- SENASA residue standards:Tighter veterinary drug monitoring is accelerating adoption of phytogenic feed additives as antibiotic alternatives in export-oriented feedlots.
- Pellet technology diffusion:Mash-to-pellet conversion is reducing feed wastage in swine operations across Buenos Aires province interior.
Market Restraints
- Corn-soybean cost volatility:Grain reserve policy shifts by the Argentine Secretariat of Agriculture alter input cost structures quarterly for domestic formulators.
- Additive import friction:SENASA approval pathways for novel enzymes and acidifiers extend commercialization timelines by 18-24 months.
- Water scarcity:Feedlot effluent discharge regulations in Buenos Aires province constrain expansion of large-scale finishing operations.
Strategic Opportunities
- Phytogenic formulation premium:Export certification requirements for EU-bound beef are creating price premiums for additive-enhanced rations in Entre Ríos feedlots.
- Crumbles niche expansion:Broiler starter-to-grower transition protocols are opening placement opportunities between mash and pellet density configurations.
- Regional premix localization:Deficits in trace mineral bioavailability across Patagonian forage zones are pulling specialized premix manufacturing closer to end-use.
Industry Challenges
- Formulation talent scarcity:Veterinary nutritionists with SENASA compliance expertise command wage premiums that strain mid-sized miller operating models.
- Capex intensity for pellet lines:Steam-conditioning and die-maintenance equipment requires capital deployment that independent operators struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Compound Feed Market |
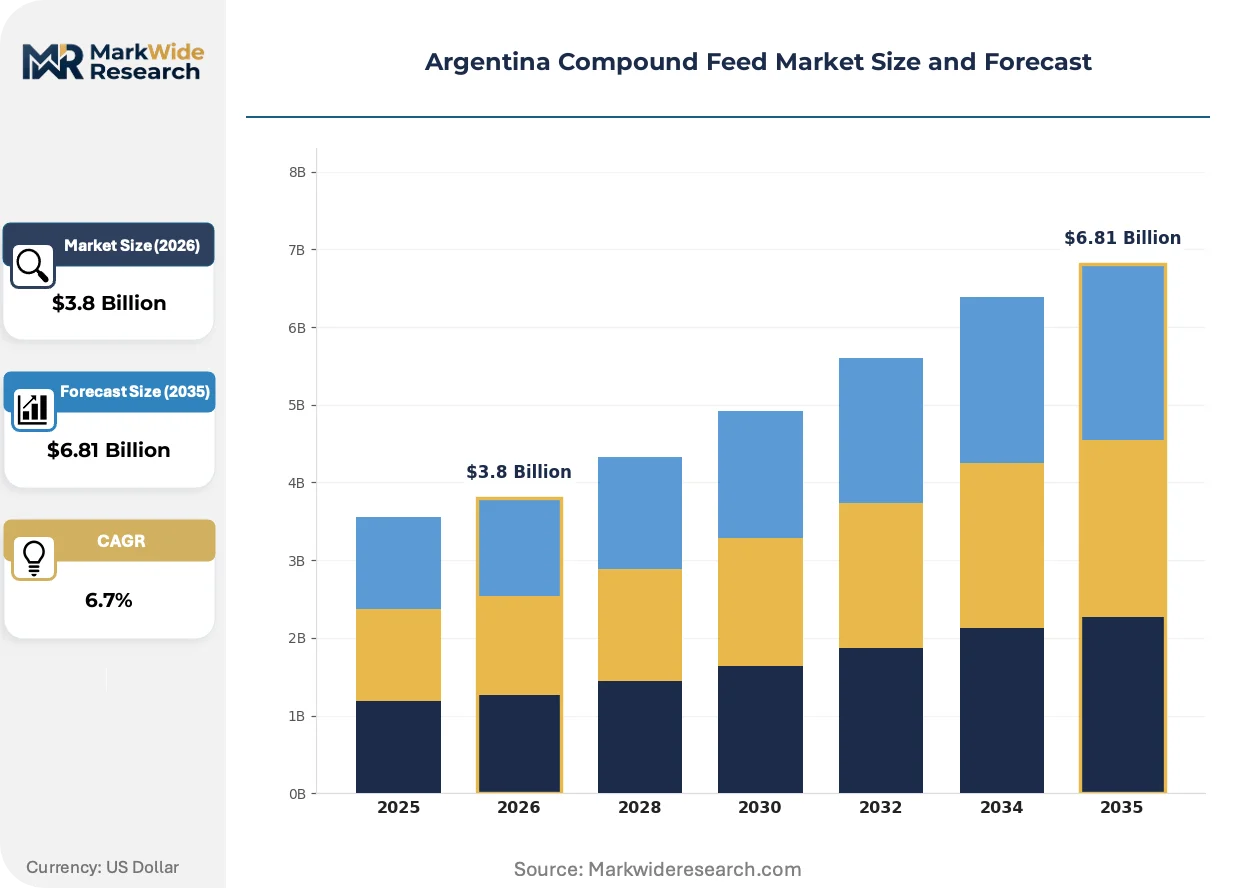
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Supplements, Minerals, Vitamins, Additives End User: Agriculture, Aquaculture, Poultry, Swine Form: Pellets, Crumbles, Mash, Powder Distribution Channel: Direct Sales, Retailers, Online Platforms, Distributors |
| Companies Covered | Land O'Lakes Inc (Purina Mills), Nutreco N.V., Archer Daniels Midland Company, Kemin Industries, DeKalb Feeds, United Animal Health, Cargill Inc, JBS S.A., Alltech Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Compound Feed Market Strategic Shifts
Precision formulation technologies and regulatory pressure on residue limits are compressing traditional mash-dominant rations toward denser, additive-enhanced configurations across Argentine livestock systems.
Near-infrared spectroscopy is integrating into on-farm feed analysis workflows, enabling real-time moisture and protein calibration. Mid-sized poultry operators in Santa Fe province are deploying portable NIR units to adjust ration batches before delivery. This capability is integrating quality control upstream, reducing rejection rates at feedlot intake points.
SENASA Resolution 710/2021 on medicated feed manufacturing is mandating dedicated production lines for antibiotic-containing rations. Large integrated processors are segregating facilities to maintain export eligibility. Swine operations in Buenos Aires province are most affected, with some operators abandoning medicated starter feeds entirely to avoid compliance complexity.
Consolidated procurement is displacing spot-market grain buying among feedlot operators with over five thousand head capacity. Long-term origination contracts with Pampas silo networks are replacing auction-floor purchases. This pattern is most visible in the western Buenos Aires grain belt, where drought risk has made price predictability more valuable than flexibility.
Argentina Compound Feed Market Segmentation
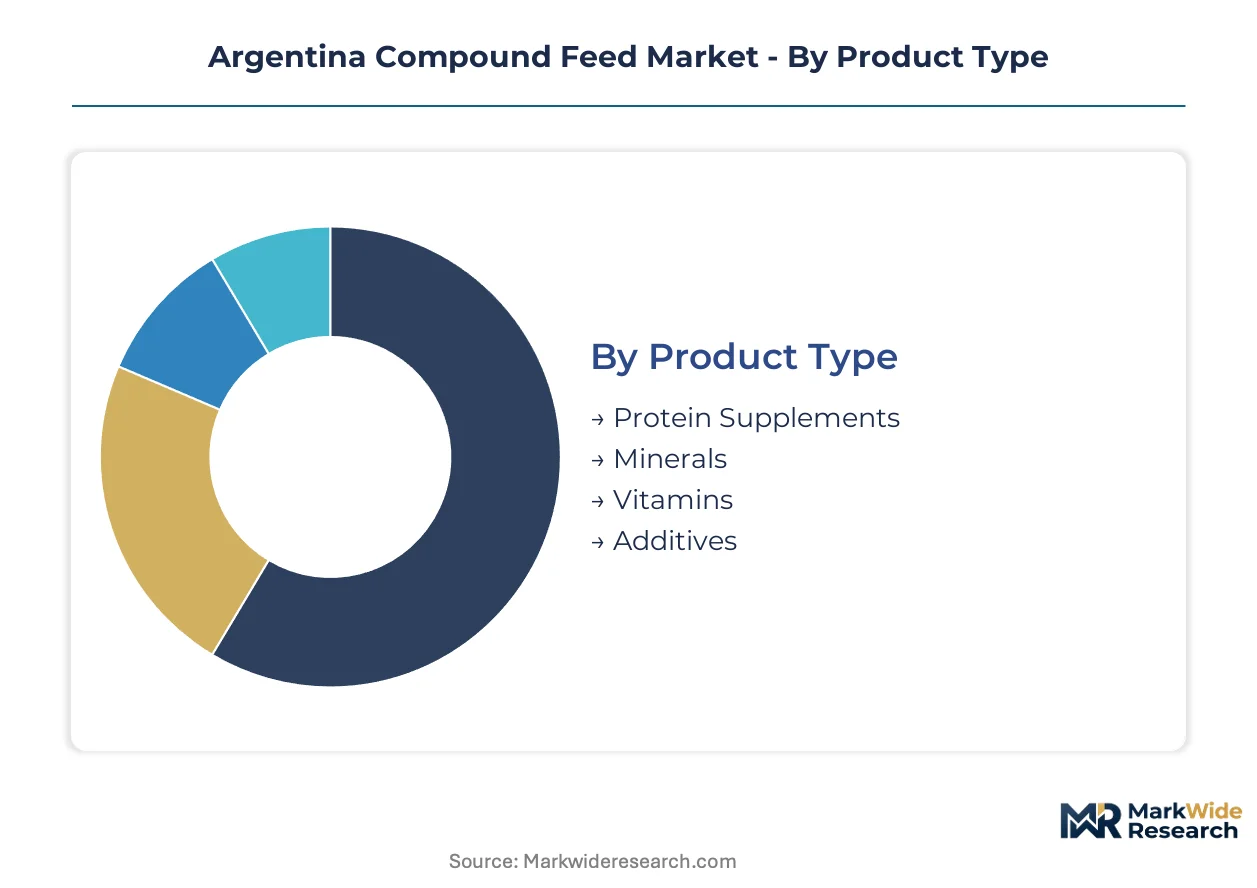
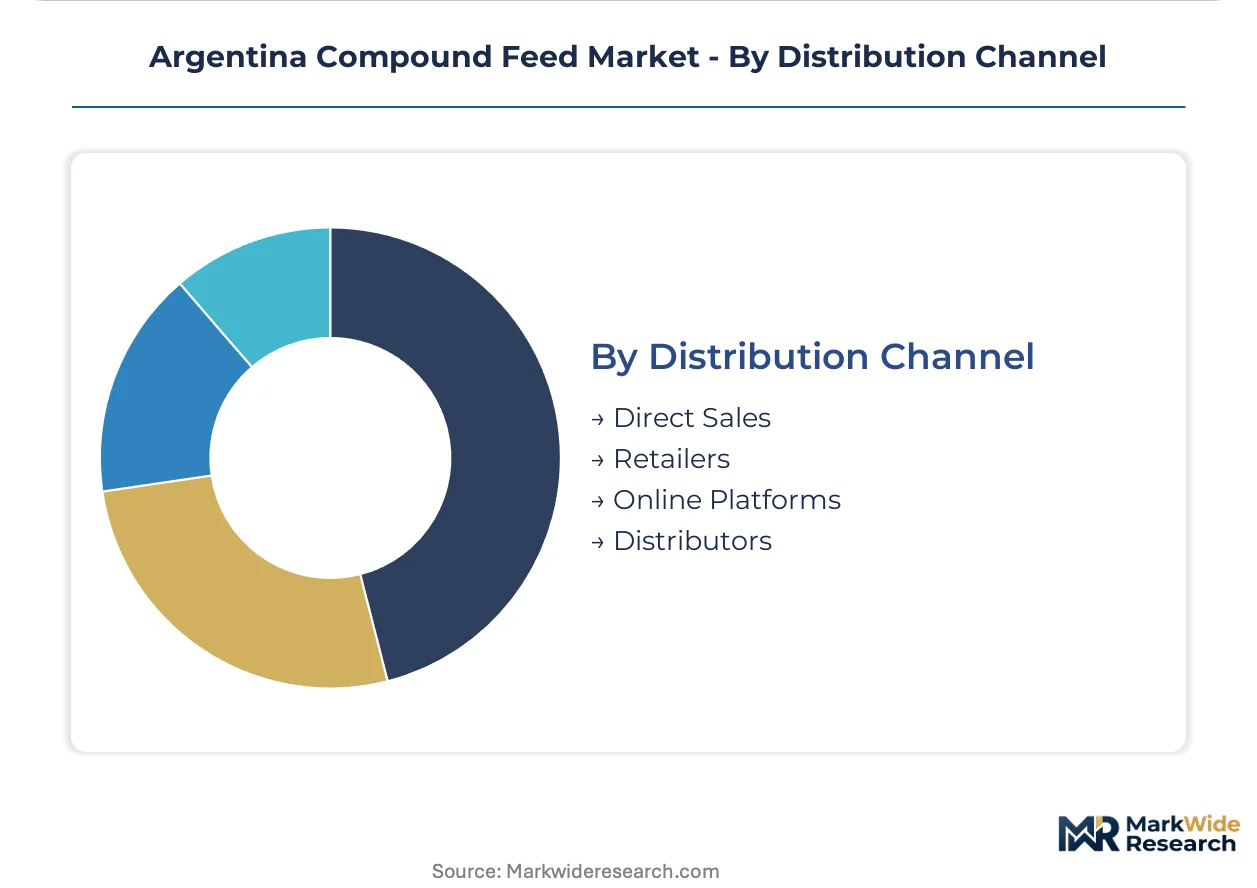
Segmentation reveals how Argentine compound feed demand fragments across species-specific formulations, physical feed forms, and procurement channels. Each dimension carries distinct margin profiles and regulatory exposure under SENASA protocols.
Product Type:
Supply concentration in corn-soybean origination shapes how value migrates toward higher-margin additive categories.
- Protein Supplements:Soybean meal and oilseed derivatives provide metabolizable energy and amino acid density for intensive livestock systems. Buenos Aires province feedlots pull the majority of volumes, though drought-induced export quotas periodically compress domestic availability.
- Additives:Phytogenics, acidifiers, and enzymes command formulation premiums as SENASA residue standards accelerate antibiotic replacement. Export-oriented beef operations in Entre Ríos generate the steepest demand growth for EU-certification-compliant rations.
- Minerals:Trace mineral premixes address bioavailability deficits in Patagonian forage zones, pulling localized manufacturing investment.
- Vitamins:Fat-soluble and water-soluble vitamin blends stabilize under heat-stressed storage conditions across the Pampas grain belt.
Additives absorb the bulk of installed capacity; additives are expanding most quickly.
End User:
Cost tier differentiation separates integrated protein processors from independent livestock operators in procurement behavior.
- Poultry:Broiler operations in Córdoba and Santa Fe provinces drive mechanized feeding system adoption, pulling pellet and crumble volumes through climate-controlled housing expansion. SENASA compliance costs compress margins for mid-sized operators lacking captive slaughter capacity.
- Swine:Finishing operations across Buenos Aires province interior are converting from mash to pelleted rations to reduce feed wastage. Resolution 710/2021 dedicated line requirements are pushing some operators toward antibiotic-free starter protocols entirely.
- Agriculture:Cattle feedlots concentrate in Buenos Aires province, where consolidated procurement contracts with Pampas silo networks displace spot-market grain buying.
- Aquaculture:Trout and shrimp producers in Patagonian water systems generate specialized demand for high-protein extruded feeds with precise lipid profiles.
Poultry absorbs the bulk of installed capacity; poultry is climbing the fastest.
Form:
Volume concentration in intensive systems favors denser physical configurations that reduce transport cost per unit metabolizable energy.
- Pellets:Steam-conditioned, die-extruded rations minimize feed wastage and improve digestibility in poultry and swine confinement operations. Capex intensity for conditioning equipment restricts adoption to integrated processors and large independents.
- Crumbles:Intermediate density between mash and pellet supports broiler starter-to-grower transitions. Santa Fe province operators are expanding crumble placement as a bridge configuration in mechanized feeding protocols.
- Mash:Traditional ground-mix rations persist in ruminant backgrounding operations with lower capital intensity requirements.
- Powder:Micro-ingredient carriers and milk replacer bases serve calf rearing and specialty additive applications.
Pellets absorb the bulk of installed capacity; crumbles are gaining share fastest.
Distribution Channel:
Customer type fragmentation separates price-sensitive spot buyers from volume-committed contract customers in channel selection.
- Direct Sales:Large feedlot operators and integrated protein processors negotiate long-term origination contracts with Pampas millers, bypassing intermediary markups. Western Buenos Aires grain belt drought risk has made price predictability more valuable than procurement flexibility.
- Distributors:Regional feed depots aggregate fragmented demand from mid-sized livestock operators across interior provinces, extending credit terms and technical support.
- Retailers:Farm supply cooperatives and agronomic centers serve smallholder poultry and swine producers with bagged product and formulation advice.
- Online Platforms:Digital procurement channels are emerging for standardized premix reorders among technically sophisticated operators with established SENASA-compliant suppliers.
Direct sales absorb the bulk of installed capacity; online platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Buenos Aires province grain belt anchors Argentine compound feed manufacturing through its Pampas silo networks and integrated processing corridors.
Buenos Aires Province
Climate-controlled poultry housing expansion in the western grain belt pulls pellet volumes through mechanized feeding systems. SENASA Resolution 710/2021 mandates dedicated medicated feed production lines, pushing large operators toward facility segregation. The Pergamino-Rojas corridor concentrates finishing feedlots with consolidated procurement contracts displacing spot-market grain buying.
Córdoba Province
Broiler intensification across the central region drives crumble demand for starter-to-grower transition protocols. The Secretariat of Agriculture monitors provincial grain reserves that alter quarterly input costs for domestic millers. The Marcos Juárez poultry cluster anchors climate-controlled housing investment with mechanized feeding system deployment.
Santa Fe Province
Portable near-infrared spectroscopy units enable real-time moisture calibration among mid-sized poultry operators. SENASA feed safety protocols tighten formulation standards for export-oriented operations. The Rafaela feed manufacturing corridor integrates quality control upstream, reducing rejection rates at feedlot intake points.
Entre Ríos Province
EU-bound beef certification requirements generate price premiums for phytogenic-enhanced rations in regional feedlots. The country's national agricultural regulator enforces veterinary residue standards that shape additive approval pathways. The Paraná River corridor concentrates large-scale finishing operations with environmental compliance coordination for effluent management.
Patagonian Provinces
Trout and shrimp producers in southern water systems generate specialized demand for high-protein extruded feeds with precise lipid profiles. Trace mineral bioavailability deficits across regional forage zones pull premix manufacturing closer to end-use. The Río Negro aquaculture cluster anchors localized production investment for specialty additive applications.
Argentina Compound Feed Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Argentine compound feed formulation and distribution. The market structure consolidates around integrated protein processors with captive slaughter capacity and independent millers serving fragmented livestock operators. Three archetypes dominate: grain-origination giants with upstream cost advantages, premix specialists addressing regional forage deficits, and integrated processors pulling feed volumes through protein platforms. Competitive intensity centers on long-term origination contracts and SENASA-compliant additive portfolios.
Among multinational agribusiness conglomerates, Cargill Inc and Archer Daniels Midland Company anchor the grain-origination tier with Pampas silo network access. Nutreco N.V. occupies a position within the premix specialization vector, while JBS S.A. exemplifies the integrated processor archetype leveraging captive protein platforms. These three entities represent distinct competitive vectors: upstream supply security, formulation expertise, and downstream demand capture.
| Leading Market Players |
|---|
| Land O'Lakes Inc (Purina Mills) |
| Nutreco N.V. |
| Archer Daniels Midland Company |
| Kemin Industries |
| DeKalb Feeds |
| United Animal Health |
| Cargill Inc |
| JBS S.A. |
| Alltech Inc |
| Others |
Value Chain & Pricing Dynamics
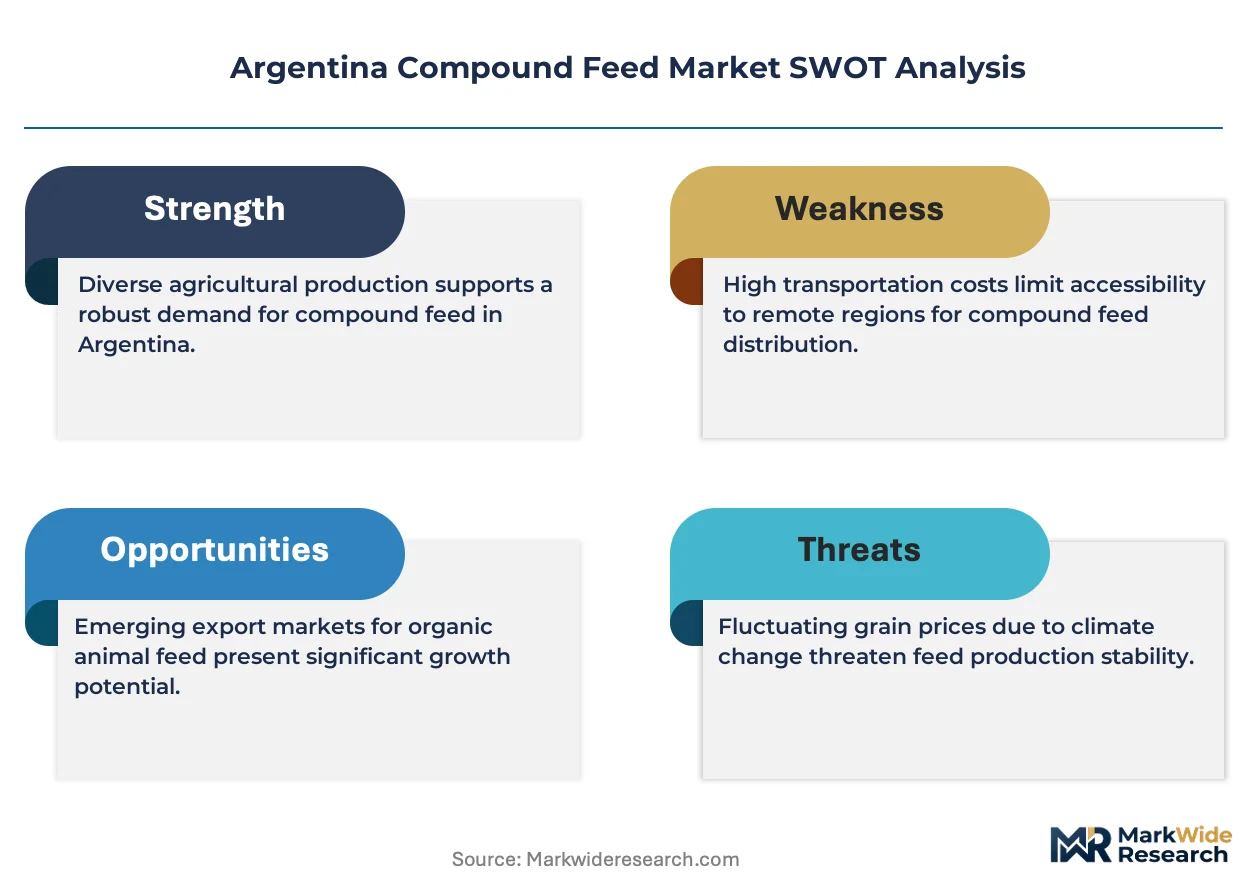
Pellet-to-mash conversion technology is simultaneously compressing per-unit feed costs and concentrating manufacturing capacity among integrated processors with steam-conditioning infrastructure. SENASA compliance investments and drought-driven grain export quotas are amplifying cost disparities between large operators and mid-sized millers across the Pampas grain belt.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as feedlot operators with consolidated contracts pay predictability margins above spot-market volatility. Contract-based long-term offtake structures separate integrated processors with captive slaughter capacity from price-sensitive independent formulators lacking volume guarantees. Price differentiation hinges on SENASA certification grade and geographic delivery cost to interior provinces. Margins are tightening due to formulation talent scarcity and dedicated line requirements under Resolution 710/2021.
Supply Chain Analysis
Workforce availability constraints in Buenos Aires and Córdoba manufacturing corridors are elevating automation investment thresholds for new capacity. Supply concentrates in Argentina's Pampas grain belt, with secondary dependencies on Brazilian soybean meal and Paraguayan corn during drought quota periods. Raw material sourcing rests on corn origination, soybean crushing, and specialized additive imports. Single-source vulnerability runs through SENASA-approved enzyme suppliers with 18-24 month approval timelines. Distribution runs through direct miller-to-feedlot contracts and regional depot networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as SENASA compliance costs and pellet line capex requirements force sub-scale operators toward exit or acquisition.
For Market Incumbents: Cement formulation expertise advantages by acquiring SENASA-certified premix specialists in Patagonia before regional localization investments mature. Lock in long-term corn origination contracts with Pampas silo networks to defend against drought-driven export quota volatility. Vertical integration into captive slaughter capacity insulates feed volume from independent feedlot procurement consolidation. For New Entrants and Emerging Players: Begin with crumble formulation niches serving Santa Fe broiler operators transitioning between starter mash and grower pellets. Target mid-sized poultry operators lacking in-house nutritionist capacity with technical support bundled into premix contracts. Deploy portable NIR spectroscopy services as a differentiated entry wedge before manufacturing scale commitments. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated protein platforms with captive feed demand and SENASA-compliant additive portfolios. Long-term viability favors operators with backward integration into grain origination and forward integration into slaughter capacity. Watch for drought-induced export quota expansions as inflection signals for input cost compression and independent miller distress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Secures corn-soybean supply security against Secretariat of Agriculture reserve policy shifts. |
| SENASA Certification Investment | Unlocks phytogenic additive formulation premiums for EU-bound beef export feedlots. |
| Pellet Line Capacity Expansion | Captures mechanized feeding system growth in Córdoba and Santa Fe climate-controlled housing. |
| Regional Premix Localization | Addresses trace mineral deficits in Patagonian forage zones with shortened delivery lead times. |
| Antibiotic-Free Protocol Development | Aligns with Resolution 710/2021 dedicated line mandates while simplifying compliance architecture. |
Study Parameters
Document review covered SENASA regulatory filings, Argentine Secretariat of Agriculture grain reserve policies, and industry trade association data, complemented by interviews with feed mill operations directors, veterinary nutritionists, poultry farm managers, and grain origination traders. Secondary validation drew from customs export records, feed manufacturing capacity databases, and provincial environmental compliance registries. Bottom-up volume estimates triangulated against top-down expenditure flows across species-specific formulation categories.
Segmented projections across product type, end user, physical form, and distribution channel dimensions generated value trajectories over the projection horizon. CAGRs emerged from historical volume elasticity analysis against livestock inventory cycles and input cost volatility patterns. Forecast inputs incorporated drought frequency modeling and SENASA approval pipeline timelines for novel additive categories.
Underlying measurement precision varies by segment; poultry and swine formulations carry tighter precision than aquaculture specialty feeds due to inventory reporting density. Forecasts reflect assumptions about grain reserve policy continuity and SENASA regulatory enforcement intensity. Material deviation in drought severity or export quota expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Mushroom Cultivation Market
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
UAE Agriculture Market
Agriculture and Agri Products
Global Ruminant Feed Market
Agriculture and Agri Products
Henequen Market
Agriculture and Agri Products
Aquatic Feed Ingredients and Products Market
Agriculture and Agri Products
Cameroon Agriculture Market
Agriculture and Agri Products
Global Warm Water Aquaculture Feed Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
Africa Poultry Feed Market
Agriculture and Agri Products
Tarragon Market
Agriculture and Agri Products
Global Guayusa Market
Agriculture and Agri Products
Marine Algae Market
Agriculture and Agri Products
Fermented Soybean Meal Protein for Animal Feed Market
Agriculture and Agri Products
Vietnam Shrimp Feed Market