
 North America Shiitake Mushroom Market | 2026-2036
North America Shiitake Mushroom Market Size, Share, and Industry Trends Forecast 2026-2036
North America Shiitake Mushroom Market Analytics
USDA Organic certification is reorganizing competitive access across the North America Shiitake Mushroom Market, raising barriers for smaller growers who lack the three-year transition period and documentation systems required. Giorgio Fresh Co. leverages its Pennsylvania-based growing infrastructure to sustain year-round fresh supply to East Coast retail chains. Monterey Mushrooms anchors the market through integrated spawn-to-shelf operations across multiple US states. Phillips Mushroom Farms differentiates via specialized organic blocks and controlled-environment agriculture techniques.
Shiitake mushrooms are wood-decaying basidiomycetes cultivated on hardwood sawdust substrates or natural logs, requiring precise humidity of 85-90% and temperature cycles between 10-20°C for primordia formation and fruiting body development; they serve commercial markets as whole fresh produce, processed ingredients, and bioactive extract sources for functional food applications. Fresh Shiitake dominates retail value capture due to perishability-driven premium positioning and short supply chains, while Shiitake Extract occupies the fastest-expanding margin pool as supplement manufacturers seek standardized polysaccharide content for immune health positioning. Dried Shiitake sustains stable volume through Asian grocery networks and food service rehydration workflows, with Wholesale channels controlling the majority of institutional flow to restaurants and food manufacturers.
The US Food and Drug Administration oversees dietary supplement labeling claims for Shiitake Extract products under DSHEA, while the USDA National Organic Program governs cultivation input restrictions and handler certification across US production zones; Canada's CFIA enforces Safe Food for Canadians Regulations that mandate preventive control plans for mushroom operations. California's Proposition 65 warning requirements and evolving state-level mycotoxin testing protocols add compliance layers for extract suppliers targeting West Coast distribution. Stakeholders must monitor whether emerging beta-glucan quantification standards and adaptogen classification debates reshape product positioning and reimbursement pathways for supplement applications.
Market Dynamics
USDA Organic certification requirements and FSMA traceability mandates are compressing grower margins while favoring operations with capital reserves for compliance infrastructure. This regulatory tightening is accelerating consolidation across the North American cultivation base.
Growth Catalysts
- Pacific Northwest Climate Infrastructure:Year-round cultivation capacity in Oregon, Washington, and British Columbia supports consistent fresh supply to West Coast retail chains without seasonal import dependency.
- DSHEA Supplement Positioning:Standardized polysaccharide extraction protocols enable immune-health marketing claims that capture premium pricing in functional food channels.
- Hardwood Sawdust Substrate Innovation:Controlled-environment agriculture techniques using optimized lignocellulosic blends reduce fruiting cycle duration and improve yield consistency.
Market Restraints
- Three-Year Organic Transition:The USDA National Organic Program mandates a 36-month land-history documentation period that locks out conventional growers from premium price tiers.
- Spawn Supply Concentration:Domestic spawn production clusters in Pennsylvania and California, creating geographic vulnerability for growers outside these zones.
- Perishability Economics:Fresh Shiitake shelf life constraints below 14 days force cold-chain investments that exclude small-scale operators from retail distribution.
Strategic Opportunities
- Canadian Prairie Expansion:Manitoba and Alberta greenhouse infrastructure repurposing offers untapped year-round production capacity with proximity to Asian grocery networks in Calgary and Winnipeg.
- Proposition 65 Compliance Services:California's warning-label requirements for mycotoxin content create advisory and testing revenue streams for laboratories serving extract suppliers.
- Direct-to-Consumer Subscription:Farm-box channels bypass wholesale margin compression while capturing household demand for medicinal mushroom cooking ingredients.
Industry Challenges
- Spawn Culture Expertise Gap:Mycelium propagation requires specialized laboratory technicians that agricultural labor pools in the US and Canada rarely supply.
- FSMA Preventive Control Documentation:The FDA's hazard analysis requirements demand record-keeping systems that many family-scale growers lack capital to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Shiitake Mushroom Market |
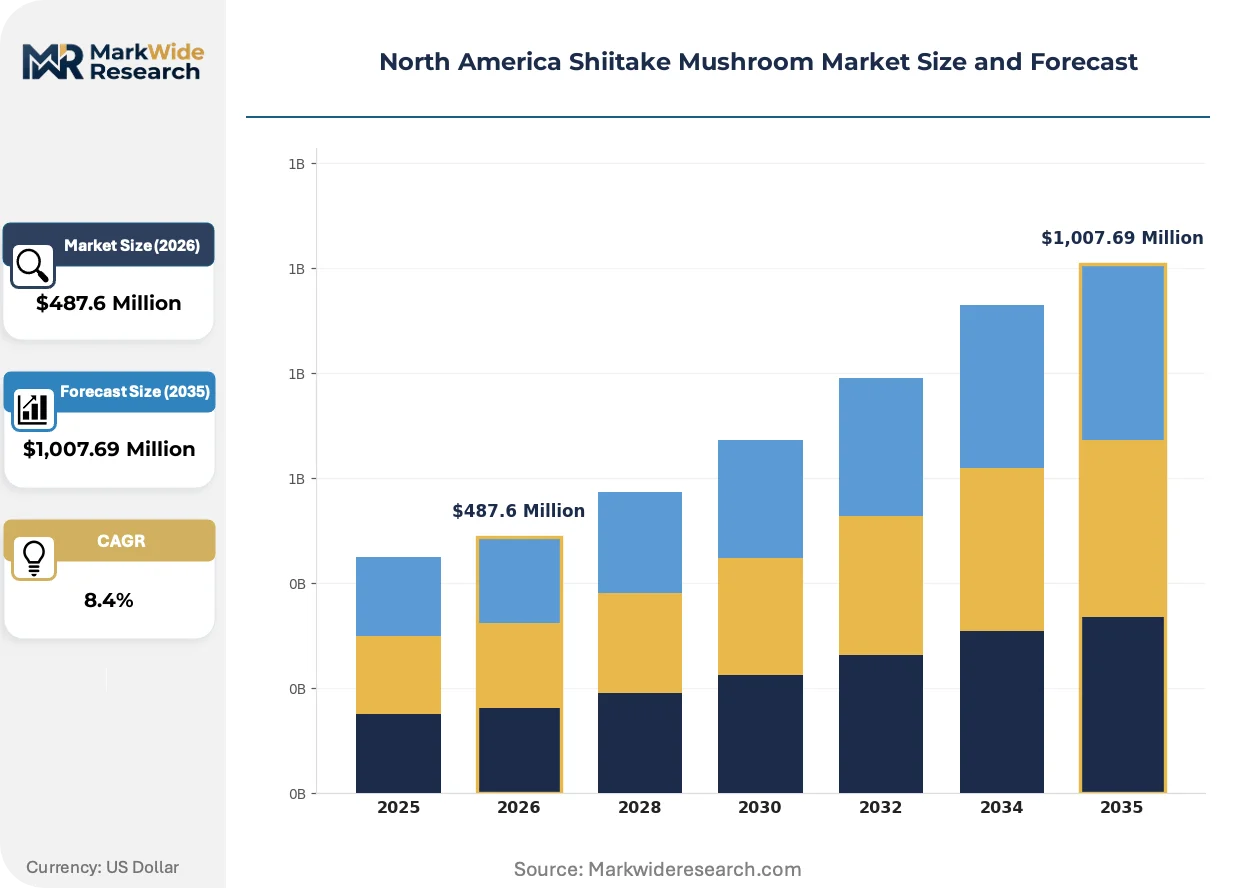
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,007.69 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Shiitake, Dried Shiitake, Shiitake Extract, Shiitake Powder Application: Culinary, Supplements, Pharmaceuticals, Animal Feed Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Households, Restaurants, Health Food Stores, Food Manufacturers |
| Companies Covered | Giorgio Fresh Co., South Mill Mushrooms Sales, Inc., Monterey Mushrooms, Inc., Bonduelle Group, Highline Mushrooms, Phillips Mushroom Farms, Hirano Mushroom LLC, Enviro Mushroom Farm, Nammex, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Shiitake Mushroom Market Evolving Landscape
Automation in climate-controlled fruiting rooms and blockchain-enabled batch tracking are reconfiguring how Shiitake moves from substrate to shelf. These shifts are compressing traditional grower-wholesaler relationships.
Automated humidity and CO2 sensing systems with IoT-enabled environmental controls are fragmenting the competitive map between large integrated operations and mid-scale specialized growers. Supplement manufacturers seeking standardized beta-glucan content are adopting these precision-agriculture outputs fastest. The technology is fragmenting procurement patterns as buyers bypass commodity brokers to contract directly with instrumented farms.
The FDA's evolving enforcement posture on DSHEA structure-function claims is tightening label substantiation requirements for Shiitake Extract products. Manufacturers now face warning-letter risk for immune-modulation language without clinical trial backing. West Coast supplement brands are responding by relocating quality-assurance functions to in-house regulatory counsel rather than outsourced consultants.
Food service distributors are unbundling fresh mushroom procurement from broadline contracts to source directly from regional greenhouse clusters. Independent restaurants in Vancouver and San Francisco are replacing Sysco-dependent ordering with twice-weekly farm delivery. This disintermediation is most visible in the Pacific Northwest, where local sourcing credentials command menu-premium pricing.
North America Shiitake Mushroom Market Segmentation
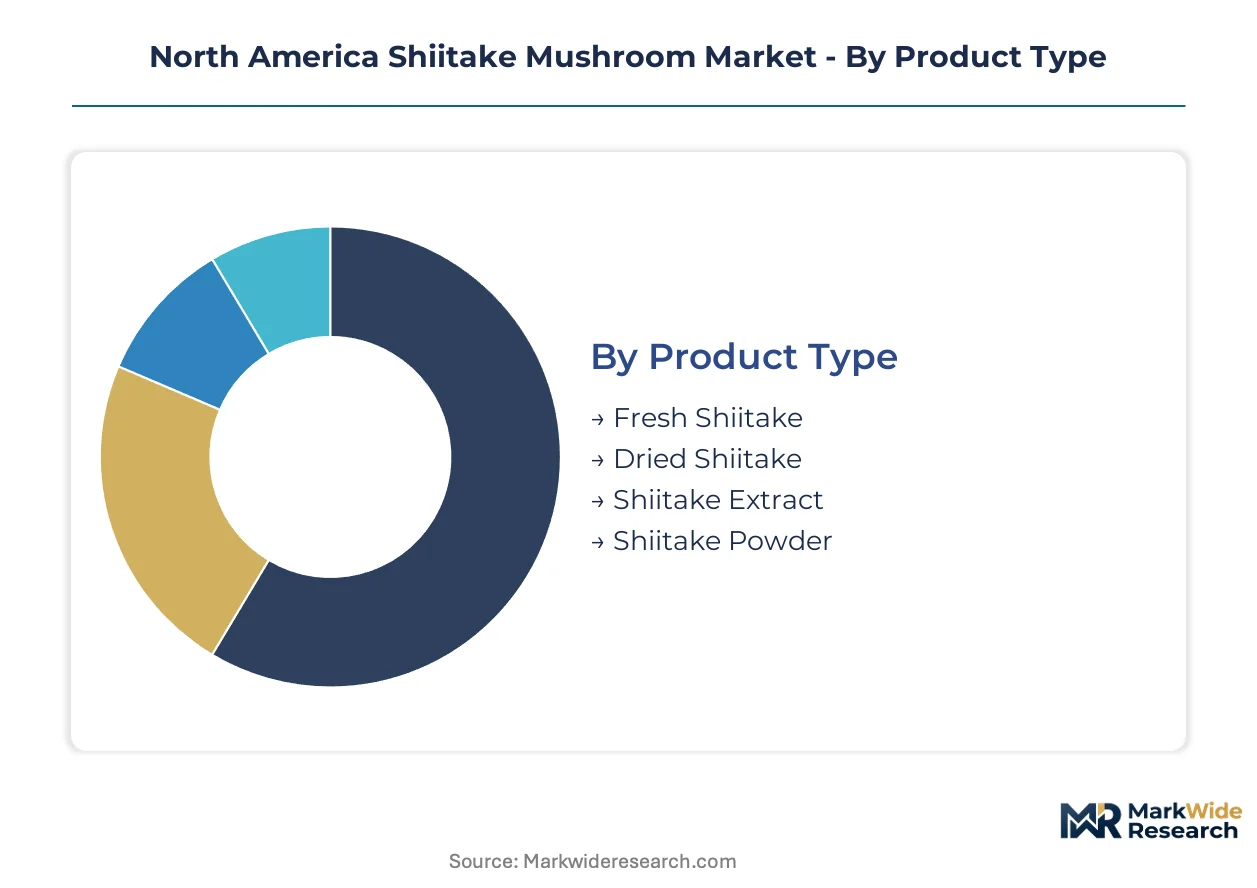
Shiitake mushroom value capture splits sharply across preservation state and extraction depth, with regulatory treatment varying by end-use pathway. Understanding these segment boundaries clarifies where USDA Organic premiums apply versus where FDA DSHEA compliance dominates margin structures.
Product Type:
USDA Organic certification requirements and FDA supplement labeling rules create divergent compliance burdens across preservation formats.
- Fresh Shiitake:Whole fruiting bodies with 10-14 day shelf life under refrigerated conditions. Pacific Northwest greenhouse clusters supply West Coast retail chains demanding local provenance credentials. Cold-chain investments and perishability economics concentrate volume among integrated operations with direct store delivery contracts.
- Shiitake Extract:Standardized polysaccharide concentrates, typically beta-glucan quantified, positioned for immune-health supplement applications. California's Proposition 65 mycotoxin warning requirements add testing layers for West Coast distribution. DSHEA structure-function claim substantiation demands clinical documentation that smaller suppliers struggle to assemble.
- Dried Shiitake:Dehydrated whole caps or slices with 12-24 month stability, rehydrated for food service and home cooking. Asian grocery networks in Vancouver, Toronto, and Los Angeles sustain consistent volume.
- Shiitake Powder:Milled fruiting body material for functional food fortification and encapsulation feedstock. Beverage manufacturers and protein blenders in Colorado and Oregon represent primary offtake.
Fresh Shiitake handles the majority of throughput; Shiitake Extract is expanding most quickly on share.
Application:
End-use concentration determines which regulatory gatekeeper—USDA, FDA, or CFIA—exerts primary compliance pressure.
- Culinary:Whole and processed mushrooms for restaurant menus, retail meal kits, and home preparation. Vancouver and San Francisco independent restaurants source directly from regional greenhouse clusters, bypassing broadline distributors.
- Supplements:Capsules, tinctures, and functional foods with standardized bioactive content. FDA warning-letter risk for unsubstantiated immune-modulation claims is tightening label language and relocating quality assurance to in-house regulatory counsel.
- Pharmaceuticals:Investigational and approved drug applications leveraging lentinan and other isolated compounds. Clinical trial documentation requirements limit participation to well-capitalized extract suppliers with dedicated regulatory staff.
- Animal Feed:Myceliated substrate and fruiting body meal for poultry and aquaculture gut health applications. Canadian Prairie feed mills trial shiitake-fortified rations for antibiotic reduction positioning.
Culinary absorbs the largest volume base; Supplements is climbing the fastest on margin contribution.
Distribution Channel:
Channel selection reflects buyer scale, certification requirements, and cold-chain capability.
- Wholesale:Institutional procurement for restaurants, food manufacturers, and supplement formulators. Sysco and UNFI broadline contracts are fragmenting as Pacific Northwest buyers unbundle mushroom procurement for direct regional sourcing.
- Supermarkets:Conventional and natural grocery retail with dedicated produce and supplement aisle placement. USDA Organic certification unlocks shelf space in Whole Foods and regional co-op chains.
- Specialty Stores:Health food retailers, Asian grocers, and farmers market direct sales. British Columbia and Oregon independents emphasize local cultivation provenance.
- Online Retail:Direct-to-consumer subscriptions, Amazon storefronts, and supplement brand e-commerce. Farm-box channels bypass wholesale margin compression for household medicinal mushroom demand.
Wholesale moves the greatest tonnage; Online Retail is gaining share fastest on household penetration.
End User:
User type dictates packaging format, certification messaging, and supply chain length.
- Restaurants:Fresh and dried formats for menu integration, with Vancouver and San Francisco independents paying premiums for twice-weekly farm delivery and local sourcing credentials.
- Food Manufacturers:Bulk dried, powder, and extract inputs for soup bases, sauces, and functional food formulations. Processed ingredient specifications require batch consistency that favors integrated spawn-to-shelf operations.
- Households:Retail-packaged fresh, dried, and supplement formats for home cooking and wellness routines. Subscription models in Pacific Coast metropolitan areas reduce price sensitivity through convenience positioning.
- Health Food Stores:Supplement and specialty dried formats with staff-trained consultative selling. Staff education requirements favor suppliers providing third-party lab results and cultivation transparency.
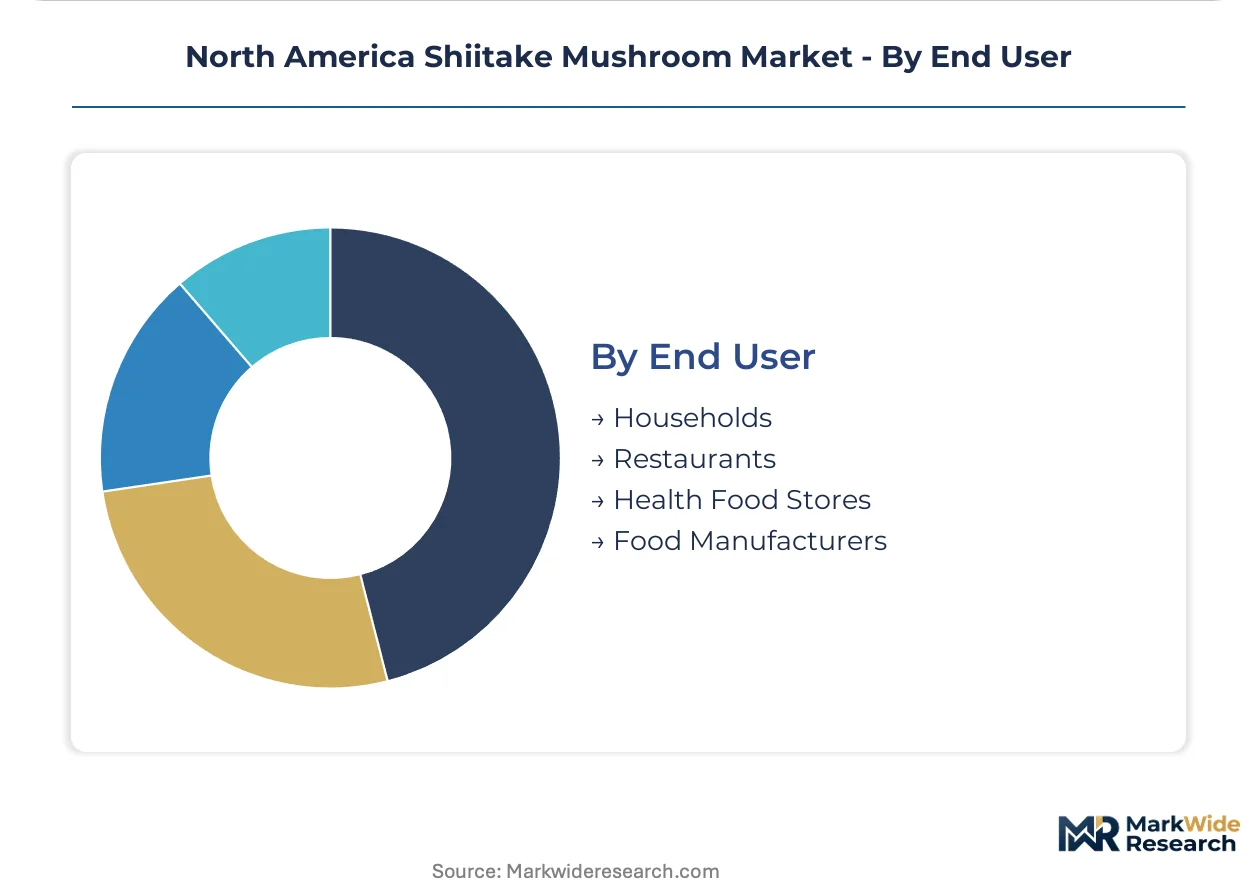
Restaurants command the highest fresh volume; Food Manufacturers is the steepest expansion trajectory on extract offtake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty retailers and health food chains concentrate demand across North America, with institutional buyers and direct-to-consumer subscription services fragmenting traditional wholesale channels. The USDA Organic certification tier and FDA DSHEA compliance requirements reshape procurement patterns differently across sub-regions.
United States
Pacific Northwest greenhouse clusters and Pennsylvania-based growing infrastructure anchor fresh supply to West Coast and East Coast retail chains respectively. The FDA's FSMA preventive control mandates and California's Proposition 65 mycotoxin warning requirements layer compliance costs on extract suppliers targeting distribution west of the Rockies. Oregon and Washington year-round cultivation capacity eliminates seasonal import dependency for Seattle and San Francisco metropolitan buyers.
Canada
British Columbia climate infrastructure supports consistent fresh production serving Vancouver's Asian grocery networks and independent restaurant direct sourcing. The CFIA Safe Food for Canadians Regulations mandate preventive control plans that favor capitalized operations over family-scale growers. Alberta and Manitoba greenhouse repurposing offers untapped expansion capacity with proximity to Calgary and Winnipeg ethnic food retail corridors.
Mexico
Central Mexican highland regions develop cultivation capacity targeting US border-crossing fresh produce logistics and domestic culinary demand in Mexico City and Guadalajara. The country's federal sanitary regulator enforces Good Agricultural Practice protocols that align with USDA import requirements for organic product entry. Michoacán and Estado de México clusters concentrate substrate preparation and spawn distribution infrastructure.
North America Shiitake Mushroom Market Competitive Landscape
Player mix skews toward integrated spawn-to-shelf operators and regional fresh specialists with direct retail contracts. The competitive map fragments across three tiers: large multi-state greenhouse networks controlling broadline distribution, mid-scale organic-certified farms capturing specialty retail premiums, and extract-focused suppliers serving supplement manufacturers. Dominant competitive moves include FSMA-compliant cold-chain infrastructure investment and USDA Organic certification acquisition to unlock Whole Foods and regional co-op shelf space.
Within the integrated multi-state tier, Monterey Mushrooms anchors scale-driven supply to national retail chains, while Giorgio Fresh Co. represents the Pennsylvania-based East Coast concentration. Phillips Mushroom Farms occupies the specialized organic and controlled-environment agriculture position. These three structures exemplify how capital reserves for compliance infrastructure separate sustainable operations from margin-compressed conventional growers.
| Leading Market Players |
|---|
| Giorgio Fresh Co. |
| South Mill Mushrooms Sales, Inc. |
| Monterey Mushrooms, Inc. |
| Bonduelle Group |
| Highline Mushrooms |
| Phillips Mushroom Farms |
| Hirano Mushroom LLC |
| Enviro Mushroom Farm |
| Nammex |
| Others |
Value Network & Pricing Analysis
Year-round greenhouse capacity utilization in the Pacific Northwest and British Columbia anchors price floors by eliminating seasonal import dependency that otherwise spikes spot pricing. This scale concentration compresses margins for smaller operators while rewarding integrated spawn-to-shelf networks with volume-negotiated offtake contracts and direct retail shelf access.
Pricing Analysis
Cost-plus contracts with hardwood sawdust indexation dominate fresh Shiitake procurement between Pacific Northwest greenhouse clusters and West Coast retail chains. Three-tier pricing structure across USDA Organic certified, conventional fresh, and dried commodity tiers separates premium positioning from standard produce and economy-grade Asian grocery supply. Pricing pressure stems from FSMA compliance cost pass-through demands that smaller growers cannot absorb. Household subscribers through farm-box channels exhibit lowest price sensitivity, while broadline food service distributors face acute margin compression.
Supply Chain Analysis
Just-in-time delivery preferences among Vancouver and San Francisco independent restaurants are displacing strategic stockpiling that once sustained Sysco-dependent procurement patterns. Spawn supply concentrates in Pennsylvania and California, with fruiting operations distributed across Oregon, Washington, British Columbia, and emerging Mexican highland clusters. Raw material dependencies include hardwood sawdust substrates, climate-control equipment, and laboratory-grade spawn cultures. Single-source vulnerability in domestic spawn production creates geographic risk for growers outside Pennsylvania and California zones. Distribution runs through direct farm-to-restaurant relationships in the Pacific Northwest and wholesale broadline contracts elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern tied to health food retail expansion cycles, with functional mushroom positioning now entering its third upswing following prior waves in the 1990s and 2010s.
For Market Incumbents: Shield organic certification premiums by accelerating FSMA-compliant cold-chain investments that smaller competitors cannot finance. Deepen backward integration into spawn production to reduce Pennsylvania and California supply concentration risk. Prioritize direct store delivery contracts with Whole Foods and regional co-op chains over broadline distributor relationships.
For New Entrants and Emerging Players: Subscription fulfillment infrastructure gaps in the Prairie provinces present immediate white-space opportunity, with Calgary and Winnipeg Asian grocery networks underserved by year-round fresh supply. Canadian Prairie greenhouse repurposing offers lowest competitive density for organic-certified entry. Target direct-to-consumer farm-box positioning with medicinal mushroom cooking education to bypass wholesale margin compression.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated spawn-to-shelf operators with established supplement extract offtake agreements. Five-to-ten year viability favors mid-scale organic-certified farms with laboratory capabilities rather than commodity fresh specialists. Monitor beta-glucan quantification standard adoption as inflection signal for extract supplier margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| USDA Organic Certification Acquisition | Unlocks Whole Foods and regional co-op shelf space with premium positioning. |
| Spawn Production Backward Integration | Reduces geographic vulnerability to Pennsylvania and California supply concentration. |
| Direct-to-Consumer Subscription Launch | Bypasses wholesale margin compression while capturing household medicinal demand. |
| FSMA Preventive Control Infrastructure | Enables retail chain compliance that excludes family-scale competitors. |
| Canadian Prairie Greenhouse Expansion | Captures untapped year-round capacity near Calgary and Winnipeg ethnic retail corridors. |
Research Methodology
Desk research of USDA National Organic Program certification databases, FDA warning letter archives, and CFIA preventive control guidance documents preceded structured interviews with mushroom cultivation operations managers, supplement manufacturer procurement leads, health food store category buyers, and cold-chain logistics coordinators. Secondary validation drew from agricultural trade association publications, hardwood substrate supply reports, and retail produce audit data. Bottom-up volume estimates triangulated against top-down value projections.
Variance decomposition across product type, application, distribution channel, and end user dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segmented growth rate blending with cross-elasticity adjustments for substitution between fresh, dried, and extract formats. Forecast inputs incorporated climate infrastructure utilization rates and DSHEA enforcement posture evolution.
Underlying assumptions cover sustained health food retail expansion and stable hardwood substrate supply, with deviation risk concentrated in FDA supplement claim enforcement intensity and organic certification backlog processing. Revision becomes warranted when beta-glucan standardization adoption crosses threshold penetration in supplement manufacturer procurement specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Asia-Pacific Chaga Mushroom Market
Agriculture and Agri Products
India Compound Feed Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
South America Animal Protein Market
Agriculture and Agri Products
Aquatic Feed Ingredients and Products Market
Agriculture and Agri Products
Ginseng Market
Agriculture and Agri Products
Australia Organic Farming Market
Agriculture and Agri Products
Pure Plant Oil Market
Agriculture and Agri Products
Asia-Pacific Animal Protein Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Algeria Agriculture Market
Agriculture and Agri Products
Australia Compound Feed Market
Agriculture and Agri Products
Swine Feed Premix Market
Agriculture and Agri Products
China Compound Feed Market
Agriculture and Agri Products
Africa Olive Market