
 Okara Market | 2026-2036
Okara Market Size, Share, and Industry Trends Forecast 2026-2036
Okara Market Analytics
Subscription-based ingredient supply programs is realigning how okara processors contract with food manufacturers. House Foods Group Inc. leverages captive tofu production across Japan to secure consistent okara volumes for ingredient extraction. Kikkoman Corporation anchors its position through fermentation expertise that extends into soy-derived byproduct valorization. Pulmuone Co. Ltd. competes in North American markets with vertically controlled okara sourcing from its Illinois plant.
Okara denotes the insoluble fibrous residue remaining after soy milk extraction, typically containing 25% protein and 50% dietary fiber on a dry basis, which food processors repurpose into flour, meat analogs, and baked goods. The product type dimension shows milk and yogurt applications dominating current volume while cheese alternatives capture expanding margin pools in specialty retail. Distribution through direct sales channels to bakeries and snack manufacturers sustains premium pricing, whereas retail store penetration remains concentrated in urban Japanese and Korean markets.
Japan's Ministry of Agriculture, Forestry and Fisheries (MAFF) and South Korea's Ministry of Food and Drug Safety (MFDS) enforce compositional standards for upcycled food ingredients that determine which okara-derived products qualify for clean-label positioning. The European Food Safety Authority (EFSA) evaluates novel food applications for okara protein isolates under consolidated EU frameworks, creating compliance thresholds for Asian exporters. Stakeholders must monitor how divergence in national upcycling certifications reshapes cross-border ingredient trade routes.
Market Dynamics
Upcycling mandates embedded in the European Commission's Farm to Fork Strategy are compressing timeframes for okara processors to certify supply chains, forcing capital reallocation toward traceability infrastructure before premium market access closes.
Growth Catalysts
- EU sustainability disclosure rules:The Farm to Fork Strategy mandates granular reporting on upcycled ingredient provenance, compelling food manufacturers to source certified okara derivatives and locking in demand for compliant processors.
- Plant-based dairy expansion:Japan, South Korea, and Taiwan are absorbing rising volumes of okara-derived ingredients as milk and yogurt alternatives capture shelf space in urban retail.
- Captive feedstock clustering:Tofu and soy milk manufacturers concentrate in Japan's Kanto region around Tokyo and Saitama, generating predictable okara supply for downstream ingredient extraction.
Market Restraints
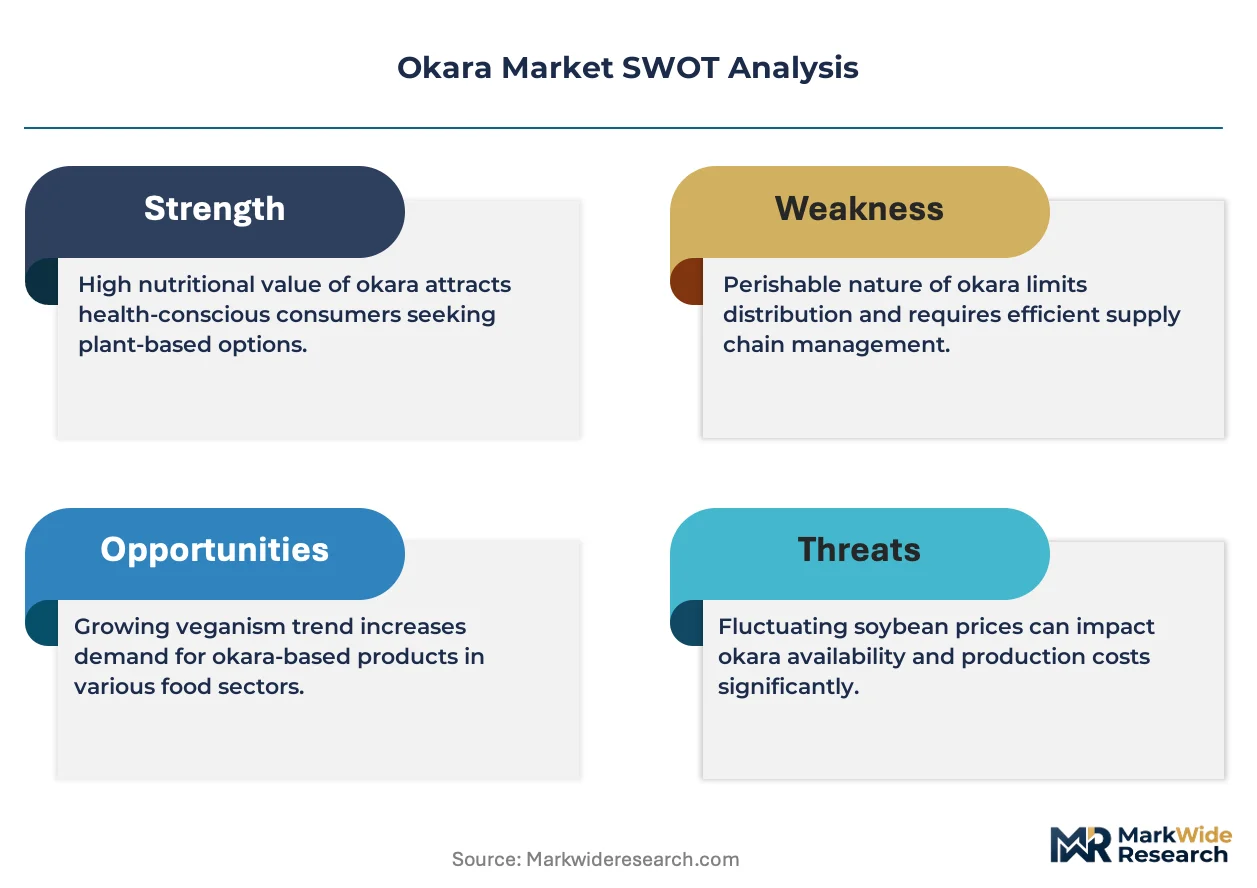
- Input cost volatility:Soybean price fluctuations transmit directly to okara economics, squeezing processor margins when commodity markets spike.
- Supply concentration risk:Japan's Kanto region dominates captive okara generation, creating geographic vulnerability if logistics disruptions isolate Tokyo-Saitama production clusters.
- Novel food approval friction:EFSA evaluation timelines for okara protein isolates extend commercialization horizons, delaying EU market entry for Asian exporters.
Strategic Opportunities
- Cheese alternative white space:Specialty retail channels in Japan and South Korea are absorbing premium-positioned okara-based cheese analogs, capturing expanding margin pools beyond commoditized milk applications.
- Direct-to-bakery channels:Bakeries and snack manufacturers are bypassing traditional distribution tiers, enabling okara flour processors to command premium pricing through relationship-based supply contracts.
- Cross-border certification harmonization:Divergence between Japan's MAFF standards and South Korea's MFDS compositional rules creates arbitrage potential for processors mastering multi-jurisdictional compliance.
Industry Challenges
- Clean-label certification timelines:MAFF and MFDS upcycled ingredient qualifications require extensive documentation, stretching product development cycles and delaying revenue recognition.
- Legacy equipment retrofitting:Traditional soy processing infrastructure lacks extraction efficiency for high-protein isolate recovery, demanding capital-intensive line upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Okara Market |
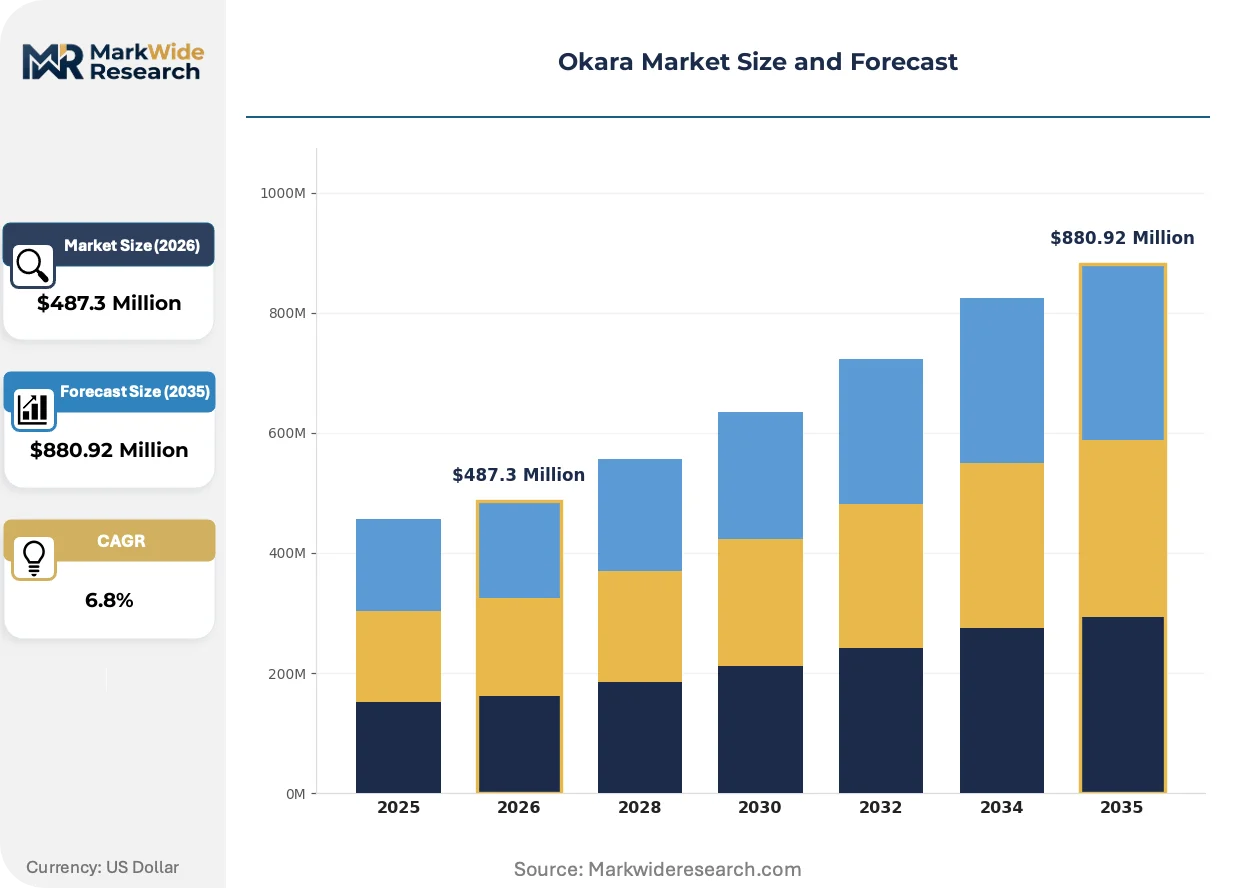
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Yogurt, Cheese, Butter Distribution Channel: Retail Stores, Wholesalers, Online, Direct Sales Customer Type: Households, Restaurants, Cafes, Bakeries End Use: Culinary, Beverage Production, Snack Industry, Desserts |
| Companies Covered | House Foods Group Inc., Kikkoman Corporation, Morinaga Nutritional Foods Inc., Vitasoy International Holdings Ltd., Pulmuone Co. Ltd., Fuji Oil Holdings Inc., Meiji Tofu Co., Marusan Ai Co. Ltd., Sunrise Soya Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Okara Market Evolving Landscape
Processing technology diffusion is redrawing competitive boundaries between centralized soy manufacturers and specialized ingredient refiners, while regulatory fragmentation across Japan, South Korea, and the EU forces multi-track compliance investment.
Enzymatic protein extraction is decentralizing okara valorization economics. Small-scale processors in Japan's Kanto region are deploying cellulase and protease systems to recover 25% protein fractions from fibrous residue. Bakeries and meat analog producers are absorbing these isolates at contract premiums, compressing the historical advantage of large tofu manufacturers who previously monopolized downstream ingredient streams.
REACH-aligned chemical safety assessments are reshaping EU import protocols for Asian okara derivatives. EFSA novel food categorization requires toxicological dossiers that extend approval timelines by 18-24 months. Japanese exporters targeting European cheese alternative manufacturers are front-loading regulatory investment, building dedicated compliance teams to navigate consolidated EU frameworks ahead of market entry deadlines.
Subscription contracting is displacing spot purchasing in bakery and snack manufacturing procurement. Japanese processors are locking 12-18 month supply agreements with Kanto-region bakeries, guaranteeing volume commitments that justify dedicated extraction line investment. South Korean snack conglomerates are replicating this model, shifting from commodity auction platforms to relationship-based ingredient partnerships that prioritize traceability over price minimization.
Okara Market Segmentation

Okara ingredient flows fragment across four distinct categorization schemes. Each dimension reveals divergent margin structures and compliance burdens that processors must navigate simultaneously.
Product Type:
Customization intensity spans from standardized commodity formats to highly specified analogs requiring novel food dossiers.
- Milk:Standardized okara protein isolates blend into fluid milk alternatives at 3-5% inclusion rates. Japanese and South Korean retail channels absorb the largest volumes as shelf-stable soy milk derivatives compete on price parity with oat and almond bases.
- Cheese:Fermentation-modified okara proteins create stretch and melt characteristics through enzymatic treatment. Specialty retailers in Japan's urban centers pay premium contract rates for analogs meeting MAFF clean-label thresholds, capturing margin pools unavailable to commoditized milk applications.
- Yogurt:Cultured okara fiber adds texture to plant-based fermented products.
- Butter:Fractionated okara lipids function as shortening agents in commercial baking.
Most installed capacity flows through milk. Expansion is steepest in cheese.
Distribution Channel:
Channel selection determines traceability investment requirements and working capital intensity.
- Direct Sales:Relationship-based contracts with Kanto-region bakeries and snack manufacturers bypass distributor markups. Japanese processors lock 12-18 month supply agreements guaranteeing volume commitments that justify dedicated extraction line investment.
- Retail Stores:Urban Japanese and Korean supermarkets concentrate okara-based product placement in premium aisles. EFSA novel food categorization extends EU retail entry timelines, compressing near-term margin realization for Asian exporters targeting European shelves.
- Wholesalers:Commodity-grade okara flour moves through foodservice distribution networks.
- Online:Direct-to-consumer channels serve niche dietary segments seeking specialty analogs.
Direct sales channels command the highest unit economics. Retail penetration is climbing fastest in South Korean urban markets.
Customer Type:
Customer sophistication ranges from price-sensitive foodservice operators to specification-driven manufacturers.
- Bakeries:Okara flour replaces wheat at 15-30% inclusion rates in high-fiber bread formulations. Kanto-region artisan bakeries source through subscription programs that prioritize consistent protein content over spot-market price minimization.
- Restaurants:Plant-based menu development drives okara protein demand in meat analog applications.
- Households:Retail-packaged okara ingredients serve home cooking and specialty diet segments.
- Cafes:Beverage-focused outlets incorporate okara into blended drinks and alternative milk offerings.
Bakeries absorb the most technically specified volumes. Restaurant procurement is expanding most quickly as plant-based menu mandates proliferate.
End Use:
End-use applications stratify by processing complexity and regulatory scrutiny intensity.
- Snack Industry:Extruded okara fiber creates texturized protein crisps and puffed formulations. South Korean snack conglomerates are shifting from commodity auction platforms to relationship-based ingredient partnerships that prioritize traceability documentation.
- Culinary:Fresh okara pulp serves traditional Japanese and Korean cuisine applications requiring minimal processing.
- Beverage Production:Fine-milled okara integrates into smoothie and functional drink bases.
- Desserts:Okara protein isolates replace dairy in mousse and custard formulations.
Snack industry offtake dominates volume flows. Dessert applications are gaining share fastest as premium positioning strategies mature.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting okara processing capacity toward jurisdictions with streamlined upcycling certification pathways. Processors in South Korea and Taiwan are capturing contract flows that Japan's lengthier MAFF documentation timelines have diverted.
Japan
Kanto-region tofu manufacturers around Tokyo and Saitama generate captive okara feedstock for downstream ingredient extraction. MAFF compositional standards for upcycled food ingredients determine clean-label qualification thresholds. Enzymatic protein extraction systems are decentralizing valorization economics as small-scale processors recover isolates for bakery and meat analog contracts.
South Korea
Snack conglomerates are absorbing rising volumes of okara-derived ingredients for extruded protein crisps and puffed formulations. MFDS enforces compositional standards that diverge from Japanese MAFF rules, creating compliance arbitrage for multi-jurisdictional processors. Seoul-based ingredient refiners are locking 12-18 month supply agreements that prioritize traceability documentation over spot-market pricing.
Taiwan
Plant-based dairy alternatives are capturing urban retail shelf space with okara protein isolates blended at 3-5% inclusion rates. The national food safety regulator evaluates upcycled ingredient applications under frameworks that compress approval timelines relative to Japanese counterparts. Tainan and Kaohsiung processing clusters are expanding extraction capacity to serve cross-strait bakery and beverage manufacturing demand.
United States
Pulmuone's Illinois facility anchors vertically controlled okara sourcing for North American plant-based dairy expansion. FDA GRAS determinations for soy-derived byproducts create a distinct regulatory pathway from EU novel food categorization. Chicago-area food ingredient distributors are building dedicated logistics for okara flour moving to artisan bakeries in the Midwest and Northeast corridors.
Germany
EFSA novel food evaluation timelines for okara protein isolates extend commercialization horizons for Asian exporters targeting European cheese alternative manufacturers. REACH-aligned chemical safety assessments are reshaping import protocols and demanding toxicological dossiers. Hamburg and Rotterdam port logistics clusters are developing specialized cold-chain handling for upcycled ingredient shipments from East Asian processors.
Okara Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. House Foods Group and Kikkoman anchor the Japanese market through captive tofu production and fermentation expertise respectively, while North American penetration depends on Pulmuone's vertically controlled Illinois supply base. Three archetypes dominate: integrated soy processors with captive feedstock, specialized ingredient refiners deploying enzymatic extraction, and cross-border traders arbitraging regulatory divergence. Competitive moves concentrate on certification infrastructure investment and subscription-based contracting to lock bakery and snack manufacturing demand.
Among Japan-based integrated processors, House Foods Group Inc., Kikkoman Corporation, and Marusan Ai Co. Ltd. exemplify the captive-feedstock archetype, leveraging in-house tofu production to secure consistent okara volumes for downstream ingredient streams. Pulmuone Co. Ltd. occupies a distinct position as a Korea-origin multinational with North American manufacturing footprint, representing the geographic-arbitrage specialist tier that navigates divergent MAFF, MFDS, and FDA compliance frameworks simultaneously.
| Leading Market Players |
|---|
| House Foods Group Inc. |
| Kikkoman Corporation |
| Morinaga Nutritional Foods Inc. |
| Vitasoy International Holdings Ltd. |
| Pulmuone Co. Ltd. |
| Fuji Oil Holdings Inc. |
| Meiji Tofu Co. |
| Marusan Ai Co. Ltd. |
| Sunrise Soya Foods |
| Others |
Value Network & Pricing Analysis
Family-owned tofu manufacturers across Japan's Kanto region anchor supply-side discipline through captive okara generation, translating predictable feedstock access into stable contract pricing for downstream ingredient processors while insulating premium tiers from commodity soybean volatility.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for okara protein isolates as enzymatic extraction systems proliferate among mid-scale processors. Contract-based long-term offtake dominates, with subscription programs locking 12-18 month volume commitments from Kanto-region bakeries. Price differentiation rests on MAFF clean-label certification tier and protein recovery efficiency, not spot-market swings. Cost compression in standard-grade flour is intensifying because soybean price spikes transmit directly to processor margins, while specialty cheese analog buyers show least price sensitivity due to limited qualified supply.
Supply Chain Analysis
Direct-to-bakery channels handle hyperscale buyer demand through relationship-based procurement that bypasses traditional distributor markups. Supply concentrates in Japan, South Korea, and Taiwan, where tofu and soy milk manufacturing clusters generate captive feedstock. Raw material dependencies center on non-GMO soybean sourcing, cellulase and protease enzyme supplies, and fermentation culture stocks. Single-source vulnerability runs through Japan's Kanto region dominance, where logistics disruptions isolating Tokyo-Saitama production clusters would cascade through downstream ingredient availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The okara market compounds steadily as plant-based dairy alternatives absorb rising volumes of upcycled protein isolates across East Asian retail channels.
For Market Incumbents: Extend fermentation expertise into cheese analog development before enzymatic specialists capture specialty retail margin pools. Secure backward integration into non-GMO soybean origination to buffer input cost volatility. Lock subscription contracts with Kanto-region bakeries through dedicated extraction line investment, defending against South Korean snack conglomerates replicating the model. For New Entrants and Emerging Players: Enter via Taiwan's compressed approval timelines for upcycled ingredient applications, where regulatory arbitrage diverts contract flows from Japan's lengthier MAFF documentation. Target dessert applications as the fastest-expanding end-use segment beyond commoditized milk. Lead with direct sales channel relationships that prioritize traceability documentation over price minimization. For Investors and Strategic Acquirers: Valuations sit cheapest among enzymatic extraction specialists without captive tofu feedstock, where technology differentiation commands scarcity premiums. The five-to-ten year viability thesis rests on EU sustainability disclosure mandates hardening demand for certified upcycled ingredients. Watch EFSA novel food approval velocity as the inflection signal determining Asian exporter market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Scale-Up | Cellulase and protease deployment in Taiwan compresses protein recovery economics for mid-scale processors. |
| Multi-Jurisdictional Certification Investment | MAFF-MFDS compliance mastery creates arbitrage capacity for cross-border ingredient traders. |
| Subscription Contracting Programs | Twelve-to-eighteen month supply agreements with Kanto bakeries justify dedicated line investment. |
| Cheese Analog R&D Pipeline | Fermentation-modified okara proteins capture specialty retail premiums beyond commoditized milk applications. |
| EU Regulatory Compliance Team Buildout | Front-loaded toxicological dossier preparation navigates EFSA novel food timelines ahead of market entry deadlines. |
Research Methodology
Coverage spans Japan, South Korea, Taiwan, and the United States, with primary inputs from each market gathered through structured interviews with tofu manufacturing executives, enzymatic extraction technology suppliers, bakery procurement managers, and regulatory affairs specialists at ingredient exporters. Secondary validation draws from MAFF compositional standards filings, MFDS upcycled ingredient registrations, EFSA novel food application databases, and customs trade data on soy-derived byproduct flows. Bottom-up volume modeling triangulates against top-down market sizing across product type, distribution channel, and end-use dimensions.
Rate-of-change decomposition isolates volume drivers from price evolution across the projection horizon. Segmentation modeling captures product type stratification, distribution channel economics, customer sophistication tiers, and end-use application complexity. CAGRs derive from installed capacity trajectories, regulatory approval velocity assumptions, and substitution elasticity estimates for plant-based dairy alternatives. Forecast inputs include enzymatic extraction technology diffusion curves and EU Farm to Fork Strategy compliance timeline assumptions.
The model holds under stable soybean commodity regimes and sustained plant-based dairy shelf space expansion; deviation in trade policy restrictions or EFSA approval delays would shift volume trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
France Animal Protein Market
Agriculture and Agri Products
GCC Poultry Meat Market
Agriculture and Agri Products
South America Compound Feed Market
Agriculture and Agri Products
Global Ruminant Feed Market
Agriculture and Agri Products
Mexico Compound Feed Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
Plant Antifreeze Market
Agriculture and Agri Products
Japan Floriculture Market
Agriculture and Agri Products
Marine Seaweed Market
Agriculture and Agri Products
Global Commercial Seaweeds Market
Agriculture and Agri Products
Global Industrial Hemp Market
Agriculture and Agri Products
Genetically Modified Feed Market
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
Marine Algae Market
Agriculture and Agri Products
North America Animal Protein Market