
 South America Animal Protein Market | 2026-2036
South America Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
South America Animal Protein Market Analytics
Soy protein concentrate is expanding its share in feed formulations for South American poultry and swine operations, altering cost structures for integrated producers. BRF S.A. leverages vertical integration from grain procurement to packaged meat exports across Mercosur trade corridors. Cargill Incorporated sustains crushing capacity dominance in Brazil's Center-West, anchoring soybean-meal supply for regional protein conversion. Archer Daniels Midland Company competes through port logistics investments that reduce export lead times to Asian buyers.
Animal protein encompasses tissue-derived nutritional inputs from livestock and aquaculture species, typically characterized by complete amino acid profiles exceeding 80% digestibility coefficients in monogastric feed applications. Its primary commercial purpose centers on human nutrition through retail meat sales and industrial ingredient supply for processed food manufacturing. Poultry leads product type volume due to shorter production cycles and lower feed conversion ratios versus beef, though beef commands premium positioning in export channels to Middle Eastern markets. Frozen form categories capture expanding share from food manufacturers seeking extended shelf stability, while fresh segments dominate Brazilian supermarket channels where same-day processing remains standard.
Brazil's Ministry of Agriculture (MAPA) enforces sanitary inspection protocols under SIF certification that govern interstate meat movement, while Argentina's SENASA administers equivalent traceability standards for bovine herd management. ANVISA in Brazil and Argentina's national food safety agency regulate maximum residue limits for veterinary pharmaceuticals, directly shaping product acceptance in regulated export destinations. Stakeholders must monitor pending EU deforestation-free supply chain regulations that threaten market access for non-compliant cattle sourcing.
Market Dynamics
Brazil's MAPA traceability mandates and cold-chain infrastructure requirements are compressing operational margins for non-integrated processors while advantaging vertically consolidated producers with captive logistics networks.
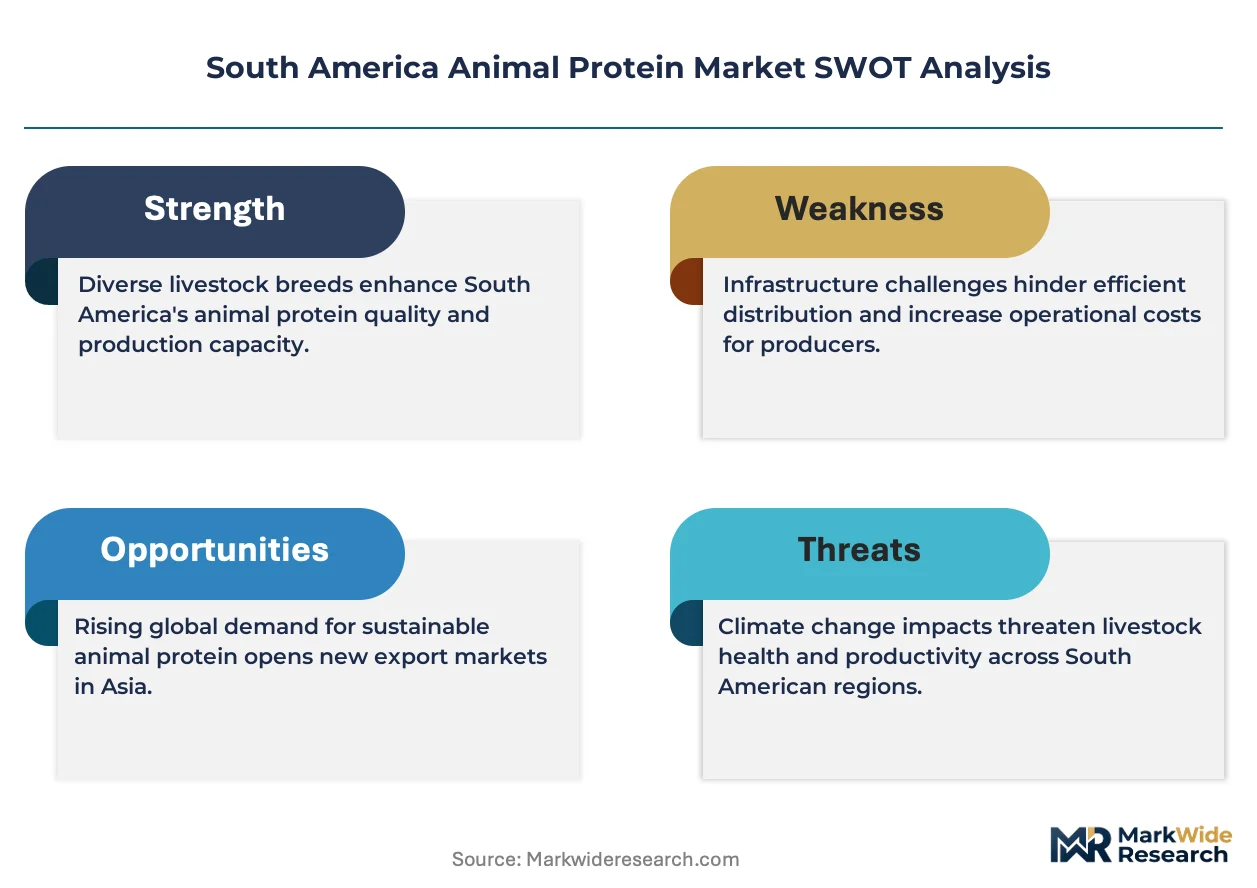
Growth Catalysts
- MAPA SIF Certification Expansion:Brazil's interstate sanitary inspection protocols now cover 85% of commercial slaughter capacity, formalizing previously informal protein flows and unlocking Mercosur cross-border sales channels for compliant operators.
- Soy Protein Concentrate Adoption:Poultry and swine feed formulations across São Paulo state operations are substituting soybean meal with higher-protein concentrates, reducing feed conversion ratios and input cost volatility for integrated producers.
- Buenos Aires Urban Consumption Density:Argentina's capital province sustains per capita protein intake rates 40% above national averages, anchoring fresh-meat distribution investments and same-day processing infrastructure deployments.
Market Restraints
- Soybean Input Cost Volatility:Brazilian Center-West crushing capacity concentration leaves protein converters exposed to basis risk between Chicago futures and domestic cash markets during harvest logistics bottlenecks.
- EU Deforestation-Free Supply Chain Regulations:Pending Brussels requirements for geolocated cattle sourcing threaten market access for Argentine and Brazilian exporters lacking farm-level traceability systems.
- Technical Cold-Chain Limitations:Last-mile refrigerated transport gaps in Paraguay's Chaco region and Bolivia's highland corridors constrain frozen product penetration outside major urban centers.
Strategic Opportunities
- Paraguay Processing Underpenetration:The country's nascent commercial slaughter infrastructure offers first-mover positioning for exporters seeking Mercosur tariff preferences with lower labor cost structures than Brazilian or Argentine competitors.
- Biogas Digesters at Feedlot Operations:Convergence of anaerobic digestion technology with manure management requirements is creating carbon credit revenue streams and energy cost offsets for large-scale cattle finishers.
- E-Commerce Direct-to-Consumer Channels:São Paulo's metropolitan cold-chain density now supports same-day delivery platforms for premium cuts, bypassing traditional supermarket intermediaries and capturing higher unit economics.
Industry Challenges
- Veterinary Pharmaceutical Residue Testing Capacity:ANVISA's tightening maximum residue limit enforcement requires laboratory certification investments that smaller Brazilian processors lack capital to deploy.
- Legacy Traceability System Integration:Argentina's SENASA bovine herd management databases remain incompatible with private sector ERP platforms, forcing dual data entry and audit preparation redundancies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Animal Protein Market |
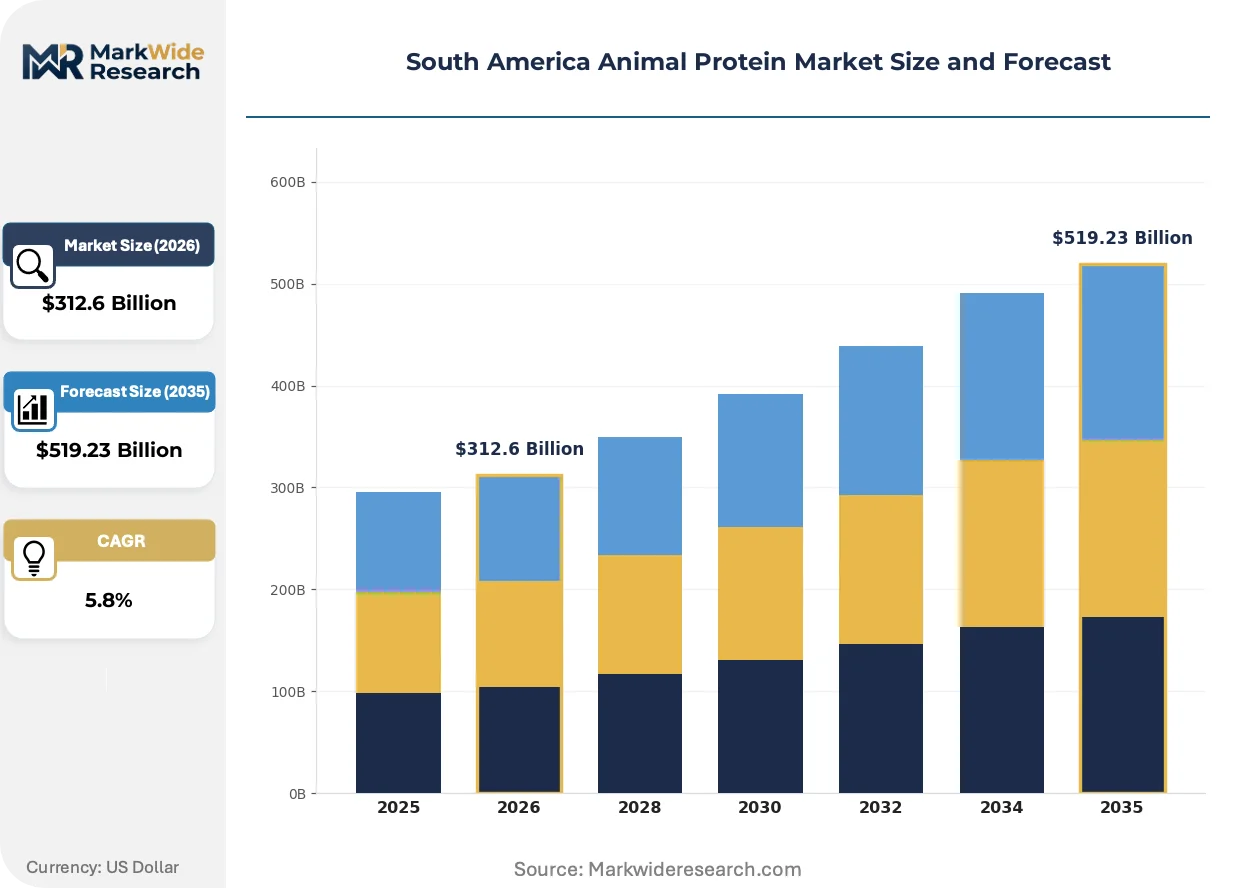
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $519.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry, Beef, Pork, Seafood End User: Restaurants, Retailers, Food Manufacturers, Households Distribution Channel: Online, Supermarkets, Wholesale, Convenience Stores Form: Fresh, Frozen, Processed, Dried |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Kerry Group plc, Darling Ingredients Inc, Royal FrieslandCampina N.V, Saputo Inc, BRF S.A., Ingredion Incorporated, Arla Foods amba, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Animal Protein Market Evolving Landscape
Digital livestock monitoring and alternative protein feed inputs are restructuring cost curves across South American protein conversion operations, while regulatory pressure on supply chain transparency accelerates technology adoption timelines.
Precision livestock monitoring systems utilizing IoT ear tags and pen-level video analytics are modularizing animal health management into discrete, subscription-based service components. Mid-scale Brazilian feedlot operators in Mato Grosso are deploying these systems faster than Argentine counterparts due to denser veterinary service networks. The technology is modularizing previously integrated husbandry functions, allowing processors to outsource health monitoring without captive veterinary staff.
ANVISA's updated pharmaceutical residue surveillance protocols now mandate third-party laboratory certification for all export-oriented slaughter facilities. The regulation is compressing operational timelines for Brazilian processors awaiting audit results before shipment releases. Frozen beef exporters to Middle Eastern markets face the steepest compliance cost increases, with several São Paulo-state facilities accelerating in-house testing laboratory construction.
Food manufacturers across Brazil's southeast industrial corridor are consolidating protein procurement through long-term supply agreements rather than spot market purchases. This contract concentration is displacing traditional wholesale market intermediaries in São Paulo's CEAGESP complex. The shift is most visible in poultry derivative purchasing, where processed food exporters seek volume certainty for export contract fulfillment.
South America Animal Protein Market Segmentation
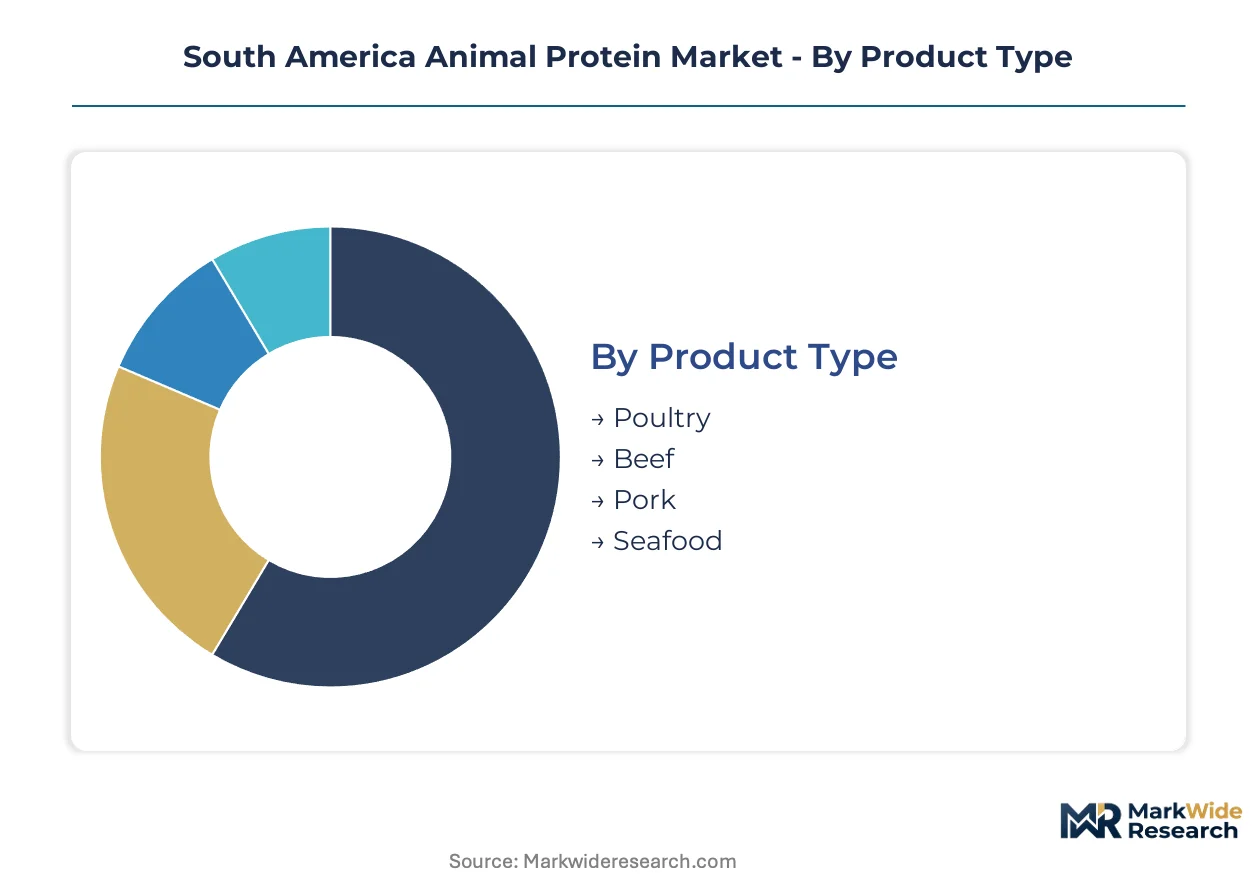
Protein sourcing decisions across South America diverge sharply by buyer sophistication, cold-chain capability, and export certification requirements. Segmentation reveals where integrated producers capture margin premiums versus commodity suppliers fighting basis risk in spot markets.
Product Type:
Poultry buyers prioritize feed conversion efficiency and shorter production cycles, while beef purchasers trade off premium positioning against traceability compliance burdens.
- Poultry:Shorter grow-out periods and superior feed conversion ratios concentrate investment in São Paulo-state integrators serving Mercosur export channels. MAPA SIF certification expansion favors operators with captive hatchery-to-processing control.
- Beef:Premium positioning in Middle Eastern export markets demands geolocated herd traceability systems to preempt EU deforestation-free regulation barriers. Argentine pasture-finished product commands price premiums against Brazilian feedlot output.
- Pork:Swine operations in southern Brazil leverage soybean meal proximity from Center-West crushing capacity.
- Seafood:Aquaculture expansion in Chilean salmon corridors and Ecuadorian shrimp zones supplies South American processing demand.
Poultry leads volumes today; beef is gaining share fastest in premium export channels.
End User:
Procurement patterns split between price-sensitive spot buyers and contract-seeking manufacturers requiring volume certainty for export fulfillment.
- Food Manufacturers:Processed meat derivative demand from Brazil's southeast industrial corridor drives long-term supply agreement consolidation, displacing CEAGESP wholesale intermediaries. Frozen poultry purchases scale with export contract volumes to Asian destinations.
- Retailers:Brazilian supermarket chains maintain same-day processing standards for fresh segments, requiring dense cold-chain infrastructure in São Paulo metropolitan zones.
- Restaurants:Foodservice operators in Buenos Aires concentrate procurement on premium fresh cuts for immediate preparation.
- Households:Direct consumption patterns track urban protein intake density, with per capita rates in Argentina's capital province exceeding national averages substantially.
Food manufacturers anchor contract volumes; retailers are expanding fastest through e-commerce platform integration.
Distribution Channel:
Channel selection reflects buyer urgency tolerance and refrigeration infrastructure access across South America's fragmented logistics landscape.
- Supermarkets:Same-day delivery platforms in São Paulo metropolitan zones now bypass traditional intermediaries, capturing premium unit economics through direct-to-consumer cold-chain density.
- Wholesale:CEAGESP complex intermediaries face displacement as integrated processors consolidate food manufacturer relationships through direct contracting.
- Online:E-commerce penetration accelerates where last-mile refrigerated transport gaps narrow.
- Convenience Stores:Limited frozen product placement outside major urban centers constrains penetration in Paraguay's Chaco and Bolivia's highland corridors.
Supermarkets dominate transaction volumes today; online channels are climbing the fastest in São Paulo cold-chain corridors.
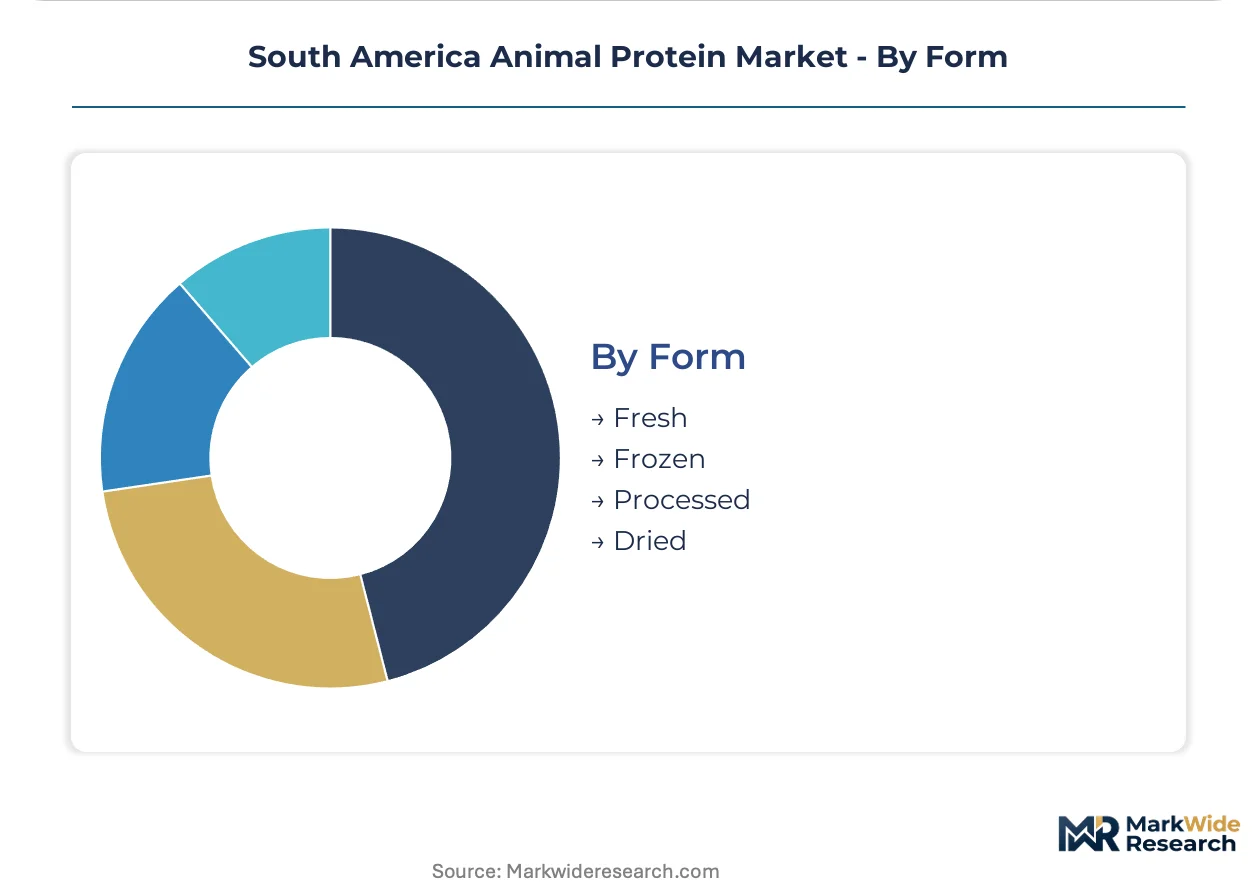
Form:
Form selection trade-offs center on shelf stability requirements against freshness premiums in divergent buyer segments.
- Frozen:Extended shelf stability captures expanding share from food manufacturers seeking export contract fulfillment certainty. Middle Eastern beef destinations require frozen form compliance with ANVISA residue testing protocols.
- Fresh:Same-day processing remains standard in Brazilian supermarket channels where metropolitan cold-chain density supports rapid turnover. Buenos Aires urban consumption density anchors fresh-meat distribution investments.
- Processed:Derivative formulations for industrial ingredient supply concentrate in Brazil's southeast manufacturing corridor.
- Dried:Preservation formats serve niche export segments and domestic shelf-stable demand.
Fresh form leads volumes today; frozen form is expanding most quickly in export-oriented manufacturing procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's integrated protein corridor anchors South American animal protein demand, with metropolitan cold-chain density supporting same-day processing standards that shape procurement patterns across the subcontinent.
Brazil
MAPA's SIF certification expansion now covers 85% of commercial slaughter capacity, formalizing interstate protein flows and unlocking Mercosur cross-border channels for compliant operators. ANVISA's tightened pharmaceutical residue surveillance mandates third-party laboratory certification for export-oriented facilities, compressing operational timelines for processors awaiting audit releases. São Paulo metropolitan zones sustain the continent's densest cold-chain infrastructure, enabling e-commerce same-day delivery platforms for premium cuts that bypass traditional supermarket intermediaries.
Argentina
Buenos Aires province concentrates per capita protein intake 40% above national averages, anchoring fresh-meat distribution investments and same-day processing infrastructure deployments for immediate-preparation foodservice channels. SENASA's bovine herd management databases administer traceability standards equivalent to Brazil's MAPA protocols, though legacy system incompatibility with private ERP platforms forces dual data entry redundancies. Pasture-finished beef from the Pampas region commands price premiums in Middle Eastern export markets against Brazilian feedlot output.
Paraguay
Nascent commercial slaughter infrastructure in the Chaco region offers first-mover positioning for exporters seeking Mercosur tariff preferences with lower labor cost structures than Brazilian or Argentine competitors. Last-mile refrigerated transport gaps outside Asunción and Ciudad del Este constrain frozen product penetration, limiting convenience store placement in rural corridors. The country's underdeveloped processing base presents acquisition opportunities for regional integrators seeking capacity expansion.
Chile
Salmon aquaculture corridors in the Los Lagos and Aysén regions supply processed seafood derivatives to South American protein converters, diversifying raw material sourcing for feed manufacturers. The national fisheries service enforces sanitary certification protocols for aquaculture exports that align with destination market requirements in Brazil and Argentina. Puerto Montt's processing cluster anchors value-added seafood ingredient production for regional food manufacturers.
Uruguay
Grass-fed beef exports to premium European and North American niche markets leverage the country's smaller-scale, traceable herd management systems that preempt EU deforestation-free regulation barriers. The Ministry of Livestock, Agriculture and Fisheries maintains geolocated cattle sourcing databases that satisfy emerging Brussels supply chain transparency requirements. Montevideo's port infrastructure supports direct export channels bypassing Argentine and Brazilian transshipment bottlenecks.
South America Animal Protein Market Competitive Landscape
Global majors compete with regional champions across crushing capacity, cold-chain logistics, and export certification capabilities. Market structure tilts toward consolidation at the upstream grain procurement and downstream branded protein levels, with fragmentation persisting in mid-scale processing. Three archetypes dominate: integrated agribusiness conglomerates controlling input supply, specialized protein derivative manufacturers serving industrial food customers, and regional packagers leveraging Mercosur trade preferences. Competitive dynamics center on backward integration into feed input supply and strategic port logistics investments that reduce export lead times.
Within the integrated agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company exemplify crushing capacity dominance and logistics optimization strategies. BRF S.A. occupies a position representing vertical consolidation from grain procurement through packaged meat exports across regional trade corridors. These three anchors illustrate divergent approaches to capturing margin premiums: upstream input control versus downstream brand positioning versus midstream processing scale.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Kerry Group plc |
| Darling Ingredients Inc |
| Royal FrieslandCampina N.V |
| Saputo Inc |
| BRF S.A. |
| Ingredion Incorporated |
| Arla Foods amba |
| Others |
Value Network & Pricing Analysis
Captive crushing capacity in Brazil's Center-West anchors both input cost positions and export pricing power for integrated protein converters serving Mercosur corridors. This upstream control insulates vertically consolidated operators from basis risk between Chicago futures and domestic cash markets during harvest logistics bottlenecks.
Pricing Analysis
Input-cost pass-through from soybean meal volatility shapes contract structures across South American protein markets. Pricing stratifies across SIF-certified export tiers, ANVISA-compliant residue-tested grades, and domestic spot-market categories. Cost compression in frozen beef export channels is intensifying because laboratory certification investments compress operational timelines for processors awaiting audit releases. Food manufacturers exhibit lowest price sensitivity due to long-term supply agreement consolidation, while spot-market wholesalers face margin erosion from contract displacement.
Supply Chain Analysis
Regional distribution centers in São Paulo metropolitan zones anchor hub-and-spoke cold-chain patterns that extend into Argentina's Buenos Aires province. Supply concentrates in Brazil, Argentina, and Paraguay, with crushing capacity in Mato Grosso and Santa Catarina feeding downstream conversion. Raw material flows draw from Center-West soybean production, Pampas pasture systems, and imported aquaculture inputs from Chile. Single-source vulnerability in laboratory testing capacity for ANVISA compliance creates shipment release bottlenecks. Distribution runs through direct-to-manufacturer contracting that displaces traditional CEAGESP wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America animal protein market functions as a stable compounder, with MAPA regulatory expansion formalizing previously informal flows and locking in compliant operators for cross-border growth.
For Market Incumbents: Deepen backward integration into feed input supply through captive crushing capacity additions in Brazil's Center-West, insulating margin positions from soybean basis risk. Invest in in-house ANVISA-certified testing laboratories to compress shipment release timelines and preempt competitor compliance advantages. Fortify Mercosur trade corridor relationships before EU deforestation-free regulations raise traceability barriers for non-compliant entrants. For New Entrants and Emerging Players: Launch via Paraguay's nascent commercial slaughter infrastructure to capture Mercosur tariff preferences with lower labor cost structures than Brazilian or Argentine incumbents. Target underpenetrated frozen product placement in Bolivia's highland corridors and Paraguay's Chaco region where last-mile refrigerated transport gaps constrain incumbent penetration. Pursue biogas digester partnerships at feedlot operations to generate carbon credit revenue streams that offset energy costs. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale Brazilian processors lacking capital for ANVISA laboratory certification because regulatory compression is forcing consolidation around compliant operators. The 5-10 year viability window favors targets with existing SIF certification and geolocated cattle traceability systems. Watch for EU deforestation-free regulation implementation timing as the inflection signal determining market access premiums for compliant versus non-compliant supply bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crushing Capacity | Cargill and ADM dominance in Center-West soy processing secures meal supply for protein conversion at cost-advantaged positions. |
| In-House Laboratory Certification | ANVISA's tightened residue surveillance mandates third-party testing capacity that São Paulo-state facilities are accelerating construction to capture. |
| Direct-to-Consumer E-Commerce Launch | Same-day delivery platforms in São Paulo metropolitan zones bypass supermarket intermediaries and capture premium unit economics for fresh cuts. |
| Geolocated Cattle Traceability Investment | Uruguay's Ministry of Livestock databases satisfy emerging EU supply chain transparency requirements that threaten Argentine and Brazilian market access. |
| Biogas Digester Deployment | Anaerobic digestion technology convergence with manure management creates carbon credit revenue streams for Mato Grosso feedlot operators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with MAPA compliance officers, SENASA traceability administrators, integrated processor procurement directors, cold-chain logistics operators, and food manufacturer sourcing managers with secondary validation. Trade flow databases, ANVISA regulatory filings, MAPA SIF certification records, and Mercosur tariff schedules anchored supply-side modeling. Bottom-up facility capacity estimates triangulated against top-down consumption projections across the analysis window.
Historical reference periods spanning pre-pandemic baselines through recent regulatory implementation phases anchored the projection horizon. Segmentation dimensions modeled include product type, form category, end-user archetype, distribution channel, and regional regulatory cluster. CAGRs were derived from compound growth trajectory analysis incorporating feed conversion efficiency improvements, certification expansion timelines, and export channel penetration rates. Soybean input cost volatility curves and cold-chain infrastructure deployment schedules fed industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU deforestation-free regulation acceleration or ANVISA residue limit tightening scenarios. Outputs reflect documented assumptions regarding MAPA SIF certification coverage expansion and Mercosur trade preference continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
South Africa Alfalfa Hay Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
North America Bonsai Market
Agriculture and Agri Products
Plant Antifreeze Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
Rice-Based Products Market
Agriculture and Agri Products
Ghana Agriculture Market
Agriculture and Agri Products
North America Bee Products Market
Agriculture and Agri Products
Asia-Pacific Animal Protein Market
Agriculture and Agri Products
Fermented Soybean Meal Protein for Animal Feed Market
Agriculture and Agri Products
Marine Seaweed Market
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
GCC Poultry Meat Market
Agriculture and Agri Products
Spain Compound Feed Market