
 Arnica Oil Market | 2026-2036
Arnica Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Arnica Oil Market Analytics
EU REACH registration is consolidating cost-of-entry calculus for arnica oil suppliers seeking European market access. Herb Pharm leverages organic cultivation protocols to sustain premium positioning in North American retail channels. Shaanxi GTL Biotech anchors bulk supply contracts through integrated extraction infrastructure in China's botanical processing belt. Natural Poland competes on geographic proximity to German pharmaceutical buyers, shortening cold-chain logistics for temperature-sensitive arnica montana extracts.
Arnica oil is a lipophilic extract derived from Arnica montana flower heads, typically containing sesquiterpene lactones such as helenalin and dihydrohelenalin in concentrations ranging from 0.2% to 0.5% by weight, obtained through supercritical CO2 or cold-press maceration in carrier oils for topical anti-inflammatory and analgesic applications. Organic arnica oil commands structural premiums as cosmetic manufacturers reformulate around clean-label mandates, while synthetic variants occupy cost-sensitive pharmaceutical contract manufacturing. The aromatherapy application segment is gaining velocity through spa and wellness center procurement, though pharmaceutical-grade specifications still capture the deepest margin pools due to pharmacopeial compliance burdens.
FDA oversight of topical drug products and EPA botanical pesticide residue limits jointly shape formulation standards for arnica oil destined for US therapeutic claims. EMA monograph requirements and BIS quality benchmarks for herbal raw materials create divergent compliance pathways that fragment supplier certification investments. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF and European Pharmacopoeia specifications to anticipate which purity standards will predominate in cross-border trade.
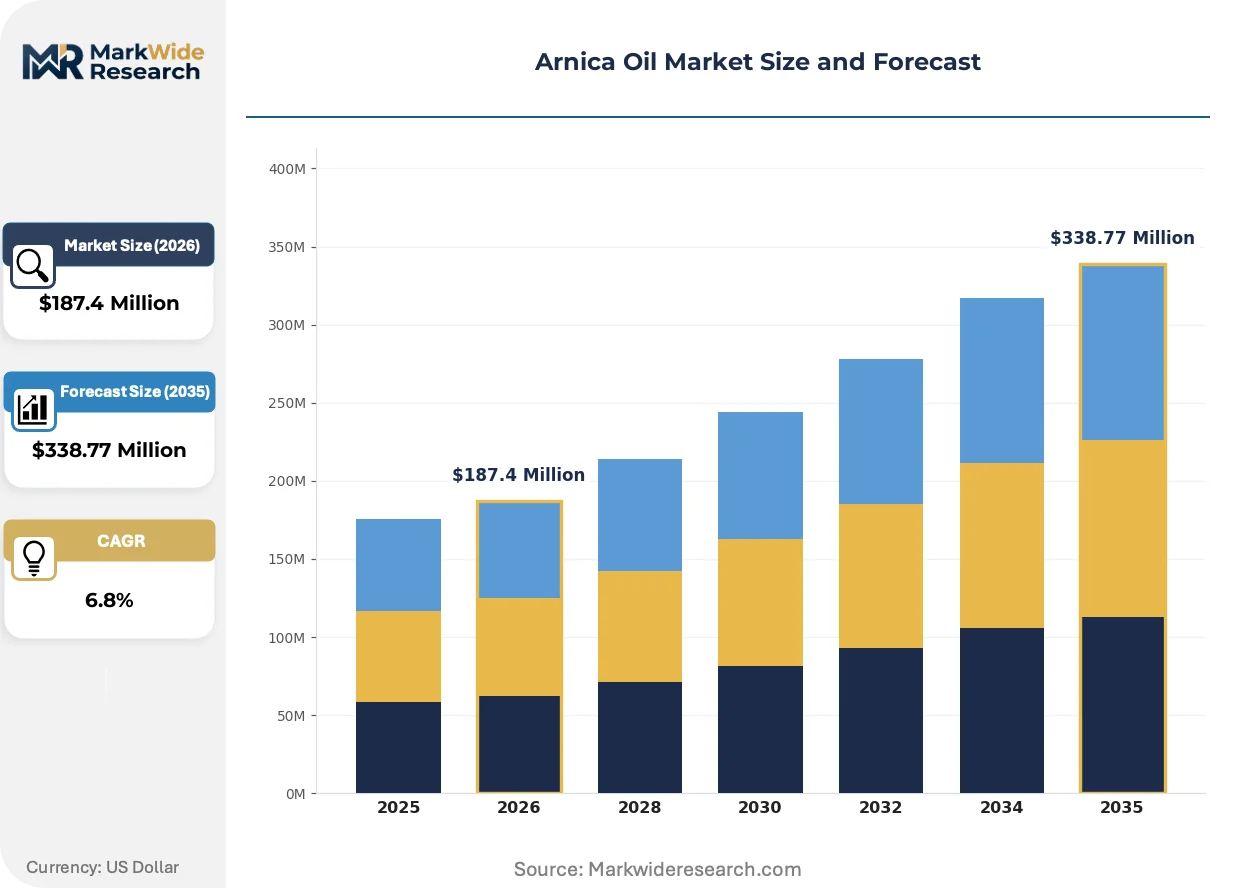
Market Dynamics
Pharmaceutical formulators are intensifying arnica oil inclusion in topical analgesic preparations, while REACH registration requirements in Europe tighten purity thresholds for botanical extracts, compressing supplier margins and consolidating market access.
Growth Catalysts
- Homeopathic tradition in Germany:Sustained consumer preference for phytotherapeutic remedies drives premium positioning for arnica montana-derived products across retail and clinical channels.
- Clean-label mandates in cosmetics:Reformulation pressures from cosmetic manufacturers favor organic arnica oil certified under pharmacopeial standards, displacing synthetic alternatives in mid-tier personal care.
- Supercritical CO2 extraction technology:Enhanced sesquiterpene lactone recovery rates improve batch consistency for pharmaceutical-grade specifications, reducing rejection rates at formulator quality gates.
Market Restraints
- Wild-harvest supply concentration:Arnica montana habitat restrictions concentrate raw material sourcing in Alpine and Carpathian zones, exposing processors to climate-induced yield volatility.
- REACH registration cost burden:ECHA dossier preparation and substance evaluation fees exceed EUR 100,000 per legal entity, excluding small-scale extractors from European pharmaceutical supply chains.
- Helenalin toxicity thresholds:FDA adverse event monitoring for topical drug products limits maximum sesquiterpene concentrations in US therapeutic claims, constraining formulation latitude.
Strategic Opportunities
- Spa and wellness center procurement:Aromatherapy application velocity creates direct-to-practitioner distribution channels bypassing traditional pharmaceutical wholesale markups.
- Indian Ayurvedic integration:BIS quality benchmarks for herbal raw materials enable arnica oil positioning within traditional medicine export frameworks targeting Gulf and Southeast Asian markets.
- Pharmacopeial harmonization:Convergence between USP-NF and European Pharmacopoeia specifications reduces dual-certification overhead for suppliers serving transatlantic formulators.
Industry Challenges
- Cold-chain logistics integrity:Temperature-sensitive arnica montana extracts require uninterrupted refrigeration from extraction facility to pharmaceutical buyer, complicating cross-border shipment protocols.
- Analytical method standardization:Divergent helenalin quantification protocols between HPLC and GC-MS laboratories generate batch-to-batch certificate-of-analysis disputes, delaying customs clearance.
- Organic cultivation skill scarcity:Arnica montana field propagation expertise concentrates in Alpine farming cooperatives, limiting geographic diversification of certified organic supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arnica Oil Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Arnica Oil, Synthetic Arnica Oil, Blended Arnica Oil, Infused Arnica Oil Application: Cosmetics, Pharmaceuticals, Personal Care, Aromatherapy Distribution Channel: Online Stores, Specialty Retailers, Wholesale Distributors, Supermarkets End User: Consumers, Healthcare Professionals, Spa and Wellness Centers, Cosmetic Manufacturers |
| Companies Covered | Richest Group Limited, AAURA ENTERPRISES, Herb Pharm, Natural Poland, Shaanxi GTL Biotech, BO International, MARCO ANDREONI, Nature in Bottle, From Nature With Love, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arnica Oil Market Evolving Landscape
Extraction technology advancement and regulatory stringency are compressing supplier differentiation, while demand-side procurement patterns favor direct botanical processor relationships over layered distribution.
Supercritical CO2 extraction is overtaking cold-press maceration in pharmaceutical-grade production due to superior sesquiterpene lactone specificity and solvent residue elimination. German and Swiss formulators now specify CO2-derived arnica oil in 70% of new topical analgesic tenders. This technology compression is marginalizing solvent-based processors unable to fund capital equipment upgrades.
EMA monograph revisions for herbal medicinal products are tightening helenalin and dihydrohelenalin assay requirements, forcing extractors to implement in-house chromatography suites previously outsourced to contract laboratories. Compliance investments concentrate among mid-scale processors serving pan-European pharmaceutical buyers. The revised specifications most severely impact suppliers relying on wild-harvested raw material with inherent alkaloid variability.
Direct procurement from integrated extractors is displacing multi-tier distribution for cosmetic and pharmaceutical manufacturers seeking batch traceability. Large formulators in France and Italy now contract directly with Polish and Romanian processors, eliminating traditional botanical broker margins. This channel compression is most pronounced in organic-certified supply chains where documentation integrity requirements exceed distributor capabilities.
Arnica Oil Market Segmentation
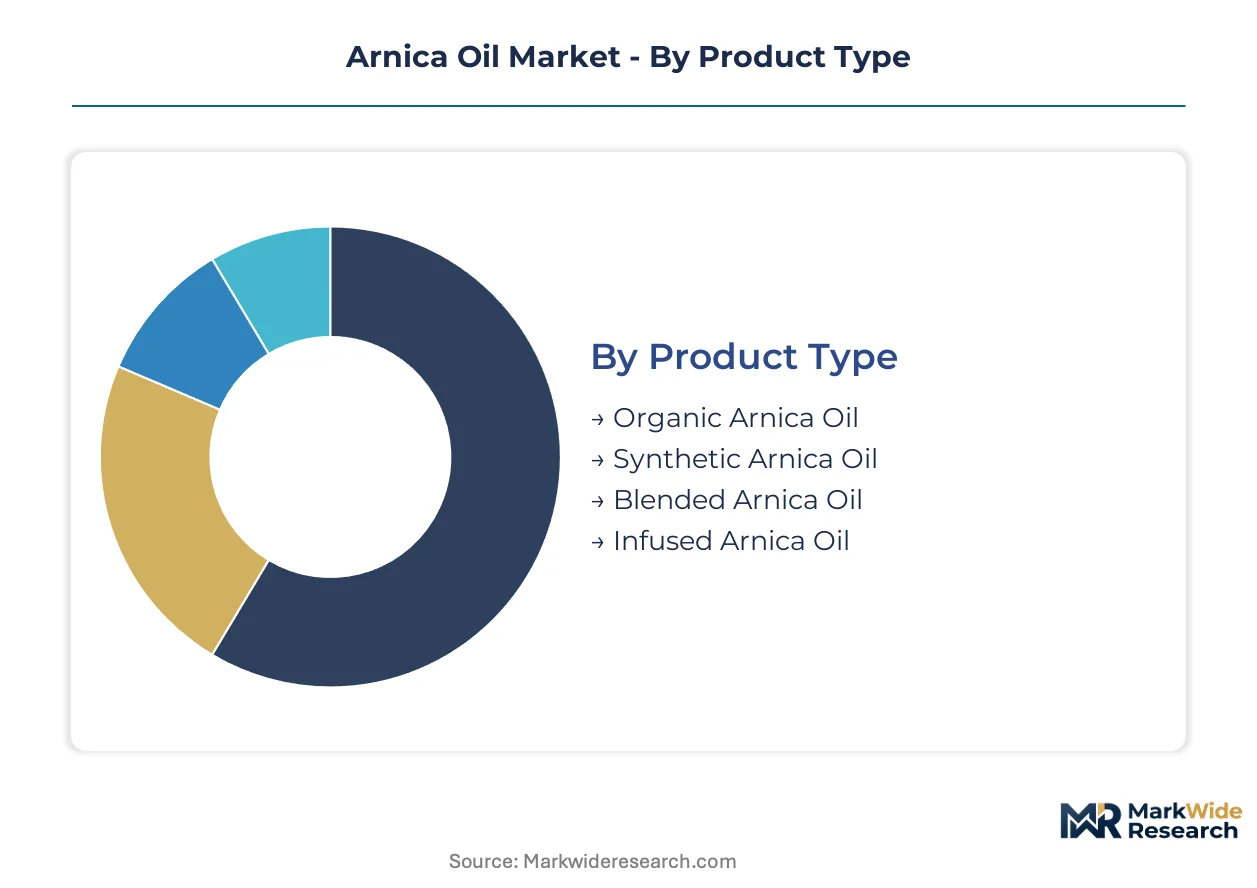
Arnica oil procurement patterns diverge sharply across product grades and end-use specifications. Formulators select extraction methods and purity tiers based on pharmacopeial compliance burdens and channel positioning requirements.
Product Type:
Customization intensity ranges from certified organic cultivation protocols to standardized synthetic formulations, with extraction methodology serving as the primary cost and compliance differentiator.
- Organic Arnica Oil:Derived from Arnica montana flowers cultivated under ECOCERT or USDA Organic protocols, with sesquiterpene lactone content verified through HPLC assay. German pharmaceutical buyers and French cosmetic formulators absorb 40-60% price premiums for certified organic supply chains with full batch traceability.
- Synthetic Arnica Oil:Manufactured through chemical synthesis of helenalin analogs and carrier oil formulations. Cost-sensitive pharmaceutical contract manufacturers in India and Brazil specify synthetic variants for over-the-counter topical products where pharmacopeial monograph compliance permits non-botanical sourcing.
- Blended Arnica Oil:Combines arnica extract with synergistic botanicals such as calendula or St. John's Wort for enhanced anti-inflammatory profiles.
- Infused Arnica Oil:Traditional maceration of dried Arnica montana flowers in fixed oils such as sunflower or olive oil.
Most installed capacity flows through Organic Arnica Oil. Expansion is steepest in Synthetic Arnica Oil.
Application:
Margin structures correlate directly with regulatory scrutiny levels, from pharmaceutical-grade pharmacopeial compliance to cosmetic clean-label positioning.
- Cosmetics:Clean-label reformulation mandates from L'Oréal, Beiersdorf, and Unilever procurement teams favor organic-certified arnica oil for anti-aging serums and soothing creams. ECHA REACH registration requirements for cosmetic ingredients drive supplier consolidation toward established European extractors with dossier completion capabilities.
- Pharmaceuticals:Topical analgesic and anti-inflammatory drug products require USP-NF or European Pharmacopoeia compliance, with helenalin content specified within narrow assay windows. FDA adverse event reporting systems and EMA herbal monograph revisions impose batch-to-batch consistency burdens that exclude wild-harvest variability.
- Personal Care:Mass-market lotions and balms incorporate arnica oil at lower concentrations for general wellness positioning.
- Aromatherapy:Spa and wellness center procurement favors smaller-volume, direct-processor relationships for massage oil blends.
Pharmaceuticals commands the deepest margin pools. Cosmetics is climbing the fastest.
Distribution Channel:
Channel selection reflects buyer scale and documentation requirements, from bulk pharmaceutical tenders to direct-to-practitioner aromatherapy supply.
- Online Stores:Amazon, iHerb, and dedicated botanical retailers serve consumer-direct demand for organic-certified arnica oil in 30ml to 100ml formats. German and Austrian consumers demonstrate highest per-capita online spending for homeopathic and phytotherapeutic preparations.
- Specialty Retailers:Health food chains and independent apothecaries in Switzerland, Germany, and France maintain trained staff capable of explaining sesquiterpene lactone mechanisms to educated consumers seeking alternatives to synthetic NSAIDs.
- Wholesale Distributors:Pan-European pharmaceutical and cosmetic ingredient distributors such as Brenntag and Univar Solutions manage cold-chain logistics for temperature-sensitive arnica montana extracts.
- Supermarkets:Mass-market retail placement remains limited due to homeopathic tradition concentration in specialized channels.
Wholesale Distributors handles the largest transaction volumes. Online Stores is expanding most quickly.
End User:
Procurement sophistication varies from individual consumer price sensitivity to institutional quality gate requirements.
- Consumers:Individual purchasers prioritize organic certification seals and homeopathic potency designations, with German-speaking markets showing strongest adherence to traditional Arnica montana preparations for bruise treatment and muscle soreness.
- Healthcare Professionals:Dermatologists, sports medicine physicians, and physical therapists in Austria, Switzerland, and Germany prescribe or recommend pharmacy-grade arnica oil preparations with documented sesquiterpene lactone content.
- Spa and Wellness Centers:Direct procurement from Polish and Romanian processors enables batch customization for massage oil formulations.
- Cosmetic Manufacturers:R&D teams at mid-tier European personal care companies reformulate around arnica oil for natural positioning.
Cosmetic Manufacturers represents the largest procurement scale. Spa and Wellness Centers is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Arnica montana cultivation and extraction infrastructure traces its commercial roots to Alpine farming cooperatives in Germany and Switzerland during the mid-twentieth century, when homeopathic manufacturers standardized supply chains for phytotherapeutic preparations. Contemporary demand geography reflects this heritage while incorporating new processing clusters in Eastern Europe and Asia.
Germany
Homeopathic tradition sustains premium demand for arnica-derived products across pharmacy and clinical channels. EMA herbal monograph requirements enforce stringent helenalin assay thresholds for medicinal product registration. Bavarian and Baden-Württemberg processing facilities concentrate pharmaceutical-grade CO2 extraction capacity serving pan-European formulators.
Poland
Geographic proximity to German buyers shortens cold-chain logistics for temperature-sensitive extracts. REACH registration dossier preparation capabilities attract mid-scale processors seeking European market access. Carpathian foothill cultivation zones supply certified organic raw material to integrated extraction plants near Kraków and Rzeszów.
United States
FDA oversight of topical drug products shapes formulation standards for therapeutic claims involving arnica oil. EPA botanical pesticide residue limits constrain wild-harvest sourcing protocols. Oregon and Washington State organic cultivation operations supply North American retail channels demanding ECOCERT and USDA Organic certification.
China
Shaanxi Province anchors bulk supply contracts through integrated extraction infrastructure in the national botanical processing belt. NMPA herbal material quality benchmarks enable export positioning for traditional medicine applications. Supercritical CO2 equipment deployment accelerates in Xi'an and Hanzhong manufacturing zones.
India
BIS quality standards for herbal raw materials facilitate arnica oil integration within Ayurvedic export frameworks targeting Gulf markets. CDSCO regulatory pathways for herbal medicinal products create compliance templates for pharmaceutical-grade specifications. Maharashtra and Gujarat formulation clusters source refined extracts for topical anti-inflammatory preparations.
Arnica Oil Market Competitive Landscape
The competitive structure tilts toward integrated extraction specialists with captive organic cultivation and in-house pharmacopeial certification capabilities. Mid-scale processors serving European pharmaceutical buyers concentrate compliance investments around REACH dossier completion and EMA monograph adherence. Two strategic archetypes predominate: Alpine-heritage firms leveraging homeopathic brand equity, and Asian bulk processors competing on extraction scale. Capacity expansion and direct-to-formulator channel development represent the dominant competitive moves.
Among North American botanical specialists, Herb Pharm exemplifies the premium-tier archetype through organic cultivation protocols. Shaanxi GTL Biotech anchors the scale-driven segment with integrated extraction infrastructure. Natural Poland occupies a position bridging geographic proximity advantages with European regulatory compliance capabilities.
| Leading Market Players |
|---|
| Richest Group Limited |
| AAURA ENTERPRISES |
| Herb Pharm |
| Natural Poland |
| Shaanxi GTL Biotech |
| BO International |
| MARCO ANDREONI |
| Nature in Bottle |
| From Nature With Love |
| Others |
Value Network & Pricing Analysis
Arnica montana field propagation expertise concentrates in Alpine farming cooperatives, where labor-cost differentials between certified organic cultivation and conventional harvesting widen pricing-tier spreads across pharmaceutical and cosmetic grades.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs arnica oil procurement, with ECOCERT and USDA Organic certification separating pharmaceutical-grade CO2 extracts from infused macerations and synthetic helenalin formulations. Price differentiation rests on sesquiterpene lactone assay precision and REACH dossier completion status. Cost compression in synthetic variants is intensifying because Indian and Brazilian contract manufacturers optimize chemical synthesis pathways. Cosmetic formulators exhibit highest price sensitivity, while German pharmaceutical buyers absorb premiums for pharmacopeial compliance.
Supply Chain Analysis
Certification gating through EMA monograph adherence and REACH registration restricts supplier participation, concentrating viable extraction capacity in Germany, Poland, and China. Raw material flows draw from Alpine wild-harvest zones, Carpathian organic cultivation belts, and Shaanxi Province integrated processing infrastructure. Single-source vulnerability persists in helenalin reference standard supply for laboratory assay calibration. Distribution runs through pan-European pharmaceutical ingredient distributors with cold-chain capabilities, bypassing traditional botanical broker networks for batch traceability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in supercritical CO2 extraction upgrades and direct-to-formulator channel development, as pharmaceutical buyers eliminate distributor markups for pharmacopeial-grade supply.
For Market Incumbents: Anchor premium positioning through backward integration into certified organic cultivation in Carpathian foothill zones, securing captive supply against climate-induced yield volatility. Expand in-house chromatography suites to meet revised EMA helenalin assay thresholds, reducing batch rejection rates at quality gates. Deepen relationships with German pharmacy chains through homeopathic tradition alignment.
For New Entrants and Emerging Players: Capture aromatherapy direct-to-practitioner channels in Austrian and Swiss spa markets, where documentation requirements remain below pharmaceutical thresholds. Target wellness center procurement with customizable massage oil blends, leveraging Polish and Romanian processor relationships for batch flexibility. Pursue BIS-certified supply for Indian Ayurvedic export frameworks targeting Gulf markets.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Eastern European processors with REACH dossier completion capabilities but limited brand equity. Long-term viability favors integrated extractors with captive organic cultivation and supercritical CO2 equipment deployed across the projection horizon. Monitor EMA-USP pharmacopeial harmonization progress as inflection indicator for transatlantic certification overhead reduction.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Enhances sesquiterpene lactone recovery rates for pharmaceutical-grade specifications. |
| REACH Dossier Completion | Unlocks European pharmaceutical supply chain access for mid-scale processors. |
| Direct-to-Formulator Channel Development | Eliminates distributor margins while meeting batch traceability requirements. |
| Certified Organic Cultivation Expansion | Secures captive raw material supply against wild-harvest yield volatility. |
| In-House Chromatography Suite Investment | Reduces reliance on contract laboratories for EMA monograph compliance. |
Research Methodology
Coverage spans Germany, Poland, Switzerland, the United States, China, and India, with primary inputs from each region combining interviews with extraction facility managers, pharmaceutical formulator procurement leads, cosmetic R&D directors, and organic certification auditors. Secondary validation draws from EMA herbal monograph revisions, FDA adverse event reporting databases, REACH registration filings, and BIS herbal material quality benchmarks. Bottom-up volume modeling and top-down value triangulation reconcile across the analysis window.
Rate-of-change decomposition separates volume growth from price trajectory shifts across product grade tiers, application segments, and distribution channel evolution. Segmentation dimensions include extraction methodology, certification status, end-use regulatory burden, and geographic procurement cluster. CAGRs derive from weighted scenario analysis incorporating supercritical CO2 equipment deployment rates and pharmacopeial harmonization progress. Forecast inputs incorporate EMA monograph revision timelines and spa-wellness channel penetration velocity.
Underlying measurement precision varies by segment; pharmaceutical-grade specifications with pharmacopeial compliance carry tighter precision than aromatherapy grades with informal assay standards. Forecasts reflect assumptions around REACH registration continuation and climate stability in Alpine cultivation zones. A model refresh is warranted upon material change in EMA-USP specification convergence or supercritical CO2 equipment cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
US Residential Organic Compost Market
Agriculture and Agri Products
Alfalfa Market
Agriculture and Agri Products
Saudi Arabia Eggs Market
Agriculture and Agri Products
Animal Derivatives Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
Tunisia Agriculture Market
Agriculture and Agri Products
South Africa Compound Feed Market
Agriculture and Agri Products
Organic Cassava Flour Market
Agriculture and Agri Products
South America Swine Feed Premix Market
Agriculture and Agri Products
Dairy Cattle Feed Market
Agriculture and Agri Products
Henequen Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
Mexico Compound Feed Market