
 Sporanox Market | 2026-2036
Sporanox Market Size, Share, and Industry Trends Forecast 2026-2036
Sporanox Market Insights
The shift from single-source API procurement to multi-source active pharmaceutical ingredient contracts is restructuring supply security for itraconazole manufacturers. Merck & Co. anchors its position through backward integration into fermentation-based azole production. Janssen Pharmaceuticals differentiates via sustained-release capsule technology that extends patent-protected formulations. Teva Pharmaceutical Industries Ltd. competes on cost-engineered generic capsules that occupy price-sensitive hospital tenders.
Sporanox (itraconazole) is a synthetic triazole antifungal agent with a molecular formula of C35H38Cl2N8O4, formulated as capsules containing pelleted drug coated onto sugar spheres for enhanced bioavailability, primarily indicated for systemic mycoses including histoplasmosis and aspergillosis. Capsule formulations dominate current revenue streams due to established outpatient compliance and pharmacy inventory familiarity, while oral solution variants capture fastest-growing share in immunocompromised patient populations requiring dose flexibility. The application landscape shows fungal infection treatment as the mature volume base, with onychomycosis representing a concentrated margin pool where branded pricing power persists against generic erosion.
FDA bioequivalence standards for itraconazole generics shape product substitution rules in US retail and hospital channels, while EMA guidelines under the EU pharmaceutical legislation framework govern centralized marketing authorization across European member states. The WHO Essential Medicines List inclusion of itraconazole influences national procurement policies in low-income markets. Stakeholders must monitor evolving pharmacovigilance requirements for azole drug-drug interactions as regulatory scrutiny intensifies across multiple jurisdictions.
Market Dynamics
FDA bioequivalence requirements for generic itraconazole are compressing branded pricing power while hospital procurement consolidation in the United States concentrates purchasing leverage among fewer pharmacy buyers. Multi-source API contracting is displacing single-supplier fermentation dependencies.
Growth Catalysts
- Immunocompromised patient expansion:Rising transplant volumes and oncology chemotherapy cycles in tertiary care centers are expanding the addressable population for systemic antifungal prophylaxis.
- WHO Essential Medicines List inclusion:National procurement programs in low-income markets reference itraconazole inclusion for histoplasmosis and endemic mycoses, channeling development financing toward supply security.
- Sustained-release formulation patents:Pellet-in-capsule technology with pH-dependent dissolution profiles extends effective half-life, supporting outpatient compliance and reducing hospital readmission costs.
Market Restraints
- Fermentation capacity concentration:Azole API production clusters in coastal China and select Indian contract manufacturers, exposing supply continuity to regional environmental enforcement actions and energy rationing.
- Triazole cross-resistance patterns:Agricultural azole fungicide runoff correlates with clinical Candida and Aspergillus resistance, narrowing therapeutic windows and triggering restrictive stewardship protocols.
- Generic substitution mandates:US state-level automatic substitution laws for AB-rated bioequivalent capsules erode branded dispensing rates in retail pharmacy channels.
Strategic Opportunities
- Oral solution pediatric dosing:Liquid formulations with weight-based titration capture immunocompromised pediatric oncology and HIV populations where capsule swallowing fails.
- India CDSCO accelerated approval pathway:The country's streamlined review for essential medicines enables faster market entry for domestic manufacturers with WHO-prequalified APIs.
- Telemedicine dermatology channels:Onychomycosis diagnosis via remote consultation platforms expands reach into underserved rural and suburban markets with limited podiatry access.
Industry Challenges
- Pharmacokinetic variability management:Itraconazole's pH-dependent absorption requires gastric acid monitoring, complicating co-administration with proton pump inhibitors and H2 blockers in polypharmacy patients.
- Drug-drug interaction surveillance:CYP3A4 inhibition necessitates therapeutic drug monitoring programs that strain hospital pharmacy clinical specialist capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sporanox Market |
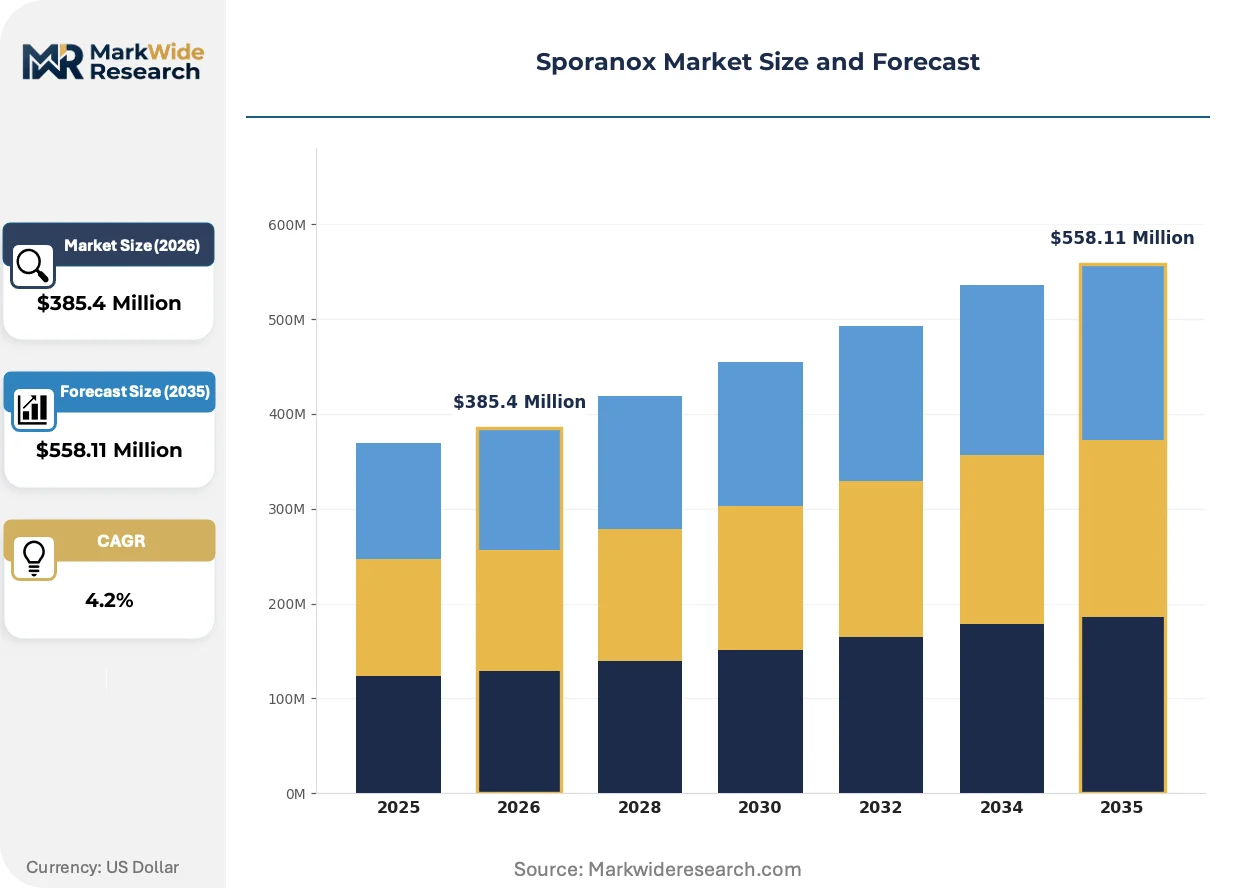
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $558.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Oral Solution, Injectable, Powder Application: Fungal Infections, Onychomycosis, Aspergillosis, Histoplasmosis End User: Hospitals, Clinics, Home Healthcare, Pharmaceutical Companies Delivery Mode: Oral, Intravenous, Topical, Inhalation |
| Companies Covered | Merck & Co., Astellas Pharma, Janssen Pharmaceuticals, Novartis AG, Gilead Sciences, Johnson & Johnson, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sporanox Market Trends and Innovations
Formulation science and regulatory science are converging to redefine competitive advantage in systemic antifungal therapy. Bioavailability engineering and pharmacovigilance automation are absorbing disproportionate R&D investment.
Nanostructured lipid carrier systems for itraconazole are absorbing development resources at major formulation houses seeking to overcome fed/fasted variability in plasma exposure. Hospital systems with embedded clinical pharmacists are piloting these platforms for transplant prophylaxis protocols. The technology is absorbing market share from conventional pellet-in-capsule products in academic medical centers with therapeutic drug monitoring infrastructure.
REACH authorization requirements for azole active substances are tightening impurity profiling standards for European market access. Manufacturers must now submit extended one-generation reproductive toxicity studies and revised environmental risk assessments for persistent metabolites. Capsule suppliers with pre-2023 dossiers face significant supplementary data costs to maintain EMA marketing authorizations.
Hospital formulary committees are consolidating antifungal stewardship decisions under infectious disease pharmacy specialists, compressing individual physician prescribing autonomy. This concentration shifts influence from retail detailing to outcomes-based contracting with integrated delivery networks. The pattern is most visible in United States Medicare Advantage plans with capitated pharmacy benefits.
Sporanox Market Segmentation
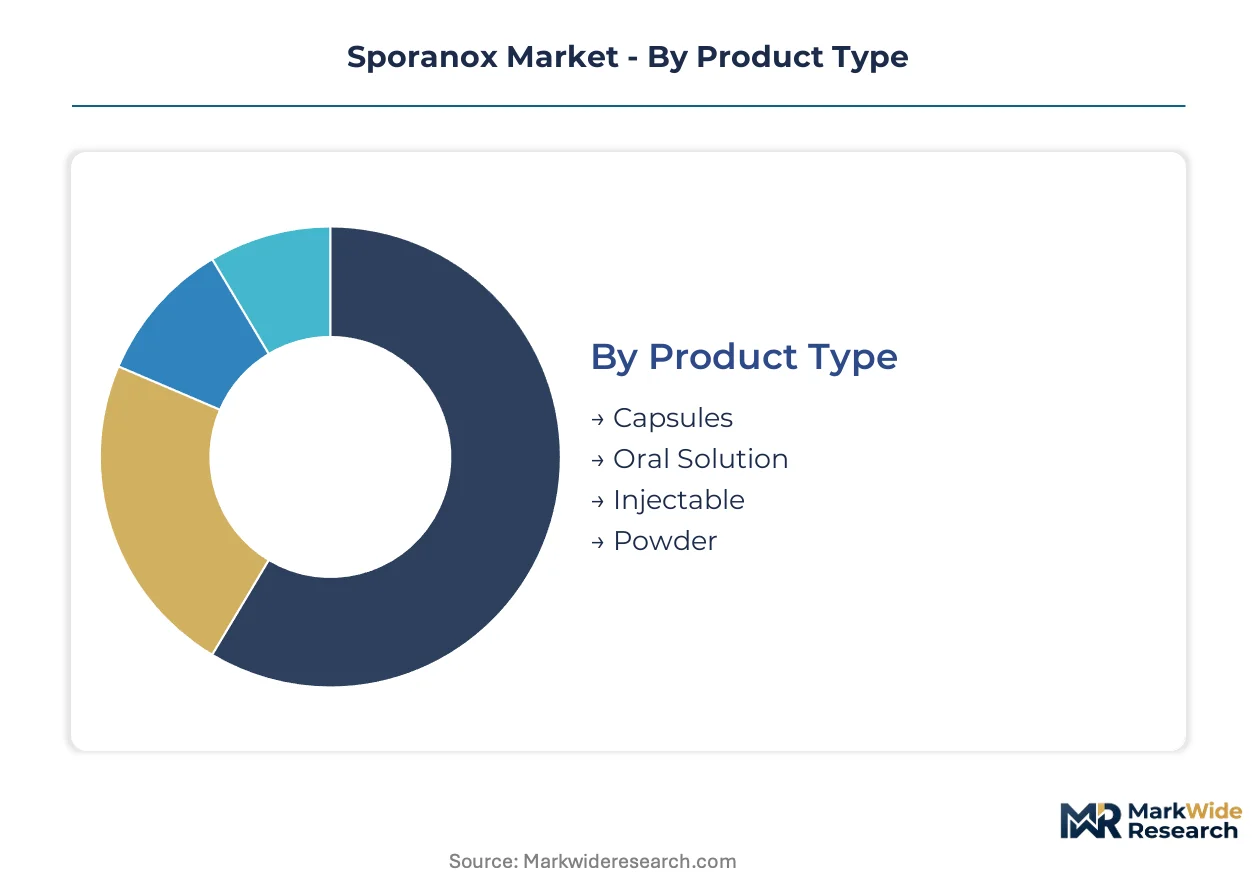
Segmentation in the Sporanox market determines manufacturing investment priorities, regulatory pathway selection, and distribution channel configuration. Each dimension—product form, clinical indication, care setting, and administration route—carries distinct margin profiles and compliance burdens that reshape competitive positioning.
Product Type:
Capital intensity varies sharply across manufacturing modalities, with sterile injectable facilities demanding the highest upfront investment while oral solids leverage depreciated infrastructure.
- Capsules:Pellet-in-capsule formulations with pH-dependent dissolution profiles require specialized coating equipment and stability chambers. Hospital pharmacies in the United States concentrate procurement here for outpatient compliance, though proton pump inhibitor co-administration complicates absorption predictability.
- Oral Solution:Liquid formulations with weight-based titration flexibility absorb development resources for immunocompromised populations. Pediatric oncology and HIV treatment centers in tertiary care settings drive demand concentration where capsule swallowing fails.
- Injectable:Cyclodextrin-complexed itraconazole for intravenous infusion demands aseptic manufacturing suites and endotoxin control systems.
- Powder:Bulk API for compounding pharmacies and regional formulation houses requires fermentation-derived starting material and micronization capacity.
Capsules absorb the bulk of installed capacity; oral solution is expanding most quickly.
Application:
Clinical indication shapes pricing power and reimbursement intensity, with systemic mycoses commanding premium formulary placement against cosmetic-adjacent conditions facing stricter prior authorization.
- Fungal Infections:Broad-spectrum prophylaxis and treatment protocols in transplant and oncology units generate recurring volume. Medicare reimbursement policies in the United States influence prescribing thresholds for systemic therapy initiation.
- Onychomycosis:Dermatology-focused indications retain branded pricing power against generic erosion where diagnostic confirmation via KOH preparation or culture justifies therapy. Telemedicine platforms are extending reach into underserved suburban markets with limited podiatry access.
- Aspergillosis:Invasive mold infections in hematologic malignancy patients require therapeutic drug monitoring and specialist stewardship oversight.
- Histoplasmosis:Endemic mycoses in Ohio and Mississippi River valleys trigger public health procurement programs referencing WHO Essential Medicines List inclusion.
Fungal infections absorb the bulk of installed capacity; onychomycosis is climbing the fastest.
End User:
Customer type determines contracting leverage and clinical support requirements, with integrated delivery networks consolidating purchasing decisions away from individual physician discretion.
- Hospitals:Formulary committees under infectious disease pharmacy specialists concentrate procurement of branded and generic itraconazole. Automatic substitution laws at the state level in the United States compress branded dispensing rates.
- Clinics:Outpatient infusion centers and specialty practices manage oral step-down therapy after inpatient stabilization.
- Home Healthcare:Visiting nurse administration of oral solutions and adherence packaging for polypharmacy patients extends therapy continuity post-discharge.
- Pharmaceutical Companies:API procurement for generic formulation and export to low-income markets with WHO-prequalified supply requirements.
Hospitals absorb the bulk of installed capacity; home healthcare is gaining share fastest.
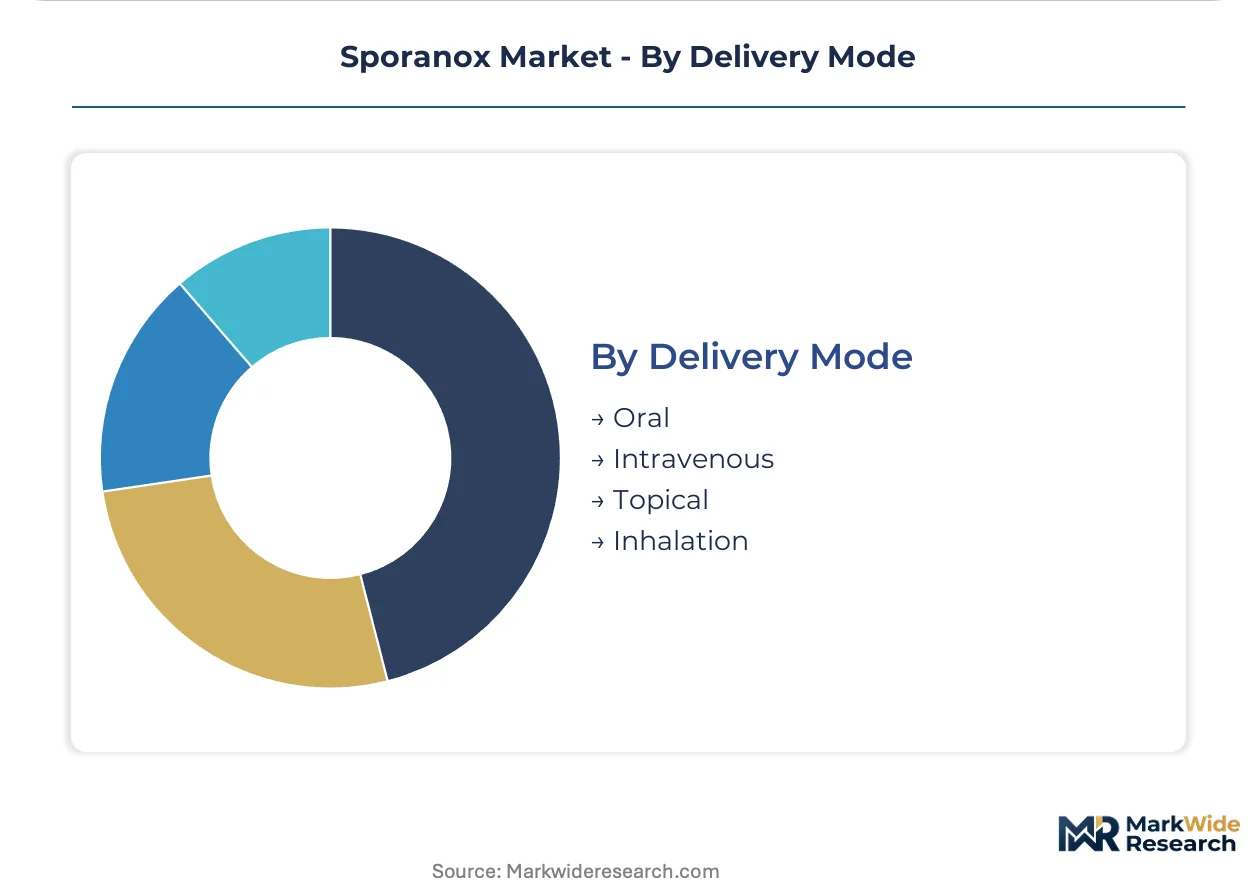
Delivery Mode:
Administration route selection follows patient acuity and gastrointestinal functional status, with parenteral options reserved for severe or malabsorptive presentations.
- Oral:Capsule and solution formulations dominate outpatient maintenance therapy. Gastric acid monitoring requirements complicate co-administration with H2 blockers and proton pump inhibitors in polypharmacy populations.
- Intravenous:Cyclodextrin-solubilized itraconazole for patients with impaired absorption or critical illness demands infusion center capacity and therapeutic drug monitoring infrastructure.
- Topical:Limited penetration for itraconazole given systemic indication focus; nail lacquer formulations compete with oral therapy in mild onychomycosis.
- Inhalation:Investigational nebulized formulations for pulmonary aspergillosis prophylaxis in lung transplant protocols.
Oral delivery absorbs the bulk of installed capacity; intravenous is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity clusters in coastal China and select Indian manufacturing zones anchor azole API supply security for itraconazole formulations worldwide. National procurement policies and reimbursement frameworks reshape demand concentration across major pharmaceutical markets.
United States
Medicare reimbursement thresholds for systemic fungal infections drive hospital formulary placement decisions in tertiary care centers. FDA bioequivalence requirements for generic itraconazole compress branded dispensing rates under state-level automatic substitution laws. The Ohio and Mississippi River valleys concentrate histoplasmosis treatment demand, anchoring public health procurement programs.
Germany
Integrated delivery networks under statutory health insurance consolidate antifungal stewardship decisions under infectious disease pharmacy specialists. EMA centralized marketing authorization procedures govern itraconazole distribution across European member states. The Rhine-Ruhr pharmaceutical manufacturing corridor hosts formulation facilities serving hospital procurement tenders.
India
CDSCO accelerated approval pathways for essential medicines enable domestic manufacturers with WHO-prequalified APIs to capture low-income market supply contracts. National procurement programs reference itraconazole inclusion on the WHO Essential Medicines List for endemic mycoses. Hyderabad and Ahmedabad fermentation clusters supply active pharmaceutical ingredient to regional formulation houses.
Japan
PMDA marketing authorization requirements for azole antifungals maintain stringent pharmacovigilance standards for drug-drug interaction surveillance. Reimbursement pricing under the national health insurance system influences prescribing patterns for systemic mycoses in hematology and transplant units. The Kanto region concentrates hospital pharmacy procurement decisions for antifungal prophylaxis protocols.
Brazil
ANVISA regulatory requirements for generic bioequivalence shape competitive entry for itraconazole capsules in the private pharmacy channel. Public health programs for endemic mycoses in the Amazon basin and southeastern states channel demand toward oral solution formulations. São Paulo-based hospital networks consolidate purchasing leverage for branded and generic antifungal therapies.
Sporanox Market Competitive Landscape
Backward integration into fermentation-based azole production dominates the current landscape as manufacturers secure API supply continuity against regional environmental enforcement risks. The market structure concentrates around three strategic archetypes: integrated pharmaceutical conglomerates with captive fermentation capacity, specialty generics houses competing on cost-engineered formulations, and innovation-focused developers of sustained-release delivery technologies. M&A activity and multi-source API contracting represent the two principal competitive moves reshaping supply security.
Among integrated pharmaceutical conglomerates, Merck & Co. and Janssen Pharmaceuticals occupy positions defined by backward integration into fermentation-based production and patent-protected formulation technologies. Teva Pharmaceutical Industries Ltd. exemplifies the specialty generics archetype, competing on cost-engineered capsule formulations for price-sensitive hospital tenders. These three anchors illustrate the tiered competitive structure where supply security, formulation differentiation, and cost engineering represent distinct strategic vectors.
| Leading Market Players |
|---|
| Merck & Co. |
| Astellas Pharma |
| Janssen Pharmaceuticals |
| Novartis AG |
| Gilead Sciences |
| Johnson & Johnson |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Bristol-Myers Squibb |
| Others |
Pricing and Supply Chain Analysis
Backward integration into fermentation-based azole production anchors both supply security and pricing power for itraconazole manufacturers, with Merck & Co. and Janssen Pharmaceuticals leveraging captive API capacity to defend margin structures against generic erosion while Teva Pharmaceutical Industries Ltd. competes on cost-engineered formulations for price-sensitive hospital tenders.
Pricing Analysis
Service-bundling separates branded formulations with therapeutic drug monitoring support from unbundled generic capsules competing purely on unit cost. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation complexity and stewardship services, with pellet-in-capsule technology commanding premium placement. Pricing pressure stems from state-level automatic substitution laws compressing branded dispensing rates in US retail channels. Hospital procurement committees exhibit lowest price sensitivity due to bundled outcomes contracts, while independent retail pharmacies face highest sensitivity to generic unit cost.
Supply Chain Analysis
Single-source vulnerability sits with coastal China fermentation clusters that supply the majority of azole API starting material. Active pharmaceutical ingredient production concentrates in China, India, and select European contract manufacturers, drawing from fermentation-derived starting material, specialized coating equipment, and cyclodextrin complexing agents. Supply chain risk centers on regional environmental enforcement actions disrupting fermentation capacity. Distribution runs through hospital procurement committees, integrated delivery networks, and wholesale distributors serving retail pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
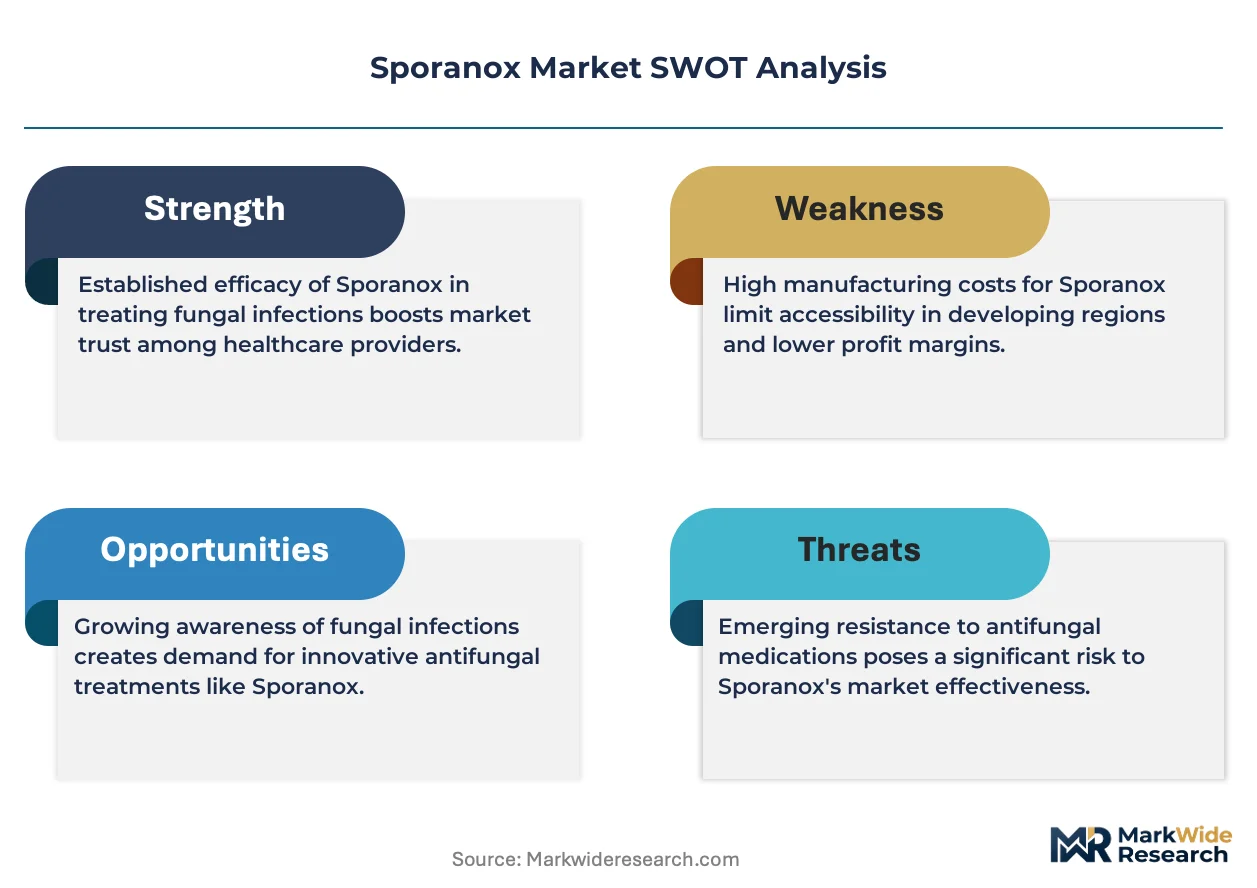
This market consolidates around manufacturers with captive fermentation capacity as FDA bioequivalence requirements and hospital procurement centralization force out API-dependent generics players lacking supply security.
For Market Incumbents: To counter generic substitution mandates eroding branded dispensing rates, Merck & Co. and Janssen Pharmaceuticals should deepen backward integration into fermentation-based azole production and invest in sustained-release formulation patents that extend effective half-life. Captive API supply and pellet-in-capsule technology with pH-dependent dissolution profiles represent the critical defensive levers against cost-engineered competitors. For New Entrants and Emerging Players: CDSCO accelerated approval pathways in India open a window for domestic manufacturers with WHO-prequalified APIs to capture low-income market supply contracts for endemic mycoses. Oral solution pediatric dosing for immunocompromised populations and telemedicine dermatology channels for onychomycosis diagnosis represent the most penetrable white-space targets, with weight-based titration flexibility as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated pharmaceutical conglomerates seeking fermentation capacity and formulation expertise. Five-to-ten year viability favors manufacturers with backward integration and sustained-release patent portfolios over pure-play generic houses exposed to pricing compression. The signal to watch is consolidation velocity among hospital procurement committees as integrated delivery networks concentrate purchasing leverage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive azole API production insulates against coastal China environmental enforcement disruptions. |
| Sustained-Release Formulation Patent Extension | Pellet-in-capsule technology with pH-dependent dissolution defends premium positioning against generic erosion. |
| Oral Solution Pediatric Development | Liquid formulations with weight-based titration capture immunocompromised oncology and HIV populations. |
| Telemedicine Dermatology Channel Partnership | Remote onychomycosis diagnosis expands reach into underserved suburban markets with limited podiatry access. |
| CDSCO Accelerated Approval Pathway Entry | Streamlined Indian regulatory review enables faster market entry for WHO-prequalified API manufacturers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews spanning drug development executives at major pharmaceutical conglomerates, regulatory affairs leads navigating FDA bioequivalence requirements, hospital formulary directors managing antifungal stewardship programs, and procurement managers at integrated delivery networks. FDA filings, EMA submissions, ClinicalTrials.gov entries, and WHO Essential Medicines List documentation provided secondary validation. Bottom-up patient population modeling and top-down pharmaceutical market sizing were triangulated to cross-verify volume and value estimates.
Segment-level granularity modeled product type across capsules, oral solution, injectable, and powder formulations; application across fungal infections, onychomycosis, aspergillosis, and histoplasmosis; end user across hospitals, clinics, home healthcare, and pharmaceutical companies; and delivery mode across oral, intravenous, topical, and inhalation routes. CAGRs were derived through regression analysis of historical pricing and volume trajectories, incorporating immunocompromised patient expansion trends and Medicare reimbursement policy evolution as key forecast inputs across the projection horizon.
The model assumes a particular technology adoption path for nanostructured lipid carrier systems; alternative pathways for conventional pellet-in-capsule formulations would alter the outlook if bioavailability engineering fails to demonstrate clinical superiority. Forecasts reflect assumptions regarding fermentation capacity continuity, regulatory scrutiny intensity for azole drug-drug interactions, and hospital formulary consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Germany Diabetes Drugs Market
Pharmaceuticals
North America Anesthesia Drugs Market
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
Hyperphosphatemia Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Skin Cancer Drugs Market
Pharmaceuticals
Veterinary Pain Management Drugs Market
Pharmaceuticals
Albinism Drugs Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Riociguat Tablets Market
Pharmaceuticals
Clozapine Market
Pharmaceuticals
Theophylline and Aminophylline Market
Pharmaceuticals
Drug Delivery Market
Pharmaceuticals
Global Hedgehog Pathway Inhibitors Market
Pharmaceuticals
Systemic Lupus Erythematous SLE Drugs Market