
 India Nicotine Replacement Therapy Market | 2026-2036
India Nicotine Replacement Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
India Nicotine Replacement Therapy Market Insights
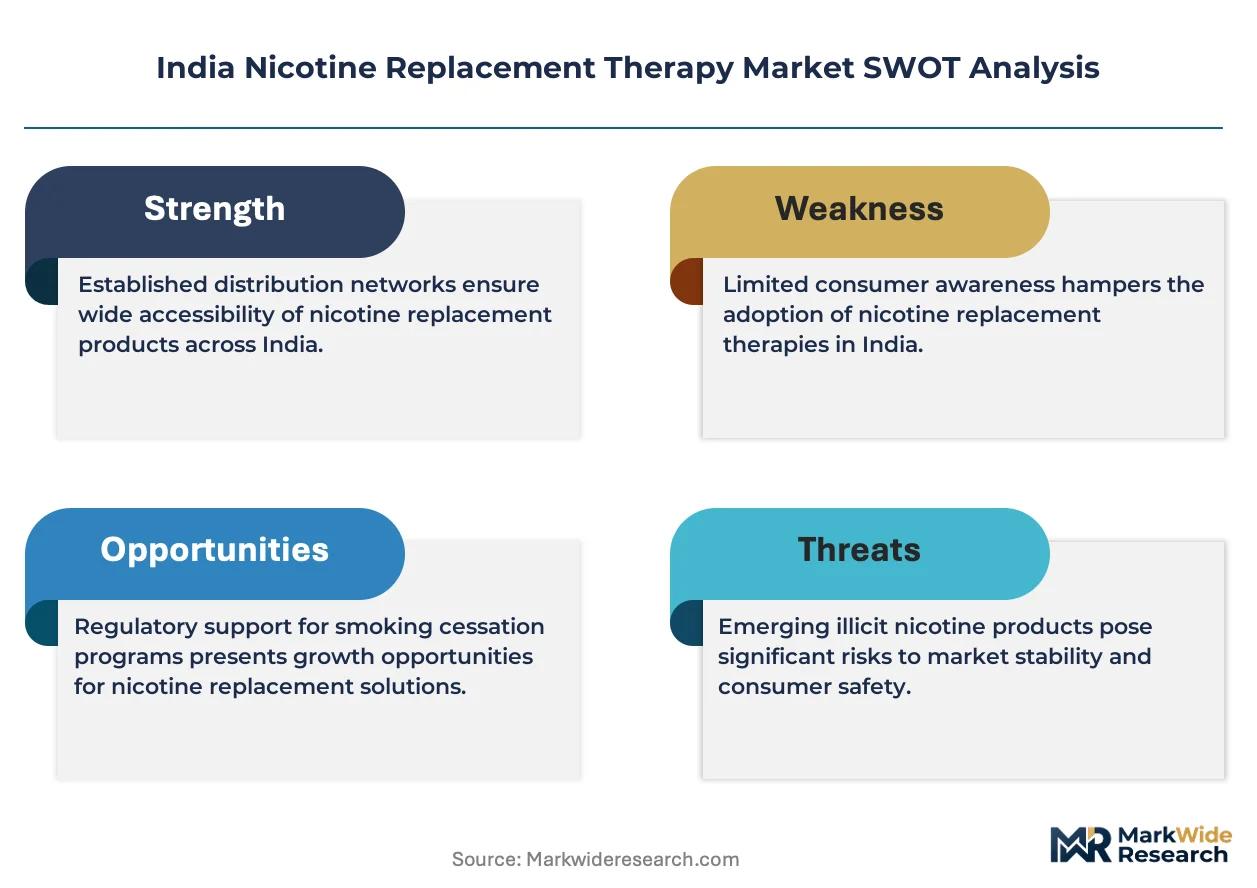
Capital-intensity divergence between multinational pharmaceutical conglomerates and domestic generic manufacturers is redrawing competitive boundaries in India's NRT landscape. Johnson & Johnson Services, Inc. leverages its transdermal patch manufacturing infrastructure to sustain premium positioning across urban pharmacy networks. Piramal Pharma Limited anchors its portfolio through oral gum and lozenge formulations that compete aggressively on price in tier-2 and tier-3 cities.
Nicotine Replacement Therapy denotes pharmacological interventions delivering controlled nicotine doses through transdermal, oral, or inhalation routes to alleviate withdrawal symptoms during tobacco cessation, with patches typically releasing 7–21 mg nicotine over 16–24 hours and gums containing 2–4 mg per piece for buccal absorption. The gum segment dominates volume through over-the-counter accessibility and familiar chewing mechanics, while transdermal patches capture margin pools through extended-release technology and higher compliance rates among hospital-directed patients. Online retail channels represent the fastest-growing delivery pathway as telemedicine platforms and e-pharmacy aggregators expand beyond metropolitan boundaries into state capitals and district headquarters.
The Ministry of Health and Family Welfare operates India's National Tobacco Control Programme, while CDSCO governs NRT product licensing and quality standards under the Drugs and Cosmetics Act, and state food and drug administrations enforce retail distribution compliance. These overlapping frameworks elevate manufacturing standards for transdermal adhesive consistency and nicotine dose accuracy while restricting unapproved spray formulations from market entry. Stakeholders must monitor how proposed amendments to COTPA advertising restrictions reshape physician-directed versus direct-to-consumer channel strategies.
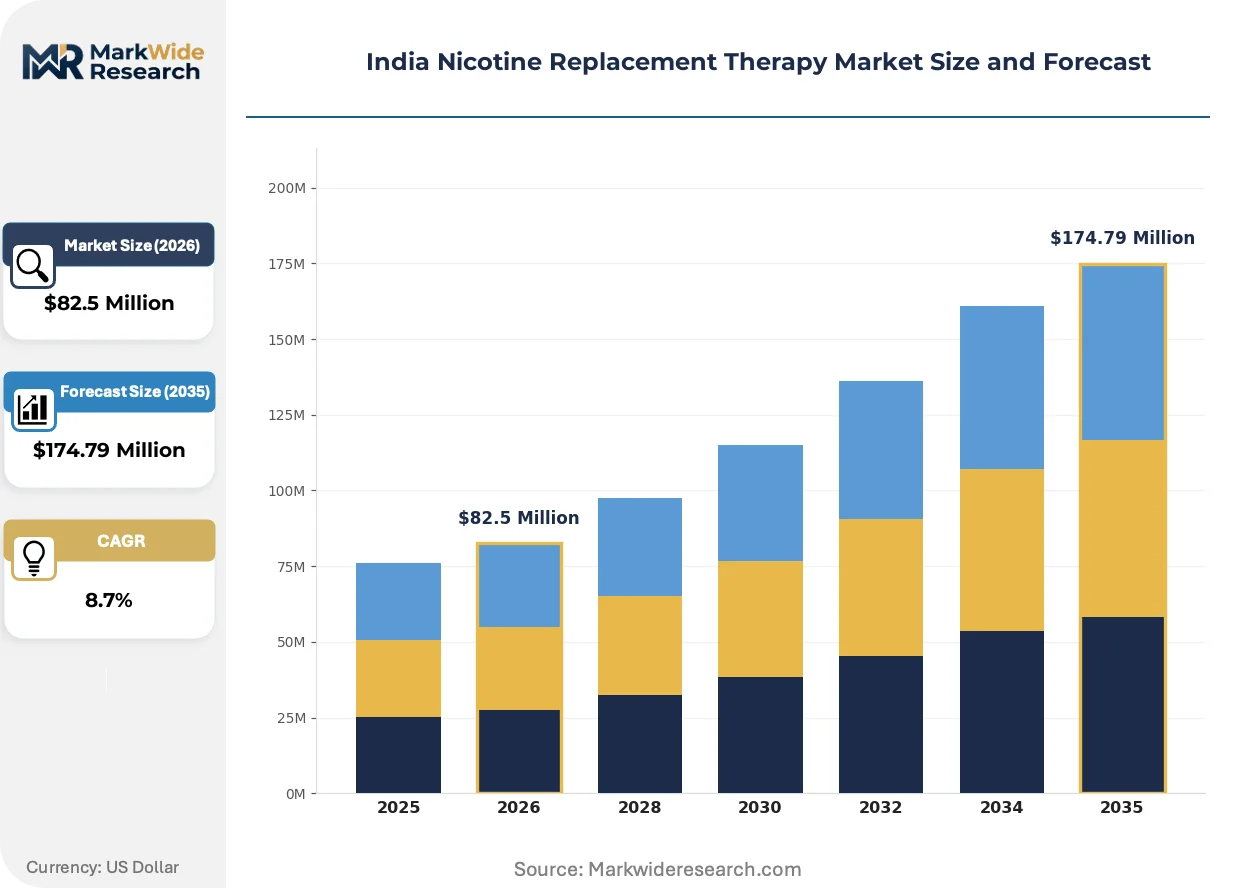
Market Dynamics
The Cigarettes and Other Tobacco Products Act (COTPA) enforcement expansion and CDSCO's tightening of transdermal patch quality standards are compressing informal nicotine product channels while legitimizing pharmacy-dispensed NRT formats across Maharashtra, Karnataka, and Tamil Nadu.
Growth Catalysts
- State-level cessation infrastructure:Maharashtra and Karnataka have integrated NRT dispensing into district hospital outpatient programs, creating institutional demand pipelines that bypass retail friction.
- Telemedicine platform expansion:E-pharmacy aggregators now deliver patches and gums to 42 district headquarters beyond Mumbai and Delhi, collapsing geographic access barriers.
- COTPA advertising prohibitions:The ban on tobacco promotion redirects consumer attention toward cessation messaging in urban media markets, elevating NRT brand recall.
Market Restraints
- Transdermal adhesive input concentration:Domestic manufacturers depend on imported pressure-sensitive adhesive polymers from German and Japanese specialty chemical suppliers, exposing margins to currency volatility.
- Gum base supply bottleneck:Two Indian excipient processors control 70% of pharmaceutical-grade gum base production, creating single-source vulnerability for lozenge and gum formulators.
- CDSCO spray formulation exclusion:The regulator's refusal to license nicotine nasal sprays eliminates a high-absorption format that commands premium pricing in European markets.
Strategic Opportunities
- Tier-3 city pharmacy networks:District-level medical stores in Uttar Pradesh and Bihar remain unserved by NRT distribution, presenting first-mover expansion terrain for oral format specialists.
- National Tobacco Control Programme integration:Proposed amendments would reimburse NRT costs through state health insurance schemes, converting out-of-pocket purchases into institutional procurement.
- Patch-gum combination protocols:Hospital-directed tapering programs that layer transdermal baseline dosing with breakthrough gum administration are displacing monotherapy prescriptions in Delhi's tertiary care centers.
Industry Challenges
- Pharmaceutical polymer formulation expertise:The specialized knowledge required for 16-hour release-rate engineering in transdermal matrices is concentrated among fewer than 12 Indian formulation scientists.
- CDSCO batch release timelines:Nicotine potency variance testing adds 8-14 weeks to product registration cycles, delaying market entry for reformulated SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Nicotine Replacement Therapy Market |
| Market Size in 2026 | $82.5 Million |
| Market Size in 2035 | $174.79 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gum, Patch, Lozenge, Inhaler Delivery Mode: Transdermal, Oral, Inhalation, Spray End User: Pharmacies, Hospitals, Clinics, Online Retail Price Tier: Premium, Mid-range, Economy, Discounted |
| Companies Covered | Johnson & Johnson Services, Inc., Piramal Pharma Limited, Glenmark Pharmaceuticals Ltd., Rubicon Consumer Healthcare Pvt. Ltd., ITC Limited, Cipla Inc., Fertin Pharma, INVENTZ Lifesciences, Rusan Pharma Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Nicotine Replacement Therapy Market Trends and Innovations
Product format diversification and channel digitization are fragmenting the traditional pharmacy-centric NRT model, with technology-enabled adherence tools and policy-mandated cessation support reshaping how nicotine dependence is treated.
Extended-release transdermal matrix technology is displacing reservoir-type patch designs in hospital procurement specifications. CDSCO-registered manufacturers in Hyderabad and Ahmedabad are adopting multilaminate adhesive systems that maintain 21 mg plasma concentration curves across 24-hour wear periods. This shift is compressing demand for older peel-and-stick formats that required twice-daily application.
The Ministry of Health and Family Welfare's proposed COTPA amendment to mandate pictorial health warnings covering 85% of tobacco packaging is accelerating state-funded cessation campaign budgets. Karnataka's health department has already allocated dedicated NRT procurement lines to district tobacco cessation clinics. Oral format suppliers are responding by redesigning lozenge packaging for clinic dispensary compatibility rather than retail shelf appeal.
Urban consumers are consolidating purchases through subscription-based telemedicine platforms that bundle NRT with behavioral counseling. Practo and 1mg now offer 12-week cessation programs with automated patch refills, displacing episodic pharmacy visits in Mumbai and Bengaluru. This channel shift is most pronounced among 25-40 year-old professionals in IT and financial services sectors who prioritize discretion and adherence tracking over price sensitivity.
India Nicotine Replacement Therapy Market Segmentation
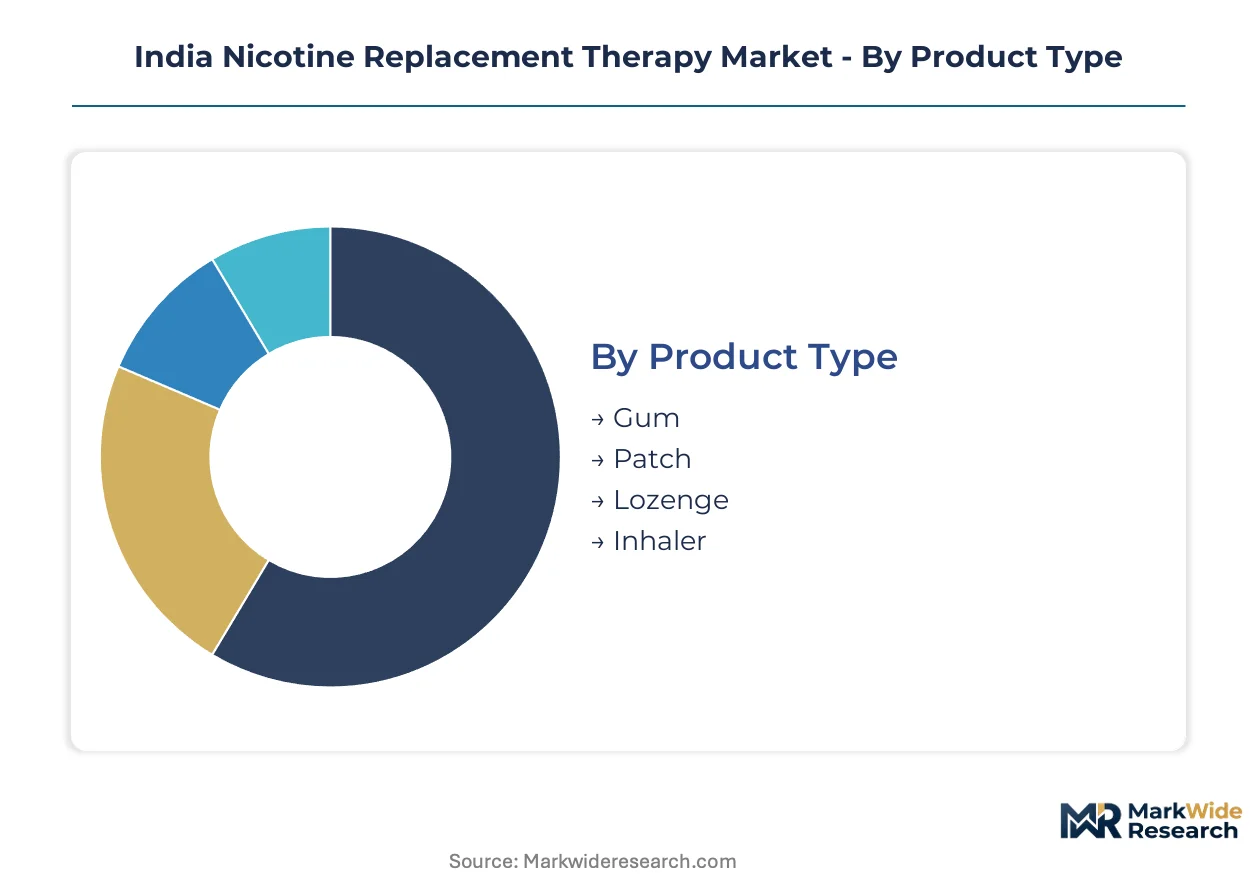
NRT segmentation in India reflects a market caught between institutional procurement standards and mass-market accessibility. Product formats, delivery modes, and channel strategies diverge sharply across state-level health infrastructure and urban retail networks.
Product Type:
Gum and patch formats dominate domestic manufacturing capacity, while lozenge production serves both local consumption and limited export orders to South Asian markets. Inhaler assembly remains import-dependent.
- Gum:Chewing-based delivery systems containing 2–4 mg nicotine per piece for buccal absorption through the oral mucosa. Maharashtra and Karnataka's district hospital outpatient programs source gum in bulk for cessation clinic dispensing, driven by over-the-counter accessibility and familiar administration mechanics that reduce patient training costs.
- Patch:Transdermal adhesive systems releasing 7–21 mg nicotine across 16–24 hour wear periods. Delhi and Mumbai's tertiary care centers specify extended-release matrix designs in procurement tenders, with CDSCO-registered Hyderabad and Ahmedabad manufacturers supplying multilaminate formats that displace older reservoir-type designs.
- Lozenge:Slow-dissolving oral tablets providing controlled nicotine release. Domestic excipient processors in Gujarat and Tamil Nadu supply pharmaceutical-grade gum base for lozenge production.
- Inhaler:Cartridge-based pulmonary delivery devices. Complete device assembly relies on imported mouthpiece components and metering valve technology.
Gum commands the established base. The steepest expansion runs through patch formats as hospital procurement specifications upgrade to extended-release matrix technology.
Delivery Mode:
Oral and transdermal routes absorb nearly all domestic demand, while spray formulations remain excluded from commercialization. Inhalation delivery occupies a narrow niche through specialized clinic protocols.
- Transdermal:Skin-absorbed nicotine delivery through adhesive patches. Karnataka and Tamil Nadu's state health departments specify transdermal protocols for district tobacco cessation clinics, with procurement volumes climbing as institutional reimbursement frameworks mature.
- Oral:Buccal and sublingual absorption via gum, lozenge, or tablet formats. Tier-2 and tier-3 city pharmacies across Uttar Pradesh and Bihar stock oral formats as their primary NRT inventory, given cold-chain independence and lower price points.
- Inhalation:Pulmonary delivery through handheld devices. Mumbai's private hospital networks prescribe inhalers for patients with oral mucosal sensitivity or patch adhesive allergies.
- Spray:Nasal or oral mucosal spray delivery. CDSCO's refusal to license nicotine nasal sprays blocks market entry despite premium pricing benchmarks in European regulatory environments.
Oral delivery anchors volume throughput. Transdermal formats are climbing the fastest as hospital-directed tapering programs displace retail self-selection.
End User:
Channel concentration varies sharply across India's urban-rural divide, with institutional procurement in Maharashtra and Karnataka contrasting against pharmacy-dependent access in northern and eastern states.
- Pharmacies:Brick-and-mortar retail dispensaries across organized chains and independent medical stores. Mumbai and Delhi's urban pharmacy networks maintain dedicated NRT shelving, while district headquarters in 42 secondary cities now receive patch and gum shipments through expanding distribution.
- Hospitals:Tertiary and district-level healthcare facilities with integrated cessation services. Maharashtra's National Tobacco Control Programme integration has established dedicated NRT procurement lines to outpatient departments.
- Clinics:Specialized tobacco cessation and respiratory health centers. Bengaluru's private clinic networks bundle behavioral counseling with 12-week NRT protocols.
- Online Retail:E-pharmacy aggregators and telemedicine subscription platforms. Practo and 1mg now automate patch refills for IT and financial services professionals aged 25–40 who prioritize discretion.
Pharmacies retain the volume base. Online retail is gaining share fastest as telemedicine platforms collapse geographic access barriers beyond metropolitan boundaries.
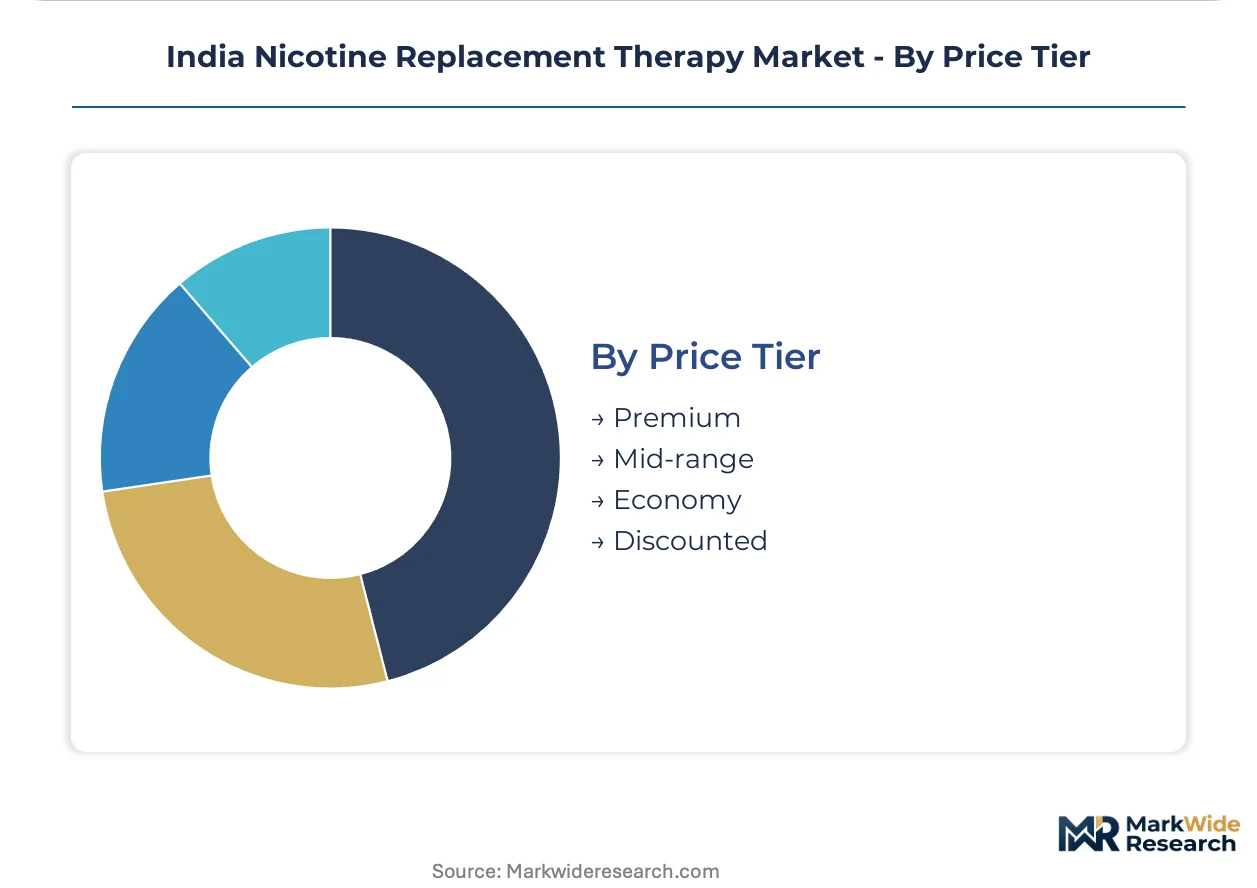
Price Tier:
Pricing stratification maps directly to channel positioning, with premium tiers capturing hospital procurement and economy tiers penetrating unserved district markets.
- Premium:Transdermal patches with 24-hour extended-release matrix technology and hospital-grade packaging. Johnson & Johnson Services maintains premium positioning through urban pharmacy network presence and clinician detailing programs.
- Mid-range:Standard gum and lozenge formats with established brand recognition. Piramal Pharma Limited competes aggressively in this tier across tier-2 and tier-3 cities.
- Economy:Generic gum formulations and older patch designs with shorter wear periods. Uttar Pradesh and Bihar's district medical stores source economy-tier oral formats as first NRT inventory.
- Discounted:Subsidized or bulk-procured supplies through state health insurance schemes. Proposed National Tobacco Control Programme amendments would expand this tier through institutional reimbursement.
Mid-range formats command current volume leadership. Premium tiers are expanding most quickly as hospital procurement specifications tighten and extended-release technology displaces older designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra and Karnataka deploy NRT through district hospital networks, while northern states rely on pharmacy retail. This institutional-versus-retail split defines India's regional consumption architecture.
Maharashtra
Mumbai's tertiary care centers anchor patch procurement through extended-release matrix specifications. The state's National Tobacco Control Programme integration has established dedicated NRT dispensing lines at district hospital outpatient departments. Pune and Nagpur medical clusters supply multilaminate transdermal formats to cessation clinics across western Maharashtra.
Karnataka
Bengaluru's private clinic networks bundle behavioral counseling with 12-week NRT protocols for IT sector professionals. The state health department has allocated dedicated procurement budgets to district tobacco cessation clinics. Mysuru and Hubballi pharmaceutical distributors now stock hospital-grade lozenge packaging designed for dispensary compatibility.
Delhi-NCR
Urban hospital pharmacies in Delhi have expanded NRT dispensing programs with patch-gum combination tapering protocols. CDSCO's centralized regulatory oversight accelerates product registration for manufacturers supplying the capital region. Gurugram and Noida telemedicine platforms automate refill subscriptions for financial services professionals aged 25-40.
Tamil Nadu
Chennai's state health infrastructure specifies transdermal protocols for district tobacco cessation clinics. CDSCO-registered manufacturers in Hyderabad supply extended-release matrix patches to Tamil Nadu procurement tenders. Coimbatore's medical device clusters assemble inhaler mouthpieces for specialized clinic protocols treating oral mucosal sensitivity.
Uttar Pradesh
District medical stores in Lucknow and Kanpur remain unserved by NRT distribution networks, presenting first-mover expansion terrain. Cold-chain independence of oral formats drives pharmacy stocking decisions across tier-3 cities. Varanasi and Prayagraj excipient processors supply pharmaceutical-grade gum base for lozenge manufacturers targeting economy-tier pricing.
India Nicotine Replacement Therapy Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in India's NRT landscape. Multinational pharmaceutical conglomerates leverage transdermal manufacturing infrastructure to sustain premium positioning across urban pharmacy networks. Domestic generic manufacturers anchor portfolios through oral formulations that compete aggressively on price in tier-2 and tier-3 cities. Capacity expansion and portfolio diversification represent the dominant competitive moves as players respond to state-level institutional procurement growth.
Within the multinational tier, Johnson & Johnson Services, Inc. occupies a position exemplifying premium transdermal positioning through urban pharmacy network presence. Piramal Pharma Limited represents the domestic generic archetype, competing across tier-2 and tier-3 cities through oral gum and lozenge formulations. Glenmark Pharmaceuticals Ltd. sits within the mid-market specialist tier, bridging hospital procurement specifications with retail accessibility.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Piramal Pharma Limited |
| Glenmark Pharmaceuticals Ltd. |
| Rubicon Consumer Healthcare Pvt. Ltd. |
| ITC Limited |
| Cipla Inc. |
| Fertin Pharma |
| INVENTZ Lifesciences |
| Rusan Pharma Ltd. |
| Others |
Pricing and Supply Chain Analysis
Domestic patch manufacturing at CDSCO-registered Hyderabad and Ahmedabad facilities operates at suboptimal scale, compressing margins and forcing oral format competitors to absorb excipient cost volatility while anchoring price floors through gum base sourcing concentration.
Pricing Analysis
Subscription-based telemedicine bundling drives lifetime value through automated refill adherence programs that layer behavioral counseling with product delivery. Three-tier pricing structure across premium, standard, and economy levels separates hospital-grade transdermal matrix patches from retail gum formats and state-subsidized clinic supplies. Cost compression in economy-tier oral formats is intensifying because excipient processors in Gujarat and Tamil Nadu command bottleneck leverage over pharmaceutical-grade gum base. Tier-3 district medical stores in Uttar Pradesh and Bihar exhibit highest price sensitivity, while Mumbai and Delhi hospital procurement shows lowest sensitivity due to institutional reimbursement frameworks.
Supply Chain Analysis
Germany and Japan anchor pressure-sensitive adhesive polymer supply for transdermal patch manufacturers, while domestic excipient processors in Gujarat and Tamil Nadu control pharmaceutical-grade gum base production for oral formats. CDSCO-registered manufacturing draws from imported specialty chemicals and captive domestic gum base processing. Single-source vulnerability concentrates in the two Indian excipient processors controlling seventy percent of gum base output. Distribution runs through state health department procurement lines to district hospitals, layered with e-pharmacy aggregator channels reaching forty-two district headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's NRT market represents early-cycle expansion as state-level cessation infrastructure penetration accelerates institutional procurement beyond metropolitan pharmacy networks.
For Market Incumbents: Fortify hospital-directed channel control by deepening backward integration into transdermal adhesive formulation capability, countering the threat of CDSCO batch release timeline compression that favors manufacturers with in-house polymer expertise. Anchor tier-2 and tier-3 city pharmacy shelf presence through oral format volume commitments that preempt generic entrants from achieving minimum viable distribution. For New Entrants and Emerging Players: CDSCO fast-track registration for multilaminate transdermal matrix designs opens first-mover positioning in Karnataka and Tamil Nadu district tobacco cessation clinic procurement. Target unserved district medical stores in Uttar Pradesh and Bihar with cold-chain-independent oral formats priced at economy tier. Pursue white-label supply contracts with state health insurance schemes as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic manufacturers with CDSCO registration infrastructure and established excipient supplier relationships over pure-play distribution assets. Five-to-ten year viability hinges on National Tobacco Control Programme reimbursement expansion converting out-of-pocket retail purchases into institutional procurement streams. Watch for proposed COTPA amendment passage as inflection signal accelerating state-funded cessation campaign budgets.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Registration Fast-Track | Accelerates market entry for multilaminate transdermal formats ahead of reservoir-type obsolescence. |
| State Health Insurance Integration | Converts out-of-pocket pharmacy purchases into institutional procurement through National Tobacco Control Programme amendments. |
| Telemedicine Platform Partnership | Captures 25-40 year-old professional segment through Practo and 1mg subscription bundling. |
| Backward Integration into Gum Base | Reduces single-source vulnerability to Gujarat and Tamil Nadu excipient processor concentration. |
| District Hospital Outpatient Expansion | Establishes institutional demand pipelines in Maharashtra and Karnataka that bypass retail friction. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with CDSCO regulatory affairs leads, hospital procurement managers at Mumbai and Delhi tertiary care centers, state health department formulary directors, and e-pharmacy aggregator supply chain heads; and secondary validation through CDSCO product registration databases, National Tobacco Control Programme budget allocations, Drugs and Cosmetics Act enforcement records, and Maharashtra and Karnataka state health department procurement tenders. Bottom-up volume triangulation across product format, delivery mode, and channel segmentation intersected with top-down value reconciliation against Ministry of Health expenditure patterns.
Across the analysis window, the forecasting framework modeled patient population segmentation by cessation protocol intensity, product format technology tier, institutional versus retail channel mix, and state-level reimbursement maturity. CAGRs derived from segment-level volume buildups calibrated to CDSCO registration pipeline visibility and state health insurance scheme expansion trajectories. Key inputs included district hospital outpatient program rollout schedules and telemedicine platform geographic expansion announcements.
Decision-makers should treat outputs as directional under assumptions of sustained COTPA enforcement expansion and National Tobacco Control Programme reimbursement amendment passage; material deviation in regulatory timeline or state fiscal capacity would warrant model refresh. Recalibration cycles align with material shifts in CDSCO registration policy, state health budget allocations, and transdermal adhesive import tariff adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Chickenpox Vaccine Market
Pharmaceuticals
Rheumatology Therapeutics Market
Pharmaceuticals
United Kingdom (UK) Diabetes Drugs Market
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market
Pharmaceuticals
OTC Analgesic Market
Pharmaceuticals
Meperidine Drugs Market
Pharmaceuticals
Bone Degeneration Therapeutics Market
Pharmaceuticals
Pregnenolone Market
Pharmaceuticals
Blood Clotting Accelerant Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Global Electronic Aspirin Market
Pharmaceuticals
Tenecteplase Drugs Market
Pharmaceuticals
Global Nasal Drug Delivery Market
Pharmaceuticals
Theophylline and Aminophylline Market
Pharmaceuticals
Pentoxyverine Market