
 Pharmaceutical Pellets Market | 2026-2036
Pharmaceutical Pellets Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Pellets Market Analysis
Modular dosage configurations are shifting buyer preferences across chronic therapy categories, enabling physicians to titrate regimens with precision. Abbott Laboratories leverages its formulation science infrastructure to sustain leadership in multiparticulate delivery systems. Colorcon Inc. anchors its competitive position through specialized coating technologies that control release kinetics. Thexa Pharma differentiates by concentrating on niche therapeutic areas where pellet geometry governs bioavailability outcomes.
Pharmaceutical pellets are spherical or cylindrical multiparticulate units, typically 0.5–2.0 mm in diameter, produced through extrusion-spheronization or fluid-bed layering processes and engineered for uniform drug distribution, controlled dissolution, and reduced gastric irritation. Their primary purpose is to enable precise dosing flexibility, protect acid-labile APIs, and facilitate combination therapies within single capsule formulations. Sustained release pellets command the largest value share due to their centrality in cardiovascular and pain management protocols, while enteric coated variants are capturing accelerated interest as biologic drug pipelines expand. Manufacturing process selection—particularly extrusion-spheronization versus advanced coating methods—determines margin structures, with equipment-intensive operations concentrating among contract manufacturers serving pharmaceutical companies.
FDA current good manufacturing practice enforcement and EMA's updated guidelines on process analytical technology are elevating quality thresholds for pellet production, directly shaping capital allocation decisions among manufacturers. The International Council for Harmonisation Q13 guideline on continuous manufacturing is additionally restructuring batch-release paradigms, favoring facilities with integrated real-time release testing capabilities. Stakeholders must monitor evolving pharmacopeial standards for dissolution testing and particle size distribution, as these specifications will determine market access for next-generation multiparticulate therapies.
Market Dynamics
FDA quality-by-design mandates and EMA process analytical technology guidelines are compressing manufacturing timelines while elevating capital requirements for pellet production facilities.
Growth Catalysts
- Chronic disease protocols:Geriatric care expansion across Germany and Japan is accelerating prescription volumes for multiparticulate cardiovascular and pain management therapies.
- EMA process analytical technology:Real-time release testing adoption is shortening batch approval cycles and reducing quality-control labor intensity.
- Fluid-bed layering:Advanced coating methods for biologic-sensitive APIs are opening new therapeutic categories previously closed to pellet formulations.
Market Restraints
- Equipment capital intensity:Extrusion-spheronization lines require specialized spheronizer bowls and precision extruders that concentrate production among contract manufacturers.
- Microcrystalline cellulose supply:Excipient sourcing dependence on Indian and Chinese suppliers creates input cost volatility and qualification delays.
- ICH Q13 continuous manufacturing:Batch-release paradigm restructuring demands facility redesigns that freeze legacy asset utilization rates.
Strategic Opportunities
- Biologic enteric coatings:Peptide and protein drug pipelines are creating demand for acid-protection pellet architectures in early-phase development.
- Modular dosing flexibility:Physician titration protocols in pain management are favoring capsule formulations with heterogeneous pellet populations.
- CDMO capacity expansion:Germany's pharmaceutical manufacturing corridor is attracting investment in dedicated pellet production suites for mid-size sponsors.
Industry Challenges
- Process analytical technology expertise:Real-time spectroscopy implementation requires cross-functional teams blending formulation science with data analytics capabilities.
- Legacy dissolution testing:USP apparatus migration and in vitro-in vivo correlation studies extend regulatory submission timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Pellets Market |
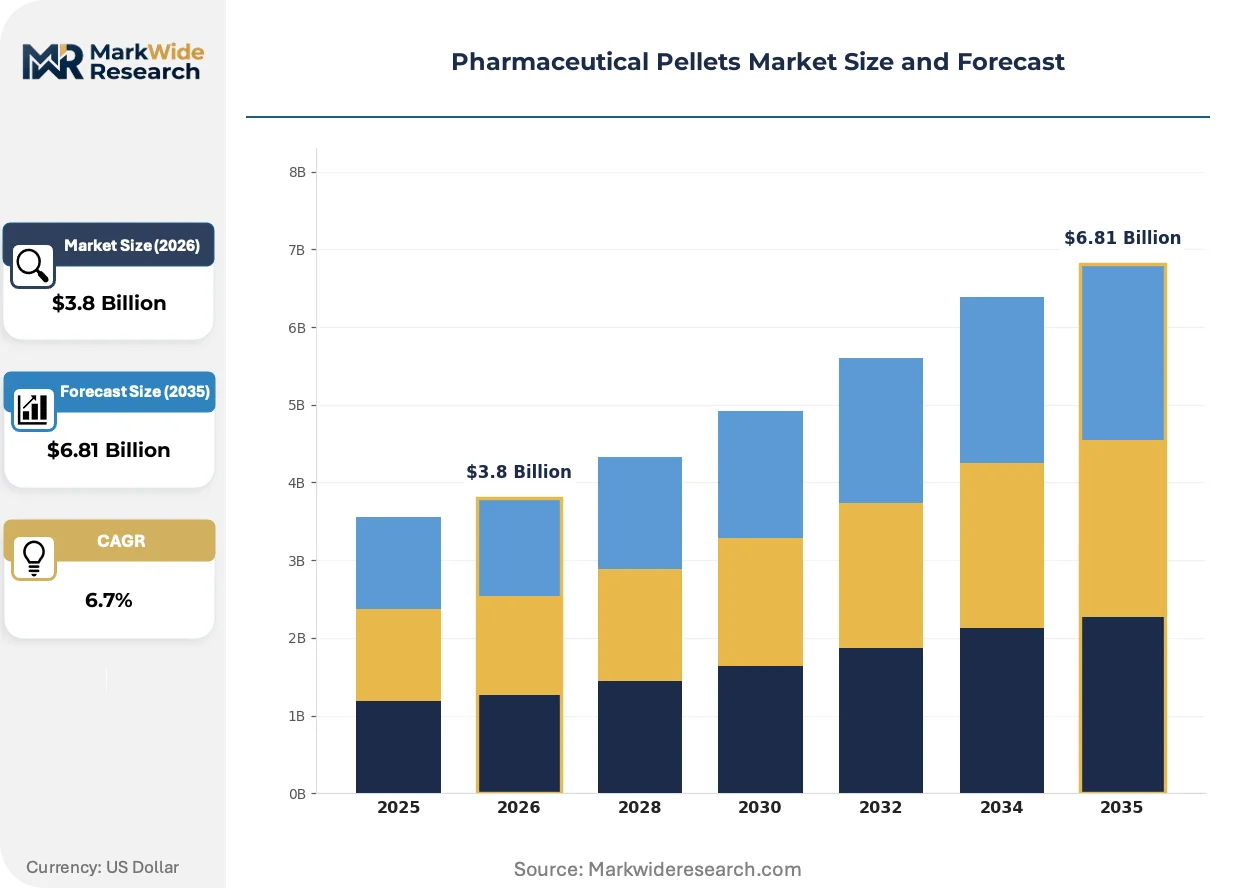
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sustained Release, Immediate Release, Enteric Coated, Delayed Release Delivery Mode: Oral, Injectable, Transdermal, Rectal Manufacturing Process: Extrusion, Spheronization, Granulation, Coating End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutions, Hospitals |
| Companies Covered | Thexa Pharma, Lograns Pharma, Abbott Laboratories, Rainbow Health Care Products, Manus Aktteva Biopharma LLP, Colorcon Inc., Avanscure Lifesciences, Chemit Laboratories, Nordic Sugar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Pellets Market Emerging Trajectories
Multiparticulate manufacturing is pivoting from batch toward continuous processing, with coating technologies and analytical methods converging to reshape quality assurance economics.
Hot-melt extrusion is overtaking conventional wet granulation for heat-stable APIs, enabling solvent-free processing that eliminates drying steps and reduces facility footprint. Cardiovascular drug sponsors are adopting this route for high-volume sustained-release programs. The technology is overtaking legacy methods in margin-sensitive therapeutic categories by compressing cycle times and excipient costs.
EMA's updated guidelines on process analytical technology are mandating real-time release testing for new marketing authorizations, forcing manufacturers to deploy in-line NIR spectroscopy and particle size analyzers. Facilities without integrated quality systems face extended regulatory review periods. Oral solid dose sponsors in the Netherlands and Ireland are restructuring quality organizations to embed PAT scientists within production teams.
Hospital procurement consolidation is compressing supplier qualification timelines, with formulary committees demanding pellet-specific bioequivalence documentation beyond standard ANDA requirements. Integrated delivery networks are replacing independent pharmacy purchasing. This concentration is most visible in US regional health systems where centralized contracting favors manufacturers with dedicated pellet technical services teams.
Pharmaceutical Pellets Market Segmentation
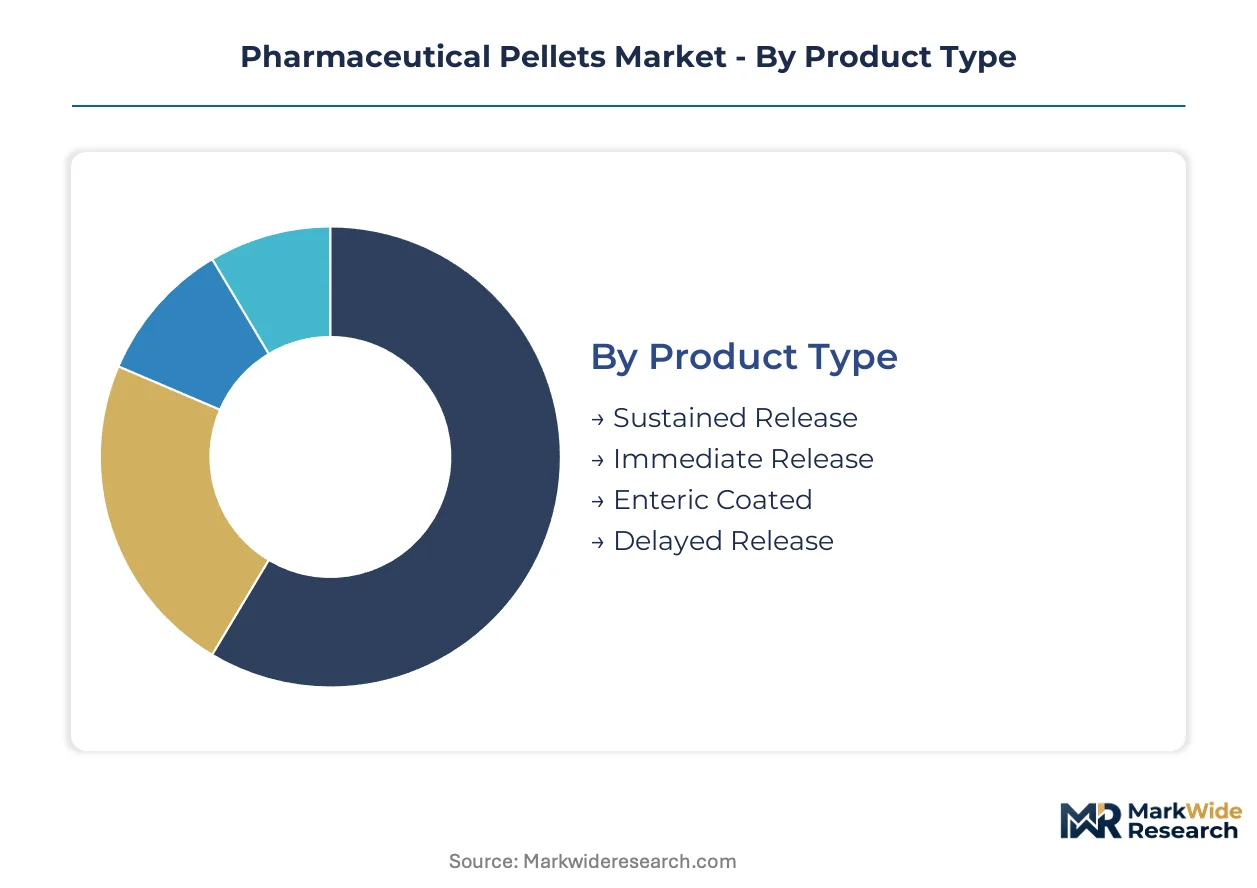
Pellet geometry and release kinetics determine equipment selection, regulatory pathways, and margin structures across therapeutic categories. Segment boundaries reflect manufacturing complexity rather than simple formulation differences.
Product Type:
Capital intensity escalates sharply with coating sophistication, as functional polymer layers demand fluid-bed investment and real-time release testing infrastructure.
- Sustained Release:Matrix or reservoir systems modulate API dissolution through hydrophilic polymer gradients or membrane-controlled diffusion. Cardiovascular and pain management protocols in Germany and Japan concentrate demand for twice-daily-to-once-daily conversion therapies.
- Enteric Coated:pH-responsive polymer films protect acid-labile actives from gastric degradation, requiring precise coating weight control and dissolution validation. Biologic drug pipelines are accelerating interest as peptide formulations seek oral bioavailability.
- Immediate Release:Rapid-disintegrating cores suit dose-flexibility applications and combination therapies.
- Delayed Release:Time-dependent or colonic-targeted systems serve chronotherapeutic indications and localized GI delivery.
Sustained release absorbs the bulk of installed capacity; enteric coated is expanding most quickly.
Delivery Mode:
Oral dominance reflects patient compliance economics, though injectable multiparticulates are commanding premium pricing in long-acting depot formulations.
- Oral:Capsule or sachet administration of pellet populations enables titration flexibility and combination dosing within single units. Hospital procurement consolidation in US regional health systems is demanding pellet-specific bioequivalence documentation beyond standard ANDA requirements.
- Injectable:Biodegradable microsphere suspensions deliver sustained plasma levels for antipsychotic and endocrine therapies.
- Transdermal:Microneedle-assisted or reservoir-type pellet integration remains exploratory.
- Rectal:Pediatric and geriatric applications exploit bypassed hepatic first-pass metabolism.
Oral delivery commands manufacturing floor space; injectable formats are climbing the fastest on value per kilogram metrics.
Manufacturing Process:
Process selection locks in facility economics for decades, with continuous manufacturing mandates reshaping legacy asset valuations.
- Extrusion:Wet or hot-melt forcing of plasticized mass through dies generates uniform cylinders prior to spheronization. FDA quality-by-design enforcement is elevating in-process control requirements for critical quality attribute monitoring.
- Spheronization:Rotational cutting and rounding of extrudate in friction bowls yields dense, low-friability spheres. EMA process analytical technology guidelines are mandating real-time particle size distribution tracking for new marketing authorizations.
- Granulation:Layering or agglomeration methods build pellets from powder seeds in fluid beds.
- Coating:Functional film deposition controls release kinetics, moisture protection, and taste masking.
Extrusion-spheronization pairs retain the largest installed base; coating capacity is gaining share fastest as functional demands intensify.
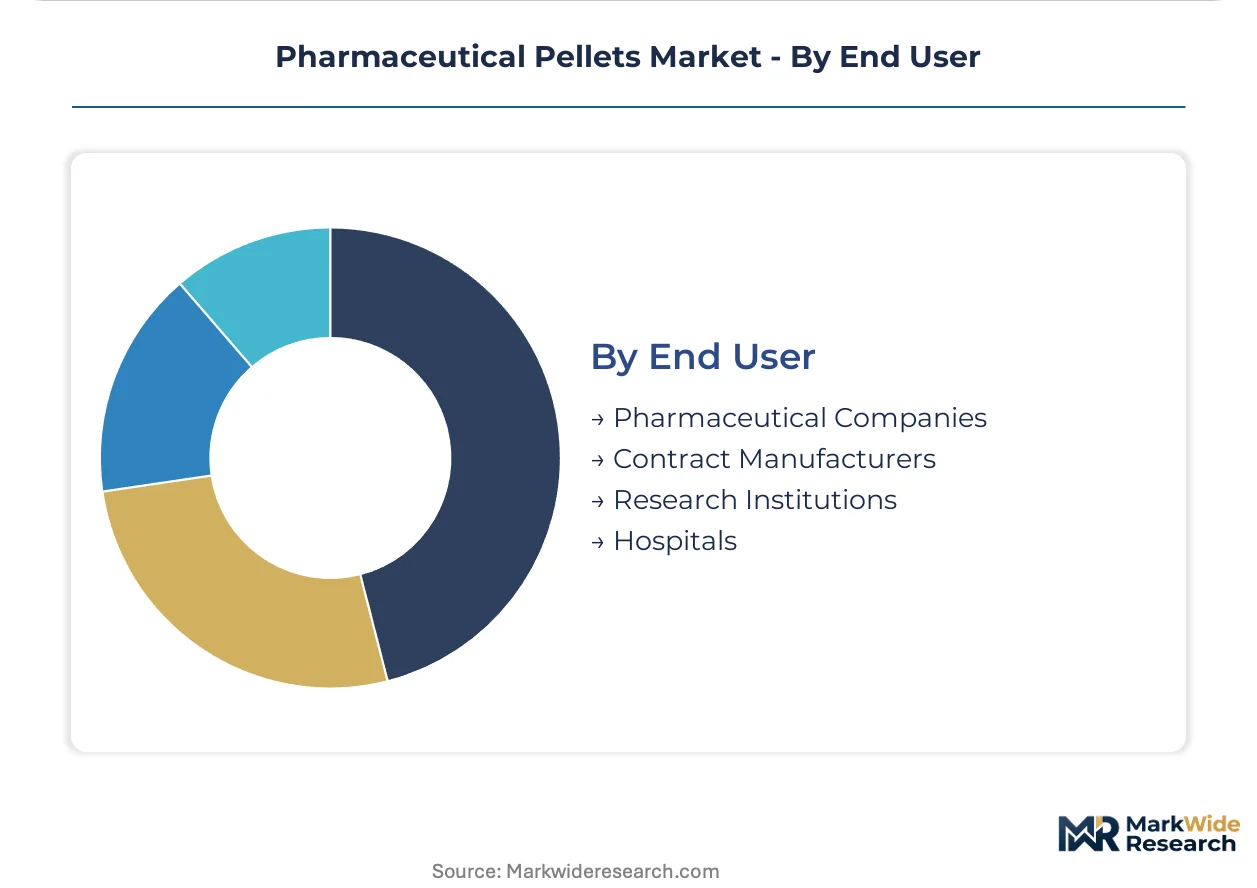
End User:
Customer type determines technical service intensity and qualification timeline, with contract manufacturers capturing capital-constrained sponsor workflows.
- Pharmaceutical Companies:Integrated formulation groups retain high-value, patent-protected programs requiring tight process control. Abbott Laboratories sustains leadership through dedicated multiparticulate delivery infrastructure.
- Contract Manufacturers:CDMOs in Germany's pharmaceutical manufacturing corridor are scaling dedicated pellet suites for mid-size sponsors lacking spheronizer capital.
- Research Institutions:Academic and government labs explore novel pellet architectures for orphan indications.
- Hospitals:Compounding pharmacies prepare patient-specific pellet blends for individualized titration protocols.
Contract manufacturers absorb the fastest-growing share of production volume; pharmaceutical companies retain the highest-margin, most complex programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany's pharmaceutical manufacturing corridor while consumption spreads across aging populations in Japan and the United States. Contract development organizations in Europe absorb capital-intensive pellet manufacturing for sponsors lacking spheronizer infrastructure. Regulatory divergence between FDA quality-by-design mandates and EMA process analytical technology guidelines shapes regional facility investment patterns.
Germany
Geriatric care expansion and cardiovascular therapy protocols drive multiparticulate prescription volumes in Baden-Württemberg and North Rhine-Westphalia. EMA process analytical technology guidelines mandate real-time release testing for new marketing authorizations. The Mannheim-Heidelberg pharmaceutical cluster hosts CDMOs scaling dedicated pellet production suites for mid-size sponsors.
United States
Hospital procurement consolidation in regional health systems demands pellet-specific bioequivalence documentation beyond standard ANDA requirements. FDA current good manufacturing practice enforcement elevates quality thresholds for extrusion-spheronization operations. New Jersey and Massachusetts formulation hubs concentrate multiparticulate delivery infrastructure for patent-protected programs.
Japan
PMDA guidelines on controlled-release formulations align with chronic disease management protocols for aging demographics. METI industrial policy supports domestic pharmaceutical manufacturing capacity. The Kansai region around Osaka maintains formulation science infrastructure for sustained-release pellet development.
India
Microcrystalline cellulose excipient sourcing and qualified supplier networks position Gujarat and Maharashtra as input cost centers. CDSCO manufacturing compliance standards tighten for export-oriented pellet producers. Hyderabad's pharmaceutical corridor attracts contract manufacturing investment serving European and North American sponsors.
Switzerland
Swissmedic quality standards and biologic drug pipeline expansion create demand for enteric-coated pellet architectures. Basel's pharmaceutical research ecosystem supports early-phase development of peptide formulations. Specialized coating technology providers concentrate in the country's precision manufacturing corridor.
Pharmaceutical Pellets Market Vendor Landscape
The competitive structure tilts toward integrated formulation specialists with captive multiparticulate delivery infrastructure. Tier-one players retain high-value patent-protected programs requiring tight process control, while contract manufacturers absorb capital-constrained sponsor workflows. Three archetypes dominate: multinational pharmaceutical companies with dedicated pellet science divisions, specialized excipient and coating technology providers, and regional CDMOs scaling equipment-intensive production suites. Capacity expansion and strategic technology licensing represent the dominant competitive moves, with players securing fluid-bed layering and real-time release testing capabilities.
Among integrated pharmaceutical companies, Abbott Laboratories anchors the multinational tier with dedicated multiparticulate delivery infrastructure. Colorcon Inc. exemplifies the specialized technology provider archetype through coating and release-kinetics expertise. Thexa Pharma occupies a position within the niche therapeutic specialist tier, where pellet geometry governs bioavailability outcomes in targeted indications.
| Leading Market Players |
|---|
| Thexa Pharma |
| Lograns Pharma |
| Abbott Laboratories |
| Rainbow Health Care Products |
| Manus Aktteva Biopharma LLP |
| Colorcon Inc. |
| Avanscure Lifesciences |
| Chemit Laboratories |
| Nordic Sugar |
| Others |
Supply Flow & Price Mechanics
Contract development organizations in Germany's pharmaceutical manufacturing corridor concentrate procurement leverage, compressing per-kilogram pricing for sustained-release pellet formulations through multi-year volume commitments.
Pricing Analysis
Cost-down pressure on standard-grade extrusion-spheronization capacity accelerates as hospital procurement consolidation in US regional health systems demands pellet-specific bioequivalence documentation beyond standard ANDA requirements. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated continuous manufacturing suites from batch-process legacy assets and unqualified import alternatives. Price differentiation traces to certification tier and real-time release testing infrastructure. Mid-size pharmaceutical sponsors exhibit highest price sensitivity; integrated multinationals with captive formulation groups prioritize process control over unit cost.
Supply Chain Analysis
Process analytical technology expertise shortages in Mannheim-Heidelberg and New Jersey pharmaceutical clusters constrain qualified spheronizer operator availability, elevating labor premiums for CDMOs with embedded PAT scientists. Manufacturing equipment concentrates in Germany, the United States, and Switzerland; microcrystalline cellulose excipient sourcing draws from Indian and Chinese suppliers. Fluid-bed layering hardware and precision extruder components create single-source vulnerability for European contract manufacturers. Distribution runs through pharmaceutical wholesaler networks serving hospital systems and retail pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous manufacturing adoption is displacing batch-process pellet production, with EMA process analytical technology guidelines and FDA quality-by-design mandates rendering legacy extrusion-spheronization lines economically obsolete.
For Market Incumbents: Extend real-time release testing capabilities across existing facility footprints before ICH Q13 batch-release paradigm restructuring freezes legacy asset utilization rates. Abbott Laboratories and Colorcon Inc. anchor defensive positioning through captive multiparticulate delivery infrastructure and specialized coating technology expertise. Backward integration into microcrystalline cellulose excipient qualification networks mitigates Indian and Chinese supply volatility.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in enteric-coated biologic pellet architectures opens white-space opportunity for specialized CDMOs serving peptide formulation sponsors in early-phase development. Target Switzerland's Basel pharmaceutical research ecosystem and Germany's Mannheim-Heidelberg cluster for contract manufacturing partnerships. Position through modular dosing flexibility capabilities enabling physician titration protocols in pain management.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier CDMOs with underutilized spheronizer capacity in Germany's pharmaceutical manufacturing corridor, where EMA process analytical technology compliance investments have strained balance sheets. Long-term viability hinges on continuous manufacturing retrofit completion and embedded PAT scientist teams. Monitor FDA enforcement action intensity against batch-process facilities as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Retrofit | ICH Q13 compliance enables real-time release testing and shortens batch approval cycles for EMA submissions. |
| PAT Scientist Team Embedding | Cross-functional formulation science and data analytics capabilities satisfy FDA quality-by-design enforcement. |
| Biologic Enteric Coating Capacity | Peptide and protein drug pipelines in Basel create demand for acid-protection pellet architectures. |
| Microcrystalline Cellulose Qualification | Indian and Chinese excipient sourcing networks reduce input cost volatility for extrusion-spheronization operations. |
| Hospital Technical Services Expansion | Pellet-specific bioequivalence documentation supports US regional health system formulary committee requirements. |
Methodological Framework
Multi-period observation of FDA warning letter issuance patterns and EMA marketing authorization approval timelines anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, CDMO operations directors, and hospital formulary directors. Secondary validation drew from FDA 483 inspection observations, EMA CHMP assessment reports, USP dissolution standard revisions, and pharmaceutical trade customs data. Bottom-up pellet production capacity modeling and top-down prescription volume analysis enabled triangulation.
Input-output matrix framing connected spheronizer utilization rates, coating capacity expansion announcements, and excipient price indices to segment-level value projections across the analysis window. Segmentation dimensions modeled encompassed release kinetics profile, manufacturing process sophistication, therapeutic category, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to validated baseline estimates, with fluid-bed layering adoption rates and continuous manufacturing penetration serving as primary forecast inputs.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in real-time CDMO capacity utilization data introduce uncertainty bands around contract manufacturing market share projections. Forecasts reflect assumptions regarding ICH Q13 implementation timelines and process analytical technology adoption curves. Material deviation in FDA enforcement intensity or EMA guideline revision schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Omeprazole and Antihistamine Market
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Denmark Pharmaceutical Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market
Pharmaceuticals
OTC Analgesic Market
Pharmaceuticals
PD-1/PD-L1 Inhibitor Market
Pharmaceuticals
Global Pharmaceutical Gelatin Market
Pharmaceuticals
Global Pharmaceutical Drug Delivery Market
Pharmaceuticals
Respiratory Virus Infection Drug Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Apalutamide API Market
Pharmaceuticals
High Potency API Contract Manufacturing Market
Pharmaceuticals
Oral Anticoagulant Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market