
 Rabeprazole Sodium Market | 2026-2036
Rabeprazole Sodium Market Size, Share, and Industry Trends Forecast 2026-2036
Rabeprazole Sodium Market Analysis
Omeprazole magnesium is restructuring cost baselines across the proton pump inhibitor class as clinicians substitute earlier-generation molecules for rabeprazole sodium in maintenance therapy. Cipla Ltd leverages vertically integrated active pharmaceutical ingredient production to defend margin structures in oral solid doses. Sun Pharmaceutical Industries Ltd anchors North American supply through its specialty distribution network. Dr. Reddy's Laboratories Ltd competes aggressively on abbreviated new drug application filings for delayed-release tablets.
Rabeprazole sodium is a substituted benzimidazole prodrug that irreversibly inhibits the hydrogen-potassium ATPase enzyme at the gastric parietal cell secretory surface, formulated predominantly as enteric-coated tablets with pH-dependent release profiles targeting proximal small intestine absorption. Tablet formulations dominate volume due to manufacturing scalability and patient compliance advantages, while oral suspension formats serve pediatric and dysphagia populations where dose flexibility governs prescribing decisions. Hospital pharmacies channel the majority of acute therapy volumes for gastroesophageal reflux disease and peptic ulcer disease, whereas retail pharmacies capture maintenance refills and over-the-counter transitions.
The US FDA bioequivalence standards for delayed-release proton pump inhibitors shape product development timelines and clinical trial investment requirements for manufacturers seeking abbreviated new drug application approvals. India's CDSCO mandates stability testing under accelerated conditions for enteric-coated formulations, directly influencing formulation chemistry choices and excipient sourcing strategies. Europe's EMA pharmacovigilance frameworks require post-market surveillance of long-term acid suppression effects, adding compliance layers for sustained market presence. Stakeholders must monitor evolving interchangeability designations and biosimilar-like substitution protocols that could restructure prescribing hierarchies across health systems.
Market Dynamics
Generic substitution is accelerating across hospital formularies as proton pump inhibitor patents expire, compressing pricing power for originator formulations while expanding volume opportunities for bioequivalent manufacturers with vertically integrated active pharmaceutical ingredient capabilities.
Growth Catalysts
- CDSCO bioequivalence tightening:India's tightened requirements for delayed-release formulations are elevating quality barriers and rewarding manufacturers with advanced dissolution testing infrastructure.
- Gastroesophageal reflux disease prevalence:Rising diagnosed cases across aging populations in India and China are expanding the addressable patient pool for maintenance therapy.
- Export market expansion:Domestic manufacturers in India are scaling enteric-coating capacity to supply regulated markets in North America and Europe.
Market Restraints
- Omeprazole magnesium substitution:Earlier-generation proton pump inhibitors are displacing rabeprazole sodium in maintenance therapy protocols due to cost differentials.
- Active pharmaceutical ingredient concentration:Key intermediate supply clusters in specific Indian states create geographic vulnerability for formulation manufacturers.
- EMA pharmacovigilance burden:Post-market surveillance requirements for long-term acid suppression effects add compliance layers that extend time-to-revenue for new entrants.
Strategic Opportunities
- Pediatric oral suspension formats:Dysphagia and pediatric populations remain underserved by tablet-centric portfolios, creating white space for dose-flexible formulations.
- US FDA abbreviated new drug application pathways:Streamlined approval frameworks for bioequivalent delayed-release products reward early movers with complex formulation expertise.
- Hospital formulary consolidation:Integrated delivery networks are centralizing proton pump inhibitor procurement, favoring suppliers with multi-product gastroenterology portfolios.
Industry Challenges
- Enteric-coating technical talent:Formulation chemists with pH-dependent release expertise are concentrated among legacy manufacturers, constraining new entrant scale-up.
- Accelerated stability testing infrastructure:CDSCO mandates for stress-condition validation require capital-intensive environmental chambers and analytical equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rabeprazole Sodium Market |
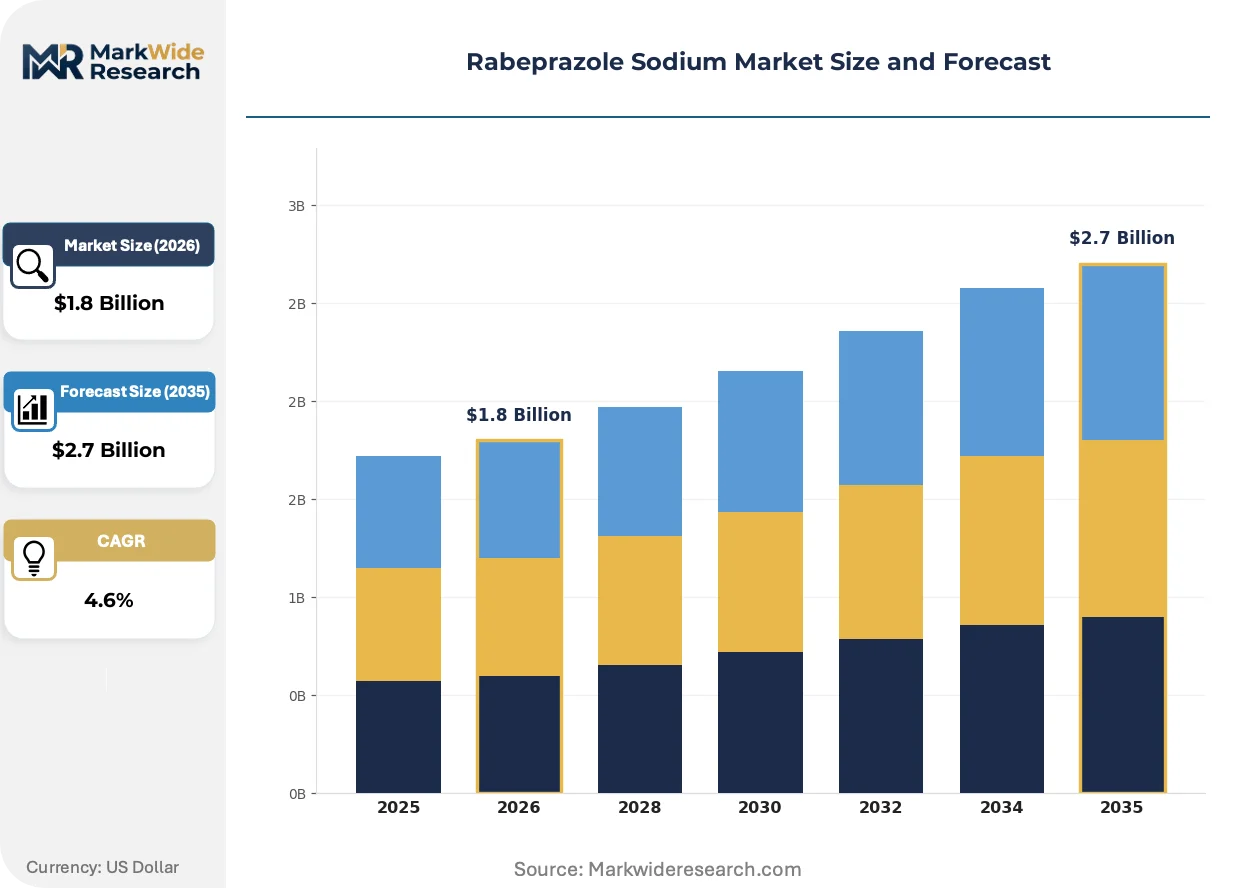
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injectable, Oral Suspension End User: Hospitals, Clinics, Home Care, Pharmacies Therapy Area: Gastroesophageal Reflux Disease, Peptic Ulcer Disease, Zollinger-Ellison Syndrome, Dyspepsia Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Direct Sales |
| Companies Covered | Cipla Ltd, Sun Pharmaceutical Industries Ltd, Alembic Pharmaceuticals Ltd, Cadila Pharmaceuticals Ltd, Dr. Reddy's Laboratories Ltd, Torrent Pharmaceuticals Ltd, Intas Pharmaceutical Ltd, Woodward Pharma, Elikem Pharmaceuticals Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rabeprazole Sodium Market Emerging Trajectories
Process analytical technology is penetrating solid-dose manufacturing floors, enabling real-time dissolution profile verification that reduces batch rejection rates and accelerates release timelines for enteric-coated proton pump inhibitors.
Continuous manufacturing platforms are automating enteric-coating application through integrated fluid-bed systems that maintain precise pH-threshold release kinetics across variable raw material inputs. Mid-tier contract manufacturers in India are adopting these systems to defend margin structures against price erosion in export markets. The technology is compressing batch cycle times from days to hours while tightening coefficient of variation on dissolution profiles.
REACH regulatory expansions in Europe are restricting certain phthalate-based enteric-coating plasticizers, forcing reformulation toward hydroxypropyl methylcellulose acetate succinate and polyvinyl acetate phthalate alternatives. Manufacturers with early polymer qualification data are securing preferred supplier status with European hospital purchasing consortia. The transition is most acute in Germany and France where national formularies have advanced sustainability procurement criteria.
Hospital procurement committees are consolidating proton pump inhibitor contracts around single-source agreements that bundle rabeprazole sodium with other gastroenterology therapeutics, displacing fragmented multi-vendor purchasing. Integrated delivery networks in the United States are leading this consolidation, replacing individual physician preference with system-level protocol adherence. The shift is visible in states with high concentration of accountable care organizations where total cost of care metrics govern formulary decisions.
Rabeprazole Sodium Market Segmentation
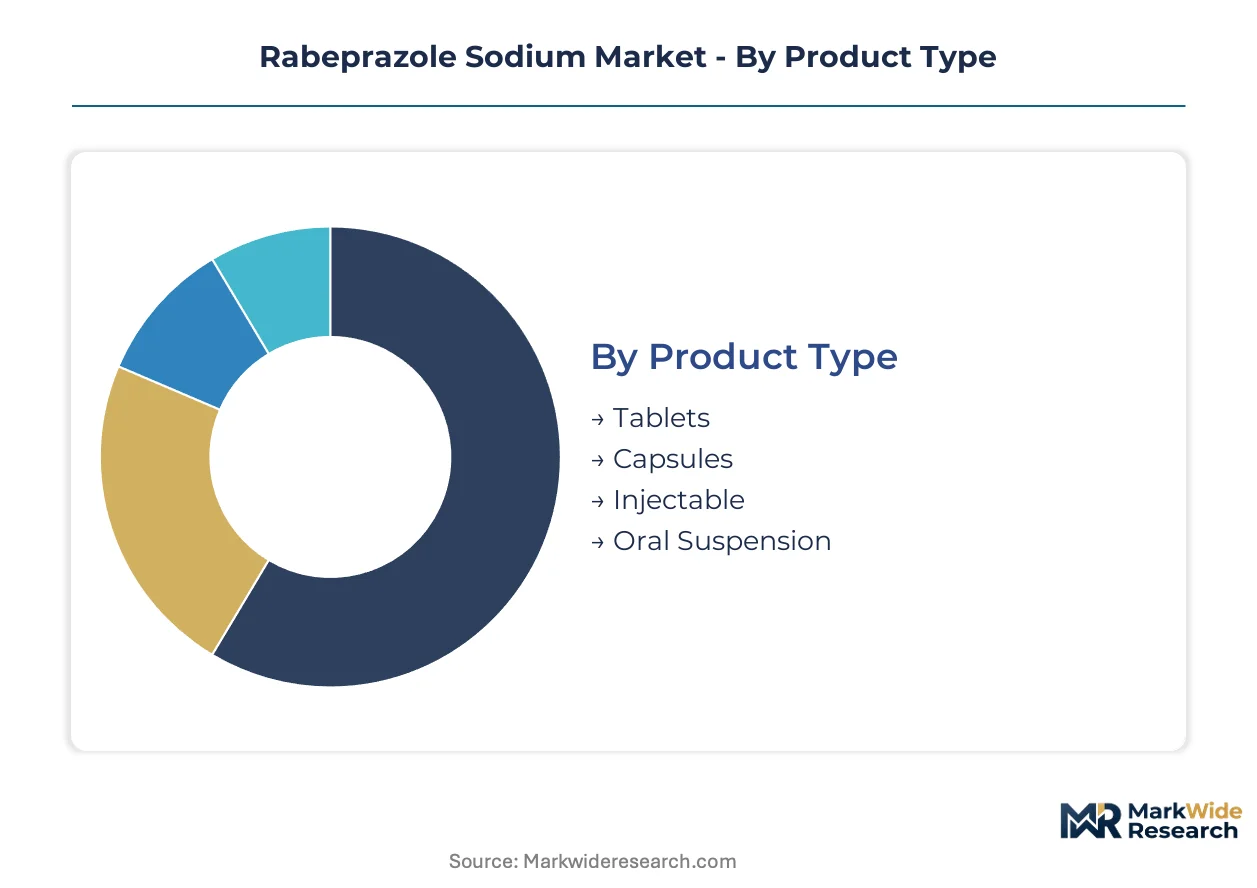
Segmentation in the rabeprazole sodium market reveals how formulation choices, care settings, and disease severity interact to create distinct commercial battlegrounds. Each dimension carries regulatory, pricing, and competitive implications that shape manufacturer strategy.
Product Type:
Volume concentrates in oral solids where manufacturing scale meets reimbursement simplicity, while premium capture depends on bioequivalence precision and pediatric accessibility.
- Tablets:Enteric-coated tablets with pH-dependent release profiles dominate acute and maintenance therapy volumes. Hospital formularies in India and the United States standardize procurement around 20mg delayed-release tablets, driven by CDSCO and FDA bioequivalence requirements that reward dissolution profile consistency.
- Oral Suspension:Granule-based suspensions enable dose titration for pediatric populations and dysphagia patients where tablet administration fails. Demand clusters in specialty clinics and home care settings across Germany and France where regulatory flexibility for alternative formulations supports premium positioning.
- Capsules:Gelatin-encapsulated enteric-coated pellets offer swallowing ease for adult patients with tablet aversion. Manufacturing requires fluid-bed coating expertise concentrated among legacy proton pump inhibitor producers.
- Injectable:Intravenous formulations serve perioperative acid suppression and nil-per-os hospital protocols. Production demands aseptic fill-finish capacity that limits supplier base to specialized contract manufacturers.
Mature deployment sits with Tablets. Newer deployment is concentrated in Oral Suspension.
End User:
Procurement authority and reimbursement pathways fragment across institutional versus ambulatory settings, with margin structures inversely related to purchasing concentration.
- Hospitals:Integrated delivery networks and government health systems drive volume through centralized tendering that prioritizes bioequivalent substitution and multi-year supply security. Formulary committees in the United States and India's public hospitals enforce protocol-driven prescribing that displaces physician brand preference.
- Pharmacies:Retail and community pharmacies capture maintenance therapy refills and over-the-counter transitions where patient co-pay sensitivity shapes generic substitution rates. India's domestic pharmacy chains and independent retailers handle the majority of ambulatory volume.
- Clinics:Outpatient gastroenterology practices initiate therapy and manage dose escalation for refractory cases. Prescribing autonomy remains higher than in hospital systems, supporting originator brand retention where clinical differentiation is asserted.
- Home Care:Long-term maintenance for chronic gastroesophageal reflux disease and Zollinger-Ellison syndrome shifts to home settings with caregiver-administered oral suspensions. Reimbursement complexity limits penetration compared to institutional channels.
Procurement consolidation is advancing fastest in Hospitals. Margin preservation depends on Pharmacy channel access.
Therapy Area:
Disease severity and treatment duration create divergent value pools, with acute interventions competing on cost and chronic maintenance rewarding formulation reliability.
- Gastroesophageal Reflux Disease:Chronic maintenance therapy represents the largest addressable population, with diagnosis rates climbing among aging demographics in China and India. Proton pump inhibitor step-therapy protocols increasingly substitute omeprazole magnesium for rabeprazole sodium in mild-to-moderate cases.
- Peptic Ulcer Disease:Eradication regimens combining rabeprazole sodium with antibiotics require precise dosing synchronization. Hospital protocols in Japan and South Korea emphasize rapid ulcer healing metrics that sustain premium positioning for faster-acting formulations.
- Zollinger-Ellison Syndrome:Rare gastrinoma-driven hypersecretion demands high-dose, long-term acid suppression with dose flexibility that oral suspensions best provide. Ultra-orphan status limits competitive pressure but requires specialized distribution.
- Dyspepsia:Functional dyspepsia without structural lesion carries diagnostic uncertainty that fuels empirical proton pump inhibitor prescribing. Over-the-counter transitions in European markets expand volume but compress pricing power.
Volume expansion is steepest in Gastroesophageal Reflux Disease. Clinical differentiation concentrates in Zollinger-Ellison Syndrome.
Distribution Channel:
Channel selection determines regulatory exposure, working capital intensity, and patient access friction, with digital intermediaries reshaping traditional pharmacy hierarchies.
- Hospital Pharmacies:Captive dispensing within integrated delivery networks ensures formulary compliance and minimizes leakage to retail competitors. India's government hospital supply chains and United States group purchasing organizations dominate procurement for inpatient and emergency department initiation.
- Retail Pharmacies:Community-based dispensing handles maintenance refills with reimbursement negotiated through pharmacy benefit managers. Germany's statutory health insurance system and India's cash-pay pharmacy market represent contrasting reimbursement environments.
- Online Pharmacies:E-commerce platforms expand geographic reach for chronic patients in rural China and tier-2 Indian cities where physical pharmacy density is low. Cold chain and counterfeit risks require authentication infrastructure investment.
- Direct Sales:Manufacturer-to-institution contracts for large hospital systems bypass wholesale markup but demand dedicated account management and inventory management services.
Institutional concentration favors Hospital Pharmacies. Patient convenience is driving investment in Online Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical special economic zones in Andhra Pradesh and Telangana concentrate rabeprazole sodium active pharmaceutical ingredient production, attracting formulation manufacturers through tax holidays and streamlined environmental clearances.
United States
Hospital formulary consolidation drives procurement centralization among integrated delivery networks in Texas and Florida. The FDA's bioequivalence standards for delayed-release proton pump inhibitors shape abbreviated new drug application timelines. New Jersey and North Carolina host specialized contract manufacturers with aseptic fill-finish capacity for injectable formats.
India
Government hospital supply chains in Maharashtra and Gujarat generate volume through centralized tendering that prioritizes domestic manufacturers. CDSCO tightened stability testing mandates for enteric-coated formulations, elevating quality barriers. Hyderabad and Ahmedabad clusters concentrate formulation chemists with pH-dependent release expertise.
China
Aging demographics in Jiangsu and Zhejiang provinces expand the addressable patient pool for gastroesophageal reflux disease maintenance therapy. NMPA aligns bioequivalence protocols with international standards, accelerating approval timelines for delayed-release generics. Yangtze River Delta manufacturers scale enteric-coating capacity for export to regulated markets.
Germany
Statutory health insurance reimbursement frameworks in Bavaria and North Rhine-Westphalia sustain premium positioning for pediatric oral suspensions. EMA pharmacovigilance requirements mandate post-market surveillance of long-term acid suppression effects. Frankfurt and Munich purchasing consortia advance sustainability criteria that favor phthalate-free enteric-coating alternatives.
Japan
Rapid ulcer healing protocols in Tokyo and Osaka hospitals sustain demand for faster-acting formulations in peptic ulcer disease eradication regimens. PMDA maintains stringent dissolution profile requirements for proton pump inhibitor generics. Kanto region manufacturers concentrate high-dose production capacity for Zollinger-Ellison syndrome therapy.
Rabeprazole Sodium Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with originator formulations retaining position in clinic-initiated therapy while bioequivalent suppliers capture hospital formulary volume. The vendor base concentrates among Indian pharmaceutical conglomerates with backward integration into active pharmaceutical ingredient production and North American specialty distributors with integrated logistics networks. Three archetypes dominate: vertically integrated API-to-formulation producers, multi-product gastroenterology portfolio builders, and region-focused generic filers with complex formulation expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves, with manufacturers securing multi-year supply agreements with group purchasing organizations and licensing pH-dependent release technologies from European coating specialists.
Among Indian pharmaceutical conglomerates, Cipla Ltd, Sun Pharmaceutical Industries Ltd, and Dr. Reddy's Laboratories Ltd occupy positions that exemplify the vertically integrated archetype, with each representing distinct strategic approaches to defending margin structures against omeprazole magnesium substitution pressure. Cipla anchors the API-to-formulation integration model through captive production of rabeprazole sodium intermediates. Sun Pharmaceutical exemplifies the North American distribution network approach, leveraging specialty logistics infrastructure to serve integrated delivery network procurement consolidation. Dr. Reddy's Laboratories represents the aggressive abbreviated new drug application filing strategy, competing on regulatory speed for delayed-release tablet approvals.
| Leading Market Players |
|---|
| Cipla Ltd |
| Sun Pharmaceutical Industries Ltd |
| Alembic Pharmaceuticals Ltd |
| Cadila Pharmaceuticals Ltd |
| Dr. Reddy's Laboratories Ltd |
| Torrent Pharmaceuticals Ltd |
| Intas Pharmaceutical Ltd |
| Woodward Pharma |
| Elikem Pharmaceuticals Pvt Ltd |
| Others |
Supply Flow & Price Mechanics
Active pharmaceutical ingredient costs for rabeprazole sodium intermediates flow from Hyderabad and Ahmedabad manufacturing clusters through three distinct pricing tiers that separate originator-grade formulations from bioequivalent tablets and economy-grade hospital tender supplies.
Pricing Analysis
Short lead-time premiums command pricing separation in hospital emergency procurement where integrated delivery networks pay elevated rates for same-week delivery of delayed-release tablets, while spot inventory discounts concentrate in retail pharmacy channels with omeprazole magnesium substitution pressure. Three-tier pricing structure across premium, standard, and economy levels stratifies by bioequivalence certification precision and dissolution profile consistency. Price differentiation hinges on CDSCO stability validation status and FDA abbreviated new drug application approval tier. Cost compression in economy-tier hospital tenders is intensifying because domestic Indian manufacturers expand enteric-coating capacity for export markets. Retail pharmacy chains exhibit highest price sensitivity; specialty clinic channels retain lowest sensitivity where clinical differentiation supports originator retention.
Supply Chain Analysis
Dual-sourcing requirements from United States integrated delivery networks and European hospital purchasing consortia mandate multi-supplier qualification for enteric-coated tablet formulations, forcing manufacturers to maintain redundant API relationships. Supply concentrates in India, China, and the United States for active pharmaceutical ingredient production and formulation finishing. Raw material dependencies center on benzimidazole intermediates, hydroxypropyl methylcellulose acetate succinate coating polymers, and pH-sensitive release excipients. Single-source vulnerability sits with specialized formulation chemists possessing pH-dependent release expertise concentrated in legacy Hyderabad and Ahmedabad facilities. Distribution runs through hospital group purchasing organizations in North America, government tender supply chains in India, and retail pharmacy networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rabeprazole sodium manufacturing is transitioning from batch fluid-bed coating to continuous process analytical technology platforms that compress cycle times and tighten dissolution profile variation.
For Market Incumbents: Anchor formulary position through captive API production of rabeprazole sodium intermediates and accelerated stability testing infrastructure that exceeds CDSCO mandates. Defend against omeprazole magnesium substitution by securing multi-year supply agreements with United States integrated delivery networks. Prioritize certification investment in REACH-compliant phthalate-free enteric-coating alternatives for European hospital procurement. For New Entrants and Emerging Players: Process analytical technology deployment offers entry path into pediatric oral suspension formats where tablet-centric portfolios leave dysphagia and pediatric populations underserved. Target specialty clinic channels in Germany and France where regulatory flexibility for alternative formulations supports premium positioning. Pursue go-to-market angle through licensing pH-dependent release technologies from European coating specialists rather than building captive formulation chemistry capability. For Investors and Strategic Acquirers: FDA abbreviated new drug application approval acceleration for complex delayed-release generics is the leading indicator that formulation expertise scarcity is intensifying acquisition premiums. Long-term viability favors vertically integrated API-to-formulation producers with backward control over benzimidazole intermediate supply. Monitor CDSCO bioequivalence tightening enforcement as inflection signal for quality-barrier elevation that rewards advanced dissolution testing infrastructure holders.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | Process analytical technology reduces batch rejection rates and accelerates release timelines for enteric-coated products. |
| Phthalate-Free Coating Reformulation | REACH compliance secures preferred supplier status with German and French hospital purchasing consortia. |
| Pediatric Oral Suspension Development | Dose-flexible formats address dysphagia and pediatric populations underserved by tablet-centric portfolios. |
| Multi-Year Supply Agreement Negotiation | Integrated delivery network contracts displace fragmented multi-vendor purchasing in United States hospital systems. |
| API Backward Integration | Captive benzimidazole intermediate production defends margin structures against price erosion in export markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs that combined with primary interviews with regulatory affairs leads, hospital procurement managers, formulary directors, and drug development executives. FDA filings, EMA submissions, CDSCO approval databases, and ClinicalTrials.gov records provided secondary validation. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Granularity-level modeling treated formulation type, end-user channel, therapy area severity, and regional regulatory cluster as distinct forecast dimensions. CAGRs derived from patient population growth trajectories, diagnosis rate shifts, and generic substitution elasticity across the projection horizon. Forecast inputs included gastroesophageal reflux disease prevalence curves, patent expiration timelines, and bioequivalence approval velocity.
Several conditions sit outside the modeled scope, including unforeseen regulatory revocation of abbreviated new drug application approvals, abrupt shifts in proton pump inhibitor step-therapy protocols, and supply disruption from active pharmaceutical ingredient facility inspections. Forecasts reflect documented assumptions about CDSCO enforcement continuity and FDA bioequivalence standard stability. Deviation in REACH regulatory expansion pace or EMA pharmacovigilance burden intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
RNA-Targeted Small Molecules Market
Pharmaceuticals
AI Drug Development Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Tuberculosis Vaccine Treatment Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
Amoxicillin Drugs Market
Pharmaceuticals
Finland Pharmaceutical Market
Pharmaceuticals
Trisenox Market
Pharmaceuticals
Brazil Diabetes Drugs Market
Pharmaceuticals
Asia-Pacific Cancer Vaccines Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
Contract Dose Manufacturing Market