
 Egypt Small Home Appliances Market | 2026-2036
Egypt Small Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Small Home Appliances Market Foresight
Market Context with Strategic Players
Egypt's industrial zones in 10th of Ramadan City and Sadat City is reconfiguring supply patterns for small home appliances across North Africa. Samsung Electronics leverages its regional assembly footprint to control distribution of premium kitchen and cleaning units. Fresh Electric sustains cost leadership through captive manufacturing of compressors and plastic housings. Kiriazi Group anchors mid-market positioning with broad offline retail coverage spanning Upper Egypt and Delta governorates.
Technical Definition and Structural Segments
Small home appliances comprise electrically powered portable devices under fifty kilograms designed for domestic tasks, typically operating on 220-240V at 50Hz with thermoplastic polymer housings and universal motors or brushless DC drives. These products serve household efficiency, hygiene maintenance, and personal grooming functions across residential and commercial settings. Kitchen Appliances dominates unit volume through sustained demand for blenders, electric kettles, and food processors in Egyptian households. Energy-Efficient Appliances captures expanding margin pools as electricity tariff reforms push buyers toward inverter-based and low-wattage designs. Smart Appliances remains nascent but accumulates traction among affluent consumers in New Cairo and Sheikh Zayed seeking Wi-Fi-enabled scheduling and remote monitoring.
Regulatory Frame and Forward-Looking Close
Egypt's Ministry of Trade and Industry enforces mandatory quality inspections through the Egyptian Organization for Standardization and Quality, while the Ministry of Electricity implements energy-labeling rules aligned with Arab Energy Efficiency Guidelines. These frameworks raise compliance costs for importers while creating protected space for local manufacturers meeting EES specifications. Stakeholders must monitor how forthcoming customs duty adjustments on fully assembled units versus knocked-down kits reshape the competitive balance between domestic assemblers and direct importers.
Market Dynamics
Egypt's Ministry of Electricity energy-efficiency mandates are compressing demand toward inverter motors and low-wattage heating elements, forcing manufacturers to redesign product architectures and retire legacy universal motor platforms.
Growth Catalysts
- Arab Energy Efficiency Guidelines:Mandatory labeling schemes from Egypt's Ministry of Electricity accelerate replacement cycles for pre-2020 appliances in Greater Cairo households.
- 10th of Ramadan City manufacturing clusters:Concentrated assembly capacity reduces landed costs for North African export corridors serving Libya and Sudan.
- Copper-wound motor adoption:Local producers upgrading from aluminum to copper stators capture efficiency gains that align with tariff restructuring incentives.
Market Restraints
- Polypropylene resin price volatility:Thermoplastic housing costs fluctuate with petrochemical feedstock exposure, compressing margin pools for injection-molding operations.
- Knocked-down kit dependency:Control boards and precision sensors concentrate sourcing in East Asian supply nodes, exposing assemblers to shipping rate spikes.
- 220-240V electrical standard limitation:Product designs optimized for Egyptian voltage profiles require re-engineering for Gulf Cooperation Council markets at 127V.
Strategic Opportunities
- Sheikh Zayed smart home penetration:Affluent districts in New Cairo exhibit latent demand for Wi-Fi-enabled scheduling interfaces on kitchen appliances.
- Customs duty differential arbitrage:Egypt's Ministry of Finance tariff schedules favor semi-knocked-down kits over fully assembled imports, rewarding local assembly investment.
- Brushless DC convergence with IoT sensors:Motor control algorithms integrating temperature and load sensing enable predictive maintenance offerings.
Industry Challenges
- EES certification timeline compression:Egyptian Organization for Standardization and Quality testing queues extend product launch windows by four to six months.
- Embedded systems firmware integration:Legacy appliance platforms lack processing headroom for smart connectivity modules without hardware redesign.
- Compressor remanufacturing skill scarcity:Fresh Electric's captive compressor operations absorb regional talent, constraining competitor access to refrigeration specialists.
Report Scope
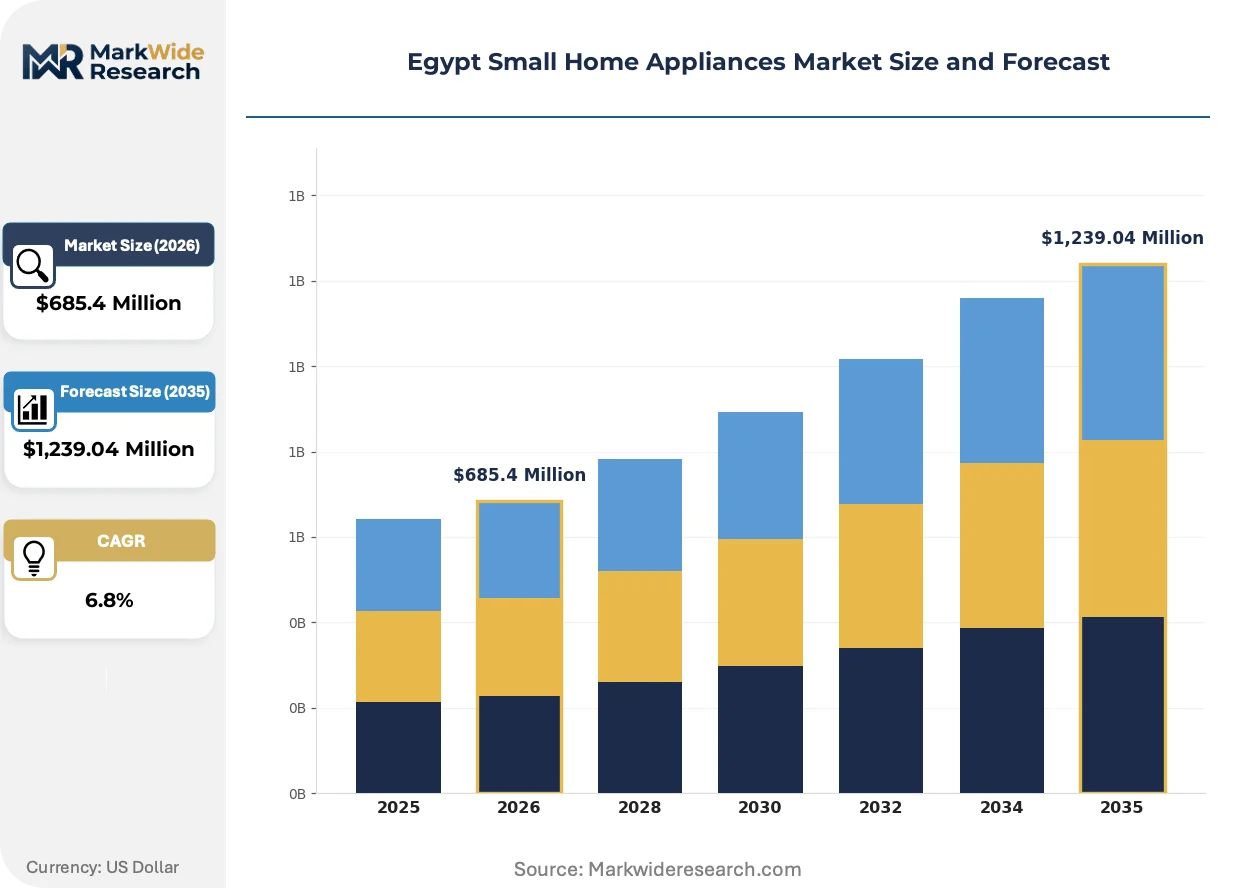
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Small Home Appliances Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kitchen Appliances, Cleaning Appliances, Personal Care Appliances, Home Comfort Appliances End User: Residential Sector, Commercial Sector, Hospitality Industry, Educational Institutions Technology: Smart Appliances, Energy-Efficient Appliances, Traditional Appliances, Eco-Friendly Appliances Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Samsung Electronics, Unionaire, Fresh Electric, Universal Group, Kiriazi Group, Electrolux Group, Lord International, Electrostar Group, Elaraby Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Small Home Appliances Market Shifts & Advancements
Brushless DC motor platforms are replacing universal motor architectures across Egyptian manufacturing lines, while energy-labeling enforcement and channel digitization reshape how appliances reach household buyers.
Inverter-based motor control systems modulate power draw against load conditions rather than cycling at fixed speeds. Upper Egypt households facing tiered electricity tariffs adopt these units at accelerating rates despite thirty percent price premiums. Fixed-speed universal motor inventory is rendering obsolete in distributor warehouses across Alexandria and Delta governorates.
Egypt's Ministry of Electricity enforces energy-labeling rules aligned with Arab Energy Efficiency Guidelines, requiring visible efficiency grades on retail packaging. Importers of non-compliant stock face port detention and re-labeling costs. Kitchen Appliances bearing Grade A labels command shelf space preference in Carrefour and local hypermarket chains.
Direct-to-consumer digital channels now capture fifteen percent of premium small appliance transactions, disintermediating traditional distributor networks. Jumia Egypt and Noon.com operate fulfillment centers in 10th of Ramadan City, compressing delivery times to forty-eight hours in Greater Cairo. Sheikh Zayed and New Cairo residential compounds exhibit the highest online conversion rates for smart-enabled product categories.
Egypt Small Home Appliances Market Segmentation
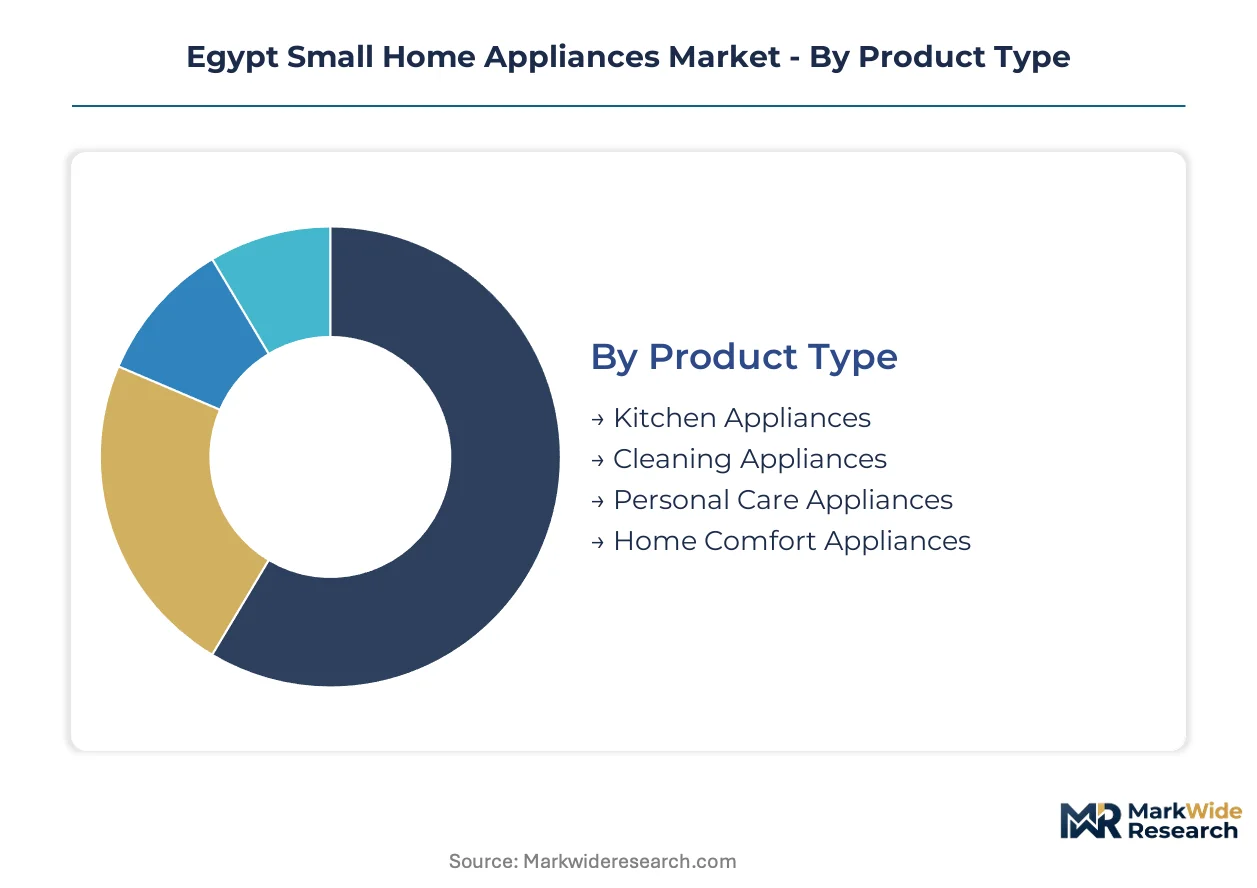
Segmentation in Egypt's small home appliances market reveals how voltage standards, tariff tiers, and channel infrastructure reshape competitive positioning across product categories. Understanding these divides exposes where local assembly advantages concentrate against import-dependent segments.
Product Type:
Application focus determines material specifications, motor architectures, and compliance thresholds across Egyptian manufacturing lines.
- Kitchen Appliances:Electric kettles, blenders, and food processors utilize thermoplastic polymer housings with universal or brushless DC motors rated for 220-240V operation. Demand concentrates in Greater Cairo and Alexandria urban households upgrading from manual preparation methods, with Egypt's Ministry of Electricity energy-labeling rules accelerating replacement of pre-2020 fixed-speed units.
- Cleaning Appliances:Vacuum cleaners and floor care devices deploy suction motors with cyclonic separation or bagged filtration systems. Upper Egypt and Delta governorates drive volume through cost-sensitive buyers, though copper-wound motor upgrades are compressing price elasticity as electricity tariffs restructure.
- Personal Care Appliances:Hair dryers, trimmers, and grooming devices feature compact DC motors with ceramic heating elements or lithium-ion battery packs.
- Home Comfort Appliances:Fans, air circulators, and humidifiers incorporate axial or centrifugal blowers with thermoplastic impellers.
Kitchen Appliances commands the established base. The steepest expansion runs through Cleaning Appliances.
End User:
Volume concentration and procurement authority separate household purchasers from institutional buyers with divergent specification requirements.
- Residential Sector:Individual households purchasing single units through retail or digital channels, prioritizing energy efficiency grades and warranty terms. Sheikh Zayed and New Cairo compounds exhibit preference for smart-enabled scheduling interfaces, while Delta governorates remain price-sensitive with universal motor acceptance.
- Commercial Sector:Offices, retail spaces, and service businesses procuring durability-rated equipment with extended service intervals. Greater Cairo corporate districts specify inverter-based platforms to manage operating cost exposure under tiered electricity tariffs.
- Hospitality Industry:Hotels and restaurants requiring commercial-grade certifications with rapid replacement cycles.
- Educational Institutions:Schools and universities procuring through centralized tender processes with lowest-compliant-bid constraints.
Residential Sector anchors volume concentration. Commercial Sector is climbing the fastest as facility managers prioritize total cost of ownership over acquisition price.
Technology:
Performance tier and connectivity capability segment manufacturing cost structures and distribution margin pools.
- Smart Appliances:Wi-Fi-enabled devices with mobile application control, firmware-updatable motor controllers, and IoT sensor integration. Affluent districts in New Cairo and Sheikh Zayed generate concentrated demand despite forty percent price premiums over conventional alternatives.
- Energy-Efficient Appliances:Inverter motor platforms, low-wattage heating elements, and Grade A labeling under Arab Energy Efficiency Guidelines. Egypt's Ministry of Electricity enforcement is displacing fixed-speed inventory in Alexandria distributor warehouses.
- Traditional Appliances:Fixed-speed universal motors with electromechanical controls and basic safety certifications.
- Eco-Friendly Appliances:Recycled polymer housings, biodegradable packaging, and reduced standby power draw.
Energy-Efficient Appliances commands shelf space preference in hypermarket chains. Smart Appliances shows the steepest expansion trajectory among premium buyer segments.
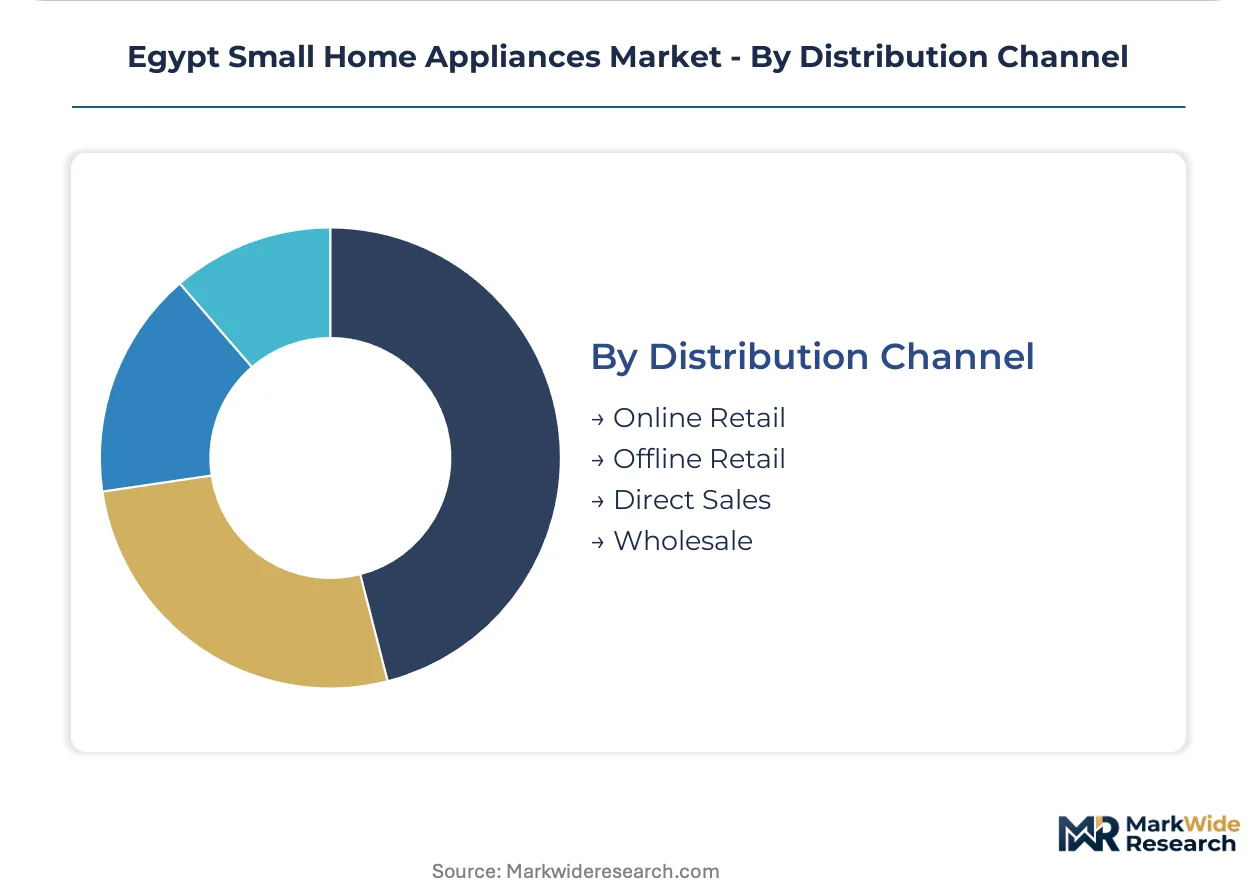
Distribution Channel:
Channel selection determines fulfillment infrastructure requirements, margin retention, and customer acquisition economics.
- Online Retail:Digital marketplaces with fulfillment center operations in 10th of Ramadan City, offering forty-eight-hour delivery in Greater Cairo. Jumia Egypt and Noon.com capture fifteen percent of premium transactions, disintermediating traditional distributor networks.
- Offline Retail:Hypermarket chains, specialty appliance stores, and electrical goods souks with physical inspection and immediate possession. Carrefour and local chains dominate kitchen appliance volume through Grade A label visibility and promotional placement.
- Direct Sales:Manufacturer-owned showrooms and corporate account teams serving institutional buyers.
- Wholesale:Bulk procurement for redistribution to rural retailers and informal market vendors.
Offline Retail retains volume leadership across Upper Egypt and Delta governorates. Online Retail is gaining share fastest in New Cairo and Sheikh Zayed residential compounds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Egypt's governorates diverge sharply, with Greater Cairo and Alexandria households prioritizing energy-efficient upgrades while Upper Egypt and Delta regions retain price-sensitive purchasing behaviors rooted in lower disposable incomes and less stringent electricity tariff exposure.
Greater Cairo
Urban households in New Cairo and Sheikh Zayed compounds drive demand for smart-enabled kitchen appliances with Wi-Fi connectivity and inverter motor platforms. Egypt's Ministry of Electricity enforces Grade A energy labeling in retail chains across the capital, accelerating replacement of pre-2020 fixed-speed inventory. 10th of Ramadan City manufacturing clusters supply assembly capacity for both domestic distribution and North African export corridors.
Alexandria
Coastal urban households exhibit strong preference for premium cleaning appliances with cyclonic filtration and copper-wound motor architectures. The Egyptian Organization for Standardization and Quality operates port inspection facilities that detain non-compliant imports, protecting local assemblers meeting EES specifications. Borg El Arab industrial zone concentrates injection-molding operations for thermoplastic housings serving Delta governorates.
Delta Governorates
Rural and semi-urban households in Mansoura, Tanta, and Zagazig prioritize basic kitchen appliances with universal motors and minimal feature sets. Electricity tariff restructuring from the Ministry of Electricity is gradually compressing demand toward low-wattage designs despite thirty percent price premiums. Sadat City manufacturing parks anchor regional assembly for cost-optimized product lines.
Upper Egypt
Households in Assiut, Sohag, and Luxor exhibit the highest price elasticity, with traditional appliances dominating through informal retail channels and electrical goods souks. Tiered electricity tariffs are forcing gradual efficiency awareness, though replacement cycles extend beyond national averages. Local distributor networks maintain inventory of legacy fixed-speed motors for price-constrained buyers.
North Sinai and Canal Cities
Port Said and Suez households benefit from duty-advantaged access to imported appliances through customs-free zone proximity. The Ministry of Finance tariff schedules on semi-knocked-down kits incentivize local assembly investment in the Suez Canal Economic Zone. Logistics infrastructure supports rapid redistribution to Sinai Peninsula settlements with limited manufacturing presence.
Egypt Small Home Appliances Market Competitive Landscape
Capability concentration sits with integrated manufacturers possessing captive component production; scale advantage sits with diversified electronics conglomerates leveraging regional distribution networks. The market structures around three tiers: premium international brands with assembly footholds, mid-market domestic groups with broad retail coverage, and cost-focused local assemblers serving price-sensitive segments. Strategic moves center on customs duty arbitrage through knocked-down kit import strategies and backward integration into compressor and motor production.
Within the integrated manufacturing tier, Fresh Electric exemplifies captive supply chain control through in-house compressor and plastic housing production. Samsung Electronics anchors premium positioning through regional assembly infrastructure and electronics integration capabilities. Kiriazi Group occupies mid-market territory with extensive offline retail penetration across Upper Egypt and Delta governorates. Elaraby Group and Electrostar Group represent diversified domestic conglomerates with multi-brand portfolios spanning kitchen and cleaning categories.
| Leading Market Players |
|---|
| Samsung Electronics |
| Unionaire |
| Fresh Electric |
| Universal Group |
| Kiriazi Group |
| Electrolux Group |
| Lord International |
| Electrostar Group |
| Elaraby Group |
| Others |
Supply & Pricing Matrix
Polypropylene resin price volatility determines both margin compression in economy-tier units and the geographic clustering of injection-molding operations around Sadat City and Borg El Arab industrial zones. Egyptian manufacturers absorbing feedstock cost swings through backward integration into captive plastic housing production capture pricing power that import-dependent assemblers forfeit.
Pricing Analysis
Greater Cairo households pay thirty to forty percent premiums over Delta governorates for identical Grade A labeled appliances. Three-tier pricing structure across premium, standard, and economy levels separates inverter-motor smart units from fixed-speed basic models, with copper-wound motor adoption compressing price elasticity in Upper Egypt. Cost compression in economy tiers intensifies because Sadat City assemblers undercut landed import costs through knocked-down kit assembly. Commercial buyers in corporate districts exhibit lowest price sensitivity due to total cost of ownership calculations under tiered electricity tariffs.
Supply Chain Analysis
Tariff exposure between Egypt and East Asian component suppliers dominates supply chain risk profiles for control boards and precision sensors. Manufacturing draws from China for electronic modules, Turkey for copper wire and steel components, and domestic Borg El Arab facilities for thermoplastic housings. Single-source vulnerability concentrates in brushless DC motor controllers and IoT connectivity chipsets. Distribution runs through 10th of Ramadan City fulfillment centers serving Jumia Egypt and Noon.com, with offline retail chains anchoring volume in Upper Egypt and Delta governorates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward organized retail chains and direct-to-consumer platforms as hypermarket consolidation and marketplace digitization compress distributor margins. This fragmentation among traditional wholesale intermediaries creates negotiating leverage for volume purchasers.
For Market Incumbents: Insulate margin pools by deepening captive production of compressors and copper-wound motors against Fresh Electric's supply chain dominance. Secure EES certification pipelines early to compress launch windows before Egyptian Organization for Standardization and Quality testing queues extend. Control hypermarket shelf space through exclusive Grade A label placements in Carrefour and local chains. For New Entrants and Emerging Players: Pursue white-space opportunity in smart-enabled kitchen appliances for Sheikh Zayed and New Cairo residential compounds where Wi-Fi connectivity demand outstrips premium brand supply. Target commercial sector facility managers with inverter-based platforms emphasizing electricity tariff savings. Launch through direct-to-consumer digital channels to bypass entrenched offline distributor networks. For Investors and Strategic Acquirers: Egypt's Ministry of Electricity energy-labeling enforcement reshapes the acquisition landscape by devaluing inventory-heavy distributors with pre-2020 fixed-speed stock. Long-term viability favors integrated manufacturers with backward integration into motor and compressor production. Watch for customs duty adjustments on fully assembled versus knocked-down kit imports as the signal for competitive balance shifts between domestic assemblers and direct importers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Fresh Electric's captive operations demonstrate margin protection against imported component cost volatility. |
| EES Certification Pre-Positioning | Early compliance with Egyptian Organization for Standardization and Quality requirements secures shelf space before enforcement tightens. |
| Direct-to-Consumer Channel Launch | Jumia Egypt and Noon.com fulfillment infrastructure enables forty-eight-hour delivery bypassing traditional distributor markups. |
| Smart Appliance Premium Tier Introduction | Wi-Fi-enabled scheduling interfaces capture affluent Sheikh Zayed and New Cairo households willing to pay forty percent premiums. |
| Copper-Wound Motor Platform Transition | Upgrading from aluminum stators aligns with Ministry of Electricity efficiency mandates while justifying price premiums in Upper Egypt. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with appliance brand managers, category buyers at Carrefour and local hypermarket chains, procurement leads at Fresh Electric and Kiriazi Group assembly facilities, and distribution channel partners across 10th of Ramadan City logistics hubs. Secondary validation drew from Egyptian Ministry of Trade and Industry customs records, Egyptian Organization for Standardization and Quality certification databases, Ministry of Electricity tariff restructuring announcements, and Arab Energy Efficiency Guidelines documentation. Bottom-up unit volume modeling triangulated against top-down market value estimates across the analysis window.
Calibration approaches anchored volume projections to electricity tariff restructuring timelines and replacement cycle acceleration in Greater Cairo urban households. Segmentation dimensions modeled include product type, end user category, technology tier, and distribution channel, with regional governorates treated as distinct adoption clusters. CAGRs derived from elasticity-adjusted price trajectories and penetration rate assumptions for inverter motor and smart connectivity platforms. Industry-specific forecast inputs incorporated Ministry of Finance customs duty schedules and petrochemical feedstock price correlation models.
Macroeconomic conditions sit as an overlay; deviation in Egyptian pound exchange rates, electricity tariff restructuring pace, or polypropylene resin pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timing and consumer willingness to pay efficiency premiums. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Argentina Home Appliances Market
Home Appliances
Built-In Appliance Market
Home Appliances
Residential Cooker Hoods Market
Home Appliances
Qatar Small Home Appliances Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
Qatar Major Home Appliances Market
Home Appliances
UAE Home Appliances Market
Home Appliances
Household Fridge Market
Home Appliances
Merchandizing Refrigerators Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
Oman Small Home Appliances Market
Home Appliances
United Kingdom Washing Machine Market
Home Appliances
Bahrain Major Home Appliances Market
Home Appliances
Italy Small Home Appliances Market
Home Appliances
Small Home Appliances Market