
 Chile Home Appliances Market | 2026-2036
Chile Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Home Appliances Market Outlook
The gap between premium and commodity tiers is expanding as inverter-driven refrigeration and smart connectivity command price multiples over basic manual-defrost units. Samsung Electronics leverages its semiconductor supply chain to integrate AI-powered cooling systems that sustain margin premiums in Santiago's upscale retail corridors. Whirlpool Corporation anchors its position through localized assembly and deep distribution partnerships with Falabella and Paris. Mabe competes aggressively in the mid-range oven segment through cost-optimized manufacturing platforms.
Home appliances encompass electrically powered devices designed for domestic tasks, typically operating at 220V/50Hz in Chile with energy efficiency ratings scaled from A+++ to D under national labeling mandates. Refrigerators dominate installed base volumes due to near-universal household penetration, while washers exhibit faster replacement cycles driven by drum-capacity upgrades and water-consumption regulations. Online Retail is capturing share from Department Stores as logistics networks deepen last-mile coverage in secondary cities. The Premium price tier concentrates margin pools among buyers seeking connected-kitchen ecosystems, whereas Economy units face compression from import tariffs on Chinese-manufactured compressors.
Chile's Ministry of Energy enforces minimum energy performance standards that reshape product portfolios, while the Superintendency of Electricity and Fuels certifies compliance through mandatory testing protocols. The national consumer protection agency, SERNAC, monitors warranty claims and durability disputes, pressuring brands to extend service coverage. Stakeholders must track regulatory alignment between Chilean efficiency mandates and Mercosur technical harmonization talks to anticipate cross-border sourcing advantages.
Market Dynamics
Chile's Ministry of Energy has tightened minimum energy performance standards, forcing manufacturers to redesign compressor architectures and accelerating the obsolescence of fixed-speed refrigeration systems across the installed base.
Growth Catalysts
- Regulatory Compression:Chile's Ministry of Energy mandates A+++ efficiency ratings for new refrigerator imports, creating forced replacement demand among households operating legacy D-rated units.
- Metropolitan Concentration:Santiago and surrounding provinces generate replacement purchases as urban households upgrade from manual-defrost to frost-free systems.
- Inverter Migration:Variable-speed compressor technology reduces electricity consumption by modulating cooling cycles, aligning with national efficiency labeling mandates.
Market Restraints
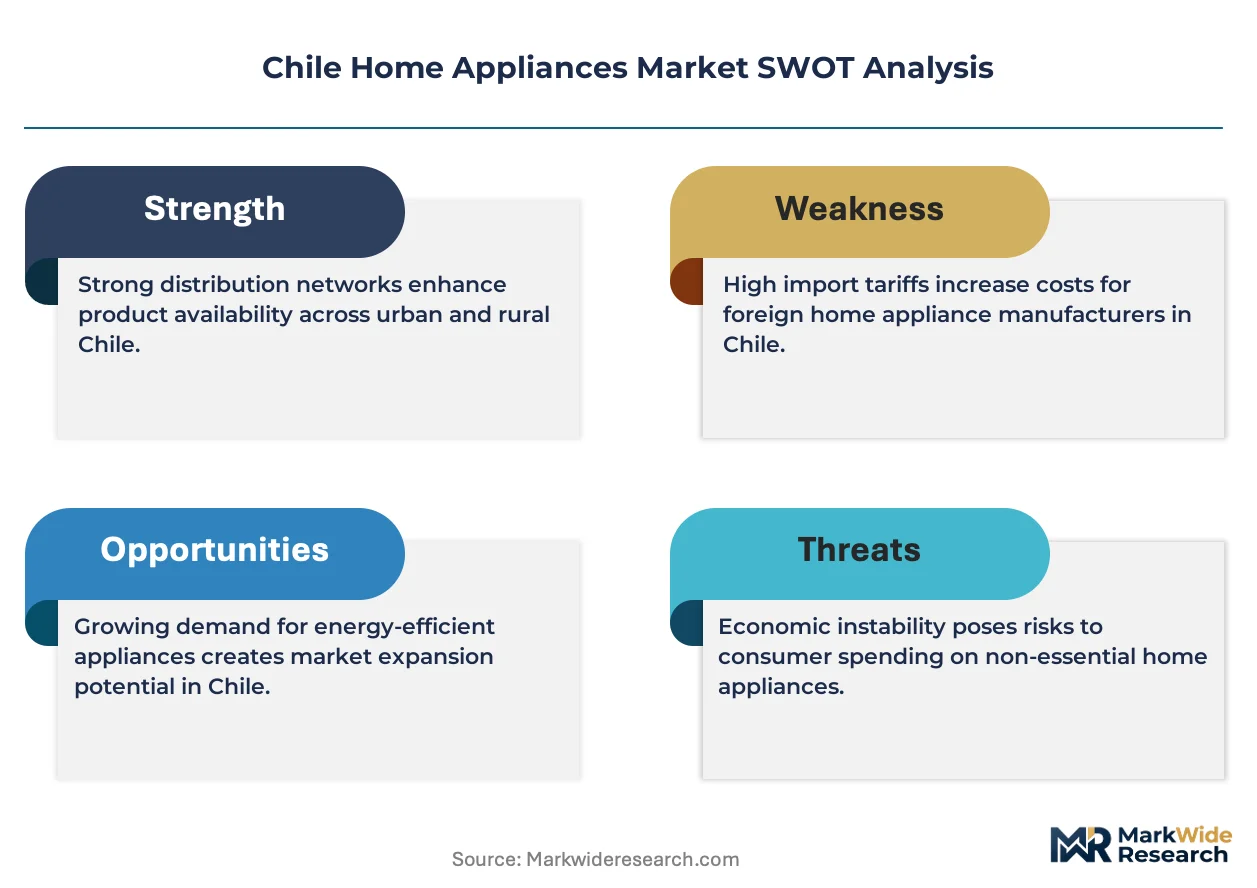
- Import Tariff Volatility:Compressor components sourced from Chinese manufacturing face duty fluctuations, pressuring landed costs for economy-tier refrigerator assembly.
- Metropolitan Saturation:Near-universal refrigerator penetration in Santiago limits organic volume expansion, forcing reliance on replacement cycles.
- Copper Price Exposure:Motor winding and electrical component costs track London Metal Exchange copper futures, creating margin unpredictability for domestic assemblers.
Strategic Opportunities
- Secondary City Logistics:Online Retail channels deepen last-mile coverage in Concepción, Valparaíso, and La Serena, capturing share from Department Store incumbents.
- Smart Convergence:AI-powered cooling systems integrating semiconductor sensors enable predictive maintenance and energy optimization for connected-kitchen ecosystems.
- Water-Efficiency Mandates:Chile's tightening regulations on washing machine water consumption per cycle create specification gaps that front-loading drum designs can exploit.
Industry Challenges
- Certification Bottlenecks:Superintendency of Electricity and Fuels testing protocols create six-to-eight month approval timelines for new refrigerator platforms.
- Legacy Inventory Stranding:Distributors face write-downs on manual-defrost refrigerator stockpiles as efficiency mandates render non-compliant units unsellable.
- Service Network Gaps:Inverter-driven compressor repairs require specialized technician training unavailable outside Santiago's metropolitan service corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Home Appliances Market |
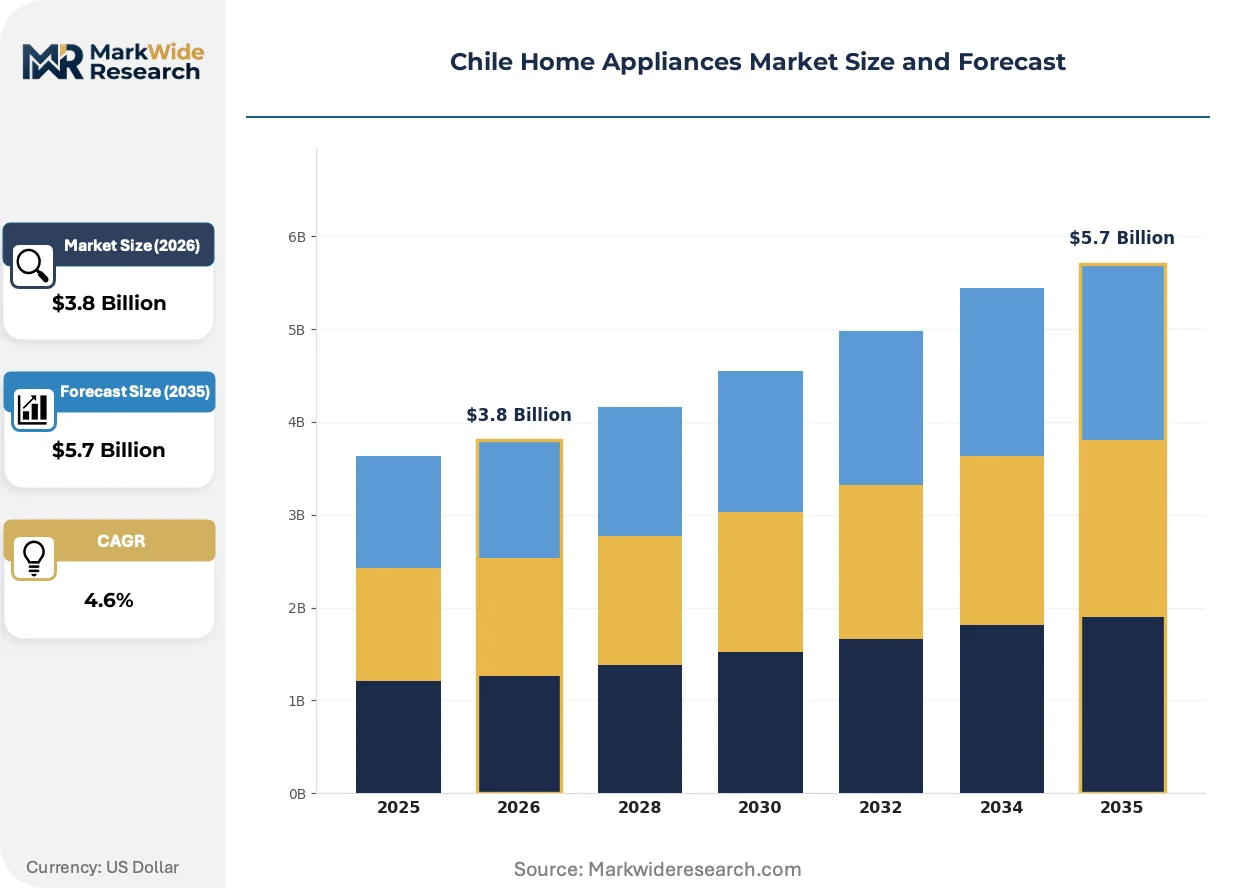
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washers, Ovens, Microwaves Distribution Channel: Online Retail, Specialty Stores, Department Stores, Warehouse Clubs End User: Households, Hotels, Restaurants, Offices Price Tier: Premium, Mid-range, Economy, Luxury |
| Companies Covered | Samsung Electronics, Panasonic Corporation, Whirlpool Corporation, Arcelik AS, Haier Electronics Group Co. Ltd, Electrolux AB, BSH Hausgeräte GmbH, Mabe, LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Home Appliances Market Strategic Shifts
Refrigeration technology is fragmenting across efficiency tiers while distribution channels splinter between legacy retail and direct-to-consumer logistics networks.
Inverter-driven compressor architecture is decentralizing cooling system design away from centralized fixed-speed platforms. Mid-range households in Santiago's condominium developments are adopting variable-speed refrigeration at accelerated replacement cycles. This diffusion is decentralizing margin capture from traditional manufacturers toward semiconductor-integrated subsystem suppliers.
Chile's Ministry of Energy enforces escalating minimum energy performance standards that compress product lifecycles. Manufacturers must redesign compressor architectures every three to four years to maintain import eligibility. The refrigerator segment bears the heaviest compliance burden as A+++ ratings become mandatory for all new unit registrations.
Online Retail channels are disintermediating Department Store dominance in secondary city markets. Falabella and Paris face share erosion as logistics operators achieve next-day delivery to Concepción and Valparaíso. This channel rotation concentrates among younger households seeking price transparency and extended warranty digital registration.
Chile Home Appliances Market Segmentation
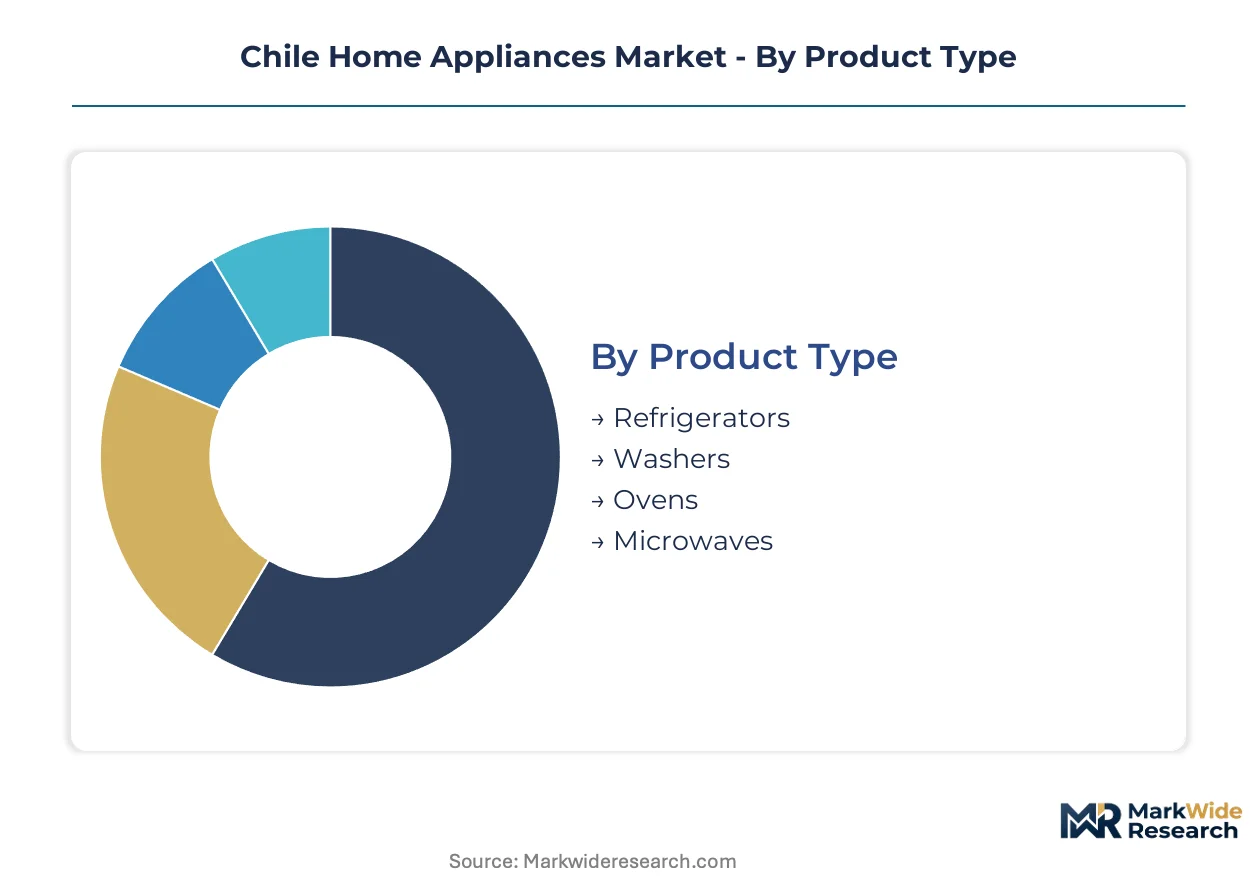
Segmentation in Chile's home appliances market reflects divergent replacement cycles across product categories and distribution channels. Understanding these fault lines clarifies where regulatory pressure and technology migration concentrate margin opportunities versus volume compression.
Product Type:
Upgrade momentum concentrates in refrigeration and laundry equipment as households replace legacy units ahead of tightening efficiency deadlines.
- Refrigerators:These units operate at 220V/50Hz with compressor architectures ranging from fixed-speed to variable-speed inverter systems. Santiago's condominium households drive replacement demand toward frost-free, A+++ rated models as Chile's Ministry of Energy phases out D-rated imports. The installed base nears universal penetration, forcing manufacturers to harvest revenue from efficiency-driven upgrade cycles rather than first-time buyers.
- Washers:Front-loading drum designs with reduced water consumption per cycle align with tightening national regulations on household water use. Replacement cycles run shorter than refrigeration as drum-capacity upgrades and energy-label improvements create specification gaps that mid-range households exploit.
- Ovens:Built-in and freestanding electric or gas-powered cooking appliances serve kitchen renovation projects.
- Microwaves:Countertop and over-range units complete appliance suites in metropolitan rental properties.
Refrigerators sit at the top of the volume ranking, with washers climbing the fastest.
Distribution Channel:
Channel economics in Chile split between logistics-heavy direct delivery and high-rent retail footprints that concentrate in Santiago's commercial corridors.
- Online Retail:Digital platforms with next-day delivery capability to Concepción, Valparaíso, and La Serena capture share from legacy retail. Younger households favor price transparency and digital warranty registration, concentrating growth in secondary cities where department store coverage thins.
- Specialty Stores:Focused retailers with technical staff and installation services anchor premium appliance sales in upscale Santiago neighborhoods.
- Department Stores:Falabella and Paris maintain metropolitan dominance through deep supplier partnerships and extended financing programs.
- Warehouse Clubs:Membership-based bulk retailers serve price-sensitive households in suburban Santiago with limited model selection.
Department Stores retain the largest transaction volume, though Online Retail is expanding most quickly.
End User:
Demand composition varies sharply between replacement-driven residential installations and commercial specifications that prioritize durability over efficiency badges.
- Households:Residential buyers dominate unit volumes, with replacement purchases concentrated in Santiago's Metropolitan Region where energy-label awareness and financing access run highest.
- Hotels:Hospitality operators in Santiago and Valparaíso specify commercial-grade refrigeration and laundry equipment with extended service contracts.
- Restaurants:Food service establishments prioritize compressor reliability and rapid repair turnaround over marginal efficiency gains.
- Offices:Corporate break-room installations represent a thin, price-sensitive segment with minimal smart-feature penetration.
Households anchor the volume base, while Hotels generate the steepest expansion trajectory in commercial-grade specifications.
Price Tier:
Pricing stratification reflects technology integration depth, with semiconductor-enabled features commanding multiples over basic manual-defrost platforms.
- Premium:Inverter-driven refrigeration with AI-powered cooling systems and connected-kitchen integration targets Santiago's upscale retail corridors. These units sustain margin pools through predictive maintenance capabilities and energy optimization algorithms.
- Mid-range:Frost-free refrigeration and front-loading washers balance efficiency compliance with accessible pricing for metropolitan condominium households.
- Economy:Manual-defrost refrigerators and basic top-loading washers face margin compression from import tariffs on Chinese-manufactured compressors.
- Luxury:Built-in appliance suites with custom paneling serve high-end residential construction in Santiago's eastern districts.
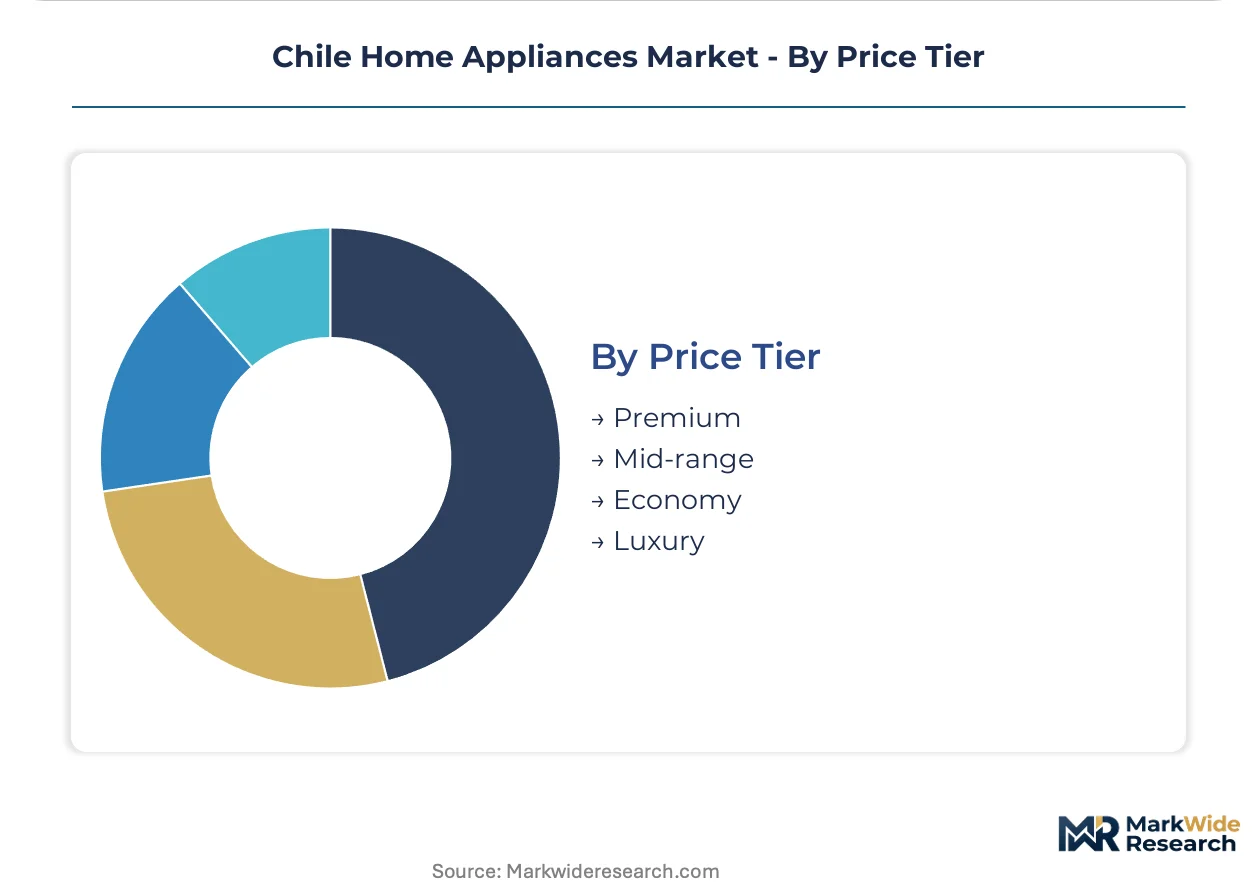
Premium tier captures the deepest margin pools, with Mid-range gaining share fastest as efficiency mandates push households up from Economy specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's skilled technician workforce concentrates in Santiago's metropolitan service corridors, anchoring the national market's repair and installation infrastructure. Regional demand patterns split between the capital's replacement-driven upgrade cycles and secondary cities where first-time penetration still occurs.
Metropolitan Region
Santiago's condominium households drive inverter-driven refrigeration upgrades ahead of Ministry of Energy efficiency deadlines. Chile's Superintendency of Electricity and Fuels operates mandatory testing laboratories in the capital, certifying A+++ rated imports before national distribution. The city's eastern districts concentrate premium appliance retail, while southern municipalities sustain mid-range volume through Falabella and Paris financing programs.
Valparaíso Region
Port logistics and tourism activity in Viña del Mar sustain commercial-grade refrigeration demand from hotels and restaurants. Regional water utility regulations tighten faster than national baselines, accelerating front-loading washer adoption in coastal condominiums. The Valparaíso-San Antonio corridor hosts secondary distribution hubs feeding central Chile's replacement market.
Biobío Region
Concepción's industrial base supports manufacturing-linked household formation, generating steady mid-range appliance demand. The national consumer protection agency SERNAC maintains a regional office here, processing warranty disputes that pressure brands to extend service coverage. Online Retail logistics now achieve next-day delivery, displacing Department Store foot traffic in the Gran Concepción metro.
Antofagasta Region
Mining industry wages sustain premium-tier penetration rates comparable to Santiago despite remote location. Desert climate conditions stress compressor durability, creating specification requirements that differ from temperate zones. The city of Antofagasta anchors northern Chile's sparse service network, with technician scarcity extending repair timelines.
Coquimbo Region
La Serena's retirement migration and agricultural processing sustain mixed residential and commercial demand. Solar photovoltaic adoption among households creates compatibility requirements for smart-connected appliance ecosystems. Regional distribution remains thin, favoring Online Retail channels over physical retail footprints.
Chile Home Appliances Market Competitive Environment
Capital-heavy producers compete with asset-light designers across Chile's appliance value chain. Domestic assembly operations anchored in Santiago face import-dependent competitors leveraging global manufacturing scale. Three archetypes dominate: multinational electronics conglomerates with semiconductor integration capabilities, regional specialists with localized distribution partnerships, and cost-optimized assemblers targeting economy-tier price points. Competitive moves concentrate on distribution depth expansion and efficiency compliance acceleration ahead of regulatory deadlines.
Among multinational electronics conglomerates, Samsung Electronics and LG Electronics exemplify the semiconductor-integrated archetype, leveraging in-house component supply to differentiate cooling system architectures. Whirlpool Corporation occupies a position representing the localized assembly model, anchoring market presence through domestic production and entrenched retail partnerships. Mabe sits within the regional specialist tier, competing aggressively in cooking appliances through cost-optimized manufacturing platforms. These three patterns illustrate how competitive positioning fragments across technology integration depth, geographic production strategy, and price-tier targeting.
| Leading Market Players |
|---|
| Samsung Electronics |
| Panasonic Corporation |
| Whirlpool Corporation |
| Arcelik AS |
| Haier Electronics Group Co. Ltd |
| Electrolux AB |
| BSH Hausgeräte GmbH |
| Mabe |
| LG Electronics |
| Others |
Value Chain & Pricing Dynamics
Inverter compressor migration simultaneously compresses manufacturing cost curves and concentrates component sourcing among semiconductor-integrated suppliers, reshaping margin capture across Chile's appliance tiers. The shift from fixed-speed to variable-speed architectures forces assemblers to secure microcontroller and sensor inputs alongside traditional motor windings, fragmenting procurement leverage.
Pricing Analysis
Installation and extended warranty bundling separates transaction structures between metropolitan Santiago retailers and direct-to-consumer online platforms. Three-tier pricing structure across premium, standard, and economy levels reflects efficiency certification grades and after-sales service depth. Price differentiation hinges on inverter technology integration and smart connectivity modules. Economy-tier units face margin compression from import tariff exposure on Chinese compressor components, while premium buyers show minimal price sensitivity to connected-kitchen feature premiums.
Supply Chain Analysis
Regional distribution centers in Santiago's Quilicura logistics corridor feed hub-and-spoke patterns radiating to Concepción, Valparaíso, and La Serena. Compressor manufacturing concentrates in China, Mexico, and Brazil, with semiconductor sensors sourcing from South Korea and Taiwan. Raw material dependencies include copper for motor windings, steel for cabinet fabrication, and refrigerant gases. Supply chain risk centers on single-source vulnerability for inverter control modules. Distribution runs through Falabella and Paris fulfillment networks alongside emerging logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's home appliances market reads as a late-cycle quality story, with replacement demand shifting decisively toward A+++ certified inverter systems ahead of regulatory deadlines.
For Market Incumbents: Cement service network dominance in secondary cities before inverter-driven repair complexity strands competitor inventory. Extend technician certification programs beyond Santiago's metropolitan corridors to capture stranded legacy unit service revenue. Defend against online retail disintermediation by embedding financing and installation into bundled offerings. For New Entrants and Emerging Players: Begin with smart-connected ecosystem plays targeting La Serena's solar photovoltaic households seeking appliance-grid compatibility. Exploit certification bottlenecks at the Superintendency of Electricity and Fuels by pre-positioning test-ready platforms ahead of efficiency mandate escalations. Pursue direct-to-consumer logistics partnerships to bypass Falabella and Paris gatekeeping. For Investors and Strategic Acquirers: Valuations sit cheapest among regional assemblers lacking semiconductor integration capabilities but holding established distribution partnerships. Long-term viability favors manufacturers with backward integration into compressor architecture design. Watch for Mercosur technical harmonization announcements as inflection signals for cross-border sourcing arbitrage.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Technology Licensing | Enables mid-tier assemblers to bridge efficiency gaps without captive R&D investment. |
| Secondary City Logistics Expansion | Captures replacement demand displacement from department stores in Concepción and Valparaíso. |
| Smart Grid Compatibility Certification | Positions premium portfolios for La Serena's distributed solar household segment. |
| Technician Training Network Buildout | Resolves service gaps that strand inverter-driven unit warranties outside Santiago. |
| Regulatory Pre-Certification Investment | Compresses Superintendency approval timelines ahead of competitor platform launches. |
Study Parameters
Coverage spans Chile's Metropolitan, Valparaíso, Biobío, Antofagasta, and Coquimbo regions, with primary inputs from each territory's distribution and regulatory nodes. The analysis combines structured interviews with appliance category managers at Falabella and Paris, procurement leads at Santiago assembly operations, service technicians across regional corridors, and officials at Chile's Ministry of Energy and SERNAC. Secondary validation draws from customs import records, Superintendency of Electricity and Fuels certification databases, SERNAC warranty dispute filings, and copper futures pricing from the London Metal Exchange. Bottom-up unit shipment estimates triangulate against top-down household penetration and replacement cycle assumptions.
Granularity-level modeling operates at product type, distribution channel, price tier, and regional sub-market dimensions across the projection horizon. Refrigerator and washer segments incorporate compressor technology migration curves and efficiency mandate compliance deadlines. CAGRs derive from replacement cycle acceleration rates and channel share shift trajectories. Industry-specific forecast inputs include copper price volatility indices and Superintendency certification throughput capacity.
Several conditions sit outside the modeled scope, including Mercosur harmonization treaty ratification timing, extreme copper price dislocations, and compressor import tariff rate modifications. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and household financing access continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Latin America Home Appliances Market
Home Appliances
France Home Appliances Market
Home Appliances
Israel Home Needs Appliances Market
Home Appliances
Residential Cooker Hoods Market
Home Appliances
Germany Home Appliances Market
Home Appliances
Household Electric Steamer Cooker Market
Home Appliances
Refrigerator Market
Home Appliances
Bahrain Home Appliances Market
Home Appliances
Japan Household Appliance Market
Home Appliances
Household Refrigerators and Freezers Market
Home Appliances
Electrical Appliances Market
Home Appliances
White Goods Market
Home Appliances
United States Small Home Appliances Market
Home Appliances
Steam Clothing Care System Market
Home Appliances
Residential Dishwashers Market
Home Appliances
Undercounter Refrigerators Market