
 Sweden Kitchen Appliances Market | 2026-2036
Sweden Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Kitchen Appliances Market Analytics
Modular appliance bundling is expanding across Swedish kitchen showrooms, where manufacturers package refrigeration, cooking, and cleaning units into coordinated design ecosystems. Electrolux AB leverages its domestic manufacturing footprint to sustain rapid fulfillment for integrated kitchen projects. BSH Home Appliances competes through specialized distribution partnerships with Nordic kitchen studios. Ikea anchors the mass-market tier with flat-pack logistics that compress delivery timelines for renovation contractors.
Sweden kitchen appliances comprise electrically powered domestic and light-commercial equipment designed for food storage, thermal processing, and surface cleaning, typically operating at 230V/50Hz with energy ratings scaled from A to G under EU harmonized standards. Refrigerators and dishwashers dominate replacement demand, while smart appliances represent the fastest-growing technology segment as Wi-Fi-enabled inventory management and remote diagnostics penetrate premium households. Conventional technology still occupies the majority of installed base volume, though margin pools concentrate in energy-efficient and hybrid configurations where component costs support higher manufacturer yields.
The Swedish Energy Agency enforces eco-design requirements that shape minimum efficiency thresholds for ovens and refrigeration compressors, while CE marking under EU machinery directives governs electrical safety and electromagnetic compatibility for market access. Sweden's building code energy performance standards, administered by the National Board of Housing, Building and Planning, increasingly mandate appliance specifications in new residential construction. Stakeholders must monitor how forthcoming EU F-Gas Regulation revisions affect refrigerant choices in heat-pump appliances, as this technical pivot will determine supplier qualification and retrofit compatibility across the Nordic installed base.
Market Dynamics
Sweden's kitchen appliance sector pivots on energy efficiency mandates from the Swedish Energy Agency, which compress replacement cycles and reshape supplier qualification criteria for heat-pump refrigeration and induction cooking systems.
Growth Catalysts
- Building code integration:The National Board of Housing, Building and Planning mandates appliance specifications in new residential construction, embedding demand into housing starts across Stockholm, Malmö, and Göteborg.
- Heat-pump technology maturation:Heat-pump dishwashers deliver operating cost reductions that accelerate replacement of conventional resistive-heating units in premium renovations.
- Southern housing turnover:Malmö and Göteborg sustain above-average appliance refresh rates as their housing stock cycles faster than northern regions.
Market Restraints
- Copper and rare-earth input volatility:Compressor motors and induction coil assemblies face raw material cost swings that squeeze manufacturer margins on mid-tier product lines.
- Nordic supplier concentration:Heat-pump component sourcing clusters among limited specialized vendors, creating qualification bottlenecks for new market entrants.
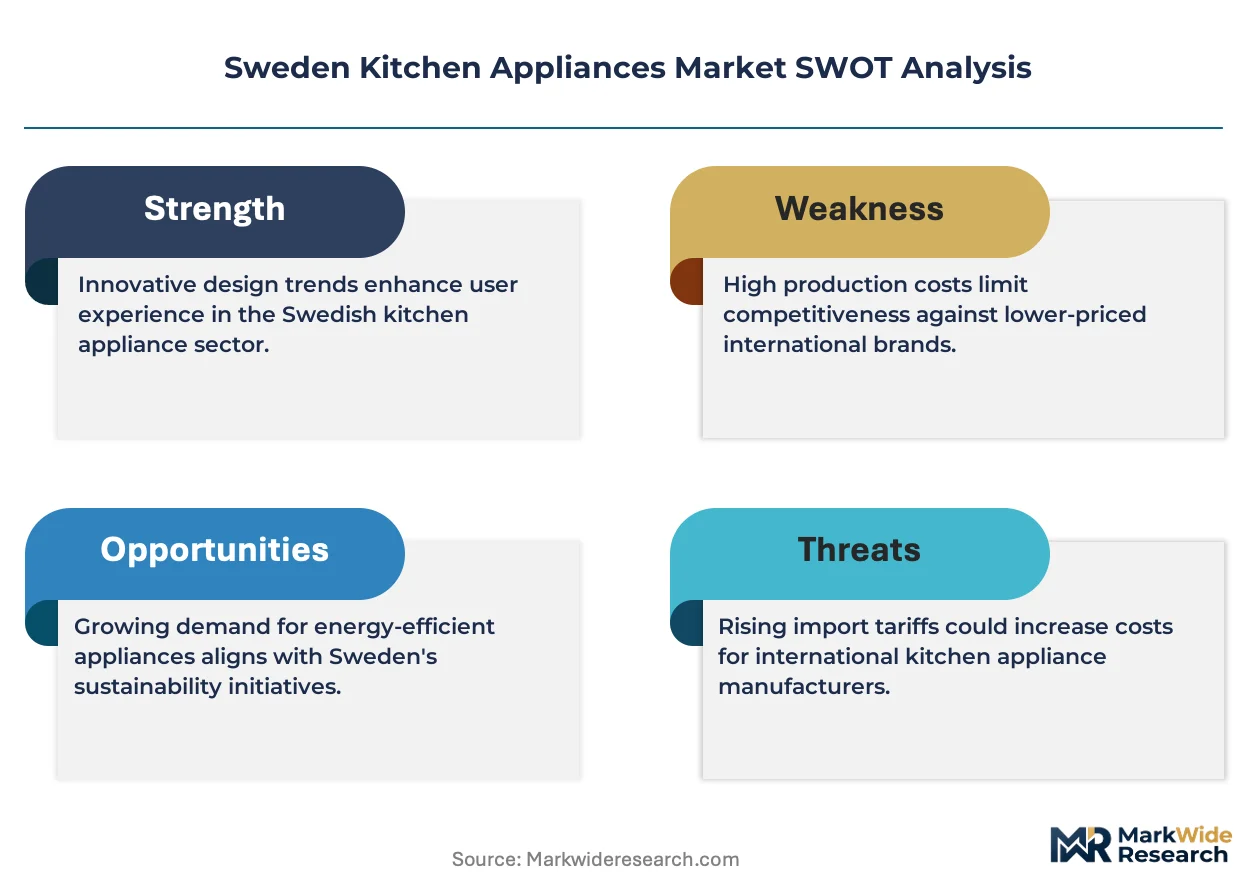
- F-Gas Regulation transition friction:Forthcoming EU refrigerant rule revisions force costly R&D retooling across the installed base retrofit channel.
Strategic Opportunities
- Smart appliance convergence:Wi-Fi-enabled inventory management and remote diagnostics penetrate premium households, opening recurring software service revenue streams.
- Modular bundling expansion:Coordinated design ecosystems package refrigeration, cooking, and cleaning units into single-transaction kitchen studio relationships.
- Rural electrification tailwinds:Grid decarbonization incentives in northern Sweden extend appliance upgrade subsidies to secondary housing stock.
Industry Challenges
- Heat-pump technician scarcity:Installation and service capacity for advanced refrigeration systems lags deployment targets in remote municipalities.
- CE marking compliance timelines:Electromagnetic compatibility testing under EU machinery directives extends product launch windows by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Kitchen Appliances Market |
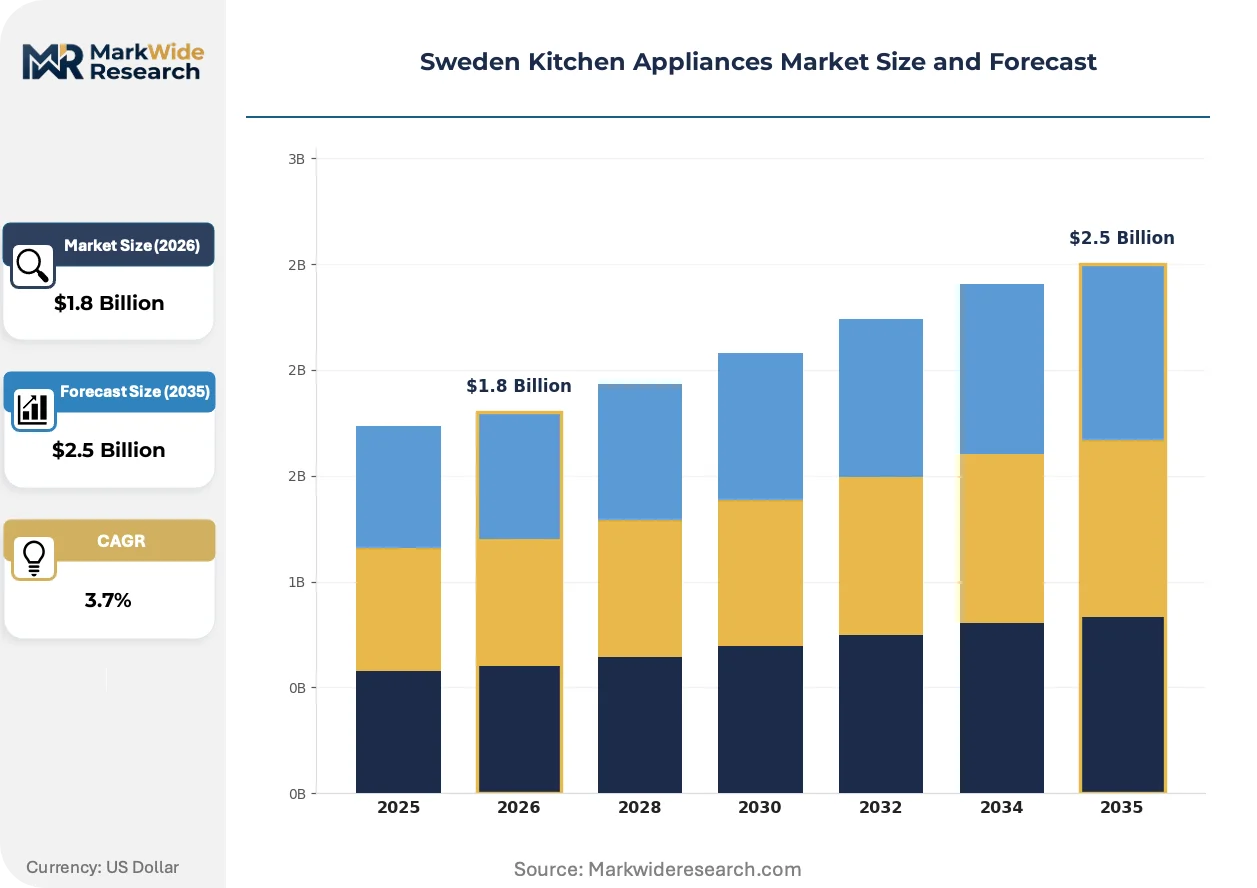
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Cooktops, Ovens, Dishwashers Technology: Smart Appliances, Energy-Efficient, Conventional, Hybrid End User: Households, Restaurants, Catering Services, Hotels Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Wholesalers |
| Companies Covered | Asko Appliances AB, LG Electronics Nordic AB, Electrolux AB, Gorenje Group, Haier Electronics Group Co. Ltd., BSH Home Appliances, Arcelik AS, Amica Wronski SA, Ikea, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Kitchen Appliances Market Evolving Landscape
Swedish kitchen appliance evolution centers on three vectors: energy efficiency technology unification, regulatory pressure on refrigerant chemistry, and procurement model compression through integrated kitchen studios.
Induction cooktop technology is unifying thermal processing control with building energy management systems. Premium kitchen studios in Stockholm's urban core specify these units for their precise power modulation and grid-responsive load balancing. This convergence compresses the traditional separation between appliance selection and whole-home energy optimization into single vendor relationships.
The EU F-Gas Regulation revision tightens refrigerant phase-down schedules for heat-pump appliances. Manufacturers must reformulate compressor systems using lower-global-warming-potential alternatives. Swedish suppliers with domestic manufacturing footprints adapt faster than import-dependent competitors, securing shelf space in Nordic kitchen studio networks.
Kitchen studio procurement consolidates previously fragmented appliance selection into bundled design contracts. Contractors and architects now specify complete refrigeration-cooking-cleaning ecosystems through single points of contact. This channel shift concentrates volume among suppliers with coordinated product portfolios and rapid fulfillment infrastructure.
Sweden Kitchen Appliances Market Segmentation
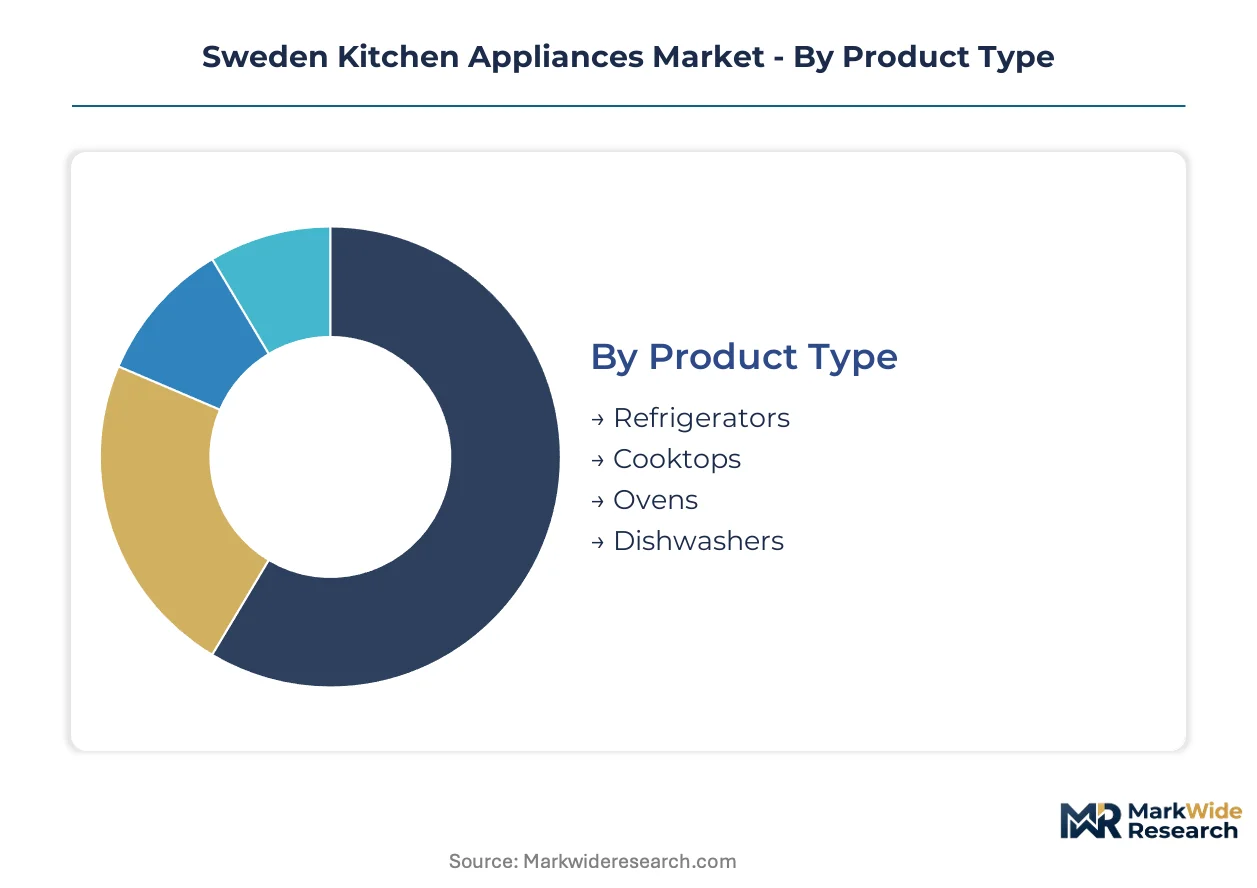
Sweden's kitchen appliance segmentation reveals how energy mandates, channel consolidation, and end-use specialization fragment demand across distinct buyer profiles. Each dimension carries unique regulatory and commercial pressures that shape supplier positioning.
Product Type:
Replacement cycles vary sharply by product category, with energy-label thresholds and housing renovation patterns driving divergent purchase timing.
- Refrigerators:Built-in and freestanding units dominate replacement volume in Stockholm's premium renovation market. Swedish Energy Agency efficiency tiers compress demand toward A-rated compressor systems, accelerating obsolescence of pre-2020 installed base.
- Dishwashers:Heat-pump technology is displacing resistive-heating models in Malmö and Göteborg housing turnover zones. Operating cost advantages from heat-pump systems justify price premiums in mid-market segments.
- Cooktops:Induction systems capture share from gas and ceramic alternatives under building code electrification mandates.
- Ovens:Pyrolytic self-cleaning and steam-assist features concentrate in kitchen studio bundled specifications.
Volume sits with refrigerators; growth tilts toward dishwashers.
Technology:
Margin pools concentrate where component costs and certification complexity erect barriers to commoditization.
- Smart Appliances:Wi-Fi-enabled inventory management and remote diagnostics penetrate premium households in Stockholm's urban core. Recurring software service revenue streams emerge as hardware margins compress.
- Energy-Efficient:Heat-pump dishwashers and induction cooktops command shelf space under Swedish Energy Agency procurement guidelines. CE marking and eco-design compliance extend product launch timelines.
- Hybrid:Dual-fuel cooking and mixed-refrigeration systems serve transitional housing stock in northern Sweden.
- Conventional:Resistive-heating dishwashers and gas cooktops retain installed base volume in secondary housing and rental markets.
Installed base weight rests with conventional systems; margin expansion tracks energy-efficient configurations.
End User:
Commercial specifications diverge from residential on durability ratings, duty cycles, and service response requirements.
- Households:Kitchen studio bundling consolidates procurement into single-transaction design contracts. Electrolux and BSH compete through coordinated product portfolios and rapid fulfillment infrastructure.
- Restaurants:Heavy-duty thermal processing equipment demands 24/7 reliability and sub-4-hour service response in Stockholm and Göteborg.
- Catering Services:Mobile and event-based operations prioritize compact footprint and rapid deployment over energy ratings.
- Hotels:Brand-standard specifications across Nordic chains concentrate volume among suppliers with pan-regional service networks.
Households anchor absolute volume; commercial segments sustain premium pricing.
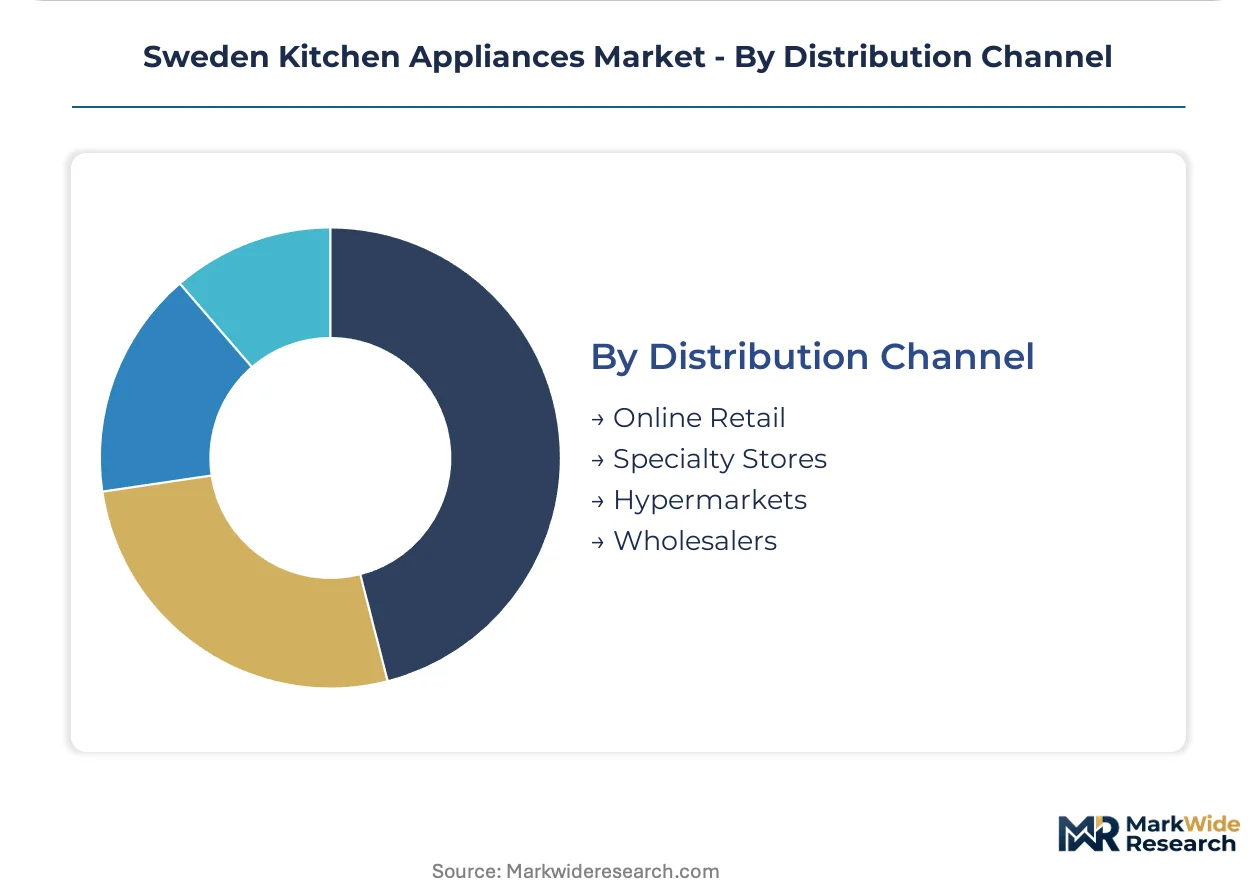
Distribution Channel:
Channel selection determines fulfillment speed, installation coordination, and after-sales service bundling.
- Specialty Stores:Nordic kitchen studios in Stockholm, Malmö, and Göteborg consolidate refrigeration-cooking-cleaning ecosystems into single points of contact. Design consultation and installation coordination justify margin premiums.
- Online Retail:Flat-pack logistics compress delivery timelines for renovation contractors sourcing standard replacement units.
- Hypermarkets:Mass-market tier concentrates on price-transparent, immediately available inventory for emergency replacement.
- Wholesalers:Multi-unit residential developers and commercial kitchen contractors source volume through project-specific pricing.
Specialty stores capture bundled premium transactions; online retail gains share in standard replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden's three metropolitan zones concentrate appliance demand through distinct housing market dynamics and municipal energy retrofit programs. The National Board of Housing, Building and Planning coordinates building code enforcement across county-level jurisdictions, while the Swedish Energy Agency administers appliance-specific efficiency thresholds that vary by regional grid intensity.
Stockholm
Stockholm's premium renovation pipeline drives replacement cycles for built-in refrigeration and induction cooktop systems. The city's climate action plan mandates electrification retrofits in pre-1990 housing stock, compressing demand timelines for heat-pump dishwashers. Kitchen studio networks in Norrmalm and Södermalm consolidate procurement into bundled design contracts for luxury residential conversions.
Göteborg
Göteborg sustains above-average appliance refresh rates through rapid housing stock turnover in Hisingen and Majorna districts. Västra Götaland County's building energy performance standards require A-rated appliances in new construction permits issued since 2023. Electrolux AB leverages its domestic manufacturing footprint to sustain rapid fulfillment for integrated kitchen projects across the western corridor.
Malmö
Malmö's densification policies accelerate replacement demand in converted industrial and port-adjacent residential zones. Skåne County participates in national grid decarbonization incentives that extend appliance upgrade subsidies to secondary housing stock. Nordic kitchen studios in the Øresund region specify coordinated refrigeration-cooking-cleaning ecosystems for cross-border renovation contractors.
Norrland
Norrland's rural electrification tailwinds extend appliance upgrade subsidies to secondary housing stock in remote municipalities. The Swedish Energy Agency's regional efficiency programs target off-grid and weak-grid areas for heat-pump technology deployment. Installation and service capacity for advanced refrigeration systems lags deployment targets in Västerbotten and Norrbotten counties.
Linköping and Uppsala
Linköping and Uppsala anchor public-sector procurement volume through university housing and municipal residential development. Östergötland and Uppsala counties enforce building code appliance specifications in student and research-staff accommodation projects. Regional kitchen contractors source volume through project-specific pricing arrangements with wholesalers serving the Mälardalen corridor.
Sweden Kitchen Appliances Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions in Sweden's kitchen appliance sector. The vendor base clusters around three strategic archetypes: domestic manufacturers with captive supply chains, Nordic distribution specialists with kitchen studio partnerships, and mass-market retailers with flat-pack logistics infrastructure. Electrolux AB and BSH Home Appliances occupy distinct positions through manufacturing scale and channel specialization respectively. Competitive moves concentrate on modular bundling expansion and smart appliance convergence rather than price-based confrontation.
Among domestic-rooted manufacturers, Electrolux AB anchors the integrated kitchen project segment through rapid fulfillment infrastructure. BSH Home Appliances exemplifies the distribution-partnership archetype via specialized relationships with Nordic kitchen studios. Ikea occupies the mass-market tier with flat-pack logistics that compress delivery timelines for renovation contractors. These three entities represent divergent strategic paths: manufacturing depth, channel control, and operational efficiency respectively.
| Leading Market Players |
|---|
| Asko Appliances AB |
| LG Electronics Nordic AB |
| Electrolux AB |
| Gorenje Group |
| Haier Electronics Group Co. Ltd. |
| BSH Home Appliances |
| Arcelik AS |
| Amica Wronski SA |
| Ikea |
| Others |
Value Network & Pricing Analysis
Kitchen studio bundling in Stockholm and Göteborg compresses procurement timelines and forces suppliers to maintain finished goods inventory for rapid fulfillment, elevating carrying costs that manufacturers recover through premium positioning on integrated refrigeration-cooking-cleaning packages.
Pricing Analysis
Short lead-time premiums dominate Swedish kitchen appliance transactions, with Stockholm renovation contractors paying markups for 48-hour fulfillment on built-in refrigeration units while spot inventory from hypermarkets trades at discounts. Pricing stratifies across premium, standard, and economy tiers based on energy efficiency certification under Swedish Energy Agency labeling and after-sales service bundling. Cost compression in mid-tier induction cooktops is intensifying because copper and rare-earth input volatility squeezes manufacturer margins. Rental property managers in secondary housing markets exhibit highest price sensitivity; luxury residential developers in Norrmalm show lowest.
Supply Chain Analysis
Dual-sourcing mandates from Nordic kitchen studios require manufacturers to qualify secondary compressor vendors for heat-pump refrigeration systems, extending qualification timelines but reducing single-source vulnerability. Component manufacturing concentrates in Germany, Poland, and China for compressor motors, induction coil assemblies, and electronic control modules. Swedish suppliers draw from rare-earth processors in China and copper smelters in Germany for critical inputs. Tariff exposure on Chinese electronic components constitutes the primary structural risk. Distribution runs through kitchen studio networks for bundled premium transactions and flat-pack logistics for mass-market online retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swedish kitchen appliance supply is tightening around qualified heat-pump component vendors, with technician scarcity for advanced refrigeration installation propping pricing power for incumbents with captive service networks.
For Market Incumbents: Cement dominance in integrated kitchen projects by expanding in-house production of heat-pump compressor systems, reducing exposure to Nordic supplier concentration. Deepen channel control through exclusive distribution partnerships with kitchen studios in Malmö and Göteborg to preempt emerging entrants. The F-Gas Regulation transition threat demands accelerated R&D investment in lower-global-warming-potential refrigerant formulations. For New Entrants and Emerging Players: Begin with rural electrification subsidies in Norrland counties, where grid decarbonization incentives create white-space demand for heat-pump dishwashers and induction cooktops underserved by incumbent service networks. Target secondary housing stock in Västerbotten and Norrbotten where installation capacity lags deployment targets. Pursue direct-to-contractor online retail with compressed delivery timelines as the initial go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors domestic-rooted manufacturers with captive refrigerant formulation capabilities and established Swedish Energy Agency certification pathways. Long-term viability hinges on supplier qualification speed through the EU F-Gas Regulation transition. Watch heat-pump technician training program graduation rates as the inflection indicator for service network scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Technology Licensing | Accelerates refrigerant compliance under EU F-Gas Regulation revision timelines. |
| Kitchen Studio Partnership Expansion | Consolidates procurement volume through single-transaction design ecosystem relationships. |
| Technician Training Program Buildout | Addresses installation capacity gaps in Norrland remote municipalities. |
| Backward Integration into Compressor Manufacturing | Reduces rare-earth input volatility exposure for induction coil assemblies. |
| Smart Appliance Platform Launch | Opens recurring software revenue from Wi-Fi-enabled inventory management services. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with kitchen studio procurement directors, appliance manufacturer product managers, and HVAC contractor service heads with validation against Swedish Energy Agency efficiency databases and National Board of Housing building permit records. Bottom-up unit shipment estimates triangulated against top-down housing stock turnover projections.
Granularity-level modeling disaggregated volume and value across product type, technology tier, end-user segment, and distribution channel throughout the forecast period. CAGRs derived from trend extrapolation of replacement cycle compression and regulatory mandate timing, with housing start correlations and energy label upgrade elasticities as industry-specific forecast inputs.
Underlying measurement precision varies by segment; household replacement demand carries tighter precision than commercial catering equipment projections. Forecasts reflect assumptions on F-Gas Regulation implementation pace and copper price trajectory. Deviation in heat-pump technician training program scale-up would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Household Coffee Machine Market
Kitchen Appliances
United States Electric Vegetable Choppers Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
Poland Household Electric Grills Market
Kitchen Appliances
Egg Boiler/Cooker Market
Kitchen Appliances
Smart Kitchen Faucet Market
Kitchen Appliances
Asia-Pacific Air Fryers Market
Kitchen Appliances
Mixer Grinder Market
Kitchen Appliances
Induction Hobs Market
Kitchen Appliances
Household Cooking Appliance Market
Kitchen Appliances
Japan Kitchen Appliances Market
Kitchen Appliances
North America Electric Kettle Market
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
Cooktop Market
Kitchen Appliances
Residential Hobs Market