
 Egg Boiler/Cooker Market | 2026-2036
Egg Boiler/Cooker Market Size, Share, and Industry Trends Forecast 2026-2036
Egg Boiler/Cooker Market Analysis
REACH compliance is restructuring material sourcing for European-bound egg boilers, forcing suppliers to substitute legacy coatings and plastics with certified alternatives. Cuisinart leverages its North American distribution network to sustain premium positioning across electric and multi-cooker formats. Hamilton Beach competes on value-engineered countertop models that dominate mass retail channels. Dash specializes in compact, design-forward units that anchor its direct-to-consumer presence.
An egg boiler/cooker is a thermostatically controlled appliance that heats water or direct-contact surfaces to precise temperatures between 160°F and 212°F to prepare eggs in styles ranging from soft-boiled to hard-boiled, omelet, or poached configurations. The device serves both household meal preparation and commercial foodservice operations requiring batch consistency with minimal labor intervention. Electric egg boilers lead volume shipments due to plug-and-convenience appeal in residential settings, while multi-cooker variants capture expanding margin pools by bundling egg functions with broader meal-prep capabilities. Stovetop egg cookers retain durable demand in price-sensitive segments and regions with unreliable electricity infrastructure.
The US Consumer Product Safety Commission enforces electrical safety standards that govern heating-element design and cord construction for countertop appliances. China's SAMR oversees mandatory GB standards certification for products manufactured or sold domestically, affecting export-origin supply chains. ISO 9001 quality management certification shapes buyer qualification criteria among commercial foodservice purchasers. Stakeholders must monitor evolving efficiency mandates and material compliance deadlines to time product redesign cycles and sourcing transitions.
Market Dynamics
Commercial quick-service restaurants are automating breakfast preparation at scale, pulling capital toward batch-capable egg cooking equipment and compressing replacement cycles for legacy countertop units.
Growth Catalysts
- EU F-Gas Regulation:Hydrofluorocarbon phase-down mandates are accelerating supplier transitions to alternative insulation foams and refrigerant-free heating architectures in appliances bound for European markets.
- Southeast Asian manufacturing clusters:Contract producers in Vietnam and Indonesia now serve dual domestic and export demand, shortening lead times for North American and European brands.
- Multi-cooker bundling:Egg-specific presets integrated into programmable pressure cookers are expanding addressable meal-prep occasions beyond standalone breakfast appliances.
Market Restraints
- Heating-element cost volatility:Nickel-chromium alloy prices fluctuate with stainless steel scrap markets, squeezing margin on entry-tier electric models.
- Supply concentration in Guangdong:Overreliance on a single Chinese province for thermostatic controller assemblies creates single-point vulnerability during peak shipping seasons.
- Induction cooktop substitution:Precision temperature control in modern induction ranges reduces need for dedicated single-purpose egg appliances in renovated kitchens.
Strategic Opportunities
- Commercial foodservice automation:Quick-service breakfast chains in the United States are piloting programmable egg stations that integrate with kitchen display systems for order-triggered batch cooking.
- India BIS certification gap:Domestic manufacturers with Bureau of Indian Standards approval hold pricing power as import compliance timelines stretch for foreign competitors.
- Silicone non-stick convergence:Platinum-cured silicone cooking surfaces paired with precision induction coils enable oil-free operation that appeals to wellness-positioned direct-to-consumer brands.
Industry Challenges
- REACH compliance timeline compression:European-bound producers face accelerated deadlines for substituting legacy PTFE coatings and halogenated flame retardants in plastic housings.
- Thermostat calibration skill scarcity:Precision temperature sensor programming for soft-boil consistency requires specialized technicians concentrated in aging workforces at original equipment manufacturers.
- GB standards divergence:China's SAMR maintains separate testing protocols for domestic versus export certification, forcing dual-track engineering and documentation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg Boiler/Cooker Market |
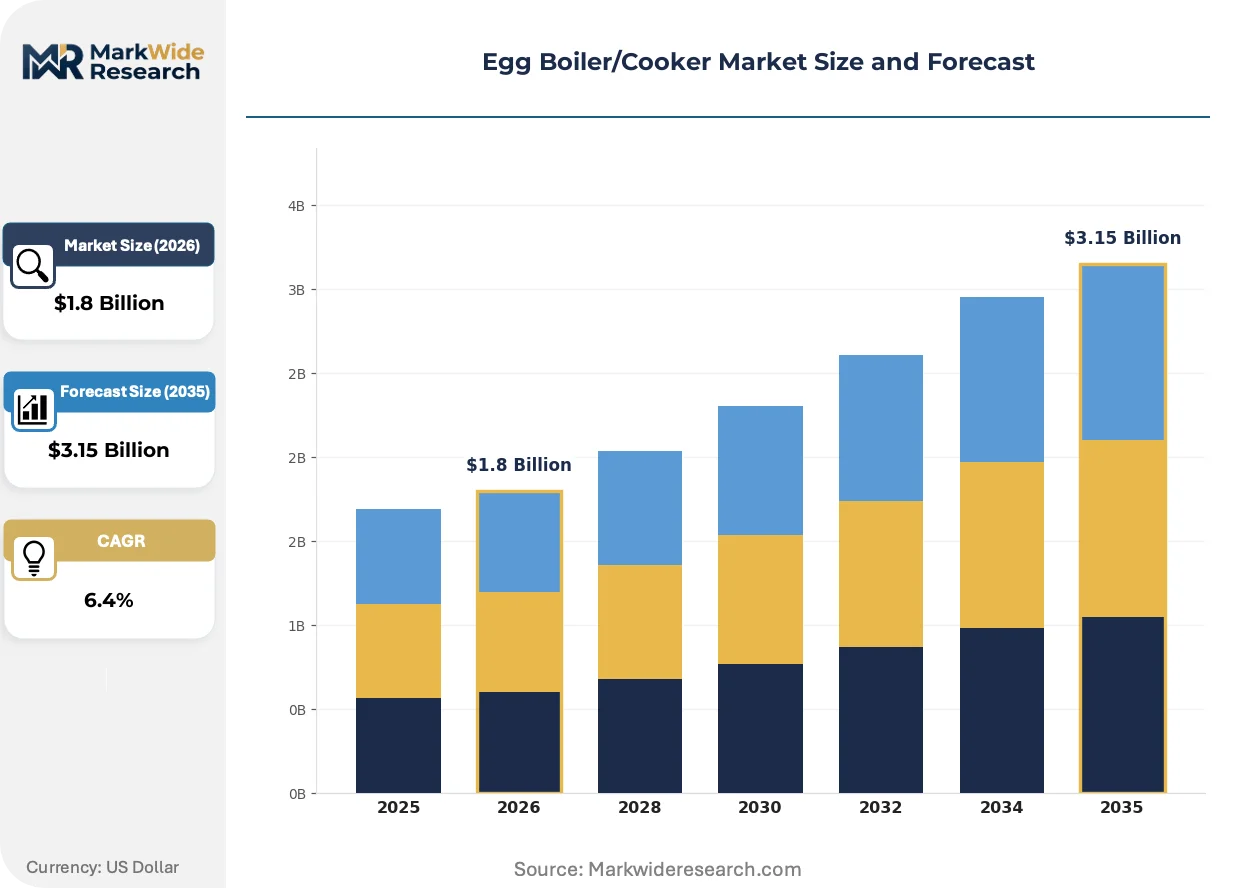
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Egg Boiler, Stovetop Egg Cooker, Microwave Egg Maker, Multi-Cooker End User: Households, Restaurants, Catering Services, Food Manufacturers Installation: Countertop, Built-in, Portable, Wall-mounted Power Rating: Low Power, Medium Power, High Power, Variable Power |
| Companies Covered | Cuisinart, Nostalgia, Dash, VOBAGA, Chef'sChoice, Elite Gourmet, BELLA, Nordic Ware, Hamilton Beach, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg Boiler/Cooker Market Emerging Trajectories
Heating architectures and control systems are undergoing rapid recalibration as energy efficiency mandates tighten and commercial operators demand programmable consistency across high-volume breakfast shifts.
Precision induction modules are converging with platinum-cured silicone cooking surfaces to eliminate oil requirements and enable rapid temperature cycling between soft-boil and omelet modes. Quick-service restaurant chains in the United States are piloting these systems for back-of-house automation. The technology is converging with kitchen display system integration to compress order-to-plate latency during peak morning rushes.
REACH substance restrictions are forcing coating suppliers to retire legacy PTFE formulations and qualify ceramic-silicone hybrid alternatives for European market access. Appliance assemblers must redesign heating-element housings to accommodate thicker, less thermally conductive non-stick layers. Multi-cooker manufacturers with existing ceramic-coating supply chains are capturing share from standalone egg boiler specialists facing reformulation delays.
Direct-to-consumer brands are unbundling after-sales service and warranty administration from traditional retail partnerships, shifting support costs to specialized third-party logistics providers. This pattern concentrates buyer data capture with digital-native sellers while mass-market retailers lose visibility into failure modes and replacement timing. The shift is most visible in North American and Western European markets where subscription-based accessory replenishment models are displacing one-time purchase economics.
Egg Boiler/Cooker Market Segmentation
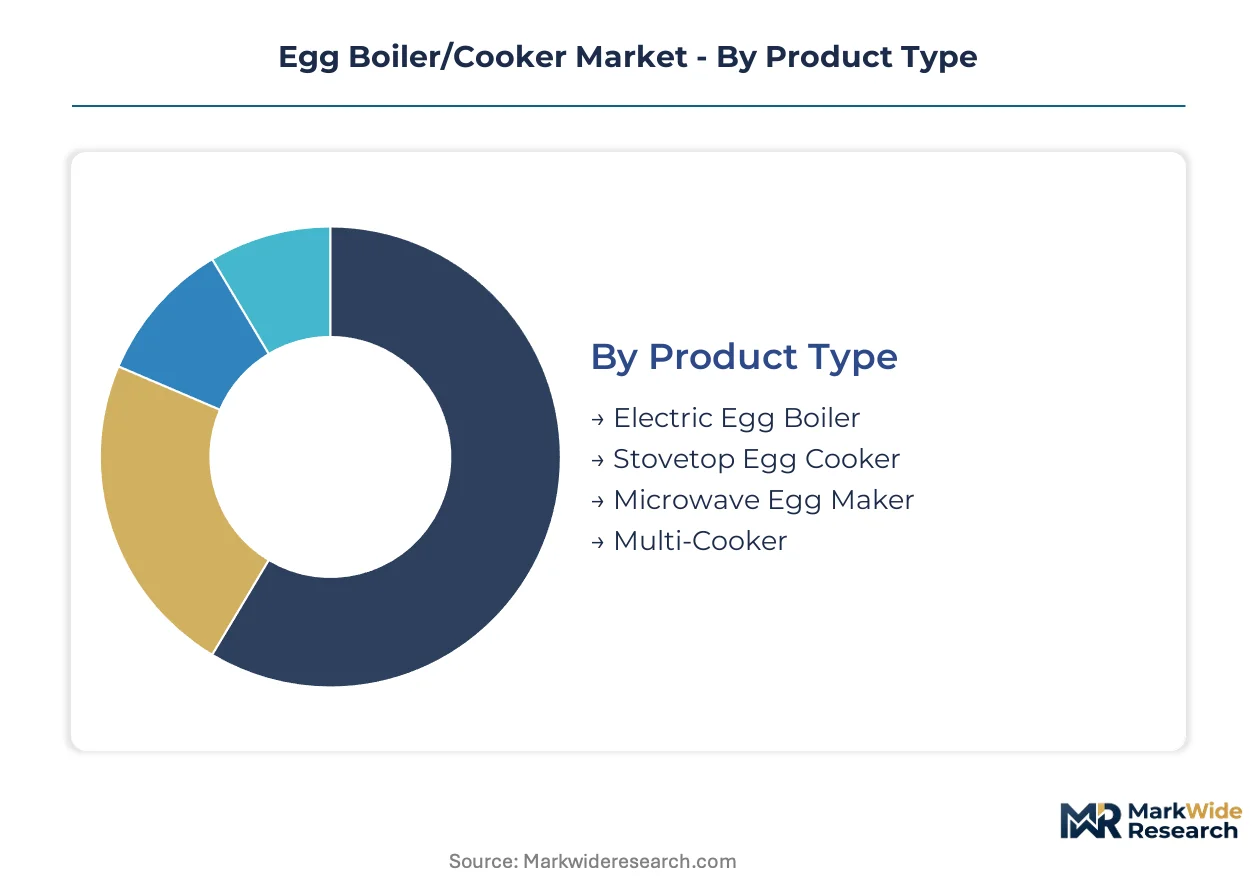
Segmentation in the egg boiler/cooker market reveals how appliance architecture and use context shape procurement decisions. Manufacturers must align product portfolios across standalone single-function units and embedded multi-cooker systems to capture diverging customer workflows.
Product Type:
Standalone electric boilers dominate residential plug-and-play convenience, while embedded multi-cooker functions are displacing dedicated units in space-constrained kitchens.
- Electric Egg Boiler:Thermostatically controlled heating elements maintain water temperatures between 160°F and 212°F for precise soft-to-hard boil consistency. Demand concentrates in North American and European households where countertop convenience outweighs stovetop labor; plug-and-operation simplicity drives replacement cycles every 4-6 years.
- Multi-Cooker:Programmable pressure-cooking platforms integrate egg-specific presets alongside rice, yogurt, and slow-cook functions. Growth is accelerating in urban apartments across Vietnam and Indonesia where single-appliance minimalism reduces kitchen clutter; bundling economics compress margins for standalone boiler specialists.
- Stovetop Egg Cooker:Stainless steel or aluminum vessels with calibrated water-fill lines for heat timing; retains durable demand in price-sensitive segments and regions with unreliable electricity infrastructure.
- Microwave Egg Maker:Polypropylene or silicone vessels designed for rapid microwave heating; appeals to dormitory residents and office workers without dedicated kitchen access.
Electric egg boilers lead volumes today; multi-cookers are gaining share fastest.
End User:
Procurement patterns diverge sharply between capital-constrained household purchasers and commercial operators optimizing labor efficiency across high-volume breakfast shifts.
- Households:Individual consumers prioritizing speed, consistency, and countertop footprint; Cuisinart and Hamilton Beach distribution networks dominate this channel through mass retail and direct-to-consumer platforms.
- Restaurants:Quick-service breakfast chains in the United States are piloting programmable egg stations that integrate with kitchen display systems for order-triggered batch cooking; automation compresses labor costs during peak morning rushes.
- Catering Services:Mobile and event-based food operators requiring portable, high-capacity units for off-premise breakfast service; durability and rapid cycle times outweigh initial equipment cost.
- Food Manufacturers:Industrial-scale egg processing for pre-cooked retail products and ingredient supply; thermostatic precision and batch traceability satisfy BRC and SQF certification requirements.
Households anchor absolute unit shipments; restaurants are expanding most quickly as automation capital deploys.
Installation:
Physical mounting configuration determines distribution channel access and after-sales service complexity, with portable and countertop formats dominating residential e-commerce.
- Countertop:Freestanding plug-in units requiring no permanent installation; Dash and direct-to-consumer brands concentrate here with design-forward compact footprints.
- Portable:Battery-operated or dual-voltage units for travel, camping, and RV applications; silicone construction reduces weight and enables collapsible storage.
- Built-in:Integrated into kitchen cabinetry or appliance banks; limited to premium renovation projects and commercial kitchen builds with custom millwork.
- Wall-mounted:Bracket-fixed units for commercial kitchens with severe counter space constraints; rare in residential applications outside institutional settings.
Countertop configurations command the largest installed base; portable units are climbing the fastest as travel and outdoor recreation demand resurges.
Power Rating:
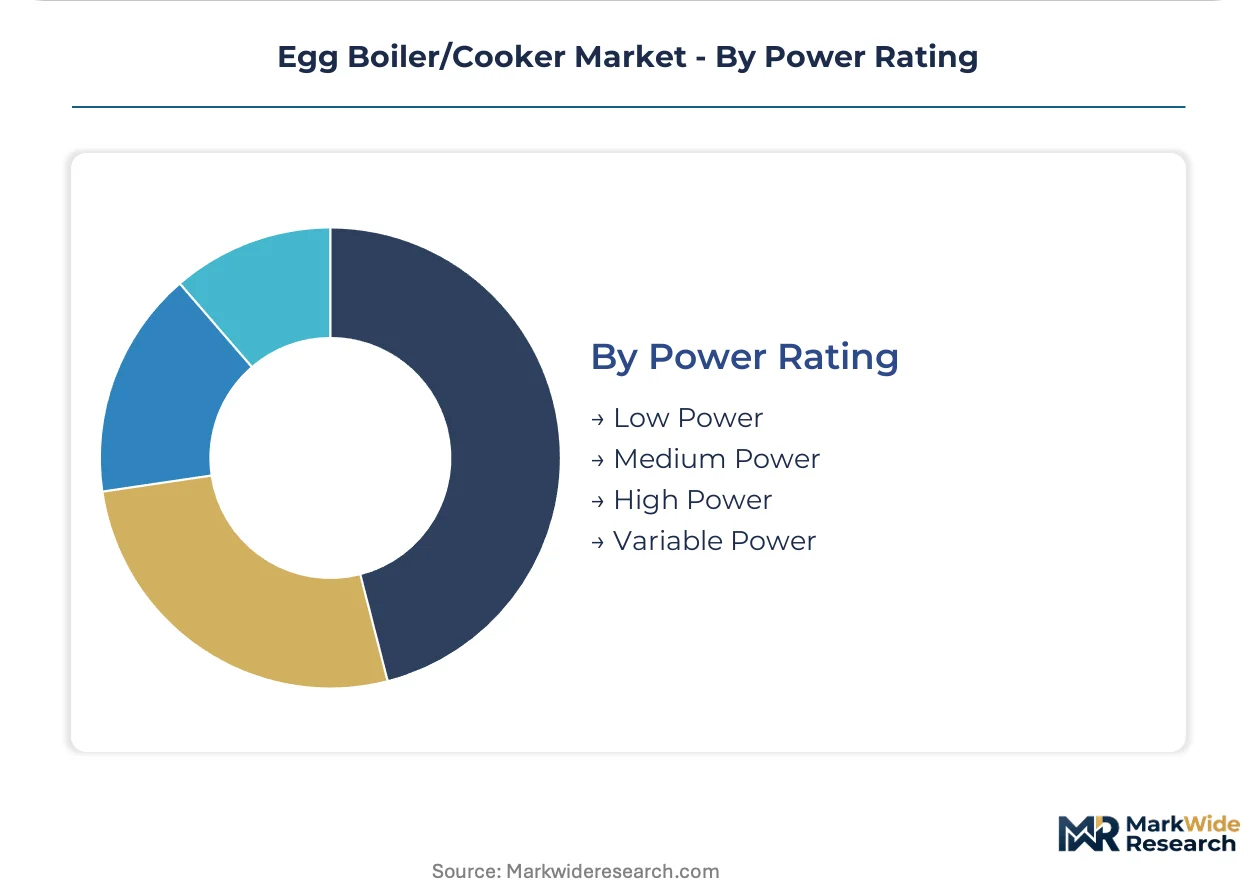
Energy input levels correlate with heating speed, batch capacity, and regulatory efficiency compliance, with variable-power architectures capturing efficiency-minded commercial buyers.
- Medium Power:Typically 300-600 watt elements balancing heating speed with circuit load; serves standard household outlets without dedicated wiring upgrades.
- Variable Power:Microprocessor-controlled wattage modulation between soft-boil and omelet modes; commercial quick-service operators in the United States pilot these systems for menu flexibility with single equipment investment.
- Low Power:Sub-300 watt units for dormitory, office, or RV circuits with strict amperage limits; extended heating cycles trade speed for electrical compatibility.
- High Power:600+ watt elements for commercial batch cooking; requires dedicated 20-amp circuits and professional installation, limiting addressable market.
Medium power ratings lead unit economics today; variable power systems are expanding most quickly as efficiency mandates tighten and commercial automation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized thermostat calibration technicians cluster in aging workforces across original equipment manufacturers in Germany, Japan, and the United States, creating geographic pockets of precision engineering expertise that shape regional competitive dynamics.
United States
Quick-service restaurant chains automate breakfast preparation with programmable egg stations integrating kitchen display systems. The Consumer Product Safety Commission enforces electrical safety standards governing heating-element design and cord construction. Commercial kitchen equipment procurement concentrates in Dallas-Fort Worth and Atlanta distribution corridors serving franchise networks.
China
Contract manufacturers in Guangdong province supply thermostatic controller assemblies for export-bound production. The State Administration for Market Regulation maintains separate GB standards testing protocols for domestic versus export certification, forcing dual-track engineering. Shenzhen and Dongguan industrial parks host concentrated assembly operations for North American and European brands.
Germany
REACH compliance deadlines accelerate substitution of legacy PTFE coatings and halogenated flame retardants in plastic housings bound for European markets. The European Chemicals Agency oversees substance restriction enforcement across member states. Precision component engineering concentrates in Baden-Württemberg automotive supplier corridors repurposing temperature control expertise.
Vietnam
Manufacturing clusters in Ho Chi Minh City and Hanoi serve dual domestic and export demand, shortening lead times for contract production. Bureaucratic import compliance timelines stretch for foreign competitors lacking established local partnerships. Binh Duong province hosts expanding appliance assembly operations serving Southeast Asian consumer markets.
India
Domestic manufacturers with Bureau of Indian Standards approval hold pricing power as import certification timelines extend. The Food Safety and Standards Authority of India regulates commercial foodservice equipment safety parameters. Maharashtra and Gujarat industrial zones concentrate contract manufacturing for regional brands targeting price-sensitive household segments.
Egg Boiler/Cooker Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: kitchen appliance conglomerates with broad countertop portfolios, direct-to-consumer specialists leveraging design-forward compact formats, and commercial foodservice equipment providers targeting automation. Consolidation pressures intensify as multi-cooker bundling compresses margins for standalone boiler specialists. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers secure thermostat calibration expertise and ceramic-coating supply chains.
Among North American kitchen appliance conglomerates, Cuisinart and Hamilton Beach occupy positions spanning premium and value-engineered tiers respectively. Cuisinart leverages established distribution networks across electric and multi-cooker formats, while Hamilton Beach competes through mass retail channel dominance. Dash exemplifies the direct-to-consumer specialist archetype with design-forward compact units anchoring digital-native sales presence. These three companies represent the primary competitive vectors reshaping procurement patterns across household and commercial end-use segments.
| Leading Market Players |
|---|
| Cuisinart |
| Nostalgia |
| Dash |
| VOBAGA |
| Chef'sChoice |
| Elite Gourmet |
| BELLA |
| Nordic Ware |
| Hamilton Beach |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation phase-down mandates gate qualified supply for European-bound production, restricting premium-tier pricing access to assemblers with certified alternative insulation and refrigerant-free heating architectures already validated by the European Chemicals Agency.
Pricing Analysis
The bundled-vs-unbundled service split separates mass-market retailers from direct-to-consumer specialists. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service inclusion. Price differentiation centers on REACH-compliant coating supply chains and thermostat calibration precision. Pricing pressure stems from nickel-chromium alloy cost volatility squeezing entry-tier electric models. Household purchasers in price-sensitive segments show highest sensitivity; commercial quick-service operators prioritize consistency over unit cost.
Supply Chain Analysis
Warehouse-distribution layer concentration in Dallas-Fort Worth and Atlanta corridors serves franchise networks with programmed replenishment. Manufacturing draws from Guangdong province thermostatic controller assemblies, Vietnam contract assembly operations, and Indonesia dual-market production facilities. Raw material dependencies include nickel-chromium heating elements, platinum-cured silicone surfaces, and ceramic-silicone hybrid coatings. Single-point vulnerability concentrates in Guangdong thermostat sourcing during peak shipping seasons. Distribution runs through mass retail channel partnerships and direct-to-consumer logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in ceramic-coating supply chain control and multi-cooker bundling economics that displace standalone boiler specialists.
For Market Incumbents: Acquire thermostat calibration expertise concentrated in aging German and Japanese workforces to defend against precision-skill scarcity. Secure ceramic-coating supply chains ahead of REACH compliance deadlines to maintain European market access. Capacity addition in Vietnam manufacturing clusters shortens lead times for North American brand partners.
For New Entrants and Emerging Players: Begin with Bureau of Indian Standards certification investment to capture pricing power in import-compliance-constrained Indian household segments. Target portable silicone-construction units for travel and outdoor recreation demand resurgence. Direct-to-consumer digital-native positioning enables subscription-based accessory replenishment economics.
For Investors and Strategic Acquirers: Roll-up economics work for direct-to-consumer specialists with captive silicone-coating supply chains because multi-cooker bundling compresses standalone boiler margins and concentrates buyer data with digital-native sellers. Long-term viability favors platform consolidation plays with backward integration into precision temperature control components. Watch kitchen display system integration adoption rates as inflection indicator for commercial automation capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Coating Supply Chain Acquisition | REACH compliance deadlines force legacy PTFE substitution, rewarding early movers with European market access. |
| Commercial Kitchen Display System Integration | Quick-service automation pilots in United States chains compress order-to-plate latency during peak morning rushes. |
| Vietnam Manufacturing Footprint Expansion | Ho Chi Minh City and Hanoi clusters shorten lead times for contract production serving dual domestic and export demand. |
| Platinum-Cured Silicone Surface Development | Wellness-positioned direct-to-consumer brands leverage oil-free operation claims for premium tier differentiation. |
| Bureau of Indian Standards Certification Investment | Domestic approval holders capture pricing power as import compliance timelines stretch for foreign competitors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with appliance engineering directors, commercial foodservice procurement managers, contract manufacturing executives, and ceramic-coating suppliers with secondary validation against customs records, SAMR GB standards filings, and ECHA substance restriction databases. Bottom-up shipment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Historical reference periods anchored growth trajectory assumptions to pre-automation baseline conditions and post-pandemic kitchen equipment replacement cycles. Segmentation dimensions modeled include product architecture, end-use application, installation configuration, and power rating tier. CAGRs derived from shipment velocity trends, replacement cycle compression, and commercial automation capital deployment patterns. Forecast inputs incorporated F-Gas Regulation phase-down timelines and REACH substance restriction enforcement schedules.
Several conditions sit outside the modeled scope, including geopolitical trade policy shifts affecting Guangdong component flows and unanticipated induction cooktop substitution acceleration. Forecasts reflect documented assumptions around thermostat calibration workforce availability and ceramic-coating qualification timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
Capsule Coffee Machines Market
Kitchen Appliances
Australia Kitchen Appliances Market
Kitchen Appliances
Japan Kitchen Appliances Market
Kitchen Appliances
US Smart Oven Market
Kitchen Appliances
United States Large Kitchen Appliances Market
Kitchen Appliances
Italy Kitchen Appliances Market
Kitchen Appliances
Toast Maker Market
Kitchen Appliances
Self-Stirring Mug Market
Kitchen Appliances
Electric Pressure Cooker Market
Kitchen Appliances
South Africa Kitchen Appliances Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Europe Household Refrigerator Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Residential Induction Cooktops Market
Kitchen Appliances
Tabletop Kitchen Products Market