
 Household Cooking Appliance Market | 2026-2036
Household Cooking Appliance Market Size, Share, and Industry Trends Forecast 2026-2036
Household Cooking Appliance Market Intelligence
Subscription-based access to guided cooking recipes and software-enabled cooking modes is expanding the value proposition beyond hardware. Samsung Electronics leverages its Tizen OS to offer integrated smart cooking experiences across its appliance portfolio. BSH Hausgeräte GmbH differentiates through its Home Connect platform, which enables remote diagnostics and control. This shift transforms one-time hardware sales into recurring revenue streams and deeper customer engagement.
Household cooking appliances encompass a range of devices designed for food preparation in residential settings. These products utilize thermal energy transfer via methods like resistive heating elements, gas combustion, or electromagnetic induction, often featuring materials like stainless steel and tempered glass for durability. While electric stoves and ovens constitute a mature product category, induction technology represents the fastest-growing segment due to its efficiency and safety. The online distribution channel is gaining share from traditional retail, especially for smaller appliances like microwaves and slow cookers.
Product design and market access are governed by a matrix of international regulations, including the EU's CE marking for safety and the US EPA's ENERGY STAR program for efficiency. In China, GB standards for electrical safety and energy consumption are mandatory for all appliances sold domestically. Manufacturers must now navigate divergent regional requirements for smart appliance cybersecurity and data privacy.
Market Dynamics
The household cooking appliance market is being fundamentally reshaped by the convergence of IoT connectivity with stringent global energy efficiency mandates. This dual pressure forces manufacturers to innovate not just on hardware performance but also on software-driven services and energy consumption optimization.
Growth Catalysts
- Induction Technology Adoption:Electromagnetic induction offers superior energy efficiency and safety compared to traditional resistive heating or gas, driving replacement sales and adoption in new residential construction, particularly in markets with high electricity costs.
- Urbanization in India:Rapidly growing disposable incomes and a cultural emphasis on kitchen modernization within India's expanding urban middle class are creating concentrated pockets of high demand for advanced and aesthetically pleasing cooking appliances.
- EU Ecodesign Directive:This regulatory framework mandates stricter energy efficiency and reparability standards for new appliances. This not only spurs innovation but also accelerates the replacement cycle for older, less efficient models across the European Union.
Market Restraints
- High Upfront Costs:The significant price premium for smart, connected, and high-efficiency appliances like induction cooktops and combination steam ovens remains a barrier to mass adoption, particularly in price-sensitive consumer segments and developing economies.
- Semiconductor Dependency:The increasing integration of smart features, digital displays, and IoT connectivity makes appliance manufacturing dependent on the volatile global supply chain for microcontrollers and other semiconductor components, introducing production risks.
- Long Replacement Cycles:Major cooking appliances are durable goods with long lifespans. This inherent market inertia slows the overall pace of technological adoption, as consumers often wait for a device to fail before purchasing a replacement.
Strategic Opportunities
- Software and Service Monetization:Expanding subscription-based models for guided recipes, specialized cooking modes, and remote diagnostic services offers a path to recurring revenue streams, shifting the business model beyond a one-time hardware sale.
- Smart Home Ecosystem Integration:There is a significant opportunity to develop appliances that seamlessly integrate with major smart home platforms, enabling unified control, voice commands, and automation routines that enhance user convenience and energy management.
- Penetration in Latin America:As urbanization and household incomes rise in countries like Brazil and Mexico, a growing consumer base is seeking to upgrade from basic appliances, creating a new growth frontier for mid-range and premium product categories.
Industry Challenges
- Cybersecurity and Data Privacy Compliance:Manufacturers face the complex and costly challenge of complying with a patchwork of regional regulations governing IoT device security and user data privacy, such as the EU's GDPR and various state-level laws in the US.
- Platform Interoperability:A lack of standardization among proprietary smart home platforms creates friction for consumers and limits the potential of a fully connected kitchen, challenging manufacturers to support multiple, non-compatible ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Cooking Appliance Market |
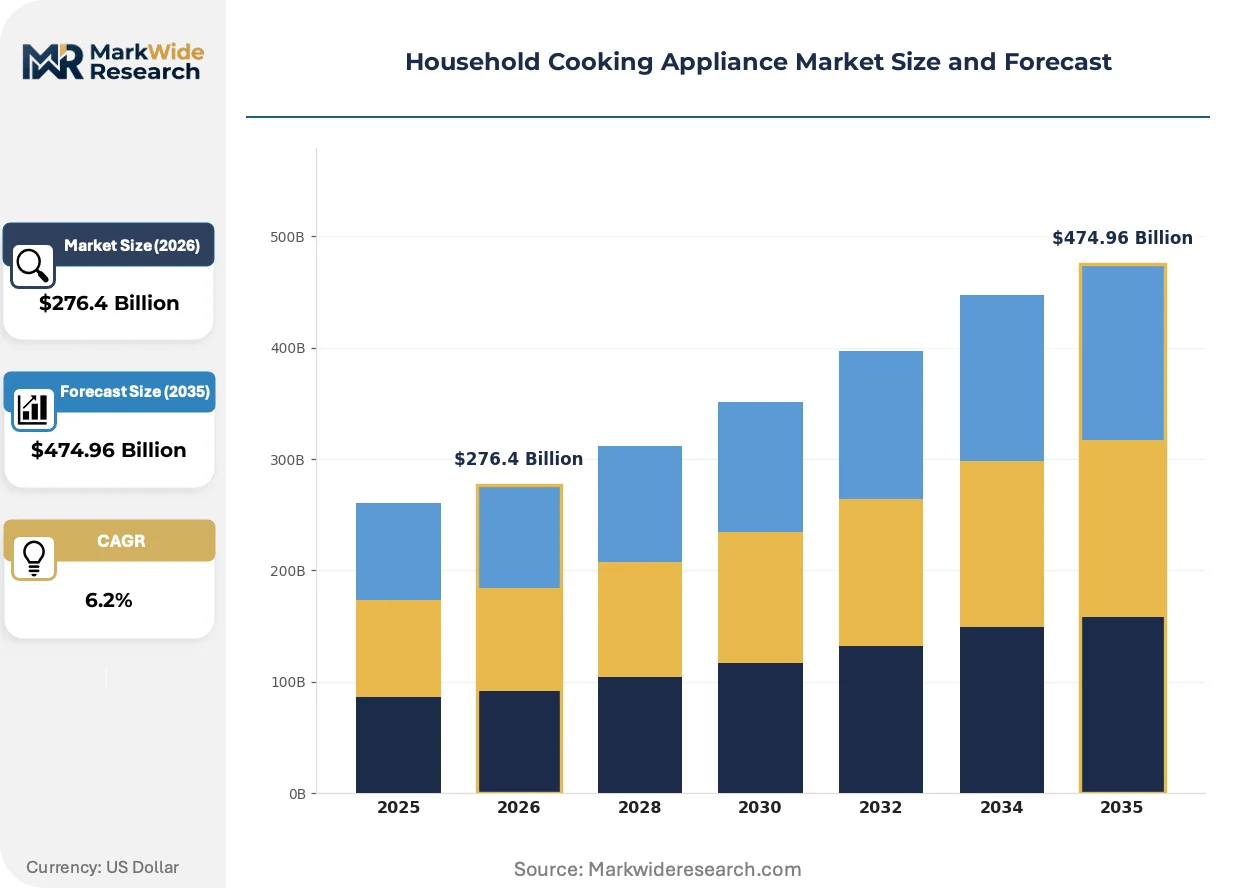
| Market Size in 2026 | $276.4 Billion |
| Market Size in 2035 | $474.96 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stove, Oven, Microwave, Slow Cooker Technology: Electric, Gas, Induction, Convection End User: Residential, Commercial, Catering, Food Service Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Whirlpool Corporation, Electrolux AB, BSH Hausgeräte GmbH, Samsung Electronics, LG Electronics, GE Appliances, Midea Group, Haier Group, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Cooking Appliance Market Strategic Shifts & Innovations
Product value is shifting from durable hardware to intelligent software platforms. This transformation is compelling manufacturers to build capabilities in user interface design, data analytics, and recurring service delivery to complement their traditional engineering expertise.
AI-driven cooking assistants use internal cameras and sensors to recognize food types and automatically adjust cooking parameters like time and temperature. This technology is being adopted by consumers in the premium residential segment who seek convenience and consistent culinary results. The integration of AI is consolidating the value of an appliance into its software capabilities, moving beyond simple thermal performance.
Evolving requirements under the US EPA's ENERGY STAR program are pushing for greater efficiency in cooking appliances. This forces investment in advanced heat transfer technologies and improved insulation to meet certification thresholds, which are a key marketing differentiator. The induction cooktop and convection oven categories are most impacted, as manufacturers compete on energy consumption metrics to gain the label.
A behavioral shift towards direct-to-consumer (DTC) online sales is gaining momentum for smaller and mid-sized appliances. This model, often paired with content marketing around recipes and lifestyle, bypasses traditional big-box retail channels that have historically dominated distribution. This trend is most pronounced in North America, where established e-commerce logistics and consumer comfort with online purchasing facilitate brand-direct relationships.
Household Cooking Appliance Market Segmentation
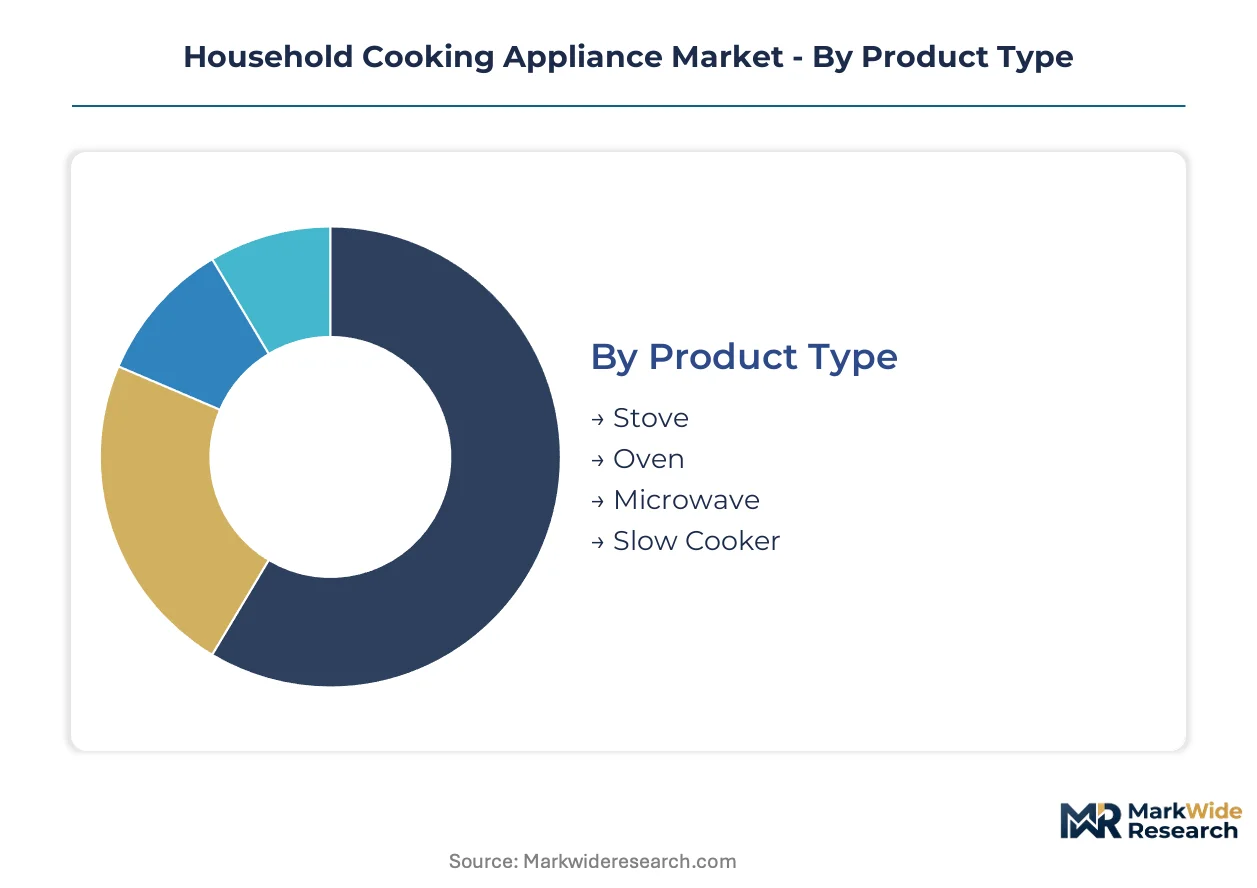
Understanding the segmentation of the household cooking appliance market allows manufacturers to precisely target product development and marketing efforts. This detailed breakdown helps identify specific consumer needs, technological preferences, and optimal distribution strategies across diverse market landscapes, ensuring competitive advantage.
Product Type:
Manufacturing cooking appliances demands varying levels of capital investment, influencing production scale and market entry barriers for different product types.
- Stove:These appliances typically combine multiple cooking surfaces, often using gas combustion or electric resistive heating elements, and are foundational in most kitchens. Demand for stoves is prevalent in new residential construction in India, driven by rapid urbanization and household modernization.
- Oven:Enclosed cooking chambers that use thermal energy transfer for baking, roasting, and broiling, frequently integrated with smart features for enhanced functionality. European households are increasingly adopting efficient oven models, spurred by the EU's Ecodesign directive.
- Microwave:Utilizes electromagnetic radiation to heat food quickly, serving as a convenience appliance in most residential settings. Online distribution channels are gaining significant share for microwave sales in North America.
- Slow Cooker:Designed for low-temperature, long-duration cooking, these appliances offer convenience for preparing stews and casseroles. This product type appeals to busy residential consumers seeking simplified meal preparation.
Stove products absorb the bulk of installed manufacturing capacity; Slow Cooker appliances are expanding most quickly.
Technology:
The cost tier of cooking appliance technology significantly influences consumer purchasing decisions, ranging from foundational options to premium innovations.
- Induction:This technology utilizes electromagnetic fields to directly heat cookware, offering superior energy efficiency and safety. Induction technology represents the fastest-growing segment, with demand concentrating in European markets due to stringent efficiency mandates.
- Electric:Appliances that rely on resistive heating elements to generate heat, forming a mature product category with widespread adoption in many developed residential markets. Electric stoves and ovens are foundational in households with established electrical infrastructure.
- Gas:Appliances that use natural gas or propane combustion to generate heat, favored in regions with established gas utility networks. Gas cooking remains popular for its precise temperature control among culinary enthusiasts.
- Convection:Incorporates a fan to circulate hot air within an oven, ensuring more even cooking and faster preparation times. Convection technology is primarily found in premium oven models.
Demand for Electric technology remains robust, while Induction technology demonstrates significant market penetration.
End User:
The specific application environment dictates the functional requirements and durability standards for cooking appliances.
- Residential:Appliances designed for use in private homes, emphasizing user-friendliness, aesthetic integration, and energy efficiency. Demand in urbanizing areas of India is driven by rising incomes and a cultural emphasis on kitchen modernization.
- Commercial:Heavy-duty appliances built for professional kitchens in restaurants, hotels, and institutional settings, requiring high capacity and durability. The growing hospitality sector fuels demand for robust commercial cooking equipment.
- Catering:Specialized equipment for mobile or event-based food preparation, prioritizing portability, rapid heating, and ease of cleaning. Catering operations require versatile appliances that can adapt to various venues.
- Food Service:Appliances for cafeterias, fast-food outlets, and other establishments focused on high-volume food production. This segment demands specialized equipment for specific menu items.
Residential represents the largest volume segment; Commercial is experiencing accelerated investment.
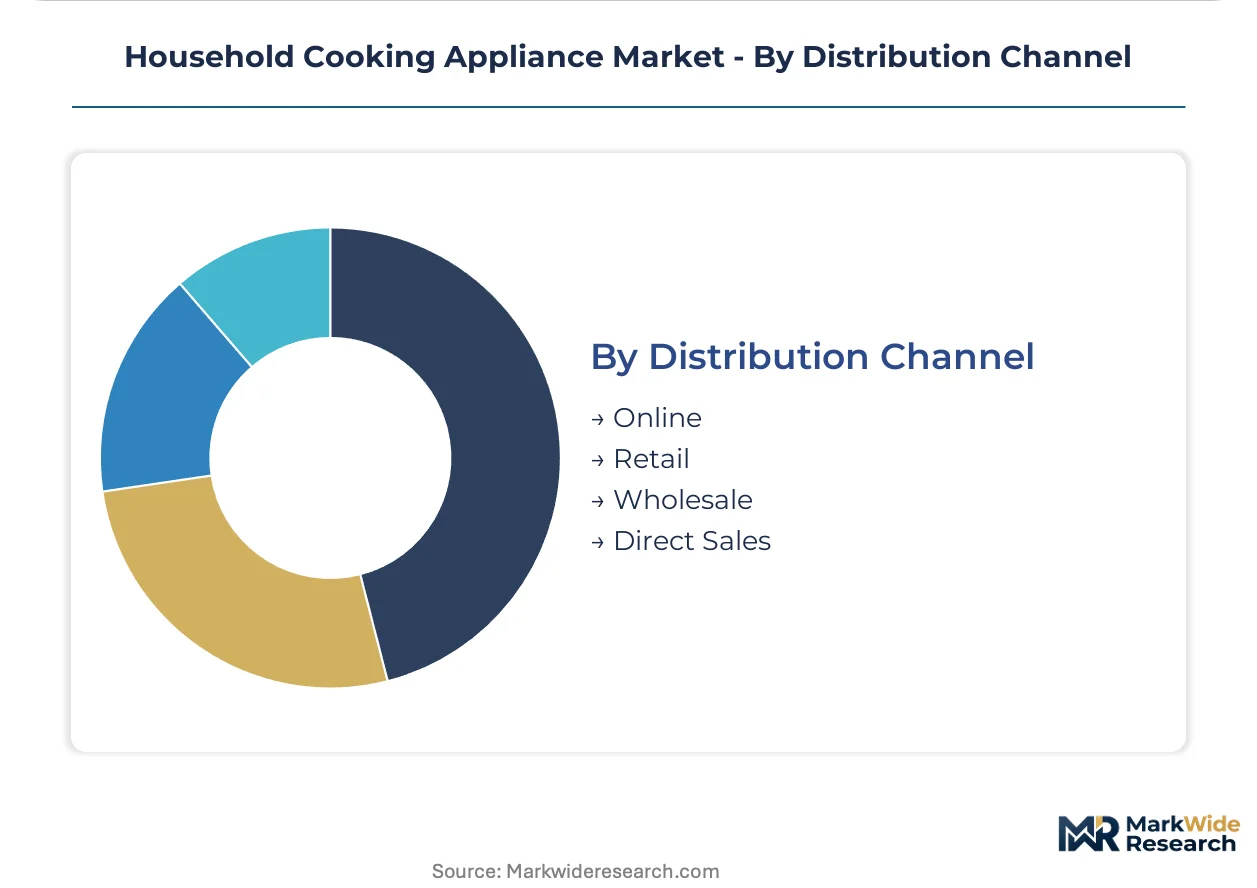
Distribution Channel:
The volume and reach of distribution channels shape market accessibility and consumer engagement strategies for appliance manufacturers.
- Online:E-commerce platforms and brand websites that facilitate direct purchasing and delivery, gaining share especially for smaller, more portable appliances. This channel is particularly strong in North America, supported by established logistics.
- Retail:Traditional brick-and-mortar stores, including big-box retailers and specialized appliance showrooms, where consumers can physically inspect products. Retail stores remain a significant channel for larger, higher-value cooking appliances.
- Wholesale:Sales of cooking appliances in bulk to distributors, contractors, or smaller retail chains, often at reduced prices. Wholesale channels provide efficient supply chain solutions for large-scale procurement.
- Direct Sales:Manufacturers selling directly to consumers, bypassing intermediaries, often through dedicated brand stores or online portals. This channel allows for greater brand control and direct customer relationships.
Traditional Retail channels maintain a strong presence; Online channels are rapidly gaining market share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global household cooking appliance market exhibits a distinct geographical divide between mature consumption hubs and emerging production centers. Demand for advanced features and energy efficiency often originates in developed economies, while manufacturing scale frequently concentrates in cost-competitive regions. This dynamic shapes investment flows and supply chain configurations across continents.
United States
Demand for smart home integration and ENERGY STAR certified appliances drives adoption in the United States. The US EPA's ENERGY STAR program encourages manufacturers to develop more energy-efficient models, impacting consumer purchasing decisions. Silicon Valley and other tech hubs in California are focal points for smart appliance software development and ecosystem integration.
Germany
German consumers prioritize product durability and advanced cooking functionalities, especially for premium oven models. The EU's Ecodesign directive mandates stringent energy efficiency standards for new appliances sold within the European Union. Munich and Stuttgart serve as key centers for engineering and design innovation in high-end kitchen equipment manufacturing.
India
Rapid urbanization and rising household incomes fuel demand for modern kitchen appliances in India. The BIS (Bureau of Indian Standards) sets quality and safety benchmarks for domestically sold electrical goods, including cooking appliances. Major metropolitan areas like Mumbai and Bengaluru are experiencing concentrated demand for aesthetically pleasing and technologically advanced stoves and ovens.
China
China's market sees high demand for induction cooktops and integrated kitchen solutions, supported by a strong domestic manufacturing base. GB standards for electrical safety and energy consumption are mandatory for all appliances sold within the country. The Yangtze River Delta region, particularly cities like Shanghai and Hangzhou, hosts significant production capacity and R&D for smart cooking technologies.
Household Cooking Appliance Market Key Industry Players
Top-tier vendors anchor the premium segment, while a diverse array of regional and specialized manufacturers competes in mid-range and value categories. The market structure exhibits a tiered consolidation, with a few global conglomerates holding substantial share. Strategic archetypes include diversified electronics giants, dedicated appliance specialists, and regional players focused on specific market needs. Dominant competitive moves involve portfolio diversification into smart home ecosystems and strategic partnerships for technology co-development.
Diversified electronics conglomerates, such as Samsung Electronics, exemplify the push towards integrated smart home ecosystems, leveraging their extensive technology portfolios to offer seamless user experiences. European appliance specialists like BSH Hausgeräte GmbH occupy a strong position in the premium segment, emphasizing design, energy efficiency, and advanced cooking functionalities. Chinese manufacturing powerhouses, including Midea Group, anchor the high-volume production and accessible technology segments, catering to a broad consumer base with competitive pricing and rapid innovation cycles.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Electrolux AB |
| BSH Hausgeräte GmbH |
| Samsung Electronics |
| LG Electronics |
| GE Appliances |
| Midea Group |
| Haier Group |
| Panasonic Corporation |
| Others |
Cost & Logistics Intelligence
The significant price premium for smart, high-efficiency appliances creates a clear divergence in market dynamics, influencing both manufacturer investment in advanced technologies and the global sourcing strategies for critical components.
Pricing Analysis
Margin tightening for basic appliance models reflects intense competition from high-volume manufacturers. The dominant pricing model remains transactional for hardware, with an evolving shift towards subscription-based services for software features. Price differentiation stems from smart functionality integration and compliance with energy efficiency standards like ENERGY STAR and EU Ecodesign. Pricing pressure intensifies in value segments due to competitive offerings from Asian manufacturers. Premium segment consumers prioritize advanced features and brand, exhibiting lower price sensitivity compared to price-sensitive buyers in developing economies.
Supply Chain Analysis
The evolving distribution model for household cooking appliances increasingly favors online channels for smaller units, while larger appliances still rely on traditional retail networks. Geographic supply concentration centers on China and South Korea, which host major manufacturing powerhouses. Production depends on critical raw materials like stainless steel and tempered glass, alongside specialized microcontrollers for smart features. Semiconductor dependency introduces significant supply chain risk due to volatile global component availability. Distribution runs through a hybrid model, balancing direct-to-consumer sales with established wholesale and retail partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The household cooking appliance market operates under supply constraints, particularly for semiconductor components, which indirectly props up pricing for feature-rich smart appliances.
For Market Incumbents:Lock in existing customer bases by expanding software-driven services and smart home ecosystem integration. Develop proprietary operating systems like Samsung's Tizen OS to enhance user experience and create walled gardens against emerging threats from specialized software providers. Invest in advanced heat transfer technologies and improved insulation to meet evolving energy efficiency mandates. Control key distribution channels, especially online, to counter the rising influence of direct-to-consumer brands.
For New Entrants and Emerging Players:The price-point gap between premium smart appliances and basic models offers white-space opportunities for mid-range innovation. Target rapidly urbanizing areas in Latin America and India with aesthetically pleasing, technologically advanced appliances at competitive prices. Focus on specific product types like slow cookers and microwaves, leveraging online distribution channels for market penetration. Implement content marketing strategies around recipes and lifestyle to build brand awareness and engage consumers directly.
For Investors and Strategic Acquirers:Re-rating potential sits with appliance manufacturers successfully transitioning to recurring revenue models via software and service monetization. Acquisition targets include dedicated appliance specialists with strong regional market access in high-growth areas or those possessing robust smart home integration platforms. The long-term viability of this market hinges on continued innovation in energy efficiency and seamless smart home connectivity. A key signal to watch is the growth in subscription service adoption rates across major appliance brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Software and Service Monetization | Transforms one-time hardware sales into predictable recurring revenue streams for manufacturers. |
| Smart Home Ecosystem Integration | Enhances user convenience and energy management through unified control and automation routines. |
| Investment in Induction Technology | Drives replacement sales and adoption due to superior energy efficiency and safety benefits. |
| Expansion of Direct-to-Consumer Channels | Bypasses traditional retail, fostering direct customer relationships and brand control. |
| Localized Product Development for Emerging Markets | Addresses specific consumer needs and income levels in regions like India and Latin America. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with product development engineers, sales channel managers, and regulatory compliance officers. This approach ensured a robust understanding of market dynamics, triangulating insights from both top-down industry reports and bottom-up stakeholder perspectives.
Market sizing and forecasts were modeled at granular levels across product type, technology, end user, distribution channel, and key geographies over the analysis window. Compound annual growth rates were derived from historical data and projected trends, considering specific industry inputs such as evolving energy efficiency mandates and global urbanization rates.
Inputs from governmental energy agencies and appliance manufacturer disclosures were available through the study window; gaps in emerging market consumption data introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Bakeware Market
Kitchen Appliances
India Mixer Grinder Market
Kitchen Appliances
Global Single Serve Coffee Maker Market
Kitchen Appliances
Smart Connectivity Kitchen Appliances Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Asia Pacific Household Electric Grills Market
Kitchen Appliances
Built-In Coffee Machine Market
Kitchen Appliances
Household Kitchen Appliances Market
Kitchen Appliances
Toast Maker Market
Kitchen Appliances
Electric Lunch Box Market
Kitchen Appliances
Outdoor Commercial Grills Market
Kitchen Appliances
Cotton Candy Maker Market
Kitchen Appliances
Smart Cooktop Market
Kitchen Appliances
South Korea Electric Hobs Market
Kitchen Appliances
Portable Sandwich Maker Market
Kitchen Appliances
Range Cooker Market