
 United States Electric Vegetable Choppers Market | 2026-2036
United States Electric Vegetable Choppers Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electric Vegetable Choppers Market Insights
Subscription-based equipment leasing is reshaping competitive dynamics in the United States electric vegetable chopper landscape, lowering capital barriers for small restaurants and cloud kitchens. Hamilton Beach leverages direct-to-foodservice distribution partnerships to sustain volume in the commercial segment. Ninja differentiates through high-RPM motor technology that commands premium positioning in the household channel. Cuisinart anchors its market presence with extensive countertop appliance ecosystems that drive cross-sell attachment rates.
Electric vegetable choppers are motorized food preparation appliances utilizing stainless steel or titanium-coated blades driven by universal or brushless DC motors, typically operating between 200 and 700 watts to dice, mince, or puree vegetables through rotary or pulsed cutting action. These units serve commercial kitchens and domestic consumers by reducing manual prep time and improving cut consistency for high-volume operations. The multi-function chopper segment leads value generation as buyers prioritize space-efficient units combining slicing, shredding, and chopping capabilities in single footprints. Online retail channels represent the fastest-growing distribution pathway, reflecting permanent shifts in how small food businesses and households research and procure kitchen equipment. Professional chopper demand concentrates in food processing units where throughput requirements exceed household-grade capacity.
The U.S. Consumer Product Safety Commission enforces blade guard and interlock standards that elevate engineering costs for entry-level manufacturers, while the Department of Energy's appliance efficiency regulations constrain motor specification choices across the product stack. California's Title 20 appliance standards create additional compliance thresholds that effectively filter out lower-tier imports from the state's commercial buyer pool. Stakeholders must monitor evolving municipal electrification incentives and commercial kitchen energy audits that increasingly influence equipment replacement cycles.
Market Dynamics
Commercial kitchen operators across the United States are accelerating equipment replacement cycles as labor costs climb and municipal electrification audits reshape capital planning timelines for foodservice operations.
Growth Catalysts
- OSHA workplace safety mandates:Stricter enforcement of repetitive strain injury protocols pushes restaurants toward motorized prep solutions that reduce manual cutting hours.
- Cloud kitchen proliferation:Ghost kitchen operators in Texas and California prioritize compact, multi-function choppers to maximize throughput in limited square footage.
- Brushless DC motor adoption:Efficiency gains from permanent magnet designs lower operating costs while maintaining blade speeds above 15,000 RPM.
Market Restraints
- Stainless steel price volatility:Fluctuations in 304-grade sheet metal costs compress margins for mid-tier manufacturers dependent on commodity sourcing.
- California Title 20 compliance:Appliance efficiency thresholds filter out lower-wattage imports, limiting budget options for small operators in the state's densest markets.
- Manual knife skill retention:Fine-dining establishments maintain traditional prep methods as a staffing and branding differentiator against automated alternatives.
Strategic Opportunities
- Subscription equipment leasing:Monthly payment models lower capital barriers for independent restaurants and emerging cloud kitchen chains.
- Texas commercial construction boom:New food hall and hotel developments in Dallas-Fort Worth and Houston create concentrated demand for professional-grade installations.
- IoT-enabled predictive maintenance:Sensor-integrated motors allow remote monitoring of blade wear and motor health, opening recurring revenue streams for manufacturers.
Industry Challenges
- Electrical contractor coordination:Commercial kitchen retrofits require certified 240V outlet installation, extending deployment timelines and raising soft costs.
- Interlock mechanism calibration:U.S. Consumer Product Safety Commission blade guard standards demand precise engineering tolerances that strain quality control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electric Vegetable Choppers Market |
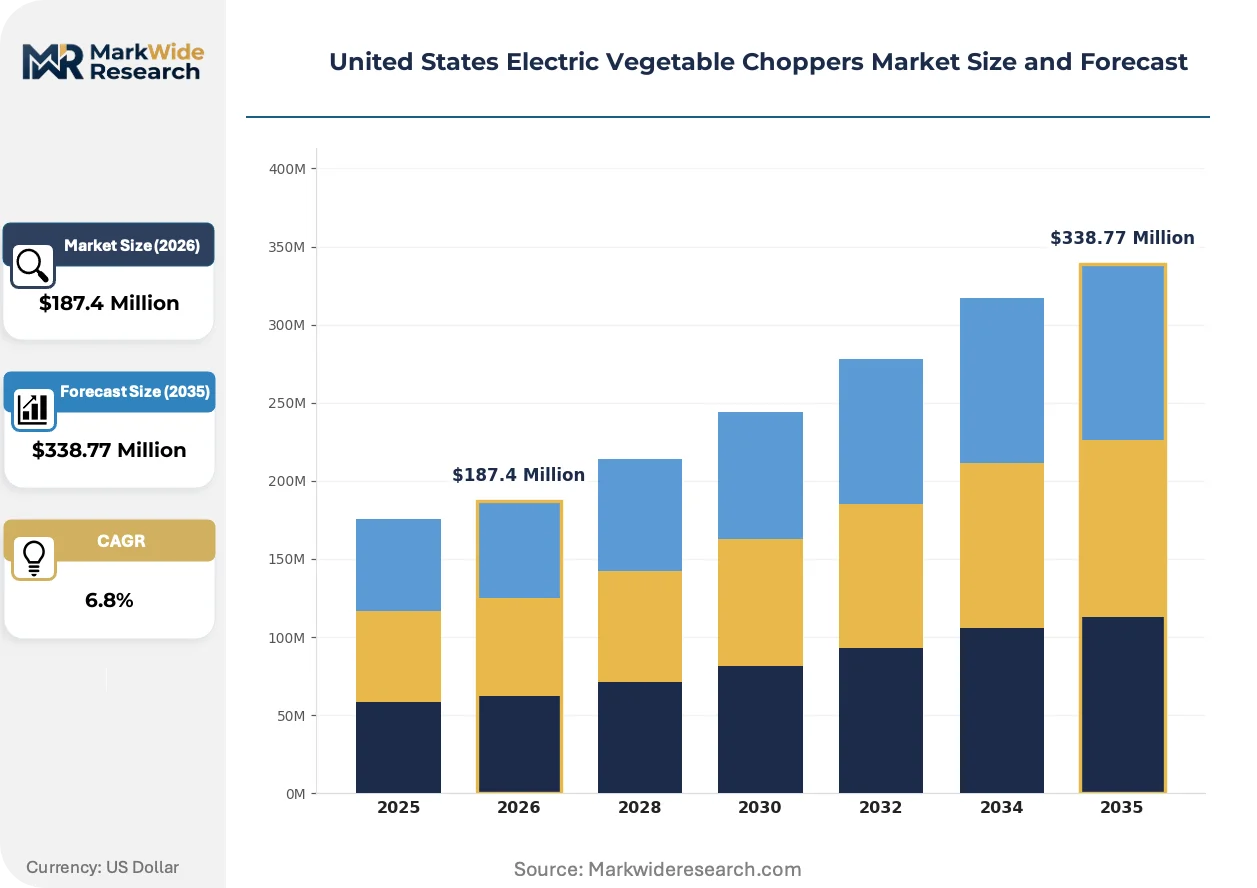
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Chopper, Electric Chopper, Multi-Function Chopper, Professional Chopper End User: Households, Restaurants, Catering Services, Food Processing Units Feature: Compact Design, Safety Lock, Multiple Speed, Easy Clean Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Proctor Silex, KitchenAid, Hamilton Beach, Black+Decker, Cuisinart, Brentwood, Oster, Ninja, Braun, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electric Vegetable Choppers Market Trends and Innovations
Equipment manufacturers are reconfiguring product architectures around energy efficiency mandates while distribution channels fragment between direct foodservice partnerships and digital procurement platforms.
Titanium-nitride blade coatings extend edge retention by 40% compared to standard stainless steel, reducing replacement frequency in high-volume commissary kitchens. Food processing facilities in the Midwest are adopting these coated systems fastest, driven by continuous-run operational requirements. The technology is rendering obsolete quarterly blade swap schedules that previously disrupted production lines.
The Department of Energy's appliance efficiency standards constrain motor wattage ceilings while preserving torque output requirements. Manufacturers must redesign winding configurations and magnetic circuits to satisfy compliance without sacrificing throughput. California's Title 20 regulations impose additional testing protocols that smaller import brands cannot satisfy, effectively ceding that geography to domestic and established international suppliers.
Small restaurants are abandoning traditional equipment dealers in favor of direct manufacturer websites and foodservice-specific e-commerce platforms. This channel migration compresses price discovery cycles and exposes buyers to specification comparisons previously mediated by sales representatives. Cloud kitchen operators in Atlanta and Phoenix demonstrate the strongest preference for digital procurement, where lease-to-own options and rapid shipping offset the inability to inspect units physically.
United States Electric Vegetable Choppers Market Segmentation
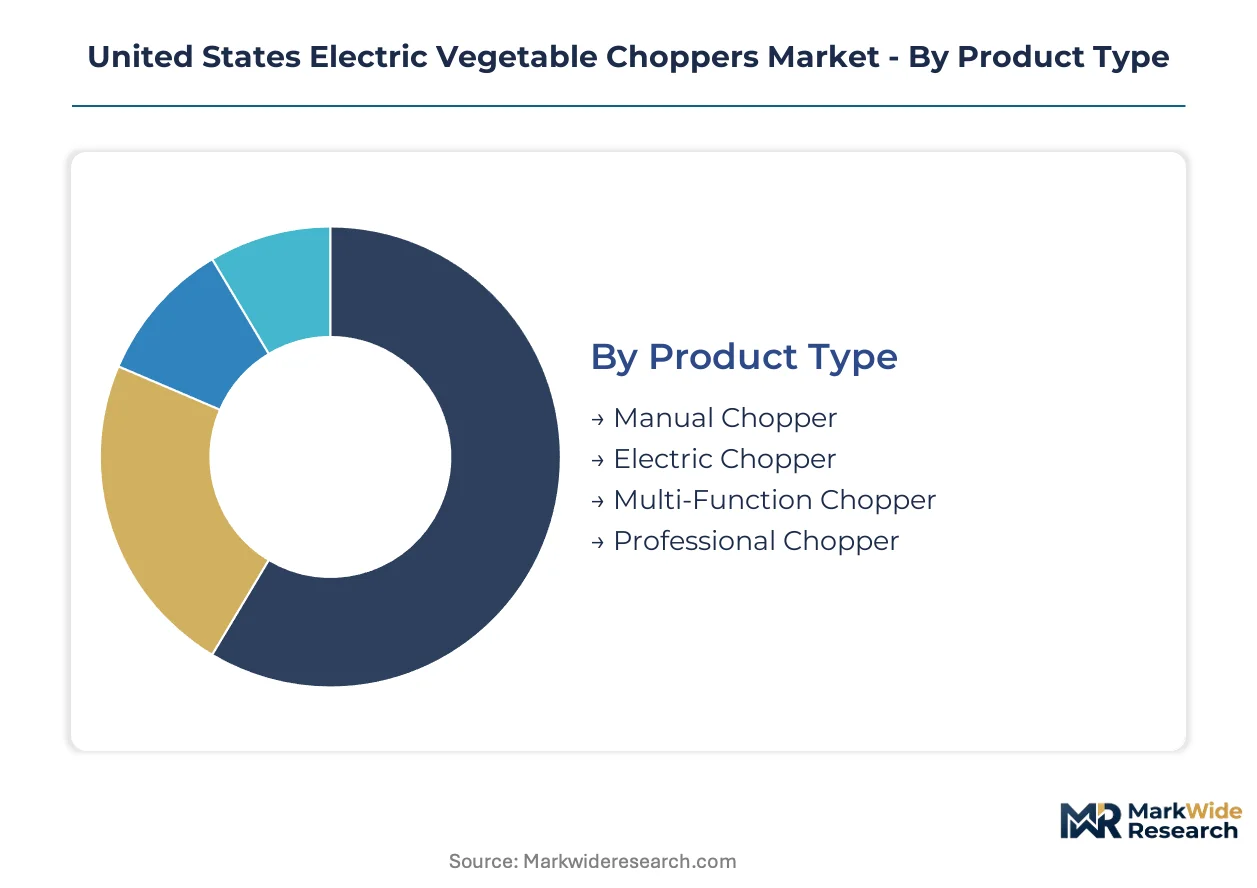
Electric vegetable chopper segmentation reveals distinct procurement patterns between cost-conscious domestic buyers and throughput-driven commercial operators. Category boundaries increasingly blur as multi-function units capture share from single-purpose alternatives.
Product Type:
Mature manual designs coexist with emerging smart-motor configurations across the maturity spectrum.
- Manual Chopper:Hand-press mechanisms utilizing spring-loaded blade arrays serve price-sensitive segments and backup redundancy roles in professional kitchens. Demand persists in rural Texas counties where electrical infrastructure reliability concerns delay electrification investments.
- Electric Chopper:Universal motor platforms operating between 200-400 watts dominate household penetration through mass-market retail placement. California Title 20 compliance costs filter out entry-tier imports, concentrating volume with domestic and established international suppliers.
- Multi-Function Chopper:Modular blade systems combining slicing, shredding, and dicing attachments address space constraints in urban cloud kitchens.
- Professional Chopper:Brushless DC motor architectures exceeding 700 watts serve continuous-run food processing operations.
Electric Chopper retains volume leadership; Multi-Function Chopper holds the steepest expansion curve.
End User:
Customer archetypes span from individual meal prep to industrial-scale commissary operations with diverging specification priorities.
- Households:Countertop units under 10-pound weight targets prioritize storage efficiency and dishwasher-safe components. Demand concentrates in suburban California markets where dual-income households trade time savings against premium positioning.
- Restaurants:NSF-certified construction with thermal overload protection withstands back-of-house temperature swings and sanitization protocols. Independent operators in Dallas-Fort Worth accelerate replacement cycles amid labor cost pressures.
- Catering Services:Portable designs with locking lid mechanisms address transport vibration and off-site power variability.
- Food Processing Units:Stainless steel contact surfaces and sealed bearing housings satisfy USDA facility audit requirements.
Households retain volume leadership; Food Processing Units hold the steepest expansion curve.
Feature:
Specification bundles differentiate across price tiers without universal premium hierarchy.
- Compact Design:Sub-8-inch footprint targets studio apartment dwellers and food truck operators with severe square footage constraints.
- Safety Lock:Dual-interlock blade engagement satisfies CPSC child safety mandates and reduces liability exposure for commercial operators.
- Multiple Speed:Variable RPM control between 8,000 and 22,000 blade rotations enables texture gradation from coarse dice to fine puree.
- Easy Clean:Tool-free disassembly and dishwasher-safe bowls reduce labor allocation to equipment maintenance in high-turnover kitchen environments.
Safety Lock retains volume leadership; Compact Design holds the steepest expansion curve.
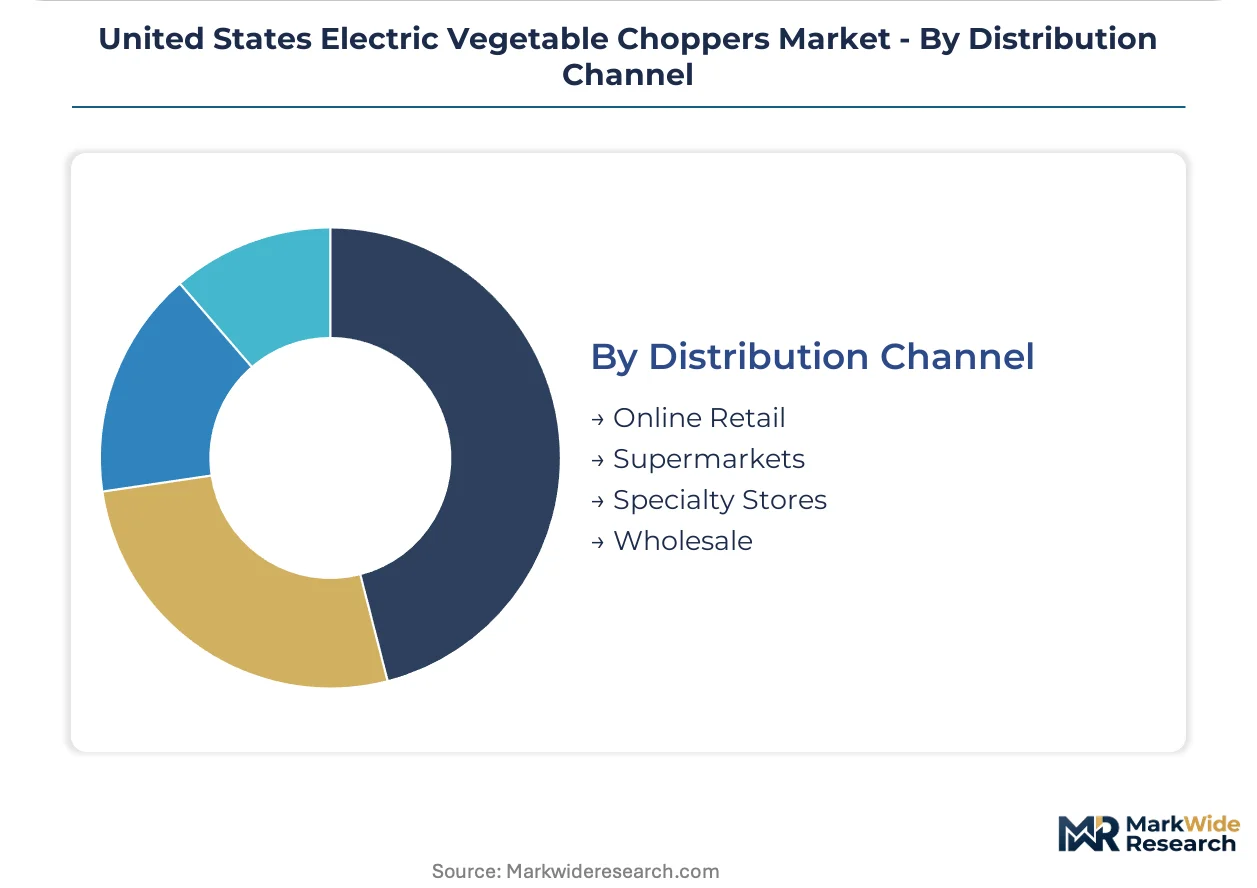
Distribution Channel:
Channel selection reflects buyer sophistication and procurement urgency requirements.
- Online Retail:Direct-to-consumer platforms and foodservice e-commerce enable specification comparison and lease-to-own financing. Cloud kitchen operators in Phoenix and Atlanta demonstrate strongest preference for digital procurement pathways.
- Supermarkets:Impulse placement and seasonal promotional cycles drive household segment trial purchases.
- Specialty Stores:Sur La Table and Williams Sonoma provide tactile evaluation for premium household positioning.
- Wholesale:Restaurant supply cooperatives and broadline distributors consolidate volume procurement for multi-unit operators.
Online Retail retains volume leadership; Wholesale holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal electrification incentives and state-level appliance efficiency mandates are redirecting procurement flows toward compliant manufacturing clusters. The Department of Energy's appliance standards create compliance thresholds that reshape sub-regional competitive positioning. California and Texas concentrate demand through divergent regulatory pathways.
California
Title 20 appliance efficiency standards filter out lower-tier imports from the state's commercial buyer pool. The California Energy Commission enforces testing protocols that elevate engineering costs for entry-level manufacturers. Los Angeles and San Francisco food hall developments drive concentrated demand for professional-grade installations with sealed bearing housings.
Texas
Dallas-Fort Worth and Houston commercial construction booms create concentrated demand for NSF-certified back-of-house equipment. OSHA workplace safety mandates in metropolitan counties accelerate replacement cycles for motorized prep solutions. Austin cloud kitchen clusters prioritize compact multi-function units to maximize throughput in limited square footage.
New York Metro
Fine-dining establishments in Manhattan maintain manual knife skill retention as staffing differentiators against automated alternatives. The state's energy audit requirements for commercial kitchens influence equipment replacement timelines. Brooklyn commissary kitchens adopt titanium-nitride blade coatings to extend edge retention in continuous-run operations.
Florida
Orlando and Miami catering services drive demand for portable designs with locking lid mechanisms addressing transport vibration. The state's hurricane resilience codes for commercial infrastructure extend deployment timelines for electrical contractor coordination. Tampa food processing facilities prioritize brushless DC motor architectures exceeding 700 watts for continuous-run requirements.
Illinois
Chicago's restaurant density concentrates procurement of subscription-based equipment leasing models lowering capital barriers for independent operators. The state's commercial kitchen energy audit programs reshape capital planning timelines for foodservice operations. Midwest food processing facilities adopt sensor-integrated motors enabling remote monitoring of blade wear.
United States Electric Vegetable Choppers Market Competitive Landscape
On the supply side, the industry is consolidating around established domestic brands with compliant manufacturing footprints and direct foodservice distribution partnerships. Three strategic archetypes dominate: mass-market retailers leveraging private-label placement, premium-tier specialists commanding positioning through motor technology differentiation, and commercial-grade fabricators anchoring volume through NSF certification and thermal overload protection. Dominant competitive moves include strategic partnerships with restaurant supply cooperatives and portfolio diversification into multi-function modular systems.
Within the mass-market tier, Proctor Silex and Black+Decker occupy positions emphasizing accessible price points through broad retail placement. Hamilton Beach exemplifies the commercial-direct archetype through foodservice distribution partnerships sustaining volume in the restaurant segment. Ninja represents the premium-tier specialist position, with high-RPM motor technology commanding differentiated household channel positioning. Cuisinart anchors the ecosystem-integrated archetype through extensive countertop appliance portfolios driving cross-sell attachment rates.
| Leading Market Players |
|---|
| Proctor Silex |
| KitchenAid |
| Hamilton Beach |
| Black+Decker |
| Cuisinart |
| Brentwood |
| Oster |
| Ninja |
| Braun |
| Others |
Pricing and Supply Chain Analysis
Stainless steel price volatility determines both pricing tier spreads and supply chain shape across the United States electric vegetable chopper market. Fluctuations in 304-grade sheet metal costs compress margins for mid-tier manufacturers dependent on commodity sourcing, forcing pricing stratification across NSF-certified professional units, Title 20-compliant domestic models, and entry-tier imports.
Pricing Analysis
Certification level creates the primary spread between NSF-rated commercial units and household-grade alternatives. Three-tier pricing structure across premium brushless DC motor systems, standard universal motor platforms, and economy manual backups reflects motor wattage and compliance investment. Pricing pressure stems from California Title 20 testing costs that filter out lower-wattage imports. Cloud kitchen operators in Texas demonstrate highest price sensitivity, while food processing facilities in the Midwest prioritize throughput over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for blade and motor component sourcing. Manufacturing concentrates in China for universal motor assemblies, Mexico for NSF-certified fabrication, and domestic facilities for brushless DC systems. Raw material dependencies center on 304-grade stainless steel from South Korea, neodymium magnets for permanent magnet motors, and copper winding stock. Single-source vulnerability persists in titanium-nitride coating technology. Distribution runs through restaurant supply cooperatives, broadline distributors, and direct-to-foodservice e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States electric vegetable chopper market sits in a cyclical recovery phase as commercial kitchen replacement cycles accelerate under OSHA workplace safety mandates and municipal electrification audit requirements.
For Market Incumbents: Build regulatory compliance moats through California Title 20 pre-certification and NSF thermal overload protection investments. Defend against emerging cloud kitchen equipment leasing platforms by anchoring direct foodservice distribution partnerships. Prioritize backward integration into brushless DC motor winding capabilities to secure supply against commodity volatility in copper and rare earth inputs. For New Entrants and Emerging Players: Mid-market independent restaurants in Dallas-Fort Worth and Houston represent the most penetrable entry point given construction-driven demand concentration and limited incumbent leasing penetration. Subscription-based equipment financing models lower capital barriers for this buyer archetype. Target digital-native procurement pathways with rapid shipping and specification transparency to offset physical inspection limitations. For Investors and Strategic Acquirers: Department of Energy appliance efficiency standard revisions reshape the acquisition landscape toward compliant manufacturing footprints. Long-term viability favors domestic and established international suppliers with Title 20 testing capabilities. Monitor municipal electrification incentive program expansions as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certification Investment | Unlocks commercial kitchen procurement channels and satisfies Dallas-Fort Worth health department requirements. |
| Brushless DC Motor Transition | Aligns with Department of Energy efficiency mandates while maintaining blade speeds above 15,000 RPM. |
| Direct Foodservice Distribution Partnership | Bypasses traditional equipment dealers and captures cloud kitchen procurement migration to digital platforms. |
| Subscription Equipment Leasing Launch | Lowers capital barriers for independent restaurants and captures recurring revenue streams. |
| Titanium-Nitride Coating Adoption | Extends blade retention 40% and reduces replacement frequency in Midwest food processing facilities. |
Research Methodology
A spread of perspectives from commercial kitchen operators, restaurant supply distributors, equipment leasing platform executives, and NSF certification auditors converged on the working assumptions. Primary interviews with back-of-house managers, procurement leads at multi-unit restaurant groups, and electrical contractors specializing in commercial kitchen retrofits combined with secondary validation. Sources included U.S. Department of Energy appliance efficiency filings, California Energy Commission Title 20 test results, OSHA workplace safety enforcement data, and customs records for 304-grade stainless steel imports. Bottom-up unit shipment estimates triangulated against top-down commercial construction spending correlations.
Demand-supply balance dynamics anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end user archetype, motor technology tier, and regional regulatory cluster. CAGRs derived from weighted average replacement cycle frequencies and new installation correlations with commercial construction permits. Industry-specific inputs incorporated cloud kitchen square footage constraints and municipal electrification audit adoption curves.
Practitioners should monitor stainless steel commodity price movements, California Title 20 testing protocol amendments, and OSHA repetitive strain injury enforcement intensity for early signals. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
South Korea Electric Hobs Market
Kitchen Appliances
Air Fryer Accessories Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
Electric Pizza Oven Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
Europe Kitchen Appliances Market
Kitchen Appliances
Global Smart Ovens Market
Kitchen Appliances
Toast Maker Market
Kitchen Appliances
Smart Kitchen System Market
Kitchen Appliances
India Electric Vegetable Choppers Market
Kitchen Appliances
Europe Household Side by Side Refrigerator Market
Kitchen Appliances
India Kitchen Appliances Market
Kitchen Appliances
Russia Kitchen Appliances Market
Kitchen Appliances
Induction Hobs Market
Kitchen Appliances
Asia Pacific Electric Vegetable Choppers Market
Kitchen Appliances
Asia Pacific Household Electric Grills Market