
 France Kitchen Appliances Market | 2026-2036
France Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
France Kitchen Appliances Market Foresight
Urban apartment dwellers is rotating toward compact, energy-rated appliances as the dominant buyer archetype in France's kitchen equipment sector. Groupe SEB leverages its deep brand portfolio to anchor premium positioning across French retail channels. Bosch Siemens competes through R&D intensity in connected cooking systems. Brandt Group specializes in regionally manufactured units that sustain its domestic production footprint.
France Kitchen Appliances encompass electrically or gas-powered equipment designed for food storage, preparation, and cooking in residential or commercial settings, typically operating at 220-240V with energy efficiency ratings scaled from A to G under EU labeling rules. Their primary purpose is to automate thermal processes, preserve perishables, and reduce manual labor in meal preparation. Refrigerators and ovens occupy the largest installed base, though smart appliances represent the fastest-growing technology tier as connectivity protocols integrate with home energy management systems. Distribution runs through specialty stores and online retailers, where margin pools concentrate in extended warranty and installation services.
France's kitchen appliance sector navigates the EU Ecodesign Directive, RE2020 building efficiency standards, and CE marking requirements that collectively mandate minimum energy performance and restrict hazardous substances in electrical components. ANSM enforces product safety surveillance, while the EU Green Deal's phasedown of fluorinated gases affects refrigeration technology choices. Stakeholders must monitor how upcoming EU AI Act provisions classify autonomous cooking algorithms and whether France extends repairability scoring beyond smartphones into major domestic appliances.
Market Dynamics
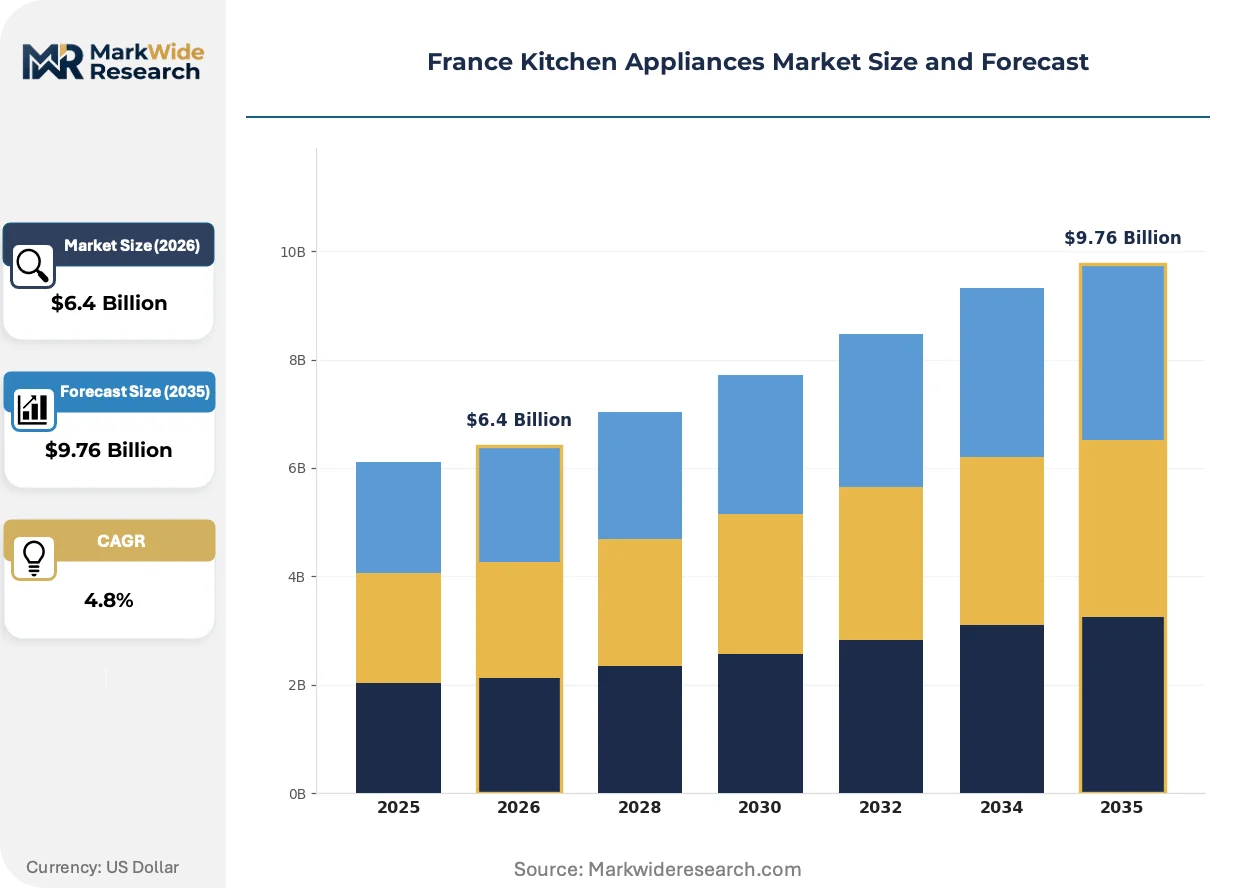
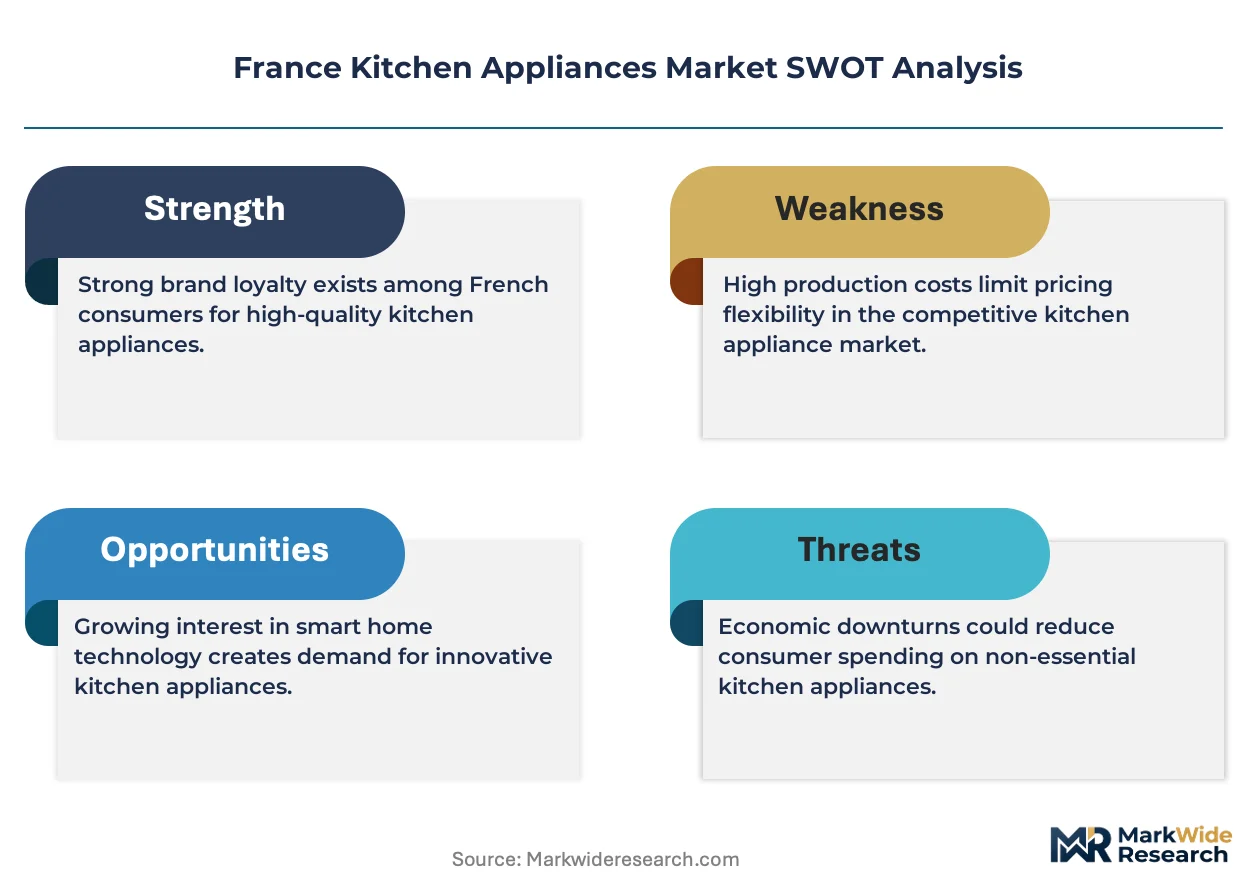
France's kitchen appliance sector faces structural pressure from the RE2020 environmental regulations, which tighten energy efficiency thresholds and compress replacement cycles for legacy equipment across residential and commercial installations.
Growth Catalysts
- RE2020 Building Standards:France's 2020 environmental regulations mandate stricter energy performance for new construction and major renovations, accelerating replacement demand for A-rated refrigerators and induction cooktops in premium housing stock.
- Île-de-France Renovation Activity:Dense renovation permits in Paris and surrounding departments concentrate demand for compact, multi-functional appliances suited to urban apartment footprints.
- Induction Technology:Gas-to-electric cooking transitions, supported by municipal bans on new gas connections in several French cities, pull demand toward high-efficiency induction hobs and compatible cookware systems.
Market Restraints
- Copper and Rare Earth Input Volatility:Electric motor windings and permanent magnets for compressor efficiency depend on copper and neodymium prices, exposing margin structures to commodity swings with limited pass-through elasticity in mass-market segments.
- Component Supply Concentration:Semiconductor modules for inverter-driven compressors and connected appliance controllers concentrate among East Asian foundries, creating vulnerability to logistics disruptions and export licensing friction.
- Fluorinated Gas Phase-down:The EU F-Gas Regulation restricts hydrofluorocarbon refrigerants, forcing costly retooling of refrigeration production lines and compressing availability of service-compatible replacement units during transition periods.
Strategic Opportunities
- Repairability Index Extension:France's existing repairability scoring for electronics creates precedent for expansion into major domestic appliances, rewarding modular designs and spare parts availability with preferential retail placement.
- Home Energy Management Convergence:Integration of kitchen appliances with residential solar-battery systems and dynamic electricity tariffs opens subscription-based optimization services for load-shifting dishwashers and refrigeration cycles.
- Auvergne-Rhône-Alpes Manufacturing Cluster:Regional specialization in precision metalwork and polymer molding supports reshoring of component production for brands seeking domestic supply chain credentials.
Industry Challenges
- Cybersecurity Certification Complexity:Connected appliances face overlapping requirements from ANSSI, GDPR data protection rules, and impending EU Cyber Resilience Act provisions, extending product launch timelines.
- Legacy Gas Infrastructure Compatibility:Mixed housing stock across French regions requires dual-fuel product variants and installer certification diversity, complicating inventory and service network configuration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Kitchen Appliances Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Dishwashers, Microwaves, Cooktops, Range Hoods Technology: Smart Appliances, Energy Efficient, Induction, Convection, Steam, Touch Control Distribution Channel: Specialty Stores, Online Retailers, Department Stores, Home Improvement Stores, Direct Sales Customer Type: Residential Users, Commercial Kitchens, Catering Services, Hospitality Venues |
| Companies Covered | Electrolux AB, Brandt Group, Groupe SEB, Bosch Siemens, Candy, BSH Hausgeräte GmbH, Haier Europe, Arcelik A.S., Whirlpool Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Kitchen Appliances Market Shifts & Advancements
Connectivity protocols and thermal efficiency standards are restructuring how French households source, operate, and service kitchen equipment, with implications for manufacturer revenue models and retail channel economics.
Steam-assisted cooking technology is fragmenting traditional oven segmentation by combining convection, microwave, and steam injection in single cavities. Urban apartment dwellers in Lyon and Bordeaux adopt these hybrid units at accelerated rates to preserve counter space. The technology is fragmenting established price tiers between built-in and countertop categories, compressing mid-range standalone microwave demand.
The EU AI Act's risk classification framework for autonomous household appliances imposes documentation and human-oversight requirements on algorithmic cooking programs. French manufacturers must adapt firmware development processes to satisfy conformity assessment procedures before CE marking. Connected cooking systems with recipe-to-appliance automation face the steepest compliance adaptation costs and timeline extensions.
Specialty kitchen retailers are unbundling installation and extended warranty services from product margins, shifting toward transparent fee-for-service models. This restructuring concentrates margin pools in Île-de-France and Provence-Alpes-Côte d'Azur where housing transaction volumes sustain bundled renovation project sales. Consumer behavior favors direct manufacturer warranty registration and third-party service platform comparison, eroding traditional retailer attachment rates.
France Kitchen Appliances Market Segmentation
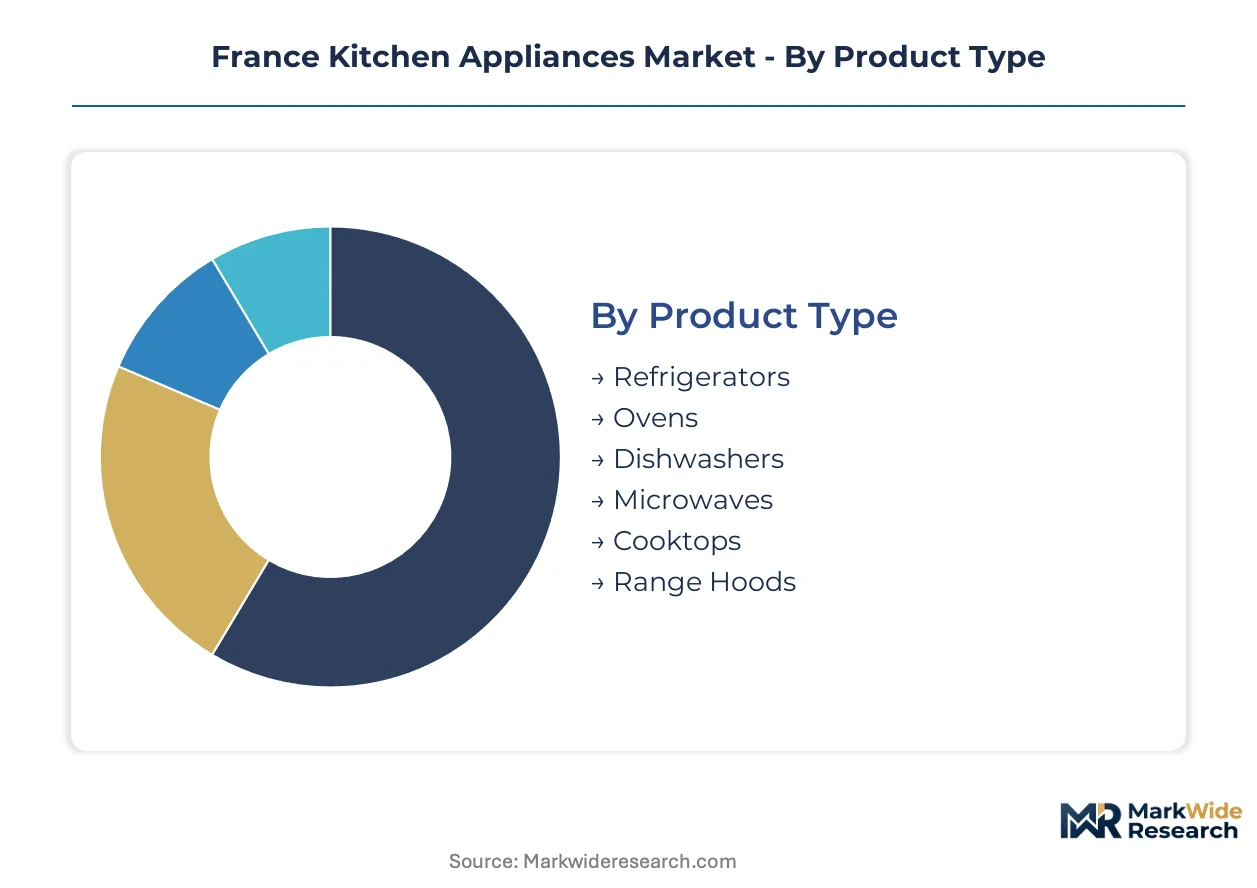
Segmentation in France's kitchen appliance market determines channel strategy and margin structure. Product type dictates installation complexity and service attachment rates. Technology tier shapes regulatory compliance burden and replacement cycle timing.
Product Type:
Channel mix varies sharply by installation requirements. Built-in categories flow through specialty retailers with bundled service contracts. Freestanding units concentrate in mass-market channels with thinner margin profiles.
- Refrigerators:Compression-based thermal systems with inverter-driven motors dominate residential replacements. Demand concentrates in Île-de-France renovation projects where RE2020 efficiency mandates accelerate A-rated unit adoption. The F-Gas Regulation phase-down forces refrigerant technology transitions that compress service compatibility during equipment swaps.
- Ovens:Built-in electric cavities with pyrolytic cleaning functions anchor premium kitchen projects. Urban apartment dwellers in Lyon and Bordeaux prioritize compact multifunction units that combine convection, steam, and microwave modes to preserve counter space in constrained floor plans.
- Dishwashers:Freestanding and integrated variants with soil sensors and variable spray arms. Water efficiency ratings drive municipal incentive eligibility in drought-prone southern departments.
- Microwaves:Solo, grill, and combination units with inverter power control. Countertop demand is softening as multifunction ovens absorb heating tasks.
- Cooktops:Gas, ceramic, and induction heating surfaces in 60cm and 90cm widths. Municipal gas connection bans in several French cities are accelerating induction conversion rates.
- Range Hoods:Extraction and recirculation systems with grease filtration and LED lighting. Aesthetic integration with cabinetry drives built-in premium placement.
By volume, refrigerators lead. By growth pace, induction cooktops are climbing the fastest.
Technology:
Cost tier stratification separates mass-market compliance-driven purchases from premium connected systems. Energy efficiency certification creates baseline entry requirements while smart features enable subscription revenue models.
- Smart Appliances:WiFi-enabled units with recipe-to-appliance automation and remote diagnostics. ANSSI cybersecurity certification and EU AI Act documentation requirements extend development timelines and concentrate vendor investment among established firmware developers.
- Energy Efficient:A-rated and above appliances qualifying for energy renovation subsidies. RE2020 building standards mandate these thresholds in new construction and major renovations across dense urban housing stock.
- Induction:Electromagnetic heating systems with rapid response and precise temperature control. French cities with gas connection restrictions are seeing accelerated residential conversion from legacy cooktops.
- Convection:Fan-assisted thermal circulation for uniform cooking across multiple rack positions. Standard feature in mid-tier and premium oven replacements.
- Steam:Injection systems for moisture-controlled cooking preserving nutrients. Hybrid steam-convection units are fragmenting traditional oven segmentation in space-constrained urban kitchens.
- Touch Control:Capacitive interfaces replacing mechanical dials and knobs. Integration with connected home systems drives placement in premium product lines.
By installed base, energy efficient units dominate. By expansion trajectory, smart appliances are gaining share fastest.
Distribution Channel:
Customer type determines channel selection. Residential purchasers split between research-intensive online comparison and tactile evaluation in physical showrooms. Commercial buyers concentrate in direct relationships with project specialists.
- Specialty Stores:Dedicated kitchen retailers with design consultation and installation coordination. Margin pools concentrate in extended warranty and project management fees rather than product markup.
- Online Retailers:Pure-play e-commerce and manufacturer direct-to-consumer platforms. Price transparency and third-party service platform comparison are eroding traditional retailer attachment rates.
- Department Stores:General merchandise retailers with seasonal appliance promotions. Freestanding compact categories dominate over built-in installation services.
- Home Improvement Stores:Big-box retailers serving renovation project demand. Self-installation preference drives freestanding dishwasher and refrigerator volume.
- Direct Sales:Manufacturer-controlled channels with bundled subscription services. Home energy management convergence opportunities concentrate in this channel for load-shifting optimization programs.
By transaction volume, specialty stores lead. By growth momentum, online retailers are pulling ahead.
Customer Type:
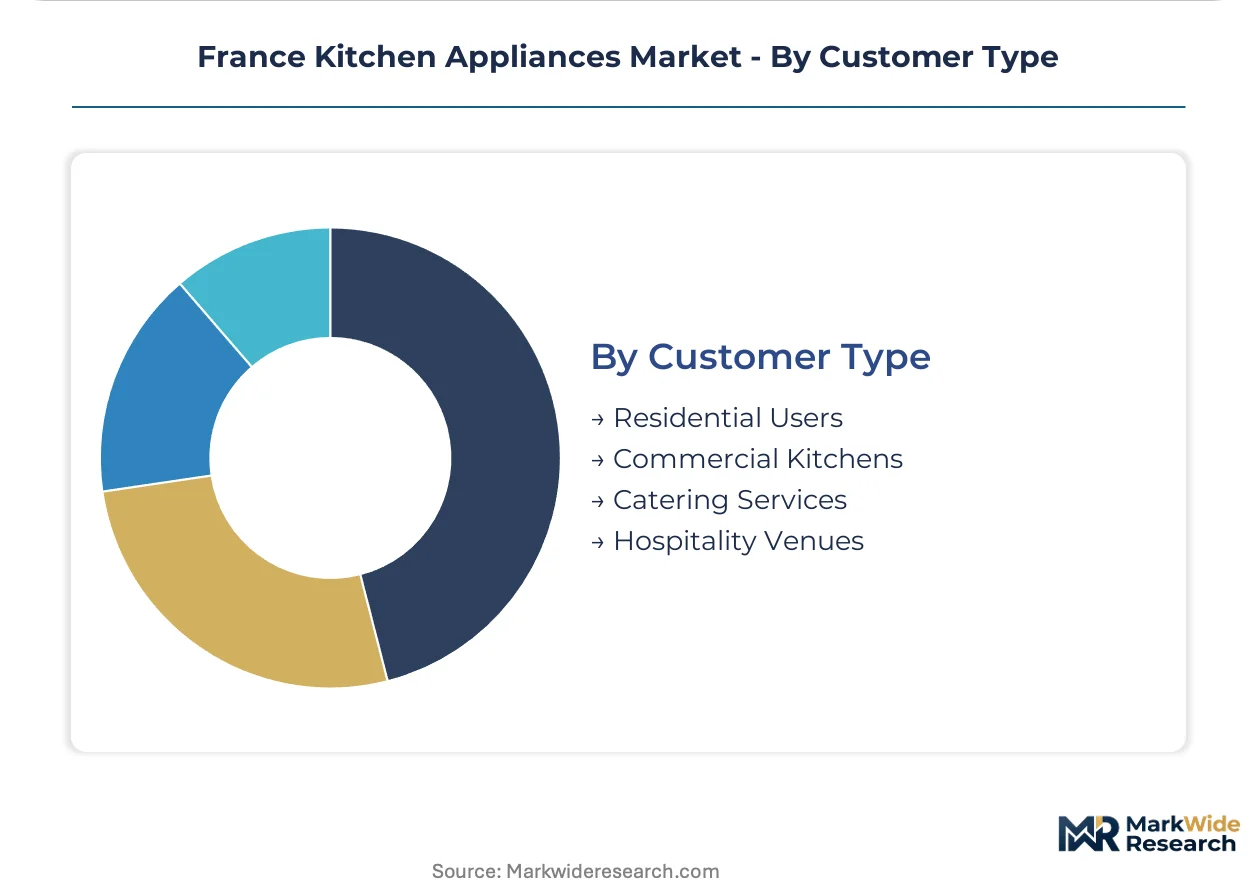
Application requirements shape product specification and service intensity. Residential replacement cycles stretch longer than commercial equipment turnover driven by durability demands and usage intensity.
- Residential Users:Individual households and multi-unit apartment owners. Compact multi-functional designs dominate urban Île-de-France demand where renovation permits remain dense.
- Commercial Kitchens:Restaurant and institutional food preparation facilities. Stainless steel construction and rapid-cycle performance specifications drive procurement decisions.
- Catering Services:Mobile and event-based food operations requiring portable or modular equipment. Rental and lease financing structures predominate over outright purchase.
- Hospitality Venues:Hotels and extended-stay properties with in-room or central kitchen facilities. Brand standardization across property portfolios concentrates volume with specified manufacturers.
By unit volume, residential users dominate. By replacement frequency, commercial kitchens cycle fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The LGV Sud-Est high-speed rail corridor and Rhône-Saône waterway network underpin France's domestic appliance logistics backbone, connecting Auvergne-Rhône-Alpes manufacturing clusters to Île-de-France consumption centers.
Île-de-France
Paris and surrounding departments generate the densest renovation permit activity nationwide, concentrating demand for compact A-rated refrigerators and induction cooktops. RE2020 building standards mandate strict energy performance thresholds for equipment installed in major renovations. The Plaine Saint-Denis logistics hub coordinates last-mile distribution to urban apartment projects.
Auvergne-Rhône-Alpes
Lyon anchors precision metalwork and polymer molding specialization that supports component reshoring initiatives. The region's industrial base supplies compressor housings and control module enclosures to domestic assembly operations. Saint-Étienne's historical appliance manufacturing heritage sustains technical workforce pipelines for regional production facilities.
Provence-Alpes-Côte d'Azur
Marseille and Nice sustain premium housing transaction volumes that drive built-in kitchen project demand. Municipal water efficiency incentives in drought-prone Var and Bouches-du-Rhône departments favor high-rated dishwasher installations. The Aix-en-Provence technology corridor hosts firmware development operations for connected appliance platforms.
Hauts-de-France
Lille's cross-border logistics position integrates Belgian and Dutch supply chain nodes for component sourcing. The region's dense social housing stock generates steady replacement demand for freestanding entry-tier units. Dunkirk's port infrastructure handles bulk steel and copper alloy imports for motor winding production.
Nouvelle-Aquitaine
Bordeaux and Biarritz renovation markets favor hybrid steam-convection ovens for space-constrained urban kitchens. The region's timber construction sector under RE2020 standards creates specification pull for electric-only cooking systems. Bayonne's proximity to Spanish component suppliers shortens procurement lead times for inverter modules.
France Kitchen Appliances Market Competitive Landscape
Concentration sits with diversified domestic manufacturers and European industrial conglomerates that control distribution relationships with French specialty retailers. The vendor base stratifies across three tiers: premium brand houses with design consultation integration, mid-market volume players competing on energy rating compliance, and private-label assemblers serving mass-market channels. Strategic moves center on repairability index positioning and home energy management platform partnerships.
Among France-based manufacturers, Groupe SEB anchors the premium tier through multi-brand portfolio depth, while Brandt Group exemplifies regional production footprint preservation. Bosch Siemens occupies the R&D-intensive connected systems segment. These three entities represent distinct competitive archetypes: brand house consolidation, domestic manufacturing fidelity, and technology-forward platform development.
| Leading Market Players |
|---|
| Electrolux AB |
| Brandt Group |
| Groupe SEB |
| Bosch Siemens |
| Candy |
| BSH Hausgeräte GmbH |
| Haier Europe |
| Arcelik A.S. |
| Whirlpool Corporation |
| Others |
Supply & Pricing Matrix
RE2020 energy efficiency certification gates both supplier qualification and price differentiation simultaneously. Manufacturers must certify A-rated and above products to access renovation project pipelines in Île-de-France, while premium positioning rests on connected feature bundling and extended warranty integration.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates transaction flows. Price differentiation hinges on energy certification grade and after-sales service bundling, with specialty retailers capturing margin in installation coordination. Cost compression in entry-tier freestanding units is intensifying because of copper and rare earth input volatility. Mass-market residential buyers in Hauts-de-France exhibit highest price sensitivity, while premium housing renovators in Provence-Alpes-Côte d'Azur accept design consultation premiums.
Supply Chain Analysis
Strategic stockpiling of semiconductor modules and compressor components prevails over just-in-time approaches given East Asian foundry concentration. Manufacturing draws from China, South Korea, and Vietnam for inverter modules and controller assemblies. Copper alloy motor windings, neodymium permanent magnets, and refrigerant-grade polymers constitute critical input dependencies. Single-source vulnerability in semiconductor supply creates exposure to export licensing friction. Distribution runs through specialty retailers with bundled service contracts and direct-to-consumer platforms with transparent fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated retail platforms and direct manufacturer channels, fragmenting traditional specialty retailer attachment rates. This consolidation compresses margin pools for intermediaries while rewarding vendors with platform control and service-layer integration.
For Market Incumbents: Fortify domestic production credentials through Auvergne-Rhône-Alpes component reshoring to preempt supply chain disruption risks. Deepen repairability index positioning ahead of anticipated regulatory extension into major domestic appliances. Vertical integration into precision metalwork and polymer molding sustains margin control against commodity volatility. For New Entrants and Emerging Players: Third-party installation and warranty service gaps in online retail channels represent immediate white-space opportunities. Target drought-prone southern departments with water efficiency-rated dishwasher offerings bundled with municipal incentive navigation. Direct-to-consumer platform entry with transparent fee-for-service models bypasses entrenched specialty retailer relationships. For Investors and Strategic Acquirers: The EU AI Act's risk classification framework reshapes the acquisition landscape by elevating firmware development capabilities to strategic priority status. Long-term viability centers on vendors with ANSSI cybersecurity certification infrastructure and algorithmic cooking program documentation competence. Acquisition targets should demonstrate modular design architectures compatible with repairability index expansion. Watch for F-Gas Regulation phase-down timeline acceleration as inflection signal for refrigeration technology transition winners.| Strategic Initiative | Industry Significance |
|---|---|
| Repairability Index Positioning | Modular design architectures capture preferential retail placement under anticipated regulatory expansion. |
| Home Energy Management Integration | Subscription-based load-shifting services monetize solar-battery convergence in Île-de-France renovation projects. |
| Cybersecurity Certification Investment | ANSSI compliance accelerates product launch timelines for connected cooking systems under EU AI Act provisions. |
| Regional Manufacturing Reshoring | Auvergne-Rhône-Alpes production footprint secures domestic supply chain credentials against East Asian concentration risk. |
| Refrigerant Technology Transition | F-Gas Regulation compliance in compressor systems preserves service compatibility during equipment replacement cycles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with kitchen retail category managers, manufacturer product development directors, regional installation service coordinators, and municipal housing renovation officers. Secondary validation incorporated EU Ecodesign Directive implementation reports, ANSM product safety surveillance records, F-Gas Regulation phase-down documentation, and customs trade data for compressor component flows. Bottom-up unit shipment estimates triangulated against top-down construction permit and housing transaction macro indicators.
Across the analysis window, volume and value outputs reflect segmentation modeling across product type, technology tier, distribution channel, and customer application dimensions. CAGRs were derived from replacement cycle timing under RE2020 efficiency mandates and urban apartment renovation permit trajectories. Forecast inputs incorporated connected appliance adoption curves, induction conversion rates in gas-restricted municipalities, and repairability index implementation probability distributions.
Underlying assumptions cover regulatory implementation timelines, commodity price stabilization bands, and semiconductor supply normalization, with deviation risk concentrated in F-Gas Regulation acceleration and EU AI Act enforcement intensity. Forecasts reflect documented scenario parameters with sensitivity ranges for policy inflection points. Revision becomes warranted when cybersecurity certification backlog durations or refrigerant technology transition costs cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Garlic Press Market
Kitchen Appliances
Capsule Coffee Machines Market
Kitchen Appliances
Middle East Electric Vegetable Chopper Market
Kitchen Appliances
China Mixer Grinder Market
Kitchen Appliances
India Kitchen Appliances Market
Kitchen Appliances
Electric Corkscrew Market
Kitchen Appliances
Kitchen Chimney Market
Kitchen Appliances
UK Cookware Market
Kitchen Appliances
South Korea Kitchen Appliances Market
Kitchen Appliances
United States Electric Vegetable Choppers Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
Global Single Serve Coffee Maker Market
Kitchen Appliances
Household Bread Machine Market
Kitchen Appliances
Small Kitchen Appliances Market
Kitchen Appliances
Household Cooking Appliance Market
Kitchen Appliances
India Mixer Grinder Market