
 Mixer Grinder Market | 2026-2036
Mixer Grinder Market Size, Share, and Industry Trends Forecast 2026-2036
Mixer Grinder Market Foresight
Polycarbonate jar housings is decoupling from traditional glass assemblies across value-engineered product lines, reducing unit costs and breakage rates in high-frequency use environments. Preethi leverages captive manufacturing in Tamil Nadu to sustain cost leadership across South Indian distribution networks. Philips competes on blade geometry patents and direct-to-retail channel control in metropolitan India. Bosch anchors premium positioning through German-engineered motor platforms and extended warranty programs targeting commercial kitchens.
A mixer grinder is an electromechanical food preparation appliance combining a rotating blade assembly with an electric motor housed in a ventilated base unit, typically operating at 10,000–22,000 RPM for wet and dry grinding applications. The device serves residential and commercial users by pulverizing spices, lentils, and vegetables into pastes or powders with interchangeable stainless steel jars. Countertop units dominate volume across Indian households due to multi-jar configurations and established repair ecosystems, while 750W power rating models capture the fastest growth as consumers prioritize grinding efficiency for hard spices like turmeric and fenugreek. Stainless steel construction leads material selection in commercial food service segments where hygiene audits and durability requirements exceed residential thresholds.
India's BIS mandates ISI certification for electrical kitchen appliances, compelling manufacturers to redesign motor windings and insulation systems to meet thermal endurance standards. The EU's RoHS directive and REACH chemical restrictions constrain plasticizer and coating choices for exporters targeting European retail channels. Stakeholders must monitor evolving energy labeling norms across India, Europe, and North America where efficiency grade thresholds directly determine retail placement and subsidy eligibility in government procurement programs.
Market Dynamics
India's BIS certification tightening for electrical appliances is forcing manufacturers to redesign motor windings and insulation systems, compressing margins while accelerating consolidation among smaller assemblers unable to absorb compliance costs.
Growth Catalysts
- Urban nuclear family formation:Dual-income households in Mumbai, Bangalore, and Delhi compress replacement cycles for multi-jar systems as cooking frequency rises and time scarcity intensifies.
- BIS thermal endurance mandates:Stricter ISI certification requirements for electrical kitchen appliances are pulling demand toward 750W models with upgraded motor platforms that meet efficiency benchmarks.
- Polycarbonate jar adoption:Value-engineered product lines are decoupling from glass assemblies, reducing breakage rates in high-frequency residential environments and lowering unit costs for mass-market penetration.
Market Restraints
- Copper and electrical steel volatility:Motor core materials face input cost swings that compress assembler margins, particularly for mid-tier manufacturers lacking captive supply arrangements.
- Tamil Nadu production concentration:Preethi's captive manufacturing dominance creates geographic supply risk, with South Indian distribution networks vulnerable to regional logistics disruptions.
- Basic blender substitution:Low-cost single-jar alternatives in rural markets constrain premium multi-jar penetration where repair ecosystems remain underdeveloped.
Strategic Opportunities
- Tier-2 and tier-3 Indian cities:Underpenetrated markets in Pune, Hyderabad, and Chennai present white space as nuclear family formats and income levels rise beyond current replacement cycle saturation.
- Commercial kitchen certification:FSSAI hygiene audit alignment for stainless steel construction creates premium positioning for Bosch's German-engineered motor platforms targeting food service verticals.
- Direct-to-retail channel control:Philips's blade geometry patent leverage enables bypass of traditional distributor markups in metropolitan India, compressing channel costs and accelerating price repositioning.
Industry Challenges
- ISI certification timeline compression:BIS thermal endurance testing cycles create working capital strain for assemblers redesigning insulation systems to meet revised electrical safety benchmarks.
- Blade geometry IP complexity:Patent thickets around stainless steel jar configurations and multi-speed coupling mechanisms create licensing friction for new market entrants.
- Legacy repair ecosystem integration:Countertop unit dominance depends on maintaining spare parts compatibility across generational motor platforms, constraining radical design overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mixer Grinder Market |
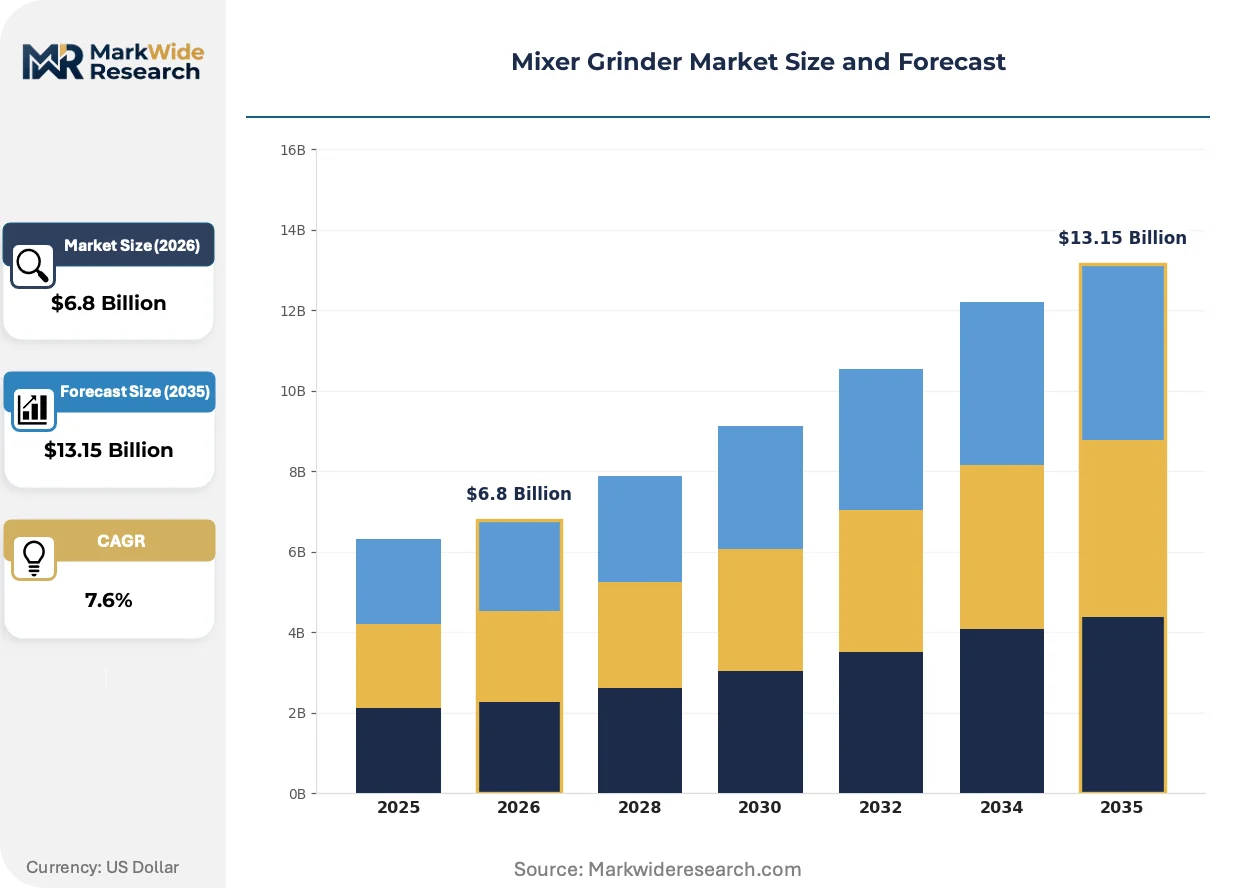
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Handheld, Immersion, Industrial Power Rating: 500W, 750W, 1000W, 1200W Material: Stainless Steel, Plastic, Glass, Ceramic End User: Household, Commercial, Food Service, Catering |
| Companies Covered | Sujata Appliances, Butterfly India, Preethi, Usha Appliances, Panasonic India, Hamilton Beach, Philips, Crompton Greaves, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mixer Grinder Market Shifts & Advancements
Material substitution and regulatory compliance are reshaping competitive positioning in mixer grinder manufacturing, with motor efficiency and jar durability emerging as primary differentiation vectors.
Brushless DC motor technology is integrating into premium 750W platforms, replacing conventional universal motors to reduce thermal losses and extend operating life. Urban Indian households in Bangalore and Mumbai are adopting these platforms at accelerating rates as electricity costs rise and warranty expectations lengthen. This motor architecture is compressing the performance gap between residential and commercial-grade units, enabling single-platform manufacturing scale.
REACH chemical restrictions and RoHS directives in Europe are constraining plasticizer and coating choices for Indian exporters targeting EU retail channels. Manufacturers must reformulate polycarbonate jar compounds and motor housing materials to eliminate restricted phthalates and heavy metal stabilizers. Exporters serving German and French markets are responding by establishing dedicated compliance testing protocols ahead of shipment, adding 4-6 weeks to production cycles.
Channel consolidation is compressing distributor tiers in metropolitan India as direct retail relationships displace traditional wholesale networks. Philips and Bosch are negotiating shelf-space agreements with organized retail chains in Delhi and Mumbai, unbundling after-sales service to authorized third-party providers. This structural shift is most visible in tier-1 cities where real estate costs and inventory velocity requirements favor centralized procurement over fragmented dealer networks.
Mixer Grinder Market Segmentation
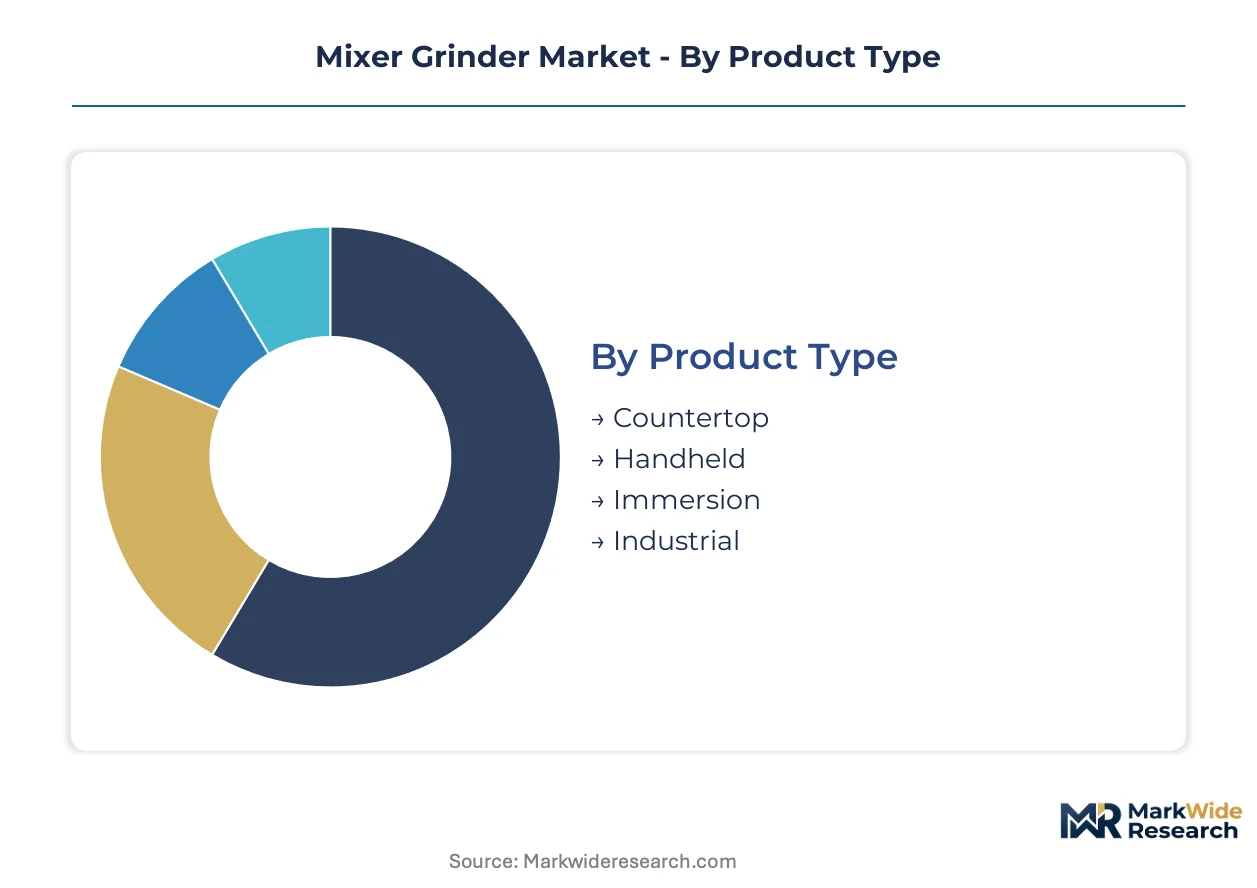
Mixer grinder purchasing decisions pivot on grinding intensity requirements, kitchen space constraints, and regulatory compliance burdens that vary sharply across residential and professional environments. Segmentation reveals how motor specifications and material choices align with distinct usage frequencies and hygiene standards.
Product Type:
Buyers in this category differentiate primarily by kitchen footprint and mobility needs rather than price sensitivity alone.
- Countertop:Stationary multi-jar units dominate Indian residential kitchens with established repair ecosystems in Mumbai, Bangalore, and Delhi. Nuclear family formats and dual-income households compress replacement cycles as cooking frequency intensifies.
- Handheld:Battery-operated portable units serve space-constrained urban apartments where storage limitations override power preferences. Demand concentrates among young professionals in tier-1 cities seeking single-jar convenience for intermittent use.
- Immersion:Stick-style blenders integrate with existing cookware for direct-container processing, reducing jar inventory requirements. Commercial kitchens in food service verticals adopt these for sauce and soup preparation where volume flexibility matters.
- Industrial:Heavy-duty continuous-duty motors withstand 8+ hour operational cycles in central commissaries and catering operations. FSSAI hygiene audit alignment drives stainless steel construction mandates in institutional food preparation facilities.
Volume sits with Countertop; growth tilts toward Industrial as commercial kitchen certification requirements tighten.
Power Rating:
Performance tier selection tracks directly against spice hardness and batch frequency in target applications.
- 750W:Mid-range platforms capture accelerating demand from urban households grinding turmeric and fenugreek regularly. BIS thermal endurance mandates pull replacement demand toward these upgraded motor platforms that meet revised efficiency benchmarks.
- 500W:Entry-level universal motors serve occasional users in rural markets where basic blender substitution constrains premium penetration. Low-cost single-jar configurations dominate where repair ecosystems remain underdeveloped.
- 1000W:High-torque designs address commercial grinding loads in catering operations with sustained duty cycles. Brushless DC motor integration is expanding operating life expectations in premium residential and light commercial segments.
- 1200W:Maximum-load continuous-duty platforms anchor Bosch's German-engineered positioning for food service verticals. Extended warranty programs target commercial kitchens where downtime costs exceed equipment premiums.
750W units command the largest installed base; 1000W platforms are climbing the fastest as electricity costs rise and performance expectations converge across residential and commercial tiers.
Material:
Material selection balances durability imperatives against weight, transparency, and chemical compliance costs.
- Stainless Steel:Hygiene-critical construction dominates commercial food service segments where FSSAI audits and durability requirements exceed residential thresholds. Catering operations prioritize corrosion resistance in high-moisture grinding environments.
- Polycarbonate:Value-engineered jar housings are displacing glass assemblies across mass-market lines, reducing unit costs and breakage rates in high-frequency residential use. REACH and RoHS compliance testing adds 4-6 weeks to production cycles for EU-bound exports.
- Glass:Traditional assemblies retain premium positioning in aesthetic-conscious households despite weight and fragility penalties. Replacement demand concentrates among older demographics with established brand loyalties.
- Ceramic:Specialized coatings address staining resistance for spice-intensive applications where visual jar clarity supports ingredient monitoring. Niche adoption remains constrained by cost premiums and supply chain fragmentation.
Stainless Steel anchors commercial procurement; Polycarbonate is gaining share fastest as breakage reduction and cost engineering reshape mass-market value equations.
End User:
End-use segmentation separates sporadic residential grinding from continuous-duty professional requirements with distinct certification and service expectations.
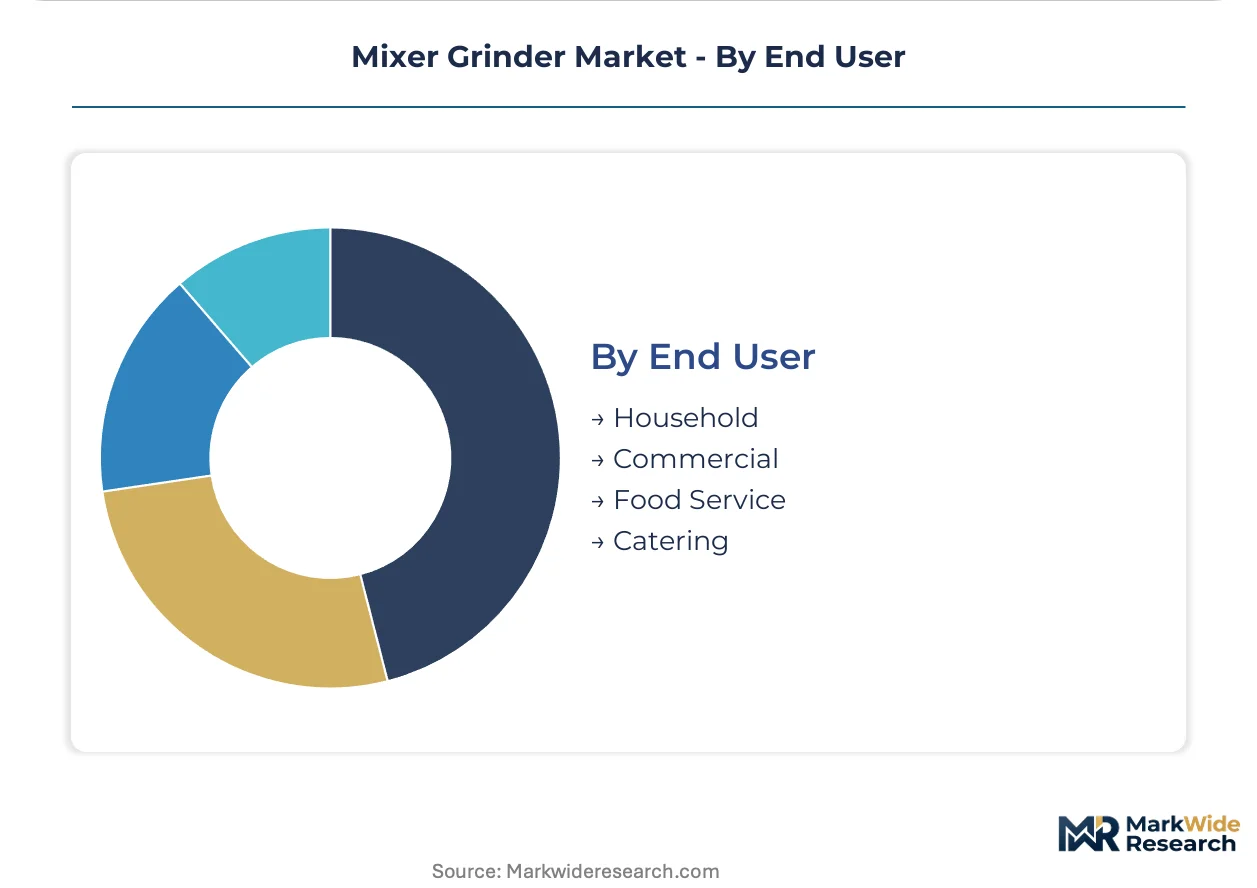
- Household:Nuclear family units in tier-1 Indian cities drive multi-jar system adoption as time scarcity intensifies and cooking frequency rises. Dual-income households compress replacement cycles relative to extended family formats.
- Commercial:Small restaurants and cloud kitchens require mid-duty platforms balancing capital constraints against operational reliability. Direct-to-retail channel control by organized brands is displacing traditional distributor networks in metropolitan procurement.
- Food Service:Institutional cafeterias and hotel chains demand FSSAI-aligned stainless steel construction with documented thermal endurance certification. Bosch anchors this premium positioning through German-engineered motor platforms and extended warranty programs.
- Catering:Mobile and event-based operations prioritize portability and rapid batch turnaround over continuous-duty specifications. Volume procurement concentrates in tier-2 cities where underpenetrated markets present white space as nuclear family formats expand.
Household segment holds the deepest penetration; Food Service shows the steepest expansion trajectory as hygiene audit standardization accelerates equipment replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban Indian households concentrate replacement demand for multi-jar mixer grinder systems as nuclear family formats and dual-income structures compress equipment lifecycles. BIS thermal endurance mandates and FSSAI hygiene audit alignment are reshaping procurement patterns across residential and commercial segments. Manufacturing gravity centers on South Indian industrial clusters with captive motor winding capabilities.
India
Mumbai, Bangalore, and Delhi drive premium 750W adoption as cooking frequency rises in time-scarce dual-income households. BIS ISI certification tightening compels motor platform redesigns to meet revised electrical safety benchmarks. Tamil Nadu hosts Preethi's captive manufacturing infrastructure, anchoring cost leadership across South Indian distribution networks.
United States
Countertop multi-jar configurations dominate residential procurement with established repair ecosystems supporting replacement cycles. FDA food contact material regulations constrain polycarbonate jar compound formulations for imported units. California and Texas metropolitan clusters concentrate demand for high-torque platforms serving spice-intensive immigrant household cooking patterns.
Germany
Commercial kitchen certification requirements pull stainless steel construction demand from institutional food service verticals. REACH chemical restrictions and RoHS directives regulate plasticizer and coating choices for EU-bound manufacturing. Bavaria-based engineering clusters anchor premium motor platform development targeting extended warranty programs.
China
Contract manufacturing capacity scales polycarbonate jar production for value-engineered export lines serving Southeast Asian markets. GB standards and MIIT energy labeling norms shape motor efficiency requirements for domestic and export-bound platforms. Pearl River Delta industrial zones concentrate blade assembly and motor housing fabrication for global OEM supply.
United Kingdom
London and Southeast metropolitan areas concentrate demand for compact handheld units in space-constrained urban apartments. ECHA compliance testing protocols add 4-6 weeks to production cycles for EU-aligned chemical safety verification. Midlands manufacturing clusters handle motor rewinding and refurbishment services supporting circular economy equipment lifecycle extension.
Mixer Grinder Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive production facilities conferring cost advantages in high-volume residential tiers while patent-holding incumbents defend premium positioning through blade geometry IP. The vendor base organizes around three strategic archetypes: South Indian integrated manufacturers with distribution depth, European engineering-led premium specialists, and diversified Asian electronics conglomerates with retail channel control. Consolidation pressure is accelerating among mid-tier assemblers lacking compliance testing infrastructure. Competitive moves concentrate on direct-to-retail channel bypass and motor platform efficiency upgrades.
Among India-based integrated specialists, Preethi, Butterfly India, and Usha Appliances exemplify the captive manufacturing archetype with Tamil Nadu production concentration and established South Indian distribution networks. These entities represent cost-engineered positioning for polycarbonate jar value lines. European engineering specialists Bosch and Philips occupy premium-tier positions through German motor platform development and blade geometry patent portfolios respectively. Hamilton Beach represents North American brand licensing approaches to Asian contract manufacturing. Panasonic India and Crompton Greaves sit within diversified conglomerate structures leveraging cross-category retail relationships and shared service infrastructure.
| Leading Market Players |
|---|
| Sujata Appliances |
| Butterfly India |
| Preethi |
| Usha Appliances |
| Panasonic India |
| Hamilton Beach |
| Philips |
| Crompton Greaves |
| Bosch |
| Others |
Supply & Pricing Matrix
Motor-winding specialists concentrated in Tamil Nadu's industrial corridors anchor cost differentials between premium German-engineered platforms and mass-market polycarbonate jar lines. Labor arbitrage across South Indian manufacturing clusters compresses assembler margins while enabling three-tier pricing stratification across residential tiers.
Pricing Analysis
Volume-massacre dynamics split the market: high-unit countertop configurations trade margin for shelf presence while 750W brushless DC platforms capture premium pricing through efficiency certification. Price differentiation hinges on BIS thermal endurance grading and captive motor production depth. Cost compression in entry-level universal motor tiers intensifies as copper and electrical steel volatility feeds through input costs. Rural single-jar substitution segments exhibit acute price sensitivity; commercial FSSAI-aligned stainless steel procurement shows markedly lower elasticity.
Supply Chain Analysis
Regional distribution centers in Mumbai, Bangalore, and Delhi orchestrate hub-and-spoke patterns radiating into tier-2 and tier-3 catchments. Manufacturing gravity draws from India, China, and Germany for motor cores, blade assemblies, and precision-engineered components respectively. Raw material dependencies center on copper windings, electrical steel laminations, and polycarbonate resin compounds. Single-source vulnerability concentrates in Tamil Nadu captive facilities where Preethi's integrated production creates geographic risk exposure. Distribution runs through organized retail chains displacing traditional wholesale networks in metropolitan procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mixer grinder market sits in a technology-transition phase as brushless DC motor architectures displace conventional universal motor platforms across premium and mid-tier residential segments.
For Market Incumbents: Cement cost leadership through backward integration into motor winding and polycarbonate jar molding capacity in Tamil Nadu and Karnataka. Defend against blade geometry patent thickets by licensing multi-speed coupling mechanisms or acquiring specialist engineering firms with established IP portfolios. Prioritize BIS pre-certification testing infrastructure to compress ISI timeline strain and accelerate replacement cycle capture. For New Entrants and Emerging Players: Begin with tier-2 Indian cities—Pune, Hyderabad, Chennai—where nuclear family formation outpaces established distribution saturation. Target cloud kitchen and small restaurant commercial segments with mid-duty 750W platforms balancing capital constraints against FSSAI hygiene audit alignment. Pursue direct-to-retail channel agreements with organized chains to bypass distributor markup compression. For Investors and Strategic Acquirers: Re-rating potential sits with integrated specialists possessing captive motor production and established South Indian distribution networks given BIS compliance consolidation pressure. Long-term viability favors backward-integrated assemblers over pure-brand licensing models. Monitor brushless DC motor adoption curves in Bangalore and Mumbai residential markets as inflection indicators for platform transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless DC Motor Platform Migration | Reduces thermal losses and extends operating life expectations in 750W tiers. |
| Backward Integration into Motor Winding | Captures margin compression from copper volatility and BIS redesign cycles. |
| Direct-to-Retail Channel Expansion | Bypasses distributor markups in Mumbai and Delhi metropolitan procurement. |
| FSSAI Hygiene Audit Alignment | Unlocks premium positioning in food service verticals requiring stainless steel construction. |
| Polycarbonate Jar Compound Reformulation | Addresses REACH and RoHS compliance for EU-bound export production cycles. |
Research Methodology
Multi-period observation of motor platform replacement cycles, BIS certification timelines, and channel structure evolution anchored the trend analysis, supplemented by interviews with plant managers at Tamil Nadu manufacturing facilities, procurement leads at organized retail chains, aftermarket service heads in Mumbai and Bangalore, and regulatory affairs specialists tracking ISI thermal endurance mandates. Secondary validation drew from BIS certification databases, FSSAI hygiene audit protocols, customs records for electrical steel and copper imports, and SEC filings of diversified conglomerates with appliance divisions. Bottom-up assembler capacity assessments triangulated against top-down replacement cycle modeling.
Segment-weighting approaches distributed volume and value projections across power rating tiers, material construction categories, and end-use segments spanning household, commercial, food service, and catering verticals. CAGRs were derived from fitted growth curves applied to installed base turnover and nuclear family formation rates across Indian urban centers. Industry-specific forecast inputs incorporated BIS compliance cost pass-through assumptions and brushless DC motor cost-down trajectories.
Underlying measurement precision varies by segment; tier-1 city household replacement data carries tighter precision than rural single-jar substitution estimates. Forecasts reflect documented assumptions regarding BIS timeline compression and motor platform transition speeds. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
India Mixer Grinder Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
Self-Stirring Mug Market
Kitchen Appliances
Digital BBQ Tongs and Thermometer Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
Europe Small Kitchen Appliances Market
Kitchen Appliances
Kitchen Appliances Market
Kitchen Appliances
Air Fryer Accessories Market
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
Electric Pizza Oven Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
United States Large Kitchen Appliances Market
Kitchen Appliances
Induction Hobs Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
UK Cookware Market
Kitchen Appliances
Modular Zero-Waste Kitchen Appliance Market