
 Japan Kitchen Appliances Market | 2026-2036
Japan Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Kitchen Appliances Market Foresight
Subscription-based filter replacement and cloud-connected recipe services is recalibrating how manufacturers monetize ongoing customer relationships. Panasonic Corporation leverages its Home Appliance IoT platform to sustain recurring engagement beyond hardware sales. Zojirushi Corporation anchors premium positioning through specialized rice cooker technology leadership. Tiger Corporation competes on thermal engineering expertise in compact form factors suited to Japanese kitchen dimensions.
Japan kitchen appliances encompass electrically powered domestic food preparation, preservation, and cooking equipment typically operating at 100V/50-60Hz with emphasis on space-efficient design and precision thermal control for residential and foodservice environments. Refrigerators dominate value contribution given continuous operation requirements and energy-label sensitivity, while smart appliances represent the fastest structural expansion as Wi-Fi connectivity and voice integration become baseline expectations. Built-in installation formats command margin premiums in new condominium construction, whereas portable segments address rental household flexibility needs across dense urban prefectures.
METI Top Runner standards and JIS C 9801 testing protocols shape efficiency benchmarks that manufacturers must satisfy for market access, with non-compliant products facing retail channel exclusion. The Consumer Affairs Agency enforces Electrical Appliance and Material Safety Law certification requirements that govern product liability and import clearance. Stakeholders must monitor evolving integration between energy-performance regulations and smart-grid compatibility standards as utilities pilot demand-response programs.
Market Dynamics
Compact urban living in Tokyo and Osaka is compressing appliance footprints while METI Top Runner standards force simultaneous efficiency upgrades, creating a dual-pressure environment where manufacturers must miniaturize without sacrificing performance metrics.
Growth Catalysts
- METI Top Runner Program:Mandatory efficiency benchmarks accelerate replacement cycles for refrigerators and ovens as consumers upgrade to compliant models. Retail channels exclude non-conforming products.
- Smart-grid pilot programs:Utility demand-response trials in the Kanto corridor create pull for Wi-Fi-enabled appliances with remote load management capabilities.
- Condominium construction:Built-in installation formats command margin premiums in new Tokyo and Osaka residential towers, anchoring high-value product lines.
Market Restraints
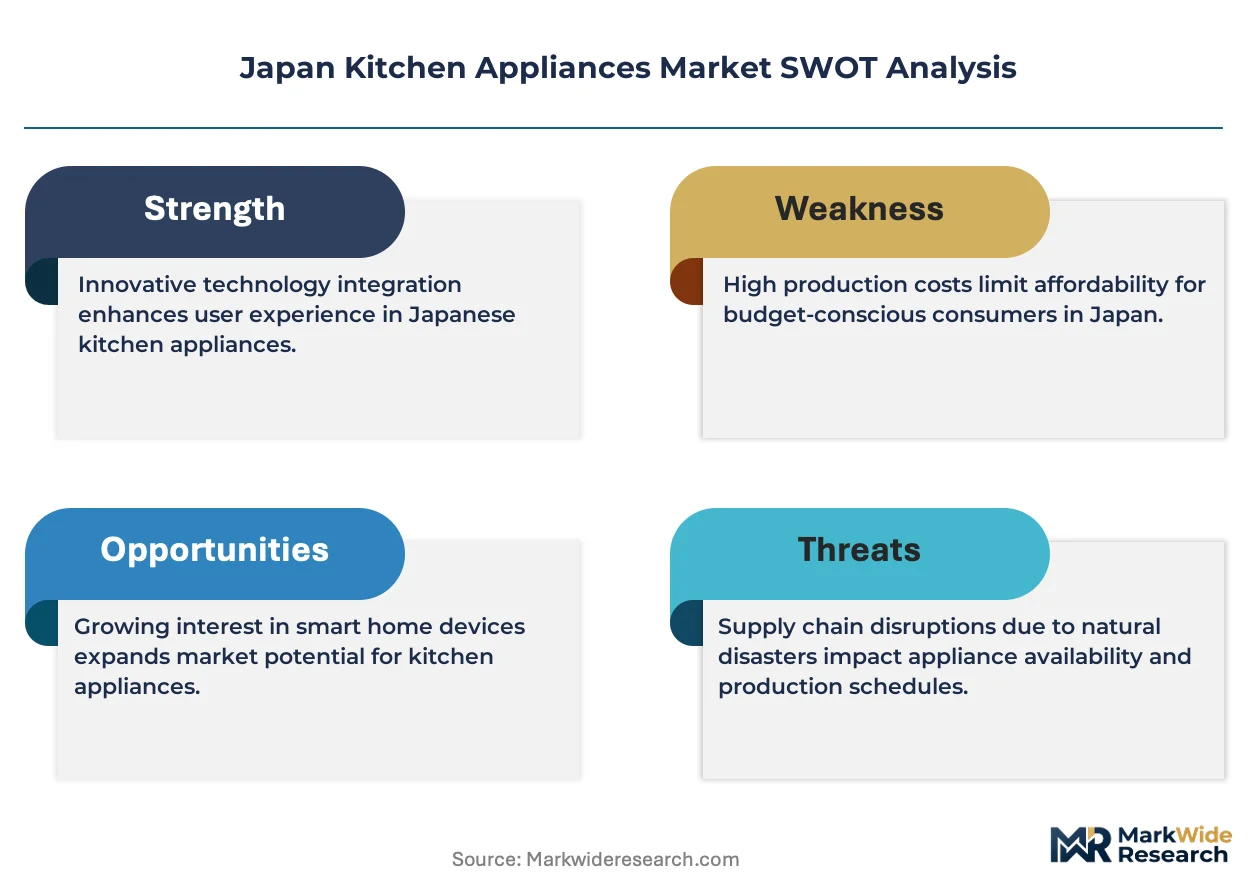
- Copper and rare earth volatility:Motor and magnet input costs fluctuate with commodity markets, compressing margins on mid-tier product lines.
- Single-frequency power infrastructure:Japan's 100V/50-60Hz split limits component standardization versus 220-240V global platforms, raising production complexity.
- Appliance longevity culture:Traditional 15-20 year replacement horizons delay smart-upgrade adoption despite efficiency gains.
Strategic Opportunities
- Kansai underpenetration:Osaka and Kyoto metropolitan areas lag Tokyo in smart-appliance density, offering whitespace for connectivity-enabled product rollouts.
- Cloud-recipe subscription models:Panasonic's Home Appliance IoT platform demonstrates recurring revenue potential beyond hardware transactions.
- JIS C 9801 certification alignment:Efficiency testing protocol harmonization with METI standards streamlines compliance for multi-product portfolios.
Industry Challenges
- Thermal engineering talent scarcity:Precision temperature control expertise for compact form factors concentrates among aging specialist engineers.
- Legacy system integration:Smart appliances must interoperate with existing home electrical panels and breaker configurations in pre-2000s housing stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Kitchen Appliances Market |
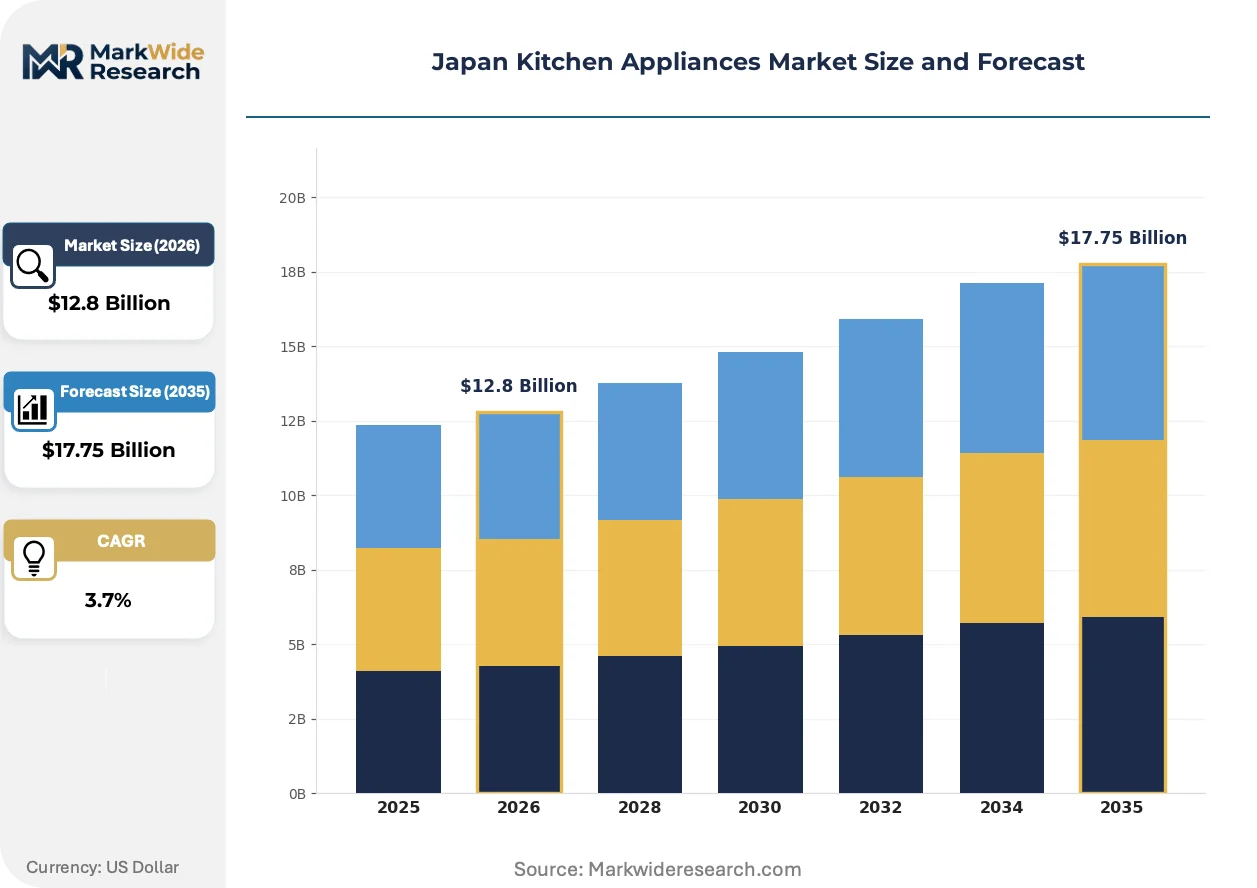
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $17.75 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Microwaves, Dishwashers Customer Type: Households, Restaurants, Cafés, Catering Services Technology: Smart Appliances, Energy-Efficient, Conventional, Hybrid Installation: Built-In, Freestanding, Portable, Under-Counter |
| Companies Covered | Hitachi Global Life Solutions, Rinnai Corporation, Panasonic Corporation, Siroca Inc., Zojirushi Corporation, Sharp Corporation, Toshiba Corporation, Tiger Corporation, Mitsubishi Electric Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Kitchen Appliances Market Shifts & Advancements
Voice integration and AI-driven cooking assistance are redefining user interfaces, while energy-performance digitization creates new data monetization pathways for manufacturers.
Inverter-controlled induction heating is converging with precision temperature sensors to enable one-degree accuracy in compact rice cookers and multi-function ovens. Urban apartment households in Greater Tokyo adopt these systems faster than national averages. The technology is converging with cloud-based recipe databases to lock users into manufacturer-specific content ecosystems.
METI's evolving integration between energy-performance regulations and smart-grid compatibility standards is reshaping product development roadmaps. Manufacturers must now design for demand-response program participation from inception rather than retrofit. The refrigerator and oven categories face the steepest compliance curves as continuous-operation appliances with highest grid-interaction potential.
Rental household flexibility needs are fragmenting purchase patterns across dense urban prefectures. Portable and countertop formats displace built-in specifications in Tokyo's lease-dominant housing market. This behavioral shift concentrates demand in Kanto corridor electronics retailers and direct-to-consumer channels versus traditional home-center distribution.
Japan Kitchen Appliances Market Segmentation
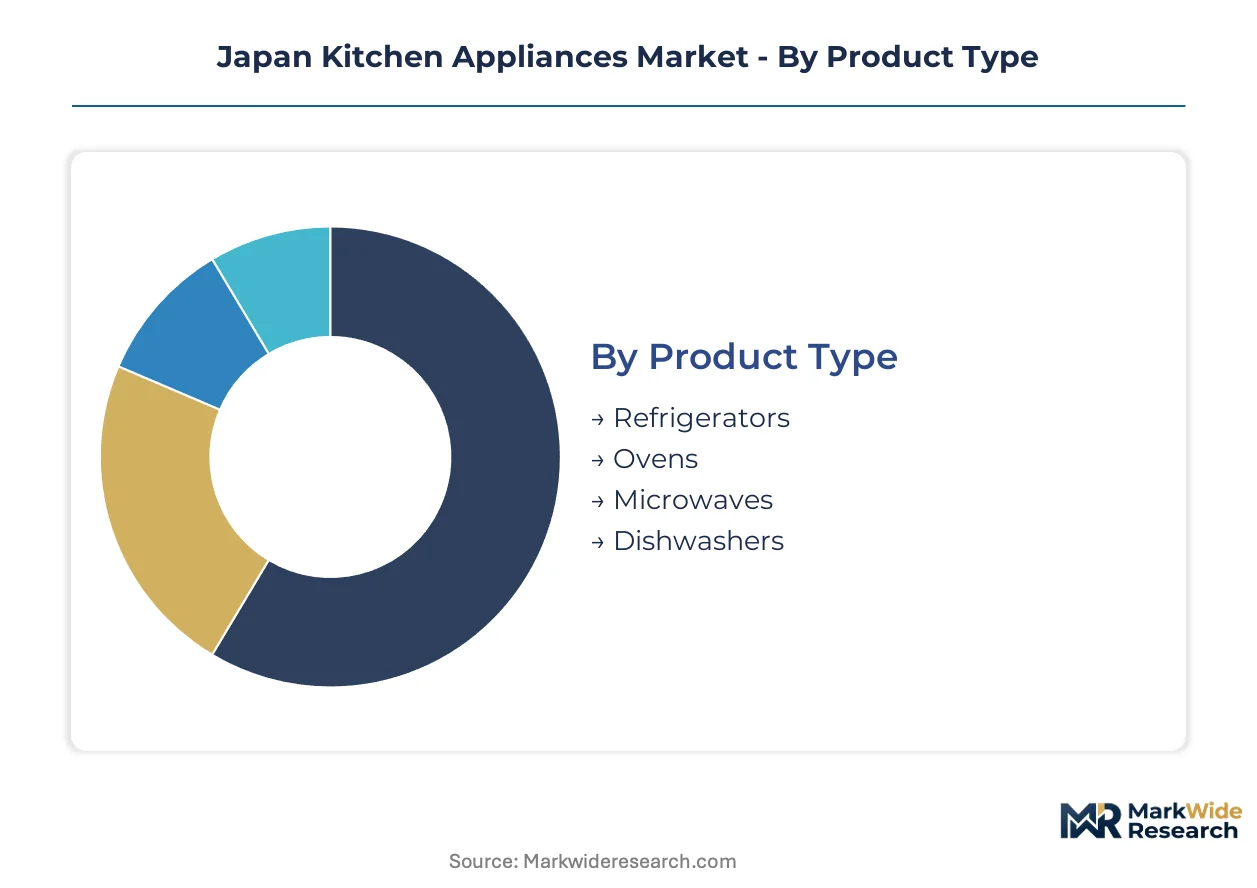
Segmentation in Japan's kitchen appliances market reveals how urban density, energy mandates, and housing tenure patterns fragment demand across incompatible product specifications. Manufacturers must align portfolio breadth with METI compliance requirements and the spatial constraints of Tokyo-Osaka apartment living.
Product Type:
Households prioritize continuous-operation appliances where energy-label sensitivity directly impacts electricity costs and replacement timing.
- Refrigerators:Continuous-operation units with inverter compressors dominate household electricity consumption profiles. Demand concentrates in Greater Tokyo condominiums where METI Top Runner compliance determines retail channel access and resale value in property transactions.
- Ovens:Compact convection and steam-combination units serve space-constrained kitchens with precision thermal requirements. Osaka and Kyoto metropolitan areas show accelerating replacement cycles as efficiency mandates render pre-2020 models non-compliant for retail sale.
- Microwaves:Inverter-controlled units with sensor cooking address speed-oriented meal preparation in dual-income households.
- Dishwashers:Compact countertop and drawer-format units penetrate Tokyo rental stock where permanent installation is prohibited.
Refrigerators lead on scale; smart-enabled ovens lead on momentum.
Customer Type:
End-use economics determine durability expectations, connectivity requirements, and service contract attachment rates.
- Households:Urban apartment dwellers in Tokyo and Osaka drive compact-format demand with 10-15 year replacement horizons. Kanto corridor households show highest smart-appliance adoption rates as utility demand-response pilots create participation incentives.
- Restaurants:Izakaya chains and ramen shops require commercial-grade thermal precision with JIS-certified electrical safety for high-duty-cycle operation.
- Cafés:Specialty coffee establishments demand compact milk-frothing and warming equipment suited to 10-square-meter service counters.
- Catering Services:Bento delivery operators prioritize portable induction units for off-site preparation with 100V compatibility across eastern and western Japan frequency zones.
Households anchor volume contribution; catering services show steepest expansion trajectory as ghost kitchen formats proliferate.
Technology:
Regulatory alignment and grid-interaction capability now precede price in manufacturer R&D allocation decisions.
- Smart Appliances:Wi-Fi-enabled units with cloud-recipe integration and remote load management. Demand clusters in Kanto corridor prefectures where TEPCO demand-response trials create participation revenue streams for connected refrigerator and oven owners.
- Energy-Efficient:Inverter-motor and induction-heating platforms meeting METI Top Runner benchmarks. Replacement cycles accelerate as retail channels exclude non-compliant legacy inventory.
- Conventional:Basic electromechanical controls without connectivity or advanced thermal management. Residual demand persists in rural prefectures with limited smart-grid infrastructure.
- Hybrid:Dual-mode units combining conventional reliability with selective smart features. Appeals to aging homeowners in pre-2000s housing stock with legacy electrical panels.
Energy-efficient models dominate current shipment value; smart appliances gain share fastest as utility program enrollment expands.
Installation:
Housing tenure and construction vintage create irreconcilable format requirements across prefecture-level markets.
- Built-In:Panel-ready refrigerator and oven units specified at condominium construction. Tokyo and Osaka new residential towers command margin premiums for seamless kitchen integration.
- Freestanding:Full-size units with finished sides for open kitchen placement. Dominates suburban single-family housing in Saitama and Chiba prefectures.
- Portable:Countertop rice cookers, induction burners, and compact ovens for rental households. Tokyo's lease-dominant market drives highest density of portable-format purchases through electronics retailers.
- Under-Counter:Drawer refrigerators and dishwasher units maximizing linear workspace. Specified in high-end Tokyo Minato-ku and Chuo-ku condominium renovations.
Freestanding formats retain volume leadership; portable segments climb the fastest as rental tenure lengthens in core metropolitan prefectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in appliance manufacturing remains limited by Japan's domestic production requirements and METI certification barriers, forcing foreign entrants to localize assembly rather than export finished goods. Energy-efficiency mandates create compliance cost differentials between domestic and imported platforms, reinforcing local manufacturing footprints.
Kanto/Tokyo
Greater Tokyo's condominium construction drives built-in refrigerator and oven specifications with METI Top Runner compliance as a mandatory resale feature. TEPCO demand-response pilot programs in Tokyo, Kanagawa, and Chiba prefectures accelerate smart-appliance penetration. Chiba's logistics corridor hosts distribution centers serving electronics retailers across the eastern 50Hz zone.
Kansai/Osaka
Osaka and Kyoto metropolitan areas exhibit smart-appliance underpenetration relative to Kanto, creating whitespace for Wi-Fi-enabled product rollouts. Kansai Electric Power trials lag TEPCO programs by 18-24 months, delaying grid-interaction incentives. Osaka's Namba and Umeda retail clusters concentrate mid-tier portable-format demand from rental households.
Chubu/Nagoya
Nagoya's automotive supply chain spillover sustains precision motor and inverter component manufacturing for appliance OEMs. Aichi prefecture's industrial density supports thermal engineering talent pools concentrated among aging specialist engineers. Toyota City and surrounding municipalities anchor component testing facilities aligned with JIS C 9801 protocols.
Kyushu
Fukuoka's semiconductor packaging facilities supply microcontroller units for inverter-controlled induction heating platforms. Kyushu Electric Power's conservative grid-interaction stance limits smart-appliance program enrollment relative to eastern utilities. Kitakyushu's legacy steel and chemical infrastructure constrains cleanroom expansion for sensor component manufacturing.
Hokkaido
Sapporo's severe winter heating loads prioritize refrigerator efficiency gains that reduce net household electricity consumption. Hokkaido Electric Power's isolated grid architecture complicates demand-response program design for smart appliances. Asahikawa's furniture manufacturing cluster supplies custom panel-ready cabinetry for built-in installations in regional condominium stock.
Japan Kitchen Appliances Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with domestic Japanese names dominating premium tiers while OEM assemblers serve private-label electronics retailers. The market exhibits moderate consolidation among diversified industrial conglomerates with appliance divisions alongside focused specialists in thermal engineering. Three archetypes predominate: diversified electronics conglomerates leveraging IoT platforms, precision thermal specialists anchored in rice cooker heritage, and regional gas appliance converters. Competitive moves concentrate on METI certification pre-emption and smart-grid partnership formation rather than price warfare.
Among diversified appliance manufacturers, Panasonic Corporation and Hitachi Global Life Solutions exemplify platform-scale positioning through home appliance IoT ecosystems. Zojirushi Corporation occupies a specialist tier defined by thermal precision heritage. Tiger Corporation represents compact-form-factor engineering focus. These three names anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Hitachi Global Life Solutions |
| Rinnai Corporation |
| Panasonic Corporation |
| Siroca Inc. |
| Zojirushi Corporation |
| Sharp Corporation |
| Toshiba Corporation |
| Tiger Corporation |
| Mitsubishi Electric Corporation |
| Others |
Supply & Pricing Matrix
Rare earth magnet costs for inverter motor compressors flow from Chinese processing facilities through Osaka-based trading houses into three-tier pricing structure across premium, standard, and economy levels, with METI Top Runner certification premiums widening spreads between compliant and legacy inventory.
Pricing Analysis
Distributor margins in the Kanto corridor electronics retail channel absorb 18-25 points before reaching urban apartment households, while direct-to-OEM discounts anchor pricing for condominium developers specifying built-in formats. Price differentiation hinges on JIS C 9801 certification grade and after-sales service bundling. Cost compression in mid-tier product lines is intensifying because copper and rare earth volatility compresses manufacturer margins. Rental households in Tokyo's lease-dominant market exhibit highest price sensitivity, whereas new condominium buyers in Minato-ku and Chuo-ku show lowest sensitivity to premium positioning.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Tokyo and Osaka residential tower developers, while electronics retailers serve fragmented portable-format purchases. Component sourcing draws from China for rare earth processing, South Korea for semiconductor packaging, and domestic Aichi prefecture for precision motor manufacturing. Critical dependencies include copper winding wire, neodymium magnets, and microcontroller units. Single-source vulnerability concentrates in Chinese rare earth refining. Distribution runs through Chiba logistics corridors serving eastern 50Hz zone retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's kitchen appliances market functions as a stable compounder where METI regulatory mandates drive predictable replacement cycles regardless of macroeconomic volatility.
For Market Incumbents: Anticipate margin compression from commodity volatility by securing captive supply of copper and rare earth inputs through backward integration into component manufacturing. Pre-empt emerging entrant threats in Kansai smart-appliance whitespace by accelerating Wi-Fi-enabled product rollouts before Kansai Electric Power demand-response trials mature. Certification investment in JIS C 9801 alignment remains essential for retail channel access.
For New Entrants and Emerging Players: Direct-to-consumer digital channels bypass established electronics retail gatekeepers in Tokyo's portable-format segment, where rental household flexibility needs fragment purchase patterns. Osaka and Kyoto metropolitan areas offer the most penetrable geography given 18-24 month lag in smart-grid program enrollment versus Kanto. Cloud-recipe subscription models provide the optimal go-to-market angle for recurring revenue attachment beyond hardware transactions.
For Investors and Strategic Acquirers: Consolidation pressure builds where thermal engineering talent scarcity concentrates among aging specialist engineers in Nagoya's automotive supply chain spillover region. Long-term viability favors diversified industrial conglomerates with captive IoT platform ecosystems over pure-play hardware manufacturers. Acquisition targets should demonstrate METI certification pre-emption capabilities and smart-grid partnership formation. Watch Kansai Electric Power demand-response trial expansion as the inflection indicator for connectivity-enabled product adoption acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Grid Partnership Formation | TEPCO demand-response enrollment creates recurring revenue streams for connected refrigerator and oven owners. |
| Cloud-Recipe Subscription Launch | Panasonic's Home Appliance IoT platform demonstrates monetization potential beyond hardware transactions. |
| METI Certification Pre-emption | Top Runner compliance determines retail channel access and resale value in property transactions. |
| Portable Format Line Extension | Tokyo's lease-dominant housing market drives highest density of countertop and drawer-format purchases. |
| Thermal Engineering Talent Acquisition | Precision temperature control expertise concentrates among aging specialist engineers in Aichi prefecture. |
Research Methodology
Bottom-up household and foodservice demand modeling reconciled against top-down component supply tracking forms the analytical core of this study. Primary interviews with product development executives at diversified appliance manufacturers, procurement leads at condominium developers, category buyers at Kanto corridor electronics retailers, and thermal engineering specialists in Nagoya industrial clusters combined with secondary validation. Secondary sources include METI efficiency benchmark disclosures, JIS C 9801 testing protocol documentation, TEPCO demand-response pilot program filings, and customs records for copper and rare earth component imports. Triangulation between bottom-up end-use enumeration and top-down supply-side aggregation ensures consistency.
Input-output matrices map refrigerator, oven, microwave, and dishwasher shipments across product type, customer segment, technology tier, and installation format dimensions over the projection horizon. CAGRs derive from regression analysis of replacement cycle timing against regulatory mandate effective dates, with smart-appliance penetration curves modeled separately from energy-efficient baseline adoption. Forecast inputs include condominium construction permits in Tokyo and Osaka, utility demand-response program enrollment trajectories, and METI Top Runner standard revision schedules.
The model assumes a particular technology adoption path; alternative pathways for voice-integrated AI cooking assistance would alter the outlook. Forecasts reflect base-case assumptions regarding METI regulatory continuity and Kanto corridor smart-grid infrastructure deployment. Commodity price volatility, single-frequency power infrastructure constraints, and appliance longevity culture present specific revision risks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
UK Cookware Market
Kitchen Appliances
Mixers and Attachments Market
Kitchen Appliances
Europe Household Refrigerator Market
Kitchen Appliances
North America Electric Kettle Market
Kitchen Appliances
Toaster Market
Kitchen Appliances
Kitchen Appliances Market
Kitchen Appliances
China Kitchen Appliances Market
Kitchen Appliances
Heavy Duty Mixer Grinder Market
Kitchen Appliances
Egg Boiler/Cooker Market
Kitchen Appliances
South Korea Electric Hobs Market
Kitchen Appliances
Household Coffee Machine Market
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
Europe Major Home Appliances Market
Kitchen Appliances
Commercial Tabletop Kitchen Products Market
Kitchen Appliances
Cotton Candy Maker Market