
 Europe Air Fryers Market | 2026-2036
Europe Air Fryers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Air Fryers Market Insights
Aftermarket service revenue is narrowing as manufacturers shift toward integrated digital ecosystems and subscription-based recipe platforms. Groupe SEB leverages its multi-brand architecture to control shelf space across European retail channels. Koninklijke Philips N.V. anchors its position through proprietary Rapid Air technology and premium positioning in Northern Europe. Electrolux Group competes on manufacturing scale and energy-efficiency credentials aligned with regional compliance frameworks.
An air fryer is a countertop convection appliance that circulates heated air between 150°C and 200°C through a compact cooking chamber to produce crisped food surfaces with minimal oil application. The device employs a high-speed fan, heating coil, and perforated basket to achieve Maillard reactions without submersion frying, serving residential and commercial food preparation needs. Digital air fryers command widening margin pools as touchscreen interfaces and programmable presets justify price premiums over standard mechanical units. Multifunctional air fryers incorporating pressure-cooking and dehydrating modes represent the fastest-expanding product configuration as consumers seek appliance consolidation. The household end-user segment sustains volume leadership while restaurants and cafés adopt commercial-grade units for streamlined back-of-house operations.
The EU Ecodesign Directive and REACH compliance requirements shape material selection and energy-labeling obligations for manufacturers distributing across member states. CE marking mandates govern electrical safety and electromagnetic compatibility, creating non-tariff barriers for non-compliant imports. France's DGCCRF and Germany's Federal Network Agency enforce national-level surveillance that amplifies these baseline requirements. Stakeholders must monitor evolving EU energy-labeling classes and right-to-repair legislation as these frameworks will determine which product configurations retain market access and consumer preference across the continent.
Market Dynamics
EU Ecodesign Directive enforcement is compressing permissible wattage thresholds, forcing manufacturers to redesign heating coils and fan assemblies while maintaining cooking performance benchmarks that consumers expect from premium countertop appliances.
Growth Catalysts
- EU Green Deal appliance standards:Mandatory energy-labeling upgrades create replacement cycles across German, French, and British households as older units lose retail authorization.
- Maillard reaction engineering:Advances in perforated basket airflow geometry enable oil-free crisping that matches deep-fried texture profiles, expanding addressable demand beyond health-conscious niches.
- Urban kitchen downsizing:Compact multifunctional units displace separate toaster ovens, dehydrators, and pressure cookers in London, Paris, and Berlin apartment installations.
Market Restraints
- Copper and aluminum coil volatility:Heating element raw material costs fluctuate with energy-intensive smelting output cuts, compressing margin buffers on mid-tier product lines.
- Chinese OEM concentration:Contract manufacturing for European brands clusters in Guangdong province, exposing supply continuity to regional power rationing and shipping rate spikes.
- REACH substance restrictions:Non-stick ceramic coating formulations face phased elimination of specific perfluorinated compounds, requiring costly reformulation cycles.
Strategic Opportunities
- Spain and Italy penetration gaps:Southern European household adoption trails Northern levels by a significant margin, offering first-mover positioning for localized recipe content and retail partnerships.
- Commercial kitchen certification:NSF International and equivalent EU hygiene standards for back-of-house equipment remain underdeveloped, creating whitespace for purpose-built stainless-steel units.
- Right-to-repair alignment:Pending EU legislation mandating spare parts availability and repair documentation favors modular designs with standardized component interfaces.
Industry Challenges
- Embedded software compliance:Cybersecurity certification for WiFi-connected units under EU Radio Equipment Directive adds development timeline months and testing overhead.
- Cross-border warranty execution:Fragmented national consumer protection laws complicate unified service networks, forcing country-specific logistics investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Air Fryers Market |
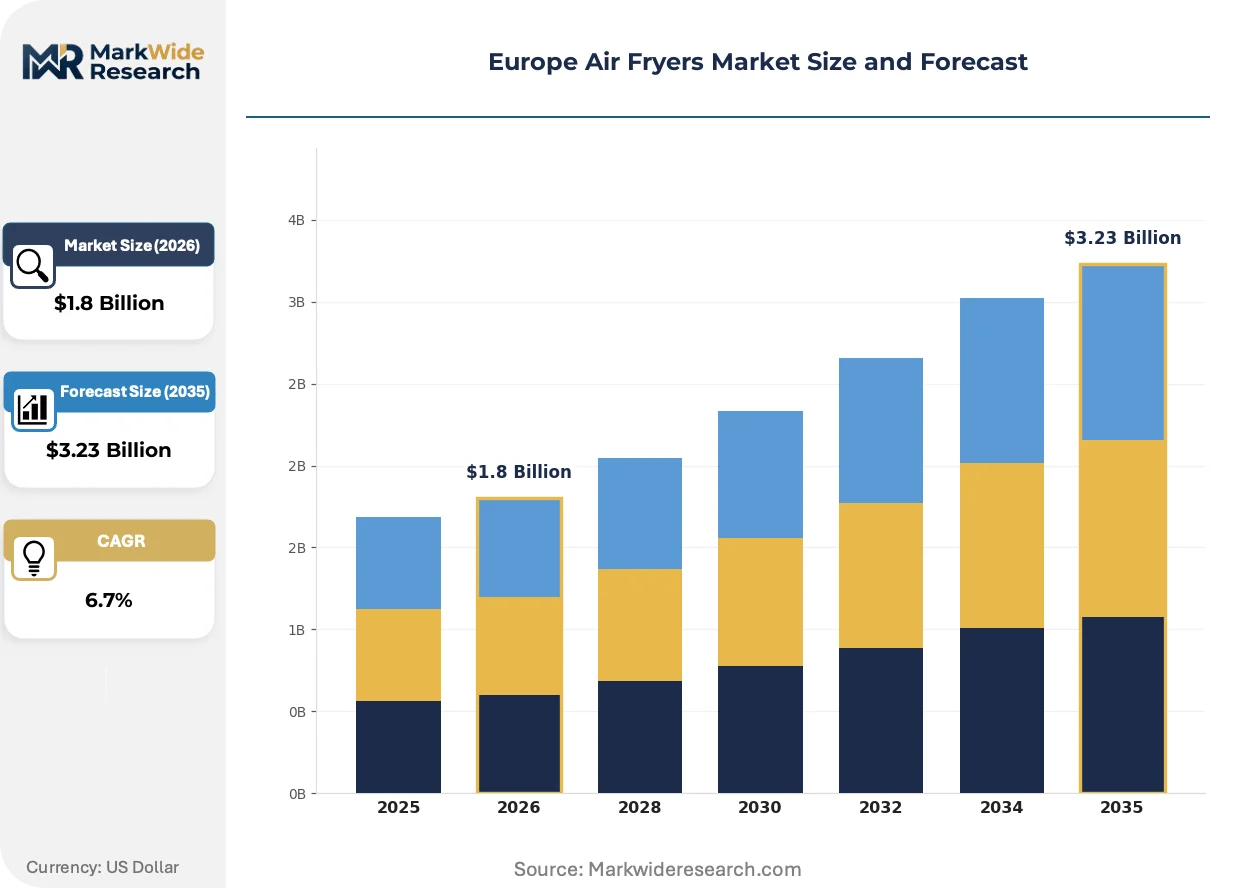
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Air Fryers, Digital Air Fryers, Multifunctional Air Fryers, Mini Air Fryers End User: Households, Restaurants, Cafés, Catering Services Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Warehouses Price Tier: Premium, Mid-range, Budget, Discounted |
| Companies Covered | Stanley Black & Decker, Electrolux Group, Koninklijke Philips N.V., Russell Hobbs, Versuni, Groupe SEB, Breville Group Limited, Tristar Group, De'Longhi, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Air Fryers Market Trends and Innovations
Digital interface integration and cooking algorithm personalization are redefining how manufacturers capture recurring revenue and build defensible brand loyalty beyond hardware replacement cycles.
Dual-zone air fryer architecture is hybridizing independent temperature and timing controls across stacked cooking chambers, enabling simultaneous preparation of proteins and starches with divergent thermal requirements. Young urban households in Copenhagen and Amsterdam adopt these configurations fastest, valuing meal-prep efficiency over unit cost. The technology is hybridizing what were separate appliance categories into consolidated countertop footprints that command price premiums.
REACH substance authorization processes are tightening scrutiny on non-stick coating chemistries, particularly fluoropolymer alternatives under sunset clause review. Manufacturers face reformulation deadlines that invalidate existing supply contracts and require new supplier qualification. French DGCCRF market surveillance has accelerated enforcement actions against non-compliant imports, shifting competitive advantage toward vertically integrated coating capabilities.
Recipe platform subscription bundling is displacing standalone hardware transactions as the primary customer acquisition mechanism. Retailers in Germany and the United Kingdom now demand API-compatible units that sync with proprietary meal-planning ecosystems. This shift concentrates margin capture with software-integrated brands while eroding price-competitive mechanical-only competitors.
Europe Air Fryers Market Segmentation
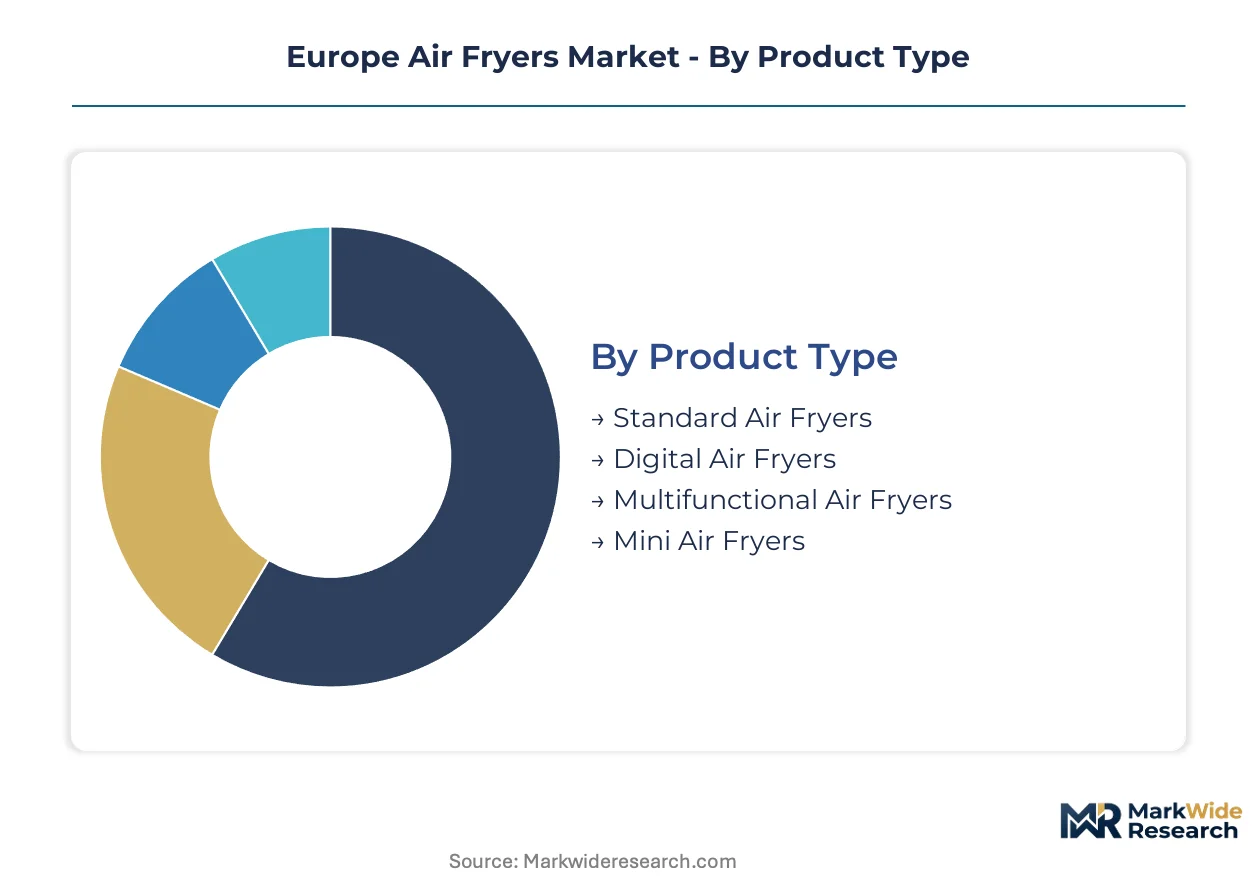
Product architecture in the Europe Air Fryers Market fragments across cooking technology sophistication, end-use intensity, channel access economics, and household willingness-to-pay thresholds. Each dimension captures distinct margin structures and regulatory exposure profiles that determine manufacturer positioning strategies.
Product Type:
Cost tier stratification separates mechanical simplicity from software-integrated premium configurations, with thermal engineering and interface complexity driving manufacturing economics.
- Standard Air Fryers:Mechanical dial controls and fixed temperature presets dominate unit economics, with French and British discount retailers moving volume through seasonal promotional cycles. Manufacturing concentrates in Guangdong province with minimal customization for national preferences.
- Digital Air Fryers:Touchscreen interfaces with programmable presets and WiFi connectivity justify 40-60% price premiums over mechanical equivalents. German households show strongest preference for app-integrated units that sync with recipe subscription services.
- Multifunctional Air Fryers:Pressure-cooking, dehydrating, and roasting modes consolidated into single footprints are climbing the fastest as Copenhagen and Amsterdam apartment dwellers seek appliance reduction.
- Mini Air Fryers:Sub-2-liter chambers target single-person households in London and Paris micro-apartments, with limited wattage appealing to EU Ecodesign compliance thresholds.
Standard Air Fryers holds installed capacity. Multifunctional Air Fryers is rotating up the share rankings.
End User:
Application intensity varies from occasional residential meal preparation to continuous commercial back-of-house operations, with duty cycles and durability specifications diverging sharply.
- Households:Residential units prioritize countertop footprint reduction and aesthetic integration with kitchen cabinetry, with Northern European households leading connected-device adoption rates.
- Restaurants:High-throughput stainless-steel configurations with rapid recovery heating elements serve back-of-house frying replacement in Berlin and Munich fast-casual chains. NSF-equivalent hygiene certification remains underdeveloped in EU markets.
- Cafés:Mid-duty cycle units balance pastry crisping demands with space constraints typical of Parisian and Milanese espresso bar layouts.
- Catering Services:Mobile event preparation requires portable configurations with generator-compatible power draws, with Spanish and Italian outdoor hospitality driving seasonal demand spikes.
Households holds installed capacity. Restaurants is rotating up the share rankings.
Distribution Channel:
Customer type access patterns separate convenience-driven digital natives from tactile evaluators who demand in-person product demonstration before purchase commitment.
- Online Retail:Amazon.de, Amazon.fr, and Amazon.co.uk dominate unit volume with algorithmic recommendation engines steering upgrade purchases toward digital and multifunctional configurations. Return logistics complexity favors established brands with reverse supply chain infrastructure.
- Specialty Stores:Kitchenware boutiques in Hamburg, Lyon, and Manchester provide hands-on demonstration that converts premium-tier consideration, with staff expertise justifying 15-25% price premiums over online equivalents.
- Supermarkets:Carrefour, Tesco, and REWE hypermarkets move budget and mid-range mechanical units through impulse placement adjacent to frozen food aisles.
- Warehouses:Metro AG and Costco wholesale formats serve small restaurant and catering procurement with volume pricing and extended warranty terms.
Online Retail holds installed capacity. Specialty Stores is rotating up the share rankings.
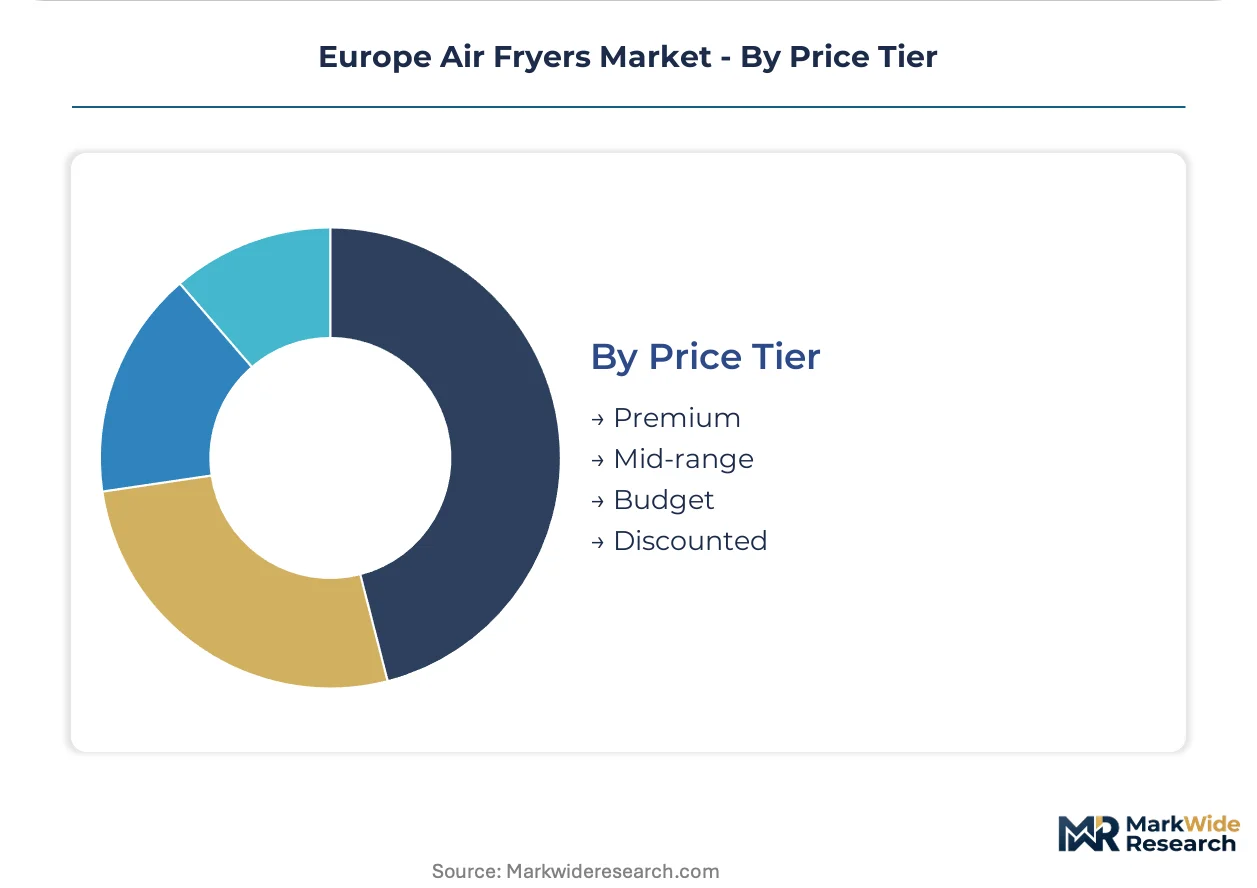
Price Tier:
Margin concentration tracks certification grade alignment, with EU energy-labeling classes and right-to-repair readiness determining which configurations sustain retail authorization.
- Premium:Proprietary airflow engineering, ceramic non-stick coatings with REACH-compliant formulations, and 5-year warranty terms anchor positioning above 200 EUR price points in German and Dutch markets.
- Mid-range:80-150 EUR positioning balances digital interfaces with mechanical reliability, capturing replacement cycles triggered by EU Ecodesign Directive enforcement.
- Budget:Sub-80 EUR mechanical units face margin compression from raw material volatility and reduced retail authorization as energy-labeling standards tighten.
- Discounted:Seasonal clearance and refurbished channels absorb inventory obsolescence from rapid model-year turnover, with French DGCCRF surveillance elevating compliance risks for gray-market imports.
Mid-range holds installed capacity. Premium is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply across the continent, with German and Dutch buyers accepting 40-60% price premiums for connected units while Spanish and Italian households remain anchored to sub-80 EUR mechanical configurations.
Germany
App-integrated digital air fryers dominate replacement cycles as households prioritize recipe platform compatibility. The Federal Network Agency enforces national-level surveillance that amplifies EU Ecodesign baseline requirements. Berlin and Munich anchor commercial-grade adoption among fast-casual chains seeking back-of-house frying alternatives.
United Kingdom
Compact multifunctional units displace separate appliances in London micro-apartments as urban kitchen downsizing accelerates. CE marking mandates govern electrical safety and electromagnetic compatibility for all imports. Manchester and Birmingham concentrate specialty retail channels where hands-on demonstration converts premium-tier consideration.
France
Health-conscious cooking gains traction among Parisian young urban households driving connected-device adoption. DGCCRF market surveillance accelerates enforcement actions against non-compliant imports, shifting advantage toward vertically integrated coating capabilities. Lyon anchors kitchenware boutique density that justifies 15-25% price premiums over online equivalents.
Netherlands
Dual-zone air fryer architecture finds fastest adoption in Amsterdam and Copenhagen as meal-prep efficiency trumps unit cost. EU Green Deal appliance standards trigger replacement cycles as older units lose retail authorization. Eindhoven concentrates manufacturing scale for energy-efficiency credentials aligned with regional compliance frameworks.
Spain
Household adoption trails Northern European levels by a significant margin, offering first-mover positioning for localized recipe content. REACH substance restrictions on non-stick ceramic coating formulations require costly reformulation cycles for market entry. Barcelona and Madrid concentrate retail partnerships awaiting premium-tier penetration strategies.
Europe Air Fryers Market Competitive Landscape
Capability concentration sits with heritage appliance manufacturers possessing proprietary airflow engineering and REACH-compliant coating supply chains; scale advantage sits with diversified conglomerates leveraging multi-brand architectures to control shelf space across European retail channels. The vendor base stratifies across three tiers: integrated digital ecosystem providers capturing recurring subscription revenue, manufacturing-scale specialists competing on EU energy-labeling compliance, and contract-dependent brands exposed to Guangdong supply continuity risks. Dominant competitive moves include portfolio diversification into multifunctional configurations and strategic partnerships with recipe platform operators to secure API-compatible retail placement.
Within the heritage European appliance tier, Koninklijke Philips N.V. and Electrolux Group exemplify divergent positioning strategies, with the former anchoring premium-tier proprietary technology positioning and the latter competing on manufacturing scale and energy-efficiency credentials. Groupe SEB occupies a position representing multi-brand architecture control across French, German, and British retail channels. These three entities collectively illustrate how compliance readiness and digital ecosystem integration separate sustainable market access from margin-compressed commodity positioning.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Electrolux Group |
| Koninklijke Philips N.V. |
| Russell Hobbs |
| Versuni |
| Groupe SEB |
| Breville Group Limited |
| Tristar Group |
| De'Longhi |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp container corridor freight volatility transmits directly into landed cost spreads between Guangdong-sourced mechanical units and EU-assembled digital configurations, compressing margin buffers on mid-tier imports while amplifying price differentiation between subscription-integrated premium brands and commodity competitors.
Pricing Analysis
Recipe platform subscription tiers now drive lifetime value capture more than hardware margins, with German and Dutch households accepting 40-60% upfront premiums for API-compatible units that sync with proprietary meal-planning ecosystems. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant ceramic coating formulations from reformulation-lagged imports and discount mechanical alternatives. Price differentiation hinges on certification grade alignment with EU energy-labeling classes and right-to-repair readiness. Cost compression in budget tiers intensifies because raw material volatility in copper and aluminum heating elements erodes already thin buffers, while Spanish and Italian households remain the most price-sensitive segment.
Supply Chain Analysis
Extended payment terms from Guangdong contract manufacturers to European brand holders have tightened to 60-90 days as energy-intensive smelting output cuts in China elevate working capital demands. Manufacturing concentrates in Guangdong province for mechanical and mid-range digital units, with Eindhoven and regional Czech facilities serving energy-efficiency-certified assembly for premium tiers. Raw material dependencies center on copper and aluminum coil stock, ceramic non-stick coating precursors, and high-temperature fan motor assemblies. Single-source vulnerability runs through Guangdong OEM clustering exposed to regional power rationing and shipping rate spikes. Distribution runs through Amazon.de, Amazon.fr, and Amazon.co.uk algorithmic channels for volume, with Hamburg, Lyon, and Manchester specialty boutiques capturing premium-tier conversion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital recipe platform subscriptions expand faster than hardware replacement cycles, converting transactional appliance purchases into recurring revenue relationships that justify 40-60% lifetime value premiums over standalone unit sales.
For Market Incumbents: Pre-empt margin compression from REACH reformulation deadlines by accelerating vertically integrated coating capabilities before sunset clause enforcement invalidates existing supply contracts. Lock in API-compatible retail placement with German and British recipe platform operators to defend shelf space against mechanical-only competitors losing authorization under tightening EU Ecodesign thresholds.
For New Entrants and Emerging Players: Build out localized recipe content partnerships in Spain and Italy where household adoption trails Northern European levels by substantial margins, enabling first-mover positioning before heritage brands redirect Southern European penetration investments. Target commercial kitchen certification whitespace for NSF-equivalent stainless-steel configurations in Berlin and Munich fast-casual chains, bypassing saturated household segments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular design specialists with standardized component interfaces that align with pending right-to-repair legislation mandating spare parts availability and repair documentation. Acquisition targets should demonstrate captive coating supply chains and energy-labeling compliance infrastructure that sustain retail authorization across the analysis window. The inflection signal to watch is DGCCRF enforcement acceleration against non-compliant imports, which would abruptly invalidate gray-market inventory and concentrate share among compliance-ready manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Recipe Platform API Integration | Amazon.de and Amazon.co.uk algorithmic recommendation engines now demand API-compatible units for premium placement. |
| REACH-Compliant Coating Verticalization | French DGCCRF surveillance accelerates enforcement against reformulation-lagged imports, shifting advantage to captive supply. |
| Dual-Zone Architecture Development | Copenhagen and Amsterdam young urban households adopt independent temperature controls fastest, valuing meal-prep efficiency. |
| Commercial NSF-Equivalent Certification | Berlin and Munich fast-casual chains seek back-of-house frying alternatives with underdeveloped EU hygiene standards. |
| Right-to-Repair Modular Design | Pending EU legislation mandating spare parts availability favors standardized component interfaces over sealed-unit construction. |
Research Methodology
A standing panel of product development directors at heritage appliance manufacturers, procurement leads at German and French retail chains, regulatory affairs specialists navigating REACH authorization processes, and aftermarket service heads provided ongoing calibration across primary interview rounds. Secondary validation drew from EU Ecodesign Directive implementation trackers, ECHA substance authorization databases, customs records for Guangdong-origin electrical appliance imports, and energy-labeling compliance registries. Bottom-up unit shipment estimates by product configuration and price tier were triangulated against top-down household penetration models for urban kitchen downsizing trends.
Scenario-bracketing around EU Green Deal enforcement timelines, raw material cost volatility bands, and recipe platform adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture sophistication, end-use intensity from residential to commercial, channel access economics, and household willingness-to-pay thresholds. CAGRs were derived from installed base replacement cycles, technology diffusion curves for connected-device adoption, and regulatory-driven authorization sunsets. Industry-specific forecast inputs incorporated REACH sunset clause schedules and DGCCRF enforcement intensity indices.
Stress conditions across copper and aluminum coil price volatility, Guangdong power rationing frequency, and EU energy-labeling class revision timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and platform ecosystem consolidation trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Range Cooker Market
Kitchen Appliances
On-The-Go Pots Market
Kitchen Appliances
Smart Cooktop Market
Kitchen Appliances
Asia Pacific Induction Hobs Market
Kitchen Appliances
Cookware Accessories Market
Kitchen Appliances
India Mixer Grinder Market
Kitchen Appliances
United States Electric Vegetable Choppers Market
Kitchen Appliances
Russia Household Electric Grill Market
Kitchen Appliances
North America Electric Vegetable Choppers Market
Kitchen Appliances
Asia Pacific Household Electric Grills Market
Kitchen Appliances
Sandwich Maker Market
Kitchen Appliances
UK Cookware Market
Kitchen Appliances
China Kitchen Appliances Market
Kitchen Appliances
Cooktop Market
Kitchen Appliances
South Korea Electric Hobs Market
Kitchen Appliances
Self-Heating Butter Knife Market