
 Intracranial Hemorrhage Diagnosis and Treatment Market | 2026-2036
Intracranial Hemorrhage Diagnosis and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Intracranial Hemorrhage Diagnosis and Treatment Market Foresight
Hospital-based stroke center networks is expanding their neurocritical care bed capacity across integrated delivery systems. Stryker Corporation dominates the neurosurgical device segment with hemorrhage evacuation platforms. Medtronic plc leverages its interventional neurology portfolio to compete in minimally invasive clot management. Koninklijke Philips N.V. anchors the imaging diagnostics layer through advanced CT and MRI systems deployed in emergency departments.
Intracranial hemorrhage diagnosis and treatment encompasses the identification and management of bleeding within the cranial vault, including epidural, subdural, subarachnoid, and intraparenchymal hemorrhage types, utilizing non-contrast CT as the gold standard imaging modality with sensitivity exceeding 95% for acute blood detection. The primary purpose is to enable rapid triage, surgical intervention, or medical management to prevent secondary brain injury and reduce mortality. CT scan and MRI modalities within the product type dimension lead current revenue contribution due to capital equipment replacement cycles and AI-integrated software upgrades, while ultrasound applications in point-of-care settings represent the fastest-growing sub-area as portable devices penetrate pre-hospital and urgent care environments. The therapy area segmentation shows neurosurgery and emergency care capturing the deepest margin pools where device-therapeutic combinations command premium positioning.
FDA breakthrough device pathways and CE marking under the EU MDR shape product development timelines and market access requirements for hemorrhage detection algorithms and interventional devices. HIPAA compliance obligations in the United States and GDPR data governance in Europe constrain cloud-based AI diagnostic deployments, creating regional variation in software-as-a-service adoption. Stakeholders must monitor reimbursement parity between AI-augmented and conventional imaging reads across national health technology assessment frameworks to calibrate commercialization sequencing.
Market Dynamics
AI-assisted hemorrhage detection algorithms are compressing diagnostic timelines from hours to minutes, forcing capital equipment vendors to bundle software subscriptions with CT and MRI hardware or risk displacement in emergency department procurement cycles.
Growth Catalysts
- FDA Breakthrough Device Pathway:The FDA's accelerated review track for AI diagnostic tools reduces time-to-market for hemorrhage detection algorithms, enabling faster commercialization of machine learning models trained on acute stroke imaging datasets.
- Pre-hospital Ultrasound Penetration:Portable point-of-care ultrasound devices are expanding into ambulance services and urgent care clinics, creating new diagnostic touchpoints before hospital arrival.
- Aging Trauma Networks:Established trauma center certification programs in the United States, Germany, and Japan are mandating neurocritical care bed expansion, driving procedure volume concentration at designated stroke centers.
Market Restraints
- EU MDR Compliance Burden:CE marking under the EU Medical Device Regulation imposes extended clinical evidence requirements and notified body capacity constraints, delaying European market entry for hemorrhage detection software.
- Cloud Infrastructure Concentration:HIPAA and GDPR data residency rules fragment cloud deployment architectures, forcing vendors to maintain separate infrastructure stacks for US and European customers and raising operational complexity.
- Neuroradiologist Workforce Scarcity:The limited pipeline of fellowship-trained specialists capable of validating AI algorithm outputs creates a bottleneck for regulatory submission and clinical adoption.
Strategic Opportunities
- Rural Hospital AI Teleradiology:Underserved regions in the United States and India present white space for cloud-connected hemorrhage detection services that extend specialist-level triage to facilities without on-site neuroradiologists.
- Interventional Clot Management Convergence:Combination device-therapeutic platforms integrating real-time imaging with minimally invasive evacuation tools command premium positioning in neurosurgical suites.
- Japan's PMDA Sakigake Pathway:Japan's fast-track approval system for regenerative medicine and AI diagnostics offers an accelerated regulatory route for hemorrhage detection algorithms targeting the Asia-Pacific region.
Industry Challenges
- Reimbursement Parity Uncertainty:National health technology assessment frameworks in the United States and Germany have not established consistent payment codes for AI-augmented versus conventional imaging reads, complicating commercialization sequencing.
- Legacy PACS Integration Friction:Hospital picture archiving and communication systems require costly middleware development to ingest AI diagnostic outputs, slowing deployment timelines and raising implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intracranial Hemorrhage Diagnosis and Treatment Market |
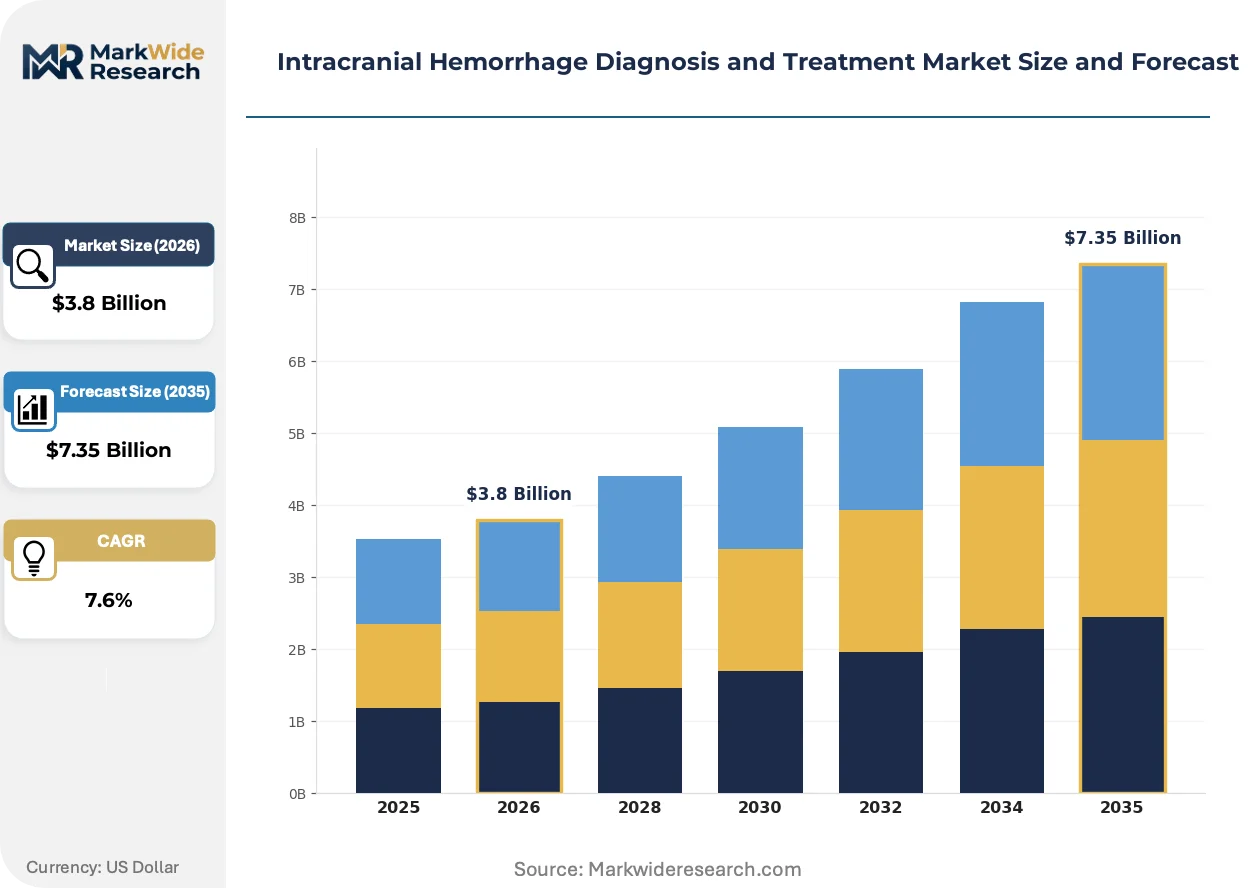
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scan, MRI, Ultrasound, X-Ray Therapy Area: Neurosurgery, Neurology, Emergency Care, Critical Care Administration Route: Intravenous, Intra-arterial, Oral, Localized End User: Hospitals, Clinics, Rehabilitation Centers, Urgent Care Facilities |
| Companies Covered | Stryker Corporation, Koninklijke Philips N.V., Medtronic plc, Novartis AG, Bristol-Myers Squibb Company, GE Healthcare, Johnson & Johnson, Integra LifeSciences Corporation, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intracranial Hemorrhage Diagnosis and Treatment Market Shifts & Advancements
Edge computing architectures and federated learning frameworks are redistributing diagnostic capability away from centralized radiology departments toward point-of-care environments, compressing the traditional imaging workflow.
Portable ultrasound devices with embedded hemorrhage detection algorithms are decentralizing acute stroke triage from hospital radiology suites to ambulance bays and community emergency departments. Emergency medical services in the United States and Germany are piloting these systems for pre-hospital identification of intracranial bleeding. The technology is compressing door-to-needle timelines by enabling treatment activation before CT confirmation.
The EU AI Act's risk classification system for medical devices is imposing new conformity assessment obligations on hemorrhage detection software marketed in Europe. High-risk AI systems must demonstrate accuracy, robustness, and cybersecurity through notified body evaluation. Vendors are restructuring quality management systems and clinical validation protocols to satisfy these requirements ahead of enforcement deadlines.
Hospital procurement committees are unbundling imaging hardware from software service contracts, treating AI diagnostic subscriptions as separate line items with distinct ROI justifications. This pattern is most visible in integrated delivery networks in the United States, where chief financial officers demand evidence-based proof of reduced length-of-stay or improved outcomes before approving recurring software fees.
Intracranial Hemorrhage Diagnosis and Treatment Market Segmentation
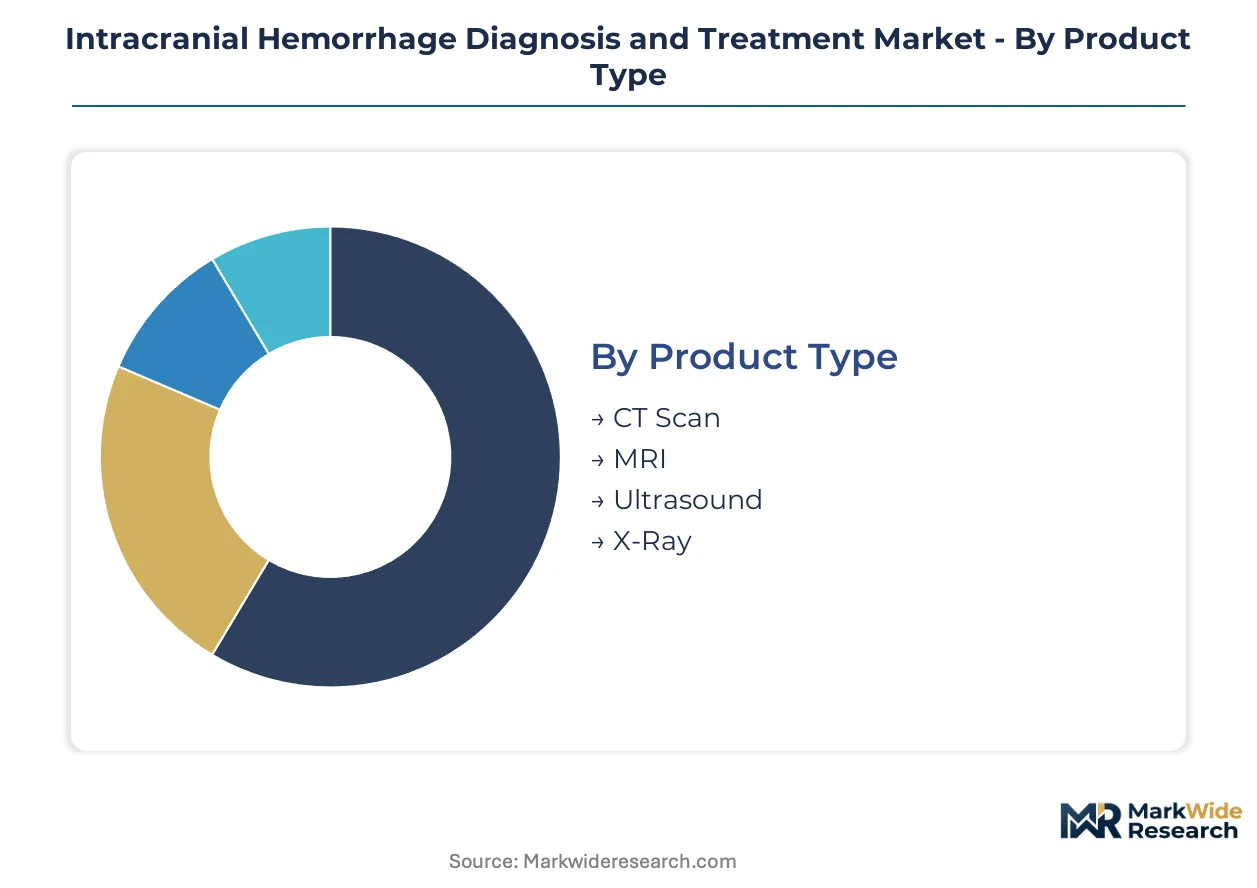
Diagnostic and therapeutic modalities for intracranial hemorrhage span distinct technical specifications, clinical settings, and delivery mechanisms. Each segmentation axis reveals where capital investment concentrates and where regulatory pathways create competitive moats.
Product Type:
Imaging resolution, scan speed, and portability define competitive positioning across hardware categories.
- CT Scan:Non-contrast head CT delivers sub-minute acquisition times with sensitivity exceeding 95 percent for acute blood detection. Emergency departments in the United States, Germany, and Japan prioritize 64-slice and 128-slice configurations for trauma bay deployment, driving replacement cycles tied to AI software integration.
- Ultrasound:Portable point-of-care devices with embedded hemorrhage detection algorithms compress door-to-needle timelines by enabling pre-hospital triage. Ambulance services in the United States and Germany are piloting these systems, creating the steepest expansion trajectory among imaging modalities.
- MRI:Magnetic resonance imaging provides superior soft-tissue characterization for subacute and chronic hemorrhage evaluation, though longer scan times limit emergency department utility.
- X-Ray:Skull radiography retains niche applications for suspected fracture correlation but lacks direct parenchymal visualization capability.
CT Scan leads on scale; Ultrasound leads on momentum.
Therapy Area:
Procedure reimbursement rates and device-therapeutic bundling determine margin capture across clinical specialties.
- Emergency Care:Trauma bay activation protocols mandate rapid hemorrhage identification to trigger neurosurgical consultation or interventional neuroradiology. Stroke center certification programs in the United States require dedicated neurocritical care pathways, concentrating procedure volume at designated facilities.
- Neurosurgery:Minimally invasive evacuation platforms and endoscopic hematoma drainage command premium pricing in operative suites. Academic medical centers in Japan and Germany drive adoption of robot-assisted navigation systems for deep-seated hemorrhage.
- Neurology:Medical management of intraparenchymal hemorrhage focuses on blood pressure control, reversal of anticoagulation, and secondary injury prevention in step-down units.
- Critical Care:Neurointensive care units manage multimodality monitoring, intracranial pressure optimization, and delayed cerebral ischemia prevention following subarachnoid hemorrhage.
Emergency Care captures the deepest margins; Neurosurgery shows the fastest technology refresh cycles.
Administration Route:
Pharmacokinetic profile and blood-brain barrier penetration dictate route selection for hemorrhage adjunctive therapy.
- Intravenous:Systemic delivery enables rapid anticoagulation reversal agents and antihypertensive titration in acute settings. United States emergency departments favor IV prothrombin complex concentrate for warfarin-associated hemorrhage.
- Intra-arterial:Catheter-directed thrombolysis and targeted drug delivery access vascular territories compromised by mass effect or edema. Japanese interventional neuroradiology suites report expanding utilization for aneurysmal subarachnoid hemorrhage.
- Oral:Maintenance antihypertensives and secondary prevention agents transition patients from acute to chronic management phases.
- Localized:Intraventricular thrombolysis and intrathecal drug delivery address compartmentalized hemorrhage complications in specialized neurocritical care units.
Intravenous dominates acute intervention volume; Intra-arterial is climbing fastest on interventional neuroradiology expansion.
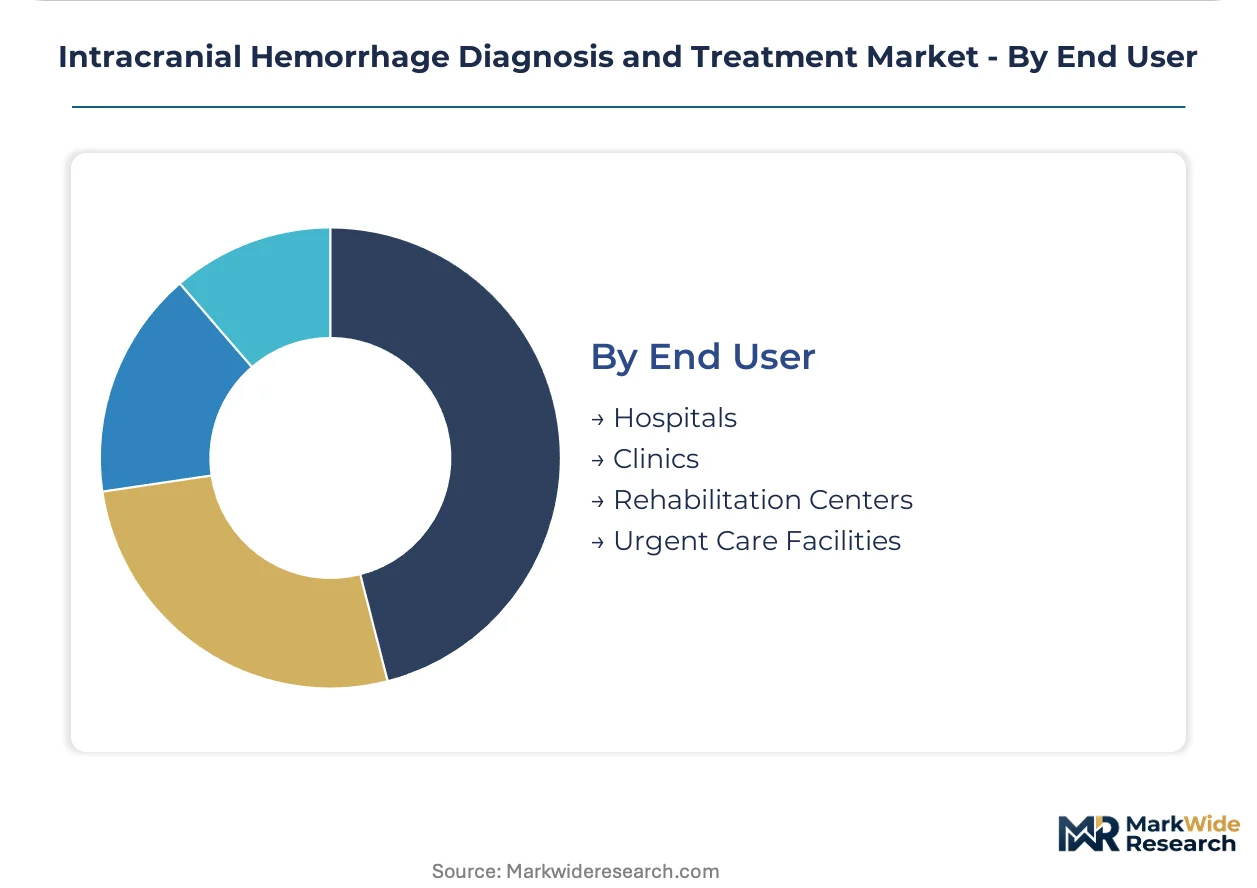
End User:
Capital intensity, specialist availability, and patient acuity stratify demand across facility types.
- Hospitals:Comprehensive stroke centers integrate CT/MRI suites, neurosurgical theaters, and neurointensive care units under unified command structures. United States hospital networks are consolidating hemorrhage care at Level I trauma designations.
- Urgent Care Facilities:Freestanding emergency centers with CT capability extend geographic coverage for time-sensitive triage decisions. Rural networks in Germany leverage these sites for pre-transfer stabilization.
- Clinics:Outpatient neurology practices manage hemorrhage risk factor modification and long-term functional recovery monitoring.
- Rehabilitation Centers:Post-acute facilities coordinate cognitive and motor recovery programs for hemorrhage survivors with residual deficits.
Hospitals anchor absolute procedure volume; Urgent Care Facilities are expanding most quickly on network decentralization strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stroke center certification programs in the United States concentrate hemorrhage care at designated Level I trauma facilities, driving neurocritical care bed expansion across integrated delivery networks. Germany and Japan sustain procedure volumes through established trauma networks and aging demographics. India and Brazil emerge as high-growth markets where network decentralization strategies extend diagnostic reach.
United States
Comprehensive stroke centers mandate 24/7 neurosurgical coverage and advanced imaging capabilities, concentrating hemorrhage cases at certified facilities. FDA breakthrough device pathways accelerate commercialization timelines for AI-assisted detection algorithms. The Texas Medical Center in Houston anchors one of the largest neurocritical care clusters, with multiple institutions deploying integrated CT-angiography suites for rapid triage protocols.
Germany
Regional trauma networks under the DGU (German Trauma Society) certification system standardize hemorrhage management protocols across federal states. EU MDR compliance requirements and CE marking pathways shape market access for diagnostic software vendors. The Berlin-Brandenburg metropolitan region hosts dense concentrations of university hospitals with integrated neuroradiology and neurosurgical departments managing complex subarachnoid hemorrhage cases.
Japan
PMDA Sakigake fast-track approvals for AI diagnostics reduce regulatory timelines for hemorrhage detection algorithms targeting the Asia-Pacific region. Aging demographics sustain elevated incidence of hypertensive intracerebral hemorrhage requiring specialized intervention. The Osaka-Kobe corridor in Kansai region concentrates advanced endovascular capabilities, with academic medical centers pioneering minimally invasive clot evacuation techniques.
India
Expanding health insurance penetration and private hospital network growth drive demand for CT and MRI installations in tier-2 cities. CDSCO regulatory pathways for medical devices govern import and local manufacturing of diagnostic equipment. The Delhi-NCR cluster aggregates neurosurgical referral volume, with corporate hospital chains establishing dedicated stroke units equipped with portable ultrasound for pre-hospital triage extension.
Brazil
ANVISA medical device registration requirements structure market entry for international imaging and interventional equipment suppliers. Public health system investments in emergency care infrastructure expand CT availability beyond metropolitan cores. The São Paulo metropolitan region concentrates private neurosurgical capacity, with academic institutions in the city advancing training programs for endovascular hemorrhage management.
Intracranial Hemorrhage Diagnosis and Treatment Market Competitive Landscape
Strategic partnerships dominate the current landscape as device manufacturers align with AI software developers to bundle diagnostic capabilities with imaging hardware. The market exhibits tiered concentration: multinational conglomerates control capital equipment segments, mid-cap specialists occupy neurosurgical device niches, and emerging AI vendors compete on algorithm performance. Three archetypes define positioning: integrated imaging-to-intervention platforms, standalone diagnostic software providers, and focused surgical instrument specialists. M&A activity and technology licensing agreements represent the primary competitive vectors as firms seek to compress time-to-market for regulatory-cleared products.
Among diversified healthcare conglomerates, Stryker Corporation, Koninklijke Philips N.V., and Medtronic plc exemplify distinct strategic postures. Stryker Corporation anchors the neurosurgical intervention archetype with its evacuation platform portfolio. Koninklijke Philips N.V. occupies the imaging systems tier through CT and MRI hardware deployed in emergency departments globally. Medtronic plc represents the interventional neurology convergence model, leveraging catheter-based capabilities across vascular and hemorrhage indications. These three entities collectively illustrate how scale, specialization, and integration define competitive positioning in hemorrhage care delivery.
| Leading Market Players |
|---|
| Stryker Corporation |
| Koninklijke Philips N.V. |
| Medtronic plc |
| Novartis AG |
| Bristol-Myers Squibb Company |
| GE Healthcare |
| Johnson & Johnson |
| Integra LifeSciences Corporation |
| Siemens AG |
| Others |
Supply & Pricing Matrix
Captive software integration within imaging hardware anchors pricing power for CT and MRI vendors serving emergency departments across the United States, Germany, and Japan. This vertical bundling of AI diagnostic subscriptions with capital equipment creates switching costs that protect margin pools while compressing standalone software pricing.
Pricing Analysis
Input-cost pass-through from rare-earth magnet supply constraints and semiconductor component shortages feeds into CT and MRI hardware pricing. Three-tier pricing structure across premium AI-integrated, standard diagnostic, and economy refurbished systems separates academic medical centers from community hospitals and urgent care facilities. Pricing pressure stems from hospital procurement committees unbundling software subscriptions from hardware contracts. Community hospitals exhibit highest price sensitivity due to constrained capital budgets, while comprehensive stroke centers prioritize throughput metrics over unit cost.
Supply Chain Analysis
CE marking and FDA 510(k) clearance gates concentrate component supply among qualified vendors in the United States, Germany, and Japan. Superconducting wire, gradient coil assemblies, and X-ray tube arrays draw from specialized manufacturers in these jurisdictions. Single-source vulnerability runs through Japanese suppliers of high-field magnet wire. Distribution runs through integrated delivery network procurement consortia and group purchasing organizations negotiating system-wide contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intracranial hemorrhage diagnosis and treatment market compounds steadily as aging demographics in developed economies sustain procedure volume expansion with limited cyclical exposure.
For Market Incumbents: Deepen AI algorithm training partnerships with academic stroke centers to lock in regulatory validation pathways and create data network effects that emerging entrants cannot replicate. Prioritize backward integration into edge computing hardware for point-of-care ultrasound to defend against software-only disintermediation. The FDA breakthrough device pathway accelerates competitor entry timelines, requiring pre-emptive portfolio refresh cycles. For New Entrants and Emerging Players: Cloud-native teleradiology platforms offer the lowest-friction entry vector for rural hospital networks in the United States and tier-2 Indian cities lacking on-site neuroradiologists. Target urgent care facilities with portable ultrasound bundled with AI detection software as a capital-light alternative to CT suite investment. Partner with emergency medical services for pre-hospital deployment pilots that establish clinical evidence before hospital procurement engagement. For Investors and Strategic Acquirers: Roll-up economics work for AI diagnostic software specialists because FDA and CE marking clearance scarcity limits viable acquisition targets and creates scarcity value for regulatory-cleared algorithms. The five-to-ten-year viability window favors platforms with demonstrated reimbursement traction over pure technology plays. Monitor CMS Medicare reimbursement determinations for AI-augmented imaging reads as the inflection signal for commercial scalability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review compresses time-to-market for hemorrhage detection algorithms targeting comprehensive stroke centers. |
| CE Marking Pathway under EU MDR | Notified body clearance enables European commercialization of AI diagnostic software with MDR-compliant quality systems. |
| Hospital System Partnership | Integrated delivery network contracts aggregate procedure volume and create switching costs for imaging hardware vendors. |
| Software Companion Development | AI algorithm subscriptions bundled with CT/MRI systems generate recurring revenue streams beyond capital equipment sales. |
| Reimbursement Strategy | CPT code establishment for AI-augmented reads determines commercial viability across Medicare and commercial payer networks. |
Research Methodology
Multiple input streams — primary interviews with neuroradiologists and stroke center directors, secondary validation through FDA 510(k) databases and CMS reimbursement filings, and procurement database analysis — were reconciled to construct market estimates. Conversations with hospital purchasing committee members, biomedical engineers, and GPO contracts managers supplemented regulatory pathway intelligence. Bottom-up procedure volume modeling and top-down capital equipment spend analysis triangulated segment sizing across the analysis window.
Data-stream reconciliation anchored forecast outputs to installed base projections for CT and MRI systems, AI software attach rates, and neurosurgical procedure volumes across product type and therapy area dimensions. CAGRs were derived from regression analysis of historical replacement cycles and penetration curves for emerging modalities like point-of-care ultrasound. Reimbursement parity assumptions and regulatory approval timelines fed scenario-weighted projections throughout the forecast period.
The model assumes a particular technology adoption path; alternative pathways for edge-computing hemorrhage detection would alter the outlook if pre-hospital deployment accelerates beyond base-case assumptions. Forecasts reflect these embedded assumptions regarding FDA breakthrough designations and EU MDR notified body capacity. A model refresh is warranted upon material change in CMS reimbursement determinations for AI-augmented imaging.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
Global Exosome Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Pressure Ulcer Relief Products Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Global Smart Inhaler Technology Market
Diagnostic and Therapeutic Devices
Phototherapy Device Market
Diagnostic and Therapeutic Devices
Upper GI Series Market
Diagnostic and Therapeutic Devices
Acupuncture Needles Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market
Diagnostic and Therapeutic Devices
Skin Biopsy Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market
Diagnostic and Therapeutic Devices
Global Cold Plasma in Healthcare Market
Diagnostic and Therapeutic Devices
Therapeutic Medical Guidewire Market
Diagnostic and Therapeutic Devices
Middle-East and Africa Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Fully Automated Coagulometer Market