
 Bio-LNG Market | 2026-2036
Bio-LNG Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-LNG Market Analytics
European biomethane liquefaction capacity is hardening as project developers scale anaerobic digestion and gas upgrading trains. TotalEnergies anchors its position through integrated biogas sourcing and liquefaction assets across France and Belgium. Shell Plc extends its marine fuel network by adding bio-LNG bunkering terminals at Rotterdam and Singapore. Nordsol specializes in small-scale liquefaction technology that converts biogas to bio-LNG at distributed agricultural sites.
Bio-LNG consists of liquefied biomethane derived from organic waste feedstocks, cooled to approximately minus 162 degrees Celsius to achieve a six-hundred-fold volume reduction for transport and storage. The fuel displaces conventional marine diesel and heavy fuel oil in shipping, and serves as a grid-injected renewable gas for power and heat applications. Liquefied biomethane dominates product type revenue due to established certification under the EU Renewable Energy Directive, while virtual pipeline delivery modes are gaining traction in regions lacking fixed LNG terminal infrastructure. Transportation applications lead absolute consumption volumes, though industrial heating segments offer higher margin capture through long-term offtake contracts.
The EU Green Deal and F-Gas Regulation shape product standards by mandating lifecycle greenhouse gas reductions and restricting high-global-warming-potential alternatives in transport and cooling. EPA renewable fuel standard pathways in the United States provide compliance credit value for biomethane-to-LNG production, while the International Maritime Organization's carbon intensity indicators accelerate shipowner interest in certified bio-LNG bunkers. Stakeholders must track feedstock certification schemes and cross-border guarantee-of-origin transferability to secure offtake premiums and avoid regulatory arbitrage risks.
Market Dynamics
Maritime shipping operators face mounting pressure from the EU Green Deal and Fit for 55 package to decarbonize heavy transport, redirecting capital toward bio-LNG bunkering infrastructure and renewable fuel offtake contracts.
Growth Catalysts
- EU Renewable Energy Directive II:Mandates binding renewable fuel quotas for heavy-duty transport and maritime sectors, creating guaranteed demand pools for certified biomethane liquefaction.
- Anaerobic digestion scale-up:Agricultural waste-to-biogas facilities in the Netherlands and Belgium are expanding liquefaction trains to capture premium marine fuel margins.
- IMO carbon intensity indicators:Shipowners operating trans-Atlantic and intra-European routes are locking in long-term bio-LNG supply to comply with vessel efficiency rating schemes.
Market Restraints
- Feedstock competition:Organic waste streams face diversion pressure from composting and animal feed markets, constraining biogas plant utilization rates in Germany.
- Liquefaction energy costs:Cryogenic cooling to minus 162 degrees Celsius consumes 8-12% of feedstock energy content, eroding plant economics during electricity price spikes.
- Grid injection parity:Biomethane producers in Denmark and Sweden can achieve higher netbacks through direct pipeline injection versus liquefaction, limiting bio-LNG supply growth.
Strategic Opportunities
- Polish and Baltic port clusters:Underdeveloped bio-LNG bunkering infrastructure along Gdansk and Klaipeda creates first-mover advantages for liquefaction project developers.
- Rail and heavy road segments:EU Alternative Fuels Infrastructure Regulation mandates refueling station networks along core transport corridors, opening demand beyond maritime.
- Virtual pipeline logistics:Containerized ISO tank delivery systems enable bio-LNG distribution to industrial heat users lacking fixed terminal access in Spain and Portugal.
Industry Challenges
- Guarantee-of-origin transferability:Cross-border certification recognition gaps between national biogas registries complicate multi-country supply chain structuring and premium pricing capture.
- Cryogenic maintenance specialization:Shortage of technicians trained in minus 162 degree Celsius storage system operations constrains plant uptime and safety compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-LNG Market |
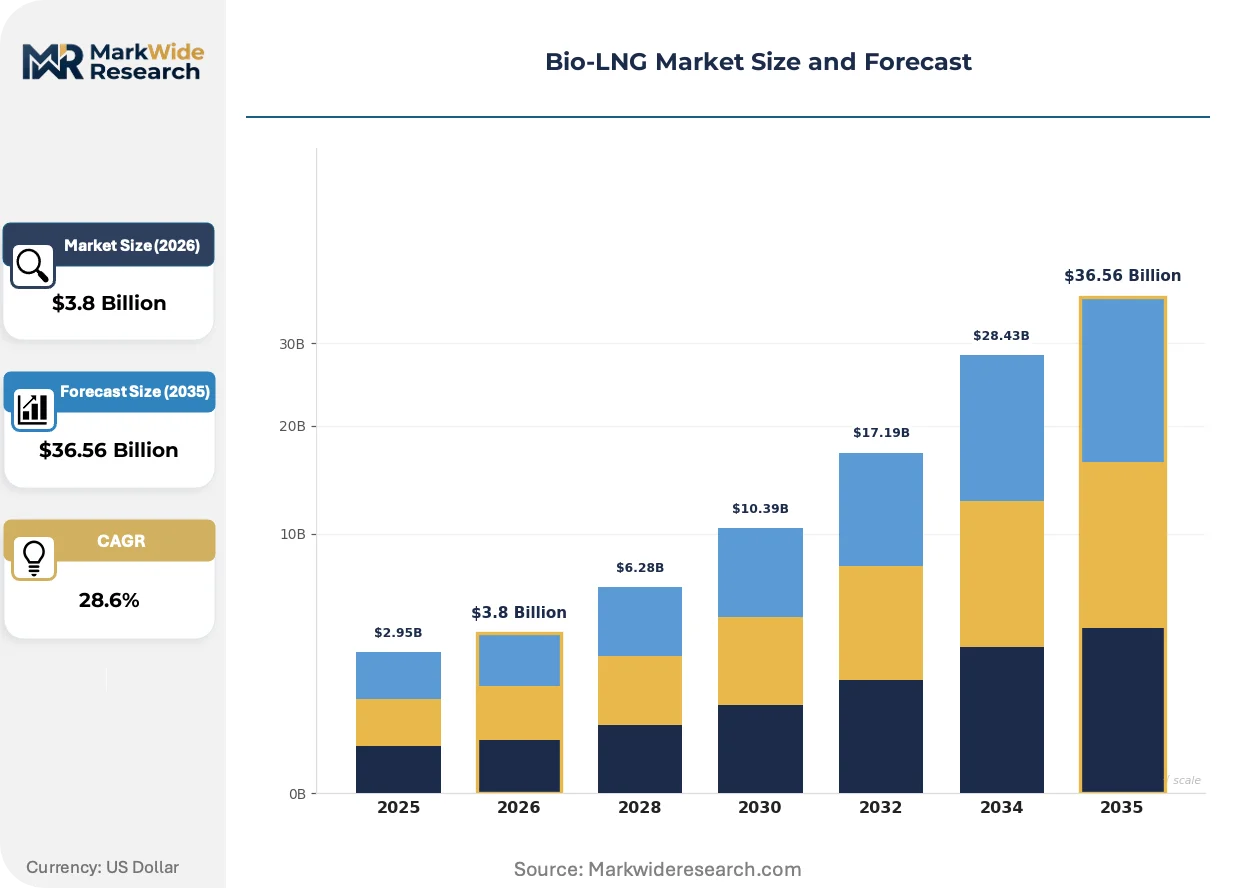
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquefied Biomethane, Renewable Natural Gas, Biofuel, Others Application: Transportation, Power Generation, Industrial Heating, Residential Heating Delivery Mode: Virtual Pipeline, Truck Transport, Direct Supply, Grid Injection End User: Utilities, Transportation Sector, Industrial Clients, Commercial Users |
| Companies Covered | Linde plc, BoxLNG Pvt. Ltd., TotalEnergies, Flogas Britain Ltd., Nordsol, Shell Plc, DBG Group B.V., Air Liquide, Titan LNG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-LNG Market Evolving Landscape
Technology developers and fuel suppliers are converging on modular liquefaction architectures and digital certification platforms to compress project timelines and unlock fragmented feedstock access.
Small-scale liquefaction skids rated below 50 tons per day are absorbing distributed biogas volumes from agricultural anaerobic digestion sites that previously lacked viable offtake pathways. Shipping operators with mid-size vessel fleets are adopting these decentralized supply points to reduce bunkering voyage deviations. The technology is absorbing stranded feedstock capacity and compressing the effective radius of economically viable biogas collection.
The EU F-Gas Regulation is tightening restrictions on high-global-warming-potential refrigerants used in conventional LNG liquefaction, accelerating adoption of mixed-refrigerant and nitrogen-expansion process alternatives. Equipment suppliers serving the biomethane sector must now certify systems for lower-carbon cooling cycles. Northern European liquefaction projects are responding by specifying hydrocarbon or nitrogen-based refrigeration trains to secure environmental product declarations.
Ship charterers are consolidating fuel procurement through marine fuel trading houses rather than contracting directly with bio-LNG producers, concentrating price-setting power among intermediaries. This intermediation shift compresses producer margins while transferring certification liability to traders with stronger balance sheets. The pattern is most pronounced in Rotterdam and Singapore, where bunker trading desks now intermediate the majority of bio-LNG stem deliveries.
Bio-LNG Market Segmentation
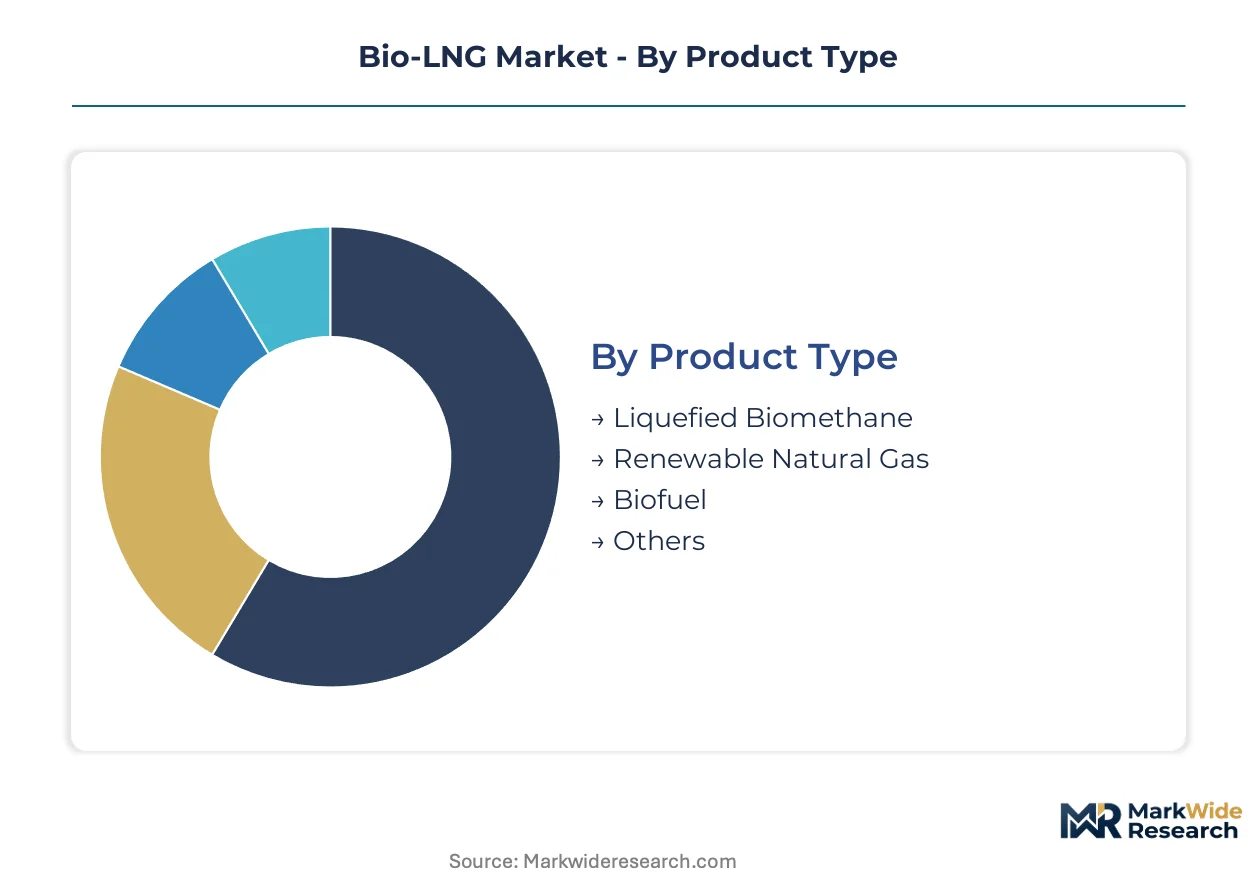
Segmentation in bio-LNG markets reveals how certification requirements, infrastructure access, and customer scale reshape competitive positioning across product grades and delivery modes. Understanding these divides enables suppliers to match production assets with premium-priced demand pools.
Product Type:
Liquefied Biomethane carries the heaviest certification burden under EU Renewable Energy Directive II, requiring mass-balance tracking and guarantee-of-origin documentation for marine fuel eligibility. Renewable Natural Gas faces lighter documentation loads when sold into vehicle fuel markets with simpler pathway approvals.
- Liquefied Biomethane:Cryogenically cooled to minus 162 degrees Celsius with six-hundred-fold volume compression for maritime bunkering. Northern European shipping corridors concentrate demand as IMO carbon intensity indicators tighten vessel compliance deadlines.
- Renewable Natural Gas:Pipeline-grade biomethane meeting gas quality specifications for direct grid injection or vehicle fueling. California LCFS and EPA renewable fuel standard pathways unlock compliance credit premiums in North American transport fleets.
- Biofuel:Broader category encompassing upgraded biogas for non-cryogenic applications. Industrial heat users in food processing and ceramics sectors source this grade where LNG terminal access remains unavailable.
- Others:Emerging product grades including bio-LNG blends with synthetic methane and hydrogen-carrier derivatives. Pilot projects in the Netherlands test these formulations for net-zero shipping corridors.
Liquefied Biomethane sits at the top of the volume ranking, with Renewable Natural Gas climbing the fastest as vehicle fuel infrastructure scales.
Application:
Cost tier differentiation separates high-margin industrial contracts from commoditized transport volumes, with power generation occupying a mid-tier position dependent on carbon pricing exposure.
- Transportation:Maritime shipping and heavy road haulage absorb the largest absolute volumes. EU Alternative Fuels Infrastructure Regulation mandates refueling station density along core corridors, concentrating demand in Germany, France, and the Netherlands.
- Industrial Heating:Ceramics, cement, and food processing facilities pay premium pricing for long-term offtake certainty. These contracts typically span 10-15 years with fixed escalation clauses, capturing higher margins than spot maritime sales.
- Power Generation:Grid-balancing peaker plants and combined-cycle facilities burn bio-LNG during renewable generation shortfalls. Dispatch economics depend on carbon price levels and coal-to-gas switching thresholds.
- Residential Heating:Distributed demand through virtual pipeline deliveries to communities lacking pipeline access. Polish and Baltic markets show emerging interest as district heating systems decarbonize.
Transportation commands the largest revenue pool, with Industrial Heating expanding most quickly as manufacturing decarbonization deadlines approach.
Delivery Mode:
Customer type and infrastructure maturity determine delivery selection, with large industrial offtakers preferring direct supply while fragmented residential demand relies on virtual pipeline flexibility.
- Virtual Pipeline:Containerized ISO tank systems enable bio-LNG distribution to stranded demand centers. Spain and Portugal lack fixed LNG terminal density, making this mode essential for industrial heat users in those markets.
- Truck Transport:Cryogenic tanker deliveries from liquefaction plants to bunkering terminals and industrial sites. Rotterdam and Singapore host the densest trucking networks with dedicated loading bays and driver certification programs.
- Direct Supply:Pipeline-connected delivery from production facility to adjacent industrial customer. Captive supply arrangements dominate in Belgian and Dutch chemical clusters where plants co-locate with anaerobic digestion complexes.
- Grid Injection:Biomethane injection into national gas networks with physical or virtual tracking to offtake points. Denmark and Sweden favor this pathway where pipeline infrastructure offers higher netbacks than liquefaction economics.
Truck Transport handles the greatest volume throughput, with Virtual Pipeline gaining share fastest in infrastructure-deficient Southern European markets.
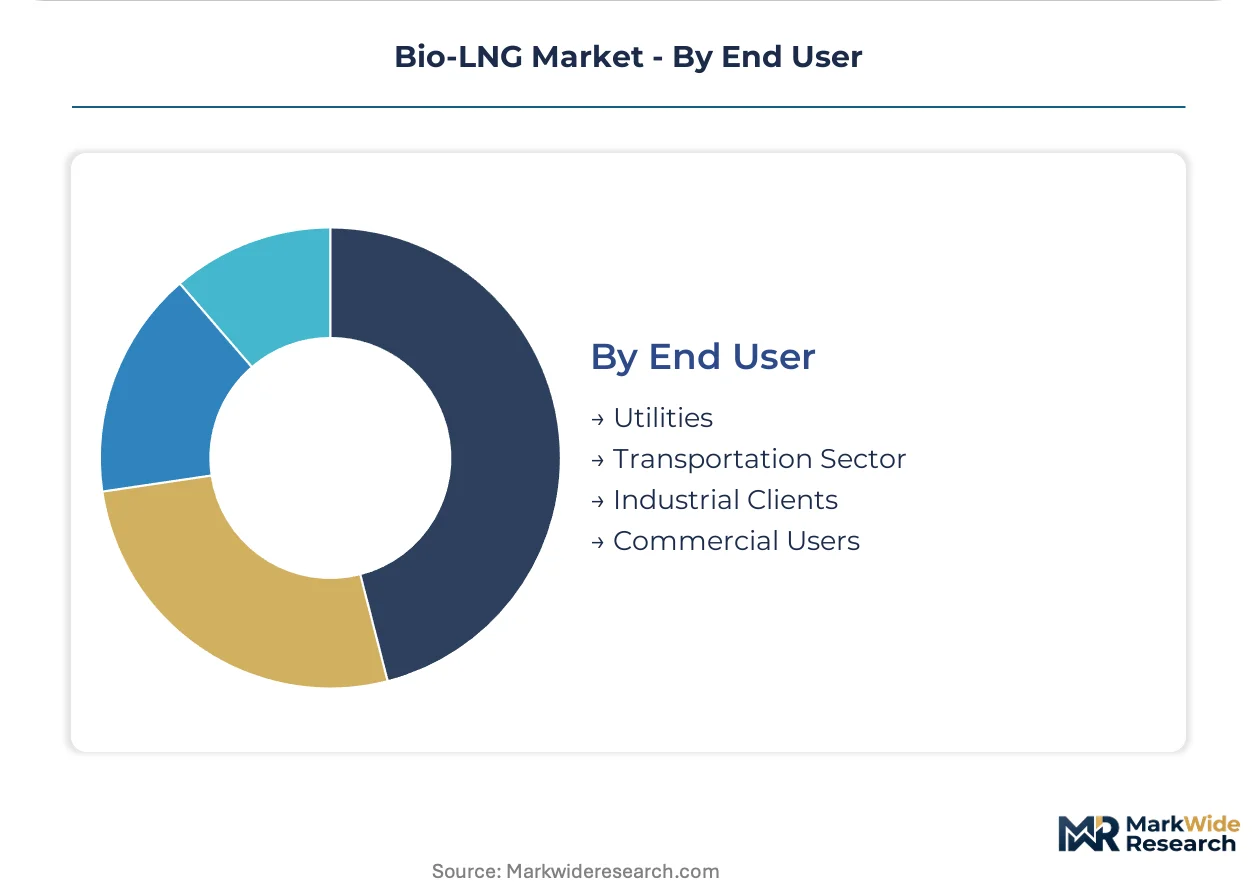
End User:
Margin concentration varies sharply by customer scale and contract duration, with utilities leveraging purchasing power while commercial users accept pricing premiums for supply security.
- Transportation Sector:Shipowners and fleet operators lock in multi-year bunkering contracts to secure IMO compliance. Marine fuel trading houses now intermediate the majority of these transactions, compressing direct producer margins.
- Industrial Clients:Cement, steel, and chemicals producers source bio-LNG for process heat and feedstock applications. These customers prioritize supply continuity over spot pricing, accepting 15-20% premiums for firm delivery commitments.
- Utilities:Gas distribution companies blend bio-LNG into supply portfolios to meet renewable gas mandates. Their scale enables aggressive price negotiation and long-term offtake tender processes.
- Commercial Users:Hotels, hospitals, and retail chains with distributed heating needs. This segment shows highest price elasticity and shortest contract durations, typically 1-3 years with spot market exposure.
Transportation Sector anchors absolute demand, with Industrial Clients showing the steepest expansion trajectory as manufacturing decarbonization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands denser liquefaction infrastructure than France, yet Dutch port clusters now outpace both in bio-LNG bunkering contract velocity. The EU Green Deal and Fit for 55 package have triggered divergent national responses, with maritime corridors reshaping investment flows.
Germany
Agricultural anaerobic digestion facilities in Lower Saxony and Bavaria supply feedstock to upgrading trains, though grid injection parity often outcompetes liquefaction economics. The Federal Network Agency regulates biogas grid access tariffs that influence producer netback calculations. Hamburg and Bremen port authorities are retrofitting bunkering infrastructure to handle cryogenic marine fuel deliveries.
Netherlands
Rotterdam's trading desks intermediate the majority of European bio-LNG stem deliveries, concentrating price-setting power among marine fuel houses. The National Climate Agreement mandates renewable gas quotas that accelerate liquefaction project approvals. Groningen and Zeeland host small-scale liquefaction skids converting distributed agricultural biogas into transportable marine fuel.
Belgium
Chemical clusters in Antwerp co-locate with anaerobic digestion complexes, enabling direct supply arrangements that bypass trucking logistics. The federal energy strategy prioritizes biomethane for hard-to-abate industrial heat applications. Flanders maintains the densest concentration of gas upgrading and liquefaction integrated facilities.
France
TotalEnergies anchors integrated biogas sourcing across northern agricultural regions, linking anaerobic digestion to captive liquefaction assets. The Multi-Annual Energy Programming framework sets binding renewable gas targets through 2028. Dunkirk and Le Havre are developing bio-LNG bunkering capacity to capture trans-Atlantic vessel traffic.
United Kingdom
Flogas Britain operates within a market where biomethane certificate trading remains fragmented across national registries. The UK Emissions Trading Scheme and renewable transport fuel obligation create overlapping compliance incentives. Thames estuary ports are evaluating liquefaction investments to serve North Sea shipping routes.
Bio-LNG Market Competitive Landscape
North European producers anchor one tier; Asian trading specialists hold procurement intermediation advantages. The vendor base stratifies between integrated energy majors with captive biogas assets and independent liquefaction technology providers. Three archetypes dominate: upstream-integrated majors controlling feedstock-to-bunker chains, modular technology licensors enabling distributed production, and marine fuel traders consolidating price discovery. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with project developers securing long-term offtake before committing liquefaction trains.
Among upstream-integrated majors, TotalEnergies and Shell Plc represent the scale-driven archetype through biogas sourcing and liquefaction asset control. Nordsol exemplifies the modular technology tier, occupying a position as a small-scale liquefaction specialist enabling distributed agricultural site conversion. These three entities span the competitive spectrum from feedstock capture through marine fuel delivery.
| Leading Market Players |
|---|
| Linde plc |
| BoxLNG Pvt. Ltd. |
| TotalEnergies |
| Flogas Britain Ltd. |
| Nordsol |
| Shell Plc |
| DBG Group B.V. |
| Air Liquide |
| Titan LNG |
| Others |
Value Network & Pricing Analysis
Marine fuel trading house consolidation in Rotterdam and Singapore is forcing liquefaction producers to accept compressed direct-sale margins and transfer certification liability to intermediary balance sheets. This procurement shift concentrates price-setting power among bunker desks while eroding producer netbacks and reshaping supply chain investment priorities toward trader-aligned volume commitments.
Pricing Analysis
Direct-to-trader discounts dominate bio-LNG price formation as ship charterers consolidate procurement through marine fuel houses rather than contracting producers directly. Three-tier pricing structure across IMO-certified premium, standard biomethane, and economy-grade industrial heat separates maritime bunkers from grid-injection alternatives. Cost compression in the standard tier is intensifying because cryogenic energy consumption erodes plant economics during electricity price spikes. Commercial users with distributed heating needs exhibit highest price sensitivity, while industrial cement and ceramics producers accept 15-20% premiums for firm 10-15 year delivery commitments.
Supply Chain Analysis
Hub-and-spoke distribution patterns radiate from Rotterdam's trading desks to bunkering terminals across Northern European shipping corridors. Supply concentrates in Germany, the Netherlands, and Belgium where anaerobic digestion complexes co-locate with liquefaction trains and chemical clusters. Feedstock supply draws from agricultural waste streams, organic municipal waste, and dedicated energy crops, though diversion pressure from composting markets constrains utilization rates. Single-source vulnerability runs through the cryogenic technician shortage that constrains plant uptime and safety compliance. Distribution runs through truck transport networks with dedicated loading bays and driver certification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in bio-LNG hinges on modular liquefaction scale-down that slashes unit capital costs and opens stranded agricultural feedstock pools previously uneconomic to collect.
For Market Incumbents: Deepen captive biogas sourcing through long-term offtake contracts with anaerobic digestion clusters in Lower Saxony and Bavaria before trader intermediation consolidates further. Add small-scale liquefaction capacity at distributed agricultural sites to absorb stranded feedstock and reduce bunkering voyage deviations for mid-size vessel fleets. Defend against Nordsol-style modular technology disruptors by locking exclusive site access agreements with farm cooperatives. For New Entrants and Emerging Players: Capture Polish and Baltic port clusters where underdeveloped bio-LNG bunkering infrastructure at Gdansk and Klaipeda creates first-mover advantages for liquefaction project developers. Target virtual pipeline delivery systems for industrial heat users in Spain and Portugal lacking fixed LNG terminal density. Enter through ISO tank containerized logistics partnerships with established cryogenic transport operators rather than greenfield terminal investments. For Investors and Strategic Acquirers: Asymmetric upside sits with modular liquefaction technology licensors enabling distributed agricultural site conversion without billion-dollar centralized plant commitments. Five-to-ten year viability favors technology providers with nitrogen-expansion process patents that satisfy tightening EU F-Gas Regulation refrigerant restrictions. Watch for guarantee-of-origin registry harmonization between national biogas databases as the signal that cross-border premium pricing capture has become structurally viable.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Liquefaction Scale-Up | Small-scale skids below 50 tons per day unlock stranded agricultural biogas volumes across distributed sites. |
| Backward Integration into Biogas Sourcing | Captive anaerobic digestion offtake secures feedstock supply before trader intermediation compresses margins further. |
| Virtual Pipeline Network Buildout | Containerized ISO tank systems penetrate infrastructure-deficient Southern European industrial heat markets. |
| EU RED II Certification Investment | Mass-balance tracking and guarantee-of-origin documentation secure marine fuel eligibility premiums. |
| Nitrogen-Expansion Process Adoption | Hydrocarbon or nitrogen-based refrigeration trains satisfy EU F-Gas Regulation while securing environmental product declarations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with liquefaction plant operators, marine fuel trading desk managers, anaerobic digestion facility owners, and shipowner procurement officers with secondary validation. Bottom-up capacity and production data triangulated against top-down regulatory mandate tracking across EU member state implementation of Renewable Energy Directive II and Fit for 55 package measures. Secondary sources included EU biomethane registry databases, IMO carbon intensity indicator filings, national biogas association production statistics, and customs trade data for cryogenic equipment imports.
Historical reference periods anchored the projection horizon to observed capacity commissioning timelines and regulatory compliance deadline clustering around IMO vessel efficiency rating schemes. Segmentation dimensions spanned product type, application, delivery mode, and end user, with additional modeling of certification tier and feedstock origin. CAGRs derived from bottom-up project pipeline aggregation weighted by probability-adjusted commissioning dates, cross-referenced against top-down renewable fuel quota mandate trajectories. Forecast inputs incorporated electricity price volatility impacts on liquefaction energy costs and cross-border guarantee-of-origin transferability development.
Underlying measurement precision varies by segment; liquefied biomethane maritime volumes carry tighter precision than virtual pipeline residential heating estimates due to bunkering terminal reporting requirements. Forecasts reflect documented assumptions regarding regulatory quota enforcement intensity and feedstock diversion competition resolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Jatropha Biodiesel Market
Alternative Fuels
Corn-Based Renewable Fuel Market
Alternative Fuels
Sustainable Fuel Market
Alternative Fuels
Lignocellulosic Feedstock-Based Biofuel Market
Alternative Fuels
E-Fuel Market
Alternative Fuels
United States Propane Market
Alternative Fuels
Renewable Aviation Fuel Market
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
Global Cellulosic Ethanol Market
Alternative Fuels
Alternate Marine Power Market
Alternative Fuels
Global Carbon-Neutral Fuels Market
Alternative Fuels
Hydrotreated Vegetable Oil Market
Alternative Fuels
Sustainable Marine Fuel Market
Alternative Fuels
Hydrogen Furnace Market
Alternative Fuels
Global Renewable Fuel Market
Alternative Fuels
Sustainable Aviation Fuel Market