
 Green Diesel Market | 2026-2036
Green Diesel Market Size, Share, and Industry Trends Forecast 2026-2036
Green Diesel Market Analysis
Specialized hydrotreating engineering talent is collapsing across North American and European refineries as legacy petroleum operators race to reconfigure units for renewable feedstocks. Neste Oyj anchors its competitive edge through proprietary NEXBTL technology and dedicated renewable product platforms at its Singapore and Rotterdam facilities. Valero Energy Corporation leverages its Diamond Green Diesel joint venture with Darling Ingredients to sustain the largest operational renewable diesel capacity in the United States. Chevron Corporation competes through controlled integration of renewable feedstock supply chains into its existing refining and distribution infrastructure.
Green diesel denotes a hydrocarbon fuel chemically identical to petroleum diesel, produced through hydroprocessing of triglyceride feedstocks at hydrogen pressures exceeding 30 bar and temperatures near 350°C, yielding cetane numbers above 70 for direct use in compression-ignition engines without blending limits. Vegetable oils currently dominate feedstock consumption due to established supply chains and consistent fatty acid profiles, though waste cooking oils represent the fastest-growing input category as collectors scale used oil aggregation networks. Hydroprocessing leads production technology deployment because refiners can retrofit existing hydrotreaters, while pyrolysis remains nascent with limited commercial units operational.
The US Environmental Protection Agency's Renewable Fuel Standard and California Air Resources Board's Low Carbon Fuel Standard collectively shape demand through credit mechanisms that monetize carbon intensity reductions. The EU Green Deal's Fit for 55 package and Renewable Energy Directive III mandate escalating sustainable fuel shares in transportation energy, forcing importers to certify feedstock sustainability through recognized voluntary schemes. Stakeholders must monitor feedstock cost volatility and policy credit price trajectories to time capacity commitments and offtake contracting strategies.
Market Dynamics
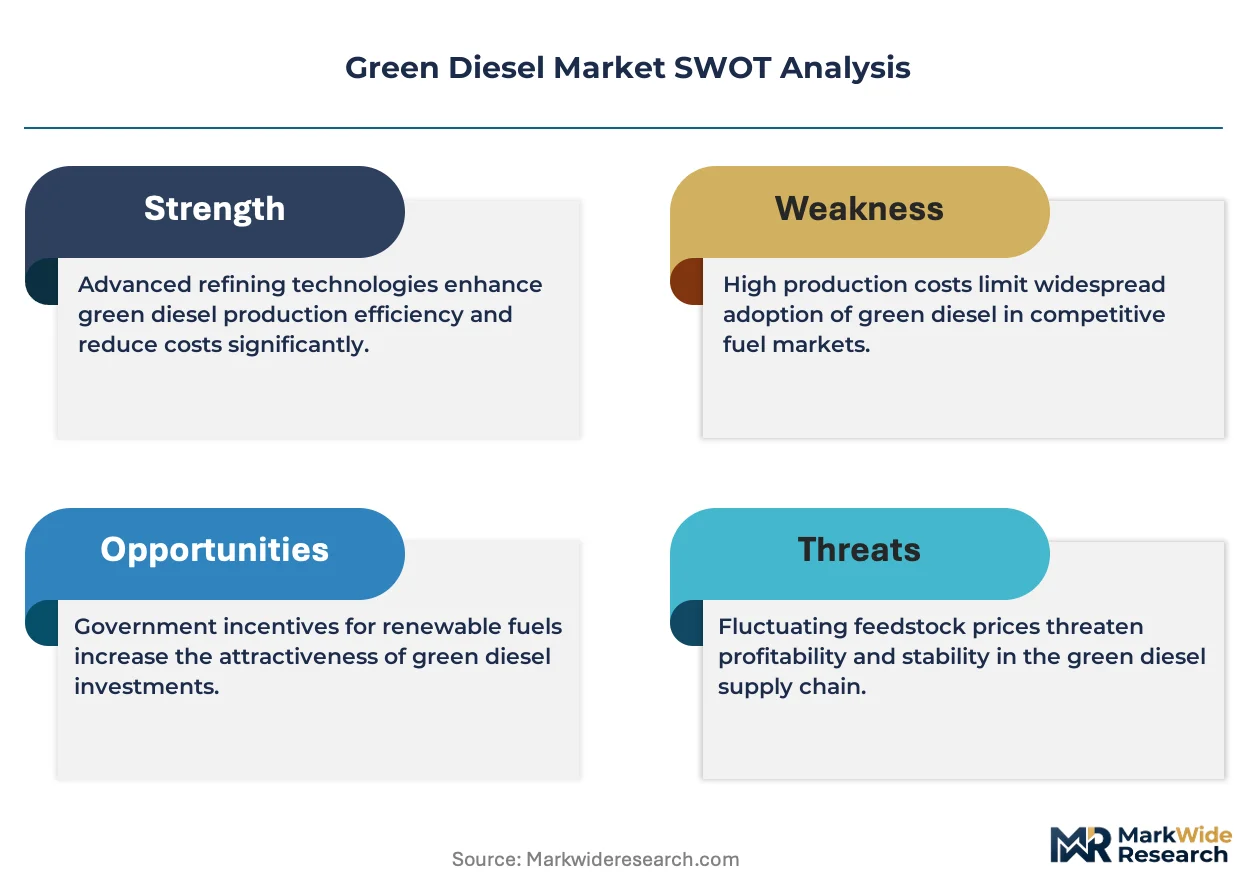
Hydrotreater retrofitting is compressing capital deployment timelines as petroleum refiners repurpose stranded assets for renewable feedstock processing. This capital recycling dynamic is redrawing competitive barriers between legacy fuel producers and pure-play renewable operators.
Growth Catalysts
- California LCFS Credit Markets:Carbon intensity-based credit trading generates direct revenue streams for producers achieving sub-fossil carbon scores, pulling capacity investments toward the US West Coast.
- EU Renewable Energy Directive III:Escalating blending mandates across member states force fuel importers to certify sustainability through recognized voluntary schemes, creating guaranteed offtake volume.
- Aviation Fuel Pathways:Commercial airlines are accelerating offtake agreements for sustainable aviation fuel derived from green diesel hydroprocessing routes.
Market Restraints
- Feedstock Cost Volatility:Used cooking oil and tallow prices swing with restaurant sector output and rendering capacity, compressing producer margins without long-term supply contracts.
- Hydrogen Supply Concentration:Steam methane reforming still dominates merchant hydrogen production, exposing renewable diesel operators to gray hydrogen carbon intensity and price spikes.
- Catalyst Deactivation Rates:Triglyceride feedstocks poison hydrotreater catalysts faster than petroleum residuum, accelerating turnaround cycles and opex inflation.
Strategic Opportunities
- Underpenetrated Maritime Bunkering:Singapore and Rotterdam port authorities are drafting green diesel inclusion rules for ocean-going vessel fuel blends.
- Pyrolysis-Hydroprocessing Convergence:Emerging thermochemical pathways upgrade lignocellulosic biomass into refinery-compatible intermediates, expanding beyond edible oil constraints.
- India BIS Standards Evolution:Draft renewable diesel specifications under Bureau of Indian Standards review signal import substitution potential for domestic agriculture residue valorization.
Industry Challenges
- Hydrotreating Engineering Talent Scarcity:Specialized process design expertise for high-pressure triglyceride processing is collapsing across North American and European refineries as workforce ages out.
- ISCC Certification Timelines:Multi-month audit queues for International Sustainability and Carbon Certification create feedstock procurement bottlenecks for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Diesel Market |
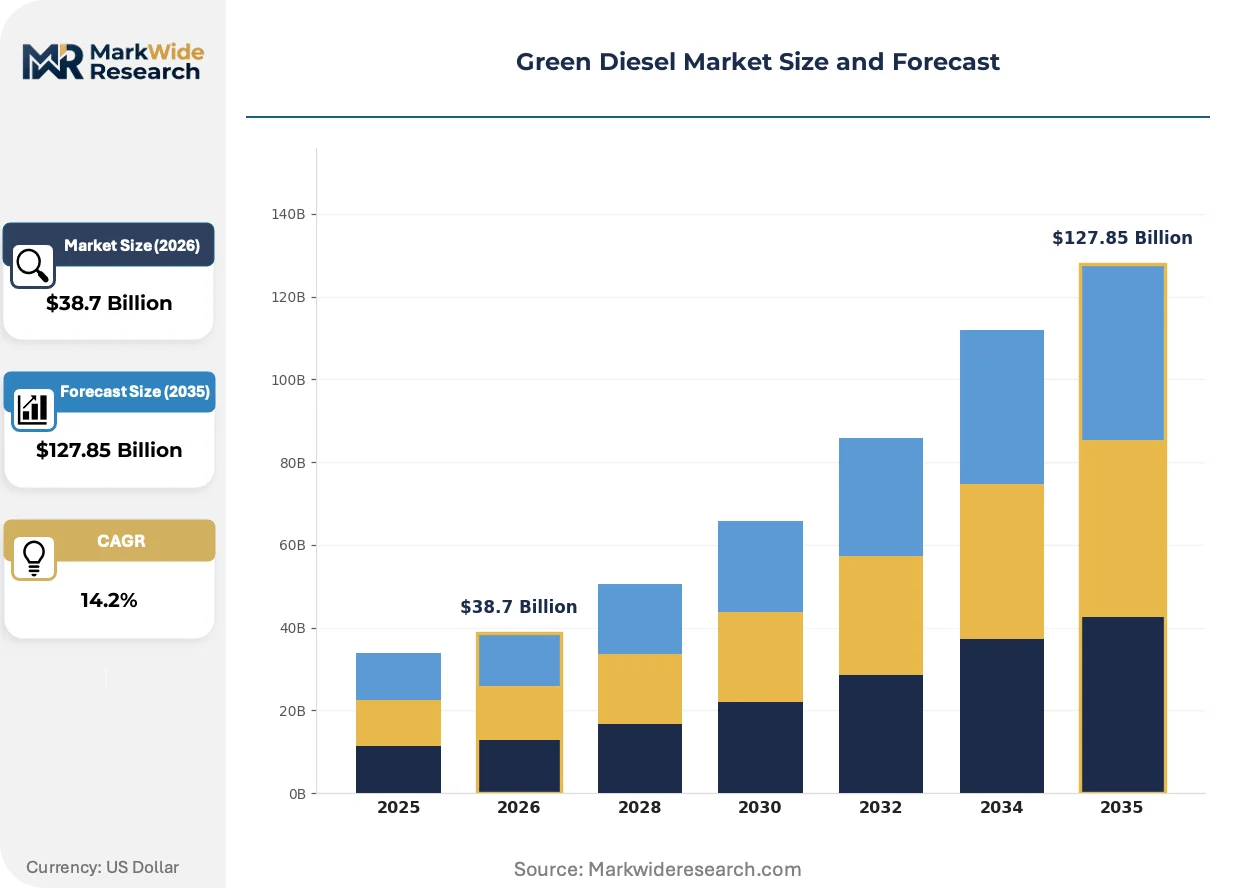
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Vegetable Oils, Animal Fats, Waste Cooking Oils, Algae Production Technology: Hydroprocessing, Transesterification, Fermentation, Pyrolysis Application: Transportation, Heating, Power Generation, Industrial Distribution Channel: Direct Sales, Distributors, Retail, Wholesalers |
| Companies Covered | Neste Oyj, Chevron Corporation, Valero Energy Corporation, Phillips 66, Marathon Petroleum Corporation, Shell Plc, Gevo, Inc., Aemetis, Inc., Global Clean Energy Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Diesel Market Emerging Trajectories
Modular reactor configurations and distributed feedstock aggregation are compressing the scale economics that once favored centralized petroleum refining. These shifts enable smaller producers to access credit markets previously captured by integrated majors.
Electrolytic hydrogen integration is miniaturizing the carbon footprint of hydrotreating operations. Renewable diesel producers in Denmark and the Netherlands are piloting 10-20 MW electrolyzer arrays co-located at refineries. These installations enable point-source green hydrogen production, eliminating transport emissions and merchant supply dependence. The technology is compressing lifecycle carbon intensity scores toward sub-20 gCO2e/MJ thresholds required for premium LCFS credit tiers.
The EU Green Deal's Fit for 55 package is tightening embodied carbon accounting for imported fuels. The Carbon Border Adjustment Mechanism will phase in scope 3 emissions reporting for maritime and road transport fuels entering European ports. US Gulf Coast exporters are responding by certifying supply chain emissions through mass-balance bookkeeping recognized under Renewable Energy Directive implementing acts.
Airline procurement departments are unbundling fuel purchasing from traditional petroleum supply agreements. Carriers in Germany and the United Kingdom are signing direct offtake contracts with renewable diesel producers for book-and-claim SAF certificate transfers. This disintermediation severs the historical link between jet fuel physical delivery and sustainability attribute ownership, concentrating contract negotiation power with sustainability officers rather than traditional fuel buyers.
Green Diesel Market Segmentation
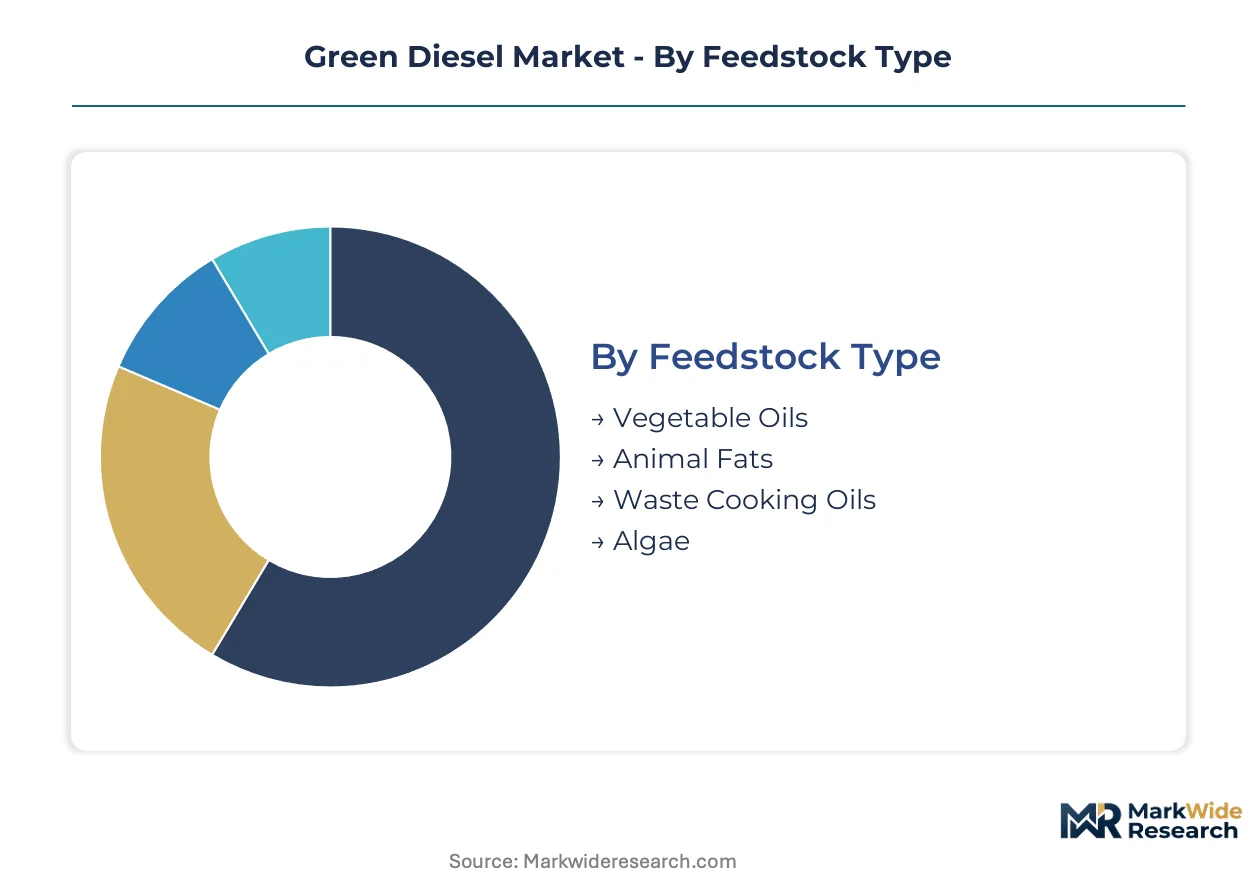
Feedstock chemistry and production technology choices determine carbon intensity scores that directly translate into credit values under California's LCFS and the EU's Renewable Energy Directive. Segmentation strategy shapes capital allocation between retrofitting existing refineries and building dedicated renewable facilities.
Feedstock Type:
Domestic supply chains dominate vegetable oil procurement, while waste cooking oil flows concentrate in export corridors to Singapore and Rotterdam renewable diesel hubs.
- Vegetable Oils:Soybean and rapeseed oils deliver consistent fatty acid profiles with established agricultural procurement networks. US Midwest crush facilities and EU oilseed processors anchor supply; sustainability certification through ISCC or RSB determines EU market access under Renewable Energy Directive III sustainability criteria.
- Animal Fats:Tallow and poultry fat offer lower carbon intensity scores than virgin vegetable oils due to waste classification. Rendering capacity in the US Plains and Brazilian beef processing clusters feed hydrotreater demand; Darling Ingredients and similar aggregators control prime collection infrastructure.
- Waste Cooking Oils:Restaurant sector aggregation networks in California and EU urban centers supply the fastest-expanding feedstock category. Used cooking oil collectors face ISCC certification bottlenecks that constrain new market entry.
- Algae:Photosynthetic lipid production remains pre-commercial with cultivation cost barriers exceeding petroleum diesel price parity thresholds.
Vegetable oils hold the largest share; momentum sits with waste cooking oils as collectors scale aggregation infrastructure.
Production Technology:
Capital intensity separates retrofit pathways from greenfield builds, with hydrotreater revamps commanding 40-60% lower unit costs than standalone renewable facilities.
- Hydroprocessing:Catalytic hydrogenation of triglycerides at 30+ bar pressure yields drop-in hydrocarbons with cetane numbers exceeding 70. Existing petroleum refineries in Louisiana, Texas, and California dominate deployment through unit retrofits; catalyst deactivation from phosphorus and alkali metals accelerates turnaround cycles.
- Transesterification:Alkali-catalyzed ester interchange produces fatty acid methyl esters with cold-flow limitations requiring blending. Smaller biodiesel producers in the US Southeast and EU peripheral markets retain this technology for regional supply.
- Fermentation:Microbial lipid accumulation from sugar feedstocks offers pathway diversification beyond triglyceride constraints. LanzaTech and similar developers pilot gas-to-liquid routes using steel mill off-gas in Belgium and China.
- Pyrolysis:Thermochemical depolymerization of lignocellulosic biomass produces oxygenated intermediates requiring secondary upgrading. Commercial units remain limited to demonstration scale in Finland and the Netherlands.
Hydroprocessing captures dominant capacity share; pyrolysis presents the steepest expansion trajectory if lignocellulosic upgrading achieves cost parity.
Application:
Carbon credit arbitrage drives geographic demand concentration, with California and EU markets offering premium pricing for certified low-carbon intensity supply.
- Transportation:Compression-ignition engines in heavy-duty trucking and rail consume the primary volume. California's LCFS credit trading pulls renewable diesel toward West Coast distribution terminals; EU member state blending mandates under Renewable Energy Directive III guarantee offtake floors.
- Heating:Residential and commercial boiler fuel oil substitution advances in Germany, Sweden, and US Northeast states with heating oil infrastructure. Seasonal demand peaks create storage arbitrage opportunities at Rotterdam and New York Harbor.
- Power Generation:Diesel generator sets in remote mining and island grids represent niche demand with limited scale.
- Industrial:Process heat and combined heat-and-power applications in food processing and manufacturing consume minor volumes.
Transportation commands absolute volume leadership; heating applications gain share fastest where district energy systems retrofit for renewable liquid fuels.
Distribution Channel:
Channel structure reflects buyer scale and credit verification requirements, with large offtakers demanding direct producer relationships for mass-balance certification.
- Direct Sales:Major airlines and integrated oil companies negotiate book-and-claim certificate transfers bypassing traditional petroleum intermediaries. Lufthansa, British Airways, and Delta Air Lines sign direct contracts with Neste and Diamond Green Diesel for SAF attribute procurement.
- Distributors:Regional fuel marketers aggregate renewable diesel volumes for fleet card programs and retail deployment. Mansfield Energy and similar intermediaries handle logistics for California LCFS compliance buyers.
- Retail:Branded fuel stations in California and Oregon offer renewable diesel at dedicated pumps with price premiums over petroleum diesel.
- Wholesalers:Terminal operators at Houston, Los Angeles, and Amsterdam-Rotterdam-Antwerp hubs blend renewable diesel into pipeline-specification products.
Direct sales capture premium pricing tiers; distributor networks expand fastest to serve mid-size fleet operators lacking procurement scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's LCFS credit markets command premium pricing power over Rotterdam's renewable diesel terminals, creating a trans-Atlantic arbitrage that pulls capacity investments toward the US West Coast. This pricing asymmetry reshapes where producers commit capital for hydrotreater retrofits versus greenfield builds.
United States
California's Low Carbon Fuel Standard generates direct revenue streams for producers achieving sub-fossil carbon intensity scores, pulling Diamond Green Diesel and Marathon Petroleum toward West Coast distribution terminals. The EPA's Renewable Fuel Standard mandates renewable volume obligations that refiners meet through credit trading. Louisiana and Texas host the densest concentration of petroleum refinery conversions, with Gulf Coast hydrogen supply networks supporting hydrotreater operations.
Germany
Lufthansa and other carriers are signing direct offtake contracts for sustainable aviation fuel derived from green diesel hydroprocessing routes, bypassing traditional petroleum intermediaries. The EU Green Deal's Fit for 55 package mandates escalating sustainable fuel shares in transportation energy. The Hamburg-Rotterdam corridor anchors North European renewable diesel logistics, with port authorities drafting green diesel inclusion rules for maritime bunkering.
Singapore
Neste Oyj's dedicated renewable product platform at its Singapore facility supplies aviation fuel buyers across Asia-Pacific commercial airlines accelerating SAF procurement. The Maritime and Port Authority of Singapore is developing green diesel blending specifications for ocean-going vessel fuel. The Jurong Island refining cluster concentrates hydroprocessing capacity serving both regional bunkering demand and European export markets.
Netherlands
Rotterdam port authorities are implementing mass-balance bookkeeping systems recognized under Renewable Energy Directive implementing acts for US Gulf Coast exporters. The EU's Carbon Border Adjustment Mechanism will phase in scope 3 emissions reporting for maritime fuels entering European ports. Electrolytic hydrogen integration pilots at Rotterdam-area refineries are compressing lifecycle carbon intensity scores toward premium LCFS credit tiers.
India
Draft renewable diesel specifications under Bureau of Indian Standards review signal import substitution potential for domestic agriculture residue valorization. The country's national biofuel policy is evolving to accommodate hydrotreated vegetable oil pathways beyond traditional biodiesel. Maharashtra and Gujarat oilseed processing clusters are evaluating feedstock aggregation infrastructure for renewable diesel supply chains.
Green Diesel Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the green diesel market. Proprietary hydrotreating process developers command premium positioning through catalyst efficiency and carbon intensity scoring, while petroleum refinery operators leverage stranded asset conversions for capital recycling advantages. Three archetypes dominate: integrated oil majors retrofitting existing units, pure-play renewable operators with dedicated facilities, and agricultural processors backward integrating into fuel production. Competitive moves concentrate on hydrotreater retrofitting timelines and long-term feedstock supply contracting.
Among integrated petroleum operators, Neste Oyj, Valero Energy Corporation, and Chevron Corporation exemplify contrasting strategic positions. Neste Oyj anchors the pure-play renewable operator archetype through its Singapore and Rotterdam facilities. Valero Energy Corporation represents the joint venture model for capacity scaling. Chevron Corporation sits within the controlled integration archetype, embedding renewable feedstock supply chains into existing refining infrastructure.
| Leading Market Players |
|---|
| Neste Oyj |
| Chevron Corporation |
| Valero Energy Corporation |
| Phillips 66 |
| Marathon Petroleum Corporation |
| Shell Plc |
| Gevo, Inc. |
| Aemetis, Inc. |
| Global Clean Energy Holdings, Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day feedstock procurement lead times for waste cooking oil and tallow concentrate pricing power with Darling Ingredients and Neste Oyj, while hydrogen supply bottlenecks at US Gulf Coast refineries compress margins for operators lacking long-term offtake contracts. This inventory-to-pricing linkage forces renewable diesel producers to balance spot market exposure against California LCFS credit arbitrage windows.
Pricing Analysis
Configured-to-order premiums for ISCC-certified sustainable aviation fuel command spreads above standard renewable diesel barge prices at Rotterdam. Contract-based long-term offtake structures dominate, with price differentiation driven by carbon intensity scores and certification tier under EU Renewable Energy Directive III. Pricing pressure stems from used cooking oil cost volatility as restaurant sector output fluctuates. Fleet operators in California exhibit highest price sensitivity; commercial airlines accepting book-and-claim certificate transfers show lowest sensitivity due to emissions compliance mandates.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose Singapore-bound vegetable oil shipments to piracy and weather delays, compressing delivery reliability for Neste's Jurong Island facility. Feedstock supply concentrates in the United States, Brazil, and Indonesia; production draws from soybean crush facilities, palm oil mills, and beef rendering plants. Hydrogen feedstock dependency rests on steam methane reforming capacity concentrated along the US Gulf Coast. Single-source vulnerability characterizes catalyst supply for hydrotreater units. Distribution runs through Rotterdam, Houston, and Los Angeles terminal hubs blending into pipeline specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green diesel capacity expansion is accelerating as a high-growth disruption, with the EU Green Deal's Renewable Energy Directive III mandating binding sustainable fuel shares that guarantee offtake floors regardless of petroleum price cycles.
For Market Incumbents: Compound feedstock security through backward integration into used cooking oil aggregation networks and rendering capacity. Lock in long-term hydrogen supply agreements with electrolyzer developers to decarbonize hydrotreater operations. Defend against pure-play renewable operators by accelerating ISCC certification timelines that create procurement bottlenecks for new entrants.
For New Entrants and Emerging Players: Differentiate on lignocellulosic feedstock pathways through pyrolysis-hydroprocessing convergence, bypassing edible oil competition. Maritime bunkering in Singapore and Rotterdam offers the most penetrable geography as port authorities draft inclusion rules. Target direct sales to airlines seeking book-and-claim SAF certificate transfers, bypassing petroleum intermediary channels entirely.
For Investors and Strategic Acquirers: Long-term, this sits as a policy-anchored infrastructure play because blending mandates under California LCFS and EU Renewable Energy Directive III create demand inelasticity. Acquisition targets should display secured feedstock supply contracts and operational hydrotreater units. Watch hydrogen electrolyzer cost curves as the inflection signal determining which producers achieve sub-20 gCO2e/MJ carbon intensity thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrotreater Retrofit Deployment | Repurposing stranded petroleum assets slashes capital deployment timelines versus greenfield renewable facilities. |
| Long-term Feedstock Supply Agreement | Darling Ingredients and similar aggregators lock in tallow and used cooking oil flows that stabilize producer margins. |
| Electrolytic Hydrogen Integration | Denmark and Netherlands pilots compress lifecycle carbon intensity toward premium LCFS credit tiers. |
| ISCC Certification Program | Multi-month audit queues create procurement bottlenecks that favor incumbents with established sustainability credentials. |
| Direct Airline Offtake Contracting | Lufthansa and Delta bypass petroleum intermediaries to secure book-and-claim SAF attribute ownership. |
Methodological Framework
Cross-validation between hydrotreater engineering specialists and California LCFS credit traders anchors the qualitative findings on retrofit economics and policy arbitrage. Primary interviews with renewable diesel plant managers, Darling Ingredients procurement leads, Neste technology licensing directors, and Lufthansa fuel sustainability officers combined with secondary validation from EPA Renewable Fuel Standard docket filings, California Air Resources Board LCFS credit transaction data, EU Renewable Energy Directive implementing acts, and Singapore Maritime and Port Authority bunkering consultations. Bottom-up capacity buildout tracking and top-down policy mandate analysis triangulate market sizing.
Sensitivity analysis around feedstock cost volatility and hydrogen supply price trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include feedstock chemistry, production technology pathway, application sector, and distribution channel structure. CAGRs derived from policy mandate schedules and announced capacity additions incorporate electrolytic hydrogen cost reduction curves and ISCC certification queue lengths as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained California LCFS credit pricing and EU Renewable Energy Directive III enforcement would require recalibration. Practitioners should keep alternative scenarios live as hydrogen supply decarbonization timelines and maritime bunkering regulation evolution shift competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Biohydrogen Market
Alternative Fuels
Green Ammonia Market
Alternative Fuels
Green Fuels Market
Alternative Fuels
Global Carbon-Neutral Fuels Market
Alternative Fuels
Sustainable Aviation Fuel Market
Alternative Fuels
Renewable Aviation Fuel Market
Alternative Fuels
Aviation Alternative Fuel Market
Alternative Fuels
Hydrogen Furnace Market
Alternative Fuels
Water As a Fuel Market
Alternative Fuels
Synthetic Fuel Market
Alternative Fuels
Sustainable Fuel Market
Alternative Fuels
Bio-Methane Market
Alternative Fuels
Jatropha Biodiesel Market
Alternative Fuels
Global Renewable Fuel Market
Alternative Fuels
Sustainable Marine Fuel Market
Alternative Fuels
Global Cellulosic Ethanol Market