
 Sustainability Management Software Market | 2026-2036
Sustainability Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainability Management Software Market Analysis
Enterprise energy buyers is unwinding the historical dominance of manufacturing-led procurement in sustainability software selection. Sphera leverages deep regulatory content libraries to anchor its position in emissions-intensive process industries. SAP competes through embedded sustainability modules within its ERP ecosystem, extending reach without standalone procurement cycles. Watershed differentiates via real-time supply chain carbon visibility, occupying a narrow but defensible tier in enterprise tech stacks.
Sustainability management software encompasses platforms that measure, track, and report environmental performance indicators across carbon emissions, energy consumption, water usage, and waste streams, typically integrating with ERP systems through API protocols to automate data collection from operational equipment and supplier networks. Cloud-based deployment leads current adoption due to lower implementation friction and automatic regulatory template updates, while carbon accounting solutions capture the fastest growth as Scope 3 disclosure mandates expand from Europe into North American procurement requirements. Compliance management retains mature, stable demand from publicly traded entities with established ESG disclosure obligations.
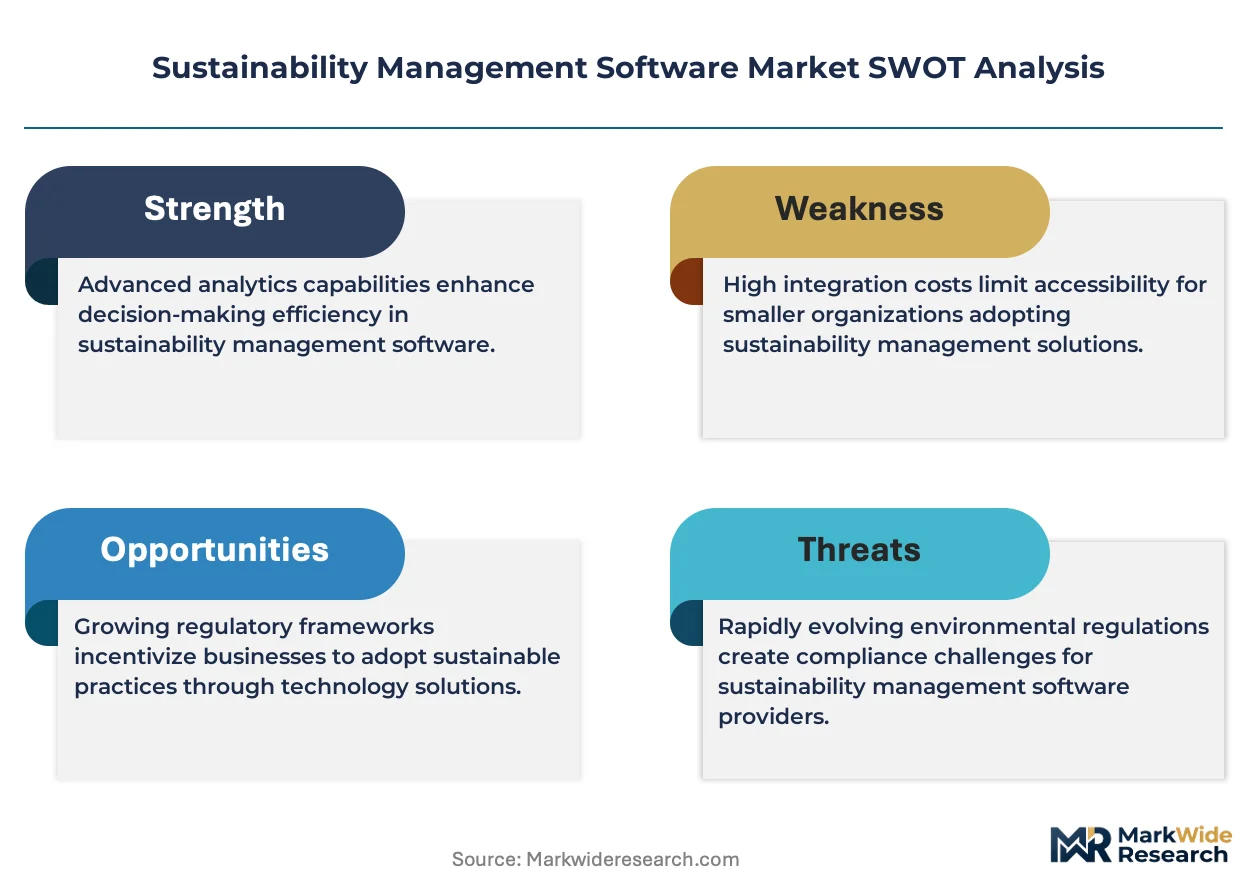
The EU Green Deal and its Corporate Sustainability Reporting Directive enforce granular disclosure standards that directly expand addressable demand for integrated reporting tools. The EPA's evolving greenhouse gas reporting rules in the United States similarly tighten data granularity requirements, forcing facility-level software upgrades. Stakeholders must monitor how API integration capabilities become the decisive procurement criterion as buyers demand seamless connectivity between sustainability platforms and existing financial systems.
Market Dynamics
Enterprise procurement teams now drive sustainability software selection ahead of traditional IT departments, compressing sales cycles and elevating API integration capabilities above feature breadth in vendor evaluations. Energy sector buyers demand real-time carbon visibility that manufacturing-led procurement historically deferred.
Growth Catalysts
- CSRD Mandates:The EU Corporate Sustainability Reporting Directive forces granular Scope 3 disclosure across European supply chains, expanding demand for integrated carbon accounting platforms that automate supplier data collection.
- Automotive Electrification:Battery supply chain traceability requirements from OEMs cascade software procurement through tiered supplier networks, embedding sustainability tools into procurement specifications.
- Cloud Migration:SaaS deployment models eliminate on-premise infrastructure barriers, accelerating adoption among mid-market manufacturers previously priced out of enterprise carbon management systems.
Market Restraints
- Data Fragmentation:Legacy ERP systems in heavy industry lack standardized emissions data fields, forcing costly middleware development before platform deployment.
- Supplier Concentration:Critical API infrastructure for utility data feeds concentrates among three North American meter data management providers, creating single-point-of-failure exposure.
- Skill Scarcity:Carbon accounting methodology expertise pools narrowly in consulting firms, constraining implementation bandwidth and elongating deployment timelines.
Strategic Opportunities
- India Industrial Corridor:PLI scheme incentives for green manufacturing create first-mover advantage for localized sustainability platforms serving textile and pharmaceutical exporters.
- Embedded Finance Convergence:Integration of carbon pricing data into trade finance workflows opens new revenue streams for platforms serving commodity trading desks.
- EPA Rulemaking:Proposed facility-level greenhouse gas reporting expansions in the United States will force software upgrades across petrochemical and power generation assets.
Industry Challenges
- Verification Bottlenecks:Third-party assurance of Scope 3 claims faces accredited auditor capacity constraints, delaying customer compliance timelines and platform value realization.
- Interoperability Debt:Proprietary data formats from incumbent industrial IoT vendors resist standardization, fragmenting platform ecosystems and raising customer switching costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainability Management Software Market |
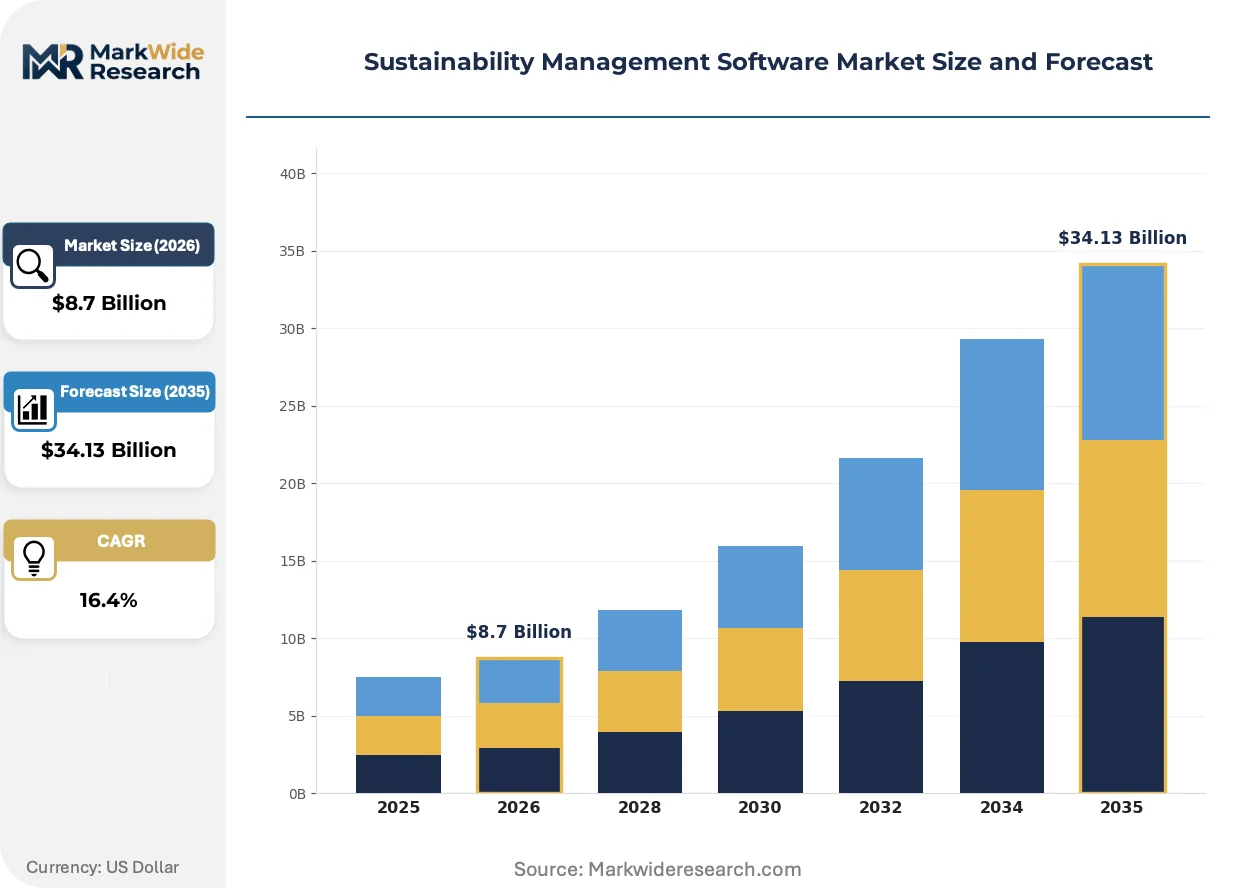
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Manufacturing, Retail, Energy, Healthcare Solution: Carbon Accounting, Compliance Management, Reporting Tools, Risk Assessment Integration Level: API Integration, Custom Integration, Third-Party Connector, Standalone |
| Companies Covered | Greenly, Sphera, Workiva, Osapiens, Watershed, SAP, SustainIQ, Tanso, Persefoni, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainability Management Software Market Emerging Trajectories
Real-time supply chain visibility is displacing static annual reporting as the core value proposition, with machine learning inference replacing spreadsheet-based carbon calculations. Platform architecture is converging around modular API-first design.
Carbon accounting technology is bifurcating between enterprise-grade platforms with embedded regulatory content libraries and lightweight point solutions targeting specific Scope categories. Automotive and electronics manufacturers adopt the former for supplier mandate enforcement, while professional services firms deploy the latter for client advisory engagements. This split is compressing mid-market vendor margins while anchoring premium pricing around compliance automation depth.
The EU AI Act's risk classification framework extends to sustainability software employing algorithmic emissions forecasting, triggering documentation and human oversight requirements for high-risk deployments. Industrial facilities using predictive carbon modeling face expanded audit trails. German chemical conglomerates are responding by segregating AI-enabled scenario analysis from core reporting functions to isolate regulatory exposure.
Chief procurement officers now embed sustainability specifications into RFP scoring matrices ahead of IT evaluation, reversing traditional vendor selection sequencing. Systems integrators and sustainability consultancies capture influence previously held by software resellers. This shift is most pronounced in France and the Netherlands, where CSRD preparatory audits have elevated procurement-sustainability collaboration to board-level reporting.
Sustainability Management Software Market Segmentation
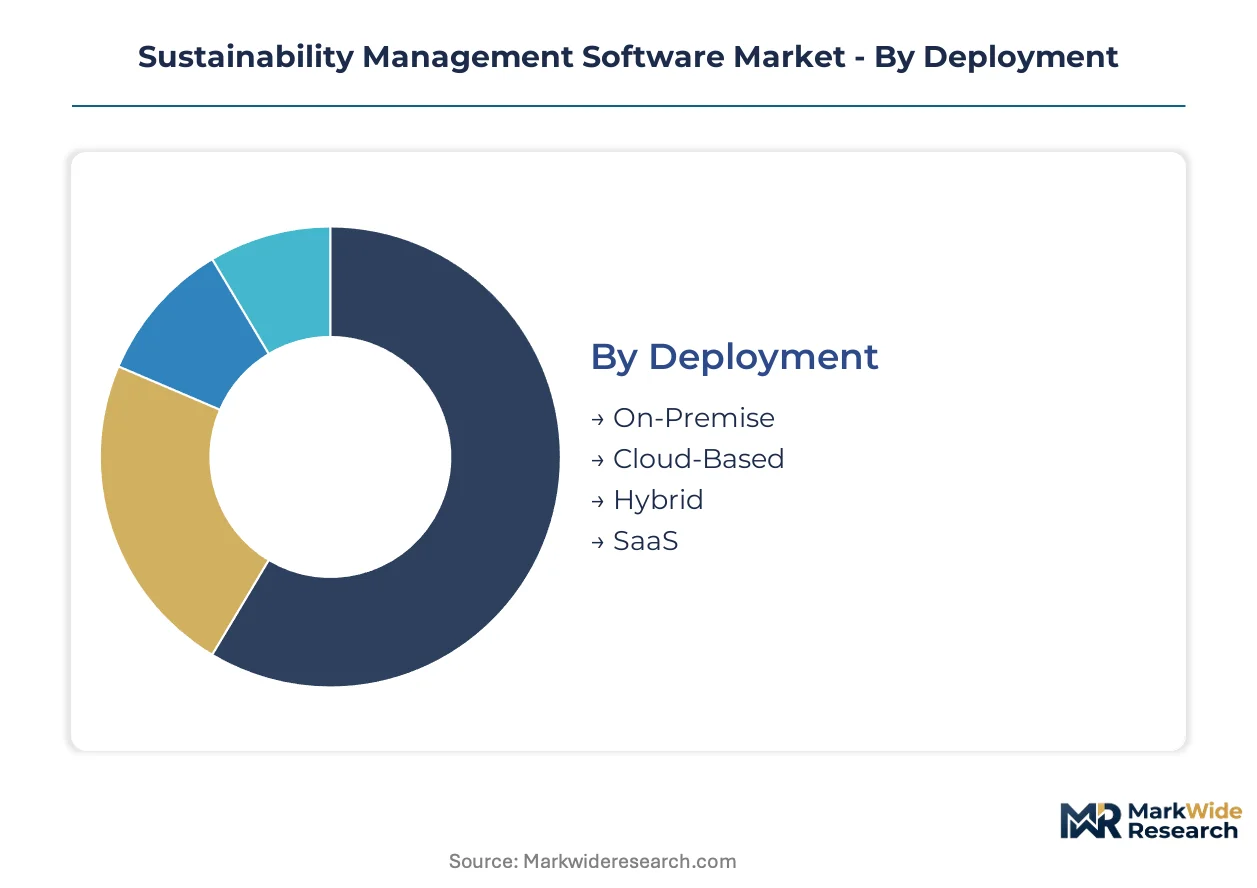
Sustainability management software segments reflect divergent procurement patterns across enterprise maturity levels. Channel strategies vary sharply between cloud-native vendors pursuing mid-market velocity and incumbent platforms defending on-premise installed bases through embedded finance partnerships.
Deployment:
Cloud-based and SaaS offerings flow through direct sales and systems integrator channels, while on-premise and hybrid deployments route through value-added resellers with implementation services.
- Cloud-Based:Multi-tenant architectures with automatic regulatory template updates eliminate infrastructure overhead. Demand concentrates among German automotive suppliers facing CSRD compliance deadlines, driven by procurement teams seeking compressed implementation timelines without IT capital allocation.
- SaaS:Subscription pricing with tiered feature access targets mid-market manufacturers previously excluded from enterprise carbon management. Expansion concentrates in India's pharmaceutical export corridor, where PLI scheme beneficiaries require rapid ESG documentation for EU market access.
- On-Premise:Single-tenant deployments persist in petrochemical facilities with stringent data sovereignty requirements and air-gapped operational technology networks.
- Hybrid:Split architectures separate sensitive emissions data on local servers while leveraging cloud analytics for regulatory reporting, common among French nuclear energy operators.
On-premise systems dominate installed base in heavy industry. Cloud-based deployment is where expansion concentrates.
End User:
Customer type determines solution complexity and sales cycle length, with energy sector buyers demanding real-time visibility while retail procurement favors standardized dashboards.
- Energy:Real-time carbon visibility platforms integrate with SCADA systems and utility data feeds. Procurement teams at German utilities and independent power producers drive fastest adoption curves, compelled by EU ETS compliance automation and FERC reporting requirements in US markets.
- Manufacturing:Scope 3 supplier engagement tools with embedded audit trails serve automotive and electronics OEMs. Demand clusters in Stuttgart-Turin industrial corridor, where tier-one suppliers cascade software mandates through battery and semiconductor supply chains.
- Retail:Consumer-facing emissions transparency tools with product-level carbon labeling support brand differentiation and regulatory compliance in French and Dutch markets.
- Healthcare:Pharmaceutical supply chain cold-chain emissions tracking addresses FDA validation requirements and EU MDR sustainability disclosures for medical device manufacturers.
Manufacturing retains largest installed base. Energy sector procurement is gaining share fastest.
Solution:
Functional modules align with customer compliance maturity, with carbon accounting commanding premium pricing and risk assessment penetrating through insurance channel partnerships.
- Carbon Accounting:Automated emissions calculation engines with Scope 1-2-3 coverage and scenario modeling capabilities. Expansion concentrates among US petrochemical facilities anticipating EPA facility-level reporting expansions, driven by compliance automation rather than voluntary disclosure.
- Compliance Management:Pre-built regulatory content libraries covering CSRD, SEC climate disclosure rules, and ISO 14064 standards. Mature demand from publicly traded entities with established ESG disclosure obligations and third-party assurance requirements.
- Reporting Tools:Template-driven disclosure automation with auditor-ready documentation formats serves professional services firms and mid-market exporters.
- Risk Assessment:Climate scenario analysis and transition risk quantification for financial institutions and commodity trading desks, expanding through embedded finance convergence.
Compliance management dominates current revenue. Carbon accounting shows steepest expansion trajectory.
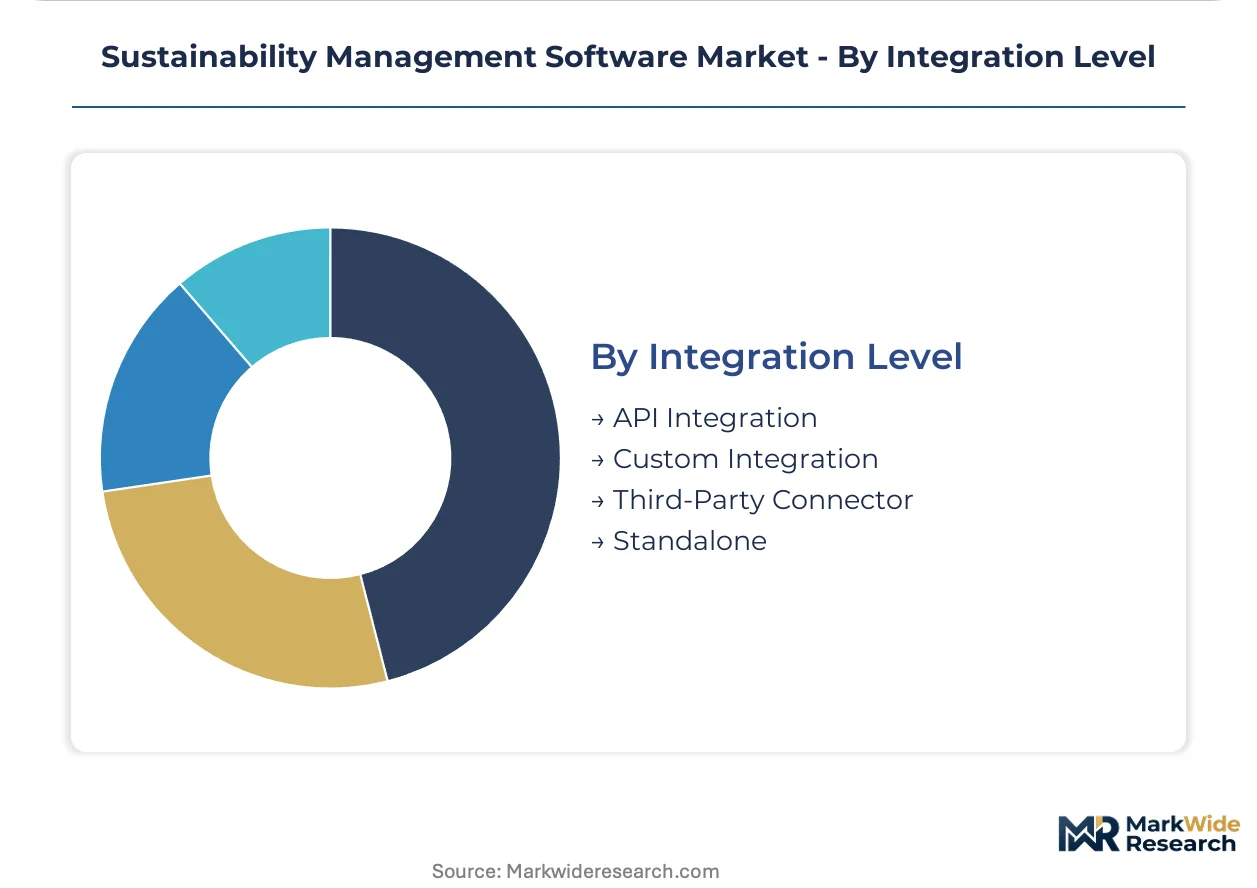
Integration Level:
Connectivity architecture determines procurement evaluation sequencing, with API capabilities now elevated above feature breadth in vendor selection matrices.
- API Integration:Standardized RESTful protocols connecting sustainability platforms to ERP, IoT, and supplier systems. Demand concentrates among procurement-led evaluations in Netherlands and France, where CSRD preparatory audits mandate seamless financial system connectivity.
- Third-Party Connector:Pre-built adapters for SAP, Oracle, and Salesforce ecosystems accelerate deployment without custom development. Common among mid-market manufacturers lacking dedicated integration teams.
- Custom Integration:Bespoke middleware development for legacy ERP systems in heavy industry with proprietary data formats, elongating sales cycles but locking in switching costs.
- Standalone:Disconnected point solutions for specific Scope categories or facility-level tracking, declining as procurement demands unified data architectures.
API integration commands premium positioning. Third-party connectors capture mid-market volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Paris high-speed rail corridor and North Sea grid interconnects accelerate software procurement cycles across continental Europe. Digital infrastructure density concentrates vendor deployment resources in Germany's industrial corridor and the Netherlands' logistics hubs.
Germany
Automotive electrification mandates from Stuttgart OEMs cascade Scope 3 software requirements through battery supply chains. The EU Green Deal's CSRD enforcement through the Federal Financial Supervisory Authority tightens disclosure timelines for chemical conglomerates. The Rhine-Ruhr industrial cluster hosts enterprise-scale carbon accounting deployments at BASF and Bayer facilities.
United States
EPA facility-level greenhouse gas reporting expansions force petrochemical and power generation asset upgrades. The SEC climate disclosure rules trigger software procurement at Fortune 500 headquarters in Houston and Chicago. The Permian Basin oilfield operators deploy real-time methane monitoring platforms to satisfy FERC compliance automation.
France
Nuclear energy operators in Île-de-France adopt hybrid cloud architectures separating sensitive emissions data from regulatory reporting functions. The EU AI Act's risk classification framework imposes documentation requirements on algorithmic forecasting tools. Lyon-based chemical manufacturers segregate AI-enabled scenario analysis from core compliance systems.
India
PLI scheme incentives for green manufacturing create first-mover demand among textile and pharmaceutical exporters in Gujarat and Maharashtra. The Bureau of Indian Standards develops ESG disclosure frameworks aligned with EU market access requirements. The Mumbai-Pune pharmaceutical corridor deploys rapid ESG documentation platforms for CSRD preparatory audits.
Netherlands
CSRD preparatory audits elevate procurement-sustainability collaboration to board-level reporting at Rotterdam logistics conglomerates. The Dutch Authority for Financial Markets enforces granular disclosure standards across port-centric supply chains. Amsterdam's financial services sector integrates carbon pricing data into trade finance workflows.
Sustainability Management Software Market Vendor Landscape
Concentration sits with ERP-embedded incumbents and cloud-native specialists. The vendor landscape organizes around three strategic archetypes: legacy platforms with regulatory content libraries, API-first supply chain visibility tools, and lightweight point solutions for mid-market Scope categories. Dominant competitive moves include embedded finance partnerships and modular API-first architecture development.
Within the ERP-embedded tier, SAP exemplifies ecosystem extension through sustainability modules integrated into existing procurement workflows. Among cloud-native specialists, Watershed occupies a position emphasizing real-time supply chain carbon visibility. Sphera anchors the regulatory content archetype with deep emissions-intensive process industry specialization.
| Leading Market Players |
|---|
| Greenly |
| Sphera |
| Workiva |
| Osapiens |
| Watershed |
| SAP |
| SustainIQ |
| Tanso |
| Persefoni |
| Others |
Supply Flow & Price Mechanics
CSRD compliance tiers gate supplier qualification and price differentiation simultaneously, forcing mid-market buyers toward standardized SaaS bundles while enterprise procurement absorbs premium pricing for embedded regulatory content libraries and API integration depth.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with three-tier pricing separating enterprise-grade platforms with automated Scope 3 supplier engagement from mid-market carbon accounting tools and lightweight point solutions for specific emissions categories. Price differentiation hinges on certification depth—ISO 14064-aligned audit trails command 40-60% premiums over basic reporting templates—and vertical integration with ERP ecosystems. Cost compression in the mid-market tier is intensifying because cloud-native entrants are undercutting incumbent maintenance contracts. Healthcare and pharmaceutical buyers exhibit lowest price sensitivity due to FDA validation requirements, while Indian textile exporters facing PLI scheme deadlines drive hardest bargain negotiations.
Supply Chain Analysis
Inventory cycles for regulatory template updates compress to 90-day refresh windows as EU AI Act documentation requirements and EPA rulemaking revisions cascade through platform roadmaps. Software development concentrates in Germany, the United States, and India, with regulatory content engineering anchored in Stuttgart and Washington while implementation services flow from Pune and Bengaluru. Critical API infrastructure for utility data feeds draws from three North American meter data management providers, creating single-source vulnerability exposure. Distribution runs through systems integrators and sustainability consultancies that have displaced traditional software resellers in procurement influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sustainability management software functions as a service-attach opportunity where recurring regulatory content subscriptions and API maintenance fees expand faster than initial platform licensing, embedding vendors into customer compliance workflows for decade-long horizons.
For Market Incumbents: Secure regulatory content library depth against cloud-native challengers by acquiring specialized emissions methodology firms in Brussels and Washington. Defend position through embedded finance partnerships with trade finance platforms in Amsterdam and Rotterdam. Prioritize API-first architecture development to match procurement-led evaluation criteria in France and the Netherlands. For New Entrants and Emerging Players: Anchor in India's pharmaceutical export corridor where PLI scheme beneficiaries require rapid ESG documentation for EU market access. Target mid-market manufacturers in Gujarat and Maharashtra with pre-configured CSRD templates priced below SAP and Sphera maintenance tiers. Pursue systems integrator channel partnerships rather than direct enterprise sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as multi-tenant architectures achieve scale efficiencies in carbon accounting automation. Favor acquisition targets with established API integration credentials and regulatory content libraries covering EU Green Deal and EPA disclosure frameworks. Monitor EPA facility-level rulemaking progress as inflection signal for US petrochemical software upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first connectivity with SAP and Oracle ecosystems captures procurement-led evaluations in Germany. |
| Regulatory Content Expansion | CSRD template libraries differentiate enterprise offerings from mid-market carbon calculators in France. |
| Embedded Finance Partnership | Carbon pricing data integration with Amsterdam trade finance desks opens commodity trading revenue streams. |
| Geographic Expansion | Localized deployment in India's pharmaceutical corridor addresses PLI scheme ESG documentation requirements. |
| Acquisition of Specialist Firm | Emissions methodology expertise pools in consulting firms, constraining implementation bandwidth for pure-play vendors. |
Methodological Framework
Desk research of regulatory filing databases, SEC climate disclosure submissions, and EU CSRD preparatory audit reports preceded structured interviews with chief sustainability officers, procurement directors at German automotive suppliers, API integration specialists, and sustainability consultancy partners. Primary fieldwork concentrated on CSRD implementation timelines across the Stuttgart-Turin industrial corridor and EPA compliance automation requirements in Houston and Chicago. Secondary validation drew from ETS transaction data, FERC greenhouse gas filings, and PLI scheme beneficiary disclosures. Bottom-up deployment estimates triangulated against top-down market sizing from ERP vendor sustainability module revenue disclosures.
Variance decomposition across deployment models, end-user verticals, solution modules, and integration complexity levels shaped the analytical framework over the projection horizon. CAGRs derived from segment-level adoption curves weighted by regulatory enforcement timelines in Germany, France, and the United States. Forecast inputs incorporated API integration penetration rates among procurement-led evaluations and cloud migration velocity among mid-market manufacturers previously excluded from enterprise carbon management systems.
Material uncertainties—EPA rulemaking delays, EU AI Act enforcement calibration, and accredited auditor capacity constraints for Scope 3 verification—sit outside the modeled envelope. Forecasts reflect assumptions regarding CSRD disclosure timeline adherence and API standardization progress across industrial IoT vendor ecosystems. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Global Resource Circulation Equipment Market
Environment & Sustainability
Recycling Equipment and Machinery Market
Environment & Sustainability
Water Filters Market
Environment & Sustainability
Philippines Gravity-Based Water Purifier Market
Environment & Sustainability
Radon Gas Test Kits Market
Environment & Sustainability
Solar Windows Market
Environment & Sustainability
Green Rebar Market
Environment & Sustainability
Blue-Green Algae Market
Environment & Sustainability
Sustainable and Green Building Materials Market
Environment & Sustainability
Eco-Friendly Tiles Market
Environment & Sustainability
US Municipal Solid Waste Management Market
Environment & Sustainability
Singapore Waste Management Market
Environment & Sustainability
Global Weather Forecasting Services Market
Environment & Sustainability
Circular Economy Logistics Design and Implementation Services Market
Environment & Sustainability
Global Water Market
Environment & Sustainability
Europe Waste Management Market