
 Singapore Waste Management Market | 2026-2036
Singapore Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Waste Management Market Analytics
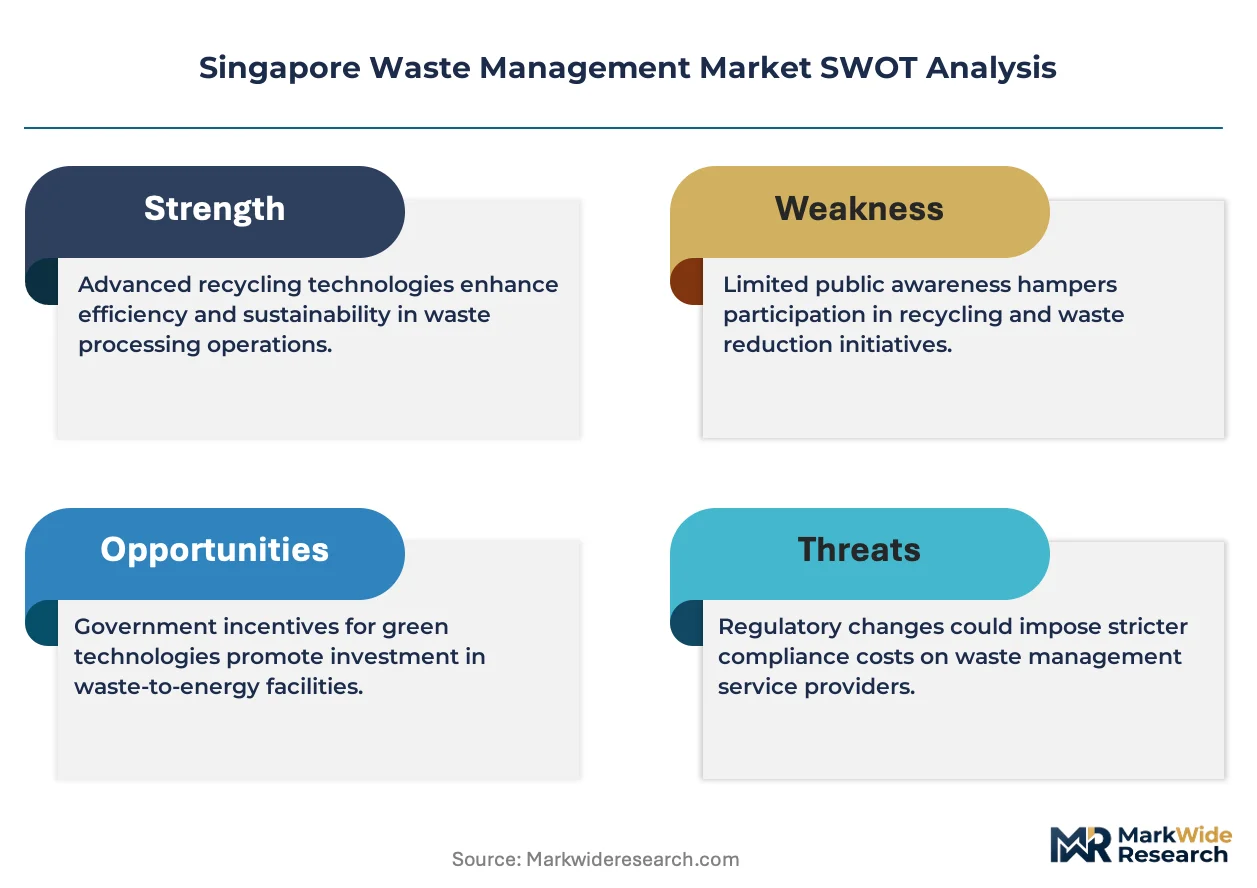
Integrated energy recovery revenue is fragmenting across Singapore's waste-to-energy operators as landfill diversion mandates harden. Sembcorp Environmental Management Pte Ltd anchors large-scale incineration capacity at the Tuas Nexus facility. Veolia Environmental S.A. competes through specialized hazardous waste treatment and industrial services. ecoWise Holdings Ltd differentiates via recycling and waste-to-resource solutions for commercial streams.
Singapore waste management encompasses the systematic collection, transport, treatment, recycling, and disposal of municipal, industrial, and hazardous waste streams, with incineration reducing waste volume by approximately 90% while recovering energy for grid injection. The sector serves urban densification imperatives, public health protection, and circular economy targets under severe land constraints. Collection services dominate volume throughput given universal door-to-door coverage across public housing estates and commercial zones. Recycling faces structural headwinds from contamination rates and export market closures, though anaerobic digestion is gaining traction for organic waste streams from food manufacturing and hospitality sectors. Treatment margins concentrate in hazardous and e-waste categories where licensing barriers limit participant entry.
Singapore's National Environment Agency enforces the Resource Sustainability Act and extended producer responsibility frameworks for e-waste and packaging, mandating collection targets and reporting obligations that reshape operator compliance costs. The Building and Construction Authority's Green Mark standards and the Energy Market Authority's grid connection rules for waste-to-energy plants further constrain facility design and revenue stacking options. Stakeholders must track regulatory tightening on carbon intensity disclosures and circularity benchmarks to anticipate capital allocation shifts across treatment technologies.
Market Dynamics
Singapore's waste management sector faces intensifying pressure from the National Environment Agency's Zero Waste Masterplan, which mandates 70 percent overall recycling rates and 30 percent reduction in waste-to-landfill by 2030. Land scarcity and carbon disclosure requirements are forcing operators toward integrated treatment precincts and circular resource recovery models.
Growth Catalysts
- Extended Producer Responsibility (EPR) Schemes:The Resource Sustainability Act mandates collection targets for e-waste and packaging waste, creating guaranteed feedstock volumes for licensed recyclers and treatment operators.
- Tuas Nexus Concentration:Co-location of incineration, water reclamation, and food waste treatment at the integrated precinct enables energy and resource synergies that standalone facilities cannot replicate.
- Industrial Closed-Loop Adoption:Electronics and precision manufacturing sectors are deploying on-site solvent recovery and metal reclamation systems to reduce hazardous waste disposal costs and meet supply chain circularity requirements.
Market Restraints
- Land Scarcity Premium:Limited industrial land availability in Singapore drives facility rental costs to levels that constrain small-scale recycling operations and organic waste processing startups.
- Export Market Closure:China's National Sword policy and subsequent Southeast Asian import restrictions have eliminated traditional outlets for contaminated plastic and mixed paper streams, forcing domestic processing investment.
- Grid Connection Friction:Energy Market Authority interconnection rules for waste-to-energy plants impose technical and timeline barriers that delay revenue realization from electricity sales.
Strategic Opportunities
- Chemical Recycling Scale-Up:Pyrolysis and gasification technologies for contaminated plastics remain underdeveloped in Singapore, creating first-mover advantage for operators securing NEA licensing.
- Food Manufacturing Anaerobic Digestion:Untapped organic waste streams from Jurong Island food processing clusters and central kitchen operations offer biogas feedstock for decentralized energy generation.
- Carbon Credit Stacking:Emerging methodologies for avoided landfill emissions and renewable energy certificates allow waste-to-energy operators to monetize climate benefits beyond electricity tariffs.
Industry Challenges
- Contamination Control Expertise:Recycling facilities face persistent operational losses from high residual contamination rates in commingled commercial and residential collections, requiring advanced sorting capital.
- Legacy Incinerator Retrofit Complexity:Aging plants at Tuas and Senoko require emission control upgrades to meet tightening NEA air quality standards without extended downtime that disrupts waste acceptance contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Waste Management Market |
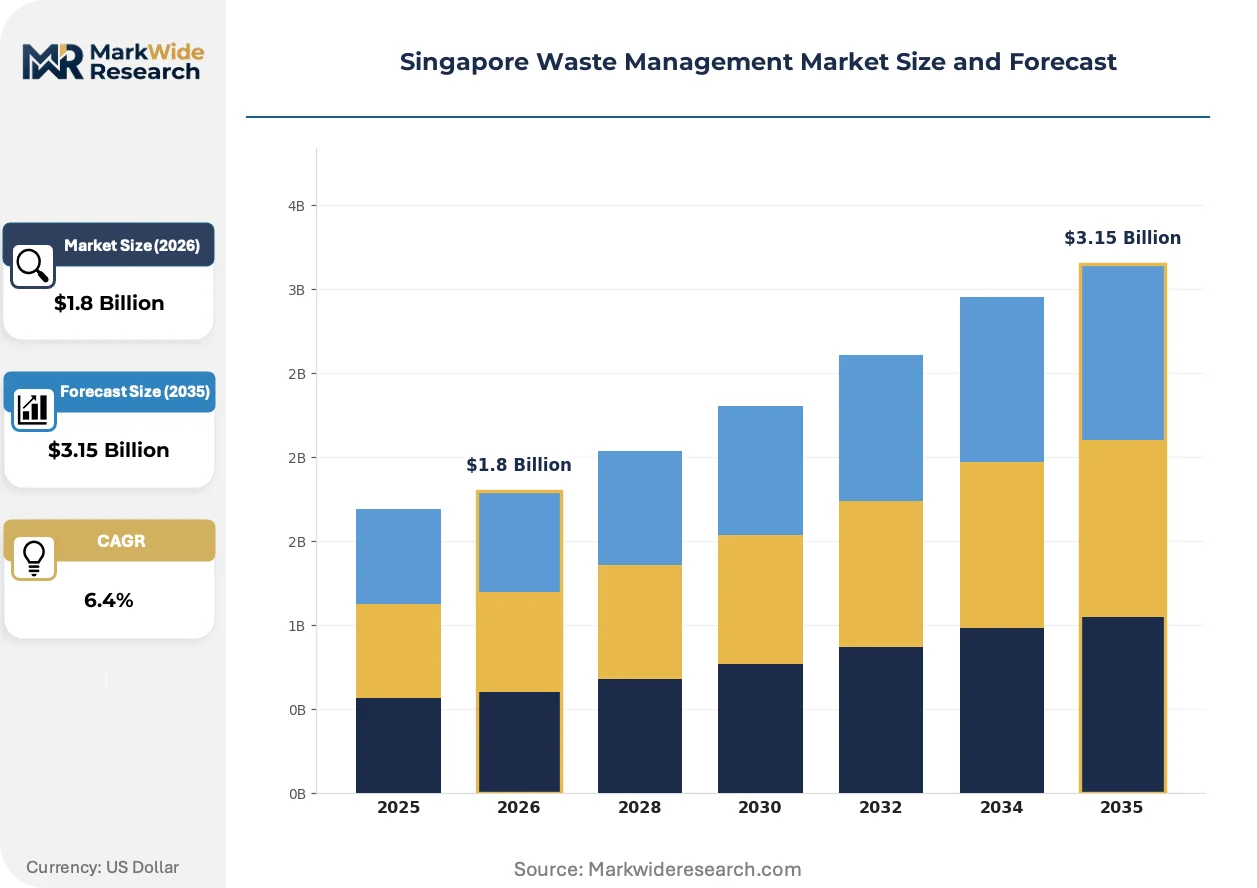
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Treatment, Recycling, Disposal Material Type: Organic Waste, Plastic Waste, Hazardous Waste, E-Waste End User: Residential, Commercial, Industrial, Government Technology: Incineration, Landfilling, Composting, Anaerobic Digestion |
| Companies Covered | Colex Holdings Limited, ECO Industrial Environmental Engineering Pte Ltd, Sembcorp Environmental Management Pte Ltd, ecoWise Holdings Ltd, Envipure, Veolia Environmental S.A., 800 Super Holdings, RICTEC PTE LTD, ALBA W&H Smart City, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Waste Management Market Evolving Landscape
Digital traceability and automated sorting systems are reconfiguring how waste streams are characterized and routed through Singapore's treatment infrastructure. Operators are deploying sensor networks and AI-driven material identification to capture value from previously unrecoverable fractions.
Optical sorting paired with robotic pickers is collapsing the economics of manual separation lines at materials recovery facilities. Commercial recyclers including those serving the hospitality and retail sectors are retrofitting plants with near-infrared spectroscopy and delta robots to handle mixed packaging at throughput rates exceeding 10 tonnes per hour. This automation compression is enabling smaller footprint facilities in land-constrained industrial zones.
Singapore's Resource Sustainability Act amendments are tightening reporting obligations for large commercial waste generators. The National Environment Agency now mandates granular waste stream data from hotels, shopping malls, and food manufacturers above volume thresholds, creating audit trails that operators must integrate into customer-facing platforms. Industrial services firms are responding by embedding IoT scales and bin-level sensors into collection contracts.
Buyers in the semiconductor and pharmaceutical manufacturing verticals are unbundling waste services from general facility management contracts. These precision industries now contract directly with licensed hazardous waste specialists for solvent recovery and sludge treatment, bypassing bundled janitorial providers. This disintermediation concentrates volume with NEA-licensed specialists holding ISO 14001 and chemical handling certifications.
Singapore Waste Management Market Segmentation
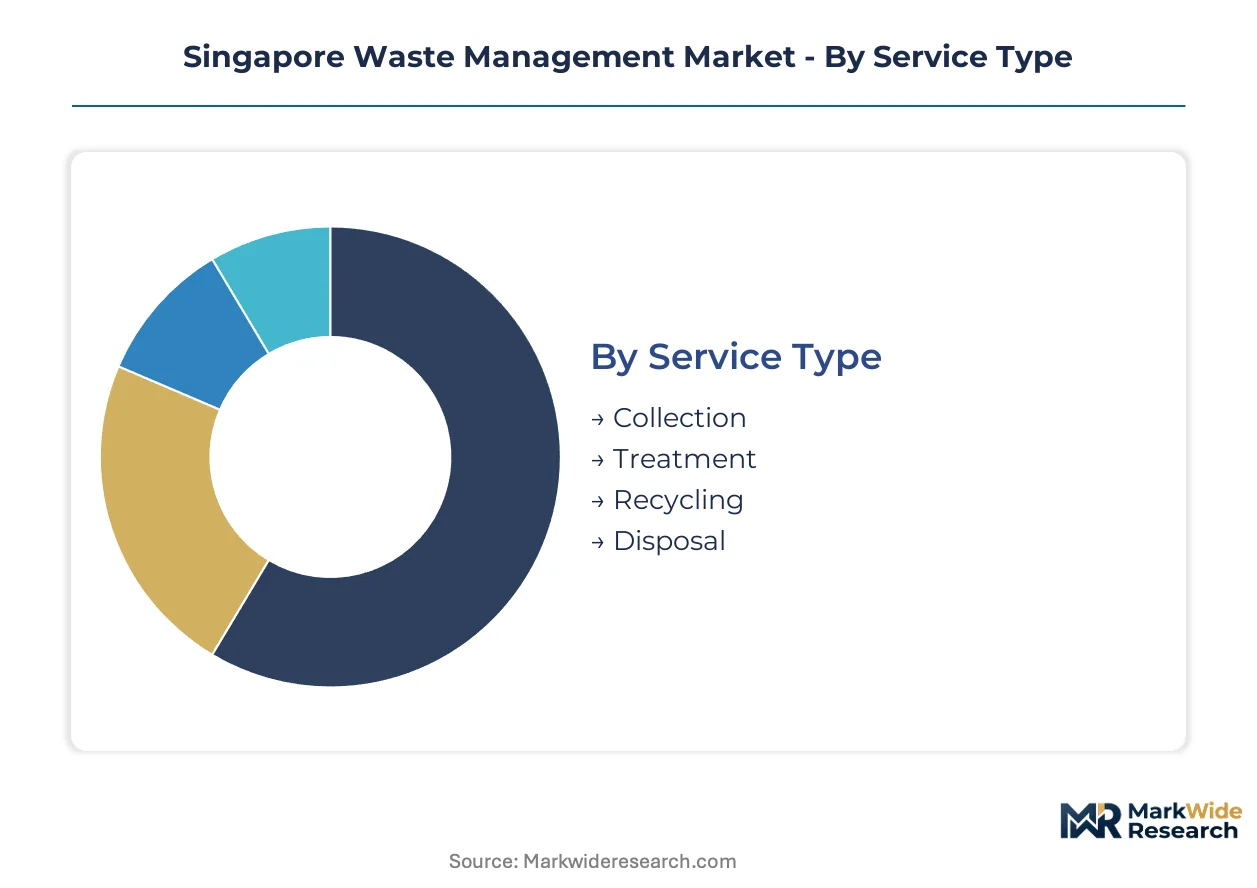
Singapore's waste management segmentation reveals how land scarcity and regulatory mandates reshape service economics across material streams. Each dimension exposes distinct margin structures, technology barriers, and compliance intensities that determine operator viability.
Service Type:
Collection services span universal door-to-door coverage in public housing estates through commercial zone consolidation, while treatment and recycling command premium margins through licensing scarcity.
- Collection:Universal door-to-door coverage across HDB estates and commercial zones generates volume throughput under NEA-regulated contracts. Public housing collections dominate tonnage, though commercial zone consolidation is gaining efficiency through route optimization algorithms.
- Treatment:Incineration at Tuas Nexus reduces waste volume by 90% while recovering energy for grid injection under Energy Market Authority rules. Licensing barriers limit participant entry, concentrating margins among NEA-approved operators with emission control compliance.
- Recycling:Materials recovery facilities face contamination headwinds from commingled streams, requiring optical sorting capital to achieve viable yield rates. Export market closures post-China National Sword force domestic processing investment with compressed economics.
- Disposal:Semakau Landfill receives pre-treated ash and non-incinerable residues under strict diversion mandates, with gate fees reflecting scarcity value of remaining capacity.
The dominant share belongs to Collection, while Treatment is closing the gap fastest through energy recovery revenue stacking.
Material Type:
Margin concentration varies sharply by contamination risk and regulatory oversight intensity across Singapore's waste streams.
- Organic Waste:Food manufacturing and hospitality sectors generate feedstock for anaerobic digestion at decentralized Jurong Island facilities. NEA mandates on food waste segregation from commercial generators above volume thresholds secure guaranteed supply for biogas operators.
- Hazardous Waste:Electronics and pharmaceutical manufacturing produce solvent-laden streams requiring ISO 14001-certified handling. Precision industries now contract directly with licensed specialists, bypassing bundled facility management providers.
- Plastic Waste:Contamination rates in post-consumer streams force chemical recycling investment where pyrolysis licensing creates first-mover advantage. Export restrictions eliminated traditional outlets, stranding mixed plastics without domestic processing scale.
- E-Waste:Extended Producer Responsibility schemes under the Resource Sustainability Act mandate collection targets with audit trail obligations. Precious metal reclamation from circuit boards concentrates value recovery with licensed dismantlers.
Hazardous Waste commands the steepest margin premium, though Organic Waste is expanding most quickly through anaerobic digestion deployment.
End User:
Customer segmentation tracks waste volume scale against compliance complexity and contract structure preferences.
- Industrial:Electronics and precision manufacturing deploy closed-loop solvent recovery to reduce hazardous disposal costs. Semiconductor verticals unbundle waste services from general facility contracts, concentrating volume with certified specialists.
- Commercial:Hotels, shopping malls, and food manufacturers above NEA volume thresholds face granular reporting mandates. IoT-enabled bin sensors and waste stream data platforms are embedding into collection contracts.
- Residential:HDB estate collections operate under universal coverage with limited price elasticity. Recycling participation rates face structural headwinds from convenience gaps and contamination feedback loops.
- Government:Public sector procurement emphasizes circular economy benchmarks and carbon intensity disclosures in vendor selection. Tuas Nexus infrastructure investments anchor public capital allocation toward integrated precinct models.
Industrial generators drive premium service margins, while Commercial is gaining share fastest through regulatory disclosure mandates.
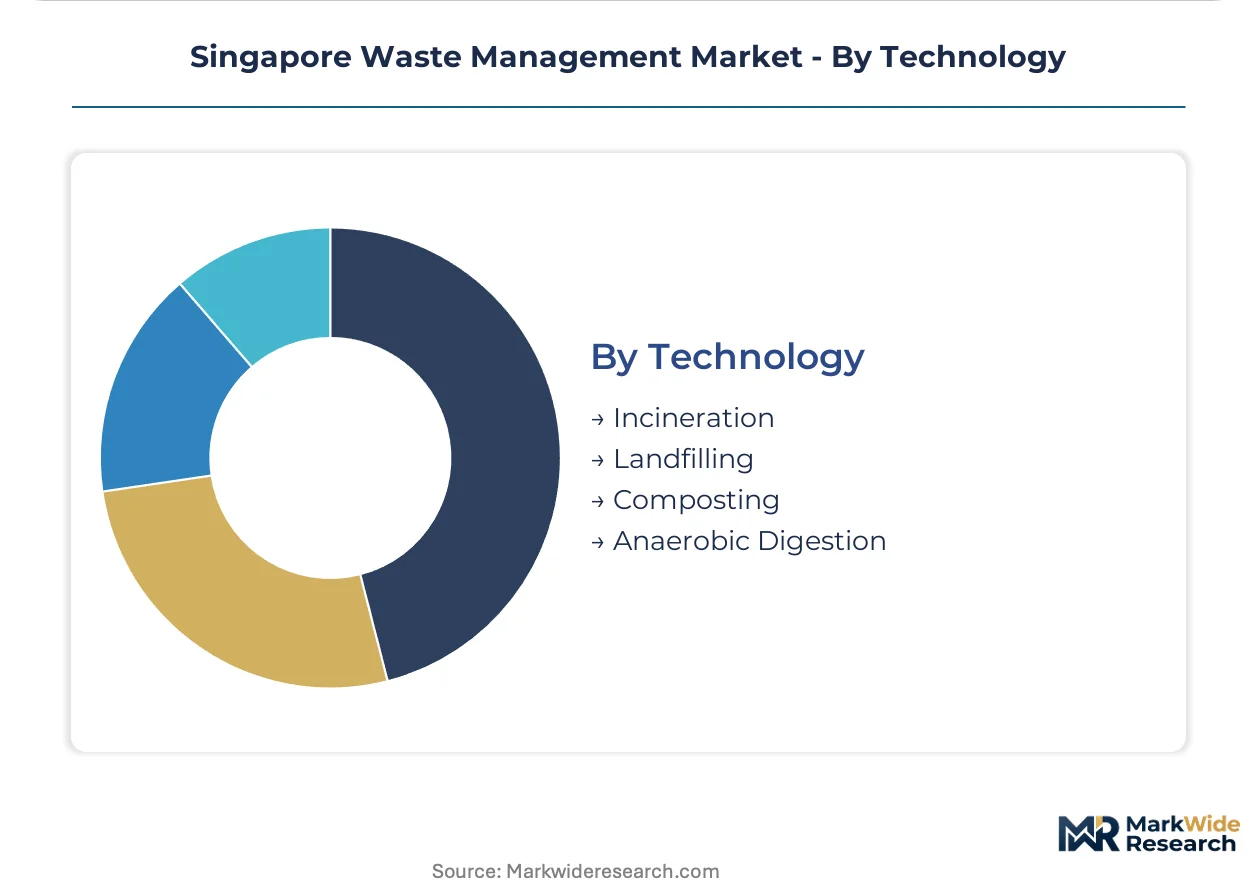
Technology:
Technology selection reflects land constraints, emission standards, and grid interconnection economics under Singapore's regulatory framework.
- Incineration:Mass burn facilities at Tuas Nexus anchor national capacity with energy recovery for grid injection. Aging plants require emission control retrofits to meet tightening NEA air quality standards without contract-disrupting downtime.
- Anaerobic Digestion:Food waste streams from central kitchens and food manufacturing clusters generate biogas for decentralized energy. Jurong Island proximity to organic waste sources enables viable scale without transport cost penalties.
- Composting:Limited land availability constrains open-air operations, though in-vessel systems serve niche horticultural and landscaping feedstock markets.
- Landfilling:Semakau Landfill receives only pre-treated ash and non-incinerable residues under 30 percent waste-to-landfill reduction targets. Gate fees reflect terminal scarcity value as diversion mandates harden.
Incineration retains dominant capacity share, though Anaerobic Digestion is climbing the fastest through food waste segregation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Singapore's industrial corridor exhibit the lowest price elasticity, absorbing premium treatment costs for hazardous waste compliance, while residential segments remain highly sensitive to collection fee adjustments. The city-state's waste management demand clusters around three geographic anchors with distinct regulatory and infrastructure profiles.
Central Region
The Central Region concentrates commercial waste generation from hotels, shopping malls, and food manufacturing facilities above National Environment Agency reporting thresholds. The Resource Sustainability Act mandates granular waste stream data from generators in this zone, driving IoT sensor deployment in collection contracts. The Orchard Road hospitality cluster and central kitchen operations in Bukit Merah anchor organic waste feedstock flows toward anaerobic digestion facilities.
Tuas Industrial District
The Tuas Industrial District hosts the Tuas Nexus integrated waste management precinct where co-located incineration, water reclamation, and food waste treatment enable energy and resource synergies. Energy Market Authority grid interconnection rules for waste-to-energy plants apply most stringently here due to high-capacity injection points. Sembcorp Environmental Management anchors large-scale incineration capacity at this facility, serving as the backbone of national waste volume reduction.
Jurong Island
Jurong Island generates concentrated hazardous waste streams from electronics and pharmaceutical manufacturing requiring ISO 14001-certified handling. Precision industries here unbundle waste services from general facility contracts, concentrating volume with licensed specialists. The island's food processing clusters provide untapped organic waste feedstock for decentralized biogas generation under NEA food waste segregation mandates.
Eastern Region
The Eastern Region encompasses aging incineration infrastructure at Senoko requiring emission control retrofits to meet tightening National Environment Agency air quality standards. Residential collections across Tampines and Bedok public housing estates generate high-throughput municipal waste with limited price elasticity. Recycling participation rates here face structural headwinds from convenience gaps and contamination feedback loops in commingled collection systems.
Western Region
The Western Region contains materials recovery facilities facing contamination pressures from commingled commercial and residential streams. Export market closures post-China National Sword force domestic processing investment with compressed economics in this zone. ALBA W&H Smart City operations here exemplify the automation shift toward optical sorting and robotic pickers handling mixed packaging at throughput rates exceeding 10 tonnes per hour.
Singapore Waste Management Market Competitive Landscape
Capability concentration sits with licensed hazardous waste specialists holding ISO 14001 and chemical handling certifications; scale advantage sits with integrated operators commanding incineration capacity at Tuas Nexus. The vendor base stratifies across three tiers: national-scale incineration operators, regional recycling and treatment specialists, and niche hazardous waste handlers. Two strategic archetypes dominate—vertically integrated precinct operators leveraging co-location synergies, and technology-forward recyclers deploying automated sorting systems. Competitive moves center on licensing acquisition for chemical recycling pyrolysis and strategic partnerships securing food manufacturing anaerobic digestion feedstock contracts.
Within the integrated operator tier, Sembcorp Environmental Management Pte Ltd and Veolia Environmental S.A. exemplify contrasting geographic origins—Singapore-based and French-based respectively—while occupying positions as scale-driven incineration and specialized hazardous treatment providers. ecoWise Holdings Ltd represents the recycling-specialist archetype, differentiated through waste-to-resource solutions for commercial streams rather than volume-driven collection economics. These three entities collectively illustrate how licensing scarcity and technology deployment separate viable operators from marginal players in Singapore's compliance-intensive market.
| Leading Market Players |
|---|
| Colex Holdings Limited |
| ECO Industrial Environmental Engineering Pte Ltd |
| Sembcorp Environmental Management Pte Ltd |
| ecoWise Holdings Ltd |
| Envipure |
| Veolia Environmental S.A. |
| 800 Super Holdings |
| RICTEC PTE LTD |
| ALBA W&H Smart City |
| Others |
Value Network & Pricing Analysis
Land scarcity premium in Singapore determines both pricing tier spreads and supply chain shape, compressing small-scale recyclers while concentrating volume with integrated precinct operators at Tuas Nexus. The National Environment Agency's licensing scarcity for hazardous waste handling and energy recovery creates steep margin gradients that reward co-located infrastructure over distributed collection networks.
Pricing Analysis
Long-term service contracts spanning collection, treatment, and energy recovery drive lifetime value more than transactional gate fees. Pricing stratifies across premium hazardous waste handling, standard municipal collection, and economy residual disposal tiers based on ISO 14001 certification status and NEA licensing tier. Cost compression in standard recycling streams is intensifying because export market closures eliminated margin buffers for contaminated plastics. Industrial generators on Jurong Island exhibit the lowest price sensitivity, absorbing premium treatment costs for solvent recovery compliance, while residential HDB estates face fixed fee structures with limited elasticity.
Supply Chain Analysis
Upstream feedstock flows concentrate on domestic commercial and industrial waste streams, with limited cross-border material movement due to Singapore's city-state geography and import restrictions. Malaysia and Indonesia provide supplemental equipment and technical services, though core treatment capacity remains captive within national boundaries. The supply chain rests on specialized incineration equipment from European and Japanese manufacturers, chemical handling systems, and automated sorting technology from German and Korean suppliers. Single-source vulnerability concentrates around grid interconnection equipment governed by Energy Market Authority technical standards. Distribution runs through NEA-licensed operators with exclusive collection zones and direct industrial contracts bypassing general facility management providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward precision manufacturing verticals unbundling waste services from bundled contracts, fragmenting procurement authority and rewarding specialized hazardous waste handlers with direct relationships.
For Market Incumbents: Build regulatory moats through NEA chemical recycling pyrolysis licensing before first-mover windows close. Incumbents should secure long-term feedstock contracts with Jurong Island food manufacturing clusters for anaerobic digestion expansion, while retrofitting aging Senoko incineration assets with emission control systems to preempt downtime risks from tightening air quality standards. Vertical integration into bin-level IoT sensor deployment captures data mandates from commercial generators above reporting thresholds. For New Entrants and Emerging Players: Pursue white-space opportunities in decentralized biogas generation serving central kitchen operations and food processing clusters underserved by Tuas Nexus concentration. New entrants should target chemical recycling scale-up for contaminated plastics where pyrolysis licensing creates barrier-protected niches, entering through partnerships with existing waste collectors seeking technology differentiation rather than competing for collection route contracts. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors licensed specialists with ISO 14001 certifications and NEA hazardous waste permits over undifferentiated collection operators. Investors should prioritize acquisition targets holding exclusive Tuas Nexus co-location rights or proprietary automated sorting technology achieving throughput rates above 10 tonnes per hour. The signal to watch is carbon credit methodology adoption for avoided landfill emissions, which would revalue energy recovery assets beyond electricity tariff economics.| Strategic Initiative | Industry Significance |
|---|---|
| NEA Pyrolysis Licensing Acquisition | First-mover positioning in chemical recycling captures stranded plastic streams post-export market closure. |
| Jurong Island Feedstock Partnership | Direct contracts with food manufacturing clusters secure guaranteed organic waste supply for biogas expansion. |
| Automated Sorting Retrofit | Optical sorting and robotic picker deployment collapses manual separation economics in land-constrained zones. |
| Grid Interconnection Capacity Reservation | Energy Market Authority queue positioning accelerates revenue realization from waste-to-energy electricity sales. |
| Carbon Credit Methodology Development | Monetization of avoided landfill emissions through emerging certification standards stacks revenue beyond tariffs. |
Research Methodology
The analysis maps collection services, treatment technologies, recycling processes, and disposal infrastructure, each validated through plant managers at materials recovery facilities, NEA regulatory affairs officers, procurement leads at semiconductor manufacturers, and grid interconnection specialists at the Energy Market Authority. Secondary sources include National Environment Agency waste statistics, Resource Sustainability Act amendment filings, Energy Market Authority grid connection rule updates, and Building and Construction Authority Green Mark documentation. Bottom-up capacity modeling triangulates against top-down waste generation estimates from commercial and industrial surveys.
Assumptions held fixed include NEA enforcement intensity for extended producer responsibility schemes and Energy Market Authority grid interconnection timelines, while carbon credit methodology adoption rates and chemical recycling technology cost curves were varied across sensitivity scenarios. Segmentation dimensions modeled encompass service type, material stream, end-user vertical, and technology selection across the projection horizon. CAGRs derive from installed capacity expansion schedules, licensing issuance patterns, and feedstock contract coverage ratios.
Sensitivities concentrate around regulatory enforcement delays for food waste segregation mandates and carbon credit certification timeline slippage that would revalue energy recovery economics. Cross-checking against National Environment Agency annual waste statistics and Energy Market Authority generation connection reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
Incinerator Market
Waste Management & Pollution Control
Nutrient Recycling Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
Metal Recycling Baler Market
Waste Management & Pollution Control
India Waste-To-Energy Market
Waste Management & Pollution Control
US Medical Waste Management Market
Waste Management & Pollution Control
India Recycling Market
Waste Management & Pollution Control
Biomedical Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Waste Management Market
Waste Management & Pollution Control
Global Waste Oil Market
Waste Management & Pollution Control
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
Waste Management Market
Waste Management & Pollution Control
Rare Earth Recycling Market