
 Circular Economy Logistics Design and Implementation Services Market | 2026-2036
Circular Economy Logistics Design and Implementation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Circular Economy Logistics Design and Implementation Services Market Insights
Digital twin modeling is rewriting how circular supply chains are architected, enabling real-time simulation of product returns and remanufacturing flows before physical deployment. Accenture leverages its cloud-based analytics platforms to optimize reverse logistics networks for multinational manufacturers. DHL anchors its competitive position through specialized fleet management services that track asset recovery across closed-loop systems. Schneider Electric differentiates by integrating energy-efficient warehouse optimization with circular material flows for industrial clients.
Circular economy logistics design and implementation services encompass the strategic planning, digital infrastructure, and operational execution required to transform linear supply chains into regenerative systems where products, components, and materials circulate at highest utility. These services deploy IoT-enabled tracking, AI-driven demand forecasting for returns, and modular sorting infrastructure to enable product lifecycle management and material recovery at scale. Reverse logistics and supply chain consulting currently occupy the largest service type segments, while sustainability reporting is expanding fastest as regulatory disclosure requirements tighten across jurisdictions. Cloud-based delivery models are gaining share against on-premise installations, particularly among mid-sized retailers and packaging suppliers seeking faster deployment without capital-intensive infrastructure.
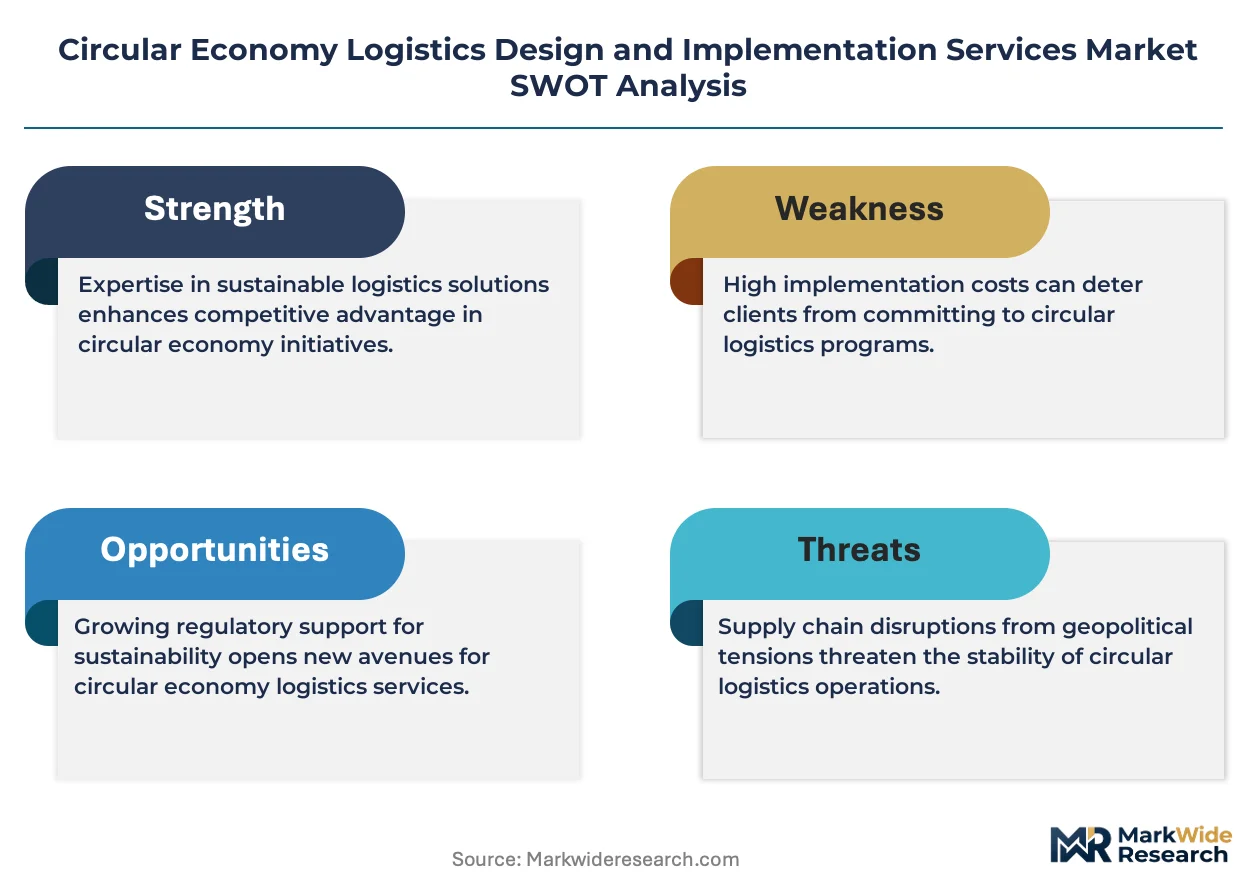
The EU Green Deal and its extended producer responsibility frameworks, alongside the EPA's evolving e-waste regulations in the United States, are mandating measurable recovery rates and emissions disclosures that directly shape procurement criteria for logistics services. REACH compliance and emerging digital product passport requirements under the EU AI Act are further embedding traceability specifications into contract terms for warehouse optimization and fleet management providers. Stakeholders must evaluate whether their technology stacks can authenticate material provenance and automate regulatory reporting before compliance deadlines harden into market access barriers.
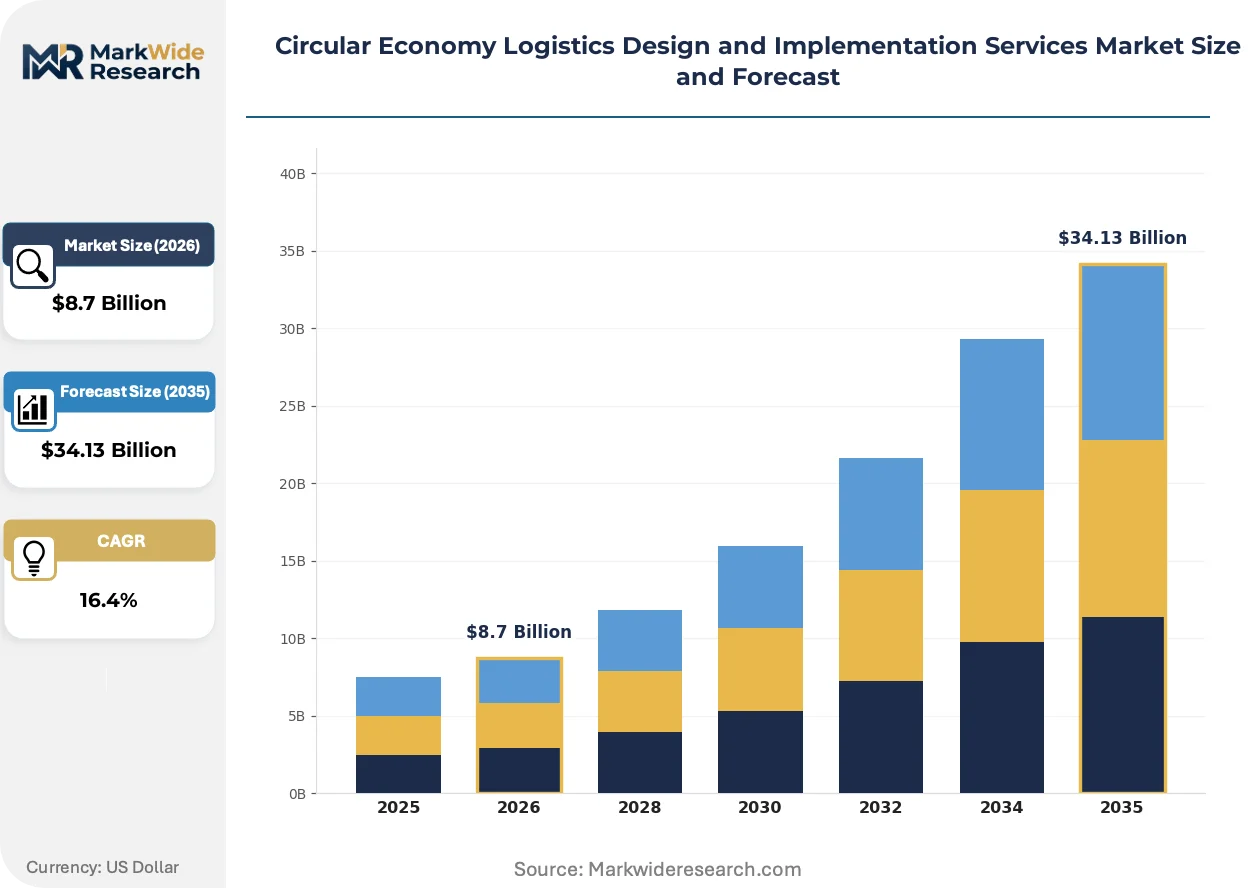
Market Dynamics
Extended producer responsibility mandates under the EU Green Deal are forcing automotive and electronics manufacturers to redesign supply chains for material recovery, creating immediate procurement demand for reverse logistics infrastructure and digital tracking systems.
Growth Catalysts
- REACH Compliance Deadlines:Chemical substance registration requirements in Europe are compelling industrial manufacturers to trace material provenance through closed-loop systems, accelerating investment in IoT-enabled sorting infrastructure.
- Automotive Closed-Loop Programs:German vehicle manufacturers are expanding battery recovery networks to satisfy battery passport regulations, directly contracting specialized fleet management and warehouse optimization services.
- Cloud-Based Deployment Models:Mid-sized packaging suppliers are adopting SaaS logistics platforms to avoid capital-intensive infrastructure, broadening addressable market penetration beyond enterprise accounts.
Market Restraints
- Sorting Infrastructure Capex:Modular automated sorting systems for mixed material streams require substantial upfront investment, limiting adoption among smaller third-party logistics providers.
- Regulatory Fragmentation:Divergent e-waste recovery rate thresholds between EPA state-level implementations and EU directives create compliance complexity for multinational service deployments.
- Legacy System Integration:Existing ERP and warehouse management systems in industrial manufacturing lack API compatibility with circular tracking platforms, extending implementation timelines.
Strategic Opportunities
- Digital Product Passport Mandates:The EU AI Act's traceability specifications will require authentication infrastructure that logistics providers can embed as value-added services before 2027 compliance deadlines.
- Remanufacturing Hub Development:Industrial clusters in the Netherlands are consolidating component refurbishment operations, creating concentrated demand for specialized reverse logistics network design.
- AI-Driven Demand Forecasting Convergence:Predictive analytics for returns volume is merging with carbon accounting platforms, enabling outcome-based pricing models tied to verified emissions reductions.
Industry Challenges
- Interoperability Standards Gap:Absence of unified data exchange protocols between material recovery facilities and transport fleets forces custom integration work on each deployment.
- Reverse Logistics Talent Scarcity:Shortage of supply chain engineers with expertise in circular flow modeling and remanufacturing network optimization constrains service delivery capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Circular Economy Logistics Design and Implementation Services Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Reverse Logistics, Fleet Management, Supply Chain Consulting, Warehouse Optimization, Sustainability Reporting Client Type: Manufacturers, Retailers, Third-Party Operators, Waste Management Firms, Packaging Suppliers Delivery Model: On-Premise, Cloud-Based, Hybrid, Managed Services, Software as a Service Application Focus: Product Lifecycle Management, Material Recovery, Packaging Reuse, Emission Reduction, Resource Optimization |
| Companies Covered | Accenture, DHL, Walmart, Unilever, Schneider Electric, Philips, Ricoh, Bosch, Tomra Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Circular Economy Logistics Design and Implementation Services Market Trends and Innovations
Digital infrastructure for circular supply chains is advancing through three concurrent shifts: simulation technologies are compressing network design cycles, regulatory traceability requirements are embedding compliance into contract structures, and buyer procurement criteria are prioritizing verified material recovery rates over unit cost.
Digital twin modeling is migrating from pilot programs to standard deployment methodology for reverse logistics network architecture. Automotive manufacturers in Germany and France are adopting cloud-based simulation platforms to test product return flows and remanufacturing facility placement before physical capital commitment. This technology is compressing implementation timelines from eighteen months to under six months while reducing network optimization errors by enabling real-time scenario testing.
The EU Green Deal's extended producer responsibility frameworks are mandating measurable recovery rates and emissions disclosures that directly shape procurement criteria for logistics services. Industrial manufacturers must now document material provenance through supply chains to satisfy REACH compliance and emerging battery passport requirements. Warehouse optimization and fleet management providers are responding by embedding automated regulatory reporting modules into standard service contracts.
Buyer evaluation criteria for logistics contracts are elevating verified circularity metrics above traditional cost-per-unit benchmarks. Electronics retailers and packaging suppliers in Northern Europe are requiring service providers to demonstrate authenticated material recovery rates through third-party audit trails. This shift is most visible in procurement decisions by multinational manufacturers with EU manufacturing footprints, where contract awards now hinge on carbon-adjusted total cost of ownership rather than standalone freight rates.
Circular Economy Logistics Design and Implementation Services Market Segmentation
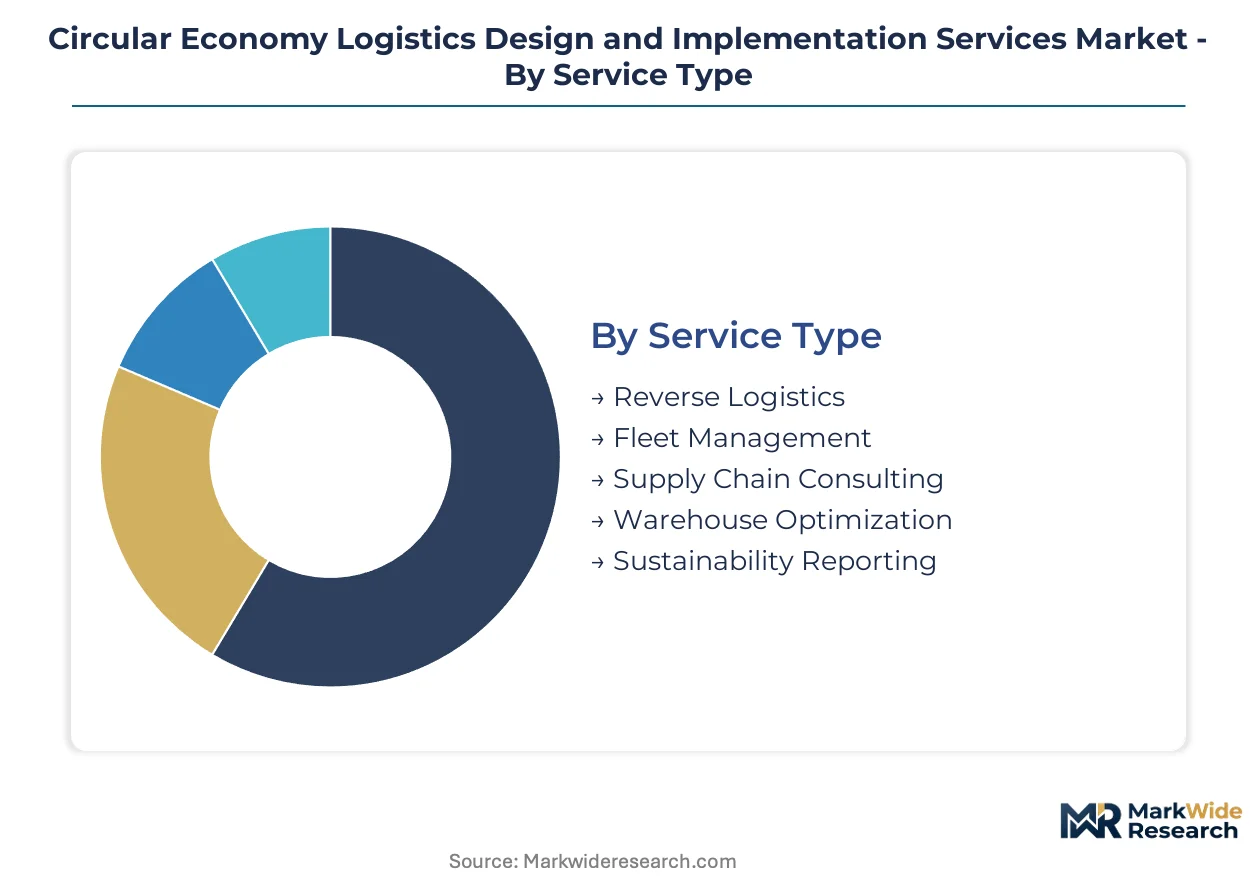
Circular economy logistics services fragment across four dimensions that determine contract structure, technology requirements, and margin profiles. Procurement patterns diverge sharply between automotive manufacturers seeking closed-loop battery recovery and retailers optimizing packaging reuse networks.
Service Type:
Cost tier separates commodity transport coordination from high-margin advisory and compliance services.
- Reverse Logistics:Physical collection, sorting, and redistribution of end-of-life products and components through dedicated return channels. German automotive manufacturers dominate procurement for battery recovery networks under EU battery passport regulations, with contract values scaling to fleet deployment scope.
- Supply Chain Consulting:Strategic redesign of linear flows into regenerative systems incorporating remanufacturing nodes and material recovery facilities. Demand concentrates among industrial manufacturers facing REACH compliance deadlines for chemical substance traceability.
- Fleet Management:Specialized vehicle allocation and routing for asset recovery operations across closed-loop systems.
- Warehouse Optimization:Layout and automation design for circular material handling and modular sorting infrastructure.
- Sustainability Reporting:Automated regulatory disclosure and carbon accounting modules embedded in logistics contracts.
Reverse logistics holds installed capacity. Sustainability reporting is rotating up the share rankings.
Client Type:
Application focus varies by sector maturity and regulatory exposure.
- Manufacturers:Industrial producers of automotive, electronics, and industrial equipment requiring closed-loop material recovery. German vehicle OEMs anchor demand through extended producer responsibility mandates, integrating digital product passport infrastructure into procurement specifications.
- Third-Party Operators:Logistics service providers seeking circular capability upgrades to retain manufacturing contracts. Investment concentrates in cloud-based tracking platforms and automated sorting systems to serve mid-sized packaging suppliers.
- Retailers:Electronics and apparel merchants redesigning return flows for refurbishment and resale.
- Waste Management Firms:Traditional disposal operators expanding into material recovery and preprocessing services.
- Packaging Suppliers:Container and pallet manufacturers developing pooling systems for reusable transport assets.
Manufacturers command the largest contract values. Third-party operators are gaining share fastest through capability acquisitions.
Delivery Model:
Volume scalability and capital commitment shape deployment architecture.
- Cloud-Based:SaaS logistics platforms enabling rapid deployment of circular tracking and demand forecasting without infrastructure ownership. Mid-sized packaging suppliers in Northern Europe favor this model to avoid capital-intensive sorting system investments while meeting EU Green Deal disclosure requirements.
- Software as a Service:Subscription-based access to AI-driven returns forecasting and carbon accounting modules. Demand is climbing the fastest among retailers seeking outcome-based pricing tied to verified material recovery rates.
- On-Premise:Dedicated server installations for large manufacturers with data sovereignty requirements.
- Hybrid:Mixed cloud-edge configurations balancing real-time processing with centralized analytics.
- Managed Services:Full operational outsourcing of circular logistics execution.
On-premise retains enterprise manufacturing accounts. Cloud-based is displacing legacy installations among mid-market entrants.
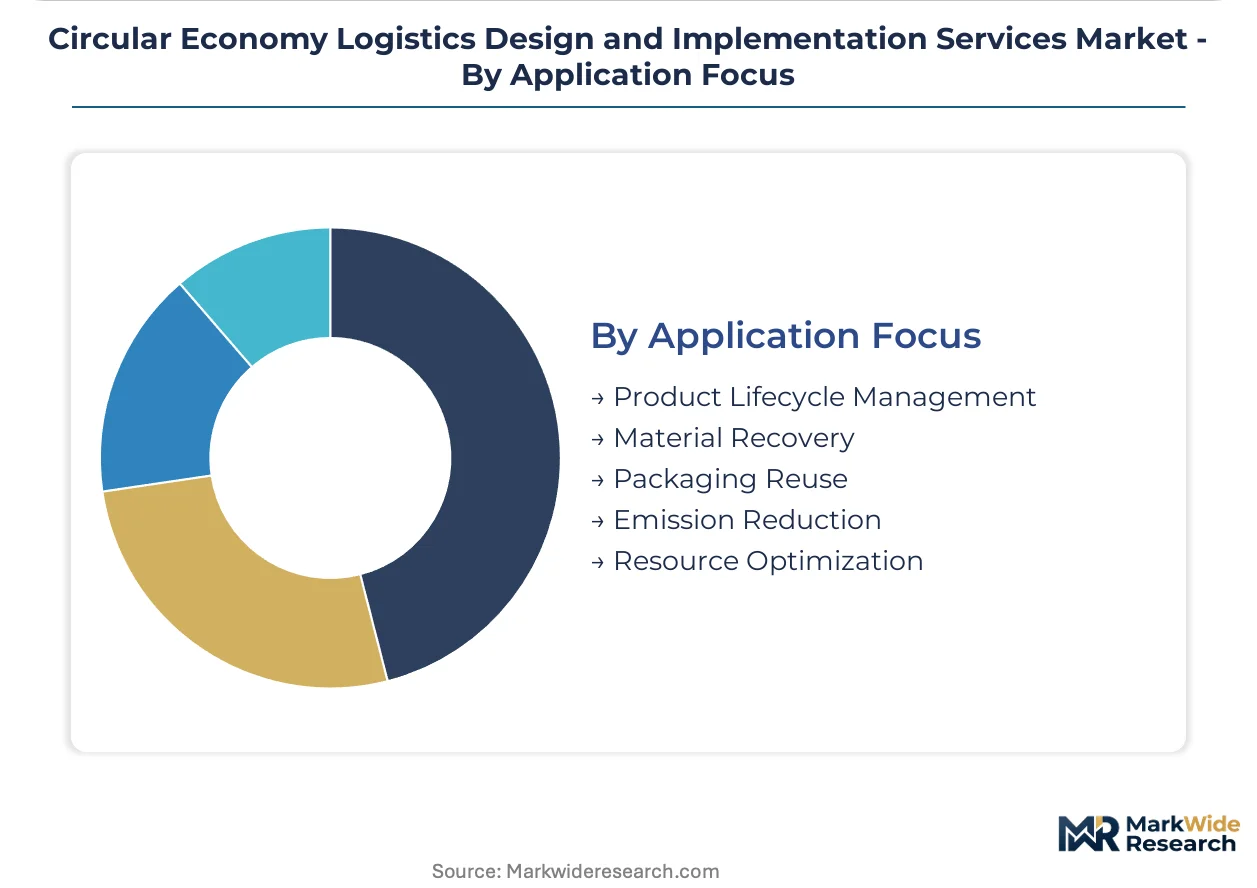
Application Focus:
Customer type and regulatory pressure determine priority use cases.
- Material Recovery:Extraction and preprocessing of valuable components from end-of-life products for reintroduction to production. Dutch industrial clusters are consolidating refurbishment operations, creating concentrated demand for specialized network design services.
- Product Lifecycle Management:End-to-end tracking and optimization of product utility across multiple use cycles. Electronics retailers require authenticated recovery rate documentation through third-party audit trails to satisfy procurement criteria.
- Packaging Reuse:Design and operation of pooling systems for returnable transport containers.
- Emission Reduction:Carbon accounting and optimization of logistics network energy intensity.
- Resource Optimization:System-wide efficiency improvements in material and energy throughput.
Material recovery holds established infrastructure. Product lifecycle management is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive manufacturers and electronics retailers concentrate procurement demand in jurisdictions with binding extended producer responsibility frameworks, creating distinct regional adoption curves for circular logistics services.
Germany
Battery recovery networks and closed-loop automotive programs dominate service procurement. The KBA enforces EU battery passport regulations that mandate traceable material flows through reverse logistics infrastructure. Stuttgart and Wolfsburg industrial clusters anchor specialized fleet management contracts for OEM remanufacturing operations.
Netherlands
Packaging reuse pooling systems and material recovery facilities attract mid-sized logistics providers seeking cloud-based deployment models. REACH compliance deadlines from ECHA drive chemical substance traceability investments. Eindhoven and Rotterdam harbor zones consolidate refurbishment hubs for electronics component preprocessing.
United States
Electronics retailers and third-party operators expand circular capability upgrades to satisfy evolving EPA e-waste recovery thresholds. State-level regulatory fragmentation complicates multinational service deployments. California and Texas metropolitan markets lead in warehouse optimization contracts for product lifecycle management platforms.
France
Industrial manufacturers facing CSRD disclosure requirements procure sustainability reporting modules embedded in logistics contracts. The EU Green Deal's extended producer responsibility frameworks shape procurement criteria. Lyon and Paris industrial basins concentrate demand for digital twin modeling of remanufacturing network architecture.
China
Electronics manufacturers and packaging suppliers invest in automated sorting infrastructure to align with dual carbon goals and evolving national standards. MEE regulations on circular economy pilot zones accelerate material recovery platform deployment. Yangtze River Delta industrial clusters drive concentrated demand for AI-driven returns forecasting systems.
Circular Economy Logistics Design and Implementation Services Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where scale advantages separate enterprise-facing integrators from mid-market SaaS providers. The vendor base organizes around three strategic archetypes: management consultancies with cloud-based analytics platforms, specialized logistics operators with dedicated fleet assets, and industrial technology providers with energy-efficient infrastructure expertise. Competitive moves concentrate on strategic partnerships for technology licensing and portfolio diversification into compliance-automation modules.
Within the consultancy archetype, Accenture anchors enterprise-facing digital infrastructure deployments. DHL occupies a position among specialized logistics operators with asset-heavy reverse network capabilities. Schneider Electric exemplifies the industrial technology tier through integrated warehouse optimization offerings. These three represent distinct competitive vectors rather than direct substitutes, with procurement decisions hinging on whether buyers prioritize analytical modeling, physical asset control, or energy-system integration.
| Leading Market Players |
|---|
| Accenture |
| DHL |
| Walmart |
| Unilever |
| Schneider Electric |
| Philips |
| Ricoh |
| Bosch |
| Tomra Systems |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in modular sorting infrastructure across Northern Europe compresses margins for warehouse optimization providers while forcing asset-heavy operators toward outcome-based contract structures. German fleet management specialists respond by embedding carbon-accounting modules into long-term service agreements, converting capital expenditure into recurring revenue streams.
Pricing Analysis
Cost-plus contracts with fuel-indexed adjustments dominate fleet management procurement for automotive battery recovery networks. Three-tier pricing structure across premium, standard, and economy levels separates digital twin-enabled advisory from commodity transport coordination. Price differentiation hinges on ISO 14001 certification tier and embedded regulatory reporting automation. Pricing pressure stems from mid-sized packaging suppliers adopting SaaS platforms to bypass capital-intensive infrastructure investments. Third-party logistics providers exhibit highest price sensitivity, while German OEMs prioritize verified material recovery rates over unit cost benchmarks.
Supply Chain Analysis
Extended payment terms from German automotive manufacturers strain working capital for specialized reverse logistics operators, accelerating adoption of supply-chain finance facilities. Equipment manufacturing concentrates in Germany, the Netherlands, and China, with IoT sensor hardware sourcing from Taiwanese component suppliers. Raw material dependencies include lithium-ion battery cells, automated sorting robotics, and cloud computing infrastructure. Single-source vulnerability runs through specialized remanufacturing tooling sourced from Stuttgart industrial clusters. Distribution runs through direct OEM contracting for enterprise accounts and partner-channel arrangements for mid-market packaging suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sustainability reporting modules attach to core logistics contracts at faster expansion rates than hardware deployment, converting one-time network design fees into recurring compliance-automation revenue. This service-attach dynamic restructures buyer relationships toward multi-year subscription frameworks.
For Market Incumbents: Harden API interoperability with legacy ERP systems to defend against cloud-native entrants targeting mid-sized manufacturers. Extend backward integration into IoT-enabled sorting hardware to capture margin from automated material recovery infrastructure. Accenture and DHL anchor positions through platform stickiness and fleet asset control respectively.
For New Entrants and Emerging Players: French industrial clusters outside Lyon and Paris present underpenetration for digital twin modeling services ahead of CSRD disclosure deadlines. White-space concentration sits with mid-sized electronics retailers requiring authenticated recovery rate documentation without enterprise-scale infrastructure investment. Target cloud-based deployment models with outcome-based pricing tied to verified emissions reductions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among SaaS logistics platforms serving packaging reuse pooling systems, offering visibility into five-to-ten-year contract renewal cycles. Acquisition priority targets hybrid technology-operations providers with embedded regulatory reporting capabilities. Monitor EU battery passport enforcement timelines as inflection indicator for contract velocity in automotive vertical.
| Strategic Initiative | Industry Significance |
|---|---|
| API Interoperability Investment | Reduces implementation timelines for legacy ERP integration in industrial manufacturing. |
| Backward Integration into Sorting Hardware | Captures margin from automated material recovery infrastructure for battery networks. |
| Cloud-Native Platform Launch | Targets mid-sized packaging suppliers seeking SaaS deployment without capital commitment. |
| Regulatory Reporting Module Development | Embeds automated compliance disclosure for EU Green Deal and REACH mandates. |
| Remanufacturing Hub Partnership | Consolidates component refurbishment demand in Dutch industrial clusters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EU regulatory databases, and customs trade records for circular economy equipment. Supply chain consulting directors, fleet operations managers at automotive OEMs, warehouse automation engineers, and sustainability compliance officers provided structured input across Germany, the Netherlands, France, and the United States. Bottom-up service provider revenue analysis triangulates against top-down market sizing from extended producer responsibility mandate scopes.
Forecast inputs include deployment model adoption curves, regulatory deadline sequencing, and technology substitution rates across the projection horizon. Segmentation dimensions encompass service type, client vertical, delivery architecture, and application focus with geographic regulatory cluster overlays. CAGRs derive from scenario-weighted projections of contract value expansion and penetration rate assumptions. Battery passport enforcement timelines and cloud platform migration velocity serve as primary demand drivers in the analytical framework.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles or EU Green Deal implementation pacing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory compliance deadlines and technology adoption S-curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Sewage Pump Market
Environment & Sustainability
End-Of-Pipe Air Pollution Control Equipment Market
Environment & Sustainability
Europe Biochar Market
Environment & Sustainability
Water Treatment Ozone Generator Market
Environment & Sustainability
Asia-Pacific Water Purifier Market
Environment & Sustainability
Global Waste Management Equipment Market
Environment & Sustainability
AI in Environmental Sustainability Market
Environment & Sustainability
Commercial Atmospheric Water Generator Market
Environment & Sustainability
Asia-Pacific Green Carbon Market
Environment & Sustainability
Singapore Air Purifier Market
Environment & Sustainability
Packaging Waste Recycling Market
Environment & Sustainability
Qatar Solid Waste Management Market
Environment & Sustainability
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market
Environment & Sustainability
Waste Compactor Bins Market
Environment & Sustainability
Outdoor Flooring Market
Environment & Sustainability
Recycled Waste Management Market