
 Recycling Equipment and Machinery Market | 2026-2036
Recycling Equipment and Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Recycling Equipment and Machinery Market Analysis
A shortage of mechatronics technicians is redrawing deployment timelines for automated sorting lines across Europe and North America. Danieli Centro Recycling leverages its Italian engineering base to sustain long-delivery contracts for heavy-duty metal shredding systems. Metso anchors Nordic market presence through vertical integration into wear-part supply chains. General Kinematics differentiates with vibratory processing technology that competes on energy efficiency in C&D waste applications.
Recycling equipment and machinery encompasses industrial systems engineered to reduce, separate, and prepare post-consumer or post-industrial materials for reprocessing, with throughput capacities ranging from 1 to 100+ tonnes per hour depending on material stream density and contamination levels. These systems serve the fundamental commercial purpose of converting heterogeneous waste into standardized feedstock that meets reprocessor quality specifications. Shredders and granulators occupy the largest installed base across plastic processing applications, where contamination tolerance requirements have tightened. Optical sorting technology represents the fastest-expanding segment, as near-infrared and X-ray fluorescence systems displace manual picking in e-waste treatment facilities. Magnetic separation equipment retains stable replacement demand within mature metal recycling yards, where margin pools concentrate in high-gradient rare-earth drum configurations.
The EPA enforces landfill diversion targets that shape municipal procurement specifications for mixed-waste processing capacity. The EU Green Deal and REACH compliance frameworks mandate recycled content thresholds that force manufacturing firms to validate feedstock purity through certified sorting equipment. China's NMPA and GB standards for imported recyclable purity have redirected investment toward domestic preprocessing infrastructure. Stakeholders must monitor how regulatory fragmentation between national recycling quality standards affects equipment interoperability and aftermarket service economics.
Market Dynamics
Automated optical sorting is compressing deployment timelines for municipal waste facilities as landfill diversion mandates harden across industrialized economies. Equipment buyers now prioritize throughput verification over capital cost in procurement specifications.
Growth Catalysts
- EU Green Deal circular economy mandates:Recycled content thresholds in packaging and automotive applications are forcing manufacturers to validate feedstock purity through certified sorting infrastructure.
- Near-infrared spectroscopy adoption:Plastics reclaimers are retrofitting lines with multi-sensor detection arrays to meet contamination tolerance requirements that manual sorting cannot achieve.
- German industrial cluster concentration:Advanced recycling parks in Bavaria and North Rhine-Westphalia are generating localized demand for high-capacity shredding and washing systems.
Market Restraints
- Mechatronics technician scarcity:European and North American deployment timelines extend by 4-8 months due to insufficient qualified maintenance personnel for automated line commissioning.
- Rare-earth magnet supply concentration:High-gradient drum configurations for metal recycling depend on Chinese-processed neodymium, exposing equipment margins to raw material volatility.
- GB standards compliance friction:China's purity requirements for imported recyclables have forced exporters to invest in domestic preprocessing, redirecting capital from equipment upgrades elsewhere.
Strategic Opportunities
- Construction and demolition waste streams:Vibratory processing applications in C&D represent underpenetrated territory where energy efficiency specifications are tightening faster than equipment supply.
- REACH-ESG convergence:Chemical compliance and sustainability reporting are merging into unified procurement criteria that favor equipment vendors with integrated data validation capabilities.
- AI-driven predictive maintenance:Sensor fusion and machine learning convergence enables remote diagnostics that reduce technician dispatch frequency for distributed recycling operations.
Industry Challenges
- Commissioning complexity with legacy mechanical lines:Retrofitting optical sorting into existing facilities requires custom engineering that stretches project timelines and strains integration specialist availability.
- Aftermarket service standardization gaps:Component interoperability between European, Asian, and North American equipment architectures fragments spare parts logistics and technician training programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycling Equipment and Machinery Market |
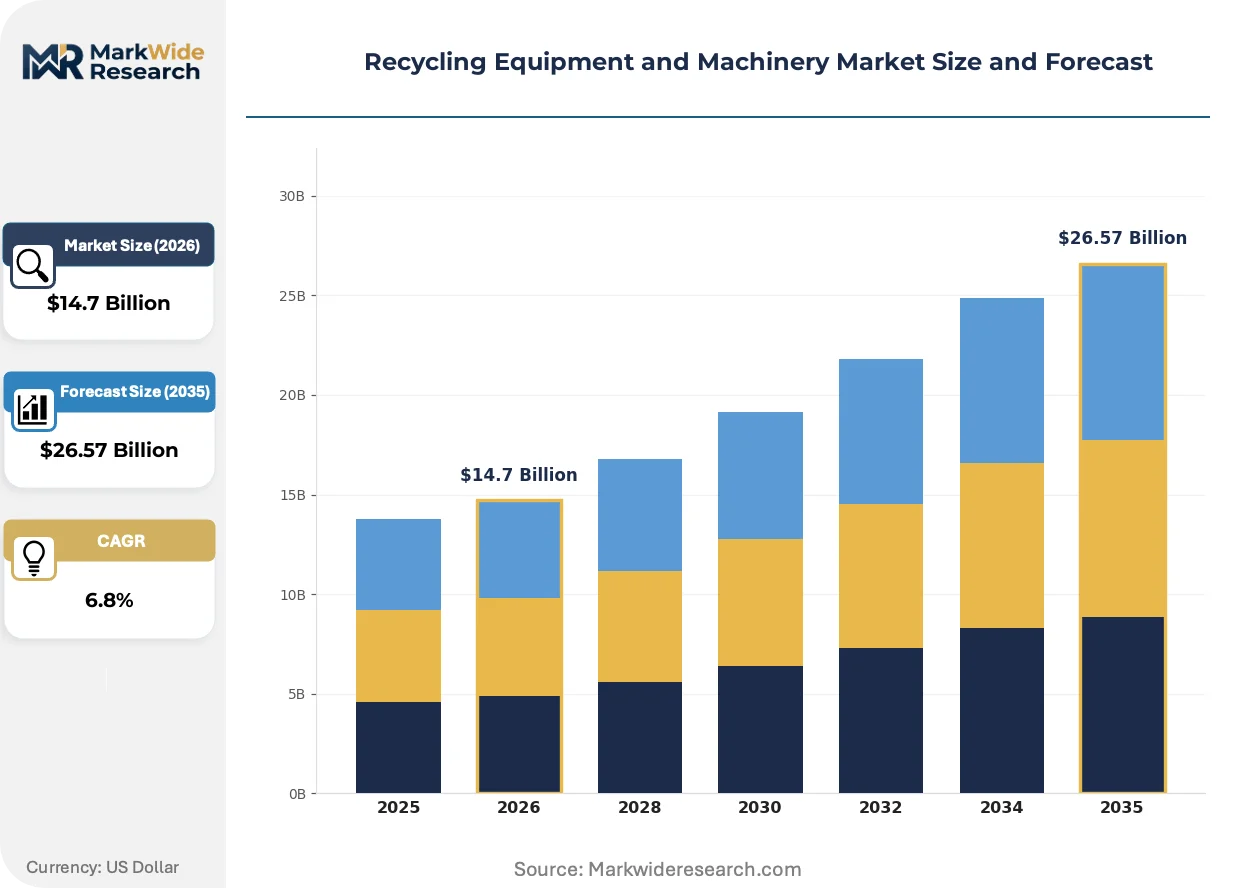
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shredders, Balers, Granulators, Crushers Application: Plastic Processing, Metal Recycling, Wood Waste Management, E-Waste Treatment Technology: Mechanical Sorting, Optical Sorting, Magnetic Separation, Aerodynamic Separation End User: Construction Companies, Manufacturing Firms, Waste Management Services, Municipalities |
| Companies Covered | The CP Group, American Baler, Danieli Centro Recycling, Lefort, General Kinematics, Metso, Eldan Recycling, BHS Sonthofen, Suny Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycling Equipment and Machinery Market Emerging Trajectories
Sensor fusion and artificial intelligence are redefining material identification accuracy while regulatory pressure on contamination thresholds accelerates equipment replacement cycles beyond traditional depreciation schedules.
Dual-energy X-ray transmission combined with deep learning classification is decomposing traditional density-based separation in e-waste processing facilities. Electronics reclaimers in Germany and Japan are deploying these systems at throughput rates exceeding 6 tonnes per hour. The technology is decomposing manual dismantling employment models while compressing payback periods for capital-intensive preprocessing investments.
REACH compliance frameworks are mandating recycled content validation through certified mass-balance accounting. Chemical manufacturers must now document feedstock provenance with equipment-generated data trails. Automotive and packaging sectors in France and Italy are responding by specifying sorting systems with integrated blockchain logging capabilities in procurement tenders.
Equipment-as-a-service contracting is displacing outright purchase for municipal waste authorities with constrained capital budgets. Danish and Swedish municipalities are piloting throughput-guarantee arrangements where vendors retain ownership and charge per-tonne processing fees. This model is most visible in Nordic markets where public sector procurement rules favor operational expenditure classification over capital debt instruments.
Recycling Equipment and Machinery Market Segmentation
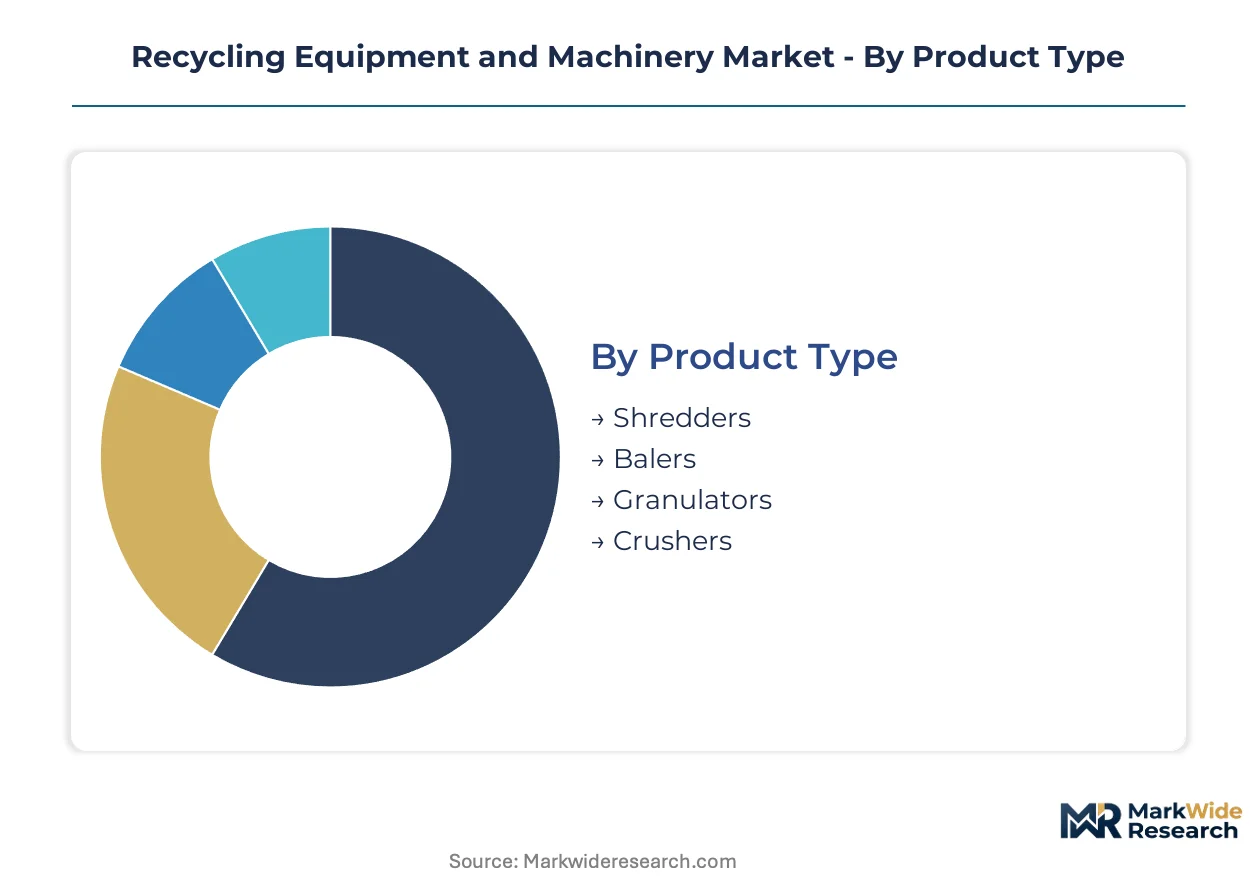
Segmentation in recycling equipment reveals how margin pools concentrate around contamination tolerance thresholds and automation intensity. Equipment buyers now prioritize throughput verification over capital cost, reshaping competitive dynamics across product categories.
Product Type:
Margin pools concentrate in high-wear components and precision cutting systems where replacement cycles generate recurring revenue streams.
- Shredders:Heavy-duty rotary and single-shaft configurations dominate plastic and metal preprocessing with throughput capacities from 1 to 100+ tonnes per hour. German industrial clusters in Bavaria and North Rhine-Westphalia drive demand for high-capacity shredding systems as advanced recycling parks expand.
- Balers:Hydraulic compression systems transform loose recyclable materials into dense, transport-ready bales. Municipal waste management services across industrialized economies are scaling automated baling investments as landfill diversion mandates tighten.
- Granulators:Precision cutting mills reduce plastic scrap to uniform pellet size for reprocessing feedstock.
- Crushers:Jaw and impact configurations process construction debris and bulk waste streams.
The dominant share belongs to shredders, while granulators are closing the gap fastest.
Application:
Cost tiers separate commodity preprocessing from high-purity feedstock validation where certification requirements command premium pricing.
- Plastic Processing:Contamination tolerance requirements have tightened dramatically for post-consumer resin. Near-infrared spectroscopy adoption is accelerating as reclaimers retrofit lines with multi-sensor detection arrays to meet specifications that manual sorting cannot achieve.
- Metal Recycling:Magnetic separation equipment retains stable replacement demand within mature yards. High-gradient rare-earth drum configurations concentrate margin pools, though Chinese-processed neodymium dependency exposes equipment margins to raw material volatility.
- Wood Waste Management:Biomass preprocessing systems serve energy recovery and panel manufacturing feedstock preparation.
- E-Waste Treatment:Dual-energy X-ray transmission combined with deep learning classification is decomposing traditional density-based separation. Electronics reclaimers in Germany and Japan deploy these systems at throughput rates exceeding 6 tonnes per hour.
Plastic processing holds the largest installed base, though e-waste treatment is expanding most quickly.
Technology:
Volume concentration favors established mechanical methods, though customer procurement is shifting toward sensor-based validation systems.
- Mechanical Sorting:Screens, trommels, and density-based separators remain the workhorse infrastructure across municipal facilities. Legacy mechanical lines face commissioning complexity when retrofitting optical sorting, stretching project timelines.
- Optical Sorting:Near-infrared and X-ray fluorescence systems displace manual picking across e-waste and plastic applications. The EU Green Deal's recycled content thresholds are forcing manufacturers to validate feedstock purity through certified sorting infrastructure.
- Magnetic Separation:Ferrous and non-ferrous recovery systems maintain steady demand in metal recycling yards.
- Aerodynamic Separation:Air classification systems separate light fractions from dense materials in mixed waste streams.
Mechanical sorting maintains volume leadership, yet optical sorting is gaining share fastest.
End User:
Maturity curves diverge sharply between capital-constrained public entities and manufacturing firms facing regulatory compliance deadlines.
- Construction Companies:C&D waste applications represent underpenetrated territory where energy efficiency specifications are tightening faster than equipment supply. Vibratory processing technology competes on energy efficiency in these applications.
- Manufacturing Firms:REACH compliance frameworks mandate recycled content validation through certified mass-balance accounting. Automotive and packaging sectors in France and Italy specify sorting systems with integrated blockchain logging capabilities.
- Waste Management Services:Private operators balance throughput guarantees against operational expenditure constraints.
- Municipalities:Equipment-as-a-service contracting is displacing outright purchase where capital budgets are constrained. Danish and Swedish municipalities pilot throughput-guarantee arrangements with per-tonne processing fees.
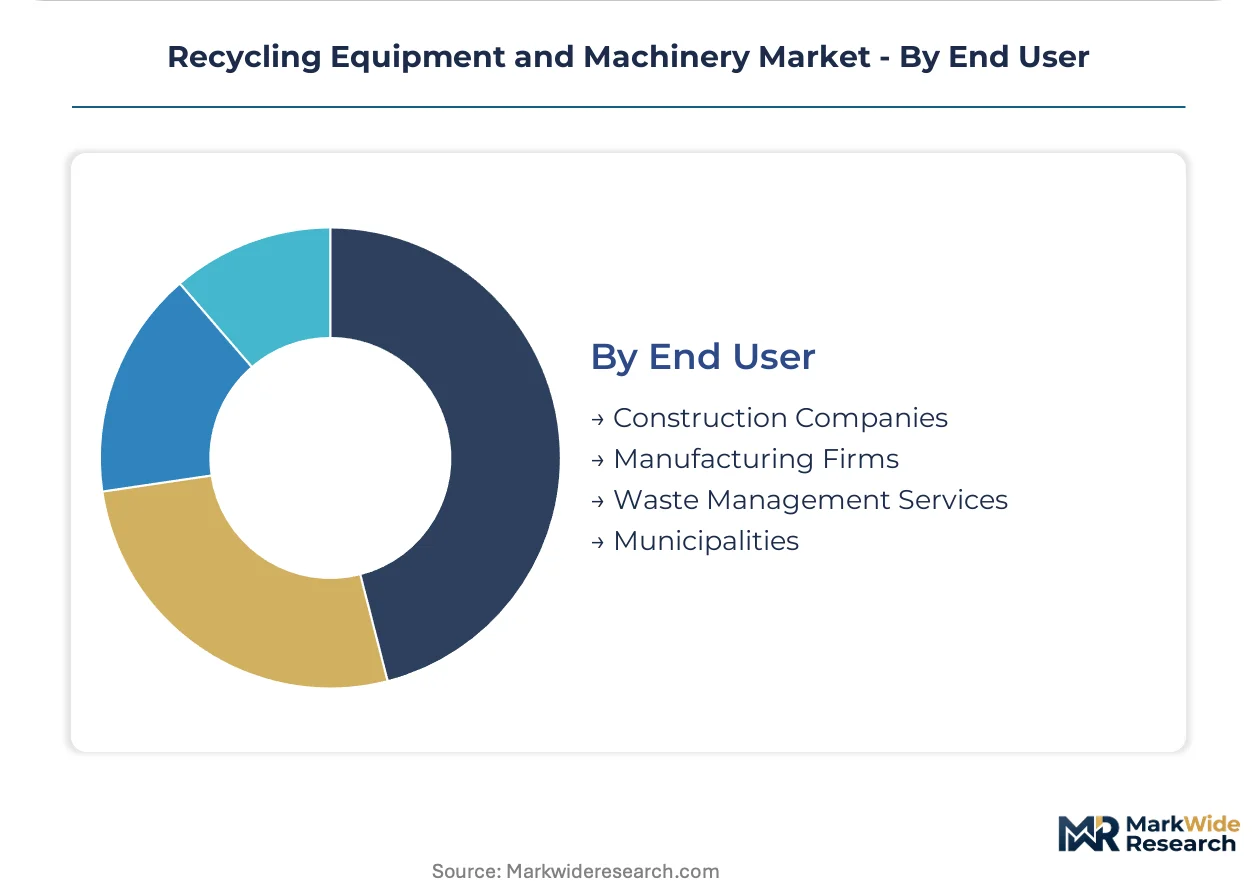
Waste management services command the dominant share, while municipalities are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment deployment patterns diverge sharply across geographies. German operators prioritize high-throughput shredding for industrial feedstock preparation. Chinese investment concentrates on preprocessing infrastructure to meet domestic purity standards. Nordic municipalities pioneer service-based contracting models.
United States
EPA landfill diversion targets drive municipal procurement for mixed-waste processing capacity. The agency enforces contamination thresholds that force equipment upgrades in legacy facilities. California and Texas lead deployment of automated baling and sorting systems as diversion mandates tighten.
Germany
Advanced recycling parks in Bavaria and North Rhine-Westphalia generate localized demand for high-capacity shredding and washing systems. The EU Green Deal's circular economy action plan accelerates equipment replacement cycles beyond traditional depreciation schedules. Electronics reclaimers deploy dual-energy X-ray transmission systems at throughput rates exceeding 6 tonnes per hour.
China
NMPA and GB standards for imported recyclable purity redirect investment toward domestic preprocessing infrastructure. The country's dual carbon goals compress timelines for energy-efficient equipment deployment. Yangtze River Delta and Pearl River Delta clusters concentrate optical sorting investments as exporters retool for compliance.
Japan
METI industrial policy supports e-waste treatment facility upgrades with sensor-based validation systems. JIS standards for recycled material quality drive procurement specifications for certified sorting infrastructure. Kansai and Chubu regions host dense concentrations of plastics reclaimers retrofitting lines with multi-sensor detection arrays.
Sweden
Danish and Swedish municipalities pilot equipment-as-a-service contracting with throughput-guarantee arrangements. Public sector procurement rules favor operational expenditure classification over capital debt instruments. Stockholm and Gothenburg anchor Nordic adoption of per-tonne processing fee models.
Recycling Equipment and Machinery Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in this market. Heavy-duty metal shredding and vibratory processing applications concentrate among engineering-centric fabricators with captive supply chains. Strategic archetypes include Italian engineering-base operators, Nordic vertical integrators, and North American vibratory technology specialists. Competitive moves center on wear-part supply chain control and energy efficiency differentiation in construction and demolition applications.
Among European engineering specialists, Danieli Centro Recycling and Metso occupy positions reflecting distinct geographic and integration strategies. Danieli Centro Recycling leverages its Italian base to sustain long-delivery contracts for heavy-duty systems. Metso anchors Nordic market presence through in-house production of wear-part supply chains. General Kinematics represents North American vibratory processing expertise competing on energy efficiency specifications.
| Leading Market Players |
|---|
| The CP Group |
| American Baler |
| Danieli Centro Recycling |
| Lefort |
| General Kinematics |
| Metso |
| Eldan Recycling |
| BHS Sonthofen |
| Suny Group |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German shredding system manufacturers sits above 85 percent, compressing delivery timelines and elevating price floors for high-tonnage configurations. This scale concentration in Bavaria and North Rhine-Westphalia industrial clusters simultaneously tightens supply availability and hardens procurement leverage for buyers seeking rapid deployment.
Pricing Analysis
Long-term offtake contracts dominate municipal procurement, with throughput-guarantee arrangements displacing spot purchases among Danish and Swedish waste authorities. Price differentiation separates CE-certified optical sorting systems from standard mechanical configurations, while aftermarket service bundling commands additional premiums. Cost compression in mid-tier baler equipment is intensifying because Chinese preprocessing infrastructure investments redirect capital from equipment upgrades elsewhere. Municipal buyers exhibit highest price sensitivity due to capital budget constraints, whereas automotive manufacturers facing REACH deadlines prioritize certification over cost.
Supply Chain Analysis
Chinese-processed neodymium for high-gradient magnetic drums represents a critical chokepoint, with 70 percent of rare-earth magnet processing concentrated in Jiangxi and Inner Mongolia. Equipment fabrication draws from German precision engineering, Italian heavy-metal fabrication, and Chinese component assembly. Single-source vulnerability in rare-earth supply exposes margins to export restriction risks. Distribution runs through OEM direct sales for large municipal contracts and specialized dealer networks for aftermarket wear-part replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recycling equipment deployment sits in early-cycle expansion as landfill diversion mandates harden across industrialized economies, with EU Green Deal recycled content thresholds forcing manufacturing validation infrastructure buildouts.
For Market Incumbents: Consolidate control over wear-part supply chains through backward integration into rare-earth magnet sourcing or captive production of high-wear shredding components. Danieli Centro Recycling and Metso demonstrate how engineering-base concentration and in-house supply chain control defend margin pools against price erosion from Asian component suppliers.
For New Entrants and Emerging Players: CE marking fast-track for AI-driven predictive maintenance modules offers entry into fragmented municipal service markets. Construction and demolition waste vibratory processing remains underpenetrated, with energy efficiency specifications tightening faster than established supply. Partner with equipment-as-a-service platforms to bypass capital-sales barriers among budget-constrained municipalities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor fusion specialists with proven deployment at 6-tonnes-per-hour throughput rates. Long-term viability hinges on software-enabled service revenue streams rather than hardware depreciation cycles. Monitor GB standards compliance friction as inflection indicator for domestic preprocessing infrastructure investment waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Reduces exposure to Chinese neodymium price volatility for drum separator manufacturers. |
| AI-Driven Predictive Maintenance Platform Launch | Enables remote diagnostics that reduce mechatronics technician dispatch frequency across distributed operations. |
| Throughput-Guarantee Service Contracting | Aligns vendor incentives with municipal operational expenditure classification preferences in Nordic markets. |
| Dual-Energy X-Ray Transmission Certification | Validates e-waste processing purity for EU Green Deal compliance in German and Japanese facilities. |
| Construction Waste Vibratory Processing Expansion | Captures energy efficiency premiums in C&D applications where specifications outpace equipment supply. |
Methodological Framework
Operator-level perspectives from maintenance directors at municipal waste facilities, aftermarket service heads at shredding system OEMs, plant engineers at plastics reclaimers, and procurement leads at automotive manufacturers anchored the qualitative base. These primary interviews combined with customs trade data on equipment imports, EPA enforcement action records, EU Green Deal implementation progress reports, and SEC filings from publicly traded machinery manufacturers. Bottom-up capacity estimates triangulated against top-down market sizing from national waste diversion statistics.
Sensitivity analysis tested forecast robustness across scenarios for rare-earth magnet price volatility, mechatronics technician availability, and landfill diversion mandate acceleration. Segmentation modeling tracked product type, application, technology, and end-user dimensions alongside regional regulatory cluster variations. CAGRs derived from equipment replacement cycle analysis, capacity expansion announcements, and procurement pipeline visibility across the projection horizon. Near-infrared spectroscopy adoption curves and X-ray fluorescence deployment rates served as technology-specific validation inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement, stable rare-earth supply chains, or continued municipal capital access would require recalibration. Forecasts reflect documented assumptions about regulatory trajectory and technology cost curves. Practitioners should keep alternative scenarios live as Chinese GB standards compliance requirements and technician training pipeline expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Waste Management
PET Bottle Recycling Market
E-Waste Management
Smart Waste Collection Market
E-Waste Management
Release Liner Recycling Market
E-Waste Management
Packaging Waste Recycling Market
E-Waste Management
Solar Trash Compactors Market
E-Waste Management
North America E-Waste Management Market
E-Waste Management
Europe E-Waste Management Market
E-Waste Management
Global E-Waste Recycling and Reuse Service Market
E-Waste Management
Smart Waste Management Market
E-Waste Management
Solar Panel Recycling Management Market
E-Waste Management
APAC E-Waste Management Market
E-Waste Management
Electronic Waste Recycling Market
E-Waste Management
Lithium-Ion Battery Reuse and Recycling Market
E-Waste Management
Aluminum Cans Recycling Market
E-Waste Management
E-Scrap Recycling Market
E-Waste Management
Electronic Scrap Recycling Market