
 Latin America Public Infrastructure Safety Market | 2026-2036
Latin America Public Infrastructure Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Public Infrastructure Safety Market Insights
Fragmentation among transportation authorities and utility providers across Latin America is recalibrating vendor engagement models, forcing suppliers to diversify channel structures. Cisco Systems leverages its networking infrastructure footprint to anchor smart city deployments across major metropolitan zones. Genetec Inc. competes through video management specialization for critical bridge and tunnel monitoring. Hexagon AB sustains geographic dominance via geospatial analytics platforms tailored to seismic-prone infrastructure corridors.
Latin America public infrastructure safety encompasses engineered systems, sensor networks, and analytical platforms designed to monitor structural integrity, detect anomalies, and coordinate emergency response across transportation, water, and energy assets. These systems typically integrate IoT sensors with sub-millimeter displacement detection thresholds and real-time telemetry to prevent catastrophic failure. Inspection services command established budget allocations from aging bridge inventories, while AI analytics represents the fastest-expanding technology segment as agencies automate crack detection and predictive degradation modeling. Monitoring solutions for water supply infrastructure occupy concentrated margin pools where leakage detection contracts bundle hardware with long-term service agreements.
Brazil's ANTT and Mexico's SCT enforce structural assessment mandates that directly shape procurement specifications for roadway and railway monitoring systems. ISO 55000 asset management standards and national seismic codes in Chile and Peru further condition product certification requirements and market access thresholds. Stakeholders must weigh regulatory divergence against platform standardization when allocating R&D across multi-country deployment strategies.
Market Dynamics
AI-powered predictive maintenance is compressing inspection cycles across Latin America's aging bridge and tunnel networks, forcing asset owners to reallocate capital from reactive repairs toward continuous monitoring infrastructure.
Growth Catalysts
- Brazil's ANTT structural mandates:Federal requirements for roadway asset assessment are expanding procurement volumes for displacement sensors and telemetry systems across the southeastern corridor.
- Seismic code enforcement:Chile and Peru are tightening national building standards for infrastructure resilience, accelerating certification demand for geospatial monitoring platforms in fault-adjacent corridors.
- IoT sensor maturation:Sub-millimeter crack detection thresholds now achievable at utility-scale price points are enabling network-wide deployment across water distribution and energy transmission assets.
Market Restraints
- Import dependency for precision sensors:Regional production gaps force reliance on East Asian component suppliers, exposing procurement timelines to shipping volatility and currency fluctuation.
- Interoperability gaps:Proprietary data formats from incumbent monitoring vendors create lock-in effects that delay multi-asset platform consolidation.
- Fiscal constraint cycles:Brazilian state-level budget compression periodically freezes infrastructure technology refresh programs despite federal mandate pressure.
Strategic Opportunities
- Colombia's underpenetrated Andean corridor:Tunnel and hydroelectric monitoring deployment lags regional peers, creating first-mover terrain for integrated platform vendors.
- AI-video convergence:Machine vision for surface defect detection is merging with thermal imaging analytics, opening unified procurement bundles for bridge and pipeline operators.
- Long-term service contracting:Leakage detection mandates in São Paulo and Mexico City are shifting hardware sales toward decade-spanning performance agreements with embedded sensor refresh cycles.
Industry Challenges
- Geotechnical-AI skill scarcity:The intersection of civil engineering domain knowledge and machine learning implementation expertise remains concentrated in São Paulo and Mexico City consulting pools.
- Legacy SCADA integration friction:Water utility operators face multi-year migration timelines when connecting new IoT sensor layers to decades-old control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Public Infrastructure Safety Market |
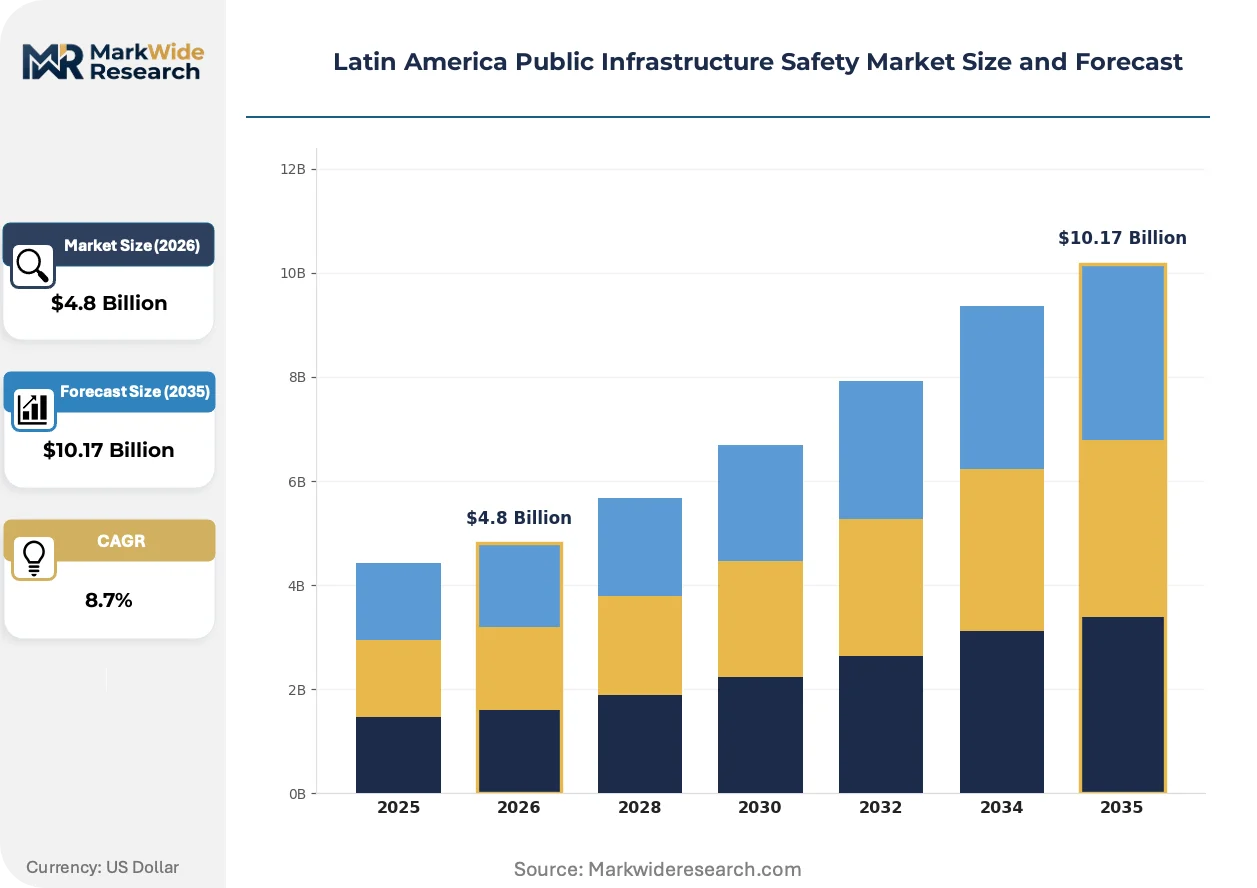
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection Services, Monitoring Solutions, Emergency Response, Safety Audits End User: Government Agencies, Construction Firms, Transportation Authorities, Utility Providers Technology: IoT Sensors, AI Analytics, Drones, Geographic Information Systems Application: Roadways, Bridges, Railway Systems, Water Supply Infrastructure |
| Companies Covered | Cisco Systems, Inc., Genetec Inc., Esri Global, CGI Inc., ALE International Inc., Raytheon Co., Lockheed Martin Corporation, General Dynamics Corporation, Hexagon AB, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Public Infrastructure Safety Market Trends and Innovations
Digital twin technology is penetrating Latin American infrastructure management, creating real-time virtual replicas that compress decision latency from months to hours for critical asset interventions.
Computer vision algorithms trained on concrete degradation patterns are automating crack classification across Brazilian federal highway networks. ANTT contractors are piloting these systems at forty bridge sites spanning Paraná and Santa Catarina. The technology is automating inspector dispatch prioritization, reducing manual assessment cycles from quarterly to continuous coverage without proportional staff expansion.
Mexico's SCT is revising concession contract language to mandate real-time structural data sharing with federal databases. This regulatory pivot forces private toll operators to standardize sensor output formats and telemetry protocols. The policy shift most acutely affects the Mexico City-Querétaro corridor, where concession holders are accelerating platform upgrades to meet 2026 compliance windows.
Performance-based contracting is displacing capital expenditure procurement for water leakage detection in São Paulo metropolitan utilities. Contractors now assume sensor ownership and maintenance burden, monetizing through verified water loss reduction rather than hardware margins. This model is concentrating vendor selection authority among three state-level water companies controlling sixty percent of Brazil's treated water distribution volume.
Latin America Public Infrastructure Safety Market Segmentation
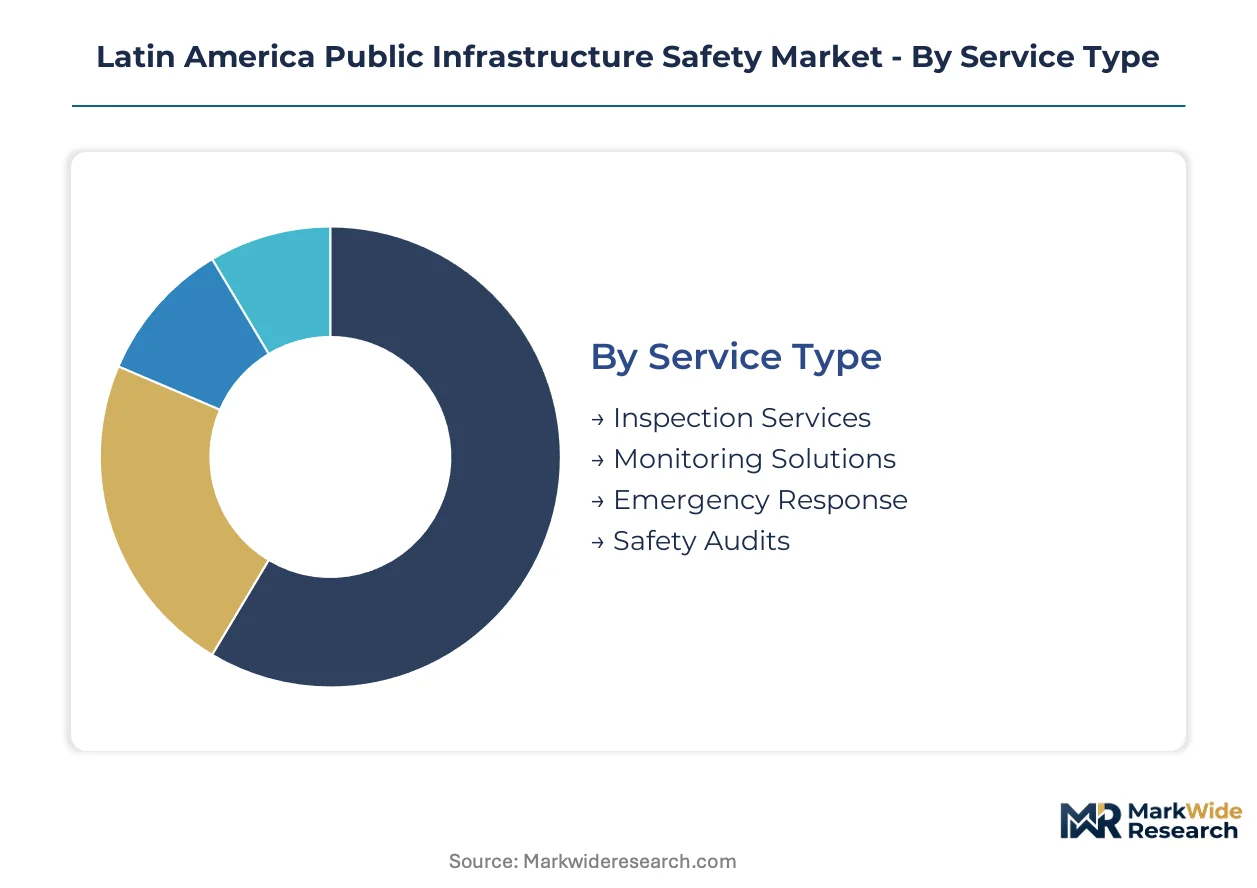
Segmentation in Latin American infrastructure safety reveals how procurement authority fragments across government tiers and how technology maturity varies by asset type. Vendors must calibrate pricing and partnership models to these structural divides rather than applying uniform go-to-market strategies.
Service Type:
Supply concentration in sensor manufacturing and telemetry platforms is reshaping how service providers bundle hardware with recurring revenue streams across the region.
- Inspection Services:Manual and semi-automated structural assessments conducted by certified engineers remain the baseline procurement category for aging bridge inventories. Brazilian state DOTs in São Paulo and Minas Gerais maintain dedicated inspection budgets under ANTT federal guidelines, though staffing gaps compress cycle frequencies.
- Monitoring Solutions:Continuous sensor networks with real-time telemetry represent the technology frontier, displacing periodic inspections in critical corridor deployments. Chile's seismic code enforcement and Mexico's SCT concession mandates are accelerating displacement sensor procurement for fault-adjacent bridges and toll road networks.
- Emergency Response:Coordinated dispatch systems integrating structural failure alerts with civil defense protocols. Colombian Andean corridor tunnel operators are piloting automated closure systems tied to geotechnical trigger thresholds.
- Safety Audits:Compliance documentation services tied to ISO 55000 certification requirements and national regulatory frameworks. Peruvian water utilities increasingly bundle audit obligations with long-term monitoring contracts.
Inspection Services absorbs the bulk of installed capacity; Monitoring Solutions is expanding most quickly.
End User:
Customer type determines contract structure, with government mandates driving standardization while private operators retain flexibility for integrated platform selection.
- Government Agencies:Federal and state transportation departments control procurement through regulatory mandate compliance. Brazil's ANTT and Mexico's SCT specify technical requirements that cascade to concession holders and municipal operators.
- Construction Firms:Project-phase safety systems deployed during major infrastructure builds, with handover protocols to permanent operators. Santiago and Bogotá metro extensions are embedding sensor infrastructure into construction contracts.
- Transportation Authorities:Operating entities managing roadway and rail networks with direct responsibility for structural integrity. São Paulo's metropolitan rail operator CPTM is consolidating legacy monitoring systems under unified telemetry platforms.
- Utility Providers:Water and energy transmission operators with concentrated demand for leakage detection and pipeline integrity systems. SABESP and Mexico City's SACMEX are shifting toward performance-based sensor service contracts.
Utility Providers concentrate margin capture through long-term agreements; Government Agencies dominate absolute procurement volume.
Technology:
Cost tier differentiation separates premium AI-analytics platforms from commodity sensor hardware, with integration capabilities becoming the decisive vendor selection criterion.
- IoT Sensors:Sub-millimeter displacement detection devices and environmental monitors forming the physical layer of infrastructure networks. Brazilian federal highway contracts now specify IP67-rated devices with 10-year operational lifespans for tropical climate exposure.
- AI Analytics:Machine learning platforms automating crack classification, degradation prediction, and anomaly detection from multi-source data feeds. ANTT contractors at forty Paraná bridge sites are piloting computer vision systems that compress assessment cycles from quarterly to continuous coverage.
- Drones:Aerial inspection platforms for inaccessible structural elements and rapid post-event damage surveys. Chilean concession operators deploy thermal-imaging drones across the Pan-American Highway corridor.
- Geographic Information Systems:Spatial data platforms integrating sensor telemetry with seismic risk mapping and asset registries. Hexagon AB maintains regional dominance through fault-zone corridor deployments in Peru and Chile.
IoT Sensors represent the foundational installed base; AI Analytics is gaining share fastest through regulatory automation mandates.
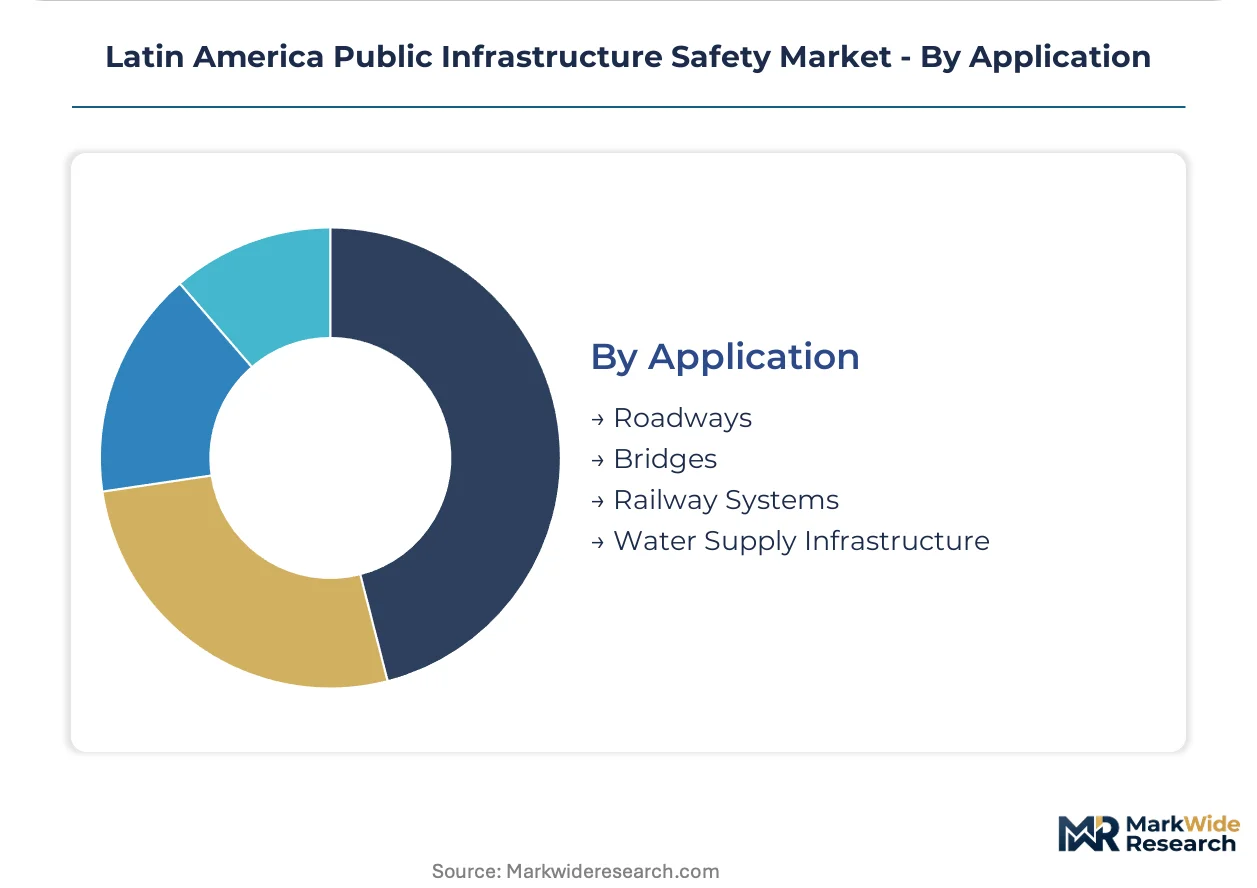
Application:
Volume concentration in roadway networks creates scale economies, while specialized applications in water and rail command premium pricing for domain-specific expertise.
- Roadways:Federal and state highway monitoring encompassing pavement condition, tunnel ventilation, and slope stability systems. Brazil's southeastern corridor spanning São Paulo to Rio de Janeiro concentrates deployment density and vendor competition.
- Bridges:Structural health monitoring for suspension, cable-stayed, and viaduct assets with displacement sensor networks and load testing protocols. ANTT regulations mandate assessment frequencies that scale with traffic volume and structural age.
- Railway Systems:Track geometry monitoring, tunnel clearance detection, and overhead line inspection for passenger and freight networks. Mexico's SCT is revising concession language to mandate real-time structural data sharing with federal databases.
- Water Supply Infrastructure:Leakage detection, pressure monitoring, and pipeline integrity systems for treated water distribution. São Paulo metropolitan utilities are displacing capital expenditure procurement with decade-spanning performance agreements.
Roadways anchor the majority of deployed systems; Water Supply Infrastructure is climbing the fastest as leakage reduction mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority fragments across federal transportation departments, state-level DOTs, and metropolitan utility operators, with Brazil and Mexico commanding the dominant share of displacement sensor and telemetry system deployment.
Brazil
ANTT structural assessment mandates cascade to state-level operators across São Paulo, Minas Gerais, and Paraná, expanding displacement sensor procurement for aging viaduct inventories. Federal guidelines specify IP67-rated devices with decade-long operational lifespans for tropical climate exposure. The southeastern corridor anchoring São Paulo to Rio de Janeiro concentrates vendor competition and deployment density for bridge monitoring networks.
Mexico
SCT concession contract revisions mandate real-time structural data sharing with federal databases, forcing toll operators toward standardized telemetry protocols. The Mexico City-Querétaro corridor faces accelerated platform upgrade timelines to meet 2026 compliance windows. Private operators in this corridor are consolidating legacy monitoring architectures under unified data exchange frameworks.
Chile
National seismic code enforcement accelerates certification demand for geospatial monitoring platforms across fault-adjacent infrastructure corridors. The Pan-American Highway concession operators deploy thermal-imaging drones and displacement sensors under tightened building resilience standards. Santiago metro extension projects embed sensor infrastructure directly into construction handover protocols.
Colombia
Andean corridor tunnel and hydroelectric monitoring deployment lags regional peers, creating first-mover terrain for integrated platform vendors. The country's national infrastructure agency is revising concession language to mandate automated closure systems tied to geotechnical trigger thresholds. Bogotá metro extensions are embedding structural health monitoring into construction-phase safety systems.
Peru
National seismic regulations condition product certification requirements for fault-zone corridor deployments, with water utilities increasingly bundling ISO 55000 audit obligations with long-term monitoring contracts. Metropolitan Lima's treated water distribution operators are shifting toward performance-based sensor service agreements. The coastal seismic belt drives concentrated demand for geospatial analytics platforms from international specialists.
Latin America Public Infrastructure Safety Market Competitive Landscape
North American networking and defense conglomerates anchor one tier; European geospatial and video management specialists hold differentiated positions in seismic monitoring and critical infrastructure visualization. The vendor base stratifies across three archetypes: diversified technology platforms with smart city deployment capabilities, domain-specific monitoring specialists, and defense-industrial contractors repurposing surveillance architectures. Consolidation pressure concentrates among sensor hardware suppliers facing utility-scale pricing compression, while platform vendors pursue strategic partnerships to bridge legacy SCADA integration gaps.
Within the diversified technology tier, Cisco Systems, Inc. exemplifies the networking infrastructure archetype anchoring metropolitan smart city deployments, while Genetec Inc. occupies a specialist position in video management systems for critical bridge and tunnel monitoring. Hexagon AB represents the geospatial analytics archetype sustaining regional presence through seismic-prone corridor deployments. These three companies illustrate how competitive positioning diverges between horizontal platform breadth and vertical application depth across Latin American procurement structures.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Genetec Inc. |
| Esri Global |
| CGI Inc. |
| ALE International Inc. |
| Raytheon Co. |
| Lockheed Martin Corporation |
| General Dynamics Corporation |
| Hexagon AB |
| Others |
Pricing and Supply Chain Analysis
AI-powered crack detection maturation at utility-scale price points simultaneously compresses hardware margins and consolidates procurement authority among Brazilian state water companies and Mexican federal concession holders. This technological inflection redraws supplier economics by shifting revenue capture from equipment sales toward decade-spanning performance agreements with embedded sensor refresh cycles.
Pricing Analysis
Volume concentrates in commodity IoT sensors while margin pools accrue to AI analytics platforms and long-term service contracts. Price differentiation hinges on ISO 55000 certification tier and after-sales telemetry bundling. Pricing pressure intensifies in displacement sensor hardware as East Asian component suppliers flood utility-scale tenders. Government agencies exhibit highest price sensitivity due to fiscal constraint cycles, while private toll operators under SCT mandate pressure show greater willingness to absorb premium platform costs.
Supply Chain Analysis
Dual-sourcing requirements from ANTT and SCT procurement specifications force qualified vendor lists spanning East Asian component suppliers, European geospatial analytics providers, and North American platform integrators. Raw material dependencies center on precision MEMS sensors, fiber-optic strain gauges, and ruggedized telemetry enclosures. Supply chain risk concentrates in shipping volatility across Pacific routes and currency fluctuation exposure. Distribution runs through federal transportation departments cascading mandates to state DOTs and metropolitan utility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where Brazil's ANTT structural assessment mandates erect regulatory moats favoring certified incumbents with established federal contractor status.
For Market Incumbents: Acquire AI-analytics capabilities to defend against pure-play computer vision entrants automating crack classification. Consolidate sensor manufacturing partnerships in Taiwan and South Korea to secure component supply amid shipping volatility. Deepen vertical integration into long-term service contracting to lock out hardware-only competitors. For New Entrants and Emerging Players: Enter via Colombia's underpenetrated Andean corridor where tunnel and hydroelectric monitoring deployment lags regional peers. Target leakage detection mandates in São Paulo metropolitan utilities shifting toward performance-based procurement. Lead with unified platform pitches bridging legacy SCADA integration gaps that incumbents struggle to address. For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays as sensor hardware commoditization pressures mid-tier suppliers. Long-term viability favors vendors with captive federal contractor relationships and recurring revenue concentration. Monitor SCT concession compliance deadlines as inflection indicators for platform upgrade spending waves.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Analytics Acquisition | Computer vision automation at ANTT bridge sites compresses inspection cycles and displaces manual assessment revenue pools. |
| Long-Term Service Contracting | Performance-based leakage detection agreements with SABESP and SACMEX shift hardware margins to decade-spanning recurring revenue. |
| Geospatial Platform Integration | Seismic code enforcement in Chile and Peru drives certification demand for fault-zone corridor monitoring deployments. |
| SCADA Modernization Partnership | Legacy control architecture migration opens multi-year integration timelines for water utility operators across São Paulo. |
| Dual-Sourcing Qualification | East Asian component supplier diversification reduces procurement timeline exposure to shipping volatility and currency fluctuation. |
Research Methodology
Multi-period observation of ANTT procurement volumes, SCT concession compliance timelines, and seismic code enforcement trajectories anchored the trend analysis, supplemented by interviews with federal transportation planning officers, state DOT procurement leads, water utility engineering directors, and concession operator asset managers. Secondary validation drew from ANTT regulatory filings, SCT concession contract revisions, Chilean seismic building code updates, and ISO 55000 certification databases. Bottom-up sensor deployment tallies triangulated against top-down infrastructure budget allocations across the analysis window.
Input-output matrices modeled volume and value projections across service type, end user archetype, technology tier, and application segment throughout the forecast period. CAGRs derived from regression analysis of historical procurement cycles against regulatory mandate acceleration curves. Industry-specific forecast inputs incorporated AI-analytics adoption rates at federal bridge inspection sites and performance-based contracting penetration in metropolitan water utilities.
Revisions become necessary when Brazilian state-level fiscal constraint cycles deepen, Mexican concession compliance deadlines shift, or East Asian component supply disruptions materialize. Deviation in ANTT mandate enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Blast Resistant and Bulletproof Buildings Market
Critical Infrastructure Protection
Tank Protection Market
Critical Infrastructure Protection
Global Perimeter Protection Market
Critical Infrastructure Protection
Insider Threat Protection Market
Critical Infrastructure Protection
Asia Pacific Tank Protection Market
Critical Infrastructure Protection
North America Tank Protection Market
Critical Infrastructure Protection
Asia-Pacific Public Infrastructure Safety Market
Critical Infrastructure Protection
Europe Pipeline Security Market
Critical Infrastructure Protection
Smart Sandbag Market
Critical Infrastructure Protection
Counter Cyberterrorism Market
Critical Infrastructure Protection
UK Critical Infrastructure Protection Market
Critical Infrastructure Protection
Utilities Security Market
Critical Infrastructure Protection
Critical Infrastructure Monitoring Market
Critical Infrastructure Protection
Perimeter Defense System Market
Critical Infrastructure Protection
Infrastructure Protection Market
Critical Infrastructure Protection
Continuous Threat Exposure Management Market