
 Europe Cargo and Vehicle Screening Market | 2026-2036
Europe Cargo and Vehicle Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cargo and Vehicle Screening Market Insights
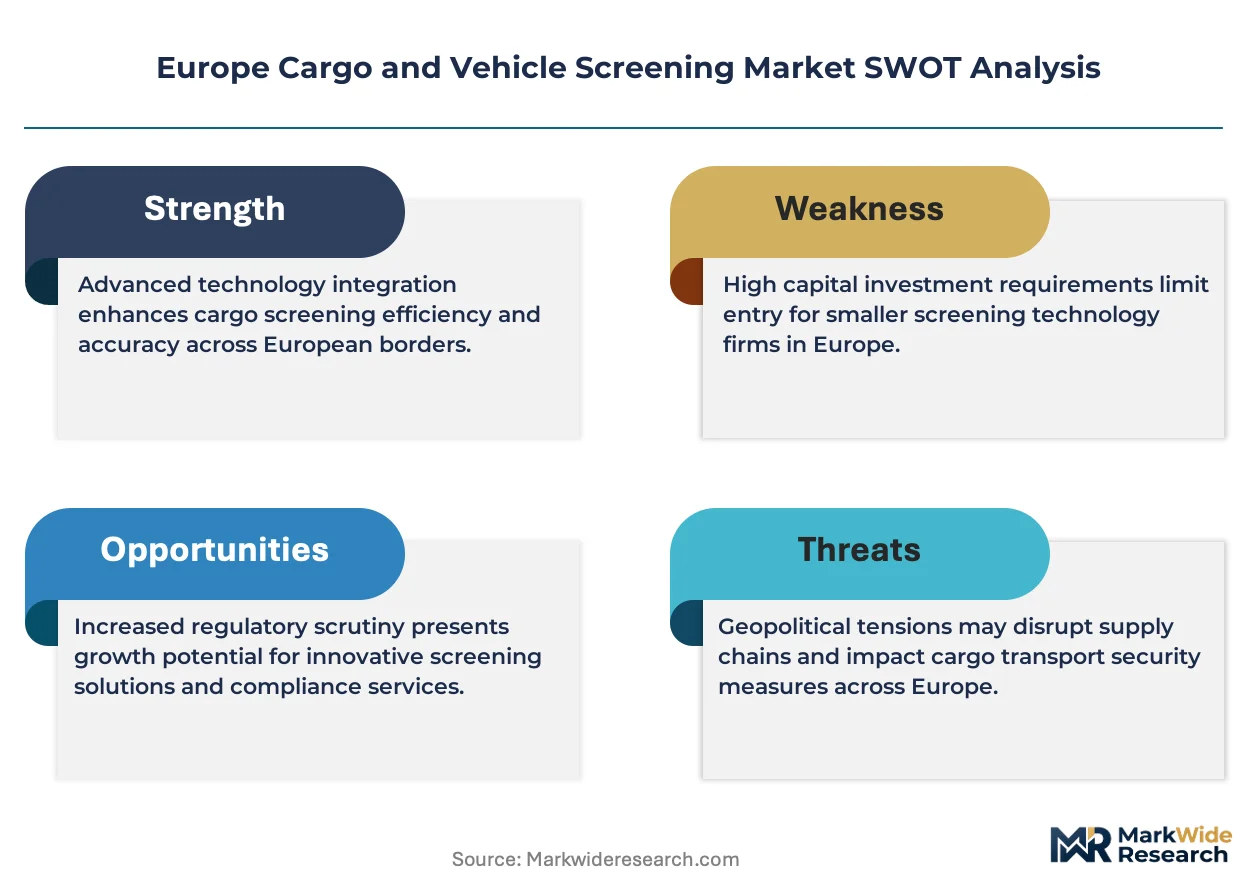
CE marking under the EU Machinery Directive and the EU AI Act conformity assessments for automated threat recognition is bifurcating the supplier landscape into qualified integrators and peripheral equipment vendors. Smiths Detection leverages its deep certification portfolio to anchor premium positions across EU maritime gateways. Rapiscan Systems competes on manufacturing scale, sustaining cost advantages in high-throughput portal deployments. 3DX-RAY specializes in mobile screening architectures, occupying niche segments where rapid redeployment flexibility commands priority.
Europe cargo and vehicle screening encompasses integrated detection platforms that combine dual-energy X-ray transmission with computed tomography reconstruction to identify contraband, explosives, and radiological materials in sealed containers and commercial vehicles without physical unloading. Systems typically operate at 3-6 MeV energy levels to penetrate steel walls exceeding 300 mm equivalent density, serving customs authorities and critical infrastructure operators requiring continuous flow inspection. X-ray scanners lead installed base value across the product mix, though computed tomography segments attract disproportionate R&D investment as automated material discrimination becomes mandatory for EU Authorized Economic Operator certifications. Customs inspection applications generate the steadiest procurement volumes, while border control deployments show the fastest upgrade urgency driven by Schengen Area perimeter hardening mandates.
EMA coordination on dual-use export controls, EU Green Deal procurement criteria, and the F-Gas Regulation on cooling systems for detection equipment collectively reshape equipment specifications and vendor eligibility across member states. The EU AI Act's risk classification for biometric and automated threat detection systems imposes additional conformity burdens that favor established suppliers with dedicated regulatory affairs functions. Stakeholders must monitor the interplay between national customs modernization timelines and harmonized certification requirements to anticipate where procurement windows will open or contract.
Market Dynamics
The EU AI Act's risk classification framework for automated threat detection systems is forcing customs authorities to accelerate equipment replacement cycles ahead of conformity deadlines, compressing procurement timelines and favoring suppliers with established CE marking portfolios.
Growth Catalysts
- EU Customs Union Code compliance:Member states must deploy non-intrusive inspection systems at designated border crossing points, creating mandated procurement volumes for dual-energy X-ray and computed tomography platforms.
- Schengen Area perimeter hardening:External border agencies in Poland, Hungary, and Greece are prioritizing vehicle screening upgrades to manage irregular migration flows and contraband trafficking through land corridors.
- Authorized Economic Operator certification:Freight forwarders and logistics operators in Rotterdam, Hamburg, and Antwerp are installing advanced material discrimination systems to secure customs simplifications and expedited clearance.
Market Restraints
- High-purity germanium detector shortages:Cryogenic cooling requirements under the F-Gas Regulation constrain supply chains for radiological identification modules, extending lead times for integrated screening systems.
- Linear accelerator component concentration:S-band magnetron and klystron manufacturing concentrates among a handful of specialized suppliers in Germany and Switzerland, creating single-source vulnerabilities for 6 MeV X-ray sources.
- CE marking complexity:The EU Machinery Directive's conformity assessment procedures for ionizing radiation equipment impose 12-18 month certification timelines that delay new entrant market access.
Strategic Opportunities
- Eastern European port modernization:Romania's Port of Constanta and Bulgaria's Port of Burgas are expanding container throughput capacity, opening greenfield installation windows for integrated screening architectures.
- Rail freight corridor expansion:The Rhine-Alpine and North Sea-Baltic TEN-T corridors are adding dedicated screening infrastructure at intermodal terminals to handle China-Europe block train volumes.
- EU Green Deal procurement criteria:Energy efficiency mandates for public procurement are creating preference premiums for solid-state X-ray sources and liquid-cooled detector arrays that reduce operational carbon intensity.
Industry Challenges
- Machine learning model validation:Automated threat recognition algorithms require extensive training datasets that customs agencies are reluctant to share across jurisdictions, fragmenting AI development efforts.
- Legacy system interoperability:New CT reconstruction platforms must integrate with existing customs information systems built on disparate national architectures, complicating deployment timelines.
- Radiation safety officer scarcity:Qualified personnel for regulatory compliance and equipment maintenance are concentrated in Western European labor markets, constraining expansion in Central and Eastern Europe.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cargo and Vehicle Screening Market |
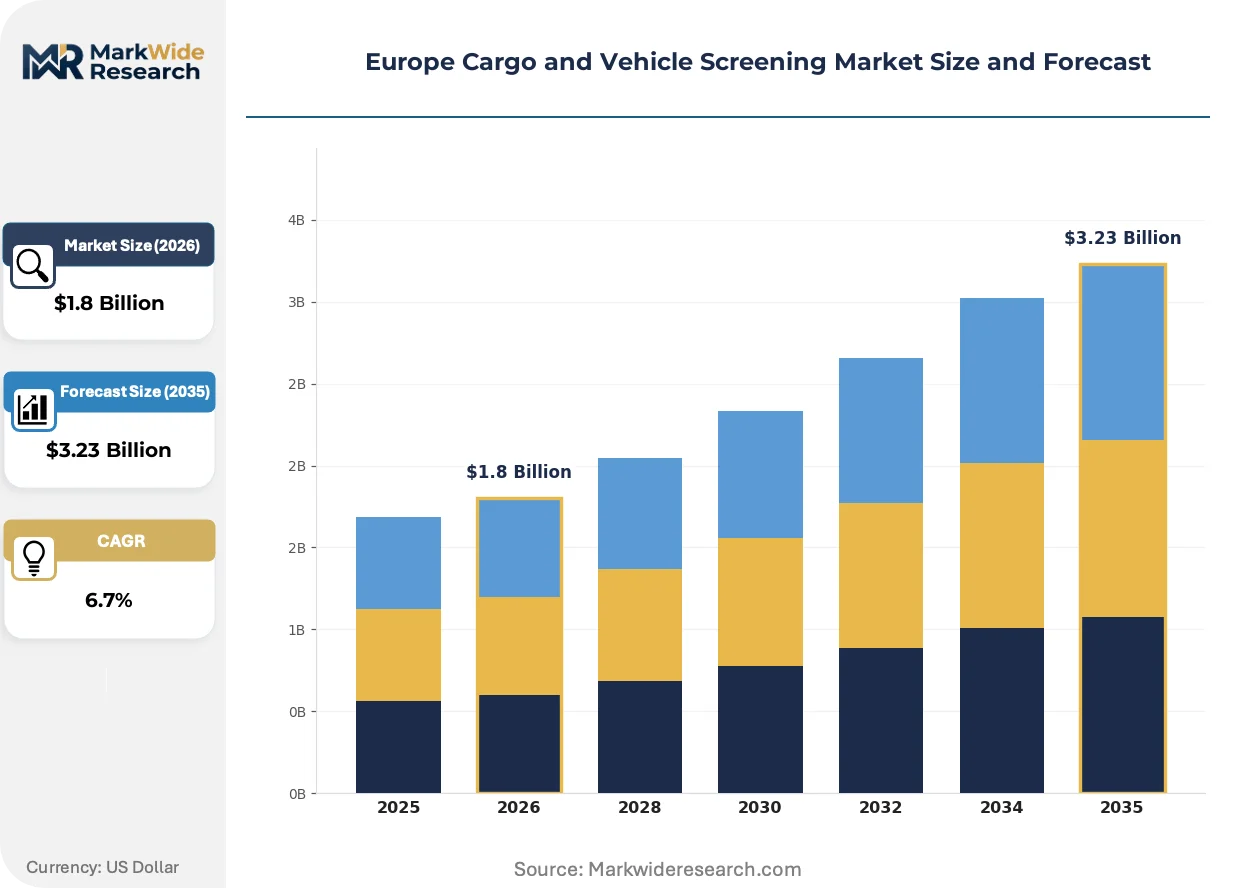
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray Scanners, Explosive Detectors, Metal Detectors, Radiation Detectors Application: Customs Inspection, Airport Security, Border Control, Shipping Port Security End User: Government Authorities, Logistics Companies, Airports, Shipping Companies Technology: Computed Tomography, Dual-Energy X-ray, Laser-Based Detection, Advanced Imaging |
| Companies Covered | Rapiscan Systems, 3DX-RAY, Nuctech Company Limited, Westminster Group Plc, LINEV Systems, Nuctech Netherlands B.V., Leidos Inc., Smiths Detection, Astrophysics Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cargo and Vehicle Screening Market Trends and Innovations
Computed tomography reconstruction algorithms are displacing conventional dual-energy X-ray transmission as the default specification for high-throughput customs installations, driven by automated material discrimination mandates and throughput optimization requirements.
Photon-counting detector arrays with cadmium zinc telluride semiconductors are displacing energy-integrating scintillator technologies in next-generation mobile screening units. Dutch and Belgian customs agencies are piloting these systems at roving checkpoint deployments. The shift is displacing legacy silicon photomultiplier supply chains and compressing price premiums for spectral imaging capabilities.
The EU AI Act's conformity assessment procedures for high-risk biometric and automated decision systems are reshaping vendor qualification requirements. Equipment suppliers must demonstrate algorithmic transparency and bias mitigation protocols to secure CE marking. Maritime gateway operators in France, Spain, and Italy are prioritizing suppliers with dedicated regulatory affairs functions capable of navigating multi-jurisdictional approval timelines.
Performance-based service contracts are replacing traditional capital purchase models among major freight terminal operators. Rotterdam World Gateway and DP World Antwerp are contracting screening throughput guarantees rather than equipment ownership. This shift concentrates vendor risk on uptime performance and algorithm update cycles, most visible in the Netherlands and Belgium where terminal automation investments are deepest.
Europe Cargo and Vehicle Screening Market Segmentation
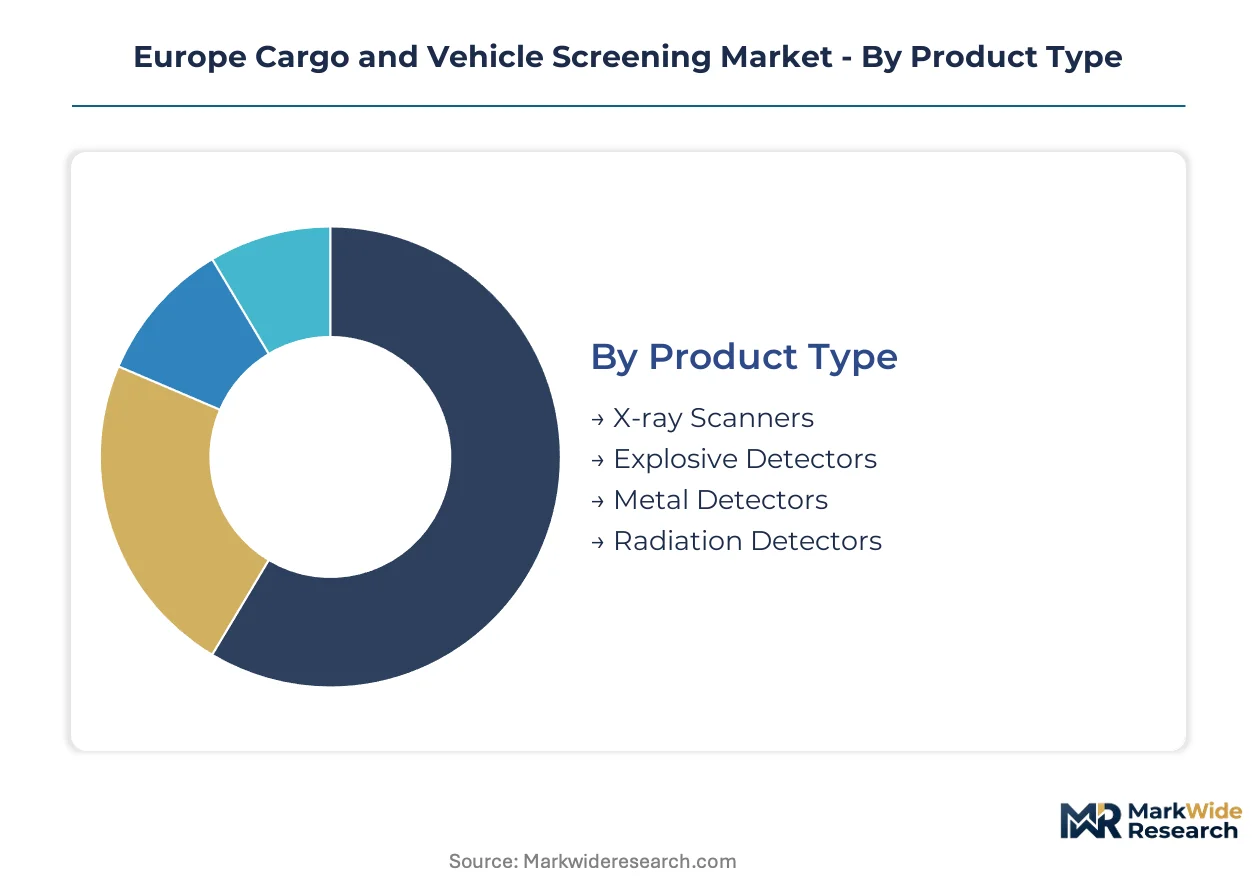
Segmentation in the Europe cargo and vehicle screening market reveals how procurement priorities diverge between regulatory compliance mandates and operational throughput optimization. Understanding these divisions helps suppliers align R&D investment with where buyer budgets concentrate.
Product Type:
Margin pools concentrate in integrated systems combining multiple detection modalities, with standalone components facing commoditization pressure from modular procurement strategies.
- X-ray Scanners:Dual-energy transmission systems operating at 3-6 MeV dominate maritime gateway installations across Rotterdam, Hamburg, and Antwerp. German customs authorities are accelerating replacement cycles for legacy single-energy units ahead of EU AI Act conformity deadlines for automated threat recognition.
- Explosive Detectors:Ion mobility spectrometry and chemiluminescence analyzers provide trace particle detection for container interiors without unloading. Polish and Hungarian border control agencies are expanding mobile deployment fleets to address Schengen perimeter hardening mandates along eastern land corridors.
- Metal Detectors:Ferromagnetic and eddy-current systems serve secondary screening roles at vehicle checkpoints.
- Radiation Detectors:High-purity germanium and sodium iodide scintillator modules identify radiological contraband; F-Gas Regulation constraints on cryogenic cooling extend lead times for integrated systems.
The dominant share belongs to X-ray Scanners, while Explosive Detectors is closing the gap fastest.
Application:
Procurement volume concentrates where regulatory mandates intersect with high-throughput operational requirements, creating divergent equipment specifications across use cases.
- Customs Inspection:Non-intrusive inspection systems at designated EU border crossing points must comply with the EU Customs Union Code. French and Spanish maritime customs are prioritizing computed tomography platforms with automated material discrimination to secure Authorized Economic Operator certification throughput.
- Airport Security:Integrated hold baggage and cargo screening systems serve freight terminals at Frankfurt, Amsterdam Schiphol, and Paris Charles de Gaulle. EASA coordination with national aviation authorities is harmonizing performance standards for explosive detection systems.
- Border Control:Mobile and fixed vehicle screening architectures address irregular migration and contraband trafficking. Greek land border agencies are deploying rapid-redeployment units at Evros corridor checkpoints.
- Shipping Port Security:Container terminal operators in Belgium and the Netherlands are contracting performance-based throughput guarantees rather than capital equipment purchases.
Customs Inspection commands the largest procurement base, though Border Control is expanding most quickly.
End User:
Buyer sophistication varies sharply between state agencies with dedicated regulatory affairs functions and private operators prioritizing total cost of ownership metrics.
- Government Authorities:National customs administrations and border guard agencies across Germany, France, and Italy drive premium equipment specifications. CE marking requirements under the EU Machinery Directive favor established suppliers with dedicated compliance teams.
- Logistics Companies:Freight forwarders and 3PL operators in the Netherlands and Belgium are adopting service-based contracting models. Rotterdam World Gateway and DP World Antwerp are negotiating uptime guarantees and algorithm update cycles rather than equipment ownership.
- Airports:Hub operators integrate screening systems with baggage handling and cargo terminal automation platforms.
- Shipping Companies:Container lines are installing pre-screening capabilities at origin ports to expedite EU destination clearance.
Government Authorities retain the dominant procurement volume, while Logistics Companies are gaining share fastest through performance contracting adoption.
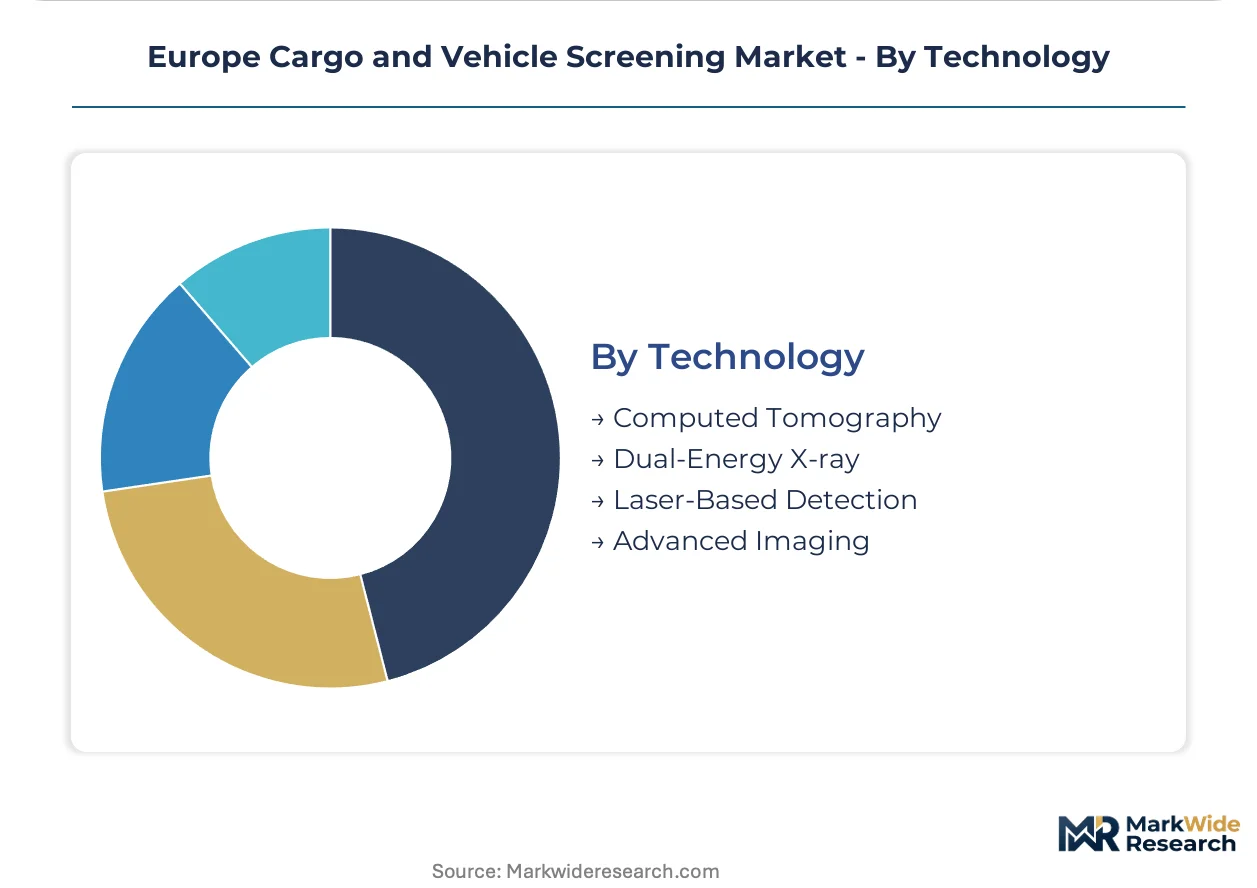
Technology:
Investment intensity clusters where automated decision systems trigger EU AI Act high-risk classification requirements, reshaping vendor qualification barriers.
- Computed Tomography:Multi-angle reconstruction algorithms enable automated material discrimination without human interpretation. Dutch and Belgian customs pilots at roving checkpoints are validating photon-counting cadmium zinc telluride detector arrays for mobile deployment.
- Dual-Energy X-ray:Conventional transmission imaging remains the installed base standard for high-throughput portal screening. Energy-integrating scintillator technologies face displacement by spectral imaging capabilities in next-generation procurement specifications.
- Laser-Based Detection:Standoff chemical sensing systems serve niche applications where non-contact vapor analysis is required.
- Advanced Imaging:Passive millimeter-wave and active radar systems complement ionizing radiation technologies at vehicle checkpoints.
Dual-Energy X-ray maintains the largest installed base, though Computed Tomography is climbing the fastest as automated material discrimination becomes mandatory for EU customs simplifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Customs Union Code compliance mandates and Schengen Area perimeter hardening programs are redirecting procurement budgets toward non-intrusive inspection systems at designated border crossing points across member states.
Germany
Replacement cycles for legacy single-energy X-ray units at Hamburg and Bremerhaven container terminals are accelerating ahead of EU AI Act conformity deadlines for automated threat recognition. The Federal Ministry of Finance coordinates customs modernization timelines with CE marking requirements under the EU Machinery Directive. Bavarian manufacturers in Munich and Nuremberg supply S-band magnetron components for 6 MeV linear accelerator sources.
Netherlands
Rotterdam World Gateway and DP World Antwerp are contracting performance-based throughput guarantees rather than capital equipment purchases for container screening infrastructure. The Dutch Customs Administration pilots photon-counting cadmium zinc telluride detector arrays at roving checkpoint deployments under EU Green Deal procurement criteria. Eindhoven-based semiconductor fabs supply detector substrate materials for next-generation mobile units.
France
Maritime customs at Marseille-Fos and Le Havre are prioritizing computed tomography platforms with automated material discrimination to secure Authorized Economic Operator certification throughput. The French National Agency for Food, Environmental and Occupational Health Safety enforces radiation safety protocols for ionizing equipment deployment. Paris-region regulatory affairs consultants support multi-jurisdictional approval timelines for CE marking portfolios.
Poland
Border Guard agencies along the Belarus and Ukraine land corridors are expanding mobile vehicle screening fleets to manage irregular migration flows and contraband trafficking. The Polish Ministry of Interior allocates EU cohesion funds for Schengen perimeter hardening infrastructure under the Integrated Border Management Strategy. Warsaw and Krakow logistics hubs are installing pre-screening capabilities for east-west freight corridors.
Belgium
Port of Antwerp-Bruges terminal operators are negotiating uptime guarantees and algorithm update cycles with screening system vendors. The Belgian Federal Public Service Finance administers customs simplification programs requiring advanced material discrimination for Authorized Economic Operator status. Flanders-based engineering firms specialize in CT reconstruction platform integration with legacy customs information systems.
Europe Cargo and Vehicle Screening Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and manufacturing scale. The supplier landscape bifurcates between established integrators with dedicated regulatory affairs functions and peripheral equipment vendors serving modular procurement strategies. Three archetypes dominate: premium-positioned certification holders, scale-driven manufacturing specialists, and niche mobile deployment experts. Competitive moves concentrate on strategic partnerships for algorithm development and geographic expansion through local subsidiary establishment.
Among UK-based suppliers, Smiths Detection and 3DX-RAY exemplify contrasting strategic positions within the market structure. Smiths Detection anchors the premium-tier vector through deep CE marking portfolios across EU maritime gateways. 3DX-RAY occupies a specialist position in mobile screening architectures where rapid redeployment flexibility commands procurement priority. Rapiscan Systems represents the scale-driven manufacturing archetype, sustaining cost advantages in high-throughput portal deployments. These three companies collectively illustrate how certification depth, manufacturing scale, and deployment flexibility segment competitive positioning across customs and border control applications.
| Leading Market Players |
|---|
| Rapiscan Systems |
| 3DX-RAY |
| Nuctech Company Limited |
| Westminster Group Plc |
| LINEV Systems |
| Nuctech Netherlands B.V. |
| Leidos Inc. |
| Smiths Detection |
| Astrophysics Inc. |
| Others |
Pricing and Supply Chain Analysis
Performance-based service contracts with throughput guarantees lock in multi-year supply access for terminal operators while capping price volatility exposure across EU maritime gateways. These arrangements concentrate vendor risk on uptime performance and algorithm update cycles, binding pricing visibility to operational reliability metrics rather than capital equipment depreciation schedules.
Pricing Analysis
Certification level (CE marking under EU Machinery Directive and EU AI Act conformity) creates the primary spread between premium integrators and peripheral equipment vendors. Three-tier pricing structure separates deep-certification holders from modular component suppliers and commodity scanner manufacturers. Cost compression in standard-tier dual-energy X-ray systems is intensifying as Dutch and Belgian terminal operators shift from capital purchase to service contracting. Logistics companies adopting performance-based models show highest price sensitivity, while German and French customs authorities with dedicated regulatory affairs functions prioritize certification depth over unit cost.
Supply Chain Analysis
Germany and Switzerland anchor S-band magnetron and klystron manufacturing for 6 MeV linear accelerator sources, while Dutch semiconductor fabs supply cadmium zinc telluride detector substrates for next-generation mobile units. High-purity germanium crystals for radiological identification modules draw from specialized cryogenic cooling supply chains constrained by F-Gas Regulation phase-down schedules. Single-source vulnerability concentrates in linear accelerator component tiers, with tariff exposure minimal but regulatory restriction significant for non-EU component sourcing. Distribution runs through authorized integrator networks with CE marking competence, bypassing direct OEM-to-end-user channels for complex system deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from photon-counting detector architectures that displace legacy scintillator technologies in mobile screening segments. The threat accelerates as Dutch and Belgian customs pilots validate cadmium zinc telluride arrays for roving checkpoint deployment.
For Market Incumbents: Compound certification depth under EU AI Act high-risk system classifications to anchor premium positioning across maritime gateways. Prioritize in-house production of linear accelerator subsystems to reduce exposure to German and Swiss magnetron supply concentration. Defensive moves must address photon-counting detector substitution before spectral imaging capabilities commoditize standard dual-energy X-ray transmission margins. For New Entrants and Emerging Players: Differentiate on rapid-redeployment mobile architectures for Schengen perimeter hardening corridors in Poland, Hungary, and Greece where legacy fixed installations cannot match irregular migration flow volatility. Target eastern European port modernization at Romania's Port of Constanta and Bulgaria's Port of Burgas where greenfield installation windows lack entrenched supplier relationships. Go-to-market angle should emphasize algorithm transparency documentation for EU AI Act conformity assessment acceleration. For Investors and Strategic Acquirers: Specialist regulatory affairs consultancies with multi-jurisdictional CE marking track records represent the most defensible acquisition archetype as conformity burdens intensify under EU AI Act implementation. Long-term viability hinges on positioning upstream of equipment procurement cycles where certification delays determine vendor selection. Signal to watch is acceleration in German customs replacement timelines for legacy single-energy units, indicating conformity deadline compression that favors established integrators with dedicated compliance functions.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | CE marking portfolios under high-risk classification secure premium positioning at Hamburg and Rotterdam terminals. |
| Photon-Counting Detector Integration | Cadmium zinc telluride arrays displace legacy scintillator supply chains in Dutch mobile screening pilots. |
| Performance-Based Service Contracting | Throughput guarantees shift vendor risk from capital sale to uptime accountability at Antwerp-Bruges. |
| Eastern European Geographic Expansion | Greenfield installations at Constanta and Burgas bypass entrenched Western European supplier relationships. |
| Linear Accelerator Backward Integration | In-house S-band magnetron production reduces single-source vulnerability from German and Swiss component concentration. |
Research Methodology
The analysis maps X-ray scanner, explosive detector, radiation detector, and computed tomography platform sub-sectors, each validated through customs procurement officers, terminal operations directors, and regulatory affairs specialists at screening system vendors. Primary interviews with border guard agency planners and freight forwarder compliance managers combined with secondary validation from EU Customs Union Code implementation reports, F-Gas Regulation impact assessments, and national customs modernization disclosures. Bottom-up equipment installation tracking and top-down procurement budget analysis triangulate market sizing across the projection horizon.
Consistency checks against external benchmarks validated volume and value outputs for divergence from reported national customs expenditure patterns and terminal operator capital commitment disclosures. Segmentation dimensions modeled include product type, application, end user, and technology tier across the analysis window, with CAGRs derived from equipment replacement cycle timing and regulatory deadline compression effects. Forecast inputs incorporated Schengen perimeter hardening budget allocations and Authorized Economic Operator certification adoption rates at Rotterdam, Hamburg, and Antwerp logistics hubs.
The analysis sits within stated boundaries; outcomes outside EU AI Act implementation timelines or F-Gas Regulation phase-down schedules would require recalibration. Forecasts reflect assumptions on customs agency willingness to share training datasets for machine learning model validation and terminal operator acceptance of performance-based contracting terms. Recalibration cycles align with material shifts in EU Green Deal procurement criteria adoption and national customs modernization program accelerations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Europe Security Screening Market
Security and Surveillance
Global Security Advisory Services Market
Security and Surveillance
Radar Security Market
Security and Surveillance
Stadium Security Market
Security and Surveillance
Proactive Security Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
Explosive Vapour Detector Market
Security and Surveillance
Threat Detection Systems Market
Security and Surveillance
Destructible Security Labels Market
Security and Surveillance
Integrated Security Services Market
Security and Surveillance
Security Holograms Market
Security and Surveillance
Air Cargo Security and Screening Systems Market
Security and Surveillance
Air Cargo Security Equipment Market
Security and Surveillance
Private Military Security Services Market
Security and Surveillance
Security System Integrators Market
Security and Surveillance
Global Firearm Sight Market