
 Ultrasound Needle Guides Market | 2026-2036
Ultrasound Needle Guides Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Needle Guides Market Analytics
Single-use specification upgrades is reorganizing procurement priorities across interventional suites. CIVCO Medical Solutions leverages its disposable guide portfolio to anchor hospital contracts in North American academic medical centers. GE Healthcare sustains technology leadership through integrated ultrasound-needle navigation ecosystems. Siemens Healthineers AG competes on electromagnetic tracking compatibility with its imaging platforms.
Ultrasound needle guides are sterile mechanical or sensor-enabled attachments that align biopsy needles, drainage catheters, or regional anesthesia needles with ultrasound transducer imaging planes, typically manufactured from medical-grade polymers or aluminum with disposable snap-on designs rated for 18-25 gauge instruments. Single-use product types command the dominant volume share as infection control protocols eliminate reprocessing workflows in busy procedural environments. Electromagnetic technology segments attract premium positioning where real-time needle tip tracking reduces procedural time and complication rates in deep-tissue interventions.
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements shape material biocompatibility and sterility assurance documentation burdens for manufacturers entering either market. The EU AI Act and ISO 13485 quality management standards further constrain software-enabled hybrid navigation systems that blend optical and electromagnetic tracking. Stakeholders must monitor evolving reimbursement codes for image-guided procedures and pre-empt sterilization validation demands before dual-market product submissions.
Market Dynamics
Single-use sterilization mandates from FDA and EU MDR are compressing reprocessing economics across interventional radiology suites, forcing hospitals to absorb premium disposable pricing while vendors retool material specifications for biocompatibility compliance.
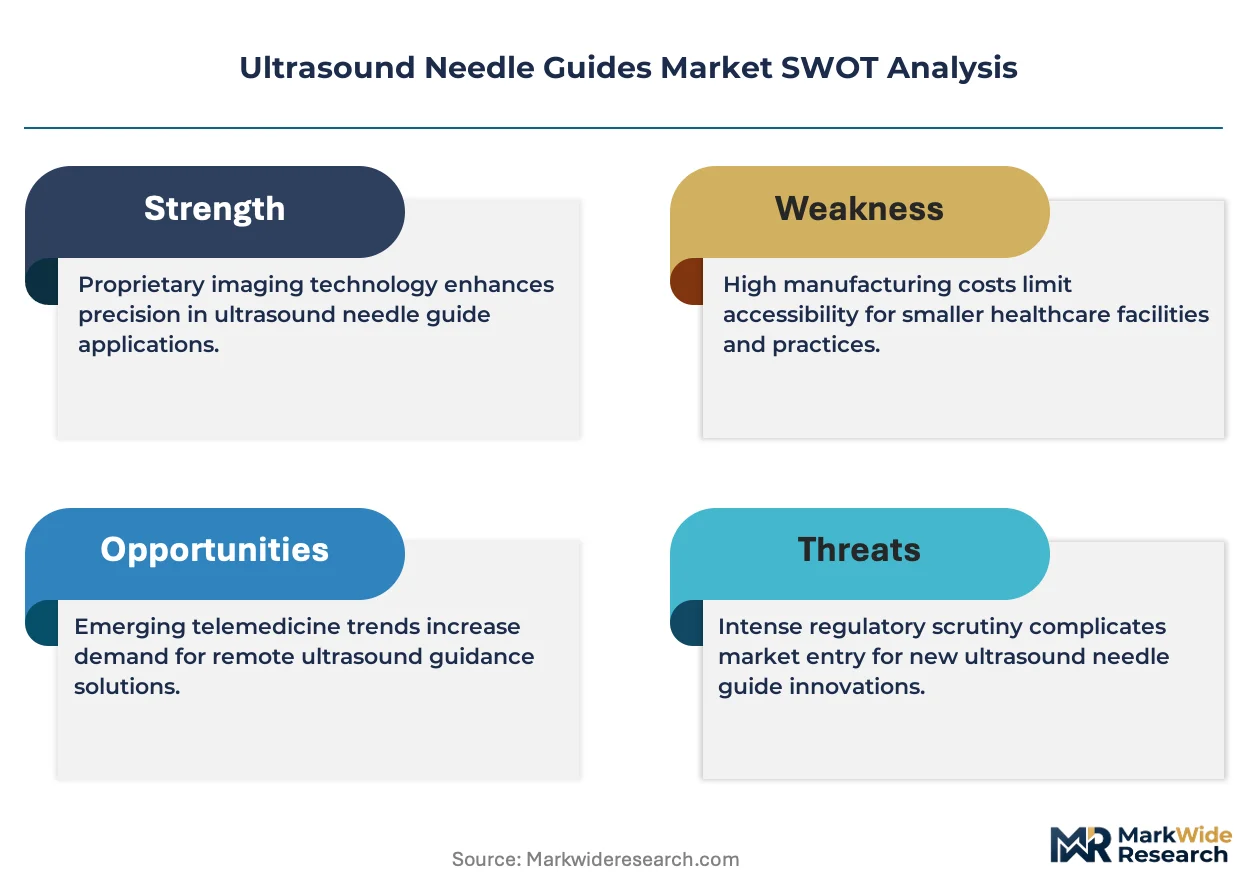
Growth Catalysts
- EU MDR Class IIa Certification:Stricter sterility documentation requirements eliminate marginal competitors and consolidate procurement toward validated suppliers with established quality management systems.
- Interventional Radiology Expansion:Hospital-based IR departments in the United States are standardizing disposable needle guide protocols to reduce cross-contamination liability and procedural turnaround times.
- Electromagnetic Tracking Integration:Real-time needle tip visualization technology reduces deep-tissue complication rates and commands premium positioning in academic medical centers performing complex biopsies.
Market Restraints
- Medical-Grade Polymer Cost Volatility:Specialized polymer feedstocks for single-use guides face petrochemical price swings that compress manufacturer margins without commensurate pricing flexibility.
- German Supplier Concentration:Precision aluminum machining for reusable guide components clusters in southern Germany, creating geographic supply vulnerability and extended lead times during demand surges.
- Optical Navigation Substitution:Camera-based needle tracking systems from surgical robotics vendors threaten electromagnetic ultrasound guide adoption in high-volume procedural settings.
Strategic Opportunities
- China NMPA Streamlined Pathways:Accelerated registration timelines for Class II devices create first-mover advantage for disposable guide manufacturers establishing local production partnerships.
- Ambulatory Surgery Center Penetration:Freestanding ASCs performing regional anesthesia and pain management procedures represent underserved volume for simplified, lower-cost disposable guide SKUs.
- AI-Enabled Hybrid Navigation:Convergence of machine learning trajectory prediction with electromagnetic tracking enables autonomous needle path optimization in deep-lesion interventions.
Industry Challenges
- ISO 13485 Implementation Timeline:Small and mid-sized manufacturers face 12-18 month quality system certification delays that stall dual-market FDA-EU submissions and contract eligibility.
- Legacy Ultrasound Platform Integration:Proprietary transducer connector geometries from established imaging vendors force guide manufacturers to maintain fragmented SKU portfolios across incompatible hardware ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Needle Guides Market |
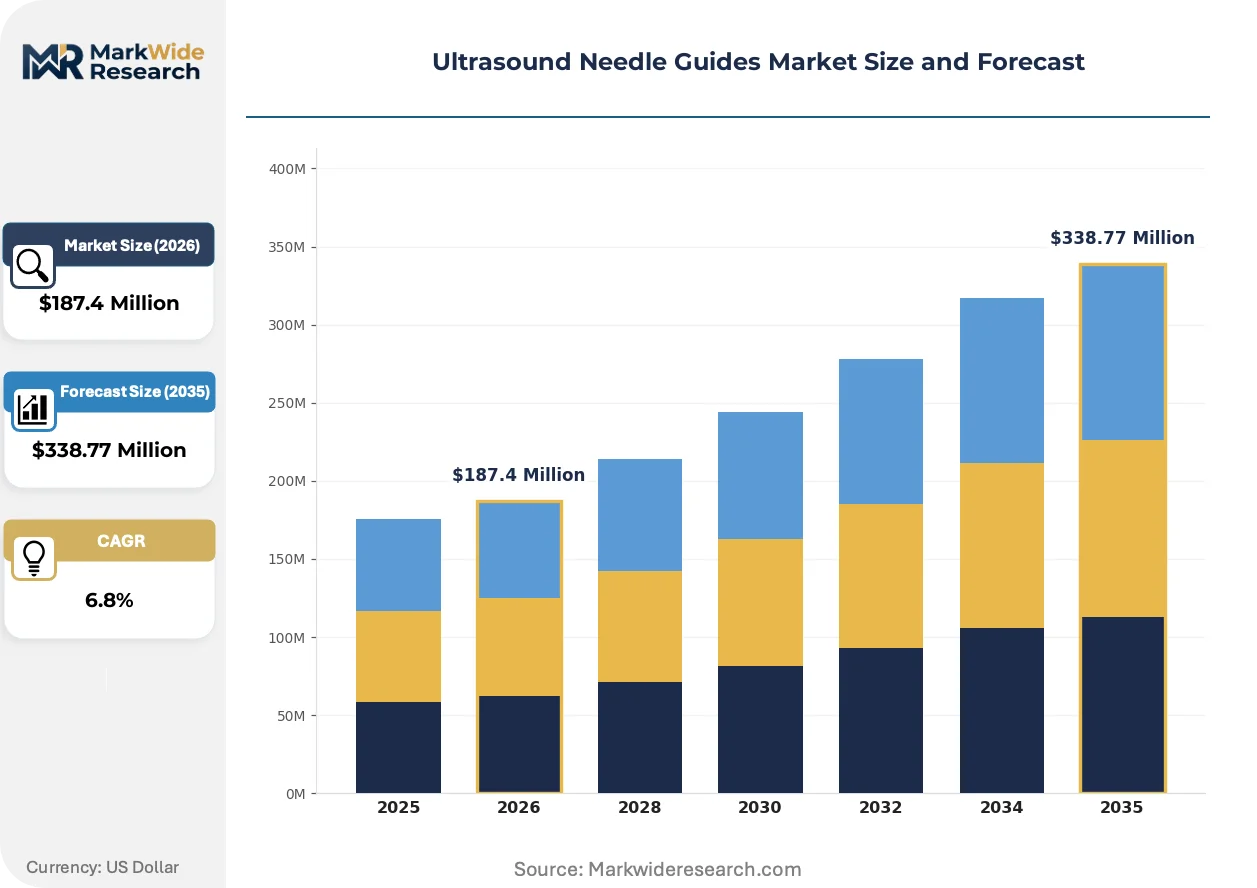
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Reusable, Disposable, Specialty Technology: Electromagnetic, Optical, Ultrasonic, Hybrid End User: Hospitals, Diagnostic Centers, Outpatient Clinics, Research Institutions Application: Biopsy, Drainage, Anesthesia, Cardiovascular |
| Companies Covered | CIVCO Medical Solutions, GE Healthcare, FUJIFILM Sonosite, Inc., Becton, Dickinson and Company, Siemens Healthineers AG, GEOTEK MEDICAL LTD, Argon Medical Devices, Aspen Surgical Products, Inc., Sheathing Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Needle Guides Market Evolving Landscape
Real-time navigation ecosystems are fragmenting traditional mechanical guide categories as electromagnetic and optical tracking modalities compete for procedural standardization across interventional specialties.
Disposable polymer needle guides are decomposing the reusable aluminum guide installed base in hospital radiology departments. Academic medical centers in the United States are transitioning procurement specifications toward single-use designs within 18-month capital refresh cycles. This shift compresses aftermarket service revenue for legacy guide manufacturers while opening volume contracts for sterilization-validated disposable suppliers.
EU MDR technical documentation requirements are extending product registration timelines for software-enabled navigation systems. Manufacturers must submit clinical evidence packages for electromagnetic tracking algorithms alongside mechanical biocompatibility data. The regulation most affects hybrid optical-electromagnetic platforms seeking CE marking, forcing vendors to sequence market entry with documentation-heavy conformity assessments.
Hospital procurement committees are consolidating needle guide purchasing into broader ultrasound system negotiations. Bundled capital equipment contracts now specify disposable guide minimum volume commitments across multi-year service agreements. This pattern concentrates purchasing leverage with integrated imaging vendors in the United States and Germany, displacing standalone guide suppliers from sole-source hospital agreements.
Ultrasound Needle Guides Market Segmentation
Segmentation in the ultrasound needle guides market reveals distinct margin architectures across sterility protocols, tracking modalities, and procedural settings. Procurement committees weight infection control liability against capital efficiency when allocating spend across product categories.
Product Type:
Premium margin pools concentrate in validated single-use designs where sterilization documentation commands pricing power against commodity alternatives.
- Single-Use:Medical-grade polymer construction rated for 18-25 gauge instruments eliminates reprocessing workflows. Hospital-based interventional radiology departments in the United States absorb premium pricing to reduce cross-contamination liability and procedural turnaround times.
- Reusable:Precision aluminum machining supports multiple sterilization cycles with snap-on connector geometries. German supplier concentration in southern Bavaria creates geographic supply vulnerability and extended lead times during demand surges.
- Disposable:Lower-cost polymer variants target high-volume ambulatory settings with simplified SKU portfolios.
- Specialty:Custom-configured designs for proprietary transducer ecosystems serve academic medical center research protocols.
The dominant share belongs to Single-Use, while Disposable is closing the gap fastest.
Technology:
Technology segmentation tracks where real-time visualization capabilities justify capital expenditure against mechanical alignment alternatives.
- Electromagnetic:Sensor-enabled needle tip tracking reduces deep-tissue complication rates through real-time position feedback. Siemens Healthineers AG competes on electromagnetic compatibility with its imaging platforms in academic medical centers performing complex biopsies.
- Optical:Camera-based trajectory verification offers lower per-procedure cost without electromagnetic interference concerns.
- Ultrasonic:Native ultrasound signal processing provides needle enhancement without auxiliary hardware.
- Hybrid:Convergence of machine learning trajectory prediction with electromagnetic tracking enables autonomous needle path optimization in deep-lesion interventions.
Electromagnetic holds the installed base advantage, though Hybrid systems are expanding most quickly in tertiary care settings.
End User:
End user segmentation maps procurement authority concentration against procedure volume density.
- Hospitals:Centralized purchasing committees bundle needle guide commitments into multi-year ultrasound system service agreements. CIVCO Medical Solutions leverages disposable guide portfolios to anchor contracts in North American academic medical centers.
- Diagnostic Centers:Focused imaging workflows prioritize throughput-optimized mechanical guides over navigation ecosystems.
- Outpatient Clinics:Freestanding regional anesthesia and pain management sites represent underserved volume for simplified disposable SKUs.
- Research Institutions:Investigational device exemptions support early-stage hybrid navigation validation studies.
Hospitals command the volume majority, while Outpatient Clinics are gaining share fastest as ambulatory surgery center penetration accelerates.
Application:
Application segmentation reflects reimbursement alignment and procedural complexity gradients across interventional specialties.
- Biopsy:Tissue sampling precision demands drive electromagnetic tracking adoption where lesion depth exceeds superficial visualization. GE Healthcare sustains technology leadership through integrated ultrasound-needle navigation ecosystems in oncology workflows.
- Drainage:Percutaneous catheter placement requires real-time tip confirmation in fluid-filled cavities.
- Anesthesia:Regional nerve block protocols standardize disposable mechanical guides across high-volume operating rooms.
- Cardiovascular:Vascular access procedures utilize sterile attachments for central line and pacemaker lead placement.
Biopsy generates the highest revenue per procedure, while Anesthesia delivers the steepest volume expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision aluminum machining for reusable guide components clusters in southern Germany, creating geographic supply vulnerability and extended lead times during demand surges. Hospital procurement committees in the United States absorb premium disposable pricing to reduce cross-contamination liability. Chinese manufacturers exploit NMPA streamlined pathways to establish local production partnerships.
United States
Hospital-based interventional radiology departments standardize disposable needle guide protocols to reduce procedural turnaround times. FDA 510(k) clearance pathways shape material biocompatibility documentation burdens for manufacturers entering the market. Academic medical centers in Boston and the Research Triangle anchor technology adoption for electromagnetic tracking integration.
Germany
Precision aluminum machining for reusable guide components concentrates in southern Bavaria, creating supply vulnerability during demand surges. EU MDR Class IIa certification requirements eliminate marginal competitors and consolidate procurement toward validated suppliers. Siemens Healthineers AG leverages electromagnetic tracking compatibility to compete in academic medical centers performing complex biopsies.
China
Accelerated NMPA registration timelines for Class II devices create first-mover advantage for disposable guide manufacturers establishing local production partnerships. The country's national medical device regulator tightens sterility assurance standards under harmonized GB requirements. Manufacturing clusters in the Yangtze River Delta scale polymer injection capacity for single-use guide export.
Japan
PMDA quality management standards constrain software-enabled hybrid navigation systems seeking market entry. METI industrial policy supports domestic precision manufacturing for medical-grade polymer feedstocks. The Osaka-Kobe manufacturing corridor maintains specialized machining capacity for reusable aluminum guide components.
India
CDSCO streamlined pathways for Class B medical devices attract disposable guide manufacturers seeking cost-optimized production bases. The country's national pharmaceutical regulator aligns device registration requirements with international harmonization frameworks. Manufacturing clusters in Maharashtra and Gujarat scale polymer molding capacity for regional export.
Ultrasound Needle Guides Market Competitive Landscape
Concentration sits with integrated imaging vendors bundling needle guide commitments into multi-year ultrasound system service agreements. The vendor base spans three strategic tiers: diversified imaging conglomerates with navigation ecosystems, specialized disposable guide manufacturers with sterilization validation, and regional machining specialists serving reusable aluminum segments. Competitive moves concentrate on electromagnetic tracking licensing and disposable portfolio expansion.
Within the integrated imaging tier, GE Healthcare and Siemens Healthineers AG exemplify platform-centric positioning, while CIVCO Medical Solutions anchors the specialized disposable segment. These three entities represent divergent archetypes: technology convergence through ultrasound-needle navigation ecosystems, electromagnetic compatibility with proprietary imaging platforms, and hospital contract anchoring through validated single-use portfolios.
| Leading Market Players |
|---|
| CIVCO Medical Solutions |
| GE Healthcare |
| FUJIFILM Sonosite, Inc. |
| Becton, Dickinson and Company |
| Siemens Healthineers AG |
| GEOTEK MEDICAL LTD |
| Argon Medical Devices |
| Aspen Surgical Products, Inc. |
| Sheathing Technologies, Inc. |
| Others |
Value Network & Pricing Analysis
EU MDR Class IIa certification gates both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb documentation costs that stratify market access while hospitals pay premiums for validated single-use portfolios.
Pricing Analysis
FDA 510(k) clearance pathways dictate the pricing tier structure across the ultrasound needle guides landscape. Three-tier pricing separates electromagnetic navigation ecosystems from standard disposable mechanical guides and economy polymer variants. Price differentiation rests on sterilization validation grade and electromagnetic tracking integration depth. Cost compression in economy polymer tiers is intensifying because Chinese manufacturers exploit NMPA streamlined pathways to undercut Western suppliers. Ambulatory surgery centers exhibit highest price sensitivity, while academic medical centers performing complex biopsies absorb premium positioning for navigation-enabled systems.
Supply Chain Analysis
Trans-Pacific container availability fluctuations from Shanghai to Los Angeles strain inbound logistics costs for medical-grade polymer feedstocks. Precision aluminum machining concentrates in southern Germany, polymer injection molding clusters in China's Yangtze River Delta, and sterilization validation services anchor in the United States. Raw material dependencies draw from specialized petrochemical derivatives, medical-grade thermoplastics, and electromagnetic sensor components. Single-source vulnerability concentrates in German precision machining for reusable guide components. Distribution runs through hospital procurement committees bundling needle guide commitments into multi-year ultrasound system service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical navigation systems from surgical robotics vendors threaten electromagnetic ultrasound guide adoption, forcing incumbents to defend installed base relationships while new entrants exploit service-layer gaps.
For Market Incumbents: Shield electromagnetic tracking ecosystems through proprietary transducer connector geometries that fragment competitor SKU portfolios. Deepen backward integration into medical-grade polymer feedstocks to compress margin exposure from petrochemical price volatility. Anchor hospital contracts with disposable guide minimum volume commitments across multi-year service agreements before optical navigation substitutes gain procedural standardization. For New Entrants and Emerging Players: Ambulatory surgery center sterilization validation represents the most penetrable service-layer gap where incumbents under-serve with overspecified hospital-grade portfolios. Target simplified, lower-cost disposable SKUs for freestanding regional anesthesia and pain management sites. Pursue China NMPA streamlined pathways through local production partnerships to establish cost-optimized manufacturing bases for regional export. For Investors and Strategic Acquirers: EU MDR implementation deadlines reshape the acquisition landscape toward sterilization-validated suppliers with established ISO 13485 quality management systems. Long-term viability centers on navigation ecosystem convergence rather than standalone mechanical guide manufacturing. Monitor electromagnetic-optical hybrid navigation validation studies in academic medical centers as the inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIa certification eliminates marginal competitors and consolidates procurement toward validated suppliers with quality management systems. |
| Hospital System Partnership | CIVCO Medical Solutions leverages disposable guide portfolios to anchor multi-year contracts in North American academic medical centers. |
| Software Companion Development | GE Healthcare sustains technology leadership through integrated ultrasound-needle navigation ecosystems in oncology biopsy workflows. |
| Reimbursement Strategy | Alignment with evolving CPT codes for image-guided procedures determines premium product uptake in hospital-based interventional radiology. |
| FDA Submission | 510(k) clearance pathways shape material biocompatibility documentation burdens for manufacturers entering the United States market. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital purchasing committees, biomedical engineers, interventional radiologists, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement codes. Bottom-up and top-down triangulation cross-checked polymer feedstock cost structures against electromagnetic tracking system pricing premiums.
Across the analysis window, the forecasting framework modeled volume and value trajectories across product type, technology modality, end user setting, and application specialty dimensions. CAGRs were derived from procedural volume elasticity to reimbursement alignment and sterilization protocol adoption curves. Electromagnetic tracking penetration in deep-tissue interventions and ambulatory surgery center disposable guide conversion rates served as key forecast inputs.
Underlying assumptions cover sustained FDA and EU MDR single-use mandates, stable petrochemical feedstock availability, and reimbursement code stability for image-guided procedures, with deviation risk concentrated in optical navigation substitution acceleration and China NMPA regulatory harmonization pace. Practitioners should keep alternative scenarios live as surgical robotics platform capabilities and hybrid navigation validation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Global Surgical Lasers Market
Surgical Instruments
Laparotomy Sponges Market
Surgical Instruments
Needle Holders Market
Surgical Instruments
Lumpectomy Market
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Europe Biosurgery Market
Surgical Instruments
Adult Cardiovascular Surgical Instruments Package Market
Surgical Instruments
Ultrasonic Surgical Cutters Market
Surgical Instruments
Disposable Surgical Devices Market
Surgical Instruments
Cystoscopy Needles Market
Surgical Instruments
US Surgical Sutures Market
Surgical Instruments
Global Arthroscopy Instruments Market
Surgical Instruments
Cheilectomy Market