
 Surgical Stapling Devices Market | 2026-2036
Surgical Stapling Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Stapling Devices Market Intelligence
A capital-intensity divergence between integrated manufacturers and component assemblers is reorganizing competitive tiers in surgical stapling. Medtronic Plc leverages its captive polymer molding operations to control cartridge supply chains. Johnson & Johnson (Ethicon, Inc.) sustains dominance in reloadable cartridge platforms through proprietary anvil technology. Lepu Medical Technology anchors its position in China by competing on cost-optimized manual stapler production at scale.
Surgical stapling devices are mechanical or electromechanical instruments that deploy linear or circular arrays of titanium or stainless steel staples to approximate tissue during resection, anastomosis, or transection procedures, with jaw compression pressures typically calibrated between 1.5 and 3.5 kg/cm² to ensure hemostasis without tissue necrosis. Their primary commercial purpose is to reduce operative time and leak rates relative to hand-sewn closure in minimally invasive and open procedures. Powered staplers lead the product type landscape due to surgeon preference for consistent firing force in thick tissue applications, while disposable staplers capture expanding volume in ambulatory surgical centers seeking to eliminate reprocessing overhead. Gastrointestinal surgery remains the largest application segment, though gynecological procedures represent the fastest-growing addressable pool as laparoscopic hysterectomy protocols standardize.
The FDA's 510(k) premarket notification framework governs stapler safety validations in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements for powered and fully automated systems entering European markets. ISO 13485 quality management certification functions as a baseline threshold for original equipment manufacturers seeking access to regulated jurisdictions. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA guidance on stapler malfunctions to anticipate certification delays and portfolio prioritization decisions.
Market Dynamics
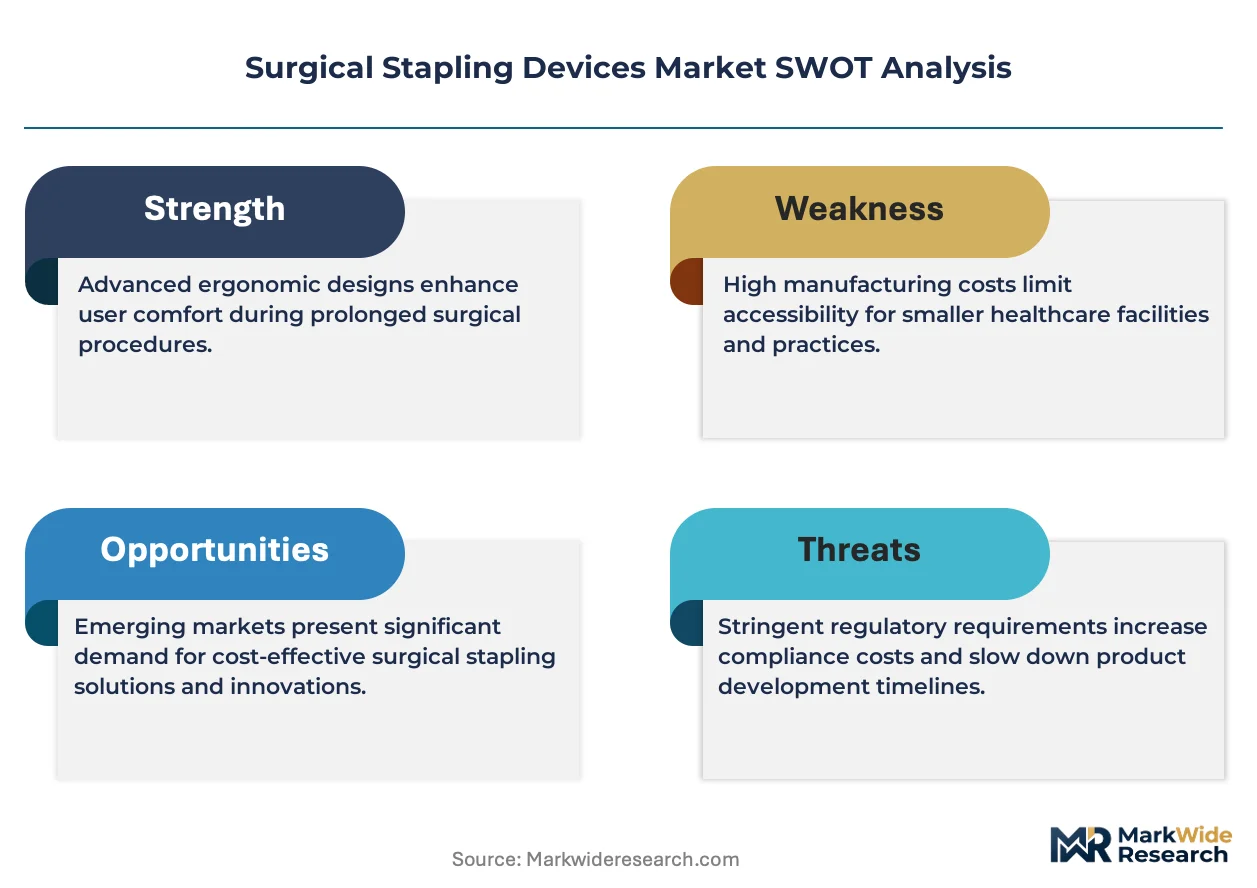
Powered stapler adoption is compressing the addressable market for manual devices as hospital procurement committees standardize on single-vendor platforms to reduce training overhead and inventory complexity.
Growth Catalysts
- Ambulatory surgical center expansion:Freestanding ASCs in the United States are converting procedure volumes from inpatient settings, creating concentrated demand for disposable cartridge systems that eliminate reprocessing infrastructure.
- FDA 510(k) pathway efficiency:The premarket notification framework for powered staplers accelerates product iteration cycles relative to premarket approval requirements, enabling faster feature deployment.
- Laparoscopic protocol standardization:Gynecological surgery societies are mandating mechanical stapling for hysterectomy anastomosis, institutionalizing device-dependent surgical technique.
Market Restraints
- Titanium price volatility:Staple wire feedstock costs fluctuate with aerospace demand cycles, compressing margin predictability for cartridge manufacturers without long-term supply contracts.
- EU MDR clinical evidence requirements:The Medical Device Regulation imposes extended trial timelines for powered staplers entering European markets, delaying revenue recognition versus historical CE-marking timelines.
- Hand-sewn closure persistence:Cost-sensitive public hospital systems in emerging markets continue favoring suture-based techniques for routine gastrointestinal resections.
Strategic Opportunities
- Brazilian public hospital modernization:ANVISA regulatory harmonization with ISO 13485 standards is opening procurement channels for quality-certified manufacturers previously excluded by local content requirements.
- RFID-enabled cartridge tracking:Convergence of near-field communication with staple line integrity sensors creates differentiated value propositions for liability-conscious health systems.
- India PLI scheme leverage:The production-linked incentive framework for medical devices subsidizes domestic manufacturing scale-up for export-oriented stapler assembly operations.
Industry Challenges
- Polymer molding talent scarcity:Precision cartridge housing production requires specialized injection molding technicians, creating recruitment bottlenecks for manufacturers expanding capacity.
- ISO 13485 certification timelines:Notified body backlogs for quality management system audits extend market entry schedules by 8-14 months for new market entrants.
- Legacy anvil compatibility:Hospital-installed bases of reloadable stapler handles create switching friction against fully disposable platform conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Stapling Devices Market |
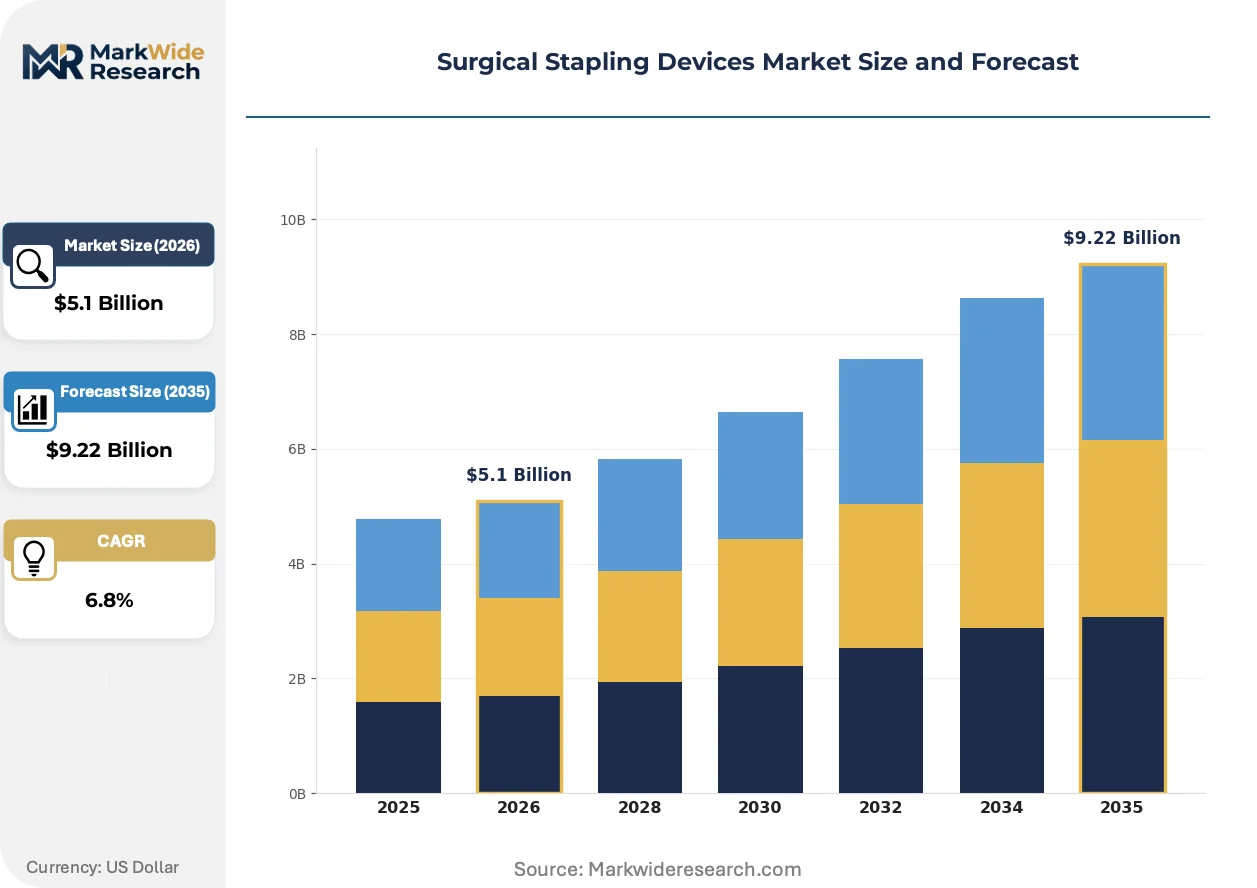
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $9.22 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Staplers, Powered Staplers, Articulating Staplers, Disposable Staplers Application: Gastrointestinal Surgery, Thoracic Surgery, Gynecological Procedures, Urological Treatments, General Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Academic Medical Centers Technology: Single-Use Mechanism, Reloadable Cartridges, Semi-Automated Systems, Fully Automated Devices |
| Companies Covered | Intuitive Surgical Inc, CONMED Corporation, Medtronic Plc, Smith+Nephew, B. Braun SE, Johnson & Johnson (Ethicon, Inc.), 3M Company, Purple Surgical, Lepu Medical Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Stapling Devices Market Strategic Shifts & Innovations
Battery-powered firing mechanisms are rewriting performance benchmarks for tissue compression consistency, while regulatory data requirements and procurement centralization reshape how manufacturers prioritize R&D investment.
Smart staplers integrating load-cell feedback and real-time tissue thickness measurement are displacing empirical firing techniques in bariatric and thoracic procedures. Academic medical centers in the United States and Germany are piloting these systems for complex anastomoses where leak rates carry mortality consequences. The technology is displacing conventional powered staplers in premium-tier hospital contracts, compressing price realization for first-generation electromechanical platforms.
The EU Medical Device Regulation's post-market surveillance requirements are forcing manufacturers to maintain active implantable device-level traceability for powered staplers. This obligation is extending product development timelines and inflating quality assurance headcounts for European market access. Smaller manufacturers without captive clinical affairs teams are outsourcing post-market clinical follow-up to contract research organizations, fragmenting compliance cost structures.
Hospital consolidation into integrated delivery networks is consolidating purchasing authority into centralized value analysis committees. These committees are unbundling device procurement from traditional distributor relationships, negotiating direct manufacturer contracts for high-volume staple cartridge categories. The shift is most visible in the United States, where systems like HCA and CommonSpirit are standardizing on single-source agreements across multi-state facility footprints.
Surgical Stapling Devices Market Segmentation
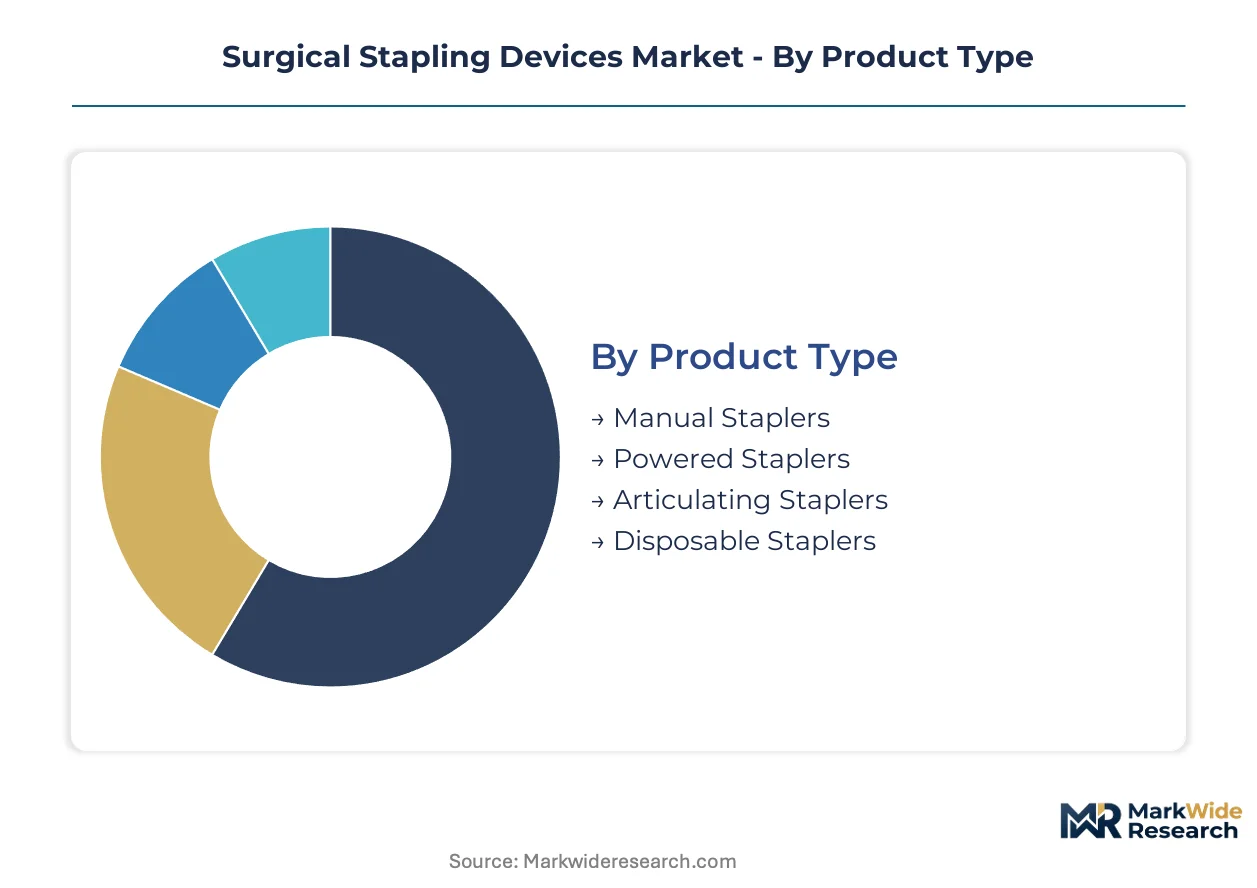
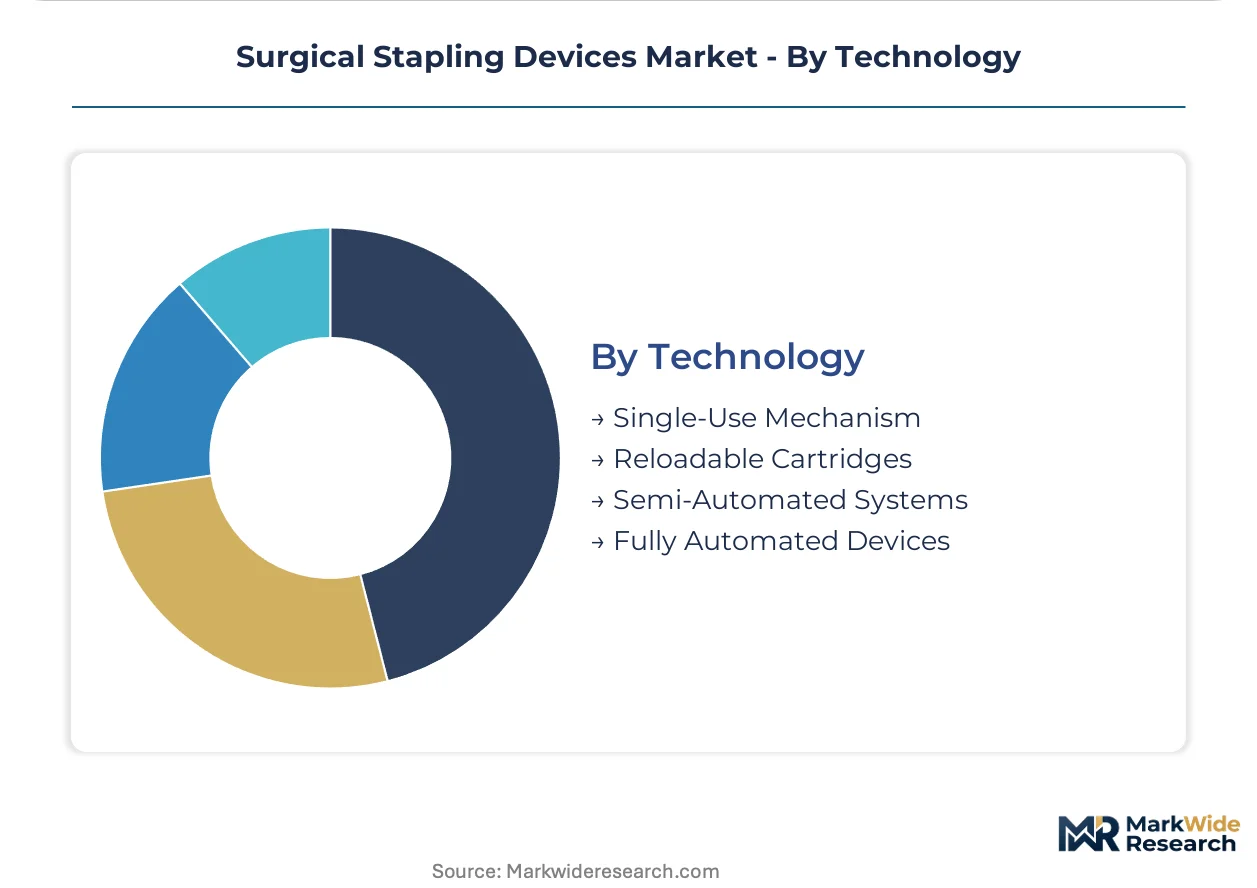
Surgical stapling devices fragment across four intersecting dimensions that determine procurement priorities, regulatory pathways, and margin architecture. Each category carries distinct FDA 510(k) requirements, reimbursement codes, and supply chain configurations that shape manufacturer portfolio decisions.
Product Type:
FDA clearance pathways diverge sharply between powered and manual staplers, with powered systems requiring electrical safety validations and battery subsystem documentation that manual platforms bypass entirely.
- Powered Staplers:Electromechanical instruments deploy staples using battery-driven firing mechanisms calibrated for consistent compression force across tissue thicknesses. Hospital procurement committees in the United States standardize on these platforms to reduce training overhead and inventory complexity. The FDA's 510(k) framework for powered staplers accelerates product iteration relative to premarket approval timelines.
- Disposable Staplers:Single-use instruments eliminate reprocessing infrastructure requirements, making them dominant in ambulatory surgical centers converting procedure volumes from inpatient settings. Freestanding ASCs in the United States favor these systems for their elimination of sterilization overhead and reduced liability exposure.
- Manual Staplers:Hand-actuated mechanical devices remain prevalent in cost-sensitive public hospital systems where capital constraints limit powered platform adoption.
- Articulating Staplers:Flexible shaft configurations enable stapling access in confined anatomical spaces during laparoscopic procedures.
Established volume favors powered staplers; emerging adoption favors disposable platforms.
Application:
Procedure-specific reimbursement codes and clinical evidence requirements segment demand by surgical specialty, with gastrointestinal and thoracic applications commanding distinct regulatory dossiers.
- Gastrointestinal Surgery:Resection and anastomosis procedures in colorectal and gastric interventions constitute the largest addressable volume for stapling platforms. Academic medical centers in Germany and the United States pilot smart staplers with load-cell feedback for these high-leak-risk applications.
- Gynecological Procedures:Laparoscopic hysterectomy protocols are standardizing mechanical stapling for anastomosis, institutionalizing device-dependent surgical technique across hospital systems. Surgical societies in the United States mandate stapling for specific hysterectomy steps.
- Thoracic Surgery:Lung resection and bronchial closure procedures require precise staple line integrity where leak rates carry mortality consequences.
- Urological Treatments:Prostatectomy and nephrectomy applications demand specialized cartridge configurations for vascular pedicle control.
- General Surgery:Appendectomy, cholecystectomy, and hernia repair represent high-volume, lower-acuity applications where cost optimization dominates procurement.
Institutionalized protocol favors gastrointestinal applications; gynecological procedures are climbing the fastest.
End User:
Customer type determines pricing tolerance, contract structure, and service requirements, with hospital consolidation reshaping purchasing authority across facility categories.
- Hospitals:Inpatient facilities with centralized value analysis committees negotiate direct manufacturer contracts for high-volume staple cartridge categories. Integrated delivery networks like HCA and CommonSpirit standardize on single-source agreements across multi-state footprints.
- Ambulatory Surgical Centers:Freestanding facilities prioritize disposable cartridge systems that eliminate reprocessing infrastructure and reduce turnover time between cases.
- Academic Medical Centers:Teaching hospitals pilot smart staplers with real-time tissue thickness measurement for complex anastomoses where clinical outcomes drive purchasing decisions.
- Specialty Clinics:Focused urology and gynecology practices favor procedure-specific cartridge configurations with lower minimum order quantities.
Contract concentration favors hospitals; volume migration favors ambulatory surgical centers.
Technology:
Cartridge mechanism design determines regulatory classification, with fully automated systems facing heightened EU MDR clinical evidence requirements.
- Reloadable Cartridges:Proprietary anvil technology platforms allow handle reuse with disposable staple cartridges, creating switching friction against fully disposable conversions. Hospital-installed bases of reloadable handles sustain legacy compatibility requirements.
- Single-Use Mechanism:Fully disposable systems bypass reprocessing validation entirely, aligning with ASC operational models and liability reduction priorities.
- Semi-Automated Systems:Partially powered firing mechanisms bridge manual and fully powered categories for cost-conscious facilities.
- Fully Automated Devices:Complete electromechanical control with integrated sensors faces extended EU MDR trial timelines, delaying revenue recognition versus historical CE-marking schedules.
Legacy installed base favors reloadable cartridges; regulatory efficiency favors single-use mechanisms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of surgical stapling devices concentrate in manufacturing clusters serving regulated markets, while import dependence characterizes emerging economies building surgical infrastructure. Trade balances reflect divergent regulatory maturity and domestic production capabilities across major economies.
United States
Hospital consolidation into integrated delivery networks like HCA and CommonSpirit drives bulk procurement of disposable stapler systems. FDA's 510(k) clearance pathway for powered staplers accelerates product iteration cycles relative to premarket approval timelines. Minneapolis and Boston anchor device manufacturing clusters where polymer molding operations supply cartridge housings.
Germany
Academic medical centers in Heidelberg and Berlin pilot smart staplers with load-cell feedback for complex anastomoses where leak rates carry mortality consequences. EU Medical Device Regulation imposes stricter clinical evidence requirements for powered systems entering European markets. Baden-Württemberg concentrates precision engineering subcontractors serving stapler mechanism assembly.
China
Lepu Medical Technology anchors domestic production through cost-optimized manual stapler manufacturing at scale. NMPA regulatory harmonization with ISO 13485 standards streamlines quality certification for export-oriented operations. Suzhou and Shenzhen house injection molding clusters supplying cartridge components to regional assemblers.
India
The PLI scheme for medical devices subsidizes domestic manufacturing scale-up for export-oriented stapler assembly operations. CDSCO quality management requirements create entry barriers for uncertified imports. Gujarat and Karnataka host emerging production facilities targeting Middle East and African markets.
Brazil
ANVISA regulatory harmonization with ISO 13485 standards opens procurement channels for quality-certified manufacturers previously excluded by local content requirements. Public hospital modernization programs create demand for disposable cartridge systems. São Paulo concentrates distribution infrastructure serving Latin American markets.
Surgical Stapling Devices Market Key Industry Players
Concentration sits with integrated multinationals controlling polymer supply chains and proprietary anvil technology. The vendor base separates into three tiers: captive manufacturers with in-house molding operations, reloadable platform specialists, and cost-optimized manual device producers. M&A activity targets cartridge technology assets, while capacity expansion concentrates in India and China to leverage export incentives and labor arbitrage.
Among diversified medical technology conglomerates, Medtronic Plc and Johnson & Johnson (Ethicon, Inc.) exemplify the integrated tier with captive supply chain control. CONMED Corporation occupies a position within the mid-tier specialist segment. These entities represent contrasting strategic postures: multinational scale versus focused surgical device specialization.
| Leading Market Players |
|---|
| Intuitive Surgical Inc |
| CONMED Corporation |
| Medtronic Plc |
| Smith+Nephew |
| B. Braun SE |
| Johnson & Johnson (Ethicon, Inc.) |
| 3M Company |
| Purple Surgical |
| Lepu Medical Technology |
| Others |
Cost & Logistics Intelligence
Long-term cartridge supply contracts lock in titanium wire feedstock access and stabilize procurement costs for integrated manufacturers serving hospital IDNs. These arrangements bind polymer housing suppliers to multi-year capacity reservations, insulating device makers from aerospace-driven titanium price cycles while constraining flexibility for spot-market sourcing.
Pricing Analysis
Hospital IDN procurement committees anchor three-tier pricing structure across premium, standard, and economy levels in surgical stapling. Price differentiation hinges on FDA 510(k) clearance tier and volume scale commitments, with academic medical centers least sensitive and ASCs most price-conscious. Pricing pressure stems from ASC conversion to disposable platforms, compressing margin realization for reloadable cartridge tiers.
Supply Chain Analysis
China and the United States anchor precision polymer injection molding for cartridge housings, while Germany concentrates anvil machining and mechanism assembly. Titanium staple wire draws from aerospace-qualified metallurgical suppliers in Japan and the United States. Single-source vulnerability sits with specialized molding technicians, constraining capacity expansion. Distribution runs through GPO contracts and direct IDN agreements, bypassing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical stapling devices market exhibits cyclical recovery characteristics as hospital capital expenditure rebounds from pandemic-era deferrals, with ambulatory surgical center construction serving as the primary cyclical driver.
For Market Incumbents: Shield proprietary anvil installed bases through backward integration into polymer molding capacity and exclusive GPO contract renewals. Threats from RFID-enabled smart stapler entrants and EU MDR compliance cost escalation demand preemptive certification investment in next-generation sensor platforms. For New Entrants and Emerging Players: Anchor in Brazilian public hospital modernization and Indian PLI-subsidized export manufacturing as white-space targets. The Brazilian ANVISA harmonization window offers the most penetrable regulatory pathway, with cost-optimized disposable platforms as the optimal go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier cartridge technology specialists with captive ISO 13485 certification and established notified body relationships. Long-term viability over the next decade rests on EU MDR compliance infrastructure and ASC channel penetration. The signal to watch is FDA 510(k) clearance velocity for powered staplers with integrated tissue sensing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance pathways for powered staplers compress competitive response windows in the United States. |
| CE Marking Pathway | EU MDR clinical evidence requirements extend timelines but create barriers against non-compliant competitors. |
| Hospital System Partnership | Direct IDN contracts with HCA or CommonSpirit standardize procurement across multi-state footprints. |
| Software Companion Development | Load-cell feedback algorithms differentiate smart staplers in bariatric and thoracic applications. |
| Reimbursement Strategy | CPT code alignment for disposable cartridges in ASC settings unlocks volume migration from inpatient settings. |
Research Approach
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at device manufacturers and refined through secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up volume modeling triangulated with top-down market sizing across product type, application, end user, and technology dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price realization effects, with segmentation modeling spanning powered versus manual platforms, gastrointestinal versus gynecological applications, hospital versus ASC end users, and reloadable versus single-use technologies. CAGRs derive from logistic diffusion curves for powered stapler adoption and linear extrapolation of ASC construction permits, with titanium price volatility and EU MDR notified body capacity as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of continued FDA 510(k) pathway efficiency and stable hospital consolidation trajectories; material deviation in regulatory timelines or titanium supply disruptions would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Endoscopic Closure Systems Market
Surgical Instruments
Ultrasonic Surgical Cutters Market
Surgical Instruments
Surgical Drainage Devices Market
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Colorectal Procedure Market
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Surgical Snare Market
Surgical Instruments
Laparoscopic Gynecological Procedures Market
Surgical Instruments
Surgical Sphincteroplasty Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Adult Cardiovascular Surgical Instruments Package Market
Surgical Instruments
High Flow Needle Sets Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Global Surgical Suction Instruments Market
Surgical Instruments
Asia Pacific Surgical Equipment Market
Surgical Instruments
Endoluminal Suturing Devices Market