
 Medical Transcription Services Market | 2026-2036
Medical Transcription Services Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Transcription Services Market Analysis
Hospital systems are gaining share as the dominant buyer archetype, while independent physician practices are shrinking as a proportion of transcription spend; the demand base is bifurcating between large consolidated health networks and smaller cash-constrained operators. Nuance Communications dominates speech recognition technology leadership in clinical documentation workflows. AQuity Solutions anchors its competitive position through hybrid service models that blend offshore labor with domestic quality oversight. MTBC sustains cost advantages by leveraging cloud-based delivery infrastructure across multi-site hospital deployments.
Medical transcription services convert physician-dictated clinical encounters into structured text records using a combination of manual typists, speech recognition engines, and natural language processing algorithms, typically achieving turnaround times between four and twenty-four hours depending on acuity and service tier. The primary commercial purpose is to generate billable, legally admissible documentation that supports reimbursement claims and continuity of care. Outsourced services command the largest revenue pool among service types, though cloud-based platforms represent the fastest-growing segment as health systems abandon on-premise infrastructure. AI-driven transcription technology is displacing manual typing in high-volume specialties such as radiology and emergency medicine, while hybrid models retain dominance in complex subspecialties where clinical nuance demands human verification.
FDA oversight of clinical decision support tools intersects with HIPAA privacy mandates to create compliance complexity for vendors integrating AI into transcription workflows, effectively raising barriers to market entry. The EPA's energy efficiency standards for data centers indirectly shape cloud-based transcription economics as server density requirements escalate. OSHA workplace guidelines for home-based medical transcriptionists affect labor cost structures in outsourced operations. Stakeholders must monitor how CMS reimbursement rulemaking around clinical documentation integrity will reshape transcription volume requirements and technology investment priorities.
Market Dynamics
The medical transcription services market is experiencing fundamental restructuring as AI-driven speech recognition technology reshapes labor composition and service delivery economics. Hospital consolidation and EHR documentation burdens are accelerating outsourcing decisions while compliance mandates complicate vendor selection.
Growth Catalysts
- HIPAA Compliance Mandates:Healthcare providers face intensifying audit scrutiny for clinical documentation integrity, driving demand for transcription vendors with certified security infrastructure and audit-ready workflows.
- Hospital System Consolidation:Merged health networks generate economies of scale in documentation outsourcing, concentrating procurement power and favoring vendors with multi-site deployment capabilities.
- Natural Language Processing Advancement:Clinical NLP engines now extract structured data from unstructured dictation, enabling population health analytics and quality reporting that manual transcription cannot support.
Market Restraints
- Cloud Infrastructure Concentration:Transcription platform providers depend heavily on hyperscale cloud providers in the United States, creating single-point vulnerability for service continuity and data sovereignty.
- Clinical Nuance Limitations:AI speech recognition struggles with accented speech, rare disease terminology, and complex subspecialty vocabulary, preserving manual labor requirements in high-acuity documentation.
- FDA Regulatory Friction:Clinical decision support integration with transcription workflows triggers software-as-medical-device classification requirements, extending compliance timelines and development costs.
Strategic Opportunities
- Ambulatory Surgery Center Expansion:Freestanding surgical facilities in the United States lack in-house documentation infrastructure, creating greenfield demand for cloud-based transcription subscriptions.
- CMS Value-Based Purchasing Alignment:Medicare reimbursement incentives for clinical documentation specificity reward health systems that invest in AI-augmented transcription for quality measure capture.
- Telehealth-Tribrid Convergence:Integration of synchronous video, asynchronous audio, and automated transcription into unified platforms addresses hybrid care documentation gaps emerging from virtual visit growth.
Industry Challenges
- Medical Vocabulary Specialization Gap:Transcription workforce training lags behind evolving subspecialty terminology in oncology genomics and precision medicine, degrading accuracy in high-revenue documentation.
- EHR Interoperability Complexity:Proprietary data formats from Epic, Cerner, and MEDITECH require costly custom integration development for seamless transcription workflow embedding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Transcription Services Market |
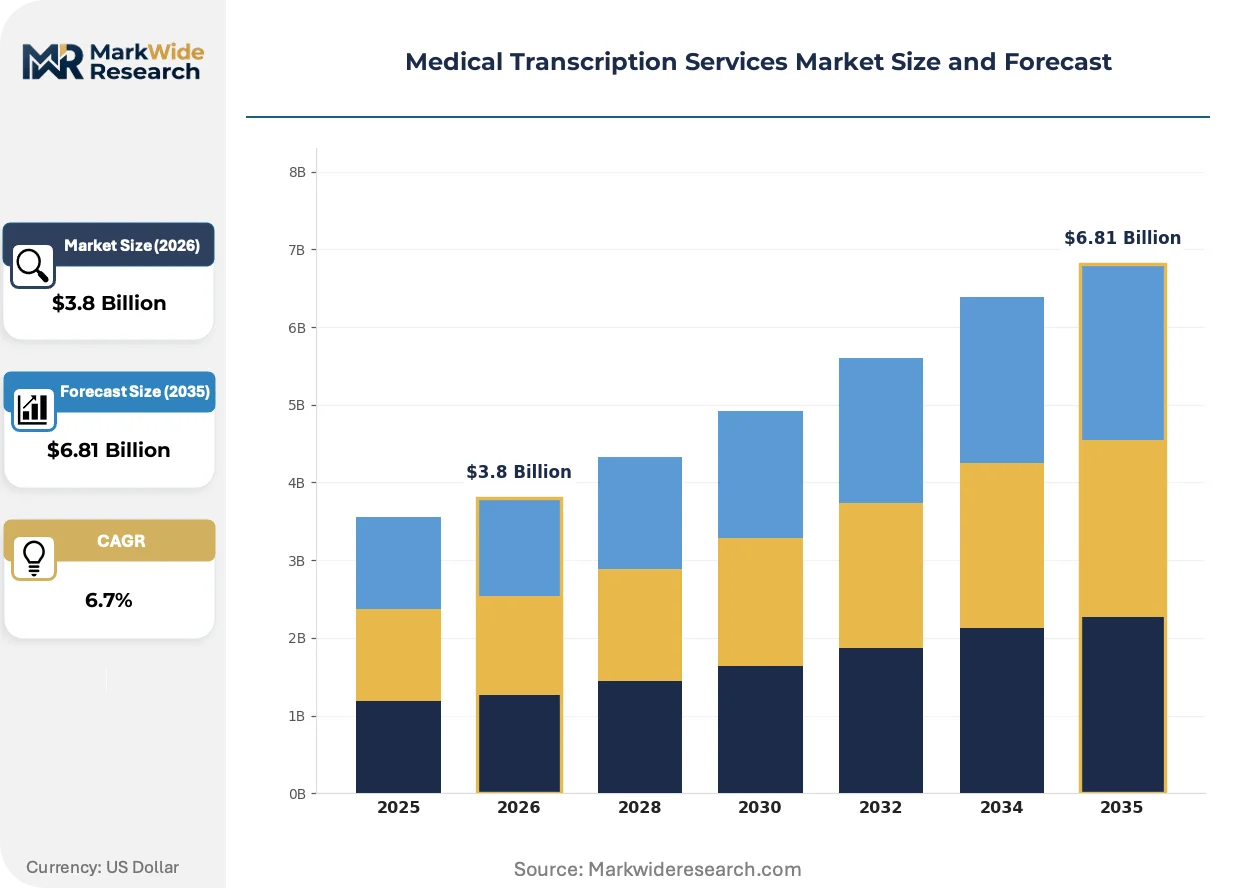
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Outsourced, In-house, Hybrid, Cloud-based End User: Clinics, Hospitals, Laboratories, Healthcare Providers Delivery Mode: On-demand, Real-time, Batch, Scheduled Technology: Speech Recognition, AI-driven, Manual Typing, Cloud Technology |
| Companies Covered | GoTranscript, InSync Healthcare Solutions, Nuance Communications, Macgence, World Wide Dictation, MedQuist Holdings, AQuity Solutions, Tomedes Translation Company, MTBC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Transcription Services Market Emerging Trajectories
Clinical documentation technology is undergoing rapid capability expansion as artificial intelligence matures and regulatory frameworks adapt. Three interconnected developments are restructuring competitive positioning and buyer expectations.
Speech recognition technology is bifurcating the transcription labor market between high-volume, low-complexity specialties and nuanced subspecialty documentation. Radiology and emergency medicine departments now deploy fully automated transcription with minimal human oversight. Complex surgical subspecialties and psychiatry retain hybrid models requiring physician-trained editors. This division is compressing pricing for commodity transcription while inflating premiums for clinical-verification services.
The FDA's evolving oversight of clinical decision support software intersects with HIPAA security rule enforcement to create dual compliance burdens for AI-integrated transcription vendors. Software outputs that trigger diagnostic or treatment recommendations face heightened regulatory scrutiny. Vendors serving academic medical centers and integrated delivery networks invest disproportionately in quality management system documentation to satisfy joint agency expectations.
Health system procurement departments now unbundle transcription services from legacy EHR implementation contracts, creating direct vendor relationships with specialized documentation platforms. This disintermediation of EHR vendors as transcription gatekeepers enables price transparency and service customization previously unavailable to hospital buyers. The shift is most visible in the United States where health system consolidation has centralized supply chain decision-making.
Medical Transcription Services Market Segmentation
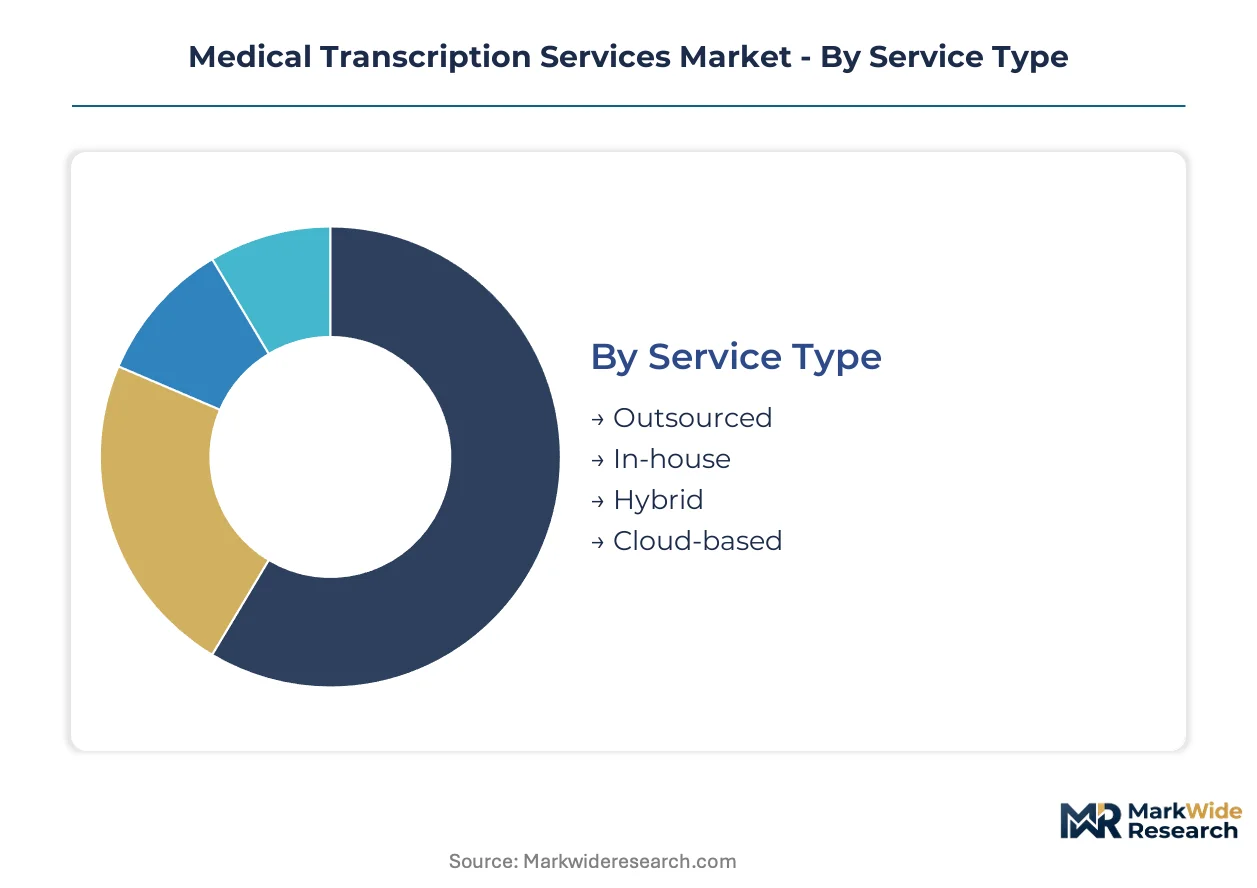
Medical transcription services fragment across service delivery models, buyer archetypes, and technology stacks that determine compliance posture, turnaround economics, and integration complexity. Segmentation reveals where procurement power concentrates and which technology transitions are displacing legacy workflows.
Service Type:
Domestic health systems favor in-house and hybrid models for HIPAA audit control, while export-oriented transcription flows concentrate in offshore outsourced operations serving United States hospital networks.
- Outsourced:Third-party vendors operate transcription labor pools from India, the Philippines, and domestic United States locations, offering 12-24 hour turnaround through distributed workforce models. United States hospital consolidation drives procurement toward multi-site vendors with SOC 2 Type II certification and dedicated account management infrastructure.
- Cloud-based:Browser-accessible platforms eliminate on-premise server maintenance, enabling ambulatory surgery centers and small clinic chains to subscribe without capital expenditure. The steepest expansion runs through this segment as health systems abandon data center ownership for AWS and Azure-hosted transcription infrastructure.
- In-house:Large integrated delivery networks maintain captive transcription departments for high-acuity specialties requiring immediate turnaround and direct physician-editor collaboration.
- Hybrid:Combines automated speech recognition front-end with human editors for quality assurance, preserving clinical nuance verification while compressing labor costs.
Outsourced commands the established base. The steepest expansion runs through cloud-based.
End User:
Cost tier separation distinguishes capital-rich hospital buyers from price-constrained independent operators, with documentation volume scale determining technology investment feasibility.
- Hospitals:Academic medical centers and consolidated health networks generate the highest transcription volumes, justifying AI speech recognition deployment and dedicated integration engineering with Epic and Cerner EHR systems. United States health system mergers concentrate procurement power among fewer buyers demanding enterprise-grade security architecture.
- Healthcare Providers:Physician practice management organizations and accountable care organizations aggregate transcription demand across affiliated clinicians, creating mid-market subscription opportunities for platform vendors. The steepest expansion trajectory sits here as provider consolidation accelerates documentation standardization requirements.
- Clinics:Independent physician practices and specialty clinics rely on pay-per-use outsourced transcription due to irregular documentation volumes and limited IT staffing.
- Laboratories:Pathology and diagnostic imaging centers require specialized terminology expertise for molecular diagnostics and genomic sequencing reports, preserving premium-priced manual transcription niches.
Hospitals command the established base. Healthcare providers are climbing the fastest.
Delivery Mode:
Application urgency separates emergency documentation requiring immediate availability from routine records tolerating batch processing economics.
- Real-time:Synchronous transcription during patient encounters supports emergency department workflow integration and operating room documentation, demanding sub-60-second latency through edge-computing speech recognition deployment.
- On-demand:Triggered by physician request with 2-4 hour turnaround targets, serving urgent care and same-day surgery centers where documentation completeness affects discharge readiness.
- Batch:Accumulated dictation queues processed during off-peak hours optimize labor costs for routine outpatient encounters with 12-24 hour acceptable windows.
- Scheduled:Pre-arranged transcription slots for predictable documentation volumes such as elective surgery pre-operative notes and discharge summary backlogs.
Batch commands the established base. Real-time gains share fastest.
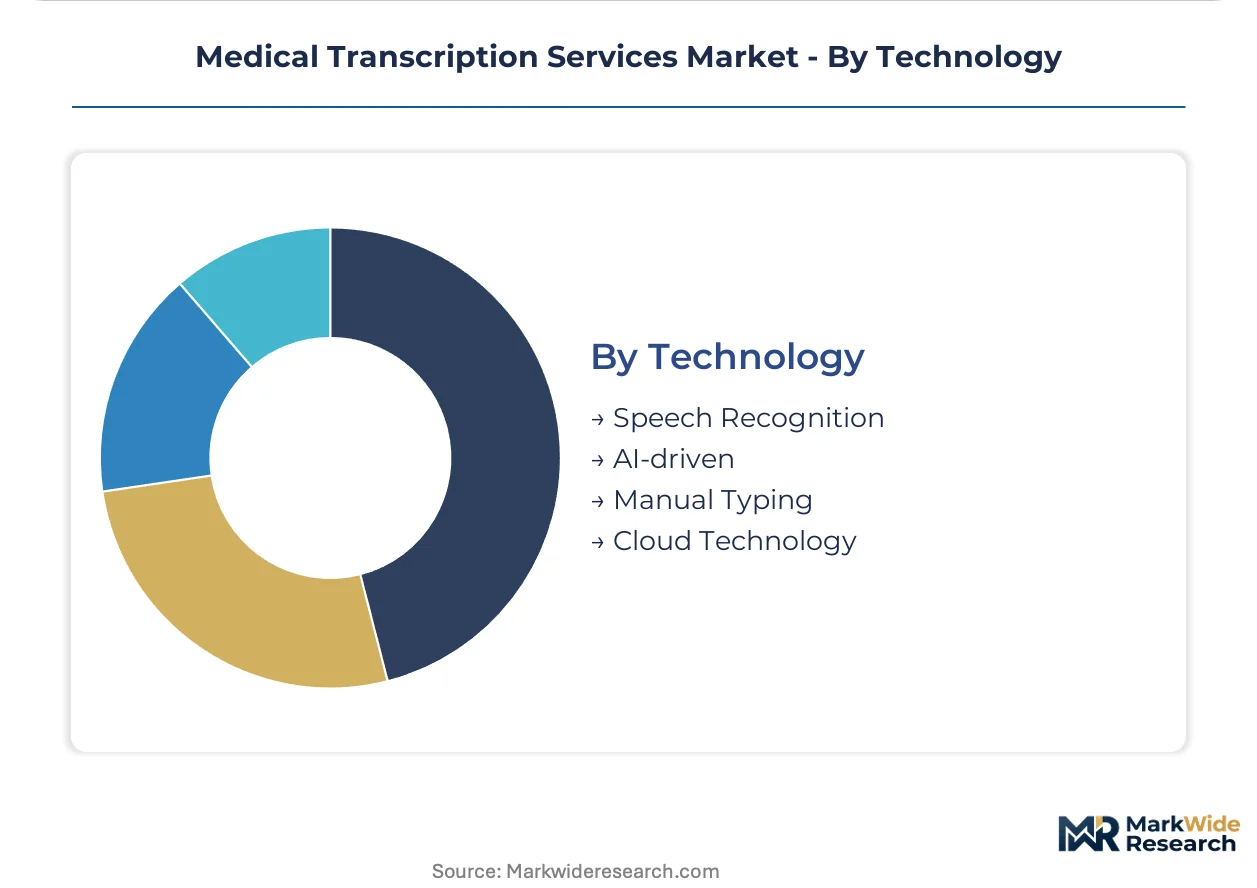
Technology:
Maturity curves separate legacy manual operations from AI deployment, with implementation cost and clinical accuracy requirements determining adoption speed across buyer segments.
- AI-driven:Deep learning models trained on millions of clinical encounters now extract structured data elements for quality reporting and population health analytics, enabling reimbursement optimization that manual transcription cannot support. United States academic medical centers pilot clinical decision support integration requiring FDA software-as-medical-device compliance pathways.
- Speech Recognition:Natural language processing engines from Nuance and 3M transform physician dictation into draft documentation with 85-95% accuracy in high-volume specialties, compressing editor labor requirements by 40-60%.
- Manual Typing:Human transcriptionists retain dominance in psychiatry, complex surgical subspecialties, and accented-speech encounters where clinical nuance and speaker variability exceed current AI capabilities.
- Cloud Technology:Distributed computing infrastructure enables elastic capacity scaling for seasonal documentation surges and disaster recovery continuity.
Manual typing commands the established base. AI-driven shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States health information exchange networks and cross-border data corridors through submarine cable landing stations in Virginia and California underpin the geographic distribution of transcription infrastructure investment.
United States
Hospital system consolidation and EHR documentation burdens concentrate procurement power among fewer buyers. HIPAA enforcement actions by the Office for Civil Rights intensify vendor security certification requirements. The Nashville-Dallas corridor hosts multiple transcription platform headquarters serving multi-site health networks.
Canada
Provincial health authority digitization initiatives expand cloud-based documentation procurement. Health Canada guidance on medical device software intersects with provincial privacy laws to shape AI transcription adoption timelines. Toronto's health technology cluster anchors vendor development for English-French bilingual clinical documentation.
United Kingdom
NHS digital transformation programs accelerate outsourcing of clinical correspondence services. NHSX interoperability standards and Information Commissioner's Office GDPR enforcement create dual compliance frameworks for transcription vendors. London's health informatics corridor concentrates platform engineering talent serving European health systems.
Germany
Hospital IT modernization funding under the Hospital Future Act drives speech recognition procurement in acute care settings. BfArM medical device classification requirements for clinical decision support integration extend vendor compliance timelines. The Munich-Berlin corridor hosts transcription technology development for German-speaking clinical workflows.
India
Export-oriented medical transcription services leverage English-language workforce availability and time-zone arbitrage for United States hospital clients. MeitY data localization guidelines and CERT-In cybersecurity directives reshape offshore delivery infrastructure requirements. Bangalore and Hyderabad transcription operations centers serve as quality oversight hubs for hybrid service models.
Medical Transcription Services Market Vendor Landscape
Listed leaders compete with private specialists across technology licensing and service delivery dimensions, producing a tiered market structure where scale advantages concentrate among platform-integrated vendors. Consolidation pressures favor multi-site deployment capabilities and SOC 2 Type II certification infrastructure. Three archetypes dominate: speech recognition technology licensors, hybrid human-AI service operators, and cloud-native platform specialists. M&A activity targets geographic expansion and EHR integration capabilities, while strategic partnerships address AI training data access and clinical NLP development.
Within the technology licensor tier, Nuance Communications exemplifies platform-integrated positioning through deep EHR workflow embedding. AQuity Solutions and MTBC occupy distinct positions in the hybrid service operator archetype, with the former representing offshore-domestic quality oversight models and the latter illustrating cloud-native multi-site deployment economics. These three anchors demonstrate how competitive differentiation flows from infrastructure choices rather than transcription labor alone.
| Leading Market Players |
|---|
| GoTranscript |
| InSync Healthcare Solutions |
| Nuance Communications |
| Macgence |
| World Wide Dictation |
| MedQuist Holdings |
| AQuity Solutions |
| Tomedes Translation Company |
| MTBC |
| Others |
Supply Flow & Price Mechanics
Capacity reservation contracts with multi-year terms lock in transcription labor pools and cloud infrastructure access while providing health systems with predictable per-line costs and audit-ready compliance documentation. These arrangements concentrate procurement leverage among consolidated United States hospital networks and compress margins for vendors serving smaller clinic operators without volume scale.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise health systems, mid-tier provider organizations, and independent practices with steep per-unit penalties for low-volume accounts. Pricing separates SOC 2 Type II certified vendors with dedicated account management from commodity offshore operators and cloud-native platform subscriptions. Cost compression in manual transcription tiers is intensifying as AI speech recognition displaces human editors in radiology and emergency medicine documentation. Independent physician practices exhibit highest price sensitivity due to irregular documentation volumes, while academic medical centers prioritize clinical accuracy verification over per-line economics.
Supply Chain Analysis
Inventory and lead-time dynamics in transcription labor markets hinge on time-zone arbitrage between India and the Philippines for overnight turnaround and domestic United States editors for same-day urgent documentation. Supply concentrates transcription workforce development in Bangalore and Hyderabad, cloud infrastructure provisioning through AWS and Azure data centers in Virginia and California, and quality oversight operations in Nashville and Dallas. The supply chain draws from English-language medical training pipelines, HIPAA-compliant data center certifications, and clinical NLP training datasets. Single-source vulnerability in hyperscale cloud concentration creates continuity risk for platform-dependent vendors. Distribution runs through direct enterprise sales to hospital procurement departments and channel partnerships with EHR integration specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through HIPAA compliance certification and EHR workflow embedding creates substantial switching costs that protect incumbent positions.
For Market Incumbents: Fortify competitive position by deepening clinical NLP R&D investment for complex subspecialty documentation where AI accuracy remains below human-editor thresholds. Pursue backward integration into cloud infrastructure through dedicated AWS and Azure capacity reservations to reduce hyperscale provider dependency. Defend against pure-play AI entrants by emphasizing hybrid human-AI service models that satisfy Joint Commission documentation integrity requirements. For New Entrants and Emerging Players: Ambulatory surgery center documentation gaps represent the most penetrable white-space target, as freestanding surgical facilities lack capital for in-house transcription departments and face urgent turnaround requirements for discharge readiness. Target this segment with browser-based subscription platforms requiring zero IT infrastructure investment. Penetrate through partnerships with surgery center management companies that aggregate procurement across multi-site networks. For Investors and Strategic Acquirers: Cloud-native platform specialists with proven Epic and Cerner integration engineering and established SOC 2 Type II audit trails represent the optimal acquisition archetype for portfolio positioning. Monitor CMS reimbursement rulemaking around clinical documentation integrity as the critical inflection signal for transcription volume requirements and technology investment prioritization across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical NLP R&D Investment | Advances accuracy in oncology genomics and precision medicine terminology where manual editors currently dominate. |
| Epic-Cerner Integration Partnership | Enables seamless workflow embedding that reduces physician documentation burden and accelerates EHR adoption. |
| HIPAA Compliance Certification Expansion | Satisfies intensifying Office for Civil Rights audit scrutiny and qualifies vendors for academic medical center procurement. |
| Hybrid Workforce Model Scaling | Combines India-Philippines overnight processing with domestic quality oversight to optimize cost-accuracy tradeoffs. |
| Ambulatory Surgery Center Market Entry | Captures greenfield demand from freestanding surgical facilities lacking in-house documentation infrastructure. |
Methodological Framework
Cross-validation between transcription vendor executive interviews and hospital procurement database analysis anchors the qualitative findings in operational reality. Primary fieldwork encompassed transcription platform CTOs, health system supply chain directors, GPO contracts managers, and clinical documentation integrity officers. Secondary validation drew from CMS Medicare reimbursement data, hospital procurement RFP documents, HIPAA breach notification archives, and cloud provider infrastructure disclosure filings. Bottom-up transcription volume modeling triangulated against top-down health system consolidation trends.
Sensitivity analysis across deployment model, buyer scale tier, and technology maturity segments informs the analytical framework over the projection horizon. Segmentation dimensions modeled include service delivery type, end-user archetype, delivery mode urgency, and AI integration depth. CAGRs were derived from volume trajectory analysis and value-per-transaction evolution. Forecast inputs incorporate EHR adoption curves, hospital merger activity, and clinical NLP accuracy improvement rates.
Underlying assumptions cover HIPAA enforcement continuity, hyperscale cloud pricing stability, and health system consolidation momentum, with deviation risk concentrated in FDA software-as-medical-device reclassification and CMS documentation requirement shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Funeral Products and Services Market
Healthcare Services
Hospital Command Center Operations Market
Healthcare Services
Canada Corporate Wellness Market
Healthcare Services
Spa Services Market
Healthcare Services
Global Concierge Medicine Market
Healthcare Services
Healthcare Patent Filing Outsourcing Market
Healthcare Services
Global Operating Room Management Market
Healthcare Services
Tissue Banking Market
Healthcare Services
Hospice Market
Healthcare Services
Australia Senior Living Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
Acute Care Market
Healthcare Services
US Care Services Market
Healthcare Services
Bruxism Management Market
Healthcare Services
Medical Spa Market
Healthcare Services
Hospital Outsourcing Market