
 Air Defense System Market | 2026-2036
Air Defense System Market Size, Share, and Industry Trends Forecast 2026-2036
Air Defense System Market Analysis
Poland's missile defense industrial base is narrowing its reliance on foreign subsystem imports through co-production agreements with Lockheed Martin Corporation. Raytheon Technologies sustains long-range interceptor development through captive gallium nitride radar foundry investments. Israel Aerospace Industries Ltd. dominates integrated battle management software architectures for layered defense networks across Eastern European deployments.
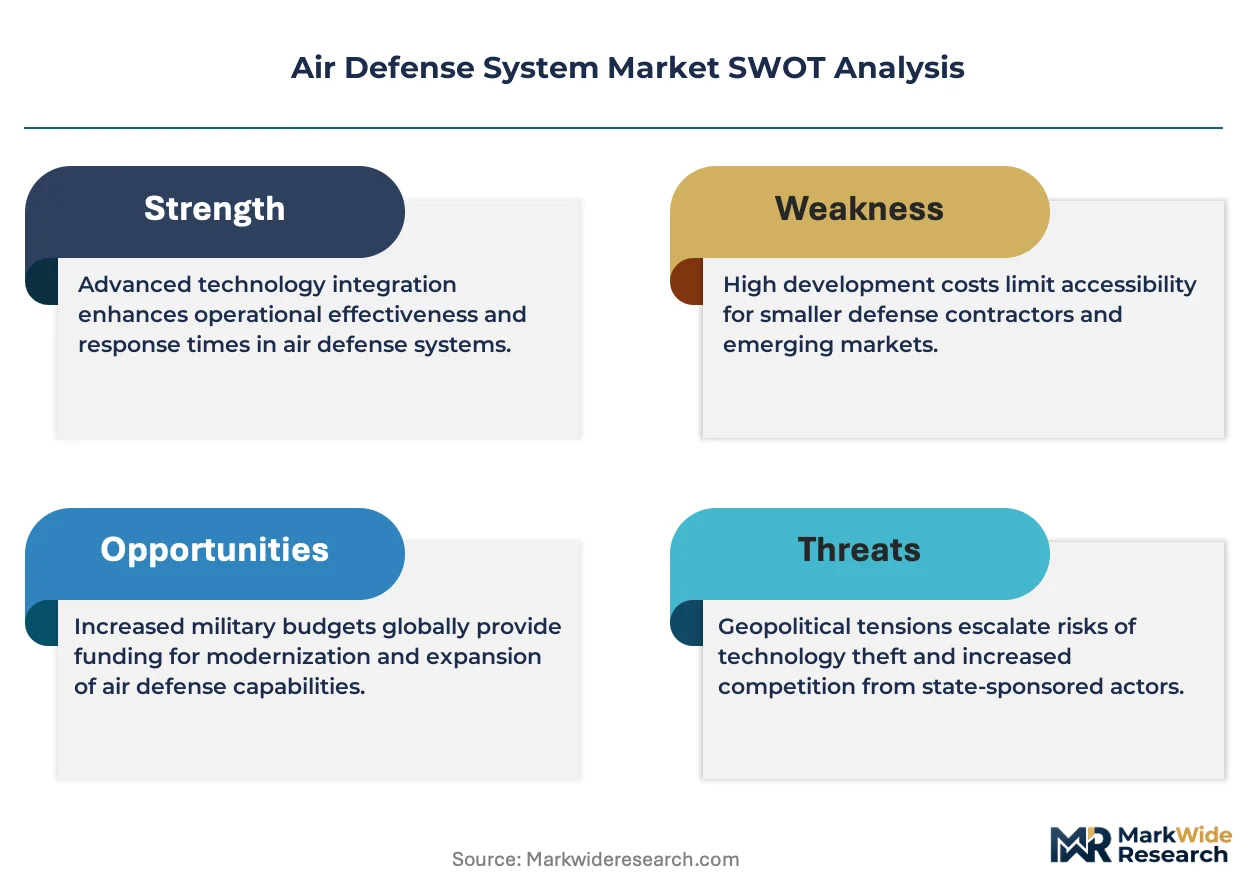
An air defense system constitutes an integrated weapons platform combining surveillance radars, fire control computers, and kinetic or directed-energy interceptors designed to detect, track, and neutralize hostile aircraft, cruise missiles, or ballistic projectiles. Missile systems occupy the largest value pool due to recurring procurement of hit-to-kill vehicles and propulsion stacks, while electronic warfare systems represent the fastest-expanding segment as jamming and spoofing capabilities merge with traditional hard-kill architectures. Ground-based technology anchors current deployment volumes, though hybrid systems linking aerial, naval, and terrestrial sensors are capturing disproportionate R&D allocation from defense ministries.
The United States Missile Defense Agency, NATO's Air and Missile Defense Committee, and Japan's Ministry of Defense shape certification pathways for cross-border system interoperability and technology transfer controls. These bodies mandate STANAG compliance for sensor fusion and restrict gallium nitride and rare-earth component sourcing to qualified domestic or allied suppliers. Stakeholders must weigh sovereign production mandates against supply chain concentration risks in semiconductor substrates and precision gyroscope manufacturing.
Market Dynamics
Hypersonic glide vehicles and autonomous drone swarms are forcing defense ministries to abandon single-layer intercept architectures in favor of networked, multi-domain sensor fusion that demands gallium nitride radar substrates and AI-enabled fire control at unprecedented scale.
Growth Catalysts
- STANAG 6016 Compliance Mandates:NATO's sensor interoperability protocols compel Eastern European members to upgrade legacy Soviet-era radars, creating captive demand for Western battle management systems.
- Directed Energy Maturation:Solid-state laser prototypes achieving 300kW output thresholds are transitioning from testbeds to mobile ground platforms, reducing per-intercept costs against drone swarms.
- Japan's Southwest Island Chain:Tokyo's dispersion of mobile interceptor units across Okinawa and the Ryukyu arc generates recurring procurement for compact, road-mobile launch systems.
Market Restraints
- Rare-Earth Magnet Concentration:Precision gyroscope and servo motor production depends on Chinese-processed neodymium and dysprosium, exposing Western prime contractors to export restriction vulnerability.
- Gallium Nitride Substrate Bottleneck:Single-crystal GaN wafer fabrication concentrates among three qualified foundries, creating 18-month lead times for active electronically scanned array radars.
- ITAR Classification Friction:US State Department munitions list controls delay technology transfer for co-production agreements with non-NATO partners, extending program timelines.
Strategic Opportunities
- Poland's Indigenous Production Mandate:Warsaw's offset requirements for Patriot and Narew programs create openings for local subsystem integration and software customization.
- Naval-Air-Ground Sensor Meshing:Convergence of shipborne Aegis ashore, airborne early warning, and terrestrial radar networks enables new integrated fire control architectures.
- Australia's Guided Weapons Enterprise:Canberra's AUKUS-aligned domestic manufacturing push offers partnership slots for precision seeker and propulsion stack suppliers.
Industry Challenges
- Cleared Workforce Scarcity:Polygraph-qualified software engineers and systems integration specialists face acute shortages, stretching program staffing across classified development environments.
- Legacy Radar Integration Complexity:Cold War-era semi-active homing systems resist seamless incorporation into modern network-centric architectures without costly mid-life upgrades.
- Hypersonic Interceptor Thermal Management:Kill vehicle designs must survive atmospheric reentry heating while maintaining guidance precision, demanding materials science breakthroughs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Defense System Market |
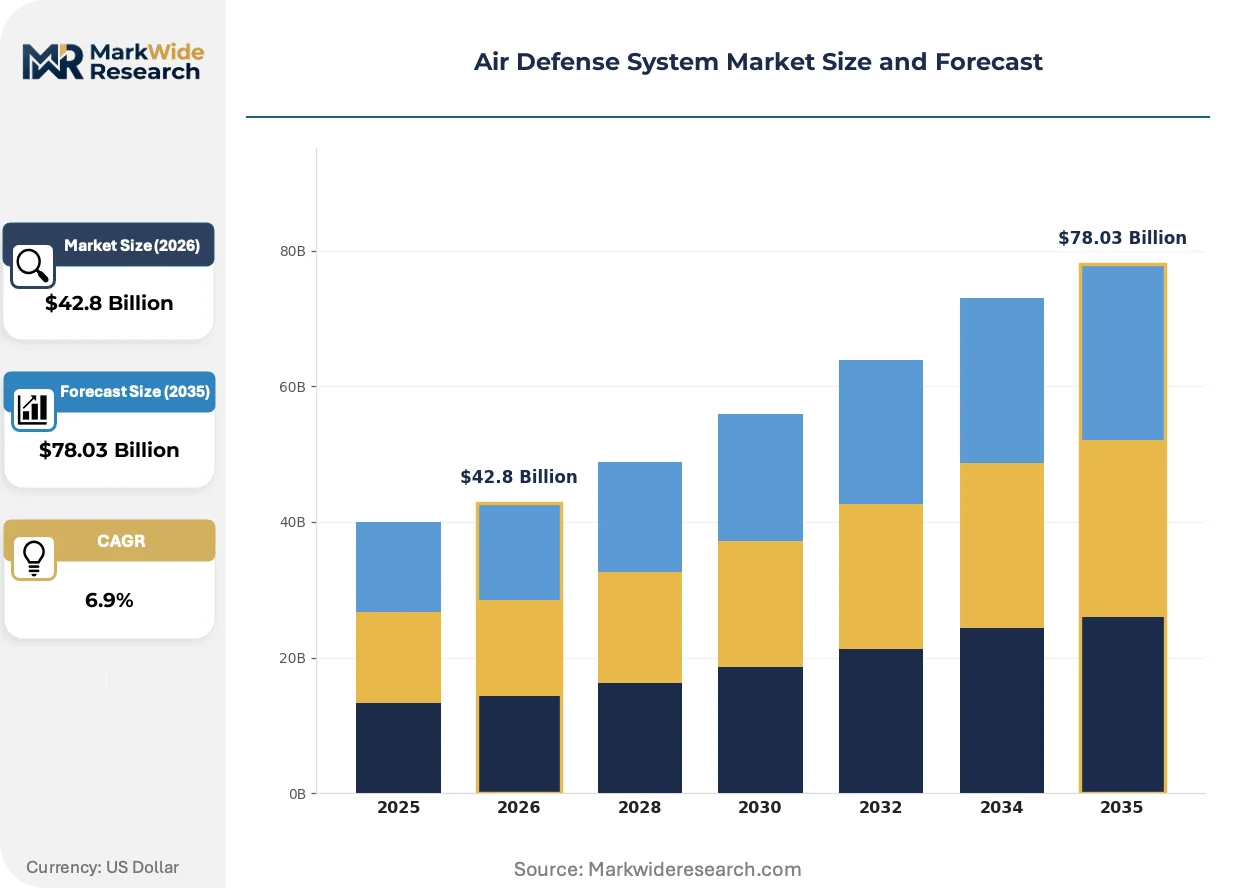
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $78.03 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Missile Systems, Radar Systems, Command & Control Systems, Electronic Warfare Systems End User: Military, Government, Defense Contractors, Aerospace Companies Technology: Ground-Based, Airborne, Sea-Based, Hybrid Systems Application: Ballistic Missile Defense, Airspace Security, Cyber Defense, Surveillance |
| Companies Covered | Lockheed Martin Corporation, Raytheon Technologies, Northrop Grumman Corporation, BAE Systems, Thales Group, Israel Aerospace Industries Ltd., Leonardo S.P.A., RTX Corporation, Hanwha Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Defense System Market Emerging Trajectories
Artificial intelligence inference at the sensor edge is compressing engagement timelines from minutes to seconds, eliminating human-in-the-loop authorization for saturation attacks while raising new questions about algorithmic accountability and electromagnetic spectrum dominance.
Solid-state active electronically scanned array radars utilizing gallium nitride transmit-receive modules are rendering obsolete mechanically scanned parabolic dish architectures. The US Missile Defense Agency and Japan's Ministry of Defense have standardized on these arrays for next-generation tracking systems. This transition compresses prime contractor margins on legacy platform sustainment while opening subsystem opportunities for specialized semiconductor houses.
REACH regulation restrictions on per- and polyfluoroalkyl substances are compelling European radar manufacturers to reformulate conformal coatings and thermal interface materials. The European Defence Agency has accelerated exemption pathways for defense-critical applications, but commercial-off-the-shelf component suppliers face compliance-driven discontinuations. German and French prime contractors are responding by qualifying domestic specialty chemical alternatives.
Buyer concentration among national procurement agencies is consolidating program authority into fewer, larger indefinite-delivery contracts. The US Army's Lower Tier Air and Missile Defense program and Poland's Wisla procurement exemplify this pattern, displacing fragmented service-specific acquisitions. This shift is most pronounced in NATO's eastern flank, where ministries of defense prioritize interoperable, multi-mission batteries over single-purpose point defense systems.
Air Defense System Market Segmentation
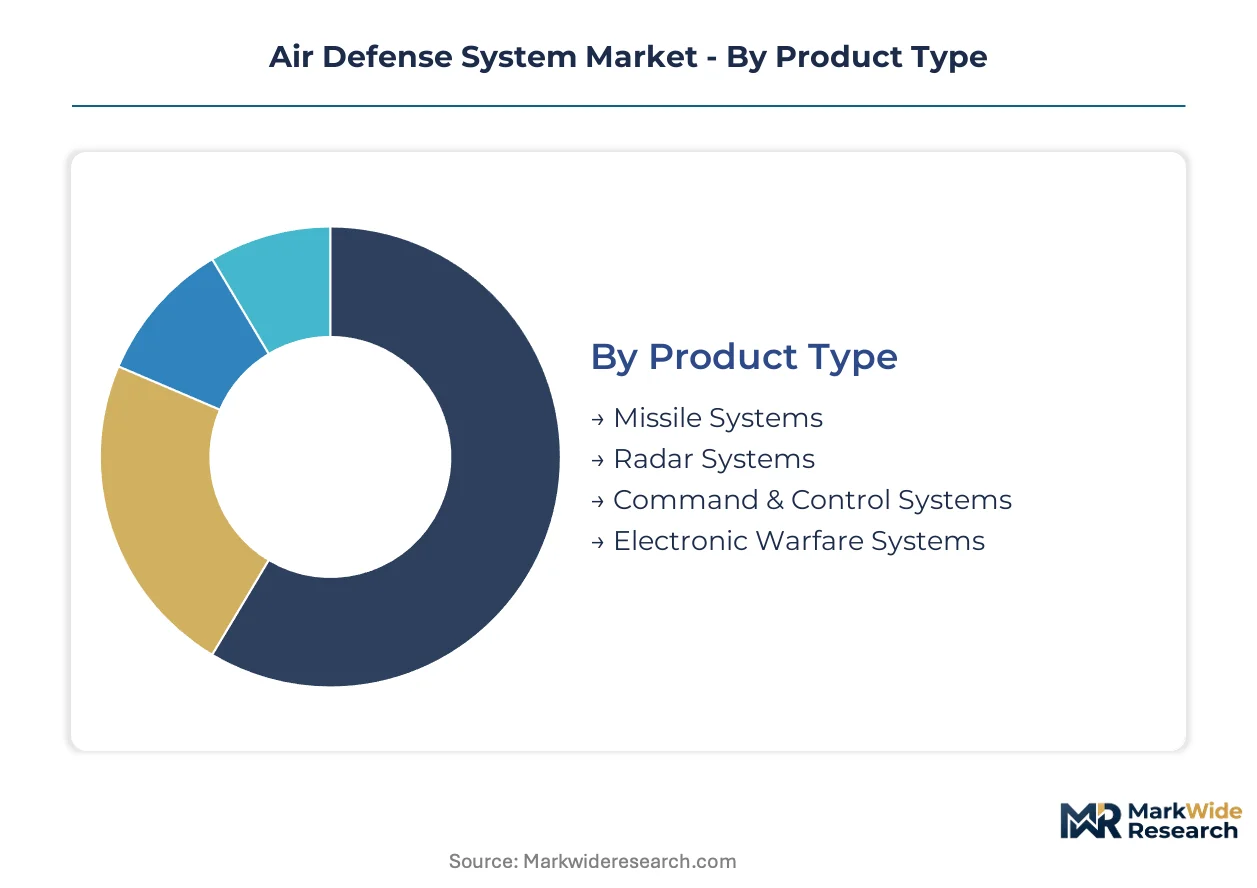
Segmentation in air defense systems reveals divergent lifecycle economics. Missile systems demand intensive depot-level refurbishment, while radar platforms require continuous software sustainment. Understanding these service intensity patterns shapes procurement strategy and vendor selection.
Product Type:
After-sales-service intensity varies sharply across product categories, with propulsion stack overhaul and seeker recalibration driving recurring revenue for missile suppliers.
- Missile Systems:Hit-to-kill interceptors and propulsion vehicles incorporate precision seekers and solid-fuel motors requiring periodic recertification. Demand concentrates in Poland and Japan as both nations establish indigenous final assembly lines for Patriot and Type-03 derivatives. Recurring procurement of propulsion stacks and guidance sections sustains long-term supplier relationships.
- Electronic Warfare Systems:Jamming pods and deception transmitters merge software-defined radio architectures with gallium nitride power amplifiers. NATO's eastern flank members prioritize these capabilities for counter-drone applications, with Romania and Bulgaria accelerating procurement following Black Sea incidents.
- Radar Systems:Active electronically scanned arrays utilize gallium nitride transmit-receive modules for target discrimination.
- Command & Control Systems:Battle management software integrates sensor feeds from heterogeneous platforms.
By volume, Missile Systems leads. By growth pace, Electronic Warfare Systems is ahead.
End User:
Cost tier stratification separates sovereign procurement agencies from subcontractor supply chains, with defense contractors absorbing technology transfer compliance burdens.
- Military:National armed forces operate the primary demand channel, with the US Missile Defense Agency and Japan's Ministry of Defense setting technical specifications. These agencies mandate STANAG interoperability and restrict gallium nitride sourcing to qualified suppliers, creating captive procurement frameworks.
- Defense Contractors:Prime contractors serve as system integrators for foreign military sales, managing ITAR clearance and co-production agreements. Poland's offset requirements for Wisla and Narew programs channel substantial contract value through this tier.
- Government:Civil defense and homeland security agencies acquire point defense for critical infrastructure.
- Aerospace Companies:Platform manufacturers integrate defensive suites into airframe designs.
By contract value, Military dominates. By commercial complexity, Defense Contractors shows the steepest expansion trajectory.
Technology:
Deployment maturity ranges from proven ground-based architectures to experimental hybrid networks demanding unprecedented sensor fusion.
- Ground-Based:Fixed and mobile terrestrial batteries anchor current deployment volumes, with Aegis Ashore installations in Poland and Romania representing capital-intensive commitments. These systems integrate with NATO's Active Layered Theater Ballistic Missile Defense network.
- Hybrid Systems:Converged naval-air-ground architectures enable integrated fire control across domains. Australia's AUKUS-aligned investments and Japan's Southwest Island Chain dispersion drive demand for mesh networking capabilities.
- Airborne:Platform-mounted defensive suites protect high-value aircraft.
- Sea-Based:Naval vertical launch systems provide fleet area defense.
By installed base, Ground-Based leads. By capability investment, Hybrid Systems is gaining share fastest.
Application:
Threat vector specialization determines procurement priority, with hypersonic glide vehicles forcing abandonment of legacy single-mission architectures.
- Ballistic Missile Defense:Exoatmospheric and terminal interceptors address theater-range threats. The US Missile Defense Agency's Next Generation Interceptor program and Japan's layered defense for Okinawa concentrate demand for hit-to-kill vehicles with divert and attitude control systems.
- Airspace Security:Counter-drone and cruise missile defense applications expand rapidly as autonomous swarm threats proliferate. Directed energy prototypes achieving 300kW output transition toward mobile deployment for this mission.
- Cyber Defense:Electronic protection for command networks resists jamming and spoofing.
- Surveillance:Persistent radar coverage for border and maritime domains.
By program scale, Ballistic Missile Defense leads. By urgency of procurement acceleration, Airspace Security is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Missile Defense Agency anchors procurement frameworks that cascade through NATO interoperability mandates and Pacific alliance structures. National procurement patterns diverge sharply between established defense industrial bases and emerging domestic production mandates.
United States
Washington's layered defense investments concentrate in ground-based midcourse interceptors and next-generation radar architectures. The Missile Defense Agency's Next Generation Interceptor program channels multi-billion dollar commitments through indefinite-delivery contracts. Arizona and Massachusetts host concentrated development clusters for gallium nitride radar substrates and precision seeker manufacturing.
Poland
Warsaw's Wisla and Narew procurement programs represent Europe's fastest-expanding interceptor demand channel. Offset requirements mandate co-production agreements that transfer subsystem integration to Polish industrial facilities. The PZL Mielec cluster in southeastern Poland is scaling final assembly capacity for Patriot-derived batteries under Lockheed Martin technology transfer protocols.
Japan
Tokyo's Southwest Island Chain dispersion generates recurring procurement for compact, road-mobile launch systems across Okinawa and the Ryukyu arc. The Ministry of Defense standardizes on gallium nitride active electronically scanned arrays through its next-generation radar roadmap. Kawasaki Heavy Industries and Mitsubishi Electric anchor production in the Kanto and Kansai industrial corridors.
Germany
Berlin's European Sky Shield Initiative commitments drive integrated air defense procurement across layered architectures. The Bundeswehr mandates STANAG 6016 compliance for sensor fusion interoperability with NATO eastern flank members. Bavaria's defense electronics corridor, centered on Munich and Ingolstadt, concentrates radar and battle management software development.
Australia
Canberra's AUKUS-aligned Guided Weapons Enterprise creates partnership slots for precision seeker and propulsion stack suppliers. The Department of Defence prioritizes domestic manufacturing for missile components through sovereign industrial capability priorities. South Australia's Osborne naval shipyard complex and Victoria's defense technology precinct are expanding co-production infrastructure.
Air Defense System Market Vendor Landscape
Capability concentration sits with prime contractors commanding captive radar foundries and cleared software development environments; scale advantage sits with system integrators managing multi-national co-production agreements. The vendor base stratifies across three tiers: sovereign prime contractors with domestic production mandates, multinational platform integrators with ITAR clearance infrastructure, and specialized subsystem houses controlling gallium nitride or precision gyroscope supply. Dominant competitive moves include technology licensing for local final assembly and vertical integration into semiconductor substrate fabrication.
Within the sovereign prime tier, Lockheed Martin Corporation and Raytheon Technologies exemplify capability concentration through captive supply chain control. Israel Aerospace Industries Ltd. anchors integrated battle management software positioning for layered defense networks. RTX Corporation sits within the multinational integrator archetype managing cross-border co-production complexity.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Raytheon Technologies |
| Northrop Grumman Corporation |
| BAE Systems |
| Thales Group |
| Israel Aerospace Industries Ltd. |
| Leonardo S.P.A. |
| RTX Corporation |
| Hanwha Corporation |
| Others |
Supply Flow & Price Mechanics
Rare-earth magnet concentration in Chinese-processed neodymium and dysprosium determines both the premium tier spread for precision-guided interceptors and the elongated supply chain shape for Western prime contractors. This chokepoint forces tiered pricing separation between ITAR-compliant domestic sourcing and foreign-dependent production lines.
Pricing Analysis
Poland commands pricing premiums 15-25% above NATO baseline for Patriot-derived batteries due to co-production offset requirements and local final assembly mandates. Pricing stratifies across ITAR-restricted gallium nitride radar tiers, standard allied-sourced configurations, and economy-grade legacy Soviet-era retrofits. Cost compression in seeker manufacturing is intensifying because gallium nitride substrate bottlenecks concentrate supply leverage among three qualified foundries. Defense contractors show highest price sensitivity due to fixed-margin foreign military sale structures, while national procurement agencies absorb premium tiers for sovereign production mandates.
Supply Chain Analysis
Extended payment terms from prime contractors to gallium nitride substrate suppliers now stretch 180-270 days, reflecting capital intensity in single-crystal wafer fabrication. Supply concentrates in the United States for radar transmit-receive modules, Japan for precision gyroscopes, and China for rare-earth magnet processing. Active electronically scanned array production draws from neodymium-dysprosium magnets, high-purity gallium nitride wafers, and precision-machined aluminum-lithium structures. Single-source vulnerability in Chinese rare-earth export licensing exposes Western contractors to disruption. Distribution runs through defense contractor integrators managing ITAR clearance for foreign military sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat structure where STANAG certification entrenchment and ITAR clearance infrastructure create switching costs that lock out unqualified competitors.
For Market Incumbents: Harden gallium nitride foundry capacity through captive wafer fabrication or long-term offtake agreements with qualified suppliers to neutralize the 18-month lead time bottleneck. Deepen software integration moats by expanding battle management architecture deployments across NATO eastern flank members before offset requirements mature local competitors. For New Entrants and Emerging Players: Pursue electronic warfare subsystem opportunities in Romania and Bulgaria where Black Sea incidents have accelerated counter-drone procurement without established incumbent relationships. Australia's AUKUS-aligned Guided Weapons Enterprise offers the most penetrable entry point for precision seeker suppliers lacking ITAR infrastructure. Position through sovereign industrial capability partnerships rather than direct prime contracting. For Investors and Strategic Acquirers: The market sits at a co-production-mandate expansion phase that favors specialized semiconductor houses with qualified gallium nitride substrate supply. Long-term viability hinges on 5-10 year visibility into NATO eastern flank procurement pipelines and Japan's Southwest Island Chain dispersion programs. Watch gallium nitride wafer pricing volatility as the inflection signal for margin compression or supply security premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Gallium Nitride Foundry Investment | Raytheon Technologies' substrate fabrication secures AESA radar supply against 18-month lead time bottlenecks. |
| Co-Production Agreement Structuring | Lockheed Martin's PZL Mielec partnership satisfies Poland's Wisla offset requirements while transferring final assembly. |
| Battle Management Software Licensing | Israel Aerospace Industries' layered defense architectures capture recurring revenue across Eastern European deployments. |
| Directed Energy Prototype Maturation | Solid-state laser 300kW threshold achievement enables mobile ground platform transition for drone swarm defense. |
| Rare-Earth Magnet Supply Diversification | Domestic neodymium processing investments reduce Chinese export restriction exposure for precision gyroscope production. |
Methodological Framework
Desk research of NATO procurement databases, national defense white papers, and SEC contractor filings preceded structured interviews with missile defense program executives, radar systems engineers, gallium nitride foundry operations managers, and Eastern European offset negotiation specialists. Secondary validation drew from US Missile Defense Agency budget justifications, Japan Ministry of Defense equipment procurement plans, and Poland Armaments Agency contract announcements. Bottom-up segment sizing triangulated against top-down defense expenditure allocation models.
Assumptions held fixed include STANAG 6016 interoperability mandates persisting across the projection horizon and gallium nitride radar standardization remaining locked in US-Japan procurement frameworks. Segmentation modeling spanned product type, end user, technology deployment mode, and threat application vector. CAGRs derived from polynomial trend fitting of historical procurement cycles adjusted for co-production agreement ramp rates. Hypersonic interceptor thermal management breakthrough timelines and directed energy mobile platform transition velocity served as scenario-variant inputs.
Macroeconomic conditions sit as an overlay; deviation in defense budget allocation priorities or rare-earth export licensing severity would shift the trajectory. Forecasts reflect documented assumptions about procurement continuity; technological substitution in radar architectures or regulatory relaxation in ITAR classifications would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Defense
Europe Air Defense Systems Market
Air Defense
Ground-Based Aircraft and Missile Defense Systems Market
Air Defense
Asia-Pacific Airborne Fire Control Radar Market
Air Defense
Global Missile Interceptor Market
Air Defense
Anti-Aircraft Defense Systems Market
Air Defense
Air and Missile Defense Radar System Market
Air Defense
Short Range Air Defense Systems Market
Air Defense
Americas Air Defense Systems Market
Air Defense
Asia-Pacific Air Defense Systems Market
Air Defense
Airborne Fire Control Radar Market
Air Defense
North America Missiles and Missile Defense Systems Market