
 Surface Acoustic Wave Sensors Market | 2026-2036
Surface Acoustic Wave Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Acoustic Wave Sensors Market Analytics
Lithium niobate is recalibrating product economics as manufacturers phase out traditional quartz substrates in high-frequency SAW designs. Murata Manufacturing Co. Ltd. leverages vertically integrated ceramic capabilities to dominate consumer electronics filter supply. TDK Electronics AG anchors European automotive qualification programs through its MEMS-SAW hybrid portfolio. Honeywell International Inc. competes in aerospace-grade pressure sensing with extended temperature-range certifications.
Surface Acoustic Wave Sensors exploit piezoelectric substrate excitation—typically lithium tantalate or lithium niobate wafers cut along specific crystallographic orientations—to generate mechanical waves whose propagation characteristics shift measurably with temperature, pressure, mass loading, or electric field exposure. Industrial Monitoring applications lead volume deployment, particularly in predictive maintenance systems for rotating machinery where wireless SAW transducers eliminate battery dependencies. Chemical Sensors represent the fastest-expanding segment, driven by food safety and environmental VOC detection mandates that demand ppb-level sensitivity without chromatographic separation.
FCC Part 15 rules govern unlicensed SAW-based RFID and wireless sensor operation in the United States, while REACH and RoHS restrict hazardous substances in European-sold piezoelectric components. Japan's METI enacts JIS standards for industrial IoT interoperability that shape SAW sensor communication protocols. Stakeholders must monitor evolving 5G NR band allocations and corresponding filter specification shifts, as these frequency plan decisions cascade directly into substrate material selection and foundry capacity allocation without multi-year adjustment windows.
Market Dynamics
Material substitution pressure from the EU F-Gas Regulation and REACH compliance is forcing foundries to abandon lead-based piezoelectric substrates mid-design-cycle, compressing qualification timelines for lithium niobate alternatives.
Growth Catalysts
- 5G NR Band Allocation:South Korean and Taiwanese foundries are expanding SAW filter capacity for sub-6 GHz and mmWave front-end modules as carriers deploy standalone 5G infrastructure.
- EU F-Gas Regulation:The European mandate for lead-free piezoelectric materials is accelerating substrate transitions toward lithium niobate wafers cut along 128°YX orientations.
- Predictive Maintenance:German and Japanese automotive manufacturers are integrating wireless SAW transducers into tire pressure monitoring and engine management systems to eliminate battery dependencies.
Market Restraints
- Substrate Supply Concentration:High-purity lithium tantalate and lithium niobate wafer production concentrates among Japanese and Chinese crystal growers, creating single-source vulnerabilities for European and North American device fabricators.
- Qualification Timeline Compression:Automotive AEC-Q200 certification cycles for SAW pressure sensors extend 18-24 months, locking designs before final 5G frequency plans stabilize.
- MEMS Substitution:Silicon-based MEMS resonators are capturing sub-GHz timing applications where SAW devices previously dominated, particularly in consumer IoT endpoints.
Strategic Opportunities
- Environmental VOC Detection:Food safety mandates in the European Union and North America are creating demand for ppb-level chemical sensors without chromatographic separation, opening industrial monitoring adjacent markets.
- India Industrial IoT:BIS standards alignment with JIS protocols is enabling Japanese SAW sensor manufacturers to enter process automation installations at Indian petrochemical and steel facilities.
- MEMS-SAW Hybrid Architectures:Convergence of thin-film bulk acoustic resonator processes with surface wave devices is enabling temperature-compensated filters for automotive radar modules.
Industry Challenges
- Crystallographic Process Engineering:Foundries face acute shortages of technicians trained in precision wafer dicing along specific Euler angles for high-frequency SAW designs.
- Cross-Border Certification Stacking:Devices qualifying under FCC Part 15 for US unlicensed operation require separate METI JIS filings for Japanese industrial IoT deployments, duplicating test matrix costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Acoustic Wave Sensors Market |
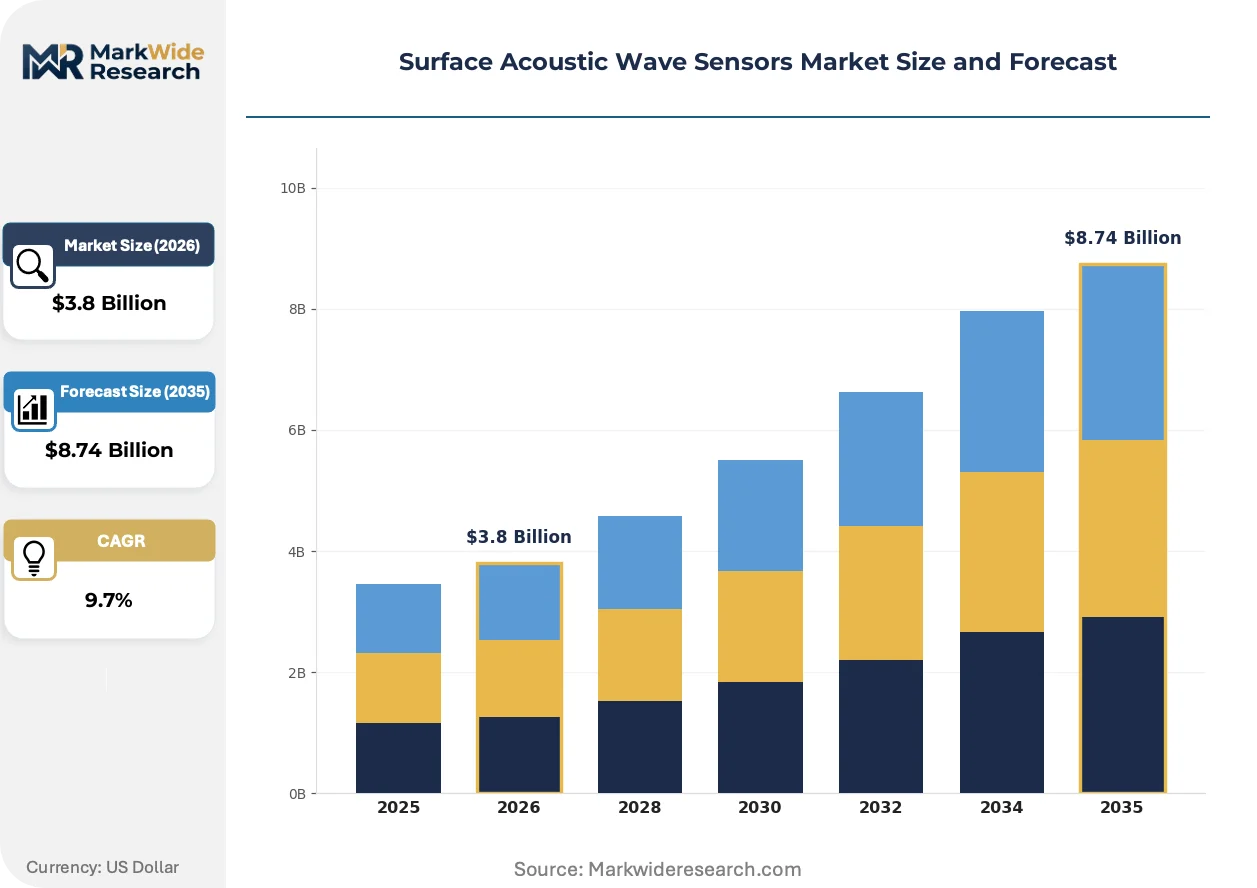
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Temperature Sensors, Humidity Sensors, Chemical Sensors Technology: RFID Technology, Wireless Technology, Microelectronic Technology, Smart Sensor Technology Application: Industrial Monitoring, Healthcare Diagnostics, Environmental Monitoring, Consumer Electronics End User: Aerospace, Automotive, Healthcare, Manufacturing |
| Companies Covered | Honeywell International Inc., Murata Manufacturing Co. Ltd., TDK Electronics AG, AVX Corporation, KYOCERA Corporation, API Technologies Corp, Boston Piezo-Optics Inc., CTS Corporation, Vectron International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Acoustic Wave Sensors Market Evolving Landscape
Substrate material physics and regulatory chemistry mandates are simultaneously reshaping device architectures and supply chain geography in surface acoustic wave sensor production.
Lithium niobate is converging with thin-film deposition techniques to enable temperature-stable high-frequency filters above 3 GHz. South Korean smartphone OEMs are adopting these substrates for 5G mid-band modules ahead of North American carrier deployments. The technology convergence is compressing the performance gap between traditional SAW and bulk acoustic wave devices in sub-6 GHz applications.
REACH substance restrictions are eliminating lead zirconate titanate from European-qualified piezoelectric components. German automotive tier-1 suppliers are re-qualifying entire sensor portfolios under the revised ECHA candidate list ahead of 2027 enforcement milestones. Chemical sensor manufacturers targeting EU environmental monitoring contracts are accelerating transitions to potassium sodium niobate alternatives.
Japanese automotive buyers are consolidating SAW sensor procurement under direct foundry contracts, bypassing traditional distributor channels for tire pressure and powertrain applications. Tier-1 suppliers in Nagoya and Toyota City are establishing vendor-managed inventory programs with lithium niobate wafer suppliers. The purchasing pattern shift is most visible in just-in-time delivery requirements for 5G automotive telematics modules.
Surface Acoustic Wave Sensors Market Segmentation
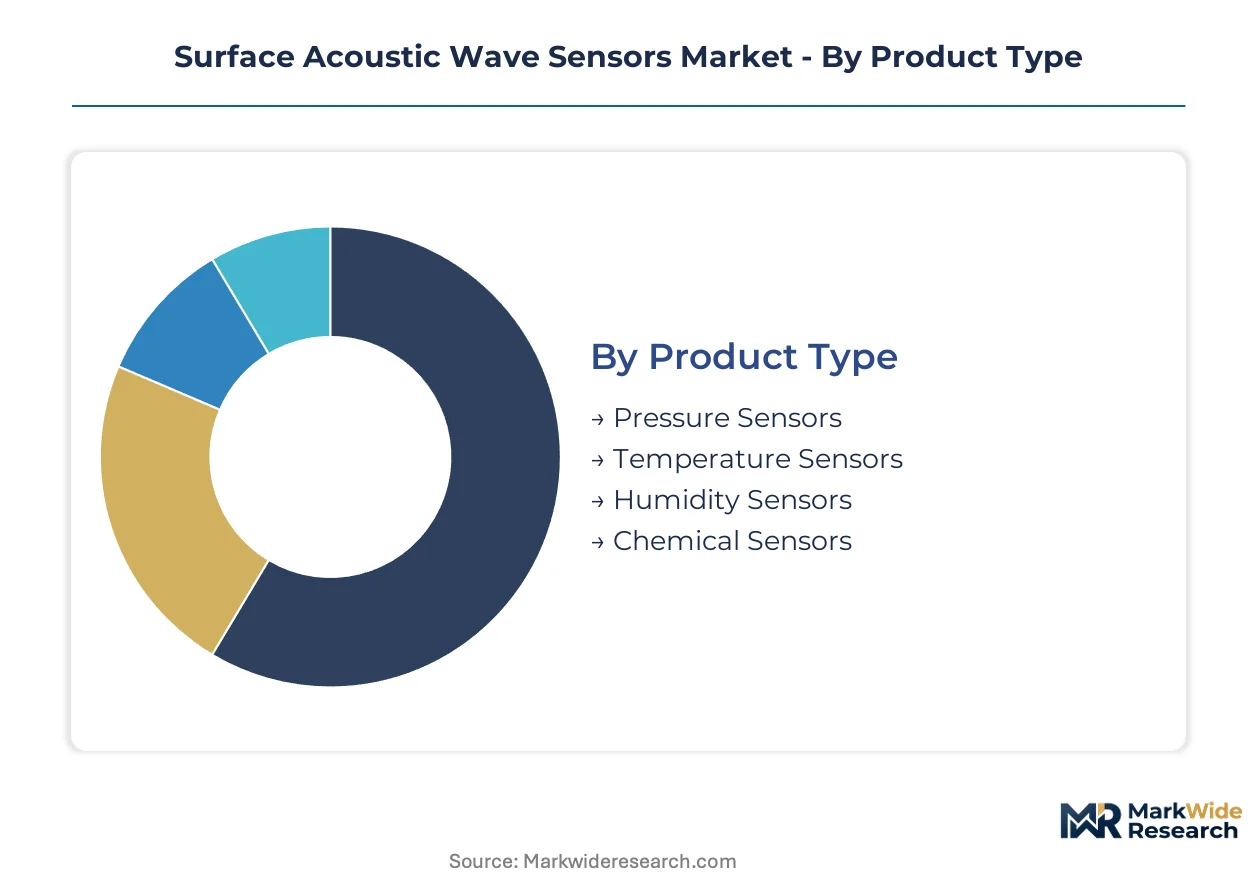
SAW sensor architectures vary dramatically across pressure, temperature, and chemical detection tasks, with substrate crystallography and electrode metallization schemes selected specifically for each target measurand. End-users in automotive and aerospace impose divergent qualification protocols that reshape foundry process flows and testing matrices.
Product Type:
Buyers in this category separate by measurement precision requirements and environmental exposure limits, with automotive TPMS specifications demanding wider temperature spans than laboratory humidity monitoring.
- Pressure Sensors:These devices employ lithium niobate substrates with interdigital transducers patterned for strain-induced frequency shifts. German automotive manufacturers specify these for tire pressure monitoring systems where battery-free wireless operation eliminates maintenance cycles.
- Chemical Sensors:Polymer-coated SAW resonators detect mass loading from VOC adsorption at ppb concentrations. Food safety inspectors in the European Union deploy these for rapid contamination screening without chromatographic separation, bypassing laboratory bottlenecks.
- Temperature Sensors:Temperature-compensated designs use dual-path architectures to cancel substrate thermal drift. Foundries in Taiwan prioritize these for 5G base station thermal management modules.
- Humidity Sensors:Hygroscopic polymer films shift resonance frequency with moisture absorption. Japanese HVAC OEMs integrate these into building automation systems for precision climate control.
Pressure Sensors lead volumes today; Chemical Sensors are gaining share fastest.
Technology:
Integration depth distinguishes procurement decisions, with RFID buyers prioritizing passive interrogation range while smart sensor adopters seek edge-processing capabilities.
- RFID Technology:Passive SAW tags encode data in reflective delay-line structures, enabling wireless reading without onboard power. South Korean logistics operators deploy these for container tracking in port automation systems.
- Smart Sensor Technology:These architectures combine SAW transduction with CMOS signal conditioning and local processing. Aerospace manufacturers in the United States specify these for engine health monitoring where onboard analytics reduce telemetry bandwidth.
- Wireless Technology:Battery-free SAW transducers communicate via RF backscatter across industrial plant floors. German predictive maintenance providers favor these for rotating machinery vibration monitoring.
- Microelectronic Technology:Hybrid MEMS-SAW devices leverage thin-film bulk acoustic resonator fabrication techniques. Taiwanese foundries develop these for temperature-stable automotive radar filters.
RFID Technology dominates current procurement; Smart Sensor Technology shows the steepest expansion trajectory.
Application:
Regulatory compliance intensity varies sharply across this category, with environmental monitoring contracts mandating traceable calibration chains absent in consumer electronics specifications.
- Industrial Monitoring:Wireless SAW transducers eliminate battery replacement in hazardous zone deployments. Japanese steel mills integrate these into predictive maintenance networks for continuous bearing temperature surveillance.
- Environmental Monitoring:ppb-level chemical detection meets EU air quality directive requirements without laboratory infrastructure. Municipal agencies in Germany deploy these for urban VOC hotspot mapping.
- Healthcare Diagnostics:Biosensor-functionalized SAW devices detect protein binding events for point-of-care testing. South Korean diagnostic instrument manufacturers qualify these for infectious disease screening platforms.
- Consumer Electronics:Miniaturized SAW filters enable 5G front-end module integration in smartphones. Taiwanese foundries supply these to South Korean OEMs for mid-band RF signal conditioning.
Industrial Monitoring anchors current volumes; Environmental Monitoring is climbing the fastest.
End User:
Certification burden separates buyers here, with aerospace and automotive demanding extended temperature qualification cycles that healthcare and manufacturing specifications rarely require.
- Automotive:AEC-Q200 qualification mandates 1000-hour high-temperature operating life tests. Tier-1 suppliers in Nagoya establish direct foundry contracts for tire pressure and powertrain sensor procurement.
- Aerospace:Extended temperature-range certifications from Honeywell and competitors address FAA requirements for jet engine pressure sensing. These specifications exclude standard industrial-grade devices.
- Healthcare:FDA and EMA biocompatibility requirements govern sensor packaging for implantable or contact applications. Diagnostic OEMs prioritize disposable SAW biosensor formats.
- Manufacturing:Process automation buyers seek cost-optimized wireless sensor networks for plant-wide deployment. Indian petrochemical facilities adopting BIS-aligned JIS standards enable Japanese supplier entry.
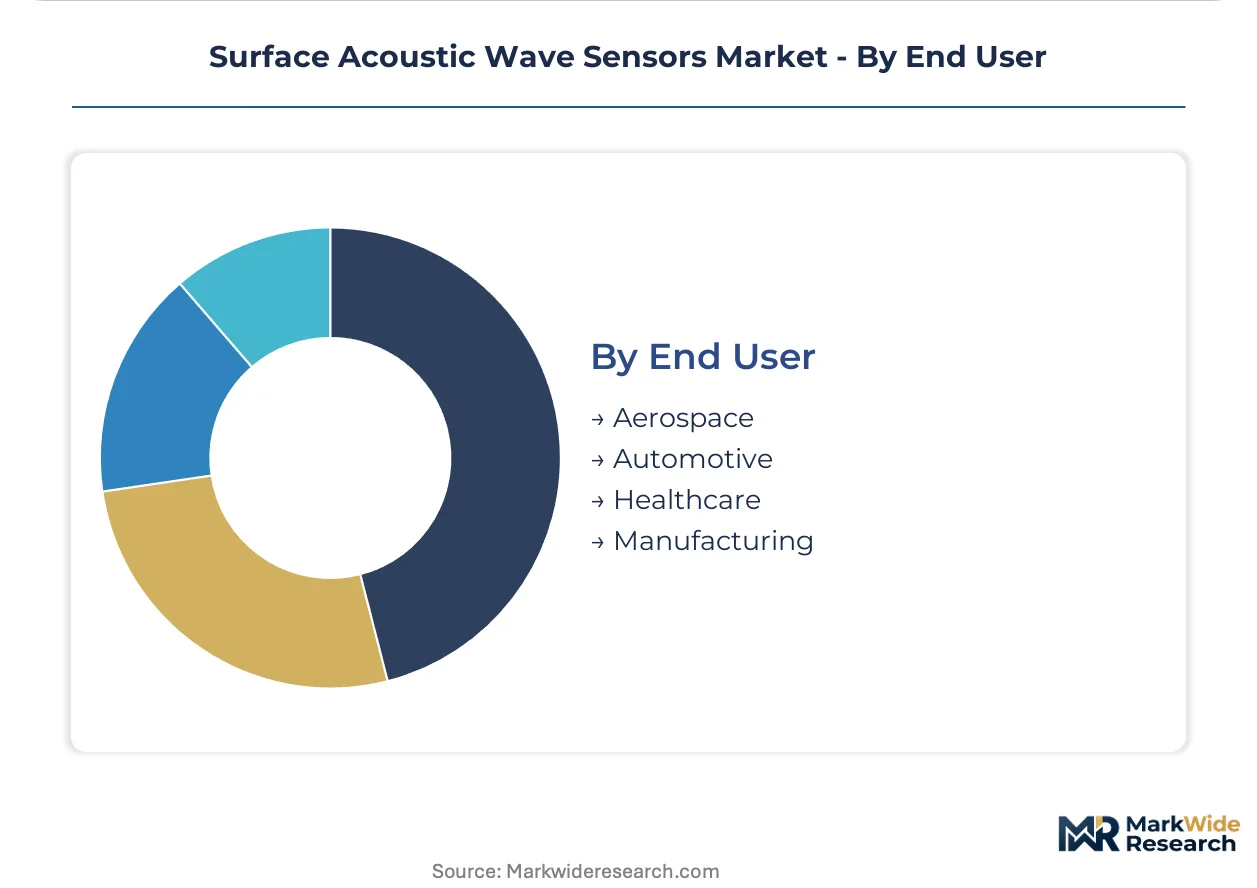
Automotive leads procurement volumes today; Aerospace is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian semiconductor fabrication clusters anchor SAW sensor production capacity, with South Korean and Taiwanese foundries commanding 5G front-end module integration while German and Japanese automotive buyers reshape procurement patterns through direct foundry contracts.
Germany
Automotive tier-1 suppliers in Stuttgart and Munich are consolidating SAW sensor procurement for tire pressure monitoring systems under direct foundry agreements. The EU F-Gas Regulation and REACH compliance deadlines are forcing mid-design-cycle substrate transitions toward lead-free lithium niobate alternatives. The Nagoya-Toyota City corridor hosts vendor-managed inventory programs with German suppliers.
Japan
METI enacts JIS standards for industrial IoT interoperability that shape SAW sensor communication protocols across predictive maintenance networks. Japanese steel mills in Chiba and Kawasaki integrate wireless SAW transducers for continuous bearing temperature surveillance. Crystal growers in Yamanashi prefecture concentrate high-purity lithium tantalate and lithium niobate wafer production.
South Korea
Smartphone OEMs in Seoul and Suwon are adopting lithium niobate substrates for 5G mid-band modules ahead of North American carrier deployments. The country's foundries are expanding SAW filter capacity for sub-6 GHz and mmWave front-end modules as carriers deploy standalone 5G infrastructure. Busan port automation systems deploy passive SAW RFID tags for container tracking.
Taiwan
Foundries in Hsinchu Science Park prioritize temperature-compensated SAW designs for 5G base station thermal management modules. The island's fabricators supply miniaturized SAW filters to South Korean OEMs for mid-band RF signal conditioning. Hybrid MEMS-SAW device development is concentrating in Taichung precision manufacturing zones.
United States
FCC Part 15 rules govern unlicensed SAW-based RFID and wireless sensor operation across logistics and aerospace applications. Honeywell and competitors address FAA requirements for jet engine pressure sensing with extended temperature-range certifications. Aerospace manufacturers specify smart sensor architectures combining SAW transduction with CMOS signal conditioning for engine health monitoring.
Surface Acoustic Wave Sensors Market Competitive Landscape
Direct foundry contracting dominates the current landscape as Japanese automotive buyers bypass traditional distributor channels for tire pressure and powertrain applications. The vendor base organizes around three strategic archetypes: vertically integrated ceramic specialists, MEMS-SAW hybrid developers, and aerospace-grade certification holders. Capacity expansion and substrate material transitions constitute the primary competitive moves, with foundries racing to qualify lithium niobate alternatives before 2027 enforcement milestones.
Among diversified electronics conglomerates, Honeywell International Inc., Murata Manufacturing Co. Ltd., and TDK Electronics AG occupy distinct positioning vectors. Honeywell exemplifies the aerospace-grade certification archetype through extended temperature-range pressure sensing. Murata represents vertically integrated ceramic capabilities that dominate consumer electronics filter supply. TDK anchors European automotive qualification programs through MEMS-SAW hybrid portfolio development.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Murata Manufacturing Co. Ltd. |
| TDK Electronics AG |
| AVX Corporation |
| KYOCERA Corporation |
| API Technologies Corp |
| Boston Piezo-Optics Inc. |
| CTS Corporation |
| Vectron International |
| Others |
Value Network & Pricing Analysis
Japanese automotive tier-1 suppliers concentrate procurement authority through direct foundry contracts for tire pressure monitoring systems, shifting pricing power toward volume-scaled contract structures with embedded lithium niobate substrate cost pass-through clauses.
Pricing Analysis
Input-cost pass-through from lithium niobate wafer suppliers dominates pricing negotiations as REACH compliance deadlines compress substitution timelines. Three-tier pricing structure across aerospace-grade, automotive-qualified, and industrial-standard certification levels separates Honeywell's extended temperature offerings from commodity humidity sensors. Cost compression in automotive-grade pressure sensors is intensifying because MEMS resonators capture sub-GHz timing share. Foundry-direct buyers in Nagoya exhibit lowest price sensitivity; Indian manufacturing adopters of BIS-aligned standards show highest.
Supply Chain Analysis
Dual-sourcing requirements from German automotive buyers mandate qualified secondary suppliers for lithium niobate substrates amid Japanese and Chinese crystal grower concentration. High-purity wafer production draws from Yamanashi prefecture facilities and select Chinese vendors. Single-source vulnerability concentrates in 128°YX-oriented lithium niobate cuts specified for 5G mid-band filters. Distribution runs through vendor-managed inventory programs at Toyota City and direct foundry contracts bypassing traditional semiconductor distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas Regulation enforcement milestones and REACH substance restrictions are accelerating material transitions and requalification investments across automotive and environmental monitoring verticals.
For Market Incumbents: Cement lithium niobate substrate qualification ahead of 2027 REACH enforcement by locking multi-year supply agreements with Yamanashi crystal growers. Deepen backward integration into precision wafer dicing capabilities to offset technician shortages threatening high-frequency design yields. MEMS resonator substitution in consumer IoT timing applications demands defensive patent positioning in hybrid MEMS-SAW architectures. For New Entrants and Emerging Players: Indian process automation buyers at petrochemical and steel facilities represent the most penetrable entry point through BIS-JIS protocol alignment partnerships with established Japanese sensor manufacturers. Environmental VOC detection contracts for EU municipal air quality mapping offer white-space expansion without competing against entrenched automotive qualification incumbents. License thin-film bulk acoustic resonator process IP from Taiwanese research institutes to shortcut temperature-compensated filter development cycles. For Investors and Strategic Acquirers: Aerospace-grade certification holders are the most active acquirer in this space as Honeywell and competitors seek extended temperature-range pressure sensing capabilities for FAA-mandated jet engine applications. Long-term viability hinges on lithium niobate substrate supply security across the next decade. Acquisition target archetypes include Japanese crystal growth specialists with 128°YX orientation process expertise. Watch for inflection in 5G NR band allocation finalization triggering foundry capacity reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Lithium Niobate Substrate Qualification | REACH compliance deadlines force mid-design-cycle transitions eliminating lead-based piezoelectric alternatives. |
| MEMS-SAW Hybrid Architecture Development | Taiwanese foundries leverage thin-film bulk acoustic resonator processes for automotive radar temperature stability. |
| Direct Foundry Contracting | Japanese automotive buyers bypass distributors to secure vendor-managed inventory at Toyota City facilities. |
| Precision Wafer Dicing Capability Expansion | Acute technician shortages in Euler angle cutting threaten high-frequency SAW design yields. |
| JIS-BIS Protocol Alignment | Japanese manufacturers enter Indian petrochemical automation through standards harmonization. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with foundry process engineers, automotive tier-1 procurement directors, crystal growth specialists, and environmental monitoring contract officers combined with secondary validation from ECHA substance restriction filings, METI JIS standard publications, FCC Part 15 rulemakings, and semiconductor trade flow databases. Triangulation across stakeholder inputs and regulatory documentation ensures segmentation integrity.
Input-output matrix framing connects lithium niobate wafer supply volumes to SAW filter production capacity across sub-6 GHz and mmWave front-end module demand trajectories. Segmentation dimensions span product type, technology integration depth, application vertical, and end-user certification tier across the projection horizon. CAGRs derive from substrate material transition velocity and automotive requalification cycle compression. Forecast inputs incorporate 5G NR band allocation timing and REACH enforcement milestone sequencing.
Underlying measurement precision varies by segment; automotive AEC-Q200 qualified devices carry tighter precision than consumer electronics filters due to extended temperature operating life test documentation. Aerospace-grade pressure sensing exhibits highest uncertainty given FAA certification variability. Forecasts reflect documented assumptions about lithium niobate substrate yield maturation and foundry technician pipeline development. Deviation in EU F-Gas Regulation enforcement timing or 5G frequency plan finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Gesture Recognition and Touch-Less Sensing Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
Global Industrial Smart Sensors Market
Sensors and Controls
Magnetoresistance Sensor Market
Sensors and Controls
GPS Tracking Device Market
Sensors and Controls
Off-Highway Machine Position and Angle Sensor Components Market
Sensors and Controls
Global Acoustic Wave Sensor Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
ASEAN Safety Sensors and Switches Market
Sensors and Controls
Motorcycle Sensors Market
Sensors and Controls
MEMS for Mobile Devices Market
Sensors and Controls
United States Scintillator Market
Sensors and Controls
Digital Array Microphone Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
Thermal Scanners Market
Sensors and Controls
Japan Digital Thermometer Market