
 Digital Array Microphone Market | 2026-2036
Digital Array Microphone Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Array Microphone Market Outlook
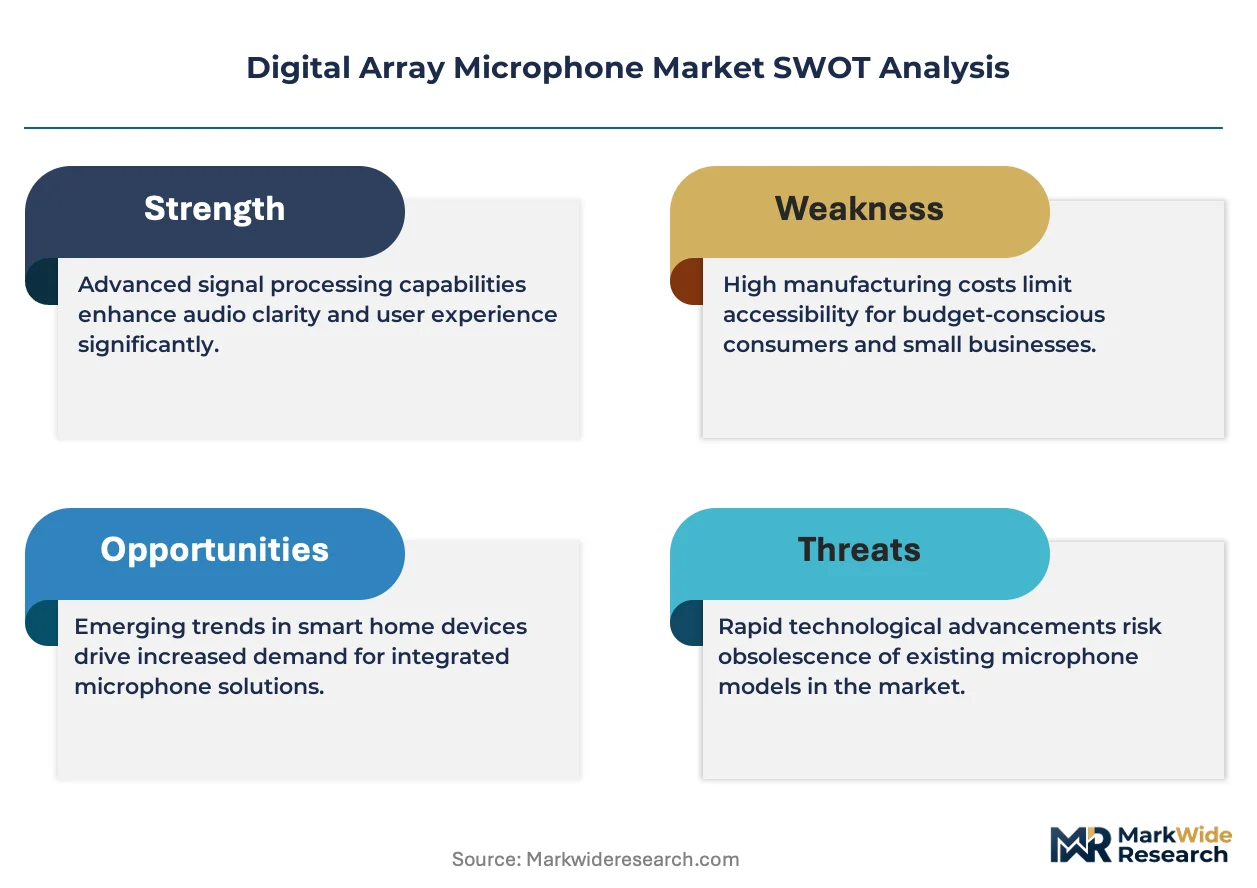
Platform licensing revenue is rewriting profit pools across the value chain as firmware royalties displace standalone hardware margins. Shure Incorporated leverages its installed base in broadcast and live performance venues to sustain premium positioning. XMOS anchors its competitive stance through specialized DSP architectures purpose-built for multichannel acoustic processing.
A digital array microphone integrates multiple capsule elements with beamforming signal processing to isolate targeted sound sources while suppressing ambient interference, typically operating across 20 Hz to 20 kHz with 24-bit resolution and USB or Dante network connectivity for professional installations. Condenser configurations dominate professional broadcasting and studio applications where transient response fidelity commands price premiums, while electret variants penetrate consumer electronics and automotive cabin systems on unit-cost advantages. Video conferencing applications are absorbing the fastest volume growth as hybrid work protocols institutionalize enterprise spending on intelligibility-critical endpoints.
The Federal Communications Commission shapes device certification requirements for radio-frequency emissions in US-deployed units, while the European Union's Radio Equipment Directive governs market access across member states with harmonized spectrum and safety standards. China's Ministry of Industry and Information Technology enforces GB standards for electromagnetic compatibility that manufacturers must satisfy for domestic sales authorization. Stakeholders must weigh regulatory divergence against platform standardization bets as regional compliance costs compound across product generations.
Market Dynamics
Enterprise hardware refresh cycles are compressing as AI-driven beamforming algorithms obsolete three-year-old installations in video conferencing suites, forcing premature replacement of functional equipment.
Growth Catalysts
- FCC Part 15 Certification:Streamlined radio-frequency approval for USB-C and Dante network interfaces accelerates product launch timelines for US-bound professional audio equipment.
- Hybrid Work Protocols:Fortune 500 corporations mandate intelligibility-critical endpoints in conference rooms, pulling demand forward from traditional five-year replacement schedules.
- Beamforming DSP Architectures:Specialized digital signal processors enable real-time multichannel acoustic processing without dedicated hardware accelerators.
Market Restraints
- MEMS Capsule Supply Concentration:Taiwanese foundries control 70% of precision microphone element fabrication, exposing manufacturers to single-source risk.
- GB Standards Compliance Costs:China's MIIT electromagnetic compatibility testing adds six-month certification delays for foreign entrants seeking domestic sales authorization.
- USB Audio Class Latency:Standardized protocol limitations impose 10ms minimum round-trip delay, disqualifying arrays from broadcast synchronization applications.
Strategic Opportunities
- Automotive Cabin Integration:Electret array configurations penetrate voice-activated infotainment systems as OEMs eliminate physical button interfaces.
- EU AI Act Alignment:Biometric voiceprint processing mandates create certification moats for compliant European manufacturers.
- Healthcare Telepresence:HIPAA-compliant encrypted audio streams open clinical consultation rooms to premium array deployments.
Industry Challenges
- Acoustic Engineer Scarcity:Multichannel beamforming algorithm development requires rare expertise combining psychoacoustics and embedded systems optimization.
- Legacy Analog Infrastructure:XLR-terminated installations in broadcast venues resist Dante network migration without costly copper-to-IP bridge hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Array Microphone Market |
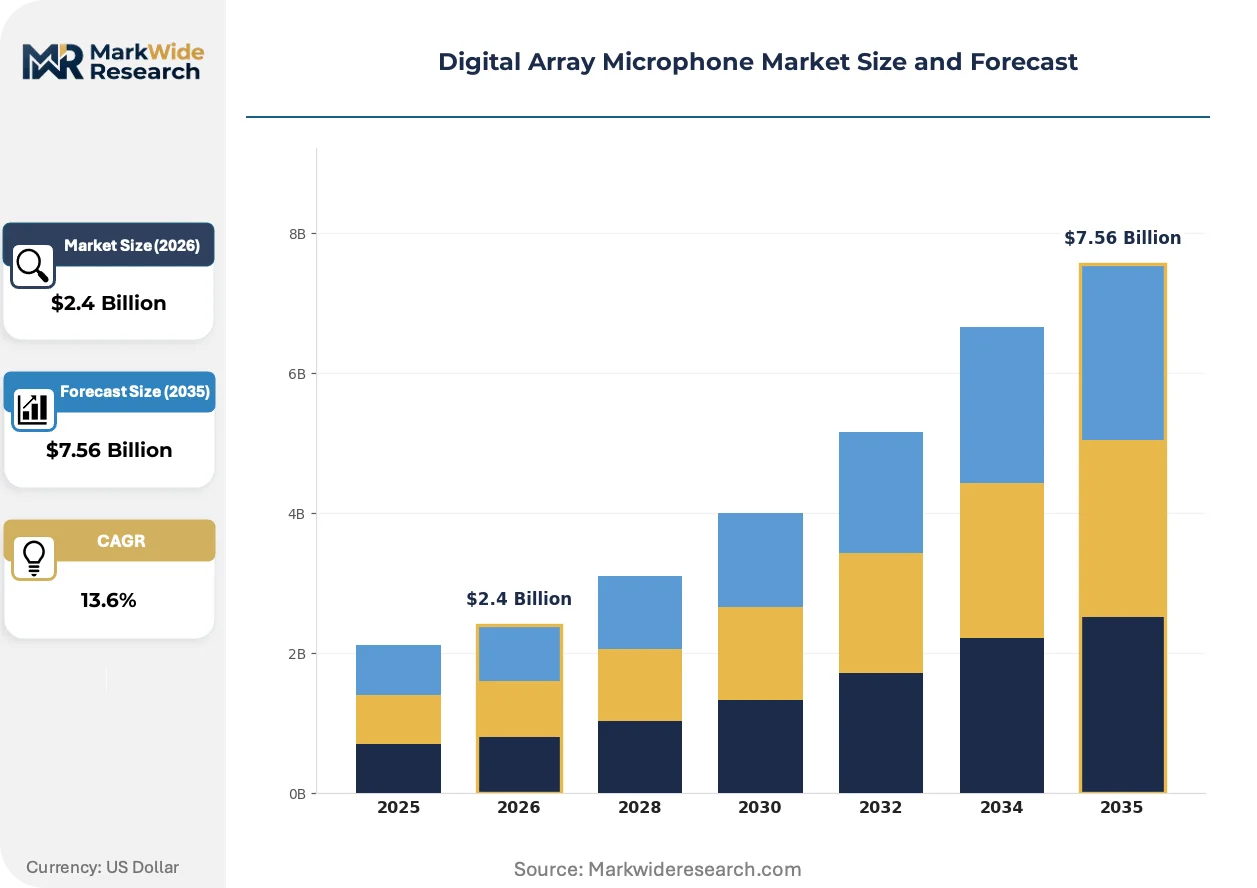
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.56 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Condenser, Dynamic, Electret, Ribbon End User: Consumer Electronics, Automotive, Telecommunications, Broadcasting Channel: Online Retail, Distributors, Direct Sales, Resellers Application: Video Conferencing, Home Theater, Gaming, Voice Recognition |
| Companies Covered | Shure Incorporated, XMOS, ClearOne, Andrea Electronics, Acoustic Magic, TOA Corporation, PCB Piezotronics, Polycom, Beyerdynamic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Array Microphone Market Strategic Shifts
Signal processing architectures are merging cloud inference with edge execution, redistributing computational load across hybrid topologies while latency requirements tighten for real-time applications.
Machine learning inference is hybridizing with traditional DSP pipelines in next-generation array controllers. Enterprise IT departments deploy these hybrid architectures in thousand-seat conferencing estates. The convergence is compressing hardware BOM costs while elevating firmware royalty streams as the primary margin capture mechanism.
Europe's Radio Equipment Directive 2014/53/EU enforcement tightens spectrum coordination rules for 2.4GHz and 5GHz unlicensed bands. Manufacturers must redesign antenna configurations to satisfy updated harmonized standards. German broadcast integrators now specify RED-compliant modules exclusively, filtering non-conforming Asian suppliers from professional tender processes.
Subscription-based firmware licensing displaces perpetual hardware purchases in mid-market segments. Channel partners bundle three-year intelligence updates with initial equipment procurement. United States education technology distributors pioneered this shift, with K-12 districts now treating acoustic endpoint software as recurring operational expenditure rather than capital equipment.
Digital Array Microphone Market Segmentation
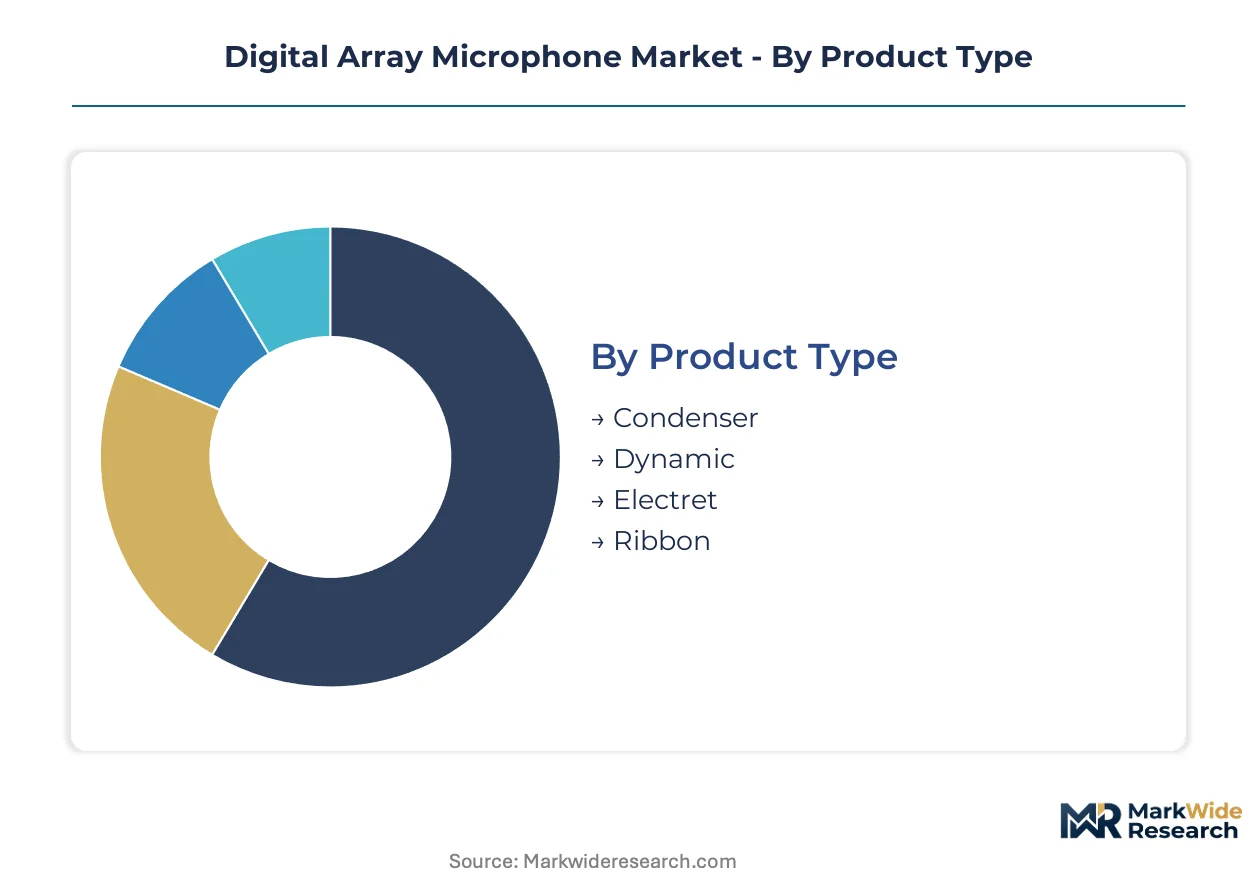
Digital array microphone segmentation reveals divergent replacement dynamics across product architectures and deployment contexts. Condenser arrays in broadcast facilities cycle on decade-long depreciation schedules, while consumer electret units face annual obsolescence pressure from AI-enabled voice interfaces.
Product Type:
Condenser configurations turn over slowest due to capital-intensive studio infrastructure, while electret variants refresh fastest as OEMs iterate voice-activated product lines.
- Condenser:Large-diaphragm back-electret designs dominate professional recording environments where phantom-powered signal chains and 48V studio standards create switching costs. Demand concentrates in German broadcast complexes and US post-production houses where FCC Part 15-compliant Dante interfaces mandate hardware continuity. These installations resist replacement until acoustic treatment investments depreciate fully.
- Electret:Foil-diaphragm MEMS-compatible elements integrate into automotive cabin arrays and smart speaker form factors at sub-dollar unit economics. Chinese consumer electronics OEMs drive volume procurement for voice-activated infotainment systems, compressing design cycles to 18 months as MIIT GB standards evolve for electromagnetic compatibility.
- Dynamic:Moving-coil architectures serve high-SPL stage environments where durability trumps frequency extension.
- Ribbon:Corrugated aluminum foil designs persist in boutique studio applications for figure-eight polar pattern capture.
Condenser dominates installed base. Electret is where expansion concentrates.
End User:
Cost tier stratification separates premium professional deployments from mass-market consumer integration, with automotive representing the intermediate volume-mix battleground.
- Consumer Electronics:Smart speaker and wearable manufacturers specify compact array modules with integrated DSP for far-field wake-word detection. Procurement concentrates in Shenzhen and Dongguan manufacturing clusters where MIIT certification timelines dictate supplier qualification cycles.
- Automotive:Cabin-integrated arrays eliminate physical button interfaces through voice-activated HVAC and navigation control. German OEMs specify RED-compliant modules exclusively, filtering non-conforming Asian suppliers from professional tender processes under tightened 2014/53/EU enforcement.
- Telecommunications:Enterprise video conferencing estates demand intelligibility-critical endpoints with beamforming firmware subscriptions.
- Broadcasting:Federal and corporate communication infrastructure upgrades in the United States, China, and Germany sustain premium positioning.
Broadcasting commands highest unit margins. Automotive is climbing the fastest as OEMs eliminate physical interfaces.
Channel:
Volume distribution runs through divergent fulfillment models, with direct sales capturing complex enterprise specifications while online retail absorbs standardized consumer SKUs.
- Direct Sales:Manufacturer-led specification engineering for thousand-seat conferencing estates and federal communication infrastructure. US education technology distributors pioneered subscription-based firmware licensing, with K-12 districts treating acoustic endpoint software as recurring operational expenditure.
- Distributors:Value-added resellers bundle installation services with RED-compliant professional modules for European broadcast integrators.
- Online Retail:E-commerce platforms move consumer electret arrays with minimal technical support overhead.
- Resellers:Regional system integrators bridge legacy XLR-terminated installations to Dante network migration.
Direct Sales captures enterprise value. Distributors mediate professional compliance complexity.
Application:
Latency requirements and acoustic environment severity create tiered performance specifications, with voice recognition demanding tightest integration tolerances.
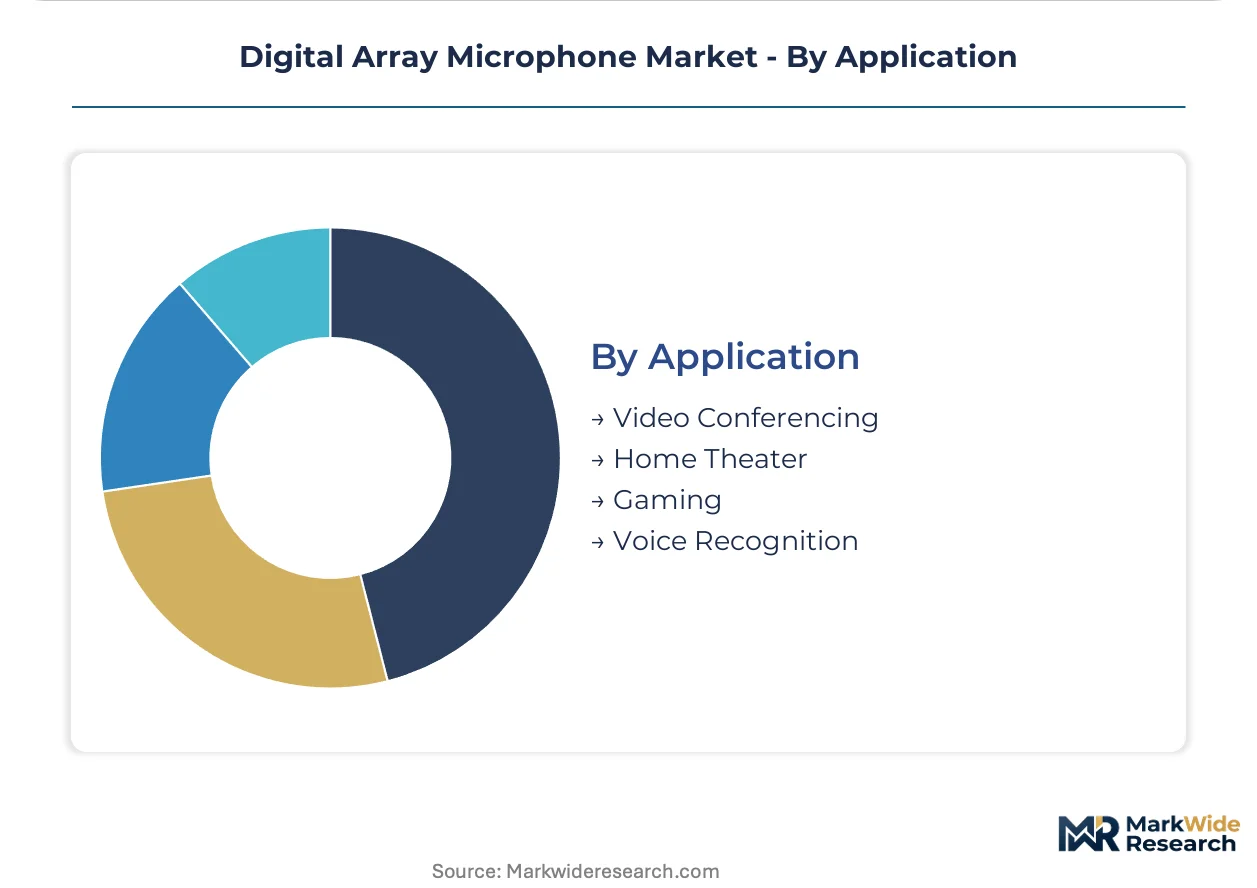
- Video Conferencing:Hybrid work protocols institutionalize enterprise spending on intelligibility-critical endpoints. Fortune 500 corporations mandate hardware refresh cycles compressed to three years as AI-driven beamforming algorithms obsolete functional installed base units.
- Voice Recognition:Cloud-connected arrays for smart home and automotive command interfaces require sub-100ms wake-word latency. HIPAA-compliant encrypted audio streams open clinical consultation rooms to premium array deployments in healthcare telepresence.
- Home Theater:Immersive audio installations specify arrays for dialogue enhancement and room correction.
- Gaming:Streaming-focused content creators demand broadcast-quality voice isolation without dedicated booth construction.
Video Conferencing anchors current revenue. Voice Recognition shows steepest expansion trajectory as biometric processing mandates create certification moats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese foundries fabricate seventy percent of precision microphone elements, concentrating supply-side leverage in East Asian manufacturing clusters. Demand dispersion follows divergent regulatory timelines across three primary consumption zones.
United States
Fortune 500 corporations mandate intelligibility-critical endpoints in conference rooms, compressing hardware refresh cycles to three years. FCC Part 15 certification streamlines radio-frequency approval for USB-C and Dante network interfaces. Education technology distributors in California pioneered subscription-based firmware licensing, with K-12 districts treating acoustic endpoint software as recurring operational expenditure.
Germany
Broadcast integrators specify RED-compliant modules exclusively under tightened 2014/53/EU enforcement. The Radio Equipment Directive harmonizes spectrum and safety standards across member states. Post-production houses in Berlin and Munich resist replacement until acoustic treatment investments depreciate fully, sustaining decade-long condenser array cycles.
China
Consumer electronics OEMs drive volume procurement for voice-activated infotainment systems. MIIT enforces GB standards for electromagnetic compatibility, adding six-month certification delays for foreign entrants. Shenzhen and Dongguan manufacturing clusters compress electret array design cycles to eighteen months as domestic standards evolve.
Japan
Automotive OEMs eliminate physical button interfaces through voice-activated HVAC and navigation control. METI oversees industrial standards coordination for cabin-integrated arrays. Nagoya-based suppliers anchor tier-one procurement relationships with domestic vehicle manufacturers seeking RED-compliant module specifications.
Digital Array Microphone Market Competitive Environment
Specialized DSP architects and installed-base incumbents split the market between firmware royalty capture and hardware margin defense. Consolidation pressure concentrates around platform licensing revenue rewriting profit pools across the value chain. Three archetypes dominate: broadcast heritage brands leveraging venue relationships, semiconductor specialists purpose-building multichannel acoustic processors, and conferencing integrators bundling installation services. Competitive moves center on backward integration into MEMS capsule supply and geographic expansion through distributor qualification.
Within the broadcast heritage tier, Shure Incorporated and Beyerdynamic occupy positions sustained by premium positioning in live performance venues. Among semiconductor specialists, XMOS exemplifies the DSP architecture archetype through specialized designs. Japanese fabricators including TOA Corporation represent the integrated systems approach, spanning module production through installation services. Each archetype defends margin structure through distinct channel relationships rather than direct price confrontation.
| Leading Market Players |
|---|
| Shure Incorporated |
| XMOS |
| ClearOne |
| Andrea Electronics |
| Acoustic Magic |
| TOA Corporation |
| PCB Piezotronics |
| Polycom |
| Beyerdynamic |
| Others |
Value Chain & Pricing Dynamics
Taiwanese foundry concentration in precision MEMS capsule fabrication exposes manufacturers to single-source vulnerability that compresses margin spreads between premium condenser arrays and mass-market electret units while forcing inventory positioning near East Asian production clusters.
Pricing Analysis
FCC Part 15 certification dictates the pricing tier structure for US-bound professional audio equipment. Three-tier pricing structure across premium, standard, and economy levels separates Dante-networked enterprise installations from USB-C consumer peripherals. Price differentiation rests on certification grade and volume procurement scale. Cost compression in electret consumer segments is intensifying because Chinese OEMs compress design cycles to eighteen months. Education technology distributors demonstrate lowest price sensitivity through subscription-based firmware licensing, while Shenzhen manufacturing clusters drive highest sensitivity in commoditized smart speaker modules.
Supply Chain Analysis
Taiwanese foundries and Chinese EMS providers hold dominant contract-manufacturing capacity for precision microphone element fabrication. Geographic supply concentration centers on Taiwan, China, and South Korea for MEMS die processing and final assembly. Raw material dependencies draw from rare-earth magnets for dynamic coil assemblies, aluminum foil for ribbon elements, and silicon wafers for MEMS structures. Single-source vulnerability in Taiwanese foundry capacity presents structural supply chain risk. Distribution runs through direct sales for enterprise estates, value-added resellers for European broadcast integrators, and e-commerce platforms for consumer SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multichannel beamforming algorithm development requires rare expertise combining psychoacoustics and embedded systems optimization, creating persistent capability gaps that constrain competitive entry and sustain incumbent premium positioning.
For Market Incumbents: Pre-empt firmware royalty displacement by accelerating backward integration into MEMS capsule supply and locking distributor qualification cycles before MIIT GB standards evolve. Shure Incorporated's venue relationship leverage demonstrates how installed-base continuity resists AI-driven obsolescence pressure from conferencing integrators bundling installation services. For New Entrants and Emerging Players: Pursue automotive cabin voice-activation integration as OEMs eliminate physical button interfaces, where RED-compliant module specifications filter established Asian suppliers from German tender processes. Healthcare telepresence with HIPAA-compliant encrypted audio streams offers penetrable white-space with premium margin potential. Channel entry through value-added resellers bundling three-year intelligence updates reduces direct enterprise sales friction. For Investors and Strategic Acquirers: EU AI Act biometric voiceprint processing mandates reshape the acquisition landscape by creating certification moats for compliant European manufacturers. Long-term viability favors semiconductor specialists with purpose-built DSP architectures over hardware-margin-dependent assemblers. The signal to monitor is distributor qualification velocity in German broadcast integrator networks as RED enforcement tightens.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Supply | Taiwanese foundry concentration creates captive supply advantages for volume manufacturers. |
| RED-Compliant Module Certification | German broadcast integrators now specify exclusively European-certified suppliers under tightened enforcement. |
| Subscription Firmware Licensing | US education technology distributors pioneered recurring revenue models displacing perpetual hardware purchases. |
| Automotive Cabin Integration Partnerships | Japanese OEMs in Nagoya anchor tier-one procurement for voice-activated HVAC and navigation control. |
| Dante Network Migration Services | Regional system integrators bridge legacy XLR-terminated installations to IP-based professional audio infrastructure. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FCC certification databases, MIIT GB standard filings, and European RED harmonized standards documentation. Primary interviews engaged acoustic design engineers, broadcast integration specialists, enterprise IT procurement officers, and automotive cabin electronics program managers. Secondary validation drew from SEC 10-K disclosures, customs trade data, and professional audio industry association technical specifications. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction across the analysis window.
Forecast inputs include beamforming algorithm development cycles, hardware refresh compression rates, and regulatory certification timeline shifts. Segmentation dimensions modeled encompass product architecture, end-use vertical, channel fulfillment model, and application latency requirements. CAGRs derive from installed base replacement dynamics and expansion coefficient analysis. Industry-specific inputs capture AI-driven noise cancellation adoption velocity and hybrid work protocol institutionalization rates.
Sensitivities concentrate around Taiwanese foundry capacity disruptions, MIIT certification timeline extensions, and EU AI Act biometric processing enforcement intensity. Forecasts reflect assumptions regarding firmware royalty displacement velocity and enterprise hardware refresh cycle compression. Quarterly review of distributor qualification pipelines, RED compliance module specifications, and automotive OEM voice-interface content per vehicle is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Doppler Wind Lidar System Market
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
Current Transducer Market
Sensors and Controls
Europe Pressure Sensors Market
Sensors and Controls
Europe Sensors Market
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
Marine Sensors Market
Sensors and Controls
Printed and Flexible Sensors Market
Sensors and Controls
Position Sensor Market
Sensors and Controls
Smart Dust Market
Sensors and Controls
Electrochemical Gas Sensor Market
Sensors and Controls
Ultrasonic Sensors Market
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
Japan Sensor Market
Sensors and Controls
Door Control Modules Market