
 Motorcycle Sensors Market | 2026-2036
Motorcycle Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Sensors Market Analysis
Adoption across the end-use mix is shifting as OEMs displace aftermarket fitment with factory-integrated sensor suites. Robert Bosch GmbH leverages its MEMS fabrication scale to dominate pressure and inertial sensing for anti-lock braking and traction control modules. Continental AG anchors European supply through captive relationships with premium motorcycle brands, while NXP Semiconductors NV competes on automotive-grade microcontroller integration that reduces ECU footprint.
Motorcycle sensors are electromechanical transducers that convert physical variables—acceleration, angular velocity, fluid pressure, thermal state—into digital signals readable by engine control or chassis management units, typically operating across temperature ranges from minus forty to one hundred twenty-five degrees Celsius and vibration spectra exceeding fifteen Grms. Their primary purpose is to enable real-time closed-loop control of powertrain efficiency, vehicle dynamics, and occupant protection systems. Pressure sensors lead product-type revenue due to ubiquitous deployment in fuel injection, tire monitoring, and oil condition tracking, while GPS-enabled technology segments capture the fastest growth as connected mobility platforms embed geolocation into insurance and fleet management offerings. Safety systems applications command the deepest margin pools because regulatory compliance mandates minimum sensor counts for anti-lock braking and combined braking systems in major production jurisdictions.
The EPA enforces evaporative emission standards that require fuel vapor pressure monitoring, while NHTSA mandates anti-lock braking performance thresholds that depend on wheel-speed and inertial sensors for compliance demonstration. Euro 5 standards administered by European national type-approval authorities extend exhaust gas temperature and oxygen sensing obligations to motorcycles above one hundred twenty-five cubic centimeters displacement. Stakeholders must monitor divergence between regional diagnostic protocols, as OBD-II harmonization in North America contrasts with developing proprietary standards in emerging production hubs, creating certification cost fragmentation that favors suppliers with multi-homologation engineering capacity.
Market Dynamics
Factory integration of electronic control units is compressing aftermarket fitment windows as OEMs specify sensor suites at the design stage rather than post-production retrofit.
Growth Catalysts
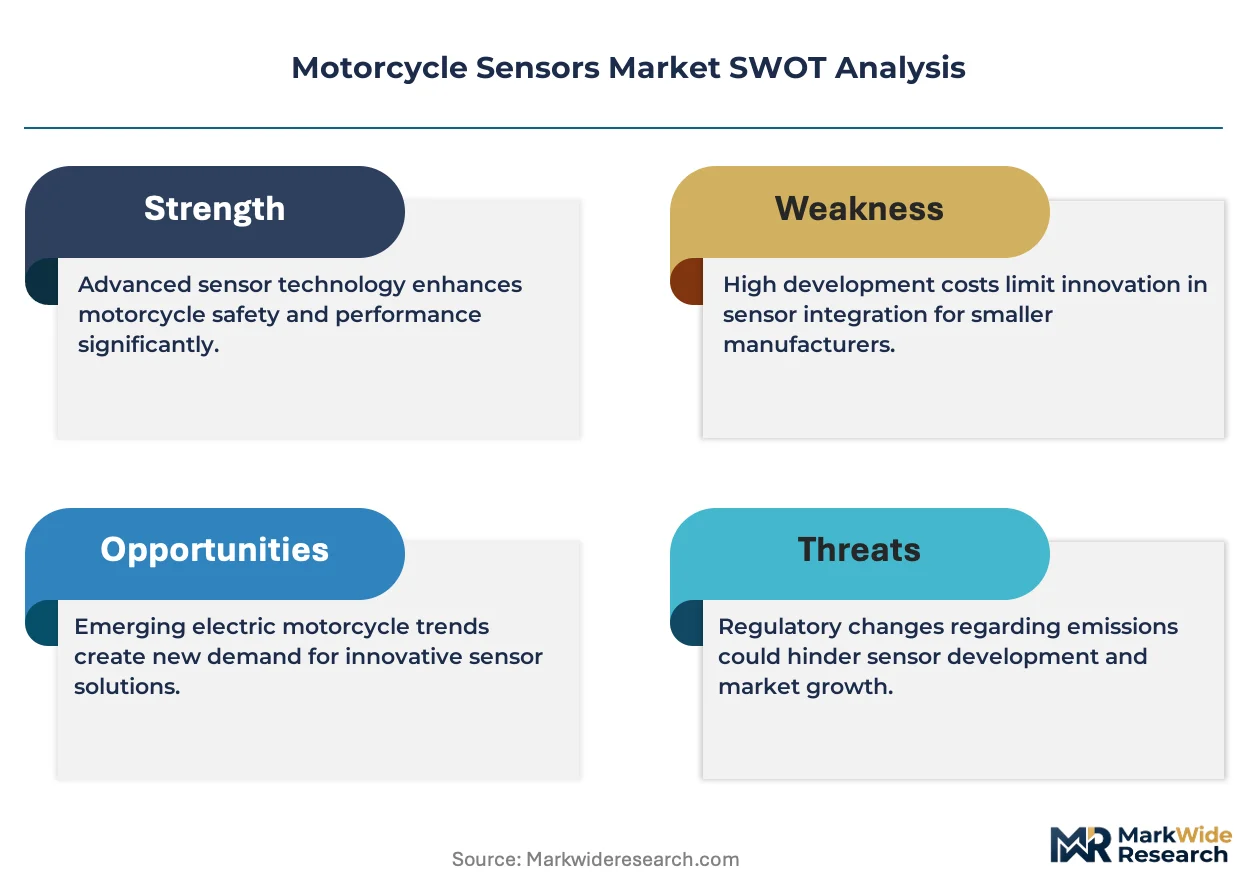
- Euro 5 emission standards:European national type-approval authorities mandate exhaust gas temperature and oxygen sensing for motorcycles above 125cc displacement, expanding sensor counts per vehicle.
- India's domestic production volumes:Government safety mandates and rising commuter segment output are enlarging the addressable sensor base across mid-range and performance categories.
- MEMS fabrication scale:Advances in micro-electromechanical systems production are lowering unit costs for pressure and inertial sensing modules deployed in anti-lock braking systems.
Market Restraints
- Raw material volatility:Rare earth element price swings for magnet-based position sensors create margin compression for tier-two suppliers without long-term purchase agreements.
- Supply concentration in East Asian packaging:Backend semiconductor assembly clusters in Taiwan and South Korea expose sensor module vendors to single-point disruption risks.
- Proprietary diagnostic protocols:Divergence between OBD-II harmonization in North America and developing regional standards in emerging production hubs fragments certification engineering capacity.
Strategic Opportunities
- Connected mobility platforms:GPS-enabled telematics integration into insurance underwriting and fleet management systems is opening recurring-revenue sensor service models.
- Evaporative leak detection:EPA fuel vapor pressure monitoring requirements for motorcycles create dedicated sensor demand in the North American aftermarket.
- Sensor fusion architectures:Convergence of inertial measurement units with machine learning inference at the edge enables predictive chassis control without centralized ECU dependency.
Industry Challenges
- Embedded software certification:ISO 26262 functional safety validation for automotive-grade sensor firmware extends development timelines by 8-14 months for new product introductions.
- Multi-homologation engineering:Simultaneous compliance with NHTSA, KBA, and BIS testing protocols strains validation lab capacity and delays regional market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Sensors Market |
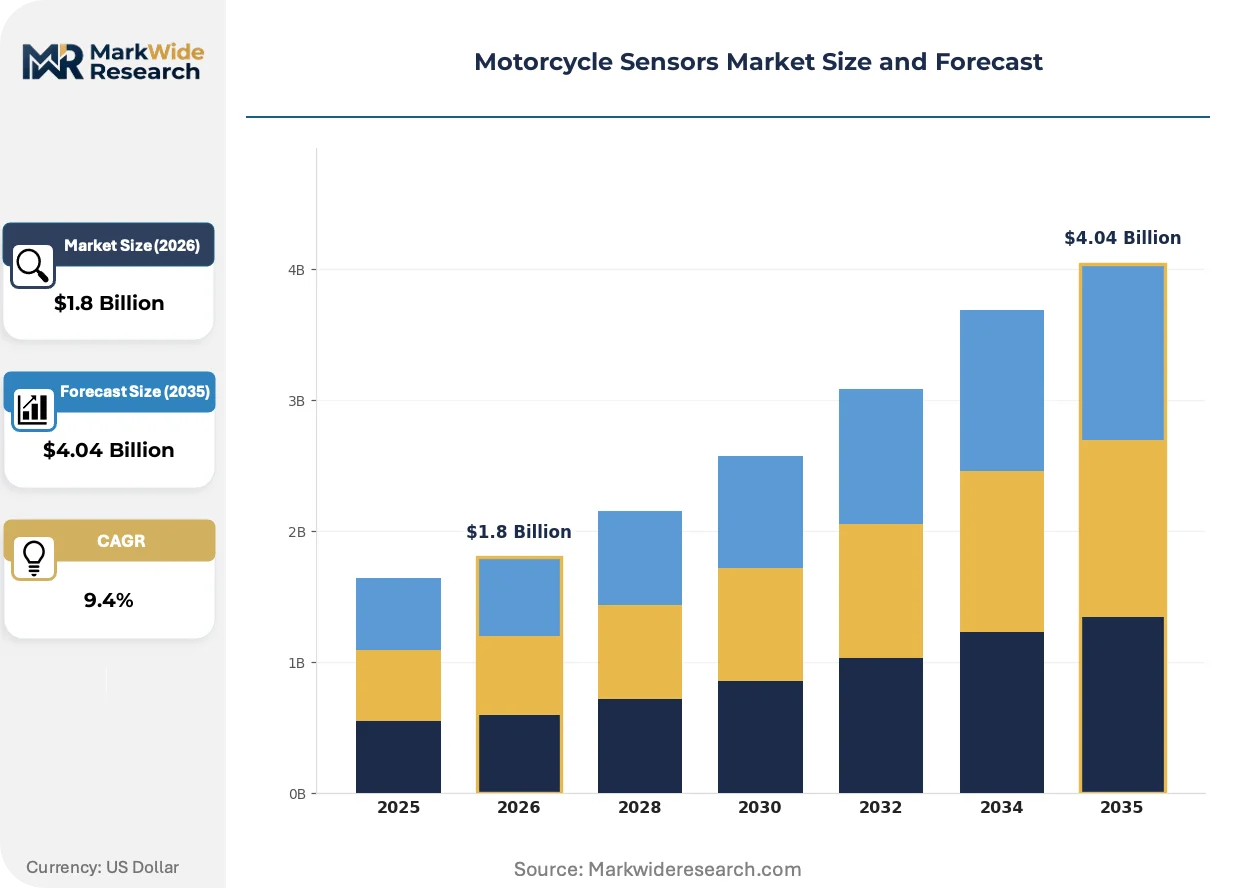
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometer, Gyroscope, Pressure Sensor, Temperature Sensor Technology: Bluetooth, RFID, GPS, Ultrasonic End User: OEMs, Aftermarket Providers, Custom Builders, Enthusiasts Application: Safety Systems, Performance Monitoring, Navigation, Theft Prevention |
| Companies Covered | Robert Bosch GmbH, Continental AG, Honda Motor Co. Ltd., Infineon Technologies AG, NXP Semiconductors NV, Denso Corporation, Mitsubishi Electric Corp., ZF Friedrichshafen AG, Hitachi Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Sensors Market Emerging Trajectories
Edge computing architectures are redistributing signal processing from centralized engine control units toward distributed sensor nodes, altering power budgets and data topology throughout motorcycle electronics.
Silicon carbide MEMS pressure transducers are replacing ceramic piezoresistive elements in fuel injection and oil condition monitoring applications. Tier-one suppliers are qualifying these devices for 150°C continuous operation. This material transition is decentralizing thermal management requirements away from module housings toward the sensing element itself.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in climate-controlled storage for humidity-sensitive sensor inventory. Logistics providers serving Bosch and Continental are retrofitting warehouse HVAC systems with CO2-based alternatives. European premium motorcycle OEMs are absorbing higher component costs as suppliers pass through compliance capital expenditure.
Fleet operators and ride-hailing platforms are unbundling sensor maintenance from traditional dealership service contracts. Direct procurement of wheel-speed and tire pressure monitoring units through B2B distributors is bypassing OEM captive parts networks. This channel disintermediation is most pronounced in Southeast Asian urban mobility deployments where vehicle utilization rates exceed 18 hours daily.
Motorcycle Sensors Market Segmentation
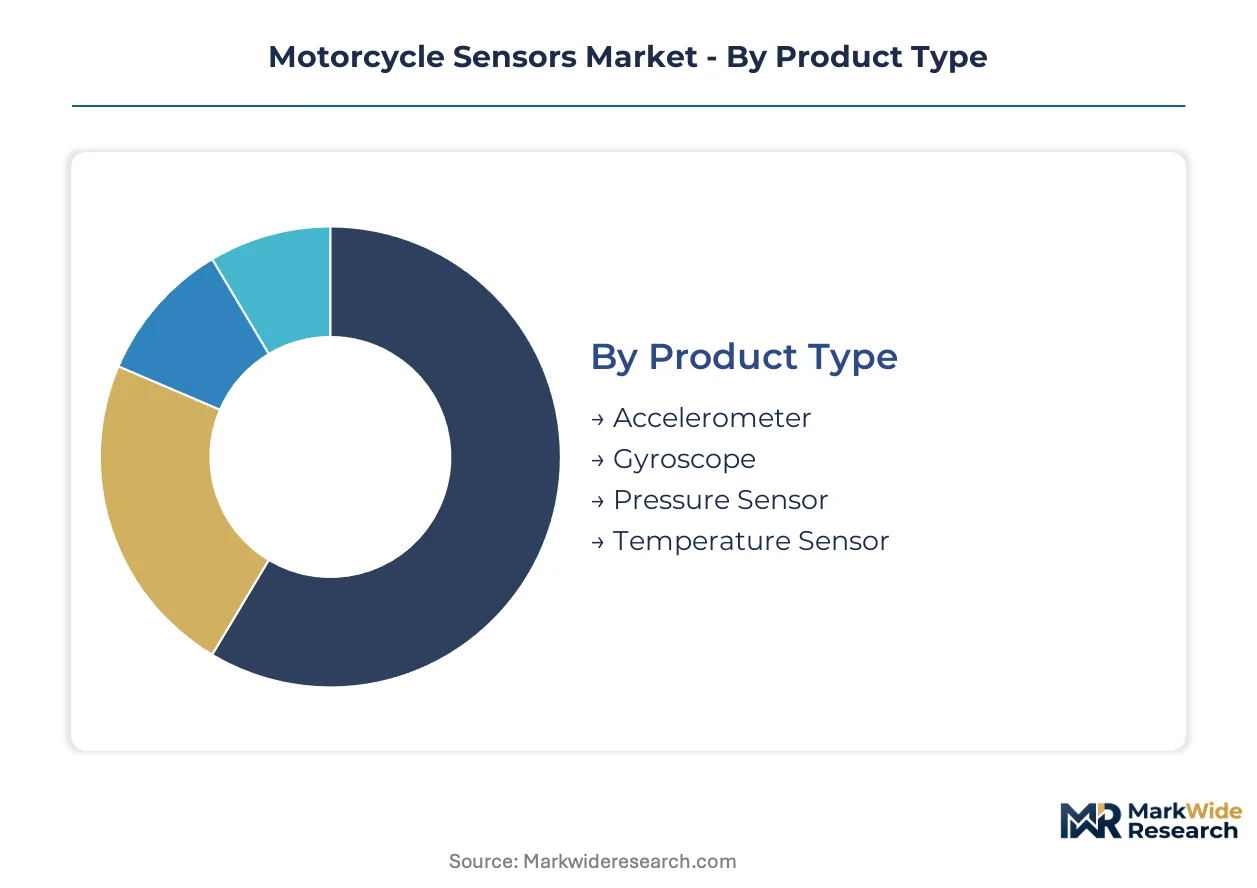
Segmentation in motorcycle sensors reveals how technical specifications, connectivity protocols, and customer procurement patterns create distinct competitive arenas. Understanding these divisions exposes where suppliers can defend margin pools versus where volume commoditization pressures dominate.
Product Type:
Volume concentration favors pressure sensing modules, while premium positioning accrues to multi-axis inertial devices.
- Pressure Sensor:Piezoresistive and capacitive transducers measure fuel injection rail pressure, tire inflation states, and lubricant condition. OEMs in India and Thailand specify these ubiquitously across commuter motorcycles to meet fuel efficiency mandates from the Bureau of Energy Efficiency and Ministry of Industry.
- Accelerometer:MEMS-based devices detect linear acceleration for anti-lock braking modulation and traction control intervention. Demand concentrates in European premium motorcycles where KBA type-approval requires documented wheel-slip mitigation for models above 125cc displacement.
- Gyroscope:Angular rate sensors enable lean-angle detection for cornering ABS and stability control. Deployment is expanding in Japanese and Italian performance motorcycles with inertial measurement unit integration.
- Temperature Sensor:Thermistors and RTDs monitor exhaust gas, coolant, and ambient thermal states. These devices face the steepest cost-down pressure from Chinese OEMs targeting domestic price-sensitive segments.
Mature deployment sits with pressure sensors. Newer deployment is concentrated in gyroscope modules for chassis dynamics applications.
Technology:
Connectivity protocols segment the market by infrastructure dependency and data throughput requirements.
- GPS:Satellite positioning modules enable real-time location tracking, geofencing, and stolen vehicle recovery. Fleet operators in Indonesia and Vietnam are embedding these into ride-hailing motorcycles where insurance underwriters demand telemetry verification of operating zones.
- Bluetooth:Short-range wireless pairs helmet displays, smartphone applications, and diagnostic tools with onboard sensor networks. Aftermarket fitment in North America leverages this protocol for tire pressure monitoring retrofit kits that bypass proprietary OEM data buses.
- RFID:Passive and active radio-frequency identification supports keyless ignition, component authentication, and supply chain tracking. European premium manufacturers use encrypted RFID for anti-theft immobilizer systems meeting Thatcham security ratings.
- Ultrasonic:Acoustic ranging sensors enable parking assistance and blind-spot detection. Adoption remains nascent, concentrated in experimental electric motorcycle platforms from California and Shanghai startups testing low-speed maneuvering aids.
Bluetooth dominates aftermarket retrofit economics. GPS is climbing the fastest as telematics service providers bundle hardware with recurring data subscriptions.
End User:
Procurement authority determines specification stringency and price elasticity across the demand base.
- OEMs:Original equipment manufacturers specify sensor suites at the motorcycle design stage, integrating devices into engine control and chassis management architectures. Factory integration locks in multi-year supply agreements with tier-one vendors like Bosch and Continental.
- Aftermarket Providers:Independent distributors and repair networks source replacement sensors for warranty expiration and crash repair. This channel fragments across regional parts importers in Brazil, Mexico, and Eastern Europe with limited technical support capabilities.
- Custom Builders:Small-volume manufacturers and modification shops procure specialized sensors for café racer, scrambler, and electric conversion projects. Quantities remain insignificant but specification flexibility attracts niche MEMS suppliers.
- Enthusiasts:Individual riders purchase diagnostic tools, tire pressure monitors, and data loggers through e-commerce platforms. Amazon and AliExpress distribution dominates this segment with minimal brand loyalty.
Specification authority concentrates with OEMs. Volume growth is shifting toward aftermarket providers as fleet operators disintermediate traditional dealer service networks.
Application:
Functional purpose determines sensor performance grading and regulatory compliance burden.
- Safety Systems:Wheel-speed, inertial, and pressure sensors enable anti-lock braking, combined braking, and traction control. NHTSA mandates in the United States and Euro 5 requirements in Europe enforce minimum sensor counts and failure-mode diagnostics for type approval.
- Performance Monitoring:Accelerometers, gyroscopes, and temperature transducers feed data acquisition for lap timing, suspension tuning, and engine calibration. Track-day participants and racing teams in Germany, Japan, and Australia drive premium demand for high-sample-rate devices.
- Navigation:GPS and inertial sensors support turn-by-turn routing, ride logging, and terrain mapping. Motorcycle-specific navigation platforms from Garmin and TomTom integrate these with glove-friendly interfaces and weatherproofing.
- Theft Prevention:Tilt sensors, motion detectors, and geolocation modules trigger alarms and recovery protocols. Urban parking congestion in São Paulo, Jakarta, and Lagos sustains aftermarket demand for standalone security systems.
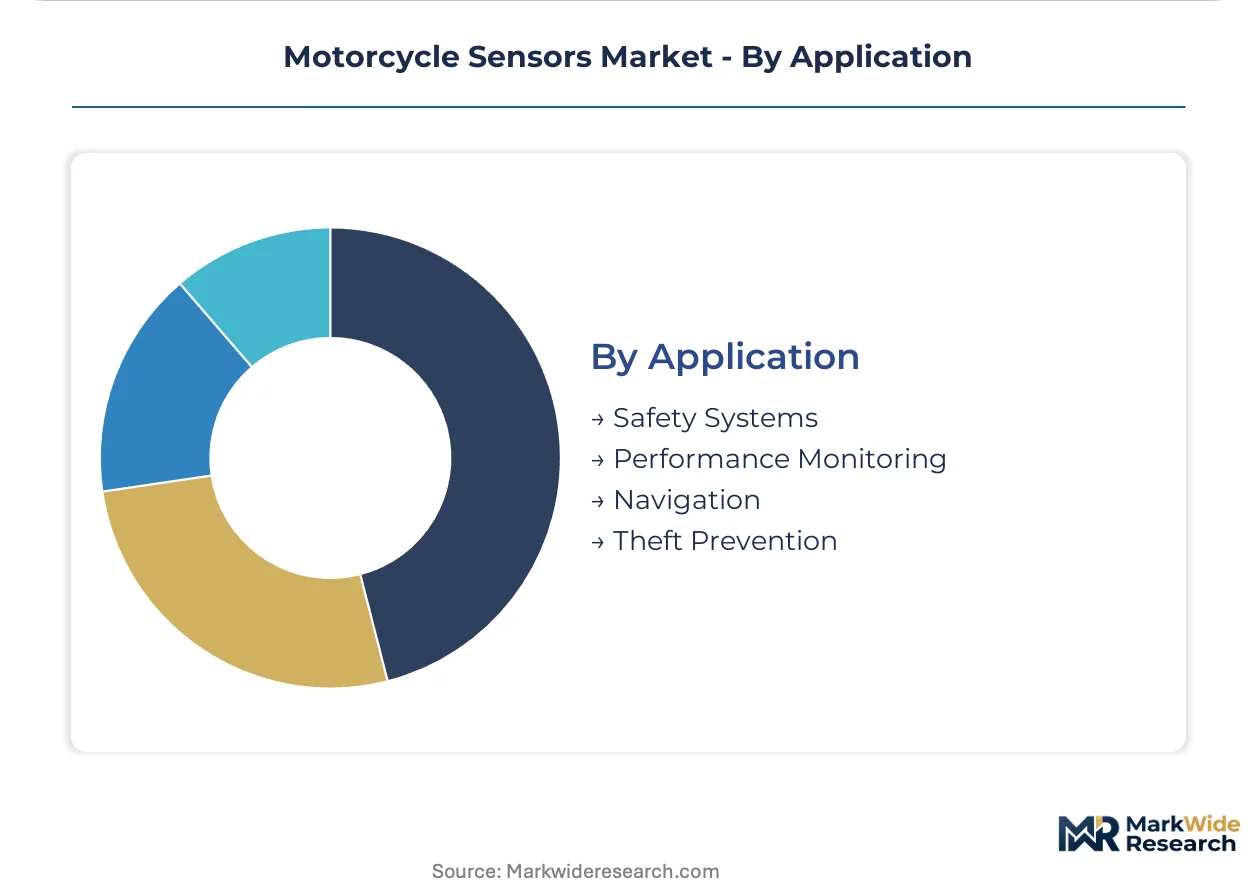
Regulatory compliance anchors safety systems deployment. Performance monitoring is gaining share fastest as track-day participation expands and data-logging becomes standard in premium motorcycle specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian electronics clusters, while consumption divides between European regulatory compliance and Indian volume expansion. This geographic split shapes supplier investment priorities across fabrication and assembly networks.
Germany
KBA type-approval mandates for motorcycles above 125cc displacement drive sensor deployment for anti-lock braking and traction control systems. Euro 5 standards administered by national authorities enforce exhaust gas temperature and oxygen sensing obligations. Stuttgart and Munich anchor Continental AG and Robert Bosch GmbH engineering centers that supply premium European OEMs.
India
Bureau of Energy Efficiency fuel efficiency mandates and Ministry of Industry safety regulations expand sensor counts across commuter and performance segments. Domestic production volumes at Chennai, Pune, and Gurugram plants create concentrated demand for pressure and inertial modules. Tier-one suppliers are qualifying local assembly lines to serve Hero MotoCorp and Bajaj Auto specifications.
United States
NHTSA anti-lock braking performance thresholds depend on wheel-speed and inertial sensors for compliance demonstration. EPA evaporative emission standards require fuel vapor pressure monitoring in the aftermarket channel. California and Michigan host development operations for GPS-enabled telematics integration into fleet management platforms.
Japan
METI industrial policy supports MEMS fabrication scale for automotive-grade pressure and inertial sensing. Domestic OEMs including Honda and Yamaha specify integrated sensor suites at the design stage rather than post-production retrofit. Aichi and Shizuoka prefectures concentrate supplier engineering capacity for chassis dynamics applications.
China
MIIT standards for motorcycle electronic control systems are converging with automotive-grade functional safety requirements. GB standards for emissions monitoring extend oxygen and temperature sensing obligations to domestic manufacturers. Yangtze River Delta electronics clusters in Shanghai and Suzhou supply both local OEMs and export assembly operations.
Motorcycle Sensors Market Vendor Landscape
Top-tier vendors anchor OEM supply relationships, while mid-scale specialists serve aftermarket retrofit and custom build segments. The vendor base stratifies across three tiers: integrated automotive suppliers with captive semiconductor fabrication, tier-two module assemblers sourcing MEMS dies from foundry partners, and regional distributors handling replacement inventory. Two strategic archetypes dominate: scale-driven MEMS fabricators competing on unit cost, and application-specific specialists defending margin through firmware integration. Competitive moves concentrate on backward integration into MEMS wafer processing and geographic expansion into Indian and Southeast Asian assembly operations.
Within the integrated automotive tier, Robert Bosch GmbH and Continental AG exemplify scale-driven positioning through captive European fabrication and design-in relationships with premium motorcycle OEMs. NXP Semiconductors NV occupies a specialist position bridging automotive-grade microcontroller integration with reduced ECU footprint requirements. These three entities represent distinct competitive vectors: Bosch anchors pressure and inertial sensing through MEMS scale, Continental leverages European premium brand captivity, and NXP competes on semiconductor integration density rather than discrete sensor manufacturing.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Honda Motor Co. Ltd. |
| Infineon Technologies AG |
| NXP Semiconductors NV |
| Denso Corporation |
| Mitsubishi Electric Corp. |
| ZF Friedrichshafen AG |
| Hitachi Ltd. |
| Others |
Supply Flow & Price Mechanics
Neodymium oxide price volatility cascades through magnet-based position sensor production, fragmenting margin structures across premium automotive-grade tiers and economy aftermarket modules as tier-two suppliers absorb raw material swings without long-term purchase agreements.
Pricing Analysis
Cost-down pressure on economy-tier pressure sensors accelerates because Chinese OEM procurement teams enforce annual price reduction targets for commuter motorcycle platforms. Pricing stratifies across automotive-grade ISO 26262-certified modules, industrial-grade fleet telematics units, and unbranded aftermarket retrofit kits. Margin tightening in the premium tier reflects firmware integration investments for edge-computing architectures. Fleet operators in Southeast Asia exhibit highest price sensitivity, while European premium OEMs prioritize functional safety certification over unit cost.
Supply Chain Analysis
Engineering talent scarcity in Yangtze River Delta MEMS foundries constrains wafer processing capacity expansion for automotive-grade pressure transducers. Backend semiconductor assembly draws from Taiwan, South Korea, and Malaysia, with silicon carbide substrate sourcing anchored in Japan and the United States. Single-source vulnerability concentrates in Taiwan packaging houses serving Bosch and Continental modules. Distribution runs through tier-one direct OEM supply agreements, regional aftermarket distributors in Brazil and Mexico, and B2B fleet procurement platforms bypassing dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The motorcycle sensors market functions as a cost-of-compliance arena where Euro 5 type-approval mandates erect engineering validation barriers that favor incumbents with multi-homologation laboratory capacity over capital-constrained challengers.
For Market Incumbents: Extend captive MEMS fabrication scale into Indian assembly operations to capture Bureau of Energy Efficiency mandate-driven volume expansion at Hero MotoCorp and Bajaj Auto. Deepen backward integration into silicon carbide wafer processing to offset rare earth magnet price volatility threatening position sensor margins. Prioritize ISO 26262 functional safety certification investment as firmware complexity extends development timelines and locks out tier-two competitors lacking validation infrastructure. For New Entrants and Emerging Players: Sensor fusion architectures for predictive chassis control without centralized ECU dependency represent the most penetrable white-space opportunity, targeting California and Shanghai electric motorcycle startups testing low-speed maneuvering aids. GPS-enabled telematics integration into usage-based insurance underwriting offers recurring-revenue positioning against transactional hardware incumbents. Pursue direct B2B fleet procurement relationships in Indonesian and Vietnamese ride-hailing platforms where vehicle utilization rates exceed eighteen hours daily and dealer network bypass is already normalized. For Investors and Strategic Acquirers: Distressed-cycle entries favor tier-two module assemblers with qualified local assembly lines in Indian industrial corridors but strained working capital from raw material price volatility. Long-term viability hinges on acquisition targets possessing multi-homologation engineering capacity spanning NHTSA, KBA, and BIS testing protocols as regulatory divergence fragments certification requirements. Monitor divergence between OBD-II harmonization in North America and proprietary diagnostic standards in emerging production hubs as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fabrication Scale-Up | Captive wafer processing at Bosch and Continental lowers unit costs for pressure sensing modules deployed in Indian commuter motorcycles. |
| Multi-Homologation Engineering Investment | Simultaneous NHTSA, KBA, and BIS compliance capacity accelerates regional market entry and defends margin pools against fragmented certification costs. |
| Edge Computing Architecture Development | Distributed signal processing at sensor nodes reduces ECU dependency and enables predictive chassis control for premium European OEM platforms. |
| GPS Telematics Platform Integration | Recurring-revenue sensor service models penetrate Indonesian and Vietnamese fleet operator procurement channels outside traditional dealer networks. |
| Silicon Carbide Material Transition | 150°C continuous operation qualification decentralizes thermal management requirements toward sensing elements in fuel injection applications. |
Methodological Framework
Multi-period observation of MEMS fabrication capacity utilization, type-approval certification timelines, and OEM platform sensor content anchored the trend analysis, supplemented by interviews with tier-one supplier procurement directors, aftermarket distributor operations heads, and fleet telematics platform engineers. Secondary validation drew from KBA and NHTSA regulatory filings, IHS Markit motorcycle production databases, and Bureau of Energy Efficiency mandate documentation. Bottom-up sensor unit economics triangulated against top-down OEM platform specification analysis.
Input-output matrices modeled volume and value projections across product type, technology protocol, end-user procurement authority, and application functional purpose throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation with macro motorcycle production forecasts and regulatory mandate implementation schedules. Industry-specific forecast inputs included Euro 5 type-approval phase-in timing and India's domestic production volume expansion trajectories.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan semiconductor packaging capacity, abrupt rare earth export restriction implementation, and unanticipated regulatory protocol harmonization between North American and Asian diagnostic standards. Forecasts reflect documented assumptions regarding MEMS cost-down curves and OEM platform sensor integration timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Aspiration Control Systems Market
Sensors and Controls
Position Sensor Market
Sensors and Controls
APAC Occupancy Sensors Market
Sensors and Controls
Global Hazardous Location Thermostats Market
Sensors and Controls
Temperature Monitoring System Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Printed Antenna Market
Sensors and Controls
APAC Temperature Sensors Market
Sensors and Controls
Silicon Photomultiplier (Sipm) Market
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
Global Space Sensors and Actuators Market
Sensors and Controls
Safety Laser Scanner Market
Sensors and Controls
Digital Automation Temperature Regulator Market
Sensors and Controls
Hazardous Area Sensors Market
Sensors and Controls
Piezoelectric Devices Market