
 Global Acoustic Wave Sensor Market | 2026-2036
Global Acoustic Wave Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acoustic Wave Sensor Market Analysis
China's Jiangsu province is reconfiguring its MEMS foundry capacity to accommodate acoustic wave sensor wafer production for automotive and telecommunications clients. Honeywell International Inc. leverages its aerospace certification heritage to dominate high-reliability SAW sensor supply for satellite and avionics programs. Siemens AG anchors its position through backward integration into quartz crystal supply and in-house fabrication of resonator structures for industrial automation.
Acoustic wave sensors are piezoelectric devices that convert mechanical acoustic waves into electrical signals, typically operating at frequencies from megahertz to gigahertz ranges using quartz, lithium niobate, or lithium tantalate substrates; they detect mass loading, temperature shifts, pressure changes, or chemical absorption with precision suited to harsh environments. Their primary purpose spans process control in refineries, structural health monitoring in aircraft, and environmental gas detection where electrochemical alternatives fail. SAW sensors occupy the largest revenue share due to mature smartphone filter applications, while BAW sensors are displacing legacy technologies in 5G base stations where higher frequency stability is required. Bulk acoustic wave variants sustain premium pricing in healthcare diagnostics, where FDA and EMA biocompatibility standards constrain supplier qualification.
FCC emissions rules in the United States and EU Radio Equipment Directive shape frequency allocation and interference thresholds for wireless sensor networks, directly constraining design architectures and testing costs for manufacturers seeking multi-region approval. Japan's METI energy efficiency standards and China's GB sensor calibration mandates add compliance layers that favor established producers with dedicated certification laboratories. Stakeholders must monitor divergence between regional spectrum policies and material substance restrictions, as simultaneous compliance across FDA, REACH, and MIIT frameworks determines which product architectures achieve commercial scale.
Market Dynamics
Automotive electrification and 5G infrastructure buildouts are compressing development cycles for acoustic wave sensors, forcing substrate suppliers to synchronize quartz and lithium niobate output with semiconductor fabrication schedules in East Asian foundry clusters.
Growth Catalysts
- EU REACH substance restrictions:Piezoelectric material compliance mandates are accelerating substrate qualification programs for European automotive and industrial sensor manufacturers.
- Telecommunications infrastructure:5G base station deployments require BAW resonators with tighter frequency stability than legacy ceramic alternatives can deliver.
- South Korean semiconductor clusters:Concentrated MEMS foundry capacity in Gyeonggi Province enables rapid prototyping-to-production scaling for consumer electronics integration.
Market Restraints
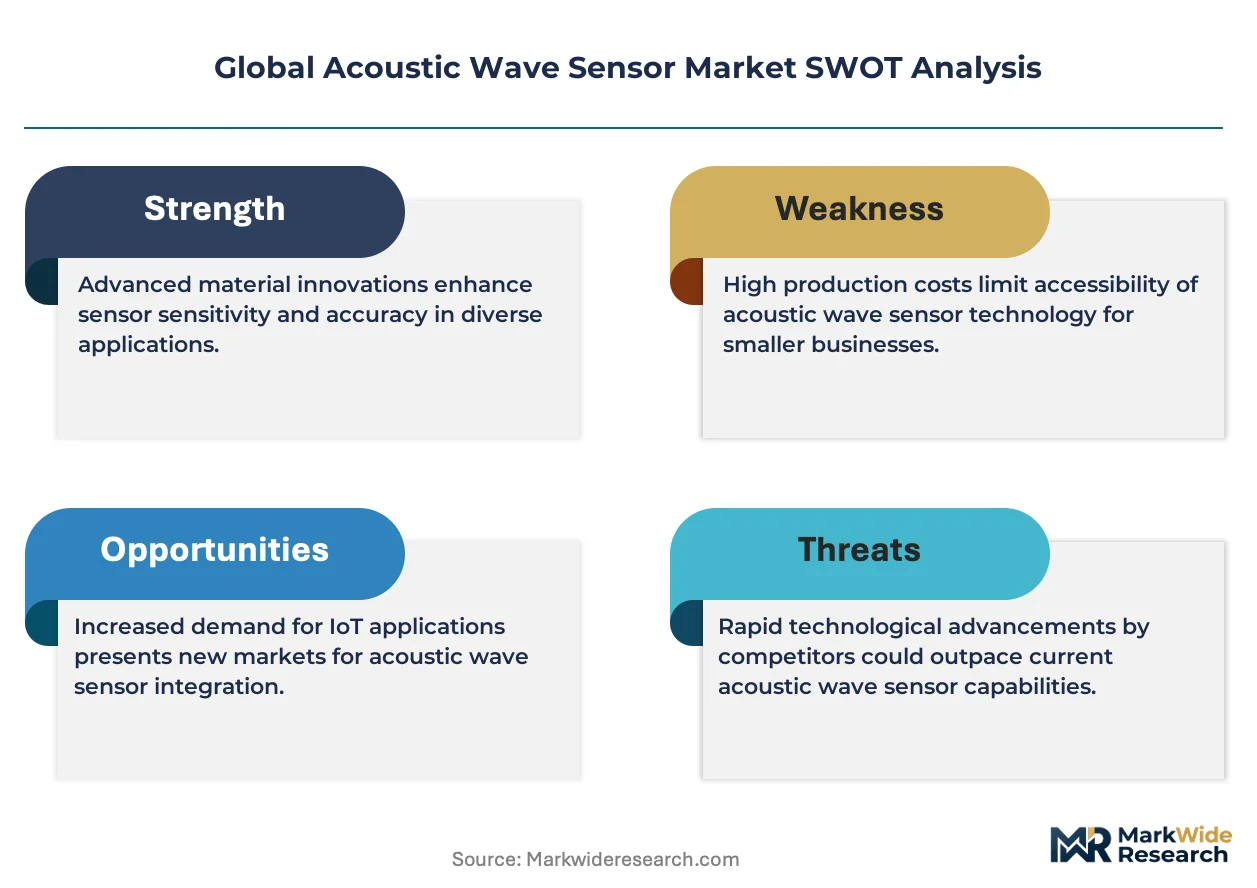
- Quartz crystal supply concentration:High-purity synthetic quartz substrate production clusters in limited geographic zones create input vulnerability for SAW device fabricators.
- FCC and EU Radio Equipment Directive interference thresholds:Multi-region certification requirements inflate testing costs and extend time-to-market for wireless sensor network architectures.
- Optical sensor substitution:Fiber Bragg grating alternatives are capturing select structural health monitoring applications in civil infrastructure where electromagnetic immunity is paramount.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Incentive structures for semiconductor packaging and testing are attracting acoustic wave sensor module assembly investments.
- Healthcare point-of-care diagnostics:FDA and EMA biocompatibility pathways for implantable BAW biosensors remain underdeveloped relative to electrochemical alternatives.
- AI-driven predictive maintenance:Convergence of acoustic wave sensing edge nodes with machine learning analytics platforms is opening industrial automation subscription revenue models.
Industry Challenges
- Piezoelectric thin-film deposition expertise:Scarcity of process engineers skilled in aluminum nitride sputtering for BAW manufacturing constrains foundry expansion timelines.
- ISO/IEC 17025 calibration laboratory access:Limited third-party certification capacity in emerging manufacturing zones delays sensor qualification for automotive safety systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acoustic Wave Sensor Market |
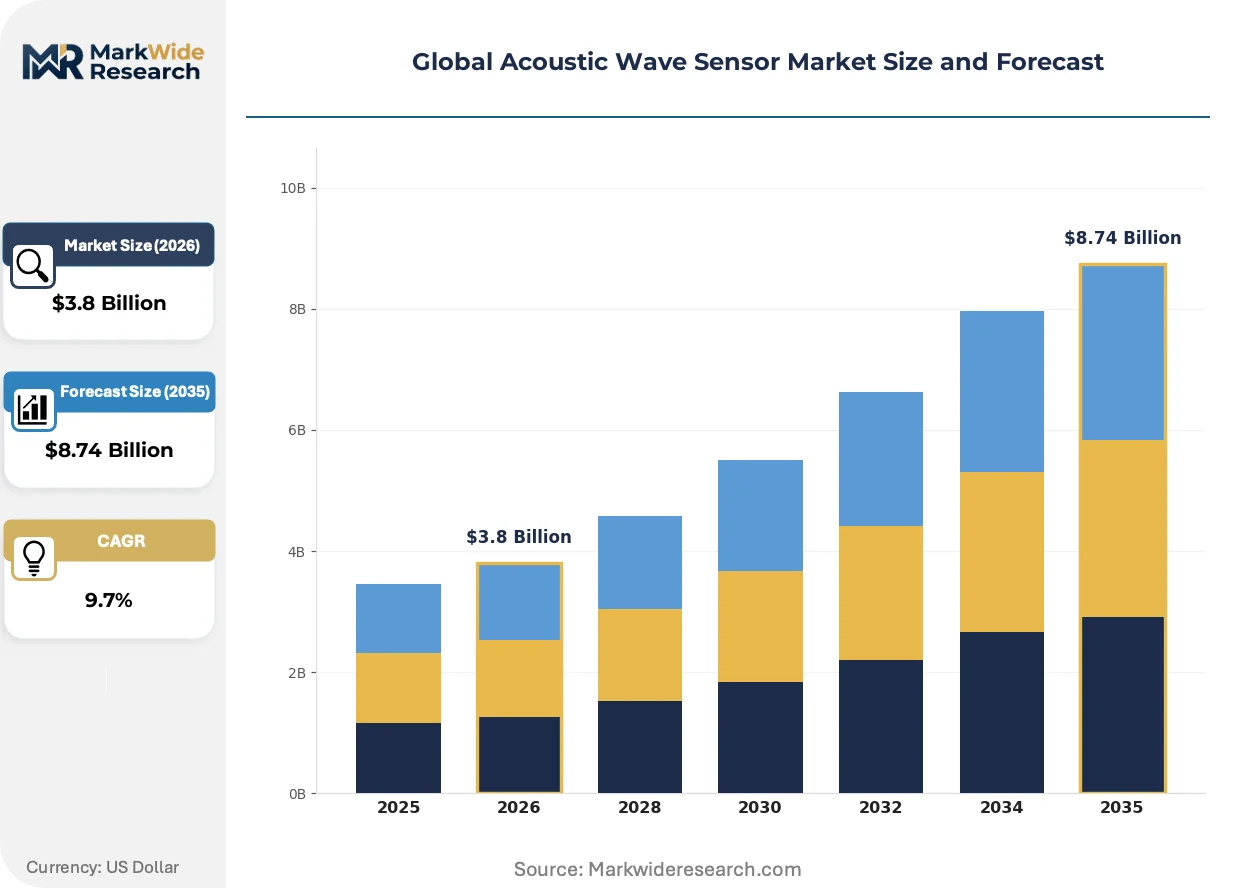
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
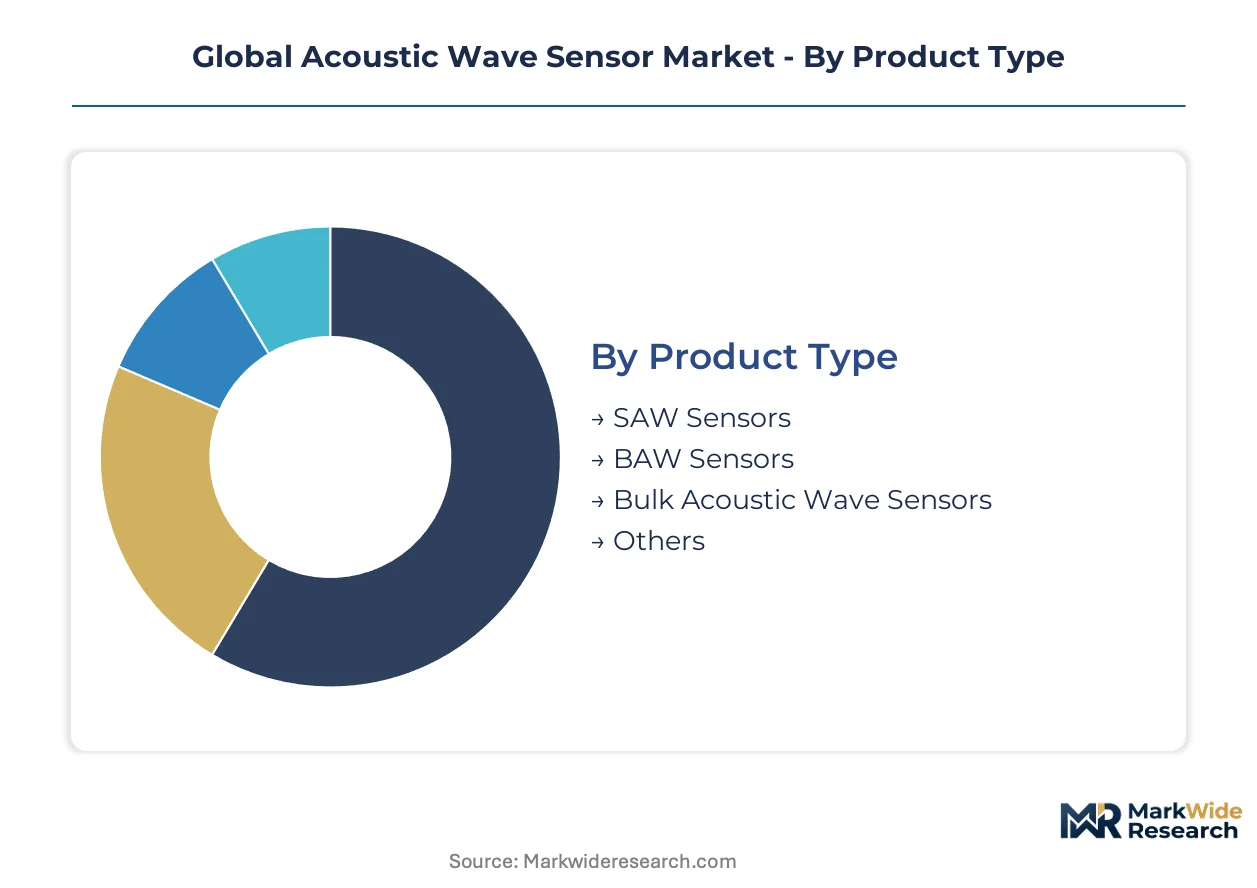
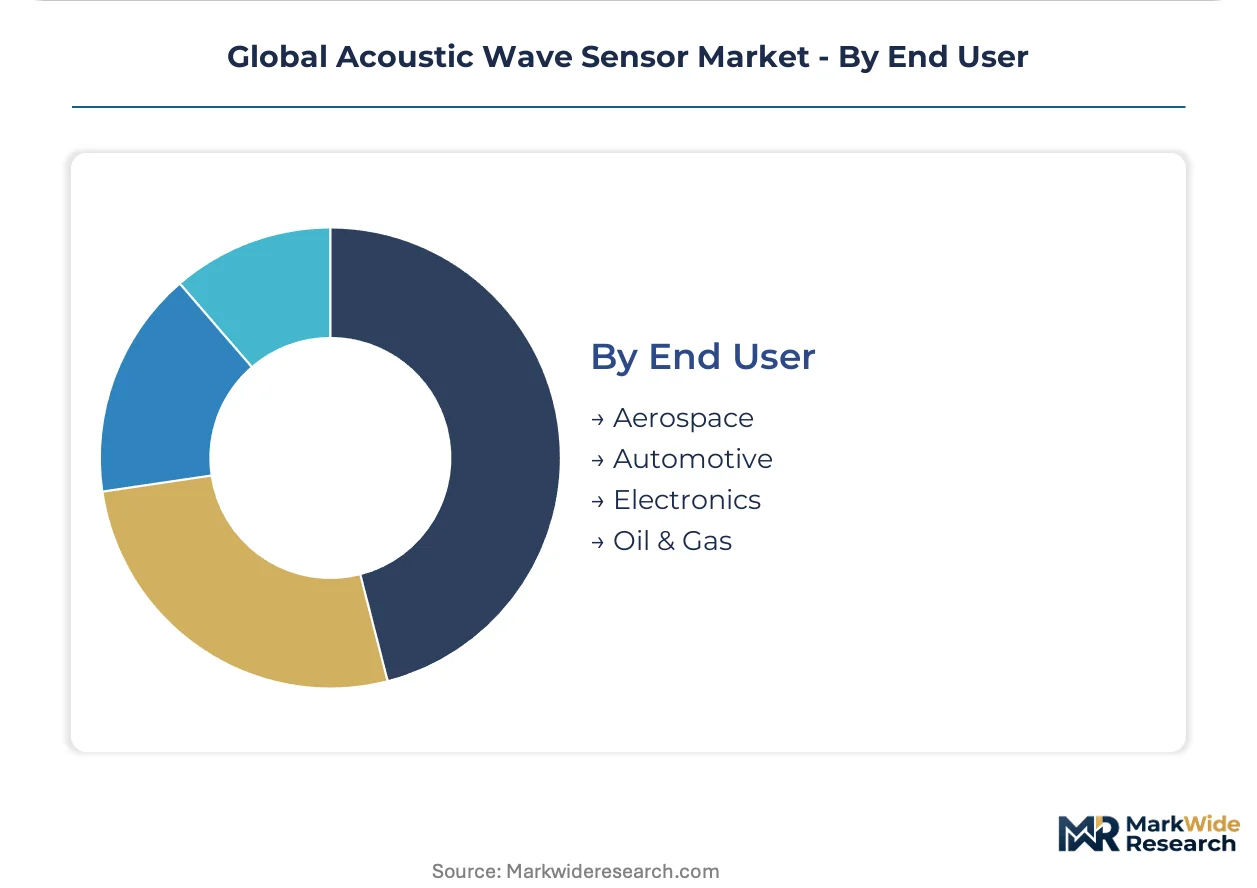
| Segmentation | Product Type: SAW Sensors, BAW Sensors, Bulk Acoustic Wave Sensors, Others Technology: Resonant, Non-Resonant, Active, Passive Application: Environmental Monitoring, Industrial Automation, Healthcare, Consumer Electronics End User: Aerospace, Automotive, Electronics, Oil & Gas |
| Companies Covered | Honeywell International Inc., Siemens AG, General Electric Company, CTS Corporation, AVX Corporation, Transense Technologies plc, Electronic Sensor Technology, Murata Manufacturing Co., Ltd., Vectron International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acoustic Wave Sensor Market Emerging Trajectories
Digital twin integration and substrate material innovation are compressing the boundary between physical sensing layers and computational analytics, restructuring how acoustic wave devices are specified, validated, and monetized across industrial verticals.
Thin-film lithium niobate-on-insulator substrates are virtualizing traditional bulk crystal resonator functions into photonics-compatible form factors. Datacom and quantum computing hardware developers in Taiwan and the United States are sampling these platforms for clock distribution and frequency synthesis. This substrate transition is virtualizing the discrete component supply chain into wafer-scale photonic integrated circuit foundries.
China's MIIT GB sensor calibration mandates and dual carbon goals are tightening traceability requirements for piezoelectric device manufacturing. Domestic certification protocols now require documented energy consumption metrics across substrate growth, wafer processing, and packaging stages. Environmental monitoring and automotive sensor suppliers targeting Chinese OEMs are restructuring supplier qualification programs to satisfy these layered compliance frameworks.
Japanese automotive Tier-1 suppliers are compressing sensor qualification cycles through parallel-track validation with METI energy efficiency standards and in-house reliability testing. This behavioral shift displaces sequential third-party laboratory dependencies with captive certification capacity. The practice is most visible in tire pressure monitoring and powertrain sensing programs where model-year refresh rates have shortened from 48 to 24 months.
Global Acoustic Wave Sensor Market Segmentation
Acoustic wave sensor procurement patterns diverge sharply across product architectures and end-use certifications, with aftermarket calibration requirements and replacement protocols creating distinct service revenue streams for each segment category.
Product Type:
After-sales service intensity varies dramatically across resonator technologies, with BAW sensors demanding specialized thin-film recalibration while SAW devices rely on standardized quartz replacement cycles.
- SAW Sensors:Surface acoustic wave devices built on quartz or lithium niobate substrates dominate smartphone RF filter applications and tire pressure monitoring systems. German automotive suppliers in Stuttgart and Munich anchor European demand for SAW-based TPMS modules, where METI energy efficiency standards in Japan and FCC emissions rules in the United States impose parallel certification burdens.
- BAW Sensors:Bulk acoustic wave resonators fabricated with aluminum nitride thin films deliver superior frequency stability for 5G base station infrastructure. South Korean foundries in Gyeonggi Province and Taiwanese semiconductor clusters concentrate BAW wafer production, driven by telecommunications infrastructure buildouts requiring tighter thermal drift specifications than ceramic alternatives permit.
- Bulk Acoustic Wave Sensors:Traditional thickness-shear mode resonators serve precision timing and gravimetric sensing in laboratory instrumentation.
- Others:Emerging flexural plate wave and shear-horizontal acoustic plate mode devices address niche chemical detection applications.
By volume, SAW Sensors lead. By growth pace, BAW Sensors is ahead.
Technology:
Cost tier stratification separates resonant architectures requiring precision frequency control from non-resonant alternatives suited to simpler threshold detection applications.
- Resonant:Frequency-stable oscillators with quality factors exceeding 10,000 serve precision timing and gravimetric measurement in pharmaceutical manufacturing and satellite payloads. FDA and EMA biocompatibility standards constrain resonant BAW adoption in implantable healthcare diagnostics, where electrochemical alternatives maintain regulatory pathway advantages.
- Non-Resonant:Amplitude-based detection circuits reduce component count for cost-sensitive consumer electronics integration. Chinese OEMs in Jiangsu province favor non-resonant SAW architectures for environmental gas detection modules, where MIIT GB calibration mandates and dual carbon goals tighten traceability requirements without demanding oscillator-grade precision.
- Active:Amplified output stages with integrated signal conditioning suit low-amplitude detection in industrial automation.
- Passive:Unamplified transducers minimize power consumption for battery-operated wireless sensor networks.
By installed base, Resonant dominates. By expansion trajectory, Non-Resonant is climbing the fastest.
Application:
Customer type segmentation reveals divergent procurement behaviors, with industrial automation buyers prioritizing ISO/IEC 17025 calibration certificates while consumer electronics purchasers emphasize volume scale and packaging miniaturization.
- Environmental Monitoring:Gas and particulate detection systems deployed in refinery perimeter networks and urban air quality stations. Honeywell International Inc. leverages aerospace certification heritage to supply high-reliability SAW sensors for EPA-compliant emissions monitoring in Houston petrochemical corridors.
- Industrial Automation:Vibration and pressure sensing for predictive maintenance in power generation and manufacturing equipment. Siemens AG anchors European demand through backward integration into quartz crystal supply and in-house fabrication of resonator structures for Industry 4.0 deployments.
- Healthcare:Point-of-care biosensors and implantable diagnostic devices subject to FDA and EMA biocompatibility qualification.
- Consumer Electronics:Microphone filters, touchscreen controllers, and motion sensors integrated into smartphone and wearable supply chains.
By revenue concentration, Industrial Automation leads. By application growth, Environmental Monitoring is gaining share fastest.
End User:
Supply concentration patterns align with end-user certification intensity, with aerospace and automotive sectors demanding captive calibration capacity while electronics buyers access commoditized foundry output.
- Aerospace:Satellite avionics and structural health monitoring systems requiring MIL-STD-883 qualification and radiation-hardened specifications. Japanese METI standards and FAA certification protocols create dual-track validation requirements for suppliers targeting geostationary communications payloads.
- Automotive:Tire pressure monitoring, powertrain sensing, and cabin environment control modules. German manufacturers in Baden-Württemberg and Japanese Tier-1 suppliers compress qualification cycles from 48 to 24 months through parallel-track validation with captive reliability testing.
- Electronics:Consumer device and telecommunications infrastructure integration with concentrated MEMS foundry sourcing from South Korea and Taiwan.
- Oil & Gas:Downhole pressure and temperature sensing for reservoir monitoring in harsh subsurface environments.
By unit volume, Electronics leads. By value per sensor, Aerospace is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex underwrites China's dominance in acoustic wave sensor substrate throughput, while the Trans-European Transport Network channels German automotive demand westward across the Rhine-Ruhr corridor.
United States
FCC emissions rules and FAA certification protocols govern wireless sensor networks for satellite avionics and industrial automation. Houston's petrochemical corridor anchors EPA-compliant emissions monitoring deployments, where Honeywell International Inc. leverages aerospace certification heritage for high-reliability SAW sensor supply.
Germany
EU REACH substance restrictions and KBA automotive safety mandates accelerate piezoelectric material qualification for tire pressure monitoring systems. Stuttgart and Munich cluster SAW-based TPMS module production, with Baden-Württemberg manufacturers compressing qualification cycles through parallel-track validation.
China
MIIT GB sensor calibration mandates and dual carbon goals tighten traceability across substrate growth and wafer processing stages. Jiangsu province reconfigures MEMS foundry capacity for automotive and telecommunications clients, integrating acoustic wave sensors into domestic OEM supply chains.
Japan
METI energy efficiency standards and shortened model-year refresh rates drive captive certification capacity among Tier-1 automotive suppliers. Nagoya and Osaka industrial zones concentrate powertrain sensing and cabin environment control module fabrication.
South Korea
Gyeonggi Province foundries synchronize aluminum nitride sputtering output with 5G base station deployment schedules. Concentrated MEMS capacity enables rapid prototyping-to-production scaling for BAW resonators displacing legacy ceramic alternatives.
Global Acoustic Wave Sensor Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying resonator substrates and fabrication services to module assemblers. The vendor base stratifies across three tiers: diversified conglomerates with captive quartz supply, semiconductor foundries with MEMS process expertise, and niche specialists in harsh-environment certification. Consolidation pressure intensifies as automotive electrification and 5G infrastructure buildouts compress development cycles, forcing substrate suppliers to synchronize output with East Asian foundry schedules. Dominant competitive moves include backward integration into lithium niobate crystal growth and strategic partnerships between sensor designers and telecommunications equipment manufacturers.
Among diversified technology conglomerates, Honeywell International Inc. and Siemens AG occupy positions spanning aerospace certification heritage and industrial automation integration. Honeywell exemplifies the high-reliability system supplier archetype, while Siemens AG anchors European demand through upstream control over quartz crystal supply and in-house resonator fabrication. CTS Corporation represents the specialized component fabricator tier, sitting within the supply chain as a supplier of precision frequency control products to module assemblers.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| General Electric Company |
| CTS Corporation |
| AVX Corporation |
| Transense Technologies plc |
| Electronic Sensor Technology |
| Murata Manufacturing Co., Ltd. |
| Vectron International |
| Others |
Supply Flow & Price Mechanics
Synthetic quartz substrate production clusters in Japan and Germany anchor upstream supply concentration, channeling margin capture toward SAW device fabricators with captive crystal growth capabilities while forcing module assemblers into long-term offtake negotiations.
Pricing Analysis
EU REACH substance restrictions dictate the pricing tier structure across European automotive and industrial sensor procurement. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade resonators with MIL-STD-883 qualification from consumer electronics commodity filters. Cost compression in standard-tier SAW modules is intensifying because Chinese foundries are scaling lithium niobate-on-insulator wafer output for telecommunications clients. Consumer electronics buyers exhibit highest price sensitivity, while aerospace prime contractors absorb premium pricing for radiation-hardened specifications.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for acoustic wave sensor module assemblers. High-purity synthetic quartz draws from Japanese and German chemical vapor deposition facilities, while aluminum nitride thin-film sputtering feeds from South Korean and Taiwanese semiconductor clusters. Single-source vulnerability concentrates in synthetic quartz substrate qualification programs, where automotive safety system certification locks fabricators into specific supplier relationships. Distribution runs through East Asian MEMS foundry hubs to German automotive Tier-1 suppliers and US telecommunications infrastructure deployers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration service contracts and predictive maintenance analytics subscriptions are expanding faster than hardware unit sales, transforming acoustic wave sensor economics toward recurring-revenue models in industrial automation verticals.
For Market Incumbents: Insulate aerospace and automotive qualification heritage through captive ISO/IEC 17025 laboratory capacity, neutralizing emerging foundry competitors from South Korea that lack certification depth. Deepen backward integration into lithium niobate crystal supply to offset quartz substrate concentration risk from Japanese suppliers. Priority investment in thin-film lithium niobate-on-insulator process expertise defends against photonics-compatible substrate substitution.
For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing offers the most penetrable geographic entry point for acoustic wave sensor module assembly, with incentive structures covering semiconductor packaging and testing investments. Target healthcare point-of-care diagnostics as the least saturated application vertical, where FDA and EMA biocompatibility pathways for implantable BAW biosensors remain underdeveloped relative to electrochemical alternatives. Go-to-market angle: partner with established MEMS foundries in Gyeonggi Province for rapid prototyping-to-production scaling without capital-intensive fabrication buildout.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed automotive sensor specialists that consolidated during the last decade's TPMS mandate waves. Long-term viability across the analysis window hinges on substrate material transition readiness and AI-driven predictive maintenance platform integration. Acquisition target archetype: mid-cap BAW resonator fabricators with aluminum nitride sputtering expertise and telecommunications equipment manufacturer relationships. Signal to watch: divergence between regional spectrum policies and material substance restrictions, as simultaneous compliance across FCC, REACH, and MIIT frameworks determines which product architectures achieve commercial scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Niobate Supply | Siemens AG's quartz crystal control demonstrates margin capture from substrate ownership in industrial automation. |
| AI-Driven Predictive Maintenance Platform Development | Convergence with machine learning analytics opens subscription revenue models in power generation equipment monitoring. |
| Healthcare Biocompatibility Certification Investment | FDA and EMA pathway development for implantable BAW biosensors addresses underpenetrated diagnostics vertical. |
| Photonics-Compatible Substrate Transition | Thin-film lithium niobate-on-insulator sampling by Taiwan datacom developers virtualizes discrete component supply chains. |
| Captive Calibration Laboratory Buildout | Japanese Tier-1 suppliers' parallel-track validation with METI standards compresses qualification cycles from 48 to 24 months. |
Methodological Framework
Operator-level perspectives from MEMS foundry process engineers, automotive Tier-1 sensor procurement managers, telecommunications equipment platform architects, and aerospace certification specialists anchored the qualitative base. Primary interview intelligence combined with secondary validation from SEC 10-K filings of listed sensor manufacturers, MIIT GB standard calibration documentation, EU REACH substance restriction databases, and customs trade data for quartz and lithium niobate substrate flows. Bottom-up segment sizing across product architectures and applications triangulated against top-down macroeconomic indicators for semiconductor capital expenditure and automotive electronics content.
Scenario-bracketing framed analytical approach across the analysis window, with base, upside, and downside cases reflecting divergence in 5G infrastructure deployment pace and automotive electrification subsidy durability. Segmentation dimensions modeled include resonator technology type, end-use certification intensity, geographic regulatory cluster, and supply chain integration depth. CAGRs derived from historical shipment correlations with downstream equipment production indices and forward-looking foundry capacity expansion announcements. Industry-specific forecast inputs encompassed aluminum nitride sputtering equipment delivery schedules and automotive model-year refresh cycle compression trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed substrate producers or rapid consolidation among South Korean foundry operators would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
US Smart Air Purifier Market
Sensors and Controls
Italy Digital Thermometer Market
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
Smart Parking Sensor Market
Sensors and Controls
Asia-Pacific MEMS and Sensors Market
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
Middle East and Africa Vibration Sensors Market
Sensors and Controls
Water and Wastewater Sensors Market
Sensors and Controls
Global Industrial Smart Sensors Market
Sensors and Controls
US Distributed Acoustic Sensing Market
Sensors and Controls
APAC Chemical Sensors Market
Sensors and Controls
2D Gesture Recognition Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Europe Sensors Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
Electric Vehicle (EV) Sensor Market