
 Gesture Recognition and Touch-Less Sensing Market | 2026-2036
Gesture Recognition and Touch-Less Sensing Market Size, Share, and Industry Trends Forecast 2026-2036
Gesture Recognition and Touch-Less Sensing Market Analysis
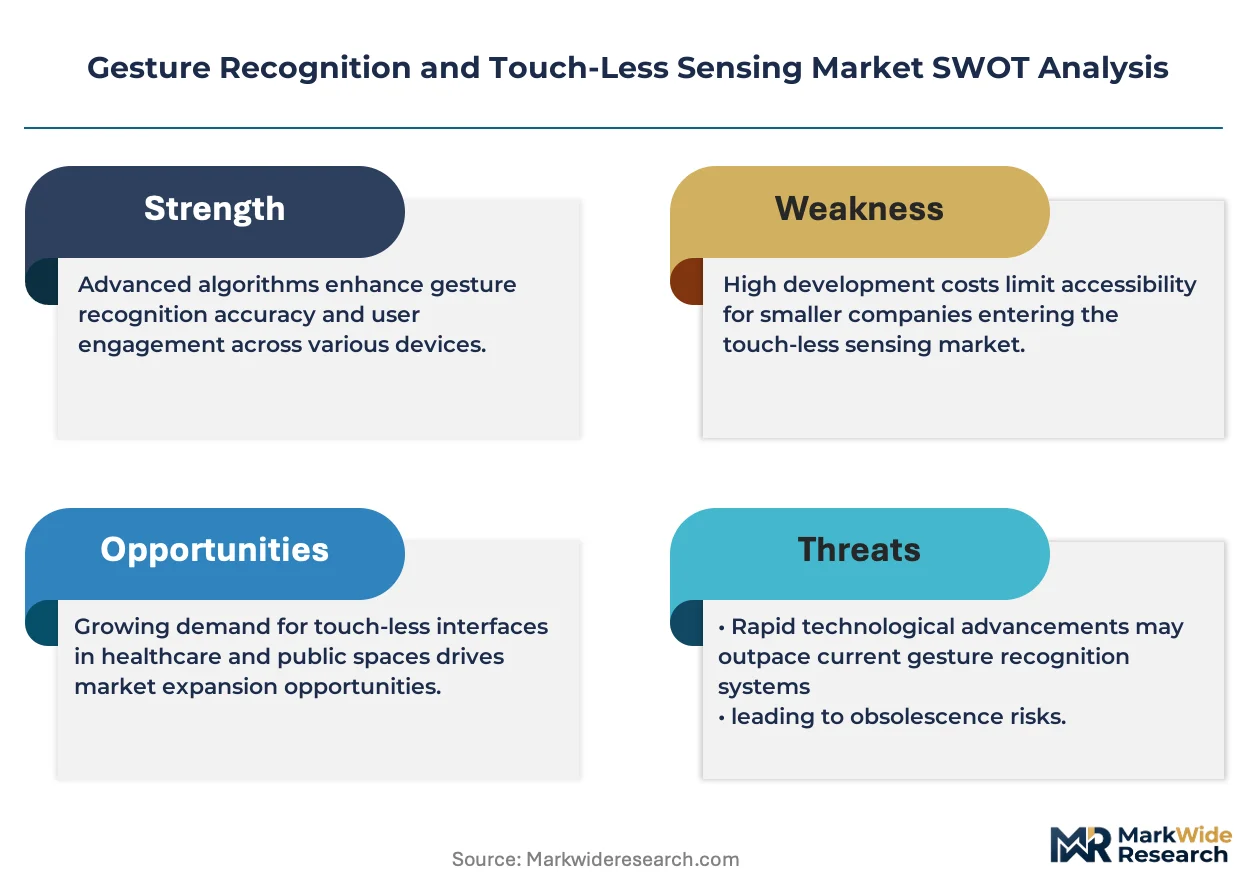
Computer vision engineering talent scarcity is bifurcating the competitive landscape between firms with captive AI labs and those dependent on outsourced model development. Apple leverages its silicon-software co-design capability to sustain end-to-end gesture pipeline control across device ecosystems. Microsoft Corporation anchors enterprise demand through Azure Kinect and HoloLens integration services for industrial clients. Infineon Technologies specializes in radar-based micro-Doppler sensing for automotive interior monitoring, competing against camera-centric rivals with privacy-preserving architectures.
Gesture recognition and touch-less sensing encompasses hardware-software systems that interpret human body motion, proximity, and biometric signatures without physical contact, typically operating through optical time-of-flight arrays at 940nm wavelength, 60GHz FMCW radar, or capacitive field distortion matrices. These systems enable hygienic human-machine interfaces in healthcare settings, driver-attention monitoring in vehicles, and spatial computing interactions in augmented reality environments. Optical sensors dominate consumer electronics volume due to smartphone integration, while ultrasonic sensors claim premium positioning in automotive gesture control where electromagnetic interference resistance matters. Software Development Kits represent the fastest-expanding solution category as OEMs seek to decouple hardware procurement from algorithm licensing.
The EU AI Act classifies biometric identification systems as high-risk, forcing providers to maintain conformity assessment documentation and human oversight protocols for European market access. FDA regulates touch-less patient monitoring devices in the United States under 510(k) pathways, while China's NMPA and GB standards govern domestic deployment of facial and gesture analytics in public infrastructure. Stakeholders must monitor divergence between privacy-centric European frameworks and performance-oriented Asian certification regimes when architecting multi-regional product strategies.
Market Dynamics
The EU AI Act's high-risk classification of biometric identification systems is forcing hardware-software decoupling across European deployments, compelling OEMs to source SDKs independently from sensor modules to maintain compliance flexibility.
Growth Catalysts
- Automotive interior monitoring mandates:Germany's KBA and EU vehicle safety frameworks are accelerating radar-based occupant detection adoption in passenger vehicles.
- GDPR-compliant sensing architectures:Privacy-preserving radar and capacitive alternatives to optical systems are gaining preference in European healthcare and public infrastructure.
- Silicon-software co-design integration:Captive semiconductor fabrication capabilities are enabling end-to-end pipeline control for gesture recognition chipsets.
Market Restraints
- 940nm optical component supply concentration:Time-of-flight sensor foundry capacity concentrates in East Asian manufacturing clusters, creating single-source vulnerability.
- FMCW radar IP licensing costs:Micro-Doppler processing patents held by automotive Tier-1 suppliers inflate BOM costs for mid-tier OEMs.
- Biometric data processing fragmentation:Divergent GDPR, NMPA GB standards, and FDA 510(k) pathways force redundant certification investments for multi-regional products.
Strategic Opportunities
- Underpenetrated industrial automation:German automotive and logistics hubs around Stuttgart show latent demand for touch-less HMI in assembly line environments.
- Software Development Kit unbundling:Algorithm licensing separate from hardware procurement is opening recurring revenue streams for computer vision specialists.
- 60GHz radar-capacitive convergence:Hybrid sensing architectures combining electromagnetic interference resistance with proximity precision are penetrating medical device manufacturing.
Industry Challenges
- Computer vision engineering scarcity:Deep learning model optimization for edge deployment requires talent pools concentrated in Munich, Stuttgart, and select US tech clusters.
- Legacy system integration friction:Retrofitting touch-less interfaces into existing automotive infotainment and industrial control architectures demands custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gesture Recognition and Touch-Less Sensing Market |
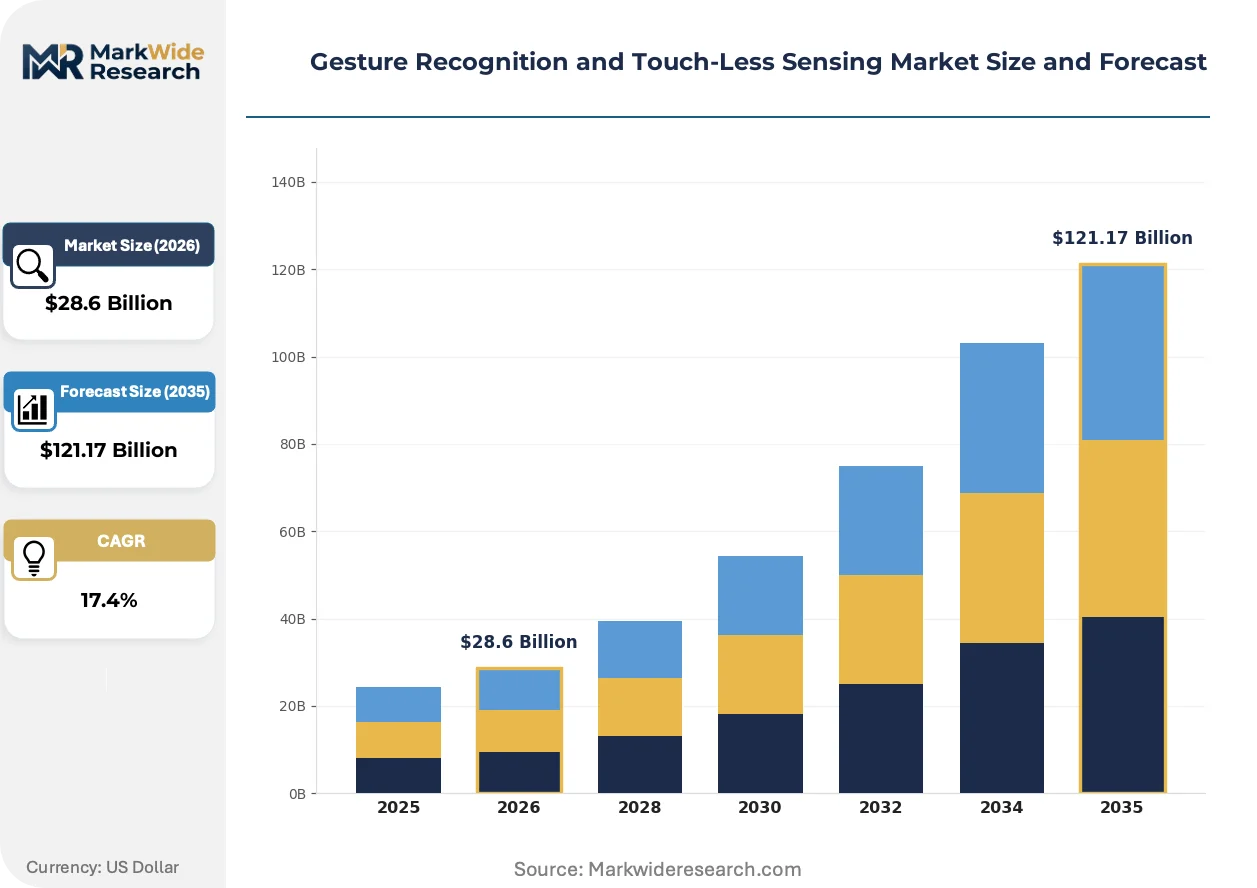
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $121.17 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Optical Sensors, Ultrasonic Sensors, Capacitive Sensors, Infrared Sensors Application: Consumer Electronics, Automotive, Healthcare, Smart Home End User: Retail, Education, Entertainment, Industrial Solution: Software Development Kits, Middleware, Integration Services, Custom Solutions |
| Companies Covered | Apple Inc., Microsoft Corporation, Microchip Technology Inc., Google LLC, Infineon Technologies, Intel Corporation, Qualcomm Inc., GestureTek, Cognitec Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gesture Recognition and Touch-Less Sensing Market Emerging Trajectories
Sensor modality substitution is compressing the competitive landscape as privacy regulations and electromagnetic resilience requirements reshape procurement criteria across automotive and healthcare verticals.
60GHz FMCW radar is supplanting camera-based gesture recognition in European automotive interior monitoring, with Munich-based OEMs adopting micro-Doppler architectures for driver-attention systems. The shift enables GDPR-compliant biometric processing without image capture, compressing market share for optical time-of-flight suppliers in premium vehicle segments.
EU AI Act conformity assessment documentation mandates are forcing SDK providers to maintain algorithm audit trails and human oversight protocols for high-risk biometric deployments. Industrial clients in Germany's sensor cluster are demanding pre-certified software modules, accelerating consolidation around vendors with captive compliance infrastructure.
Healthcare procurement teams are unbundling hardware acquisition from algorithm licensing, with German hospital networks and US clinical systems separately contracting sensor manufacturers and computer vision software houses. The disintermediation is most visible in patient monitoring device categories where FDA 510(k) pathways favor modular certification strategies over integrated system approvals.
Gesture Recognition and Touch-Less Sensing Market Segmentation
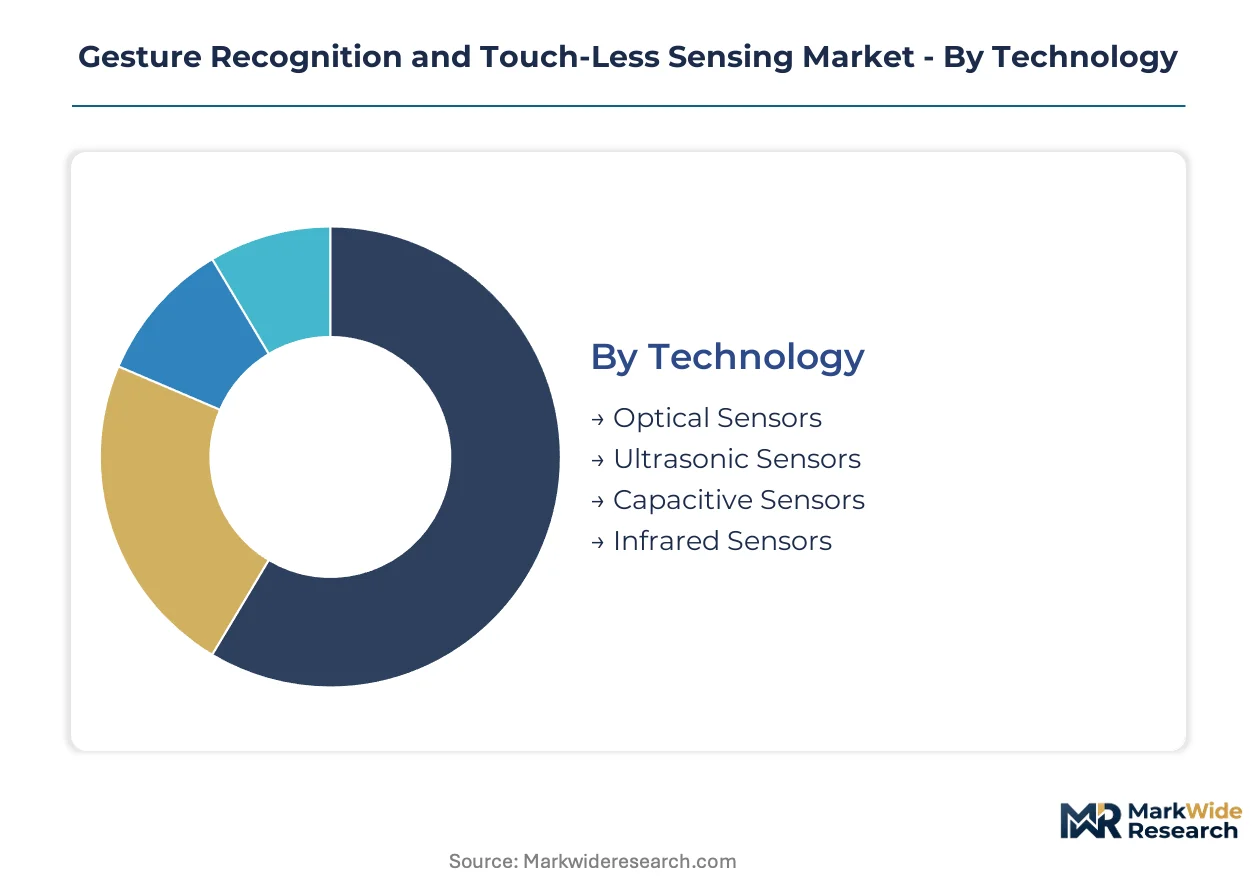
Gesture recognition and touch-less sensing markets fragment across hardware modalities, software licensing models, and vertical deployment contexts. Procurement patterns diverge sharply between volume-driven consumer electronics and compliance-heavy automotive and healthcare verticals.
Technology:
Optical and radar modalities flow through smartphone OEM direct procurement, while capacitive and ultrasonic variants concentrate in automotive Tier-1 supplier channels.
- Optical Sensors:Time-of-flight arrays operating at 940nm wavelength capture depth maps for gesture interpretation. Consumer electronics procurement in China and South Korea drives volume, though EU AI Act compliance costs are compressing margins in European deployments.
- Ultrasonic Sensors:Piezoelectric transducers emit high-frequency pulses to detect hand position and motion through time-of-flight calculation. Automotive interior monitoring in Germany's Stuttgart cluster favors this modality for electromagnetic interference immunity in EV powertrain environments.
- Capacitive Sensors:Field distortion matrices detect proximity and gesture through electrical coupling with conductive objects.
- Infrared Sensors:Thermal emission detection enables low-power presence sensing in battery-constrained devices.
Optical sensors dominate installed base. Ultrasonic variants are where expansion concentrates.
Application:
Cost tiers separate premium automotive deployments from commoditized consumer electronics, with healthcare occupying a mid-tier compliance-intensive position.
- Consumer Electronics:Smartphone, tablet, and wearable integration demands sub-millimeter precision at sub-dollar unit economics. Shenzhen and Seoul-based OEMs specify optical time-of-flight modules for gesture navigation and proximity detection.
- Automotive:Driver-attention monitoring and occupant detection systems require radar-based architectures to satisfy GDPR biometric processing constraints. Germany's KBA mandates are accelerating 60GHz FMCW adoption in Munich and Stuttgart production lines.
- Healthcare:Touch-less patient monitoring and surgical interface sterilization command premium pricing for FDA 510(k) certified systems.
- Smart Home:Gesture-controlled lighting, climate, and entertainment systems deploy lower-precision infrared and capacitive arrays.
Consumer electronics commands unit volume. Healthcare is climbing the fastest.
End User:
Customer type dictates procurement sophistication, with industrial buyers demanding SDK unbundling while retail and entertainment accept integrated hardware-software bundles.
- Industrial:Factory automation and logistics HMI applications in Germany's automotive belt require ISO-certified middleware for legacy PLC integration. Stuttgart-based manufacturers separately contract sensor vendors and algorithm providers to maintain compliance flexibility.
- Retail:Digital signage and self-service kiosk gesture interfaces prioritize cost minimization over precision.
- Education:Interactive whiteboard and presentation systems favor camera-based tracking for multi-user scenarios.
- Entertainment:Gaming and immersive experience deployments consume depth-sensing arrays for spatial interaction.
Industrial end-use dominates contract value. Retail is gaining share fastest.
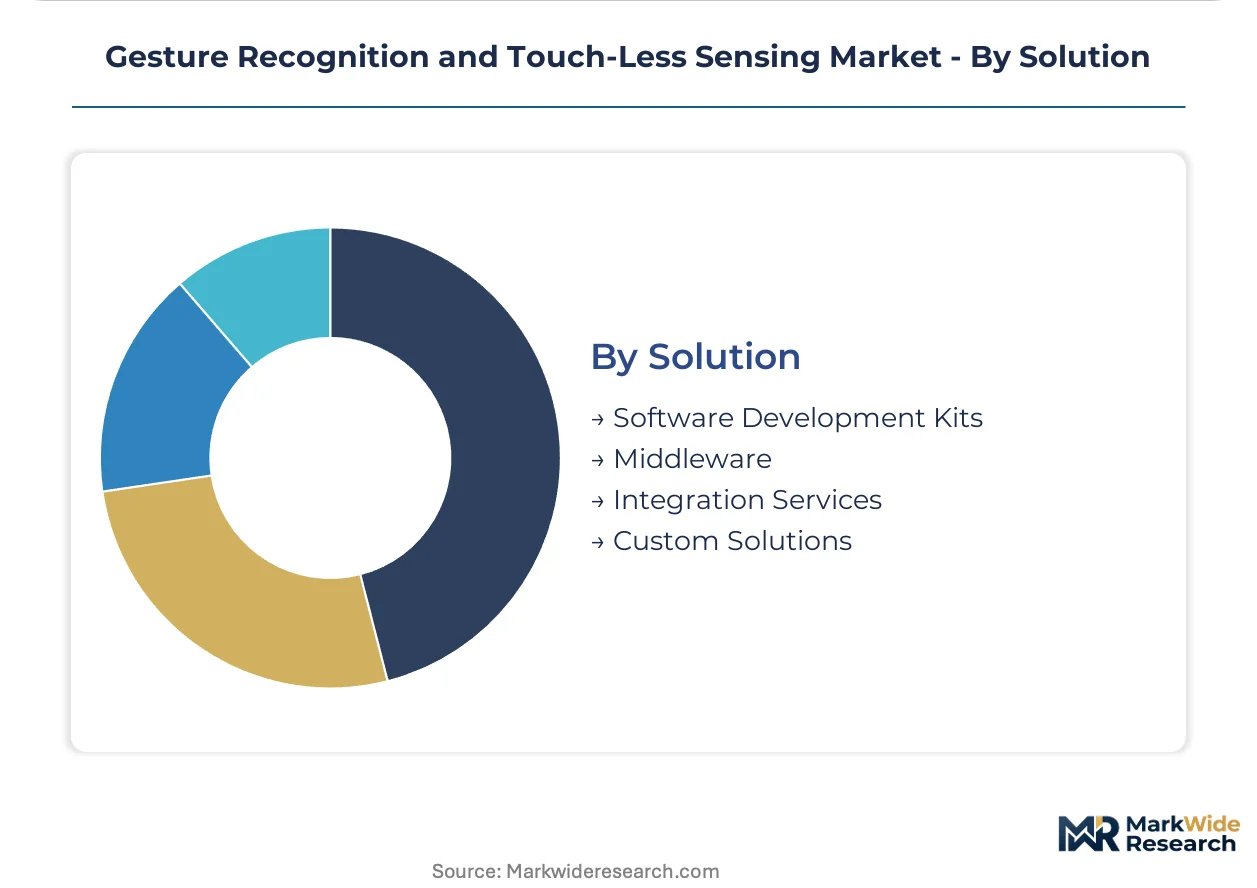
Solution:
Maturity gradients separate established SDK licensing from nascent custom development services, with margin concentration in algorithm IP rather than integration labor.
- Software Development Kits:Pre-trained gesture classification models with API abstraction layers enable rapid deployment across sensor hardware. EU AI Act conformity assessment documentation requirements are forcing SDK providers to maintain algorithm audit trails for European market access.
- Middleware:Protocol translation and legacy system adaptation layers bridge proprietary sensor outputs to standard industrial buses.
- Integration Services:Custom deployment and calibration consulting commands project-based fees.
- Custom Solutions:Bespoke algorithm development for specialized gesture vocabularies or novel sensor fusion architectures.
SDKs dominate recurring revenue. Custom solutions show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act anchors European compliance architecture, forcing biometric system providers to maintain conformity documentation across Germany, France, and neighboring jurisdictions. Procurement teams in automotive and healthcare verticals now prioritize sensor architectures that satisfy divergent regulatory requirements without hardware redesign.
Germany
Automotive OEMs in Munich and Stuttgart drive radar-based interior monitoring adoption to meet KBA mandates for driver-attention systems. The EU AI Act's high-risk classification forces SDK providers to maintain algorithm audit trails for European market access. Bavaria's sensor cluster concentrates 60GHz FMCW development for GDPR-compliant biometric processing without image capture.
United States
FDA 510(k) pathways govern touch-less patient monitoring devices in hospital networks and clinical systems across the country. Healthcare procurement teams unbundle hardware acquisition from algorithm licensing to accelerate modular certification strategies. The Pacific Northwest and Greater Boston anchor computer vision engineering talent pools for edge deployment optimization.
China
NMPA GB standards govern domestic deployment of facial and gesture analytics in public infrastructure and smart city projects. Shenzhen and Beijing-Tianjin-Hebei manufacturing clusters dominate 940nm optical time-of-flight sensor foundry capacity for consumer electronics volume. MIIT directives accelerate smartphone OEM integration of proximity detection and gesture navigation modules.
Japan
METI industrial automation incentives drive touch-less HMI adoption in factory environments and logistics operations. JIS standards certification requirements shape procurement criteria for automotive Tier-1 suppliers serving domestic OEMs. The Chubu region around Nagoya concentrates precision sensor manufacturing for electromagnetic interference-resistant automotive applications.
South Korea
MFDS medical device regulations create compliance pathways for touch-less surgical interface sterilization systems in Seoul hospital networks. The Seoul Capital Area anchors smartphone OEM direct procurement of optical sensor modules at sub-dollar unit economics. Samsung and LG supply chain proximity accelerates silicon-software co-design integration for gesture recognition chipsets.
Gesture Recognition and Touch-Less Sensing Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive semiconductor fabrication capabilities separating firms with end-to-end pipeline control from algorithm-dependent competitors. The upper tier commands premium positioning through silicon-software co-design, while mid-tier players source SDKs independently to maintain compliance flexibility. Three archetypes dominate: captive AI labs with in-house chip design, radar specialists with privacy-preserving architectures, and computer vision houses licensing pre-trained models. Competitive moves concentrate on strategic partnerships for legacy system integration and geographic expansion through pre-certified software modules.
Within the integrated technology tier, Apple Inc. and Microsoft Corporation exemplify divergent strategic positions. Apple leverages Cupertino-based silicon-software co-design to sustain end-to-end gesture pipeline control across device ecosystems. Microsoft anchors enterprise demand through Azure Kinect and HoloLens integration services for industrial clients in North America and Europe. Among semiconductor specialists, Infineon Technologies occupies a position representing radar-based micro-Doppler sensing for automotive interior monitoring, competing against camera-centric rivals with architectures that preserve biometric privacy.
| Leading Market Players |
|---|
| Apple Inc. |
| Microsoft Corporation |
| Microchip Technology Inc. |
| Google LLC |
| Infineon Technologies |
| Intel Corporation |
| Qualcomm Inc. |
| GestureTek |
| Cognitec Systems |
| Others |
Supply Flow & Price Mechanics
Fourteen-week lead times for 940nm time-of-flight sensor modules concentrate pricing power among East Asian foundries, while German automotive OEMs absorb premium logistics costs to secure GDPR-compliant radar alternatives. Inventory buffers at Munich-based Tier-1 suppliers now stretch to ninety days, reflecting single-source vulnerability in optical component supply.
Pricing Analysis
EU-to-Asia price spreads for equivalent 60GHz FMCW radar modules exceed three-to-one, driven by EU AI Act conformity documentation burdens and localized firmware certification. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels dominates procurement contracts. Cost compression in consumer electronics optical sensors intensifies as Shenzhen OEMs consolidate volume commitments. Healthcare systems show least price sensitivity due to FDA 510(k) pathway rigidity, while retail kiosk deployers negotiate aggressively on per-unit hardware.
Supply Chain Analysis
TSMC foundry capacity allocation for 940nm VCSEL arrays constitutes a chokepoint constraining optical sensor availability for European automotive programs. Taiwan, South Korea, and China anchor 940nm optical component manufacturing, while Germany and Japan concentrate 60GHz radar MMIC production. Germanium substrate supply for infrared detectors rests on Chinese refining capacity. Single-source vulnerability in VCSEL epitaxy equipment threatens capacity expansion timelines. Distribution runs through automotive Tier-1 supplier consignment models and direct OEM procurement for consumer electronics volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SDK licensing revenue is expanding faster than hardware shipments as German industrial buyers unbundle algorithm procurement from sensor acquisition. Recurring compliance-documentation subscriptions now attach to three-quarters of European healthcare deployments.
For Market Incumbents: Consolidate radar IP portfolios through targeted acquisition of micro-Doppler processing specialists in Munich and Stuttgart clusters. Infineon Technologies' captive fab model demonstrates defensible positioning against camera-centric rivals. Vertical integration into 60GHz MMIC design reduces exposure to automotive Tier-1 supplier margin extraction. Prioritize EU AI Act audit-trail infrastructure as a compliance moat. For New Entrants and Emerging Players: FDA 510(k) modular certification fast-tracks enable hospital network entry without integrated system approval burdens. Underpenetrated industrial automation in Stuttgart logistics hubs offers white-space opportunity with lower competitive density than automotive interior monitoring. Target German automotive belt assembly line HMI retrofits with ISO-certified middleware partnerships. Lead with SDK-first positioning to bypass capital-intensive sensor manufacturing. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pure-play algorithm licensing as hardware-software decoupling accelerates. Five-to-ten year viability favors firms with captive compliance infrastructure and recurring SDK revenue streams. Acquisition target archetype: computer vision specialists with EU AI Act documentation capabilities and hospital network relationships. Monitor 940nm foundry capacity utilization as inflection signal for optical sensor pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Software Co-Design Investment | Apple's captive chip design sustains end-to-end gesture pipeline control across device ecosystems. |
| EU AI Act Compliance Infrastructure | SDK providers with algorithm audit trails capture German automotive and healthcare procurement mandates. |
| Radar-Capacitive Hybrid Architecture | 60GHz FMCW convergence penetrates medical device manufacturing for electromagnetic resilience. |
| SDK Unbundling from Hardware | Recurring licensing revenue streams open for computer vision specialists serving industrial clients. |
| Automotive Interior Monitoring Certification | Germany's KBA mandates accelerate radar-based occupant detection adoption in passenger vehicles. |
Methodological Framework
The analysis maps optical sensor, radar, capacitive, and ultrasonic modality sub-sectors, each validated through semiconductor procurement executives, automotive Tier-1 supplier engineering leads, hospital biomedical device managers, and industrial automation integrators. Primary interview intelligence triangulates against FDA 510(k) filings, EU AI Act conformity assessment databases, German KBA regulatory notices, and NMPA GB standard publications. Bottom-up sensor shipment aggregation cross-checks with top-down OEM procurement spend estimates.
Consistency checks validated volume and value outputs against automotive production database benchmarks and healthcare capital equipment procurement records across the projection horizon. Segmentation dimensions modeled include sensor modality, software licensing model, vertical deployment context, and regional regulatory cluster. CAGRs derive from installed base evolution and replacement cycle analysis. Forecast inputs incorporate EU AI Act implementation timelines and German automotive safety mandate phase-ins.
Decision-makers should treat outputs as directional under sustained semiconductor foundry capacity constraints and stable regulatory enforcement intensity; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act biometric classification interpretations and NMPA GB standard revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
Sensor Based Sorting System Market
Sensors and Controls
Steam Trap Monitor Market
Sensors and Controls
Europe Optical Sensors Market
Sensors and Controls
TMAH Concentration Monitor Market
Sensors and Controls
Global Sensors and Actuators Market
Sensors and Controls
Bioacoustics Sensing Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
Touchless Sensing Market
Sensors and Controls
Asia-Pacific Bulk Acoustic Wave Sensors Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
Portable Air Purifier Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Global Temperature Sensors Market