
 MEMS for Mobile Devices Market | 2026-2036
MEMS for Mobile Devices Market Size, Share, and Industry Trends Forecast 2026-2036
MEMS for Mobile Devices Market Foresight
Asian foundry capacity is shifting toward 200mm and 300mm MEMS-dedicated lines to serve mobile sensor demand. Bosch Sensortec leverages in-house wafer fabrication to sustain cost leadership in accelerometers and gyroscopes. STMicroelectronics anchors European supply through its Catania, Italy facility while competing aggressively in Asian distribution channels.
MEMS for mobile devices are microelectromechanical systems fabricated using semiconductor processes, typically integrating mechanical elements, sensors, actuators, and electronics on silicon substrates with feature sizes ranging from micrometers to millimeters. These devices transduce physical phenomena—acceleration, rotation, pressure, or acoustic waves—into electrical signals for real-time processing within mobile computing platforms. Accelerometers and gyroscopes dominate unit volumes across smartphones and wearables, while pressure sensors command premium positioning in environmental monitoring and altitude-tracking applications. Silicon-based fabrication retains the largest share of wafer starts, though piezoelectric variants gain traction in microphone and haptic feedback segments where power efficiency and signal fidelity matter most.
FDA oversight applies where MEMS sensors interface with mobile health diagnostics, while FCC certification governs radio-frequency emissions from integrated wireless sensor hubs. EPA guidelines on semiconductor manufacturing chemicals shape foundry compliance costs and process chemistry choices. Stakeholders must monitor how evolving power-efficiency mandates from Asian regulators and European REACH substance restrictions alter material selection timelines and foundry qualification cycles.
Market Dynamics
China's MIIT power-efficiency mandates are compressing design cycles for silicon-based MEMS architectures, forcing foundries to requalify process chemistries and OEMs to consolidate sensor suppliers across flagship and mid-tier portfolios.
Growth Catalysts
- MIIT Subsystem Benchmarks:China's tightened power-efficiency standards for mobile subsystems accelerate migration toward silicon-based MEMS architectures, pulling demand through East Asian foundry networks.
- Accelerometer Integration:Smartphone OEMs are embedding motion sensors deeper into mid-tier device portfolios, expanding addressable unit volumes beyond flagship segments.
- 200mm Wafer Transition:Foundry capacity shifts toward MEMS-dedicated 200mm and 300mm lines in South Korea and Taiwan, lowering die costs for high-volume sensor categories.
Market Restraints
- Specialized Equipment Concentration:Deep reactive-ion etching and wafer-bonding equipment suppliers cluster in Germany and Japan, creating single-source vulnerability for new foundry entrants.
- Piezoelectric Material Costs:Scandium-doped aluminum nitride and PZT thin-film feedstocks face price volatility tied to rare earth processing constraints in Chinese refining corridors.
- REACH Substance Restrictions:European ECHA substance restrictions on semiconductor manufacturing chemistries extend foundry qualification timelines by 12-18 months for European-bound production.
Strategic Opportunities
- India PLI Scheme:India's production-linked incentive scheme for electronics manufacturing creates tariff-advantaged assembly capacity for MEMS-integrated mobile devices serving South Asian markets.
- Health Diagnostic Convergence:FDA-cleared mobile health interfaces using MEMS pressure and inertial sensors open reimbursement-adjacent revenue streams beyond consumer hardware.
- Environmental Sensing Bundling:Barometric pressure sensors combined with gas-sensing MEMS in wearables address altitude-tracking and air-quality monitoring use cases in outdoor recreation verticals.
Industry Challenges
- Multi-Physics Simulation Talent:The scarcity of engineers proficient in coupled electromechanical-thermal finite-element analysis constrains design velocity for fabless MEMS startups.
- FCC Certification Timelines:Radio-frequency emissions testing for wireless sensor hubs faces backlog at accredited test laboratories, delaying product launches by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MEMS for Mobile Devices Market |
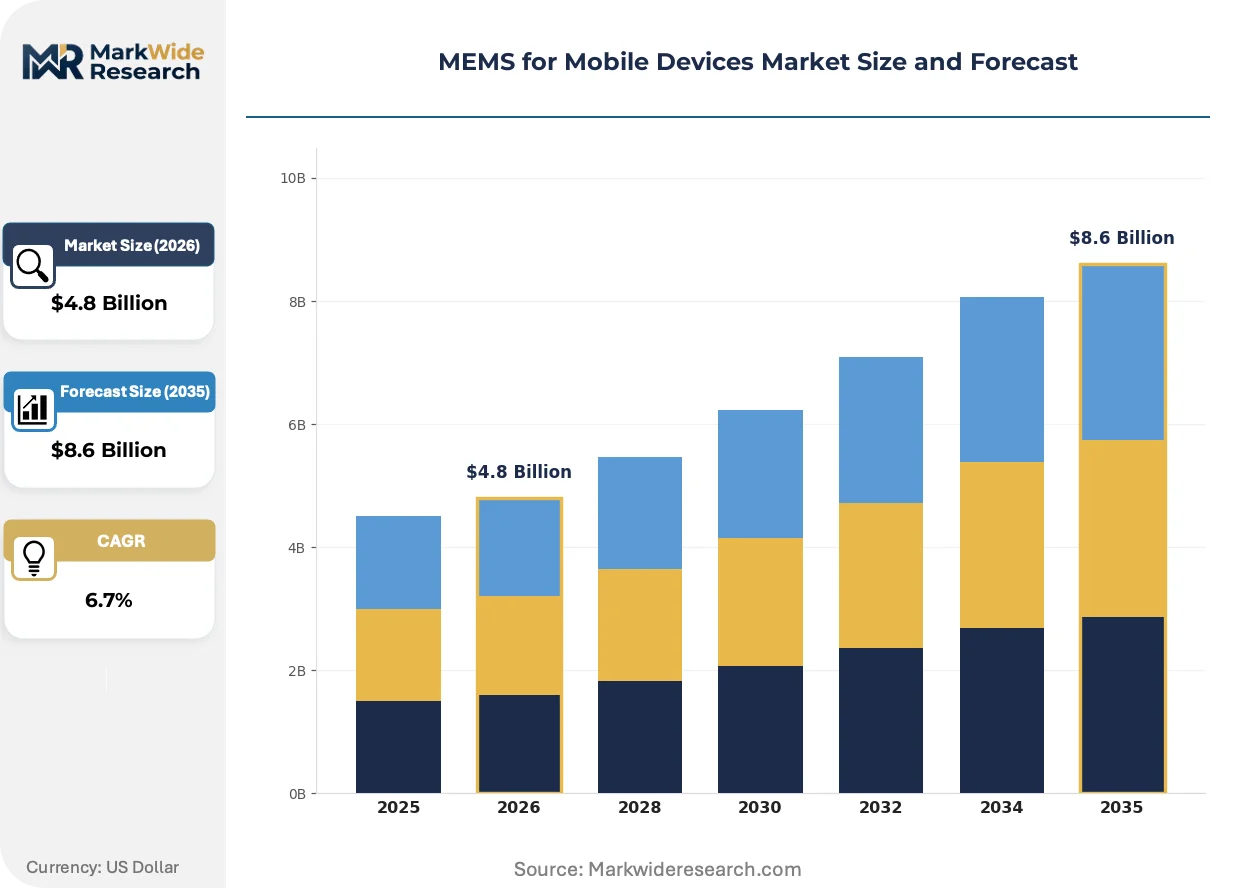
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometers, Gyroscopes, Pressure Sensors, Microphones Technology: Silicon-Based, Polymer-Based, Bulk Acoustic Wave, Piezoelectric End User: Smartphones, Tablets, Wearable Devices, Laptops Application: Navigation, Motion Control, Environmental Monitoring, Gaming |
| Companies Covered | TDK InvenSense, Goertek, Analog Devices, Texas Instruments, NXP Semiconductors, Bosch Sensortec, Knowles Corporation, Murata Manufacturing, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MEMS for Mobile Devices Market Shifts & Advancements
Sensor fusion algorithms and edge-AI integration are redefining how raw MEMS data streams convert into actionable context, compressing the value chain between silicon foundries and OEM software stacks.
Capacitive micromachined ultrasonic transducers (CMUTs) are automating spatial audio beamforming and proximity detection in flagship smartphones. Apple and Samsung flagship programs have adopted CMUT arrays for selective audio pickup, displacing conventional MEMS microphones in high-end configurations. This transition is automating the consolidation of acoustic and gesture-sensing functions onto single-die architectures, reducing bill-of-materials complexity for tier-one OEMs.
REACH substance restrictions under ECHA oversight are forcing foundries to substitute hexavalent chromium passivation layers with trivalent alternatives in etching processes. The industrial consequence extends qualification cycles for European-bound production and elevates process control requirements at Catania and Singapore facilities. STMicroelectronics and Bosch Sensortec are responding by dual-qualifying process flows to maintain CE-marked product availability without supply interruption.
Smartphone OEMs are unbundling sensor calibration and algorithm licensing from hardware procurement, shifting toward per-unit royalty models for motion-processing software stacks. This disrupts traditional component distribution through Asian electronics markets, replacing spot-market purchasing with direct foundry-to-OEM contracts. The pattern is most visible in Shenzhen and Taipei procurement corridors, where Mediatek and Qualcomm reference designs specify pre-certified sensor modules with bundled firmware licenses.
MEMS for Mobile Devices Market Segmentation
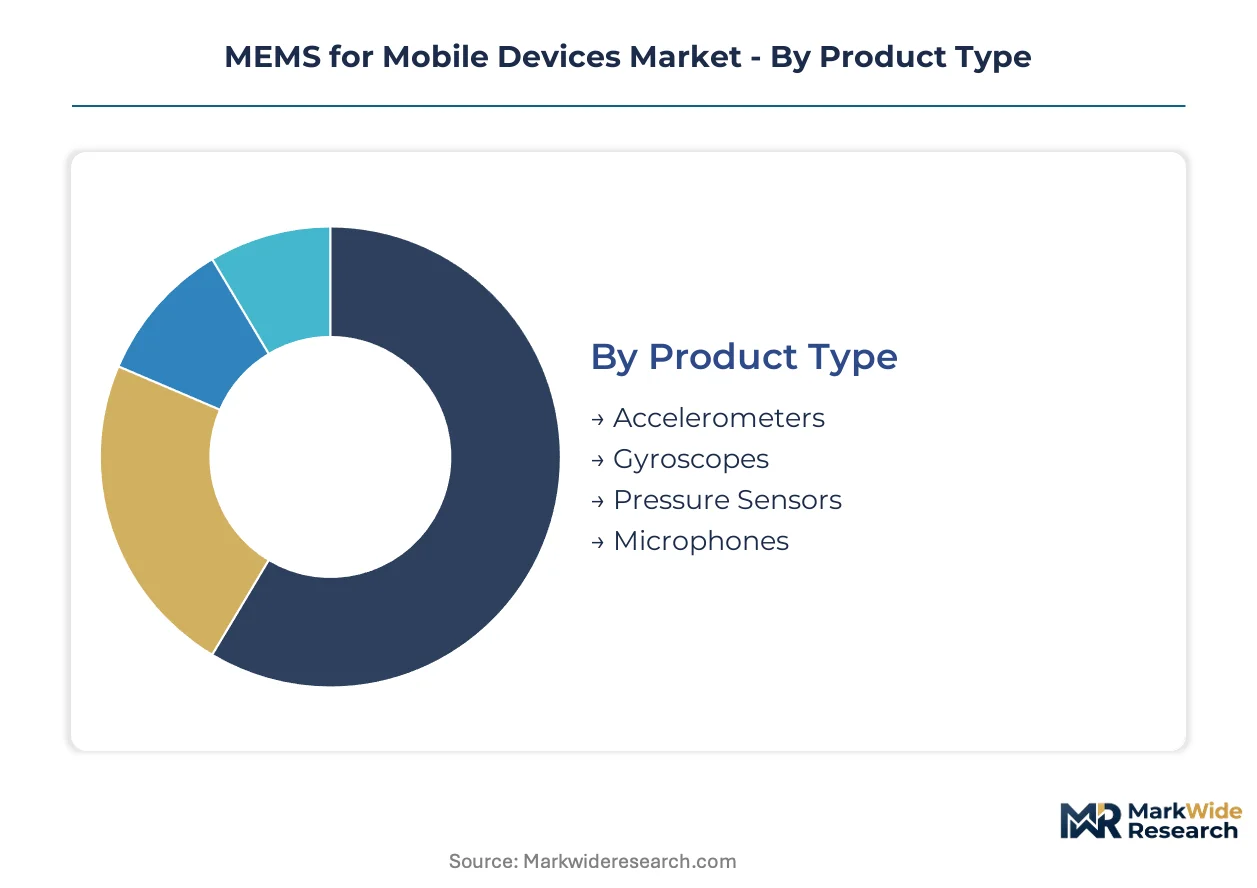
MEMS segmentation for mobile devices reflects divergent capital requirements across fabrication technologies and end-use specifications. Foundry investment intensity varies by sensor physics, die size, and packaging complexity, creating tiered barriers to entry that reshape competitive positioning across product categories.
Product Type:
Accelerometers and gyroscopes demand the heaviest upfront capital for inertial-grade calibration infrastructure and six-axis fusion testing, while microphones and pressure sensors operate on leaner qualification cycles.
- Accelerometers:Capacitive sensing structures fabricated on 200mm silicon wafers with dedicated test handlers for g-force linearity verification. Demand concentrates in Shenzhen and Taipei procurement corridors where Mediatek and Qualcomm reference designs specify pre-certified modules with bundled firmware licenses.
- Gyroscopes:Vibrating mass structures requiring vacuum encapsulation and Coriolis-force compensation algorithms. Samsung and Apple flagship programs anchor volume in South Korean and Taiwanese foundry networks, with MIIT power-efficiency mandates accelerating silicon-based architecture migration.
- Pressure Sensors:Piezoresistive diaphragms for altitude and barometric tracking, gaining traction in outdoor recreation wearables.
- Microphones:Capacitive and piezoelectric acoustic transducers, with CMUT arrays displacing conventional MEMS in high-end smartphone configurations.
Most installed capacity flows through accelerometers. Expansion is steepest in pressure sensors.
Technology:
Cost tier stratification separates mature silicon processes from emerging piezoelectric variants requiring exotic material feedstocks and specialized deposition equipment.
- Silicon-Based:Standard CMOS-compatible surface micromachining with DRIE etching and wafer-level bonding. Bosch Sensortec and STMicroelectronics anchor supply through captive foundries in Germany and Italy, with Asian expansion into South Korea and Taiwan.
- Piezoelectric:Scandium-doped aluminum nitride and PZT thin-film deposition for haptic feedback and high-fidelity microphones. Rare earth processing constraints in Chinese refining corridors create feedstock price volatility that constrains scaling.
- Bulk Acoustic Wave:Quartz and lithium niobate resonators for timing and filtering applications in wireless sensor hubs.
- Polymer-Based:Flexible substrate alternatives for conformal wearable integration, operating at lower thermal budgets.
Silicon-based processes retain the dominant share of wafer starts. Piezoelectric variants are climbing the fastest as power efficiency and signal fidelity requirements intensify.
End User:
Volume concentration varies sharply by device category, with smartphones absorbing the majority of high-precision inertial sensor output while wearables drive miniaturization roadmaps.
- Smartphones:Primary demand sink for six-axis inertial measurement units, barometric pressure sensors, and acoustic arrays. China's MIIT mandates compress design cycles and consolidate supplier relationships across flagship and mid-tier portfolios.
- Wearable Devices:Ultra-low-power specifications driving sensor fusion integration and environmental sensing bundling for altitude and air-quality monitoring.
- Tablets:Secondary motion-sensing demand with relaxed power constraints compared to smartphones.
- Laptops:Niche accelerometer adoption for drop protection and screen orientation.
Smartphone OEM procurement represents the largest revenue pool. Wearable devices are gaining share fastest on unit expansion and sensor count per device.
Application:
Margin structure diverges between commodity motion processing and regulated health-adjacent use cases requiring FDA-cleared interfaces.
- Navigation:GPS-denied positioning through inertial dead reckoning, with sensor fusion algorithms compressing value chain margins between foundries and OEM software stacks.
- Environmental Monitoring:Barometric and gas-sensing combinations for altitude tracking and air-quality alerts, opening outdoor recreation verticals.
- Motion Control:Gesture recognition and image stabilization, now standard across mid-tier smartphone portfolios.
- Gaming:Haptic feedback and controller motion sensing, absorbing lower-precision accelerometer supply.
Navigation applications command the deepest foundry relationships. Environmental monitoring is expanding most quickly on wearable integration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping MEMS fabrication geography, as power-efficiency mandates in China and substance restrictions in Europe create divergent compliance costs that push mobile sensor production toward East Asian foundry clusters with integrated supply chains.
China
MIIT power-efficiency benchmarks for mobile subsystems are compressing design cycles and consolidating supplier relationships across Shenzhen and Dongguan manufacturing corridors. The country's dual carbon goals are accelerating silicon-based MEMS migration while tightening rare earth processing oversight. Yangtze River Delta foundries in Shanghai and Suzhou are expanding 200mm MEMS-dedicated capacity to serve domestic smartphone OEM procurement.
South Korea
Samsung Electronics flagship programs anchor gyroscope and accelerometer demand through captive foundry relationships in Suwon and Pyeongtaek. The country's national semiconductor strategy channels R&D subsidies toward sensor fusion integration. Busan-Ulsan industrial clusters are attracting foreign MEMS equipment vendors to localize deep reactive-ion etching supply chains.
Taiwan
Mediatek reference designs specify pre-certified sensor modules with bundled firmware licenses, pulling procurement through Taipei and Hsinchu distribution channels. The island's semiconductor equipment import regulations favor established foundry incumbents. Tainan Science Park facilities are qualifying 300mm MEMS lines to capture die-cost advantages in high-volume microphone production.
United States
FDA oversight of mobile health diagnostic interfaces creates reimbursement-adjacent revenue streams for pressure and inertial sensor developers. FCC certification backlogs for wireless sensor hubs are extending product launch timelines. California and Texas design centers are specializing in edge-AI sensor fusion algorithms that compress value chain margins between foundries and OEM software stacks.
Germany
ECHA REACH substance restrictions on hexavalent chromium passivation are extending foundry qualification cycles for European-bound production. The country's automotive sensor heritage feeds engineering talent into mobile MEMS design. Bavarian and Baden-Württemberg industrial regions host specialized equipment suppliers for wafer-bonding and etching processes that serve Asian foundry expansion.
MEMS for Mobile Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue piezoelectric specialization and health-diagnostic convergence. The market structures around three archetypes: captive foundry operators with in-house wafer fabrication, fabless design houses licensing algorithm stacks, and diversified component conglomerates bundling sensors with wireless hubs. Consolidation pressures are intensifying as smartphone OEMs reduce qualified vendor lists, while strategic partnerships between foundries and algorithm licensors are replacing spot-market procurement.
Among diversified European fabricators, STMicroelectronics and Bosch Sensortec exemplify the captive-foundry archetype through continental manufacturing presence and Asian distribution expansion. TDK InvenSense represents the fabless-alternative model, anchoring motion-sensor design without wafer-level capital intensity. These three occupy positions that reflect divergent bets on vertical integration depth versus design agility.
| Leading Market Players |
|---|
| TDK InvenSense |
| Goertek |
| Analog Devices |
| Texas Instruments |
| NXP Semiconductors |
| Bosch Sensortec |
| Knowles Corporation |
| Murata Manufacturing |
| STMicroelectronics |
| Others |
Supply & Pricing Matrix
Flagship smartphone OEM procurement consolidation across Shenzhen and Taipei corridors anchors contract-based long-term offtake as the dominant pricing model, compressing spot-market premiums and forcing tier-two suppliers toward direct foundry negotiations.
Pricing Analysis
Distributor margins in Asian electronics markets have collapsed under direct foundry-to-OEM contracting, with pricing stratifying across premium, standard, and economy tiers based on calibration grade and bundled firmware licensing. Price differentiation hinges on ISO-certified process flows and MIIT power-efficiency compliance tiers. Cost compression in mid-tier accelerometers is intensifying because 200mm wafer capacity expansion in Taiwan and South Korea feeds die-cost deflation. Mid-tier smartphone OEMs exhibit highest price sensitivity, while Apple and Samsung flagship programs absorb premium positioning for six-axis fusion modules.
Supply Chain Analysis
Freight costs from German and Japanese equipment vendors to East Asian foundry clusters add 8-12% landed cost premiums for deep reactive-ion etching and wafer-bonding systems. Supply concentrates in Taiwan, South Korea, and mainland China, with Yangtze River Delta and Busan-Ulsan corridors feeding 200mm MEMS-dedicated lines. Raw material dependencies center on silicon wafers, scandium-doped aluminum nitride feedstocks, and specialized photoresists. Single-source vulnerability for etching equipment creates supply chain risk. Distribution runs through Mediatek and Qualcomm reference design channels specifying pre-certified sensor modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS for mobile devices offers margin-expansion potential as silicon-based process maturity drives die-cost deflation and health-diagnostic convergence unlocks premium-tier pricing for FDA-cleared interfaces.
For Market Incumbents: Extend captive foundry utilization into 300mm MEMS-dedicated lines to capture scale economies against fabless competitors threatening commoditized accelerometer segments. Deepen algorithm licensing partnerships with Mediatek and Qualcomm to lock reference design slots before Shenzhen procurement corridors consolidate further. Defensive patent positioning around Coriolis-force compensation and vacuum encapsulation processes protects gyroscope margins from emerging piezoelectric entrants. For New Entrants and Emerging Players: Shenzhen-based ODMs present the most penetrable channel partner type for unbundled sensor calibration services, bypassing hardware procurement barriers through per-unit royalty models. Target India's PLI-scheme electronics manufacturing clusters for tariff-advantaged assembly partnerships serving South Asian smartphone demand. White-space exists in environmental sensing bundling for wearable outdoor recreation verticals, with barometric-gas sensor combinations underserved by established incumbents. For Investors and Strategic Acquirers: Smartphone OEM sensor divisions are the most active acquirer in this space, seeking captive supply security amid foundry capacity constraints. Long-term viability favors fabless design houses with algorithm-software stacks over capital-intensive wafer fabrication plays. Acquisition target archetype: motion-sensor specialists with FDA-cleared health interfaces and existing Mediatek reference design certification. Watch for MIIT power-efficiency mandate tightening as inflection indicator accelerating silicon-based architecture migration and supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| 200mm to 300mm MEMS Line Transition | Die-cost reduction in Taiwan and South Korea foundries reshapes competitive economics for high-volume accelerometer categories. |
| Direct Foundry-to-OEM Contracting | Shenzhen and Taipei procurement corridors bypass distributor layers, compressing channel margins and locking volume commitments. |
| Sensor Fusion Algorithm Licensing | Per-unit royalty models replace hardware spot purchasing, shifting value capture toward software stacks in Mediatek reference designs. |
| FDA-Cleared Health Interface Development | Reimbursement-adjacent revenue streams open beyond consumer hardware for pressure and inertial sensor developers. |
| Piezoelectric Material Feedstock Security | Scandium-doped aluminum nitride sourcing from Chinese refining corridors requires dual-qualification to mitigate rare earth price volatility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with MEMS foundry operations managers, smartphone OEM procurement directors, sensor module test engineers, and reference design platform architects with secondary validation against SEC semiconductor filings, MIIT regulatory bulletins, and Yangtze River Delta industrial park capacity disclosures. Bottom-up wafer-start estimates and top-down OEM bill-of-materials analysis were triangulated for segmentation sizing.
Historical reference periods anchored the forecast window to pre-pandemic baseline capacity utilization and post-MIIT mandate implementation trajectories across the projection horizon. The analytical framework modeled product type, technology node, end-user device category, and application use case dimensions. CAGRs were derived from foundry capacity expansion schedules, OEM sensor count per device roadmaps, and power-efficiency regulatory compliance timelines. Industry-specific inputs included DRIE equipment lead times and scandium feedstock price indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance restriction enforcement, rare earth export licensing shifts, and FCC certification backlog resolution. Forecasts reflect assumptions around continued silicon-based architecture dominance and stable East Asian foundry network access. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Yaw Rate Sensors Market
Sensors and Controls
Digital Radiography Sensor Market
Sensors and Controls
Europe Sensors Market
Sensors and Controls
APAC Nano Sensors Market
Sensors and Controls
Mexico Pressure Sensor Market
Sensors and Controls
Electronic Sentry Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Global PH Sensor Market
Sensors and Controls
Latin America Occupancy Sensors Market
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
Smart Parking Sensor Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
Spain Digital Thermometer Market
Sensors and Controls
Odor Sensor Market
Sensors and Controls
Global Accelerometers Market
Sensors and Controls
Chemical Sensors Market