
 South Korea Construction Market | 2026-2036
South Korea Construction Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Construction Market Outlook
Market Context with Strategic Players
Premium design-build contracts for semiconductor fabs and data centers is decoupling from commodity residential construction in pricing power and margin structure. Hyundai Engineering & Construction leverages its integrated EPC capabilities to dominate complex industrial projects nationwide. Samsung C&T Corporation anchors the premium tier through technology-intensive infrastructure delivery. GS Engineering & Construction differentiates via modular construction expertise in urban residential towers.
Technical Definition and Structural Segments
South Korea construction encompasses the planning, engineering, and assembly of built structures using reinforced concrete with specified compressive strengths exceeding 24 MPa, structural steel conforming to KS D 3503 standards, and advanced curtain wall systems designed for seismic resistance up to magnitude 6.5. The primary purpose spans housing provision, commercial facility creation, industrial plant erection, and public infrastructure maintenance to support national economic output. Residential project types remain structurally dominant by volume but carry compressed margins, while industrial project types capture expanding margin pools driven by semiconductor and battery factory investments. Sustainable construction methods represent the fastest-growing segment as government procurement rules tighten embodied carbon thresholds.
Regulatory Frame and Forward-Looking Close
The Ministry of Land, Infrastructure and Transport enforces building energy codes that mandate zero-energy standards for public structures, while the Korea Agency for Infrastructure Technology Advancement certifies new construction technologies for market access. MFDS oversight intersects where pharmaceutical and biotech facilities require specialized cleanroom construction protocols. Stakeholders must monitor whether tightening green certification timelines will exclude smaller contractors from public bidding eligibility.
Market Dynamics
Zero-energy building mandates from the Ministry of Land, Infrastructure and Transport are compressing project timelines and forcing contractors to retool procurement networks around low-carbon materials.
Growth Catalysts
- Semiconductor Fab Construction:Samsung and SK Hynix expansion programs are pulling specialized EPC capacity into Gyeonggi Province. Cleanroom-grade concrete and vibration-isolated foundations command premium pricing tiers.
- Korea Agency for Infrastructure Technology Advancement Certification:Fast-track approval for modular building systems accelerates high-rise residential delivery in Seoul. Prefabricated bathroom pods and unitized curtain walls reduce on-site labor dependence.
- Data Center Power Density Requirements:Hyperscale cloud operators are specifying liquid cooling infrastructure and reinforced floor loading above 15 kN/m². This specialized demand segment escapes commodity pricing pressure.
Market Restraints
- Structural Steel Import Dependence:KS D 3503 certified sections rely heavily on Chinese and Japanese mill supply. Geopolitical friction and shipping volatility create input cost instability.
- Skilled Welder Shortage:Certified structural steel welders for seismic-grade connections number fewer than 12,000 nationwide. This bottleneck extends industrial project timelines by 15-20%.
- Green Cement Supply Constraints:Low-clinker alternatives meeting Ministry of Environment carbon intensity thresholds face limited domestic production capacity. Specifiers must accept imported supplementary cementitious materials.
Strategic Opportunities
- Busan Smart Port Infrastructure:Automated container terminal expansion requires specialized marine construction and underground logistics tunnels. Foreign EPC partnerships can access this procurement pipeline.
- Jeju Island Renewable Energy Islands:Offshore wind foundation construction and subsea cable landing stations present untapped marine civil engineering demand.
- Building-Integrated Photovoltaics Mandate:Revised national building codes will require BIPV-ready curtain wall specifications for commercial structures above 10,000 m².
Industry Challenges
- MFDS Cleanroom Validation Protocols:Pharmaceutical facility construction requires documented particle count performance before handover. Commissioning timelines extend 6-8 months beyond structural completion.
- Legacy BIM System Interoperability:Smaller subcontractors lack capability to exchange native model data with prime contractors' Autodesk Construction Cloud platforms. Manual translation errors propagate through quantity takeoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Construction Market |
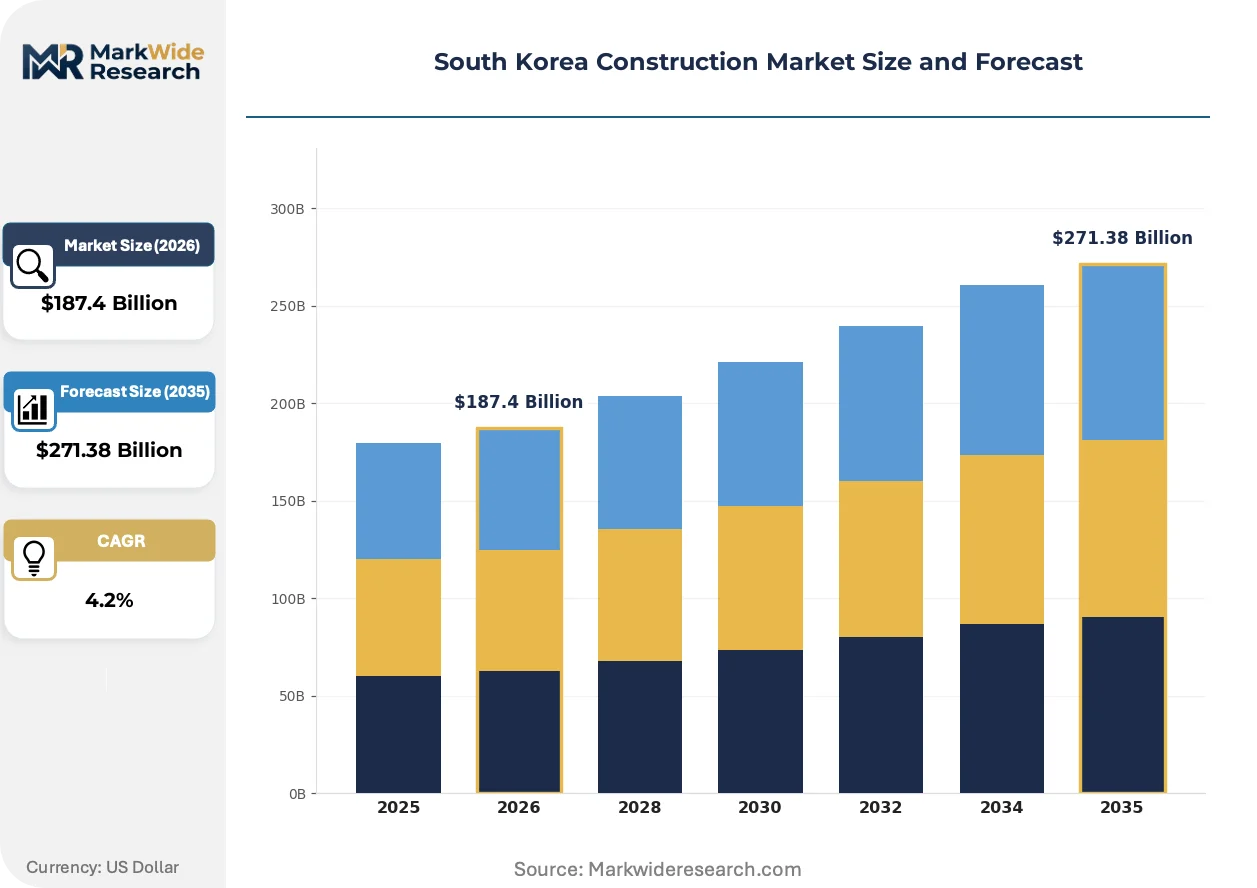
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $271.38 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Industrial, Infrastructure Building Material: Cement, Steel, Wood, Glass Construction Method: Traditional, Modular, Prefabricated, Sustainable End User: Developers, Contractors, Government, Private Sector |
| Companies Covered | Daewoo Engineering & Construction, Daelim Industrial, Samsung C&T Corporation, Movements Inc., Samsung E&A, Hyundai Engineering & Construction, POSCO Engineering & Construction, SLZ Inc., GS Engineering & Construction, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Construction Market Strategic Shifts
Digital fabrication and regulatory carbon accounting are converging to reshape how South Korean contractors bid, source, and deliver projects. Material traceability and assembly speed now determine competitive viability.
Prefabricated reinforced concrete floor cassettes with embedded MEP routing are modularizing mid-rise residential construction in the Seoul Capital Area. GS Engineering & Construction and Lotte E&C have adopted automated rebar welding for these systems. Factory-controlled curing environments reduce weather delays and compress structural cycles from 14 days to 9 days per floor.
The Ministry of Land, Infrastructure and Transport's 2030 Zero Energy Building Roadmap mandates net-zero operational carbon for all new public structures above 3,000 m². This regulation forces design-phase energy modeling using certified simulation software. Contractors must now guarantee performance outcomes rather than specify equipment alone, shifting risk allocation in design-build contracts.
Public procurement through the Korea On-Line E-Procurement System is consolidating buyer power for standard building materials. Municipal housing corporations aggregate demand for windows, insulation, and HVAC equipment across multiple projects. This concentration pressures distributors to absorb logistics costs and offer extended payment terms, squeezing working capital for smaller material suppliers serving the residential segment.
South Korea Construction Market Segmentation
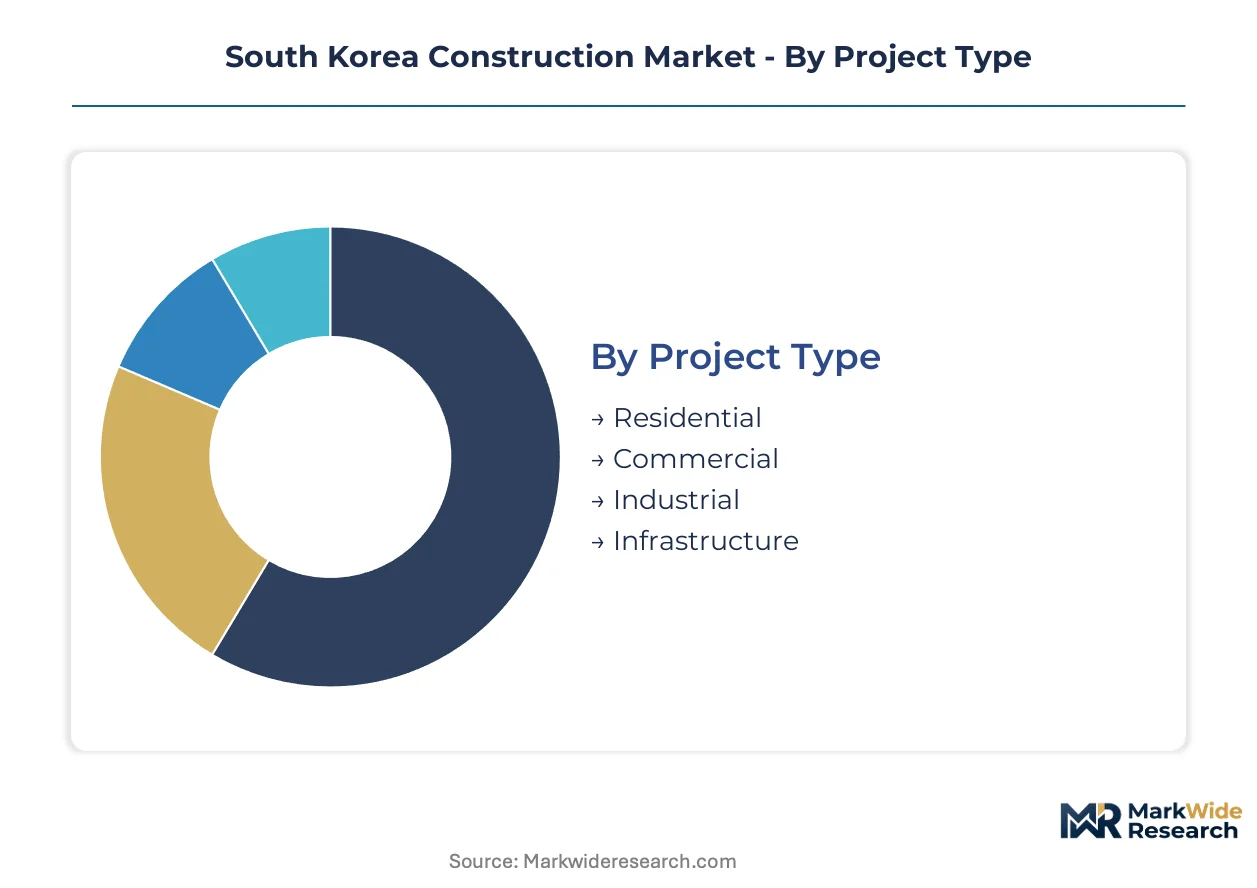
Construction project economics in South Korea diverge sharply across segment boundaries. Certification requirements from the Ministry of Land, Infrastructure and Transport and the Korea Agency for Infrastructure Technology Advancement create tiered compliance burdens that reshape contractor bidding strategies and margin profiles.
Project Type:
Zero-energy building mandates apply differentially across project categories, with public infrastructure facing the strictest operational carbon thresholds and residential construction subject to phased implementation timelines.
- Residential:High-rise apartment towers dominate volume in the Seoul Capital Area and Busan metropolitan zone. Compressed margins persist due to standardized designs and municipal housing corporation procurement concentration, though modular methods are clawing back schedule premiums.
- Commercial:Office and retail developments in Gangnam and Yeouido financial districts specify advanced curtain wall systems with BIPV integration. These projects carry extended commissioning cycles for energy performance validation under tightened building codes.
- Industrial:Semiconductor fabs and battery plants in Gyeonggi Province and Ulsan command specialized EPC capabilities. Cleanroom-grade concrete and vibration-isolated foundations require Korea Agency for Infrastructure Technology Advancement certification for structural systems.
- Infrastructure:Public transit extensions and port modernization in Busan and Incheon operate under government procurement rules with embodied carbon thresholds. Extended payment terms and performance bonding requirements filter contractor eligibility.
Leading the category by volume: Residential. Expanding most quickly: Industrial.
Building Material:
Material specification trends track the divergence between commodity residential supply and premium industrial performance requirements, with import dependence creating divergent cost volatility profiles.
- Cement:Low-clinker alternatives meeting Ministry of Environment carbon intensity thresholds face constrained domestic production. Specifiers on public projects must source imported supplementary cementitious materials, extending lead times and compressing working capital cycles for contractors.
- Steel:KS D 3503 certified structural sections anchor seismic-grade connections for high-rise and industrial applications. Heavy reliance on Chinese and Japanese mill supply exposes project budgets to geopolitical friction and shipping rate volatility.
- Wood:Cross-laminated timber gains traction in low-rise commercial and institutional projects seeking biogenic carbon accounting advantages. Domestic supply chains remain underdeveloped, limiting penetration outside demonstration projects.
- Glass:Unitized curtain wall systems with integrated photovoltaics serve commercial developments above 10,000 square meters facing revised national building codes. Korean fabricators compete with Chinese imports on cost while differentiating on seismic performance testing.
Steel dominates by installed value. Glass is climbing the fastest as BIPV mandates expand.
Construction Method:
Method selection determines labor exposure, schedule risk allocation, and eligibility for fast-track certification pathways under national technology advancement programs.
- Traditional:Cast-in-place reinforced concrete with on-site rebar assembly persists in mid-rise residential and infrastructure segments. Weather exposure and skilled labor dependence extend project timelines relative to factory-controlled alternatives.
- Modular:Prefabricated bathroom pods and unitized facade systems reduce on-site labor requirements for Seoul high-rise towers. Korea Agency for Infrastructure Technology Advancement fast-track approval accelerates permitting for certified systems.
- Prefabricated:Reinforced concrete floor cassettes with embedded MEP routing compress structural cycles from 14 days to 9 days per floor. GS Engineering & Construction and Lotte E&C have deployed automated rebar welding for these systems in the capital region.
- Sustainable:Zero-energy construction methods integrate passive design, high-performance envelopes, and renewable generation to meet Ministry of Land, Infrastructure and Transport public building mandates. Performance guarantees now shift risk to contractors beyond equipment specification alone.
Traditional methods still lead by project count. Sustainable approaches are gaining share fastest under regulatory pressure.
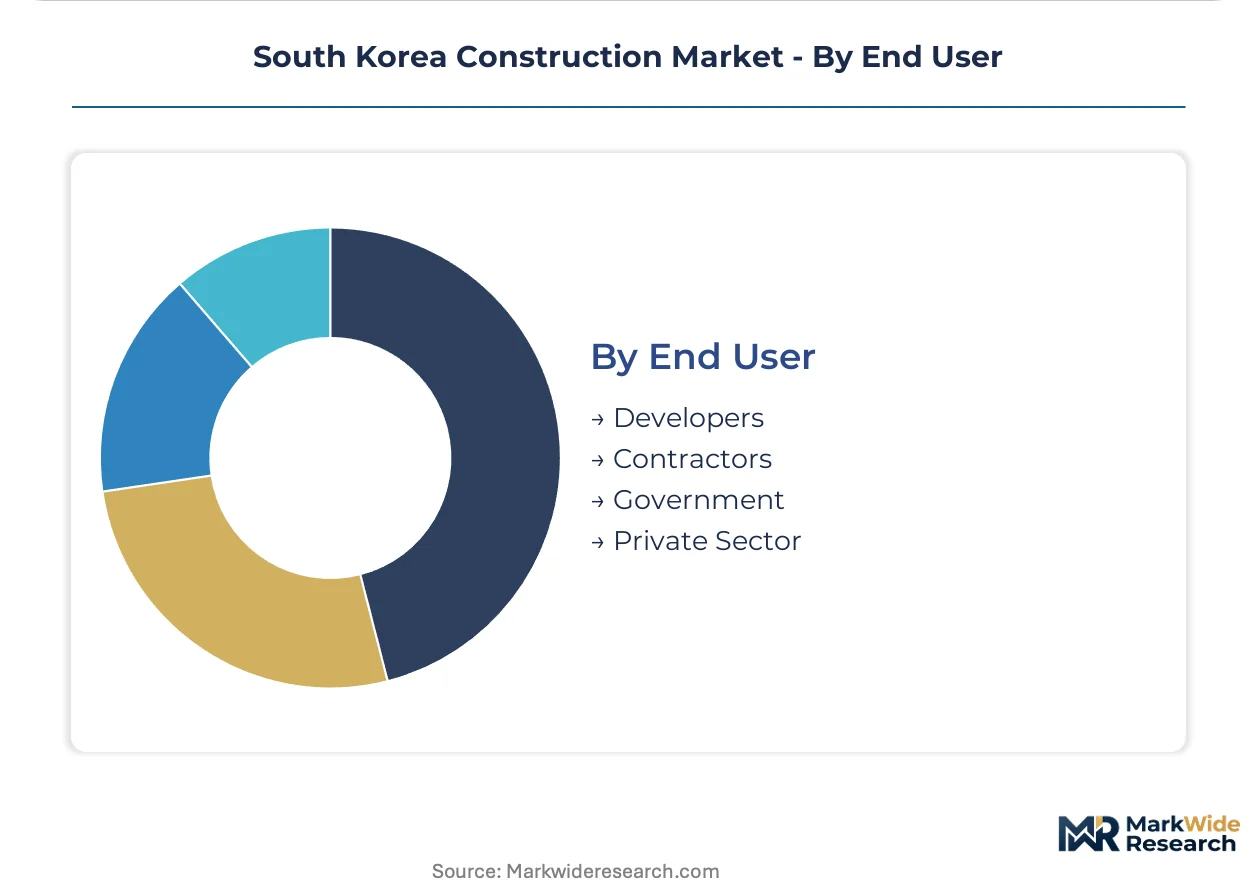
End User:
Buyer concentration and procurement sophistication create divergent pricing power dynamics across the construction value chain.
- Developers:Chaebol-affiliated real estate arms and specialized residential developers in Seoul aggregate demand across multiple towers. Their scale commands extended payment terms and logistics cost absorption from material distributors.
- Contractors:Prime EPC firms like Hyundai Engineering & Construction and Samsung C&T self-perform on complex industrial projects while subcontracting standardized residential work. Their procurement platforms increasingly require BIM interoperability from downstream partners.
- Government:Municipal housing corporations and infrastructure agencies consolidate buying power through the Korea On-Line E-Procurement System. Aggregated demand for windows, insulation, and HVAC equipment squeezes working capital for smaller material suppliers.
- Private Sector:Hyperscale data center operators and semiconductor manufacturers specify liquid cooling infrastructure and reinforced floor loading above 15 kilonewtons per square meter. This demand segment escapes commodity pricing pressure through specialized technical requirements.
Government procurement leads by contract value. Private sector industrial demand shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area concentrates the majority of South Korea's construction activity through semiconductor fab clusters in Gyeonggi Province and high-rise residential towers in Seoul proper. The Ministry of Land, Infrastructure and Transport directs infrastructure investment toward this corridor while enforcing zero-energy building codes that reshape material specifications nationwide.
Seoul Capital Area
Samsung and SK Hynix expansion programs in Gyeonggi Province pull specialized EPC capacity for cleanroom-grade concrete and vibration-isolated foundations. The Ministry of Land, Infrastructure and Transport mandates net-zero operational carbon for public structures above 3,000 square meters. Pangyo and Hwaseong host the densest concentration of semiconductor fab construction commanding premium pricing tiers.
Busan-Ulsan Industrial Belt
Automated container terminal expansion and petrochemical facility maintenance drive marine construction demand. The Korea Agency for Infrastructure Technology Advancement certifies new construction technologies for port infrastructure access. Busan Newport and Ulsan Mipo Industrial Complex anchor specialized marine civil engineering procurement pipelines.
Daegu-Gyeongbuk
Battery plant investments from LG Energy Solution and Samsung SDI expand industrial construction volumes. The Ministry of Environment enforces carbon intensity thresholds for cement-intensive projects. Gumi and Pohang concentrate cleanroom-adjacent manufacturing facility builds with seismic-grade structural requirements.
Daejeon-Sejong
Government complex relocation and administrative city expansion sustain public infrastructure demand. The Korea On-Line E-Procurement System consolidates buying power for standardized building materials. Sejong City hosts concentrated public sector construction subject to embodied carbon procurement rules.
Gwangju-Honam
Renewable energy island initiatives and offshore wind foundation construction create marine civil engineering opportunities. The Ministry of Trade, Industry and Energy coordinates investment in subsea cable landing stations. Sinan and Yeonggwang counties host untapped demand for specialized port and energy infrastructure.
South Korea Construction Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification capability and project complexity. The South Korea construction market structures around three tiers: integrated EPC conglomerates commanding industrial projects, modular construction specialists capturing residential schedule premiums, and regional contractors competing on municipal infrastructure bids. Strategic archetypes include technology-intensive infrastructure delivery, factory-controlled prefabrication systems, and public sector procurement aggregation. Dominant competitive moves center on Korea Agency for Infrastructure Technology Advancement certification acquisition and BIM platform interoperability mandates that filter subcontractor eligibility.
Within the integrated EPC tier, Hyundai Engineering & Construction and Samsung C&T Corporation exemplify full-service delivery capability spanning complex industrial and premium infrastructure segments. GS Engineering & Construction occupies a position among modular construction specialists leveraging prefabricated systems for urban residential compression. Daewoo Engineering & Construction and Daelim Industrial sit within the tier of diversified conglomerates balancing public infrastructure exposure with industrial project selectivity. POSCO Engineering & Construction represents the vertical integration archetype with captive steel supply advantages. These groupings illustrate how certification depth and procurement platform scale determine tier positioning rather than geographic coverage alone.
| Leading Market Players |
|---|
| Daewoo Engineering & Construction |
| Daelim Industrial |
| Samsung C&T Corporation |
| Movements Inc. |
| Samsung E&A |
| Hyundai Engineering & Construction |
| POSCO Engineering & Construction |
| SLZ Inc. |
| GS Engineering & Construction |
| Others |
Value Chain & Pricing Dynamics
Zero-energy building mandates from the Ministry of Land, Infrastructure and Transport gate qualified supply access and premium-tier pricing power. Contractors lacking Korea Agency for Infrastructure Technology Advancement certification face exclusion from public bidding, compressing margins in residual commodity segments while certified players capture performance-guarantee premiums.
Pricing Analysis
Outcome-based pricing tied to energy performance guarantees anchors premium tiers in South Korea's construction market. Three-tier pricing structure across premium, standard, and economy levels separates zero-energy certified contractors from conventional builders from unqualified regional players. Cost compression in residential segments is intensifying because municipal housing corporations aggregate demand and force logistics cost absorption. Developers and government procurement offices show highest price sensitivity, while hyperscale data center operators prioritize technical specification compliance over unit cost.
Supply Chain Analysis
KS D 3503 certified structural steel supply rests on Chinese and Japanese mill production, exposing project budgets to geopolitical friction and shipping volatility. Low-clinker cement alternatives and supplementary cementitious materials draw from constrained domestic capacity and extended import lead times. Single-source vulnerability concentrates in cleanroom-grade concrete admixtures for semiconductor fab construction. Distribution runs through prime contractor procurement platforms that increasingly mandate BIM interoperability from downstream partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled welder scarcity—fewer than 12,000 certified structural steel welders nationwide—props pricing power for qualified contractors and extends project timelines by 15-20 percent.
For Market Incumbents: Extend certification depth beyond current Korea Agency for Infrastructure Technology Advancement holdings to defend against modular construction specialists encroaching on high-rise residential. Backward integration into prefabricated concrete floor cassette production secures schedule compression advantages. Reinforce BIM platform interoperability mandates that filter subcontractor eligibility and consolidate procurement control. For New Entrants and Emerging Players: Launch via specialized marine civil engineering partnerships targeting Busan Smart Port infrastructure and Jeju offshore wind foundation construction. White-space availability concentrates in automated container terminal expansion and subsea cable landing stations where foreign EPC collaboration opens procurement access. Target building-integrated photovoltaics-ready curtain wall specification gaps ahead of revised national building code implementation. For Investors and Strategic Acquirers: Korea Agency for Infrastructure Technology Advancement fast-track approval acquisition by mid-tier contractors is the leading indicator that modular construction capability premiums are becoming monetizable. Long-term viability favors targets with factory-controlled prefabrication systems and established relationships with municipal housing corporations. Watch for Ministry of Land, Infrastructure and Transport green certification timeline tightening that excludes smaller contractors from public bidding eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Korea Agency for Infrastructure Technology Advancement Certification Acquisition | Fast-track permitting access accelerates project delivery timelines in Seoul high-rise residential. |
| Modular Construction System Deployment | Prefabricated bathroom pods and unitized facades reduce on-site labor dependence by 30 percent. |
| Zero-Energy Performance Guarantee Contracts | Outcome-based risk allocation shifts contractor accountability from equipment to operational carbon results. |
| Building-Integrated Photovoltaics Capability Buildout | BIPV-ready curtain wall specifications capture commercial developments above 10,000 square meters. |
| Cleanroom Construction Specialization Investment | MFDS validation protocols for pharmaceutical facilities command 6-8 month commissioning timeline premiums. |
Study Parameters
Document review covered Ministry of Land, Infrastructure and Transport regulatory filings, Korea Agency for Infrastructure Technology Advancement certification databases, and Korea On-Line E-Procurement System award records, complemented by interviews with EPC contractor procurement directors, structural engineering firm technical leads, municipal housing corporation planning officers, and steel distributor logistics managers. Secondary validation drew from customs trade data, construction industry association reports, and corporate disclosure filings. Bottom-up project pipeline analysis and top-down macroeconomic triangulation anchored market sizing.
Market value and volume outputs across the projection horizon reflect segmented modeling by project type, building material, construction method, and end user, with industrial facility investments and public infrastructure renewal tracked separately. CAGRs were derived from regression analysis against semiconductor capital expenditure cycles, battery plant investment waves, and zero-energy building mandate implementation schedules.
The model assumes a particular technology adoption path for modular and prefabricated construction systems; alternative pathways for traditional cast-in-place methods would alter the outlook if skilled labor shortages resolve faster than projected. Forecasts reflect assumptions about regulatory enforcement consistency, import supply stability, and certification timeline adherence. A small set of triggers—green cement supply expansion, welder training program graduation rates, and MFDS cleanroom protocol revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Steel Beam Market
Structural Construction
Saudi Arabia Prefabricated Building and Structural Steel Market
Structural Construction
Prefabricated Steel Bridge Market
Structural Construction
United Arab Emirates Structural Steel Fabrication Market
Structural Construction
Global Concrete Contractor Market
Structural Construction
Glue Laminated Beams Market
Structural Construction
Elastomeric Bearings Market
Structural Construction
China Structural Steel Fabrication Market
Structural Construction
North America Structural Steel Fabrication Market
Structural Construction
Sandwich Plate System Market
Structural Construction
Global Structural Steel Fabrication Market
Structural Construction
Saudi Arabia Structural Steel Fabrication Market
Structural Construction
Timber Frame Construction Market
Structural Construction
Self-Consolidating Concrete (SCC) Market
Structural Construction
Ceiling Expansion Joint Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market